
 Smart Food Logistics Market | 2026-2036
Smart Food Logistics Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Food Logistics Market Intelligence
The market for smart food logistics is shifting as premium services, offering end-to-end blockchain traceability and real-time quality assurance, diverge from commodity-level GPS tracking. Sensitech Inc. specializes in cold chain monitoring solutions for high-value pharmaceuticals and perishables. Controlant leverages its cloud-based platform to provide comprehensive supply chain visibility. Meanwhile, Geotab Inc. competes by offering scalable telematics for a broader fleet management audience.
Smart food logistics involves the application of digital technologies to optimize the transportation and storage of food products. Systems integrate components like IoT sensors that provide real-time data on temperature, humidity, and shock events to a central platform. Within the application segment, cold chain monitoring commands the highest value due to its criticality for perishable goods. Among technologies, the adoption of blockchain is accelerating for its ability to provide immutable records for quality assurance and traceability.
Regulatory frameworks such as the FDA's Food Safety Modernization Act in the United States and the EU's General Food Law mandate stringent traceability and safety protocols. These regulations compel food distributors and retailers to invest in compliant logistics technologies to avoid penalties and ensure market access. Stakeholders must now decide whether to build proprietary platforms or partner with specialized technology providers to meet evolving compliance and consumer transparency demands.
Market Dynamics
The convergence of stringent food safety regulations and accessible digital technologies is the central force shaping the smart food logistics market. Mandates for end-to-end traceability compel investment, while cost-effective IoT sensors and cloud platforms provide the tools for compliance and operational efficiency.
Growth Catalysts
- Regulatory Mandates:Frameworks like the FDA's Food Safety Modernization Act and the EU's General Food Law require verifiable proof of temperature control and product provenance, directly stimulating investment in compliant smart logistics systems by food producers and distributors.
- IoT Sensor Affordability:Declining costs of IoT sensors for temperature, humidity, and shock monitoring enable broader deployment beyond high-value perishables, making real-time tracking economically viable for a wider range of food products.
- Consumer Demand for Transparency:Heightened consumer interest in food origins and safety is pressuring retailers and food service companies to adopt technologies like blockchain to provide verifiable, transparent supply chain histories from farm to table.
Market Restraints
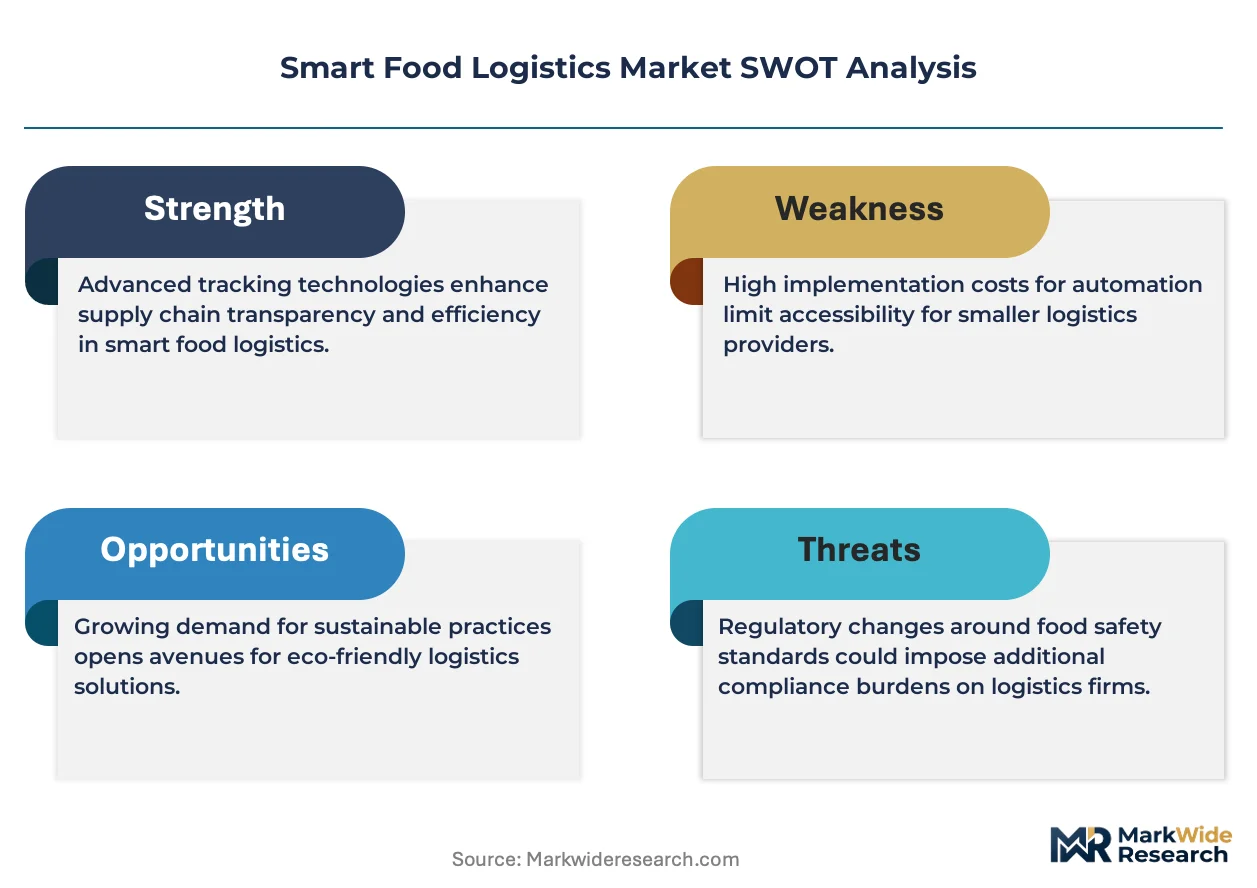
- High Implementation Costs:The significant upfront capital investment required to deploy comprehensive smart logistics solutions, including hardware, software, and system integration, presents a substantial barrier for small and medium-sized food enterprises.
- System Integration Complexity:Integrating modern IoT and blockchain platforms with pre-existing, often outdated, legacy systems such as ERP and WMS creates significant technical hurdles, data silos, and operational friction for many companies.
- Lack of Data Standardization:The absence of universally accepted data protocols across different technology vendors and supply chain partners hinders seamless interoperability, complicating data sharing and creating fragmented visibility.
Strategic Opportunities
- Emerging Market Penetration:Expanding services into Southeast Asian and Latin American markets, where growing food export sectors require advanced logistics to meet international food safety standards, offers significant growth potential for technology providers.
- Predictive Analytics Services:Leveraging AI and machine learning on collected IoT data to offer predictive analytics for spoilage risk, route optimization, and demand forecasting represents a high-value service opportunity beyond simple monitoring.
- Expansion into Food Fraud Prevention:Applying blockchain traceability to combat adulteration in high-value dry goods, such as premium spices, coffee, and olive oil, opens a new application segment focused on authenticity and quality assurance.
Industry Challenges
- Specialized Talent Shortage:A scarcity of professionals with hybrid expertise in supply chain logistics, data science, and IoT systems integration constrains the ability of companies to effectively implement and manage smart logistics platforms.
- Cybersecurity Vulnerabilities:Protecting sensitive supply chain data stored on cloud platforms and transmitted from thousands of IoT devices against cyberattacks is a critical operational challenge that demands continuous investment in security infrastructure.
- Demonstrating Return on Investment:Logistics managers face difficulty in clearly quantifying the financial benefits of smart logistics systems, making it challenging to build a compelling business case to secure necessary budget approvals.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Food Logistics Market |
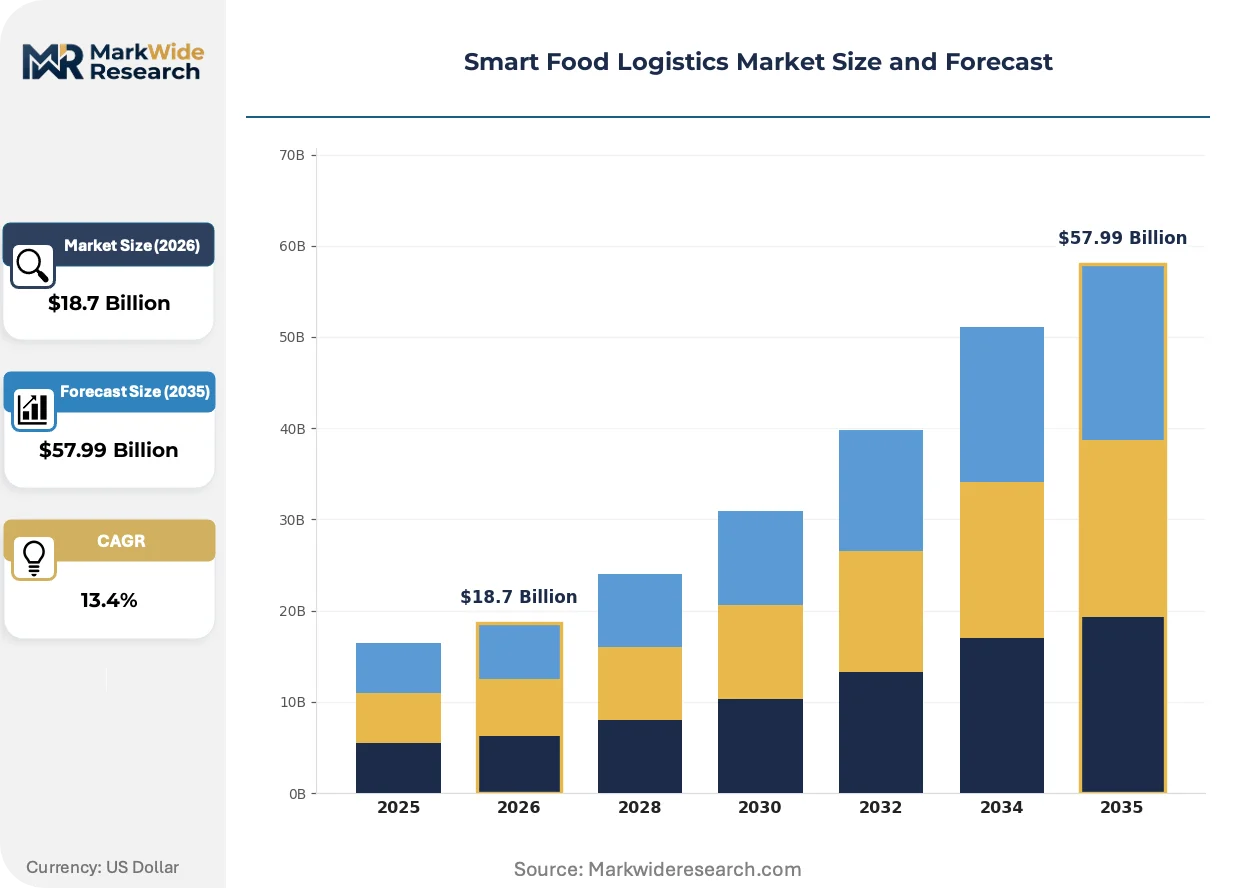
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $57.99 Billion |
| CAGR (2026 – 2036) | 13.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: RFID, GPS Tracking, IoT Sensors, Blockchain, Cloud Computing Application: Cold Chain Monitoring, Inventory Management, Route Optimization, Temperature Control, Quality Assurance End User: Food Retailers, Food Processing Plants, Cold Storage Providers, Food Distributors Distribution Channel: Direct Sales, Online Platforms, Wholesale Distributors, Third-Party Logistics, Freight Forwarders |
| Companies Covered | ORBCOMM Inc., Sensitech Inc., Berlinger & Co. AG, Geotab Inc., Kii Corporation, Controlant, Samsara Inc., Teletrac Navman, Monnit Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Food Logistics Market Strategic Shifts & Innovations
Automation and intelligence are reshaping the market, moving capabilities beyond simple location tracking toward proactive quality assurance and automated compliance. The integration of real-time sensor data with immutable ledgers is creating a new standard for supply chain integrity and operational visibility.
Blockchain technology provides a distributed, immutable ledger for recording every transaction and handoff within the food supply chain. Food processors and large retailers are adopting the technology to create a single source of truth for provenance and compliance checks. The technology is expanding into a complete quality assurance framework, linking transactional data with live IoT sensor feeds to automate safety and quality verification.
Regulatory frameworks like the FDA's Food Safety Modernization Act (FSMA), specifically Rule 204, are creating new traceability requirements. The rule mandates that companies maintain and share extensive records for certain high-risk foods at critical points in the supply chain. Cold chain providers and distributors shipping to the United States are most impacted, accelerating their adoption of digital record-keeping platforms to ensure compliance.
A notable demand-side shift sees food distributors moving away from one-time purchases of standalone hardware toward subscription-based service models. This "Logistics-as-a-Service" (LaaS) approach bundles sensor hardware, cloud software, and data analytics into a recurring operational expense, which is easier to budget. The model is gaining traction among mid-sized enterprises in North America and Europe that prefer to outsource technology management.
Smart Food Logistics Market Segmentation
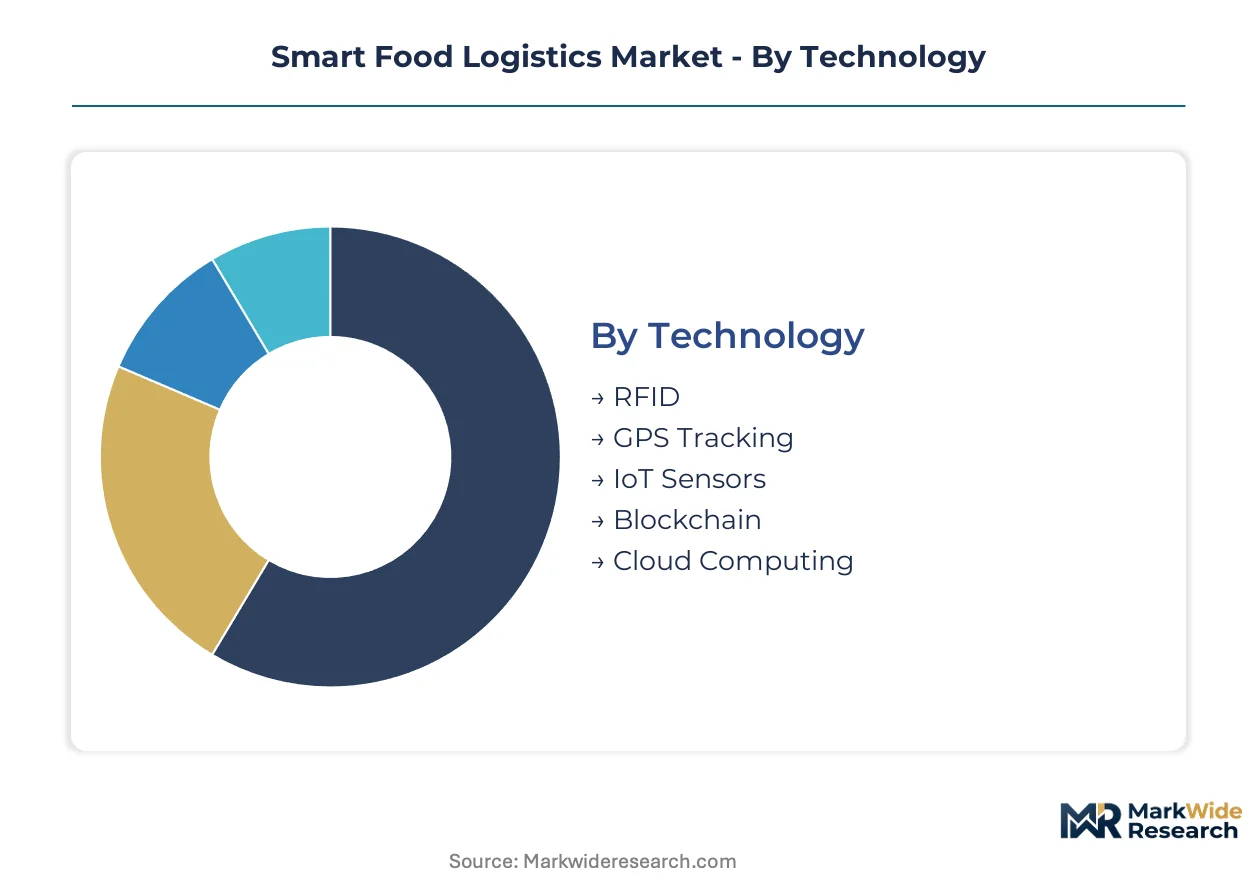
Segmentation analysis provides a critical lens to understand the diverse technological adoption, application priorities, and end-user demands shaping the smart food logistics market. It highlights where innovation and investment are most concentrated across the complex food supply chain.
Technology:
The smart food logistics market's technology adoption reflects a continuous upgrade cycle, moving from foundational tracking systems to sophisticated data-driven platforms.
- IoT Sensors:These devices gather real-time environmental data like temperature, humidity, and location from food shipments. Demand concentrates in cold chain monitoring for perishable goods, driven by stringent regulatory compliance.
- Blockchain:This distributed ledger technology provides an immutable record of product provenance and supply chain transactions. Food processors and large retailers in Europe and the United States leverage blockchain for enhanced traceability and food fraud prevention.
- RFID:Radio-frequency identification tags enable automated inventory tracking and asset management within warehouses and distribution centers.
- GPS Tracking:Global Positioning System modules offer basic real-time location monitoring for transport vehicles and containers.
- Cloud Computing:Cloud platforms provide scalable infrastructure for data storage, analytics, and software-as-a-service applications in logistics.
IoT Sensors sits at the top of the volume ranking, with Blockchain climbing the fastest.
Application:
Applications within smart food logistics differentiate based on their criticality to product integrity and operational value for food businesses.
- Cold Chain Monitoring:This application involves continuous tracking of temperature and humidity for sensitive perishable goods throughout the supply chain. Its high value stems from preventing spoilage and ensuring compliance with food safety regulations like the FDA's FSMA.
- Quality Assurance:This application integrates real-time sensor data and traceability records to verify product quality and safety at various touchpoints. Large food manufacturers and retailers in North America utilize it to meet consumer transparency demands and reduce recalls.
- Inventory Management:This application uses digital tools to track stock levels, optimize warehouse layouts, and reduce waste across food storage facilities.
- Route Optimization:This application employs algorithms to determine the most efficient delivery paths, minimizing fuel costs and transit times for food distributors.
- Temperature Control:This application focuses on maintaining specific environmental conditions within storage and transport units for food products.
Cold Chain Monitoring commands the highest value, while Quality Assurance applications are expanding most quickly.
End User:
The smart food logistics market's end-user landscape reflects varying degrees of supply chain control and technological sophistication.
- Cold Storage Providers:These entities manage temperature-controlled warehousing and distribution for perishable food items. Demand for smart logistics solutions here is high due to the critical need for precise environmental control and regulatory compliance, particularly in the United States.
- Food Distributors:These companies manage the movement of food products from producers to retailers or foodservice establishments. They require advanced tracking and optimization tools to handle diverse product portfolios and complex delivery networks efficiently.
- Food Retailers:These businesses, including supermarkets and grocery chains, implement smart logistics for in-store inventory, last-mile delivery, and supply chain transparency.
- Food Processing Plants:These facilities use smart logistics to monitor raw material intake, manage internal production flows, and track finished goods shipments.
Cold Storage Providers represent a significant investment segment, with Food Retailers demonstrating increasing strategic adoption.
Distribution Channel:
Distribution channels for smart food logistics solutions are shaped by the diverse purchasing preferences and technical capabilities of their customer base.
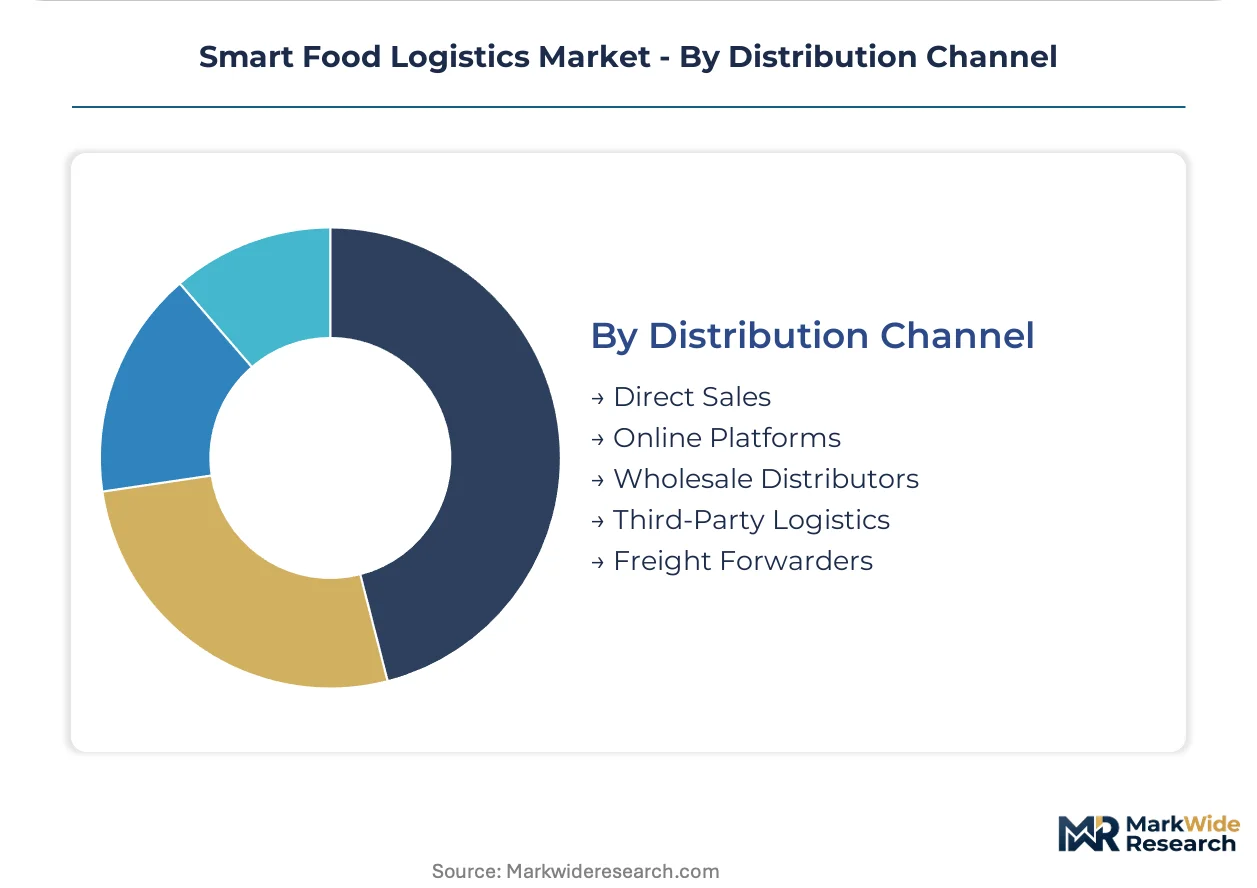
- Third-Party Logistics:These providers offer outsourced logistics services, including transportation and warehousing, integrating smart solutions for their clients. Demand from 3PLs is strong as they seek to offer value-added services and operational efficiencies to food producers and retailers.
- Direct Sales:This channel involves technology vendors selling solutions directly to end-user companies, often for complex or customized smart logistics deployments. Large food enterprises prefer direct engagement for strategic implementations and long-term partnerships.
- Online Platforms:These digital marketplaces and SaaS portals offer subscription-based smart logistics software and hardware bundles to a broad customer base.
- Wholesale Distributors:These intermediaries resell smart logistics hardware and software to smaller businesses within the food supply chain.
- Freight Forwarders:These entities manage international and complex shipping, increasingly adopting smart tracking for compliance and visibility across borders.
Third-Party Logistics providers drive substantial solution volume, while Online Platforms show strong growth in accessibility.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global smart food logistics market exhibits varied development across key regions, largely influenced by logistics expertise and technological infrastructure. Talent pools in supply chain management and data analytics drive innovation in several leading economies. These regions actively deploy advanced solutions to enhance food safety and operational efficiency.
United States
Demand in the United States stems from extensive food distribution networks and stringent food safety regulations. The FDA's Food Safety Modernization Act (FSMA) mandates comprehensive traceability, compelling investment in digital platforms. Technology hubs like Silicon Valley are developing advanced IoT and blockchain solutions for food supply chains.
Germany
Germany's robust industrial base and strategic position in Europe drive demand for efficient smart food logistics. The EU's General Food Law requires high standards for food safety and traceability, fostering advanced monitoring systems. Logistics corridors around Frankfurt integrate real-time tracking and quality assurance technologies.
China
China's enormous consumer market and expanding cold chain infrastructure generate substantial demand for smart food logistics. Government initiatives, such as the "Internet Plus" strategy, encourage digital transformation in agricultural supply chains. Major port cities like Shanghai are becoming centers for logistics technology deployment, improving cold chain management.
India
India's rapidly urbanizing population and significant food wastage issues drive the need for optimized smart food logistics. The Food Safety and Standards Authority of India (FSSAI) is tightening traceability norms, pushing for digital record-keeping. Logistics parks near Delhi are witnessing increased investment in IoT-enabled warehouses and distribution hubs.
Brazil
Brazil's position as a major agricultural exporter necessitates advanced smart food logistics to meet international market standards. Its national agricultural regulations often align with international food safety protocols, driving technology adoption. Key agricultural regions like Mato Grosso implement digital solutions for farm-to-port traceability.
Smart Food Logistics Market Key Industry Players
Top-tier vendors anchor the smart food logistics market with comprehensive platforms, while niche specialists focus on specific technology applications or regional requirements. The market structure is evolving from fragmented solution providers towards more integrated offerings. Two strategic archetypes are emerging: full-suite integrators and specialized technology providers. Competitive moves frequently involve strategic partnerships to expand geographic reach and portfolio diversification into new services like predictive analytics.
Specialists in cold chain monitoring exemplify the focused technology provider archetype; Sensitech Inc. offers solutions for high-value perishables, anchoring this segment with precise temperature control. Controlant, a European-based entity, represents providers leveraging cloud-based platforms for comprehensive supply chain visibility and real-time data aggregation. Geotab Inc. occupies a position among telematics providers, offering scalable fleet management solutions to a broader audience within the logistics sector, emphasizing vehicle tracking and operational efficiency. These companies collectively illustrate the diverse approaches to smart food logistics.
| Leading Market Players |
|---|
| ORBCOMM Inc. |
| Sensitech Inc. |
| Berlinger & Co. AG |
| Geotab Inc. |
| Kii Corporation |
| Controlant |
| Samsara Inc. |
| Teletrac Navman |
| Monnit Corporation |
| Others |
Cost & Logistics Intelligence
Global semiconductor component prices influence the cost structure of smart food logistics solutions, impacting hardware for IoT sensors. These input costs cascade into the tiered pricing models offered by technology providers, affecting service affordability.
Pricing Analysis
Bundled service offerings, combining hardware, software, and analytics, represent the dominant pricing structure in smart food logistics. Pricing stratifies across premium, standard, and economy tiers based on customization level and integrated after-sales support. Pricing softness stems from increasing competition among technology providers and the commoditization of basic GPS tracking. Mid-sized food enterprises exhibit higher price sensitivity, while large cold storage providers prioritize comprehensive, higher-value solutions.
Supply Chain Analysis
Logistics and freight costs significantly influence the overall supply chain for smart food logistics hardware and deployment. Component manufacturing for IoT sensors concentrates in China, while advanced software development hubs are prominent in the United States and Germany. The industry relies on a stable supply of specialized IoT sensor components and cloud computing infrastructure. Single-source vulnerability for key hardware components poses a structural risk, with distribution primarily running through third-party logistics providers and direct sales channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The smart food logistics market functions as a stable compounder, driven by continuous regulatory mandates for food safety and traceability. This foundational demand ensures sustained investment and technological evolution across the supply chain.
For Market Incumbents: Lock in existing client relationships by deepening integration with enterprise resource planning (ERP) and warehouse management systems (WMS). Acquire niche predictive analytics firms to counter the commoditization of basic GPS tracking solutions. Invest proactively in advanced blockchain capabilities to meet evolving traceability standards like FDA FSMA Rule 204. This secures market share against emerging competitors offering point solutions.
For New Entrants and Emerging Players: Capture market share in underpenetrated emerging markets, particularly within Southeast Asia's expanding cold chain infrastructure. Target specialized applications like food fraud prevention for high-value dry goods, such as premium coffee and spices. Mid-sized food distributors in these regions represent the most penetrable segment for new offerings. Offer flexible Logistics-as-a-Service (LaaS) subscription models to reduce upfront capital investment for new clients.
For Investors and Strategic Acquirers: Asymmetric upside sits with specialized technology providers offering advanced predictive analytics and blockchain solutions. The market offers sustained growth potential over the next decade due to regulatory tailwinds and consumer transparency demands. Acquisition targets should possess robust intellectual property in real-time quality assurance or immutable traceability platforms. Industry consolidation among third-party logistics providers integrating smart solutions is a key inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Product Launch: Predictive Analytics Module | This enhances proactive risk management for perishable goods, moving beyond reactive monitoring. |
| Platform Integration: ERP/WMS System APIs | This reduces system integration complexity for food distributors, improving operational efficiency. |
| Strategic Partnership: Regional Cold Chain Operators | This expands market reach into new geographies and strengthens local distribution networks. |
| Acquisition of Specialist Firm: Blockchain Traceability Provider | This secures advanced immutable record-keeping capabilities, meeting stringent regulatory requirements. |
| Geographic Expansion: Southeast Asian Markets | This leverages growing food export sectors in emerging economies, capturing new demand. |
Research Approach
Multiple input streams — primary interviews, secondary research, and proprietary databases — were reconciled to build a comprehensive market view. Interviews with logistics managers, supply chain directors, IoT solution architects, and food safety officers provided qualitative insights. Secondary validation drew from FDA filings, EU General Food Law documents, industry association reports, and corporate financial statements. Bottom-up and top-down triangulation ensured data accuracy and consistency across all market segments.
Data stream reconciliation established an analytical framework for market sizing and forecasting across the analysis window. The model segmented the market by technology, application, end-user, distribution channel, and regional regulatory adherence. Compound annual growth rates were derived from historical data trends and projected technological advancements. Forecast inputs included IoT sensor adoption rates within cold storage and global cold chain infrastructure development.
Geopolitical shifts, new food safety regulations, and cybersecurity threats are the dominant revision risks to market forecasts. Forecasts reflect assumptions regarding technological diffusion and continued investment in digital logistics solutions. Stakeholders should weigh these assumptions against their own operating context and risk appetite.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service
Food Trays Market
Food Service
Fast Food Market
Food Service
Global Sushi Restaurants Market
Food Service
Food & Beverage in Asia Market
Food Service
Catering Food Warmers Market
Food Service
UAE Food Service Market
Food Service
Global Online Food Delivery Services Market
Food Service
Global Meal Kit Market
Food Service
Air Fryer Meal Kits Market
Food Service
Shaker Bottles Market
Food Service
Takeout Dinner Market
Food Service
Vietnam Online Food Delivery Market
Food Service
Smokeless Grill Market
Food Service
Tabletop Pizza Oven Market
Food Service
Haute Cuisine Market
Food Service
Latin America Inflight Catering Market