
 Food Service Pasta Market | 2026-2036
Food Service Pasta Market Size, Share, and Industry Trends Forecast 2026-2036
Food Service Pasta Market Intelligence
Contract-based volume commitments for institutional buyers is rebalancing how manufacturers allocate production capacity between spot food service sales and long-term catering agreements. Barilla G. E R. Fratelli Spa leverages its vertical integration into durum wheat milling to secure consistent semolina supply for high-volume restaurant contracts. Ebro Foods S.A. anchors its competitive position through geographic diversification across European and Latin American food service channels. Dakota Growers Pasta Company, Inc. specializes in bulk-format pasta tailored to school and hospital feeding programs in North America.
Food service pasta comprises durum wheat semolina or alternative grain formulations extruded through bronze or Teflon dies, then dried to moisture levels below 12.5 percent for extended shelf stability in commercial kitchens; its primary purpose is to deliver consistent cook yield and texture under high-throughput restaurant conditions. Spaghetti maintains volume leadership across restaurant chains due to its universal menu compatibility and minimal training requirements for line cooks. Penne competes aggressively in catering services where sauce retention and portion uniformity drive procurement decisions. Ready-to-cook formats within packaging type segments are capturing margin pools as operators trade labor savings against per-unit cost premiums.
The FDA enforces allergen labeling and fortification standards for pasta distributed through interstate food service channels, while the USDA administers commodity procurement rules that shape institutional purchasing specifications for school nutrition programs. The EU's F-Gas Regulation and broader Green Deal targets are pressuring pasta manufacturers to decarbonize thermal drying processes and document agricultural emissions across wheat supply chains. Stakeholders must monitor how escalating sustainability disclosure requirements in Europe migrate into North American distributor scorecards and reshape supplier qualification criteria.
Market Dynamics
The EU Green Deal's F-Gas Regulation is forcing pasta manufacturers to decarbonize thermal drying operations, reshaping capital allocation between energy retrofits and capacity expansion across European production networks.
Growth Catalysts
- Full-service restaurant expansion:North American and European chains are adding customizable pasta stations, driving bulk semolina demand for high-throughput kitchen environments.
- Farm to Fork Strategy:The EU's mandatory sustainability disclosure for wheat sourcing is certifying supply chains that food service distributors now prioritize in procurement scorecards.
- Bronze die extrusion:Artisanal texture profiles are capturing premium menu positioning as Italian heritage brands supply certified durum formulations to upscale dining groups.
Market Restraints
- Durum wheat price volatility:Concentrated cultivation in Mediterranean growing regions exposes margins to climate-driven yield fluctuations and input cost spikes.
- Natural gas dependency:Thermal drying processes in Italy and Spain remain tethered to fossil fuel pricing, compressing margins when energy markets tighten.
- Alternative grain substitution:Chickpea, lentil, and rice-based pasta formulations are displacing traditional semolina in health-focused institutional feeding programs.
Strategic Opportunities
- Ready-to-cook formats:Par-cooled and quick-reconstitution pasta is capturing margin pools as labor-strapped operators trade per-unit premiums for kitchen efficiency gains.
- CSRD-aligned supply chains:Early adoption of EU corporate sustainability reporting standards opens preferred supplier status with ESG-mandated institutional buyers.
- School nutrition channels:USDA commodity procurement rules favor domestic wheat sourcing, creating captive demand for North American millers meeting fortified pasta specifications.
Industry Challenges
- Retrofitting legacy drying infrastructure:Heat pump and solar thermal conversions require 18-36 month implementation timelines, delaying compliance with tightening emissions benchmarks.
- Allergen segregation protocols:Gluten-free production lines demand dedicated extrusion and packaging equipment, complicating multi-format manufacturing footprints.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Food Service Pasta Market |
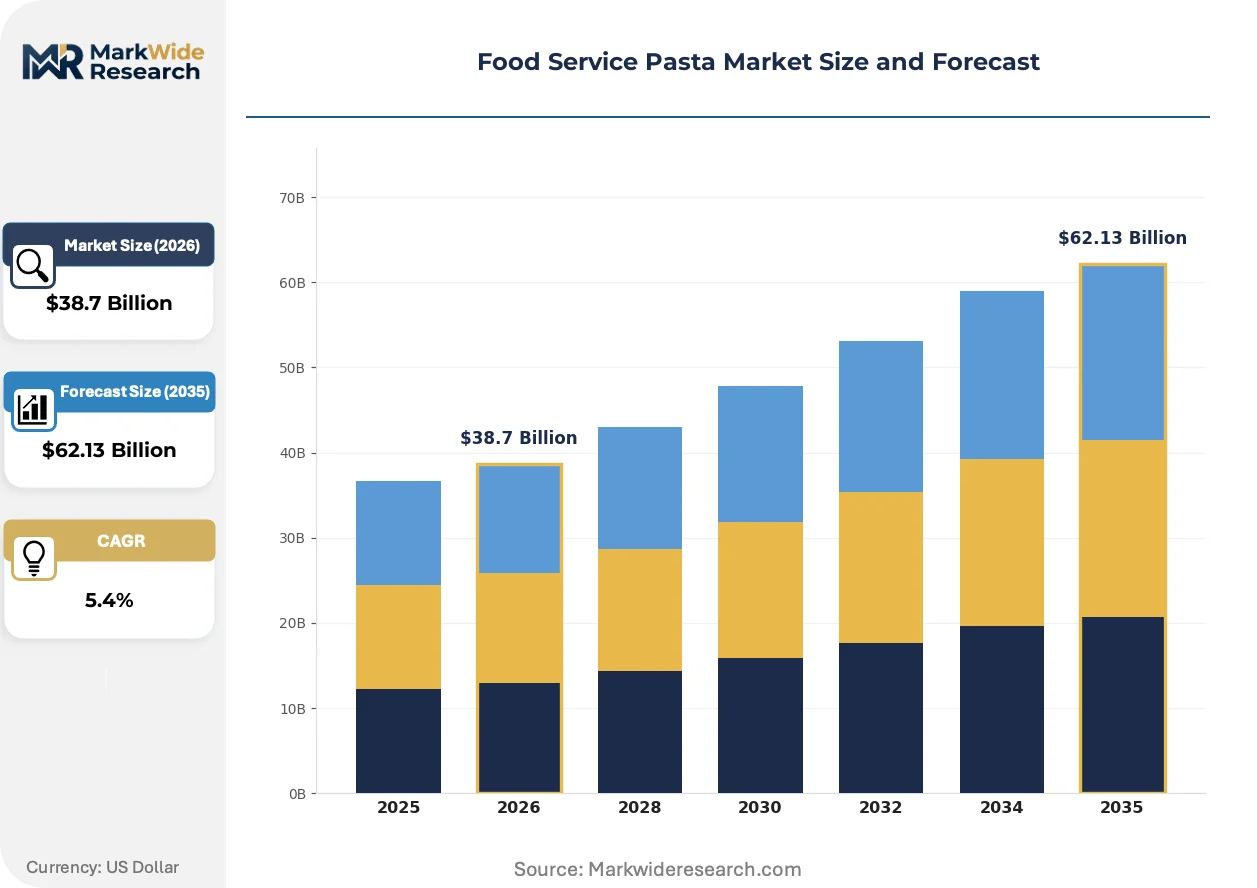
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $62.13 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Spaghetti, Penne, Fusilli, Farfalle End User: Restaurants, Cafes, Catering Services, Institutions Packaging Type: Bags, Boxes, Bulk, Ready-to-Cook Distribution Channel: Wholesale, Retail, Online, Direct Sales |
| Companies Covered | F.lli De Cecco di Filippo SpA, Armanino Foods of Distinction, Inc., Barilla G. E R. Fratelli Spa, M. Dias Branco, Dakota Growers Pasta Company, Inc., Ebro Foods S.A., Ajinomoto Co. Inc., MAKFA, Nestlé, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Food Service Pasta Market Strategic Shifts & Innovations
Energy recovery systems and alternative protein formulations are converging to redefine production economics and product positioning across food service pasta supply chains.
Heat pump drying technology is converging with thermal storage systems to stabilize energy input costs for continuous extrusion operations. Italian and Spanish manufacturers are piloting installations to buffer against natural gas price volatility. This convergence is compressing the payback period for capital-intensive retrofits while satisfying F-Gas Regulation phase-down timelines.
REACH chemical safety protocols are extending scrutiny to processing aids and packaging migrants in durum wheat supply chains. Manufacturers must now document substance thresholds across semolina milling and extrusion lubricants. Food service distributors in Germany and France are translating these requirements into supplier qualification questionnaires that filter non-compliant mills.
Direct sourcing contracts between restaurant groups and regional millers are displacing traditional broadline distributor intermediation. Chains with 50-plus unit footprints are negotiating volume commitments for custom die shapes and protein specifications. This pattern is most visible in the US Northeast and Midwest, where independent restaurant groups aggregate procurement through purchasing cooperatives.
Food Service Pasta Market Segmentation
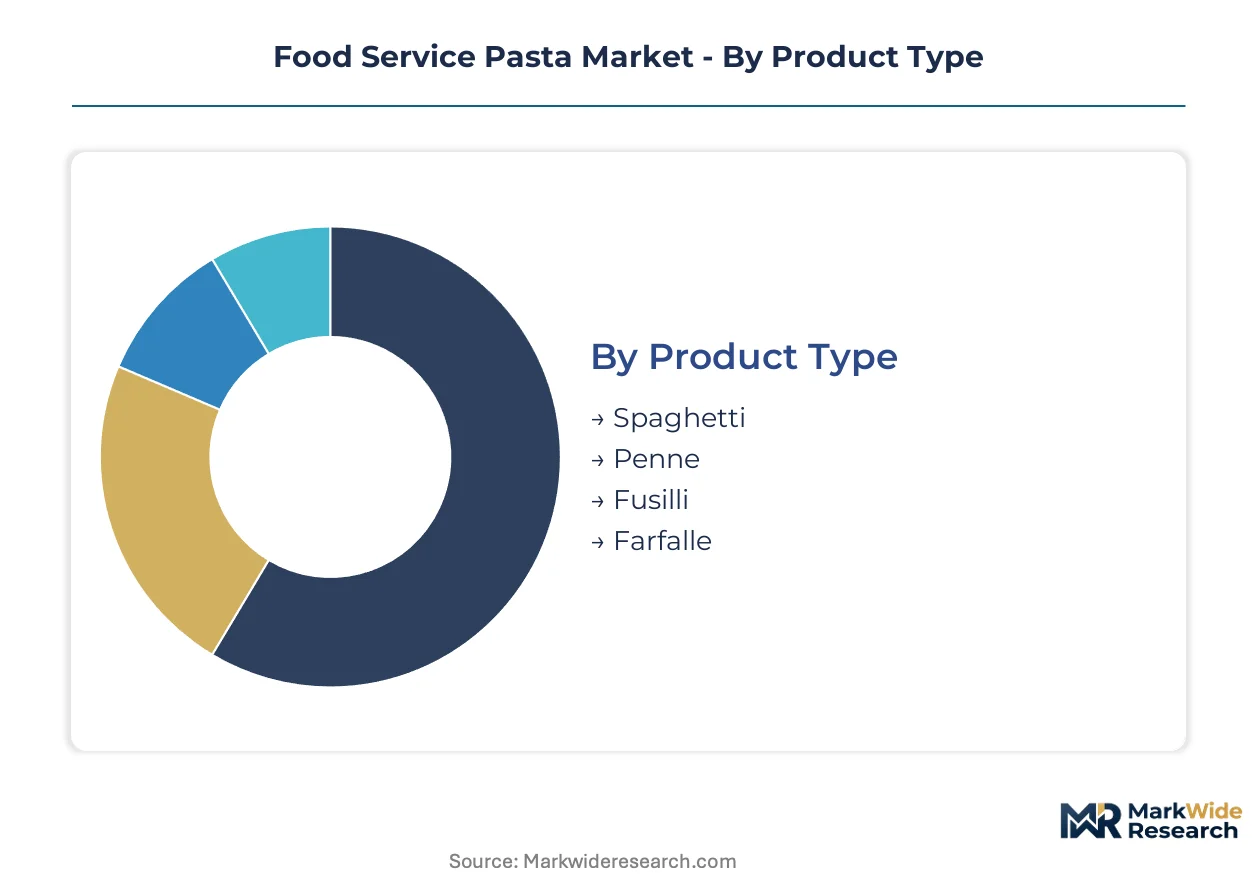
Food service pasta procurement varies sharply by operational scale and kitchen throughput requirements. Segment-specific certification burdens from FDA fortification rules to EU sustainability disclosure reshape supplier qualification pathways across institutional and commercial channels.
Product Type:
FDA allergen labeling applies uniformly across all formats, while EU Farm to Fork Strategy mandates diverge for heritage-designated versus commodity semolina formulations.
- Spaghetti:Long cylindrical extrusions from durum wheat semolina deliver consistent cook yield across high-throughput line kitchens. Full-service restaurant chains in Italy and the United States concentrate procurement here, trading menu versatility against minimal cook training requirements. Bronze die variants command premium placement in upscale dining procurement scorecards.
- Penne:Diagonal-cut tubular shapes optimize sauce retention for catering portion uniformity. Institutional feeding programs in German hospitals and French school nutrition channels specify this geometry for tray-line efficiency, though durum wheat price volatility compresses margins on volume contracts.
- Fusilli:Corkscrew profiles from Teflon die extrusion suit quick-service applications with aggressive sauce adherence requirements.
- Farfalle:Bow-tie configurations serve boutique cafe segments where plate presentation drives menu differentiation.
Leading the category by volume: Spaghetti. Expanding most quickly: Penne.
End User:
Cost tier stratification separates commodity-grade specifications from artisanal procurement, with certification thresholds scaling from USDA commodity rules to private ESG mandates.
- Restaurants:Full-service chains demand consistent semolina protein content for al dente texture reliability under variable kitchen conditions. Italian heritage brands supply bronze-extruded formats to upscale groups in Milan and Rome, while Teflon-die commodity volumes flow to mid-market operators in Spain and Portugal.
- Catering Services:Par-cooled and rapid-reconstitution formats capture procurement share where labor scarcity drives kitchen efficiency trade-offs. German and French contract caterers prioritize portion uniformity and hold stability over per-unit cost premiums.
- Cafes:Limited-menu operators favor smaller pack formats with extended ambient shelf stability.
- Institutions:USDA commodity procurement rules and EU public tender frameworks mandate fortified wheat sourcing with documented supply chain transparency.
Volume concentrates in Restaurants. Fastest climb: Catering Services.
Packaging Type:
Margin structures diverge between bulk commodity handling and value-added ready-to-cook convenience, with shelf-life extension technologies requiring differentiated regulatory documentation.
- Ready-to-Cook:Pre-portioned and par-cooled formats reduce labor input for operator kitchens. North American hospital and school feeding programs in California and Texas pilot these formats despite per-unit premiums, trading against wage inflation and staff turnover.
- Bulk:Unpackaged semolina extrusions in 10-20kg food-grade containers serve high-volume institutional kitchens with dedicated dry storage. Italian and Spanish manufacturers allocate capacity here for EU public procurement tenders with strict local wheat content rules.
- Bags:Polypropylene or paper laminate configurations dominate mid-scale restaurant distribution.
- Boxes:Retail-branded formats penetrate food service through dual-use procurement in smaller independent operators.
Fastest-gaining share: Ready-to-Cook. Largest volume position: Bulk.
Distribution Channel:
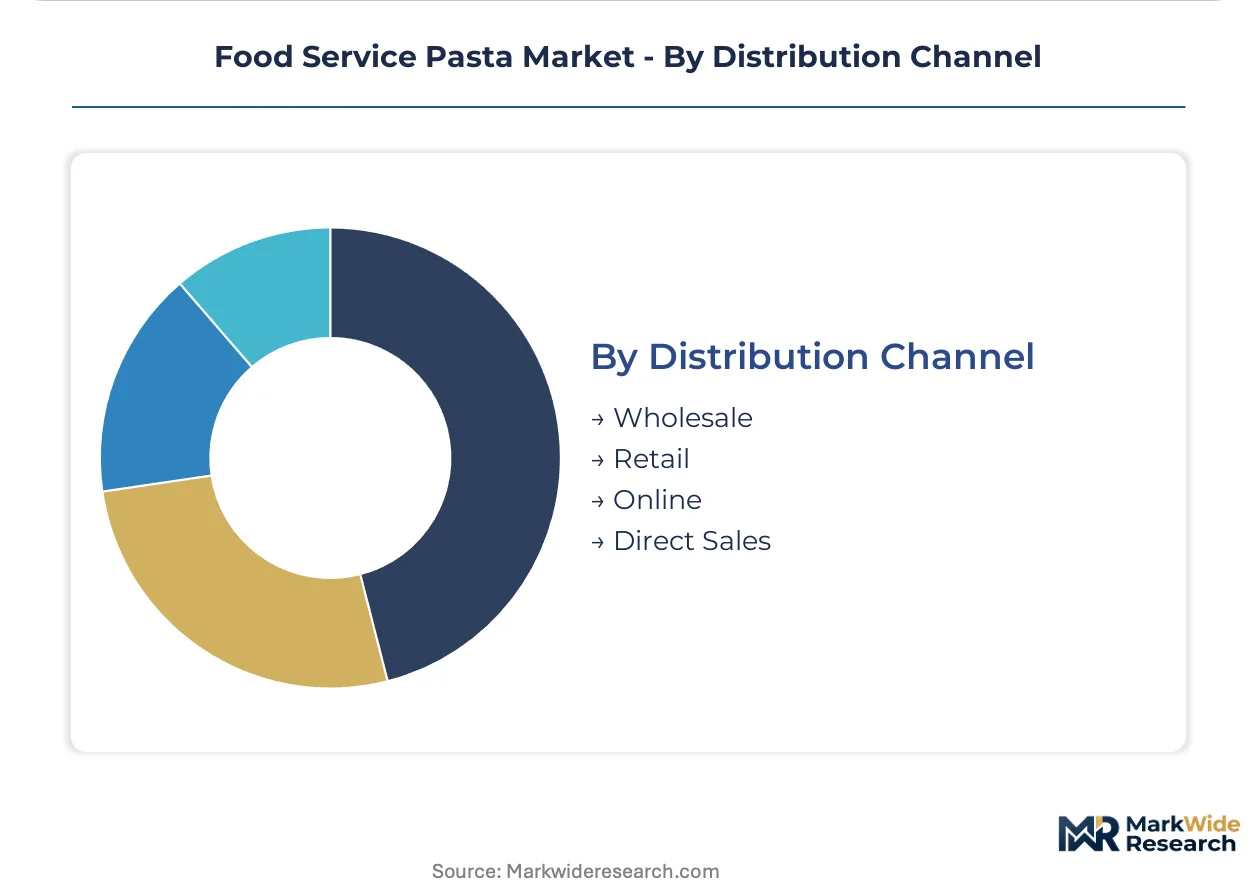
Customer-type concentration shapes channel power, with direct sourcing agreements displacing traditional broadline intermediation among multi-unit restaurant groups.
- Wholesale:Broadline distributors consolidate procurement for independent operators lacking volume leverage. Sysco and US Foods specifications in the American Northeast and Midwest increasingly incorporate ESG scorecard elements migrated from European procurement templates.
- Direct Sales:Restaurant groups with 50-plus unit footprints negotiate custom die shapes and protein specifications directly with regional millers. This pattern concentrates in the US Northeast and Midwest purchasing cooperatives, bypassing distributor markups for predictable volume commitments.
- Retail:Cash-and-carry formats serve small independent cafes with immediate need fulfillment.
- Online:Digital procurement platforms capture emerging share among tech-enabled catering startups.
Volume leadership: Wholesale. Steepest expansion trajectory: Direct Sales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Parma anchors food service pasta manufacturing through its dense cluster of heritage semolina mills and bronze-extrusion specialists supplying restaurant chains across Southern Europe. The concentration of durum wheat processing infrastructure in this Emilian corridor shapes procurement patterns for premium food service channels.
United States
School nutrition programs and hospital feeding systems drive institutional demand for fortified pasta formats. USDA commodity procurement rules mandate domestic wheat sourcing for federal nutrition assistance, creating captive demand for Great Plains millers. North Dakota and Minnesota host the primary durum wheat milling corridor supplying these institutional channels.
Italy
Artisanal bronze-extrusion heritage and protected designation of origin frameworks sustain premium positioning in upscale restaurant procurement. The EU Farm to Fork Strategy tightens sustainability disclosure requirements for wheat supply chains. Gragnano near Naples maintains its historical concentration of traditional pasta factories serving Michelin-tier dining groups.
Germany
Contract catering operators prioritize portion uniformity and extended hold stability for industrial kitchen environments. REACH chemical safety protocols extend scrutiny to processing aids and packaging migrants across semolina supply chains. The Rhine-Ruhr industrial corridor hosts specialized manufacturers supplying hospital and corporate canteen networks.
Spain
Mid-market restaurant chains drive volume demand for Teflon-die commodity pasta with consistent cook yield. The EU F-Gas Regulation pressures manufacturers to decarbonize thermal drying operations. The Ebro River valley clustering of pasta factories faces compressed margins from natural gas price volatility during energy market tightening.
France
Public tender frameworks for school nutrition mandate documented supply chain transparency and fortified wheat specifications. EFSA nutritional labeling requirements shape product formulation for institutional channels. The Hauts-de-France region hosts manufacturing capacity serving northern European catering networks with par-cooled formats.
Food Service Pasta Market Key Industry Players
Capital-heavy millers with captive durum wheat sourcing compete with asset-light brand licensors and regional extrusion specialists across fragmented procurement channels. The vendor base splits between vertically integrated agricultural processors controlling upstream grain supply and contract manufacturers serving private-label restaurant programs. Three archetypes dominate: heritage Italian houses with bronze-die certification, North American bulk suppliers to institutional feeding programs, and diversified European food conglomerates with geographic portfolio balancing. Competitive moves concentrate on direct sourcing agreements with multi-unit restaurant groups and heat pump drying retrofits to satisfy tightening emissions benchmarks.
Among heritage Italian producers, F.lli De Cecco di Filippo SpA and Barilla G. E R. Fratelli Spa exemplify the premium-tier archetype through their geographic naming and generational corporate structures. Ebro Foods S.A. represents the diversified European conglomerate model with its Spanish corporate suffix and multinational positioning. Dakota Growers Pasta Company, Inc. anchors the North American institutional specialist segment through its regional naming and incorporated structure targeting bulk-format procurement channels.
| Leading Market Players |
|---|
| F.lli De Cecco di Filippo SpA |
| Armanino Foods of Distinction, Inc. |
| Barilla G. E R. Fratelli Spa |
| M. Dias Branco |
| Dakota Growers Pasta Company, Inc. |
| Ebro Foods S.A. |
| Ajinomoto Co. Inc. |
| MAKFA |
| Nestlé |
| Others |
Cost & Logistics Intelligence
Multi-unit restaurant groups with 50-plus unit footprints concentrate procurement leverage, anchoring contract-based pricing that trades volume commitments against per-unit premiums for custom die specifications and certified durum formulations.
Pricing Analysis
Cook-yield consistency anchors value-based pricing, with operators paying premiums for semolina formulations that deliver predictable al dente texture under variable kitchen conditions. Pricing stratifies across bronze-extruded heritage tiers, commodity Teflon-die volumes, and par-cooled ready-to-cook convenience formats. Cost compression in bulk institutional channels is intensifying because USDA commodity procurement rules cap allowable premiums for fortified pasta specifications. School nutrition programs exhibit highest price sensitivity, while upscale dining groups in Milan and Rome demonstrate lowest sensitivity to per-unit premiums for artisanal certification.
Supply Chain Analysis
Regional distribution centers in the US Northeast and Midwest aggregate procurement through purchasing cooperatives that bypass traditional broadline distributor markups. Supply concentrates in Italy, the United States, and Spain, with durum wheat milling anchored in the Emilian corridor, North Dakota-Minnesota corridor, and Ebro River valley respectively. Manufacturing draws from concentrated Mediterranean durum wheat cultivation, natural gas-dependent thermal drying infrastructure, and bronze or Teflon die extrusion equipment. Single-source vulnerability runs through Italian heritage mills controlling premium bronze-die capacity. Distribution feeds from mill-direct arrangements and broadline wholesaler networks serving fragmented independent operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Heat pump drying retrofits are displacing legacy natural gas thermal infrastructure, compressing payback periods while satisfying EU F-Gas Regulation compliance timelines.
For Market Incumbents: Deploy heat pump drying retrofits to defend margin position against natural gas price volatility and tightening EU emissions benchmarks. Barilla's backward integration into durum wheat milling offers a template for securing captive semolina supply against climate-driven yield fluctuations. Incumbents should consolidate certification investment in CSRD-aligned supply chains to maintain preferred supplier status with ESG-mandated institutional buyers. For New Entrants and Emerging Players: Independent restaurant purchasing cooperatives in the US Midwest represent an underserved buyer archetype with aggregated volume but fragmented supplier relationships. Contract catering operators in Germany and France prioritize portion uniformity and extended hold stability over per-unit cost premiums, creating white-space for par-cooled format specialists. New entrants should anchor go-to-market strategy through direct sourcing agreements that displace traditional broadline intermediation. For Investors and Strategic Acquirers: The window for entry favors regional millers with installed bronze-die capacity and established direct relationships with multi-unit restaurant groups. Acquisition targets should demonstrate viable heat pump drying conversion pathways and documented supply chain transparency aligned with tightening EU sustainability disclosure requirements. Watch for F-Gas Regulation enforcement acceleration as inflection indicator for stranded asset risk in legacy thermal infrastructure.| Strategic Initiative | Industry Significance |
|---|---|
| Heat Pump Drying Retrofit | EU F-Gas Regulation compliance buffers manufacturers against natural gas price volatility in Italian and Spanish production clusters. |
| CSRD-Aligned Supply Chain Certification | Early adoption opens preferred supplier status with ESG-mandated institutional buyers in German and French procurement channels. |
| Direct Sourcing Agreement | Restaurant groups with 50-plus unit footprints negotiate custom die shapes and protein specifications, bypassing distributor markups. |
| Backward Integration into Durum Wheat Milling | Captive semolina supply secures consistent raw material access against climate-driven yield fluctuations in Mediterranean growing regions. |
| Par-Cooled Format Development | Labor-strapped operators in North American hospital and school feeding programs trade per-unit premiums for kitchen efficiency gains. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs, combining primary interviews with restaurant procurement directors, mill operations managers, contract catering executives, and broadline distributor category buyers with secondary validation from FDA fortification standards, EU Farm to Fork Strategy documentation, and USDA commodity procurement rules. Bottom-up volume modeling triangulated against top-down market sizing from trade association shipments and customs export records.
Reconciliation of production capacity data, import-export flows, and end-use consumption patterns shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, end-user channel, packaging format, and distribution pathway, with additional granularity on die material certification and wheat origin specifications. CAGRs were derived from trend extrapolation of historical volume trajectories adjusted for regulatory phase-in timelines and technology adoption curves. Forecast inputs incorporated energy price scenarios and durum wheat yield variability from Mediterranean climate patterns.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EU Green Deal enforcement acceleration, natural gas price volatility, and alternative grain substitution rates in institutional feeding programs. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service
Europe Cloud Kitchen Market
Food Service
Global Vending Machine Market
Food Service
Europe Inflight Catering Market
Food Service
Global Online Food Ordering Market
Food Service
Commercial Grills Market
Food Service
Takeout Dinner Market
Food Service
Restaurant Takeout Market
Food Service
Food Service Market
Food Service
Global Meal Kit Market
Food Service
Cambodia Foodservice Market
Food Service
Oman Food Service Market
Food Service
Bahrain Food Service Market
Food Service
Meal Voucher Market
Food Service
Canada Food Service Market
Food Service
Air Fryer Market
Food Service
Contract Catering Market