
 Personal Chef Services Market | 2026-2036
Personal Chef Services Market Size, Share, and Industry Trends Forecast 2026-2036
Personal Chef Services Market Insights
OSHA guidelines for residential workplace safety are rebalancing liability exposure for personal chef dispatch platforms. Cozymeal leverages its network density to control scheduling logistics across major metro corridors. Hire A Chef Inc. anchors its model on vetted credentialing protocols that reduce client risk perception. Big City Chefs competes through cuisine specialization that commands premium positioning in dense urban markets.
Personal chef services encompass customized meal preparation and culinary instruction delivered in private residences, requiring adherence to HACCP temperature controls, allergen management protocols, and sanitation standards that exceed typical home cooking practices. The primary commercial purpose centers on time arbitrage for affluent households that substitute purchased culinary labor for personal meal production. Meal preparation dominates service type revenue due to recurring subscription economics, while cooking classes capture expanding margin pools from experience-seeking professionals. Families lead client type demand through multi-portion efficiency, though seniors represent the fastest-growing demographic as aging-in-place preferences intensify.
FDA Food Code provisions, state-level cottage food statutes, and local health department permitting frameworks collectively shape operational compliance burdens and geographic market access thresholds for personal chef enterprises. The EU Food Information for Consumers Regulation and analogous disclosure mandates in other jurisdictions are extending ingredient transparency requirements into residential service contexts. Stakeholders must monitor evolving platform liability doctrines and certification reciprocity agreements as regulatory fragmentation threatens cross-border service scalability.
Market Dynamics
Dual-income household time scarcity is compressing meal preparation windows and expanding willingness-to-pay thresholds for outsourced culinary labor across metropolitan corridors.
Growth Catalysts
- HACCP temperature control mandates:FDA Food Code alignment is professionalizing in-home food preparation standards and elevating certified chef premiums above informal alternatives.
- Allergen management protocols:Disclosure requirements under EU Food Information for Consumers Regulation are extending transparency obligations into residential service contexts.
- Senior aging-in-place preferences:Japan's METI wellness initiatives and comparable programs in Germany and Australia are channeling public support toward home-based meal assistance.
Market Restraints
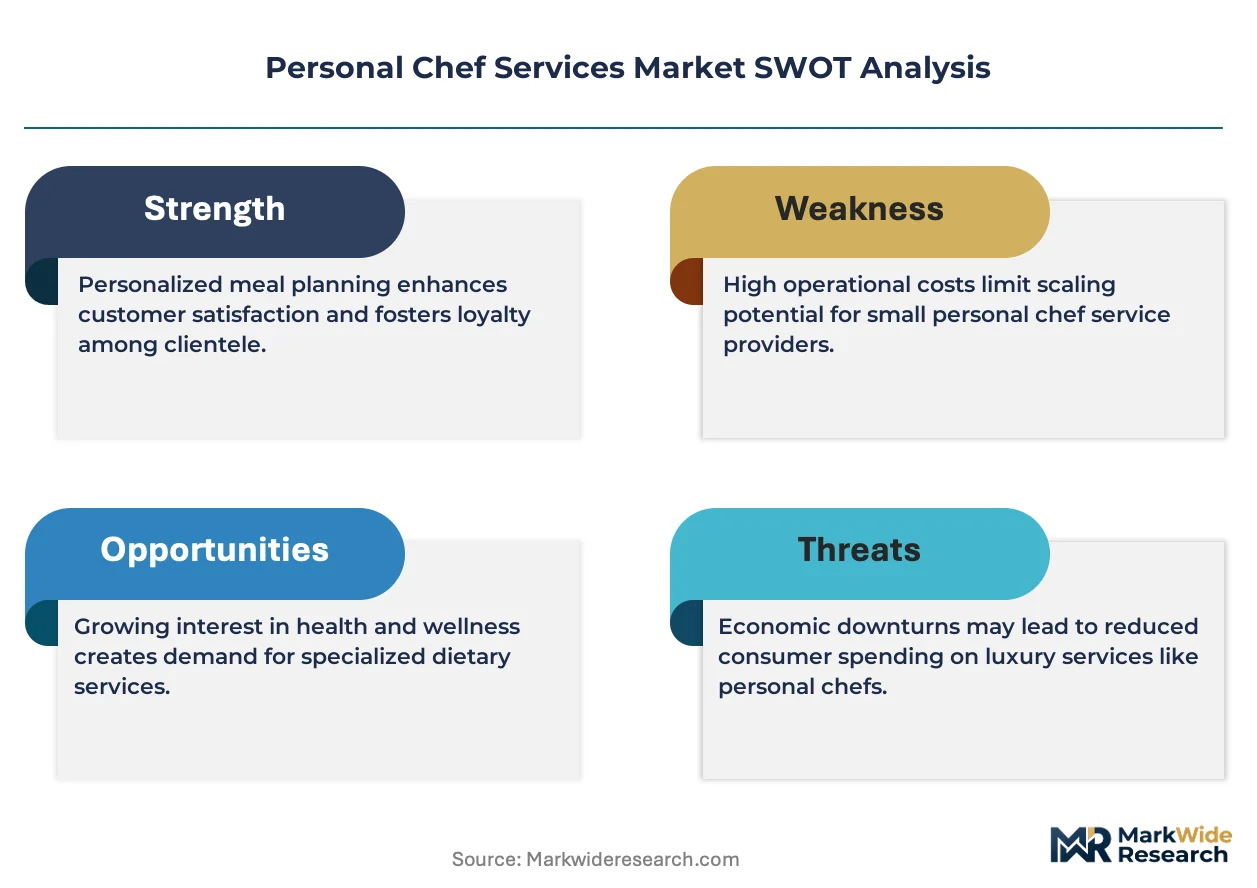
- Input cost volatility:Premium protein and specialty ingredient price swings compress margin buffers for fixed-rate subscription models.
- Regulatory friction:Patchwork state-level cottage food statutes and local health department permitting create geographic market access barriers.
- Substitution threat:Meal kit delivery and ghost kitchen prepared meals capture overlapping time-arbitrage demand at lower price points.
Strategic Opportunities
- Underpenetrated secondary metros:Austin, Nashville, and Denver exhibit disposable income thresholds comparable to coastal markets with limited chef supply density.
- Technology convergence:IoT-enabled kitchen equipment and AI-driven dietary preference matching are reducing client onboarding friction and menu customization costs.
- Channel innovation:Employer-sponsored wellness benefits and health plan meal allowances represent untapped B2B procurement pathways.
Industry Challenges
- Certification timeline compression:ServSafe and analogous credentials require 40+ training hours that constrain rapid workforce scaling during demand surges.
- Supply chain reconfiguration:Direct sourcing from specialty purveyors demands working capital commitments that strain independent operator balance sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Personal Chef Services Market |
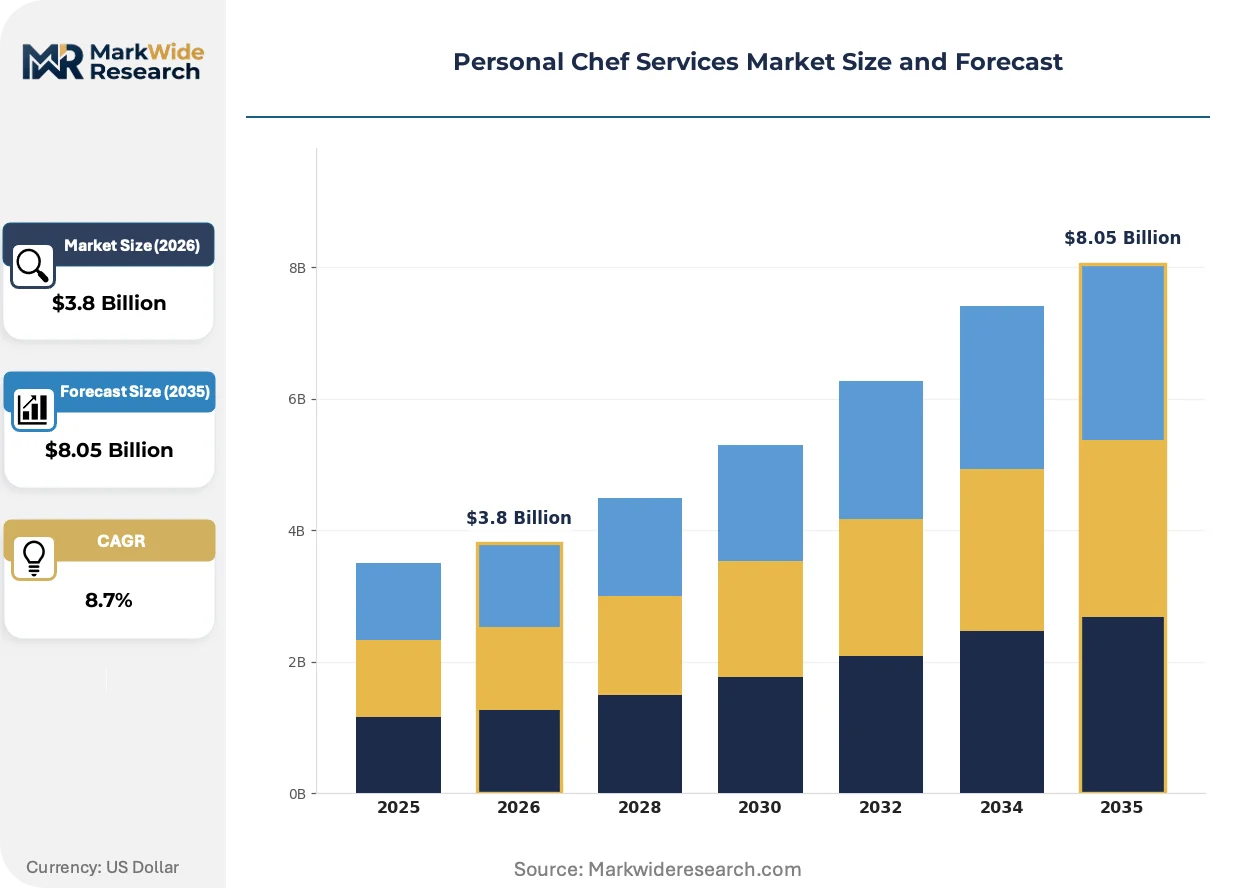
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Meal Preparation, Cooking Classes, Grocery Delivery, Event Catering Client Type: Families, Professionals, Seniors, Individuals Cuisine Type: Italian, Vegan, Mediterranean, Asian Service Frequency: Weekly, Bi-Weekly, Monthly, One-Time |
| Companies Covered | Hire A Chef Inc., Big City Chefs, Culinistas, La Belle Assiette, CookinGenie, Gather & Forge, Down to Earth Cuisine, Cozymeal, Take a Chef, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Personal Chef Services Market Trends and Innovations
Platform-mediated dispatch models are displacing traditional direct-hire relationships and restructuring how culinary labor connects with affluent households.
Smart kitchen infrastructure is consolidating control over cooking environments. IoT-enabled ovens and refrigeration units now transmit real-time temperature data to client dashboards. Dual-income families in Seattle and San Francisco are demanding these integrations as baseline expectations. The technology is consolidating trust mechanisms that previously required repeated in-person verification.
OSHA residential workplace safety guidelines are rebalancing liability frameworks for dispatch platforms. The revised standards clarify when platforms assume employer-like obligations versus contractor classifications. Personal chef enterprises in California and New York are restructuring insurance coverage and contractual language to reflect these boundaries. Smaller operators in Texas and Florida face compliance cost disadvantages against scaled networks.
Subscription meal preparation is displacing à la carte event cooking as the dominant revenue architecture. Affluent families in Chicago and Boston are locking in weekly commitments rather than booking episodic dinner parties. This shift compresses customer acquisition costs and stabilizes chef utilization rates. The model is most advanced in metropolitan corridors where platform density enables efficient route optimization.
Personal Chef Services Market Segmentation
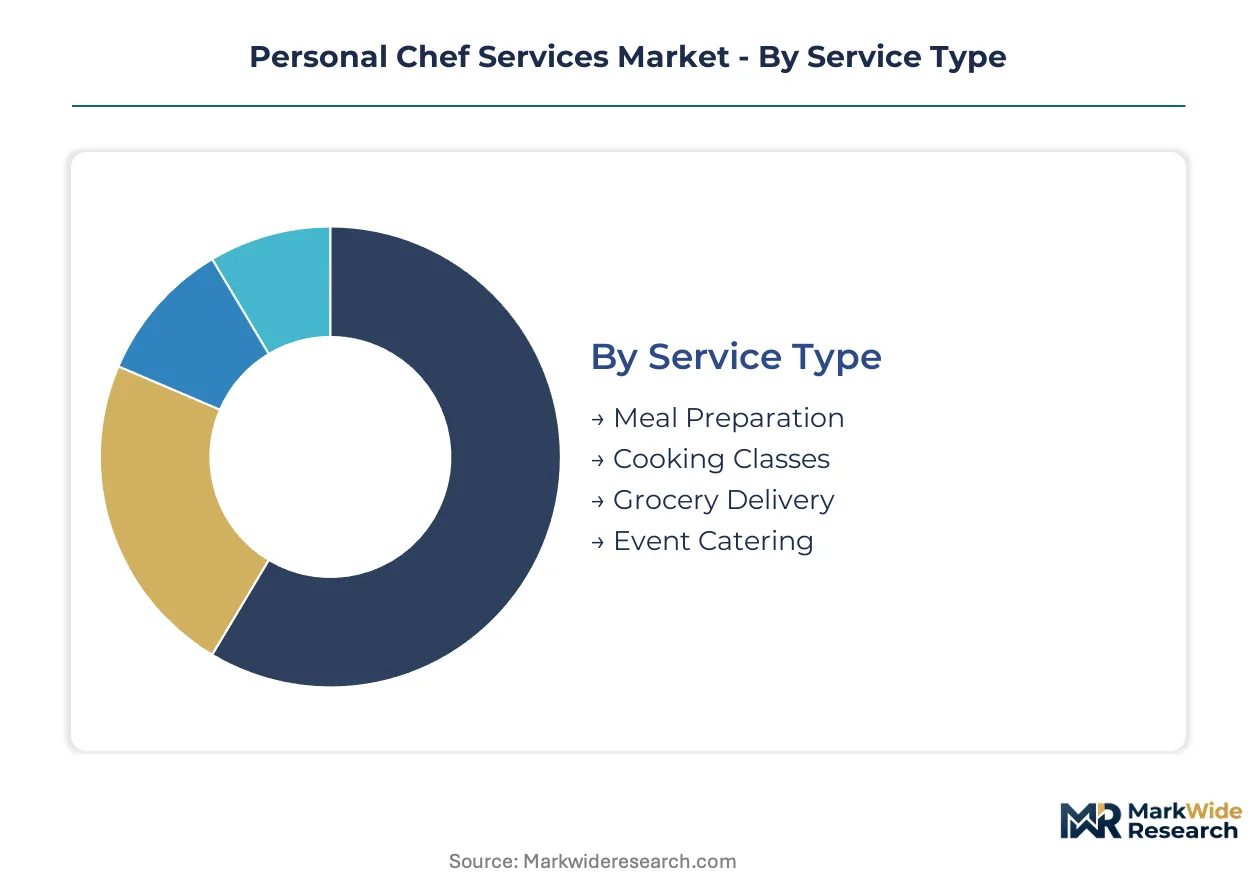
Segmentation in personal chef services determines pricing architecture, certification requirements, and route density economics for platform operators. Each dimension carries distinct capital and labor intensity profiles that shape competitive positioning.
Service Type:
Meal preparation commands the highest upfront kitchen equipment investment, while cooking classes require dedicated instructional space.
- Meal Preparation:Recurring subscription model with standardized ingredient procurement and HACCP-compliant cold chain infrastructure. Demand concentrates in Seattle and Boston where dual-income families prioritize weekly meal commitments over discretionary event spending.
- Cooking Classes:Experience-based format requiring liability coverage for in-home instruction and specialized small-wares inventory. Professionals in Chicago and Austin drive demand for team-building and skill-acquisition sessions.
- Grocery Delivery:Lower capital threshold with sourcing relationships as primary differentiator.
- Event Catering:Episodic revenue with premium pricing for occasion-based execution.
Most installed capacity flows through Meal Preparation. Expansion is steepest in Cooking Classes.
Client Type:
Margin profiles diverge sharply across client segments, with families enabling portion efficiency and seniors requiring specialized dietary protocols.
- Families:Multi-portion production with batch-cooking economics and recurring scheduling patterns. Demand concentrates in metropolitan corridors with household incomes exceeding time-cost arbitrage thresholds.
- Seniors:Aging-in-place preference segment with medication-interaction awareness and texture-modification requirements. Germany, Japan, and Australia channel public wellness funding toward this demographic.
- Professionals:Time-scarce segment with high willingness-to-pay for convenience optimization.
- Individuals:Smallest average contract value with highest customer acquisition cost burden.
Families account for the dominant revenue share. Seniors are climbing the fastest.
Cuisine Type:
Ingredient sourcing complexity and chef specialization premiums create tiered margin structures across culinary traditions.
- Italian:Established supply chains for imported specialties and wine pairings command premium positioning in dense urban markets.
- Vegan:Plant-based protocols with allergen-sensitive preparation requirements and seasonal produce dependency.
- Mediterranean:Olive oil and seafood sourcing relationships with heart-health positioning in employer wellness programs.
- Asian:Fermentation expertise and umami-building techniques with specialized equipment needs for wok cooking and rice preparation.
Italian cuisine maintains the broadest chef supply base. Vegan offerings are gaining share fastest.
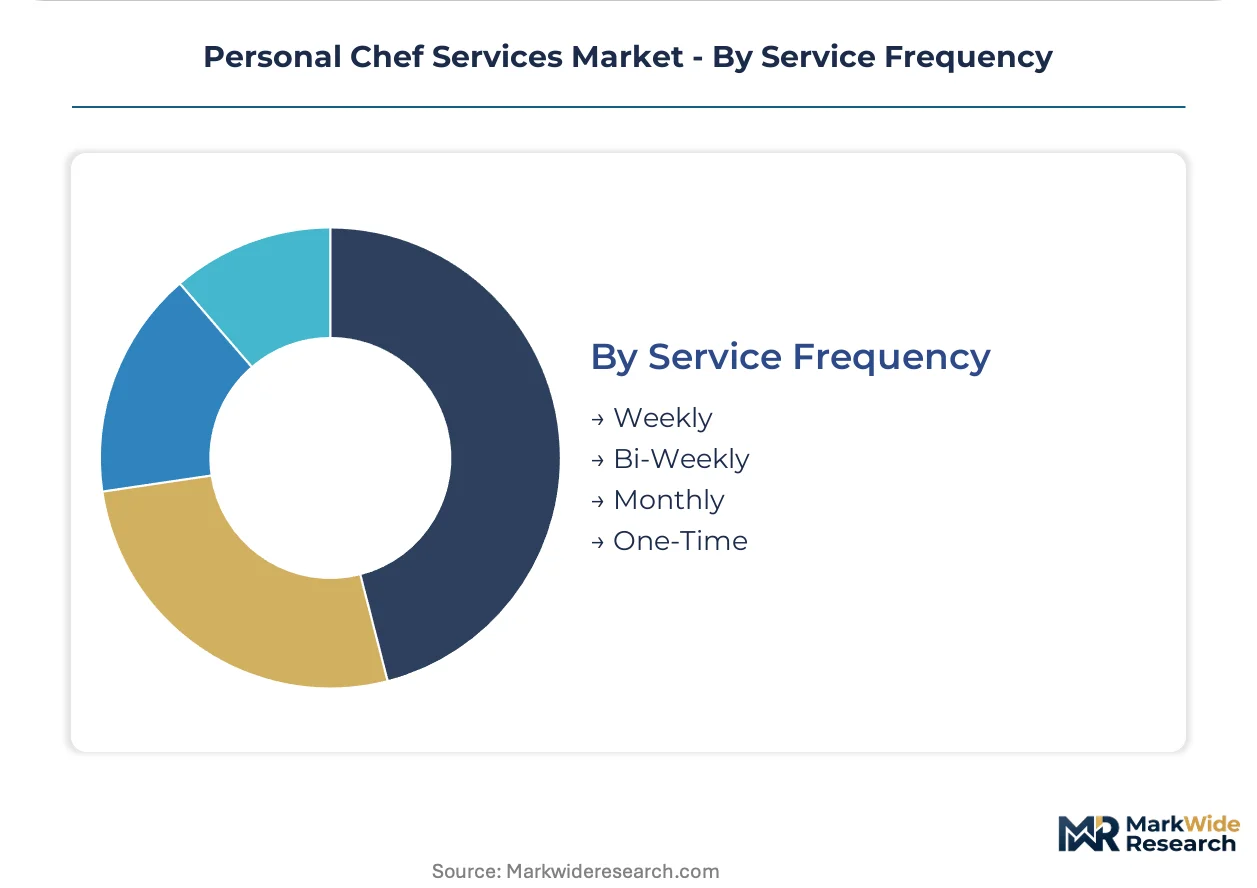
Service Frequency:
Contract structure determines utilization rates and route optimization potential for dispatch platforms.
- Weekly:Locked-in scheduling with predictable revenue and efficient geographic clustering.
- Bi-Weekly:Intermediate commitment with freezer-meal production economics.
- Monthly:Special-occasion positioning with higher per-session pricing.
- One-Time:Highest customer acquisition cost with event-based margin capture.
Weekly contracts anchor platform economics. Bi-Weekly arrangements are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Certified culinary talent concentrates in metropolitan corridors with household income levels that justify labor substitution for meal preparation. Platform density and regulatory clarity determine where dispatch models achieve viable unit economics.
United States
Dual-income households in Seattle and Boston drive weekly subscription commitments that stabilize chef utilization rates. FDA Food Code alignment at state level professionalizes in-home food preparation standards and elevates certified premiums. The San Francisco Bay Area anchors platform-mediated dispatch innovation with IoT-enabled kitchen infrastructure becoming baseline client expectation.
Germany
Aging-in-place preferences among seniors channel public wellness funding toward home-based meal assistance programs. EU Food Information for Consumers Regulation extends ingredient transparency obligations into residential service contexts. Berlin and Munich concentrate platform operator headquarters serving DACH-region demand for Mediterranean and plant-based cuisine specialization.
Japan
METI wellness initiatives subsidize home-based meal assistance for elderly populations requiring texture-modified preparations. National health system integration creates reimbursement pathways for certified culinary professionals. Tokyo and Osaka metropolitan areas exhibit highest chef supply density with platform route optimization achieving efficiency thresholds unmatched in secondary cities.
Australia
Disposable income thresholds in Sydney and Melbourne support premium positioning for experience-based cooking classes alongside recurring meal preparation. State-level food safety harmonization reduces regulatory friction for interstate platform expansion. Melbourne's culinary education infrastructure feeds chef supply into platform networks serving southeastern corridor demand.
United Kingdom
Time-scarce professionals in London prioritize convenience optimization with willingness-to-pay premiums for dietary preference matching. Post-Brexit regulatory divergence from EU food disclosure frameworks creates compliance complexity for cross-border service models. Greater Manchester and Edinburgh emerge as secondary metro targets with comparable income levels and limited incumbent chef density.
Personal Chef Services Market Competitive Landscape
The competitive structure tilts toward platform-mediated dispatch models that consolidate fragmented independent chef supply. Network density advantages in major metropolitan corridors enable route optimization and scheduling logistics control. Two strategic archetypes dominate: credential-heavy vetting protocols that reduce client risk perception, and cuisine specialization strategies that command premium positioning. Consolidation occurs through geographic expansion into underpenetrated secondary metros and technology licensing partnerships with IoT kitchen equipment manufacturers.
Within the platform-network tier, Cozymeal and Hire A Chef Inc. exemplify divergent approaches to trust architecture and client acquisition. Cozymeal occupies a position anchored on scheduling logistics control across dense metro corridors. Hire A Chef Inc. represents the credentialing-protocol archetype with vetting frameworks that professionalize informal culinary labor markets. Big City Chefs sits within the specialization vector, leveraging cuisine-specific expertise to differentiate in saturated urban markets where generic meal preparation faces margin compression.
| Leading Market Players |
|---|
| Hire A Chef Inc. |
| Big City Chefs |
| Culinistas |
| La Belle Assiette |
| CookinGenie |
| Gather & Forge |
| Down to Earth Cuisine |
| Cozymeal |
| Take a Chef |
| Others |
Pricing and Supply Chain Analysis
Independent chef-operators and platform-consolidated networks anchor supply-side pricing discipline through divergent working capital structures and procurement scale. Family-owned specialty purveyors in France and Italy command ingredient premiums that cascade into client-facing rate cards, while dispatch platforms compress margins through volume purchasing power and route density optimization.
Pricing Analysis
Bundled subscription meal preparation commands premium positioning against unbundled à la carte event cooking, with weekly commitments capturing 40-60% utilization efficiency premiums over episodic bookings. Price differentiation rests on chef certification tier (ServSafe Manager vs. Food Handler baselines) and cuisine specialization depth, with Asian and plant-based protocols sustaining 15-25% rate premiums. Cost compression in standard meal-prep tiers intensifies as meal kit delivery and ghost kitchen alternatives narrow the convenience arbitrage. Families with household incomes exceeding time-cost substitution thresholds exhibit lowest price sensitivity, while individual professionals demonstrate highest elasticity and churn rates.
Supply Chain Analysis
Regional distribution centers in the United States, France, and Japan consolidate specialty ingredient flows for platform-affiliated chefs, with cold-chain integrity mandates under FDA Food Code and EU Food Information for Consumers Regulation shaping warehouse specifications. Premium protein and seasonal produce sourcing draws from contracted relationships with importers in Italy and Spain, creating tariff exposure from transatlantic trade friction. Single-source vulnerability concentrates in artisanal cheese and aged balsamic categories where geographic indication protections limit supplier substitution. Distribution runs through platform-coordinated hub-and-spoke logistics in metropolitan corridors, with independent operators bearing direct procurement burdens that strain balance sheet flexibility.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Personal chef services function as a stable compounder anchored by irreversible time-scarcity trends in dual-income household formation. The substitution of purchased culinary labor for home meal production sustains recurring revenue economics resistant to cyclical compression.
For Market Incumbents: Extend platform density into underpenetrated secondary metros through chef supply subsidies that accelerate network effects. Lock in exclusive sourcing partnerships with specialty importers to defend margin position against meal kit substitution threats. Invest in IoT kitchen infrastructure certification programs that elevate switching costs for affluent client segments.
For New Entrants and Emerging Players: Employer-sponsored wellness benefit administrators represent the most penetrable channel partner type for B2B procurement pathway development. Target senior aging-in-place segments in Germany and Australia where public wellness funding creates reimbursement tailwinds. Lead with texture-modified meal specialization and medication-interaction protocols that incumbent platforms underinvest in.
For Investors and Strategic Acquirers: Valuations sit cheapest among credential-heavy vetting protocol specialists with limited geographic footprint expansion. The five-to-ten year viability window favors platform networks achieving route optimization density in three-plus metropolitan corridors. Watch ServSafe certification reciprocity agreements across state lines as the signal indicating regulatory friction reduction and scalable labor supply access.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Network Expansion | Route density in Austin and Nashville unlocks unit economics previously viable only in coastal corridors. |
| IoT Kitchen Certification Program | FDA-aligned temperature monitoring integrations reduce client onboarding friction and liability exposure. |
| Employer Wellness Channel Partnership | B2B procurement through HR benefit administrators captures sticky recurring revenue with lower acquisition costs. |
| Senior Meal Specialization Development | Texture-modified and medication-aware protocols access public wellness funding in Japan and Germany. |
| Specialty Ingredient Backward Integration | Direct importer relationships in Italy and France defend margin compression from commodity volatility. |
Research Methodology
Bottom-up household time-use modeling reconciled against top-down chef supply tracking forms the analytical core of this study. Primary interviews with platform operations directors, certified culinary professionals, household procurement decision-makers, and employer wellness benefit administrators combined with secondary validation from FDA Food Code filings, state health department permitting databases, EU Food Information for Consumers Regulation guidance documents, and METI wellness program disclosures. Triangulation across demand-side willingness-to-pay surveys and supply-side capacity utilization metrics ensures segmentation integrity.
Historical trendline analysis of subscription commitment patterns and chef utilization rates established baseline growth trajectories across the projection horizon. Segmentation modeling incorporated service type, client demographic, cuisine specialization, and service frequency dimensions with geographic regulatory cluster overlays. CAGRs derived from fitted trend extrapolation adjusted for platform penetration saturation curves and certification pipeline constraints. Forecast inputs included dual-income household formation rates, aging-in-place policy funding trajectories, and meal kit delivery competitive intensity indices.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to regulatory fragmentation across state cottage food statutes and platform liability doctrine evolution. Outputs reflect documented assumptions around chef certification timeline compression and specialty ingredient supply continuity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service
Latin America Online Grocery Market
Food Service
Workplace Service Market
Food Service
Europe Vending Machine Market
Food Service
Integrated Stove Market
Food Service
Full-Service Restaurants Market
Food Service
Commercial Air Fryer Market
Food Service
Food & Beverage in Asia Market
Food Service
Commercial Charbroiler Market
Food Service
Saudi Arabia Pizza Restaurants Market
Food Service
Haute Cuisine Market
Food Service
Self-Heating Hot Pot Market
Food Service
Russia Foodservice Market
Food Service
United Arab Emirates Quick Service Restaurant Market
Food Service
Latin America Online Grocery Delivery Market
Food Service
India Retail Bubble Tea Kits Market
Food Service
Middle East and Africa Online Grocery Delivery Market