
 Food & Beverage in Asia Market | 2026-2036
Food & Beverage in Asia Market Size, Share, and Industry Trends Forecast 2026-2036
Food & Beverage in Asia Market Insights
Premium nutrition positioning is decoupling from commodity-grade food and beverage production across Asia. Yili leverages its Mongolian grassland sourcing to sustain a premium dairy identity that commands shelf-space premiums in tier-one Chinese cities. Wahaha competes through dense distribution control, occupying over two million rural and urban retail points that block challenger brand access. Jollibee navigates this split by positioning its QSR menu as accessible comfort food in the Philippines while exporting higher-margin specialty sauces to Middle Eastern diaspora markets.
Food and beverage in Asia encompasses the processing, preservation, packaging, and distribution of edible goods and drinkable liquids, spanning everything from UHT milk sterilization at 135-150°C for 1-5 seconds to nitrogen-flushed snack packaging that extends shelf life to twelve months. Dairy and beverages together anchor the largest margin pools, with yogurt and functional drinks capturing disproportionate value as health-conscious urban consumers trade up from plain white milk. Online retail and food service distribution channels are expanding fastest, though supermarkets still dominate absolute transaction volume across Japan, South Korea, and coastal China.
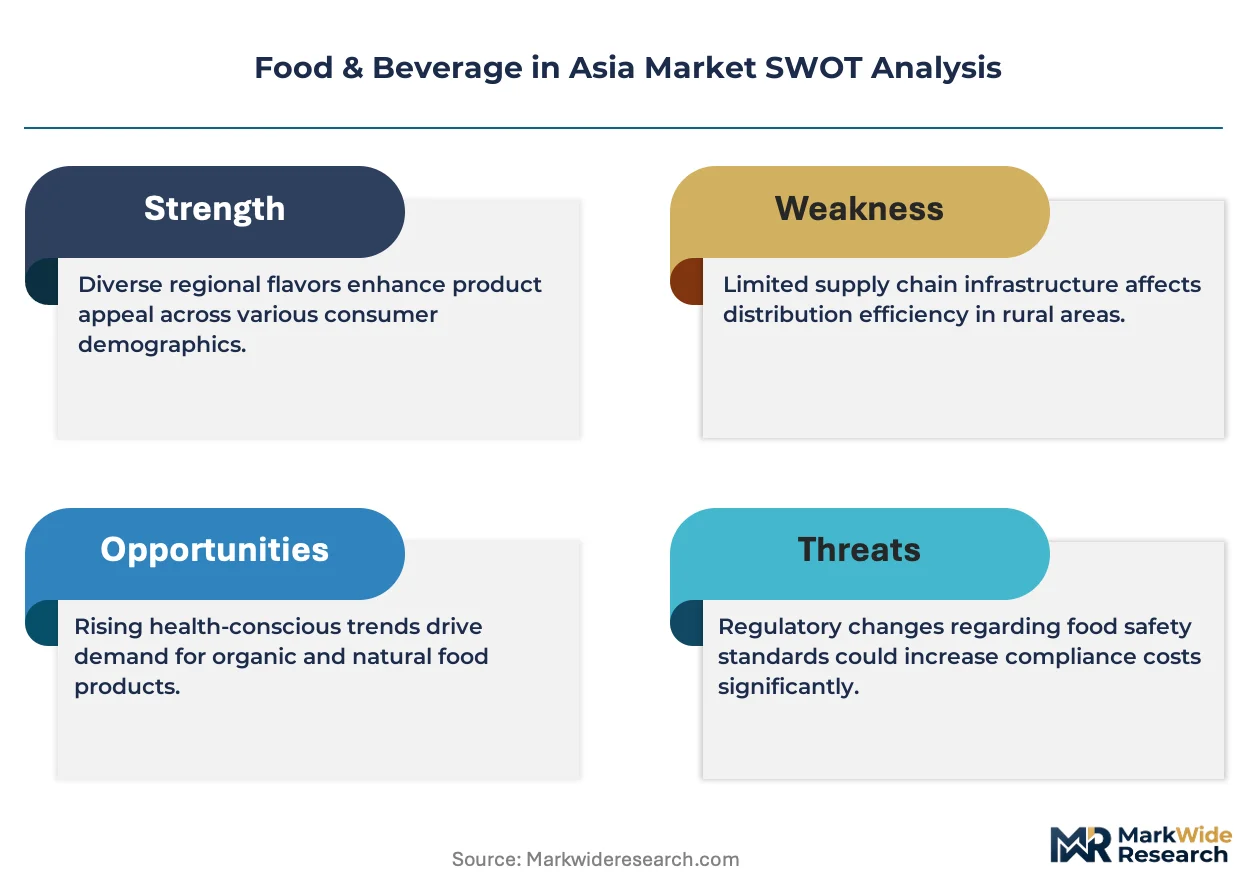
FSSAI in India enforces incremental fortification mandates for edible oils and milk, while China's SAMR tightens GB standard compliance timelines for imported infant formula and health foods. Japan's Consumer Affairs Agency and METI coordinate on GMO labeling and plastic packaging reduction targets that reshape formulation and material choices for exporters. Stakeholders must monitor how divergent national implementation speeds of these standards fragment cross-border product platform strategies.
Market Dynamics
China's SAMR enforcement of stricter GB food labeling standards is forcing simultaneous reformulation across multinational packaged food portfolios and creating compliance cost asymmetries between domestic and imported brands. This regulatory compression cascades through supply chains as manufacturers race to meet divergent national implementation timelines.
Growth Catalysts
- Urban retail penetration:Organized retail expansion in India's Mumbai, Delhi, and Bangalore clusters is concentrating demand for branded packaged foods and driving cold-chain infrastructure investment.
- FSSAI fortification mandates:India's edible oil and milk fortification requirements are creating mandatory volume pulls for micronutrient premix suppliers and reformulation service providers.
- QSR procurement scaling:Southeast Asian quick-service restaurant chains are accelerating purchases of ready-to-cook sauces and frozen dim sum to standardize kitchen operations across franchise networks.
Market Restraints
- Palm oil price volatility:Input cost swings for Asia's dominant cooking oil constrain margin predictability for snack and instant noodle manufacturers.
- Import dependency for dairy proteins:Southeast Asian markets rely on concentrated New Zealand and Australian whey supply, exposing processors to currency and freight shocks.
- Technical shelf-life limitations:Clean-label reformulations struggle to match the twelve-month stability of nitrogen-flushed conventional packaging without synthetic preservatives.
Strategic Opportunities
- Secondary city expansion:Vietnam's Da Nang and Indonesia's Surabaya represent underpenetrated zones where modern trade penetration remains below twenty percent.
- Functional beverage convergence:Probiotic and adaptogen ingredient technologies are merging with traditional herbal formulations to capture wellness-oriented consumers.
- Japan's plastic reduction targets:METI packaging mandates are accelerating demand for biodegradable films and refill station infrastructure investments.
Industry Challenges
- Food technologist scarcity:Formulation expertise for clean-label and allergen-free product development outpaces Southeast Asian university pipeline output.
- Legacy ERP integration:Track-and-trace compliance with China's GB standards requires costly retrofitting of batch recording systems at mid-tier processors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Food & Beverage in Asia Market |
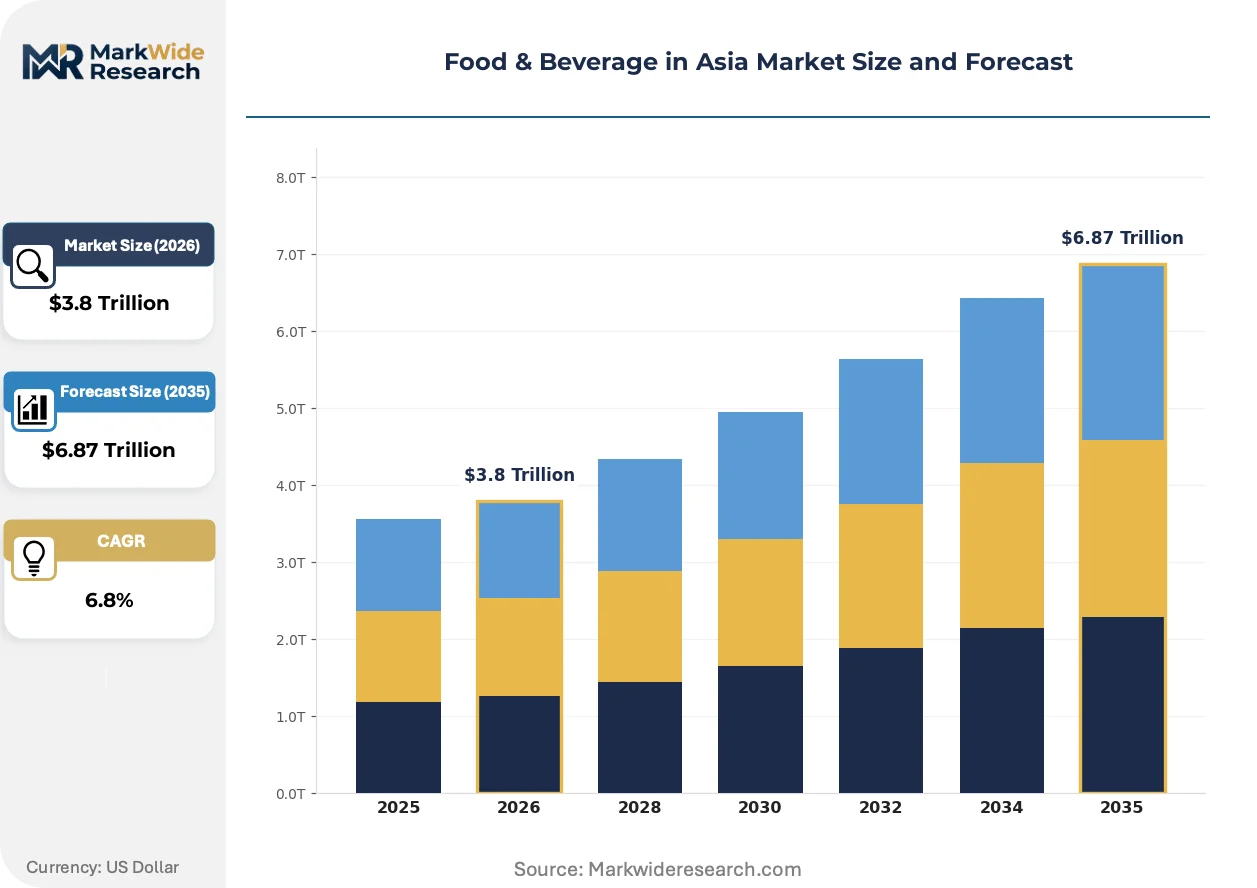
| Market Size in 2026 | $3.8 Trillion |
| Market Size in 2035 | $6.87 Trillion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dairy, Beverages, Snacks, Packaged Foods Distribution Channel: Supermarkets, Online Retail, Convenience Stores, Food Service Customer Type: Retail Consumers, Restaurants, Wholesalers, Institutions End Use Industry: Catering, Hospitality, Retail, Manufacturing |
| Companies Covered | Uni-President, Wahaha, Yili, Master Kong, Wuliangye Yibin, Zhejiang Hengyi Group, New Hope Group, Jollibee, WH Group, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Food & Beverage in Asia Market Trends and Innovations
Reformulation pressures and channel fragmentation are compressing product development cycles while expanding the technical capabilities required for market access. The intersection of regulatory compliance and consumer preference shifts is redrawing competitive boundaries.
High-pressure processing technology is absorbing capital investment from premium juice and ready-meal manufacturers seeking extended chilled shelf life without thermal degradation. Japanese and South Korean retailers are adopting HPP-treated products at accelerated rates to differentiate fresh assortments. This capital absorption is compressing returns for conventional thermal processing equipment suppliers.
Japan's Consumer Affairs Agency coordination with METI on GMO labeling and plastic packaging reduction targets is reshaping material sourcing decisions for exporters serving the Japanese market. Manufacturers must now dual-source film substrates and reformulate around approved ingredient lists. Infant formula and health food categories face the tightest compliance windows and highest certification costs.
Direct-to-restaurant procurement platforms are disintermediating traditional distributor layers in Southeast Asian food service supply chains. Cloud kitchens and independent restaurant operators in Bangkok and Jakarta now source frozen dim sum and cooking bases through mobile ordering interfaces. This channel shift is most visible in Vietnam's Ho Chi Minh City cluster where distributor margins face sustained compression.
Food & Beverage in Asia Market Segmentation
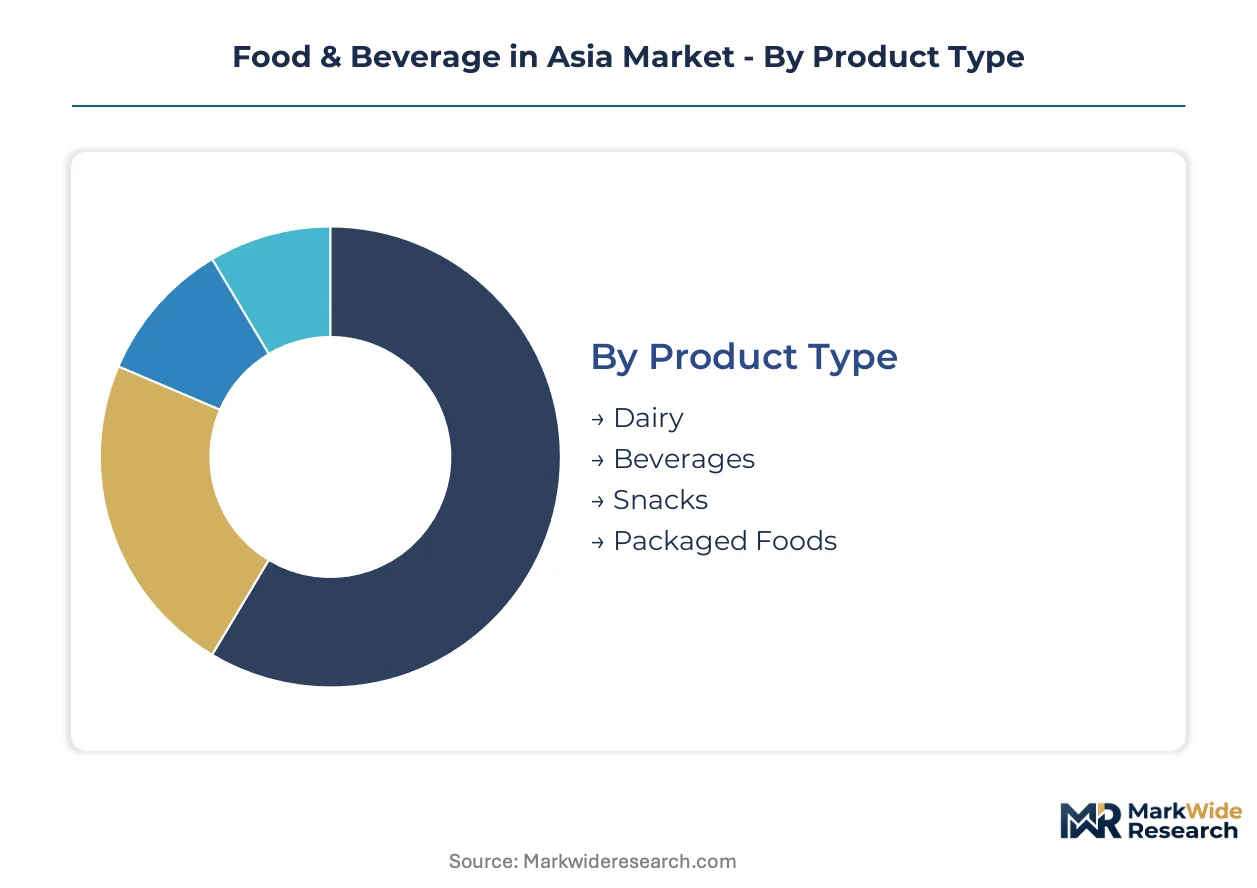
Segmentation in Asia's food and beverage sector reveals how regulatory burdens and channel economics concentrate margin capture. Certification requirements from China's SAMR, India's FSSAI, and Japan's Consumer Affairs Agency fragment product platforms across these divides.
Product Type:
Dairy and beverages carry the heaviest certification loads, with infant formula facing China's GB standard compliance timelines and FSSAI fortification mandates governing edible oils and milk.
- Dairy:UHT sterilization at 135-150°C anchors liquid milk production, while yogurt and functional dairy drinks command shelf-space premiums in tier-one Chinese cities. SAMR's stricter labeling enforcement is forcing reformulation across multinational portfolios.
- Beverages:Probiotic and adaptogen technologies merge with traditional herbal formulations. High-pressure processing absorbs capital investment from premium juice manufacturers seeking chilled shelf life without thermal degradation.
- Snacks:Nitrogen-flushed packaging extends shelf life to twelve months. Clean-label reformulations struggle to match this stability without synthetic preservatives.
- Packaged Foods:Ready-to-cook sauces and frozen dim sum scale through QSR procurement networks across Southeast Asian franchise operations.
Dairy sits at the top of the volume ranking, with beverages climbing the fastest.
Distribution Channel:
Channel selection determines cold-chain infrastructure requirements and regulatory touchpoint density, with direct-to-restaurant platforms disintermediating traditional layers.
- Supermarkets:Absolute transaction volume dominance persists across Japan, South Korea, and coastal China. Modern trade penetration in Vietnam's Da Nang and Indonesia's Surabaya remains below twenty percent.
- Online Retail:Mobile ordering interfaces now serve cloud kitchens and independent operators in Bangkok and Jakarta. This channel expands fastest alongside food service digitization.
- Convenience Stores:Dense urban networks in Tokyo, Seoul, and Shanghai capture impulse beverage and snack purchases.
- Food Service:Quick-service restaurant chains accelerate procurement of standardized cooking bases to harmonize kitchen operations across franchise networks.
Supermarkets retain volume leadership, though online retail gains share fastest as procurement platforms compress distributor margins.
Customer Type:
Customer scale dictates formulation batch sizes and compliance cost amortization, with institutional buyers absorbing fortification mandates at volume.
- Retail Consumers:Urban clusters around Mumbai, Delhi, and Bangalore concentrate demand for branded packaged foods as organized retail penetration deepens.
- Restaurants:Cloud kitchens in Ho Chi Minh City source frozen dim sum through mobile interfaces, bypassing traditional distributor layers.
- Wholesalers:Legacy ERP systems require costly retrofitting for track-and-trace compliance with China's GB standards.
- Institutions:Schools and hospitals drive mandatory volume pulls for FSSAI-mandated micronutrient premixes in edible oils and milk.
Retail consumers anchor absolute demand, with restaurants expanding most quickly through platform-enabled procurement.
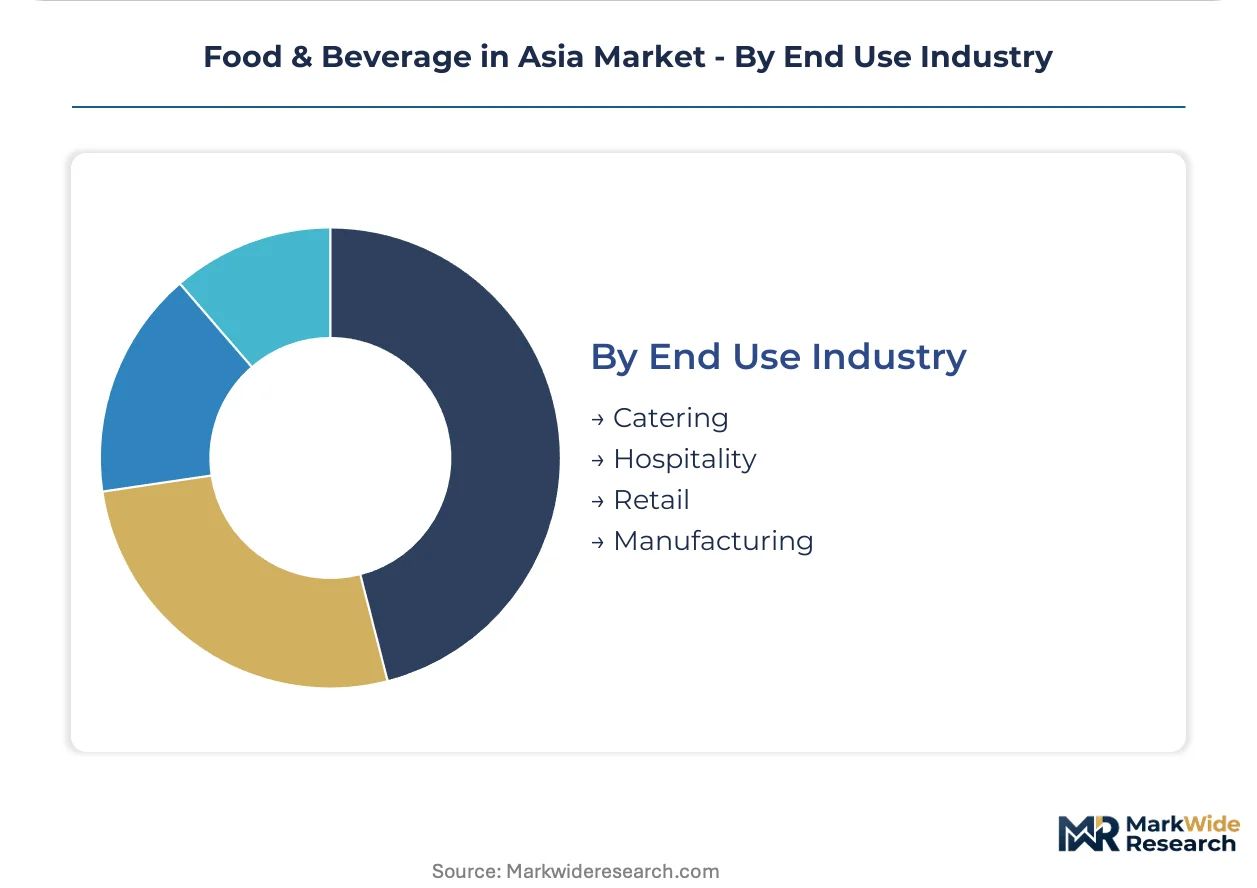
End Use Industry:
End-use application shapes packaging material choices and shelf-life specifications, with Japan's METI plastic reduction targets forcing substrate dual-sourcing.
- Catering:Central kitchen operations demand ready-to-cook sauces with standardized viscosity and flavor profiles across outlet networks.
- Hospitality:Premium positioning requires biodegradable films and refill station infrastructure to satisfy METI compliance windows.
- Retail:Supermarket assortments differentiate through HPP-treated fresh products, compressing returns for conventional thermal processing equipment suppliers.
- Manufacturing:Food technologist scarcity for clean-label and allergen-free development outpaces Southeast Asian university pipeline output.
Retail commands the largest volume position, with manufacturing showing the steepest expansion trajectory as reformulation cycles compress.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China commands the largest absolute food and beverage production capacity across Asia, while India generates the fastest volume growth trajectory among major economies. Regulatory divergence between these markets fragments product platform strategies for multinational portfolios. Cold-chain infrastructure gaps in secondary cities create distribution arbitrage opportunities for regional specialists.
China
Yili and Wahaha anchor tier-one urban demand through divergent positioning strategies, with Mongolian grassland sourcing sustaining premium dairy identity. SAMR enforcement of stricter GB food labeling standards forces simultaneous reformulation across multinational packaged food portfolios. Shanghai and Beijing clusters concentrate health-conscious consumer trading-up from plain white milk to functional dairy drinks.
India
Urban clusters around Mumbai, Delhi, and Bangalore concentrate demand for branded packaged foods as organized retail penetration deepens. FSSAI fortification mandates for edible oils and milk create mandatory volume pulls for micronutrient premix suppliers. Maharashtra and Gujarat host the largest edible oil processing infrastructure serving institutional buyers.
Japan
Consumer Affairs Agency coordination with METI on GMO labeling and plastic packaging reduction targets reshapes material sourcing decisions for exporters. Tokyo and Osaka metropolitan areas drive adoption of HPP-treated fresh products to differentiate supermarket assortments. Kanto region processors dual-source film substrates to satisfy compliance windows for infant formula and health food categories.
Vietnam
Da Nang and Ho Chi Minh City represent underpenetrated zones where modern trade penetration remains below twenty percent. Direct-to-restaurant procurement platforms disintermediate traditional distributor layers in cloud kitchen supply chains. Southern provinces accelerate cold-chain infrastructure investment to support QSR procurement scaling of frozen dim sum.
Philippines
Jollibee positions its QSR menu as accessible comfort food domestically while exporting higher-margin specialty sauces to Middle Eastern diaspora markets. Metro Manila concentrates franchise network expansion for standardized kitchen operations. Luzon-based processors supply ready-to-cook sauces to harmonize outlet network flavor profiles.
Food & Beverage in Asia Market Competitive Landscape
Top-tier vendors anchor premium nutrition positioning, while mid-tier competitors compete through dense distribution control and rural market penetration. The market structure stratifies across three tiers: multinational nutrition platforms with grassland sourcing advantages, national conglomerates with two-million-plus retail point coverage, and regional QSR chains with diaspora export capabilities. Two dominant competitive moves define current dynamics: backward integration into Mongolian and New Zealand dairy supply bases, and strategic partnerships with cloud kitchen procurement platforms to bypass traditional distributor layers.
Within the premium dairy tier, Yili exemplifies grassland-sourced identity commanding shelf-space premiums, while Wahaha occupies a position defined by distribution density blocking challenger brand access. Jollibee sits within the QSR-export archetype, navigating domestic accessibility positioning against higher-margin diaspora market penetration. These three entities represent the strategic divergence between sourcing-based premiumization, channel-based volume defense, and format-based geographic arbitrage that structures competitive interaction across Asia's food and beverage landscape.
| Leading Market Players |
|---|
| Uni-President |
| Wahaha |
| Yili |
| Master Kong |
| Wuliangye Yibin |
| Zhejiang Hengyi Group |
| New Hope Group |
| Jollibee |
| WH Group |
| Others |
Pricing and Supply Chain Analysis
Food technologist scarcity across Southeast Asian universities widens labor-cost differentials between formulation-intensive premium tiers and commodity-grade production, compressing margin spreads as clean-label development cycles lengthen.
Pricing Analysis
The bundled-vs-unbundled service split separates premium dairy with Mongolian grassland provenance from unbranded commodity volumes, with certification-grade infant formula commanding sustained premiums against standard UHT milk. Price differentiation rests on SAMR compliance tier and cold-chain delivery infrastructure, with reformulation service bundling now standard for multinational portfolios. Pricing pressure intensifies in snack and instant noodle segments as palm oil input volatility erodes cost predictability. Institutional buyers in India's edible oil sector show lowest price sensitivity due to FSSAI mandate absorption, while independent cloud kitchens in Ho Chi Minh City exhibit highest sensitivity to cooking base procurement costs.
Supply Chain Analysis
Single-source vulnerability sits with New Zealand and Australian whey concentrate supply feeding Southeast Asian dairy processors. Geographic supply concentration clusters in China for nitrogen-flush packaging equipment, India for edible oil processing infrastructure, and Japan for HPP technology systems. Raw material dependencies span Mongolian grassland dairy, Indonesian palm oil, and Australian whey proteins. Supply chain risk centers on currency-exposure for dairy protein imports. Distribution runs through supermarket networks across Japan, South Korea, and coastal China, with direct-to-restaurant platforms disintermediating traditional layers in Bangkok and Jakarta.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin-expansion pathways through reformulation-service bundling and premium-tier dairy positioning, with clean-label capability scarcity supporting pricing power for qualified suppliers.
For Market Incumbents: Anchor premium positioning through captive Mongolian grassland sourcing that blocks challenger shelf-space access in tier-one Chinese cities. Defend against direct-to-restaurant platform disintermediation by integrating cloud kitchen procurement interfaces into existing distributor relationships. Prioritize SAMR pre-certification investment to compress competitor compliance windows.
For New Entrants and Emerging Players: Launch via mobile-ordering procurement platforms serving Vietnam's Da Nang and Indonesia's Surabaya cloud kitchen clusters where modern trade penetration remains below twenty percent. Target functional beverage convergence zones where probiotic and adaptogen technologies merge with traditional herbal formulations. Enter through white-label ready-to-cook sauce supply to QSR franchise networks seeking kitchen standardization.
For Investors and Strategic Acquirers: Regional QSR chains with diaspora export capabilities are the most active acquirer in this space, seeking sauce formulation assets for Middle Eastern market penetration. Long-term viability favors processors with backward integration into grassland dairy or palm oil estates that insulate margin structures from input volatility. Watch for FSSAI fortification mandate expansion into additional food categories as signal for micronutrient premix supplier consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Grassland Dairy | Yili's Mongolian sourcing commands tier-one shelf-space premiums against commodity competitors. |
| Direct-to-Restaurant Platform Launch | Mobile procurement interfaces in Ho Chi Minh City compress traditional distributor margin layers. |
| Clean-Label Reformulation Service | HPP technology investment differentiates Japanese supermarket fresh assortments from thermal-processed alternatives. |
| QSR Franchise Network Expansion | Jollibee's standardized sauce supply harmonizes flavor profiles across Philippines outlet networks. |
| FSSAI Premix Supplier Consolidation | Mandatory edible oil fortification creates volume pull for micronutrient suppliers serving Maharashtra processors. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with food technologists, QSR procurement directors, supermarket category buyers, and FSSAI compliance officers with secondary validation. Sources included SAMR GB standard filings, FSSAI fortification mandate documentation, Nielsen retail audit data for organized trade penetration, and customs records for dairy protein import flows. Bottom-up volume modeling and top-down value reconciliation triangulated segment estimates.
Segment-weighting applied product type, distribution channel, and customer type dimensions across the projection horizon, with dairy, beverages, snacks, and packaged foods carrying distinct cold-chain infrastructure coefficients. CAGRs derived from trend extrapolation against regulatory implementation timelines and channel shift velocities. Forecast inputs incorporated QSR procurement scaling rates and HPP technology adoption curves in Japanese retail.
Forecast precision tightens around the base case; tail outcomes carry wider variance under palm oil price spike conditions or accelerated SAMR compliance deadlines. Forecasts embed assumptions around urban retail penetration trajectories in Indian clusters and cloud kitchen proliferation rates in Southeast Asian cities. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service
Benelux Foodservice Market
Food Service
Online Catering Market
Food Service
Food and Grocery Retail Market
Food Service
China Retail Bubble Tea Kits Market
Food Service
Commercial Pizza Oven Market
Food Service
Global Food Platform-To-Consumer Delivery Market
Food Service
North America Smokeless Indoor Grills Market
Food Service
Turkey Retail Bubble Tea Kits Market
Food Service
Global Combi Ovens Market
Food Service
Cutting Boards Market
Food Service
Saudi Arabia Inflight Catering Market
Food Service
Instant Grocery Market
Food Service
Catering Food Warmers Market
Food Service
Turkey Food Service Market
Food Service
Mexico Foodservice Market
Food Service
West Africa Food Services Market