
 Food Trays Market | 2026-2036
Food Trays Market Size, Share, and Industry Trends Forecast 2026-2036
Food Trays Market Foresight
Packaging engineer shortages across European and North American manufacturing hubs is rotating investment toward automated thermoforming and fiber-molding lines. Huhtamaki Oyj leverages its Nordic R&D footprint to dominate molded fiber tray development for ready-to-eat applications. Dart Container Corporation sustains massive polystyrene and polypropylene capacity across the southeastern United States, anchoring its position in institutional foodservice. Genpak LLC specializes in dual-ovenable CPET trays, competing aggressively in the frozen food storage segment where thermal performance commands premium positioning.
Food trays are rigid or semi-rigid containers engineered from polymers, aluminum alloys, paperboard laminates, or molded plant fibers, typically featuring wall thicknesses of 0.3–2.0 mm and designed for single-use or limited-reuse food containment, display, and thermal protection across commercial supply chains. Compartmentalized trays isolate menu components during transport, a structural feature that dominates airline catering and school nutrition contracts where leakage prevention is specified contractually. Biodegradable fiber trays represent the fastest-expanding material category as foodservice operators face procurement mandates tied to extended producer responsibility frameworks, while clamshell configurations retain margin density in deli presentation and bakery packaging due to their integrated lid-lock mechanisms and superior shelf visibility.
The U.S. FDA maintains material contact safety standards under 21 CFR that govern polymer migration limits into fatty foods, directly shaping resin selection and multilayer barrier design for tray converters. REACH restrictions on perfluorinated compounds and the EU F-Gas Regulation governing foam-blowing agents are forcing reformulation of insulated tray lines across European supply chains, with ECHA compliance timelines accelerating capital redeployment. Stakeholders must monitor emerging state-level packaging EPR laws in California, New York, and Washington, as fragmented regulatory trajectories will fragment tray specifications and require modular manufacturing platforms capable of rapid material switching without line retooling.
Market Dynamics
The EU Green Deal's single-use plastic directives are compressing polystyrene tray volumes while fiber-molding capacity expansion lags demand curves across European supply chains. Automated thermoforming lines are absorbing engineering labor shortages that previously constrained converter output.
Growth Catalysts
- Extended Producer Responsibility frameworks:Germany's packaging ordinance mandates recycled content thresholds that fiber tray converters are racing to certify, locking in multi-year procurement contracts with foodservice distributors.
- Meal kit subscription maturation:Portion-controlled tray specifications from ready-to-eat meal providers are standardizing compartmentalized formats across North American cold-chain logistics.
- Aluminum alloy recycling infrastructure:Closed-loop recovery systems at airline catering hubs in the United Arab Emirates are cutting tray procurement costs for long-haul carriers.
Market Restraints
- Pulp fiber input cost volatility:Nordic bleached kraft pulp pricing swings are compressing molded fiber tray margins below polymer alternatives during quarterly procurement cycles.
- Perfluorinated compound reformulation timelines:REACH restrictions on PFAS grease barriers are forcing European converters to validate alternative coatings without performance degradation.
- Insulated foam tray substitution:Expanded polystyrene retains thermal performance advantages in institutional foodservice despite regulatory phase-out pressures.
Strategic Opportunities
- India foodservice packaging formalization:Quick-service restaurant chains in Mumbai and Bangalore are specifying fiber trays for dine-in and delivery formats previously served on reusables.
- Dual-ovenable CPET tray convergence:Frozen food brands are consolidating microwave and conventional oven compatibility into single SKUs, reducing retail slotting complexity.
- California SB 54 implementation:The state's packaging EPR law creates first-mover advantage for converters with modular material-switching platforms certified ahead of 2032 targets.
Industry Challenges
- Packaging engineer scarcity:European thermoforming hubs lack sufficient polymer scientists to optimize barrier layer configurations for high-fat food contact.
- Multilayer coextrusion line capex intensity:Seven-layer barrier tray production requires capital deployment exceeding mid-tier converter balance sheet capacity.
- State-level EPR fragmentation:Divergent compliance timelines across New York, Washington, and California are forcing redundant certification runs for identical tray specifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Food Trays Market |
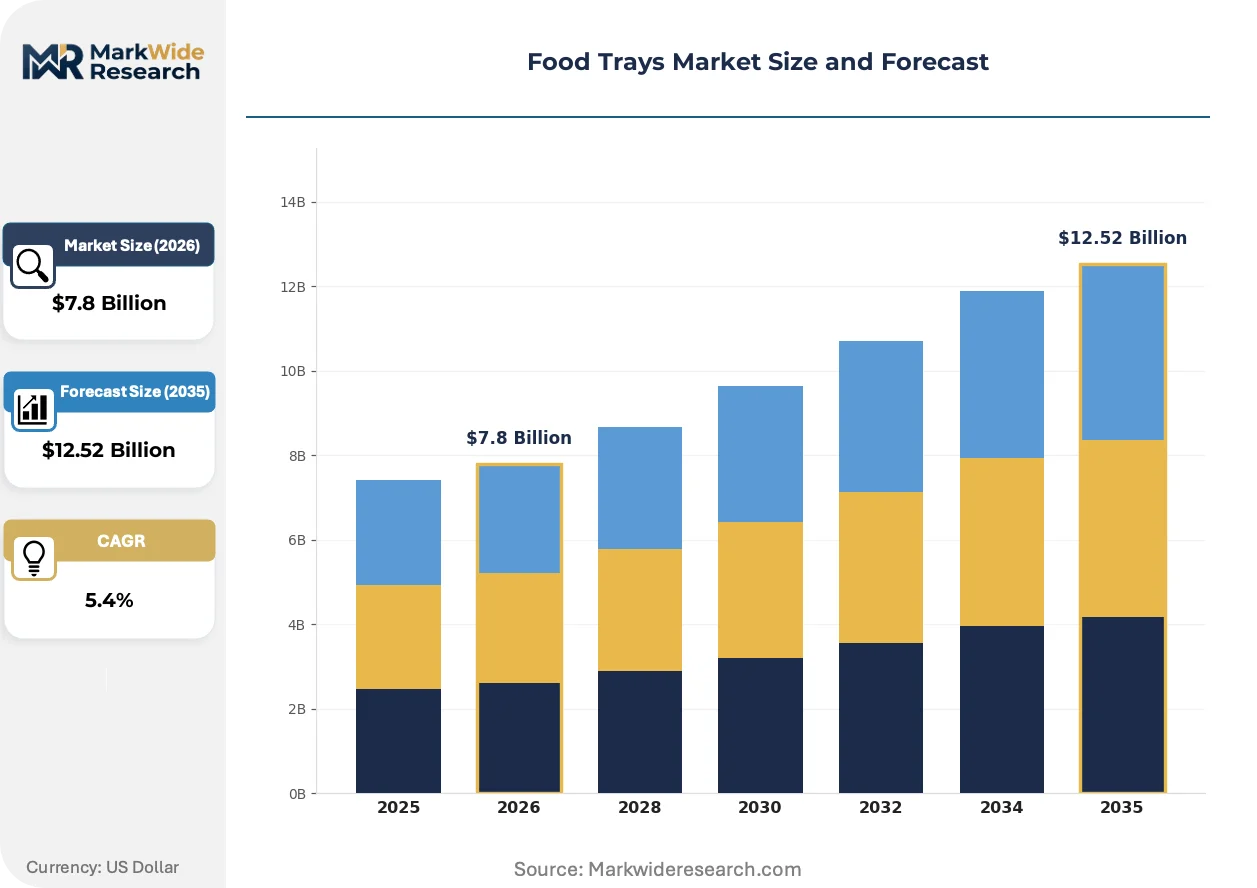
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $12.52 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material: Plastic, Aluminum, Paperboard, Biodegradable Fiber, Foam, Glass Type: Compartmentalized, Clamshell, Lid Included, Flat, Foldable, Insulated End User: Foodservice Operators, Catering Companies, Meal Kit Providers, Institutional Facilities, Event Organizers Application: Ready-to-Eat Meals, Bakery Packaging, Fresh Produce Display, Frozen Food Storage, Takeaway Packaging, Deli Presentation |
| Companies Covered | Pactiv Evergreen Inc., Dart Container Corporation, Genpak LLC, Anchor Packaging, Huhtamaki Oyj, Sabert Corporation, D&W Fine Pack, Placon Corporation, Amcor, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Food Trays Market Shifts & Advancements
Material science advances and regulatory compression are converging to reshape tray converter investment priorities. Automation and barrier coating innovation dominate capital allocation.
Molded fiber technology with integrated PLA barrier layers is supplanting conventional polymer trays in ready-to-eat applications. European airline caterers are adopting these formats at pace to meet EU Green Deal procurement mandates. The shift is compressing virgin polymer tray volumes in premium foodservice segments where thermal performance requirements have relaxed.
REACH restrictions on perfluorinated compounds are forcing reformulation of grease-resistant coatings across European supply chains. Industrial consequence includes extended validation timelines for alternative barrier chemistries at ECHA-notified bodies. Frozen food tray converters in Germany and France are most affected, accelerating partnerships with cellulose nanofibril coating developers.
Direct procurement relationships between meal kit providers and tray converters are disintermediating traditional packaging distributors. Subscription volume commitments are replacing spot-market purchasing in North American cold-chain logistics. This pattern is most visible in California and Texas, where vertically integrated meal brands are specifying custom compartment geometries for portion-controlled nutrition programs.
Food Trays Market Segmentation
Tray specifications fragment across material chemistry, structural geometry, and thermal performance requirements. Procurement patterns diverge sharply between export-oriented converters serving multinational food brands and domestic suppliers bound by local EPR mandates.
Material:
Domestic production concentrates in polymer and aluminum conversion near major food manufacturing clusters, while biodegradable fiber capacity expands primarily for export markets facing stringent single-use plastic restrictions.
- Plastic:Polypropylene and PET dominate thermoformed tray output for frozen food storage and ready-to-eat applications. Demand clusters in Germany and the United States where barrier layer specifications under FDA 21 CFR and EU food contact regulations drive multilayer coextrusion investment.
- Biodegradable Fiber:Molded pulp with PLA or cellulose nanofibril barriers is displacing conventional polymers in airline catering and premium meal kits. Nordic bleached kraft pulp supply constraints are compressing margins below polymer alternatives during quarterly procurement cycles.
- Aluminum:Rolled alloy trays serve closed-loop airline catering systems in the United Arab Emirates and long-haul carrier hubs where recovery infrastructure cuts lifecycle procurement costs.
- Paperboard:Laminated paperboard with polyethylene barriers anchors bakery packaging and deli presentation where shelf visibility and printability command specification.
- Foam:Expanded polystyrene retains institutional foodservice share despite EU Green Deal phase-out pressures, with thermal performance advantages persisting in school nutrition and healthcare contracts.
- Glass:Tempered glass trays occupy premium ready-to-eat and reusable program niches where microwave compatibility and aesthetic presentation justify weight and fragility tradeoffs.
Plastic commands the established base. The steepest expansion runs through biodegradable fiber.
Type:
Structural configurations segment by thermal protection requirements and component isolation needs, with compartmentalized and clamshell formats absorbing disproportionate engineering investment due to their complexity.
- Compartmentalized:Multi-cavity designs with 2-4 isolated sections prevent moisture migration between proteins, starches, and vegetables. School nutrition contracts and airline catering specifications mandate these formats where leakage prevention is contractually binding.
- Clamshell:Hinged lid-lock mechanisms with integrated sealing ribs dominate deli presentation and bakery packaging. Superior shelf visibility and tamper-evident closure drive premium positioning in retail environments.
- Lid Included:Separate lidding films or snap-fit covers paired with base trays serve frozen food storage where modified atmosphere packaging extends shelf life.
- Flat:Unpartitioned trays with minimal wall height serve fresh produce display and simple takeaway applications where cost minimization overrides functional complexity.
- Foldable:Crease-patterned paperboard or thin-gauge polymer designs collapse for reverse logistics in reusable programs and space-constrained catering operations.
- Insulated:Foam-core or vacuum-panel constructions maintain temperature corridors in extended delivery routes, though REACH F-Gas restrictions and single-use plastic directives are forcing material transitions across European supply chains.
Compartmentalized formats anchor institutional procurement. Clamshell configurations are climbing the fastest as retail deli and bakery segments formalize packaging specifications.
End User:
Customer concentration varies by order scale and customization requirements, with meal kit providers and institutional facilities driving divergent specification trends.
- Foodservice Operators:Quick-service restaurants and casual dining chains specify standardized tray formats across franchise networks, with procurement centralized at brand headquarters.
- Meal Kit Providers:Subscription-based ready-to-eat brands demand portion-controlled compartment geometries with precise thermal performance for cold-chain logistics.
- Catering Companies:Event and corporate catering operations balance disposability against presentation requirements, with specification volatility tied to contract duration.
- Institutional Facilities:School districts, hospitals, and correctional facilities prioritize cost minimization and regulatory compliance over aesthetic or performance features.
- Event Organizers:Stadiums, convention centers, and festival operators specify high-volume, low-unit-cost formats with rapid turnaround requirements.
Foodservice operators command the established base. Meal kit providers are gaining share fastest as subscription models mature and direct converter relationships disintermediate traditional packaging distributors.
Application:
End-use thermal and barrier requirements determine material selection, with frozen and ready-to-eat segments imposing the most stringent performance specifications.
- Ready-to-Eat Meals:Dual-ovenable CPET and fiber-PLA hybrid trays serve microwave and conventional oven compatibility requirements. Frozen food brands are consolidating formats into single SKUs to reduce retail slotting complexity.
- Frozen Food Storage:Seven-layer barrier coextrusion or aluminum-laminated structures prevent freezer burn and oxidation over extended distribution timelines.
- Takeaway Packaging:Cost-optimized polypropylene and molded fiber formats balance leak resistance against disposability in delivery and grab-and-go contexts.
- Bakery Packaging:Clamshell and lidded paperboard configurations prioritize moisture retention and visual presentation for artisan and commercial baked goods.
- Fresh Produce Display:Perforated or breathable designs regulate ethylene exchange and condensation in retail produce departments.
- Deli Presentation:High-clarity PET and hinged clamshell formats maximize product visibility while maintaining sliced meat and cheese freshness.
Ready-to-eat meals command the established base. Frozen food storage is expanding most quickly as dual-ovenable specifications consolidate procurement categories.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German converters command premium pricing for fiber-molded trays under EU Green Deal mandates, while Southeast Asian suppliers compete on polystyrene volume with minimal regulatory friction. This pricing-power asymmetry shapes procurement patterns across global supply chains.
United States
Meal kit subscription growth in California and Texas drives compartmentalized tray specifications for cold-chain logistics. FDA 21 CFR material contact standards govern polymer migration limits into fatty foods, directly shaping resin selection for converters. Thermoforming clusters in the Southeast anchor institutional foodservice supply.
Germany
Extended Producer Responsibility frameworks mandate recycled content thresholds that fiber tray converters race to certify. REACH restrictions on perfluorinated compounds force reformulation of grease-resistant coatings without performance degradation. Industrial concentration in North Rhine-Westphalia hosts validation facilities for alternative barrier chemistries.
China
Quick-service restaurant formalization in Shanghai and Beijing specifies standardized formats across franchise networks. GB standards for food contact materials govern domestic production while export-oriented converters serve European single-use plastic directives. Yangtze River Delta molding capacity expands for biodegradable fiber exports.
India
Foodservice packaging formalization in Mumbai and Bangalore drives fiber tray adoption for dine-in and delivery formats previously served on reusables. FSSAI food contact regulations shape material compliance requirements for domestic converters. Gujarat pulp processing clusters supply bleached kraft feedstock for molded fiber expansion.
United Arab Emirates
Airline catering hubs in Dubai deploy closed-loop aluminum alloy recovery systems that cut tray procurement costs for long-haul carriers. MOHAP food safety standards govern material contact specifications for aviation catering infrastructure. Emirates flight catering operations anchor regional closed-loop recovery economics.
Food Trays Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the food trays market. The vendor base separates into fiber-molding specialists commanding premium positioning under regulatory mandates and scale-driven polymer converters defending volume in institutional segments. Three archetypes dominate: Nordic R&D-intensive fiber innovators, Southeastern US polystyrene scale operators, and dual-ovenable CPET specialists competing on thermal performance. Consolidation pressures favor modular manufacturing platforms capable of rapid material switching, while strategic partnerships with cellulose nanofibril developers accelerate barrier coating validation.
Within the fiber-molding tier, Huhtamaki Oyj exemplifies Nordic technology leadership through its R&D footprint in molded fiber development. Dart Container Corporation anchors scale-driven polymer conversion capacity across the southeastern United States. Genpak LLC occupies a position in dual-ovenable tray specialization where thermal performance commands specification premium.
| Leading Market Players |
|---|
| Pactiv Evergreen Inc. |
| Dart Container Corporation |
| Genpak LLC |
| Anchor Packaging |
| Huhtamaki Oyj |
| Sabert Corporation |
| D&W Fine Pack |
| Placon Corporation |
| Amcor |
| Others |
Supply & Pricing Matrix
Fiber-molding capacity substitution for conventional thermoforming is redrawing supply geography toward Nordic pulp processing clusters while compressing polymer tray pricing power in European procurement. German converters extract premiums under EU Green Deal mandates as polystyrene scale operators in the southeastern United States defend volume through institutional contracts.
Pricing Analysis
The customization-premium spread separates configured-to-order compartmentalized trays for meal kit providers from standardized institutional formats. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and volume scale, with fiber-molded variants commanding top positioning under EPR frameworks. Pricing pressure stems from Nordic bleached kraft pulp input volatility squeezing fiber tray margins below polymer alternatives. Institutional facilities exhibit highest price sensitivity; airline caterers and premium meal kit brands demonstrate lowest.
Supply Chain Analysis
Nordic bleached kraft pulp supply concentration anchors molded fiber tray economics, with Germany, Finland, and Sweden hosting validation facilities for barrier coating innovation. Raw material dependencies center on pulp fiber, PLA resin, and aluminum alloy feedstock. Single-source vulnerability in pulp processing creates exposure to quarterly procurement cycle swings. Distribution runs through foodservice packaging distributors, though direct converter relationships are disintermediating traditional channels in North American cold-chain logistics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized polymer scientists capable of optimizing seven-layer barrier configurations represent the critical capability gap constraining European thermoforming output. This scarcity is rotating capital toward automated lines and external coating partnerships rather than in-house technical development.
For Market Incumbents: Consolidate fiber-molding capacity in Nordic regions to capture EPR-driven procurement premiums before alternative barrier chemistries achieve ECHA validation. Acquire cellulose nanofibril coating developers to secure grease-resistant technology ahead of PFAS phase-out deadlines. Anchor institutional share through long-term offtake contracts with school nutrition and healthcare facilities where thermal performance specifications persist.
For New Entrants and Emerging Players: Lead with modular material-switching platforms certified for California SB 54 compliance, targeting first-mover advantage in state-level EPR fragmentation. Penetrate Indian quick-service restaurant formalization in Mumbai and Bangalore where fiber tray specifications are displacing reusable formats. Pursue direct procurement relationships with vertically integrated meal kit brands bypassing traditional packaging distributors.
For Investors and Strategic Acquirers: California SB 54 implementation reshapes the acquisition landscape toward converters with certified modular platforms and established cellulose nanofibril partnerships. Target mid-tier European fiber specialists with ECHA validation pipelines rather than undifferentiated polymer scale operators. Watch Nordic pulp pricing volatility as the signal indicating margin compression windows for due diligence timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Cellulose Nanofibril Coating Partnership | Accelerates PFAS-free barrier validation under REACH timelines for frozen food tray converters. |
| Modular Material-Switching Platform Deployment | Enables rapid polymer-to-fiber transitions without line retooling across fragmented state EPR regimes. |
| Backward Integration into Pulp Processing | Captures margin from Nordic bleached kraft supply constraints compressing molded fiber economics. |
| Direct Meal Kit Provider Contracting | Disintermediates packaging distributors through subscription volume commitments in California and Texas. |
| Dual-Ovenable CPET Capacity Expansion | Consolidates microwave and conventional oven compatibility into single SKUs for frozen food brands. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of customs and trade data, SEC filings from publicly traded packaging converters, EU ECHA regulatory submissions, and foodservice procurement databases. Primary interviews engaged thermoforming plant managers, packaging engineers at tray converters, procurement leads at meal kit providers, airline catering operations directors, and pulp processing supply planners. Bottom-up volume estimates from converter capacity utilization triangulate against top-down demand aggregation across end-use segments.
Segmentation dimensions modeled span material chemistry, structural geometry, thermal performance tier, and end-use application across the analysis window. CAGRs derive from trend extrapolation of subscription meal kit penetration, EPR implementation timelines, and fiber-molding capacity expansion curves. Industry-specific forecast inputs include Nordic pulp pricing volatility indices and airline catering traffic recovery patterns.
The analysis sits within stated boundaries; outcomes outside sustained EU Green Deal enforcement or alternative barrier coating validation would require recalibration. Forecasts reflect documented assumptions regarding EPR adoption velocity and pulp supply stabilization. Practitioners should keep alternative scenarios live as REACH restriction timelines and state-level packaging laws evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service
Food Trucks Market
Food Service
Smart Food Logistics Market
Food Service
Healthy Takeout Market
Food Service
Europe Barbeque Grill Market
Food Service
Quick-Service Restaurants Market
Food Service
Europe Vending Machine Market
Food Service
Commercial Air Fryer Oven Market
Food Service
Restaurant Glassware Market
Food Service
Food Service Pasta Market
Food Service
North America Online Grocery Delivery Market
Food Service
Latin America Online Grocery Market
Food Service
Asia-Pacific Cloud Kitchen Market
Food Service
Europe Inflight Catering Market
Food Service
Germany Foodservice Market
Food Service
Virtual Kitchen Market
Food Service
Contract Catering Market