
 Restaurant Griddle Market | 2026-2036
Restaurant Griddle Market Size, Share, and Industry Trends Forecast 2026-2036
Restaurant Griddle Market Analytics
The US Department of Energy's commercial kitchen equipment efficiency mandates is realigning procurement specifications across chain restaurant operators. The Middleby Corporation leverages its vertical manufacturing footprint to control component sourcing for high-output griddle lines. Electrolux anchors European demand through its modular kitchen systems designed for energy-recovery integration. Illinois Tool Works Inc competes on precision temperature control technologies that reduce thermal recovery times during peak service hours.
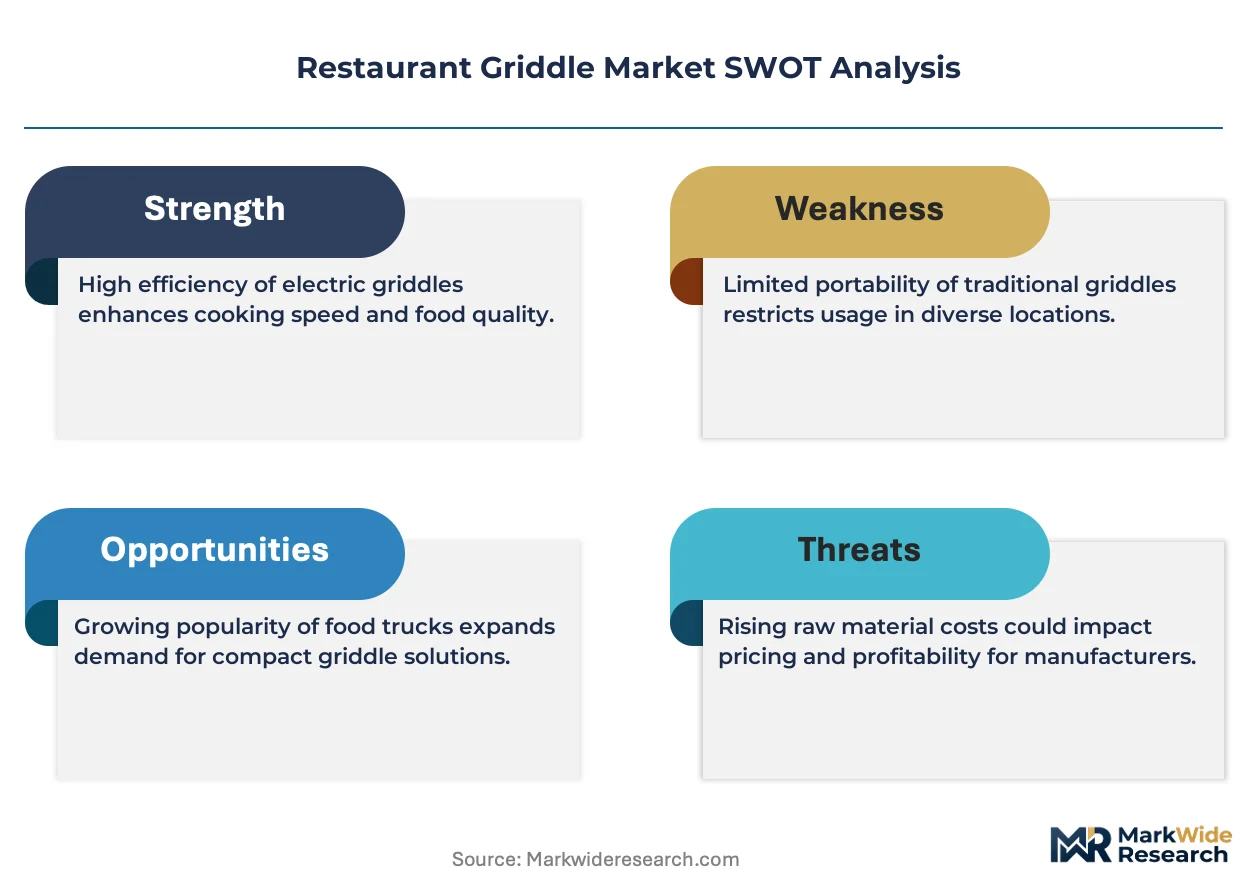
Restaurant griddles are flat or grooved metal cooking surfaces, typically constructed from polished steel or chrome composite, heated by gas burners or electric elements to temperatures between 150°C and 300°C for searing proteins and preparing breakfast items at volume. Gas griddles sustain the largest installed base across North American commercial kitchens due to faster preheat cycles and lower operational costs per BTU. Electric griddles are gaining share in urban cafés and food trucks where ventilation constraints and fire codes restrict gas infrastructure deployment. Induction heating technology leads premium positioning with sub-60-second recovery times and zone-level energy metering that appeals to operators tracking utility costs per service period.
The US Department of Energy and the EPA's ENERGY STAR program jointly shape equipment eligibility for utility rebate programs, pushing manufacturers toward documented efficiency testing and certified performance thresholds. The NSF International sanitation standard governs surface material approval and cleanability design for commercial food contact equipment across the United States. Stakeholders must monitor how municipal electrification ordinances in cities like New York and San Francisco reshape the gas-versus-electric mix in replacement purchase decisions.
Market Dynamics
The US Department of Energy's tightening efficiency thresholds for commercial kitchen equipment is forcing chain operators to accelerate replacement cycles and requalify supplier relationships around certified performance documentation.
Growth Catalysts
- ENERGY STAR Rebate Alignment:Utility incentive programs tied to EPA certification thresholds are pulling mid-scale operators toward documented efficiency tiers, expanding the addressable base for premium electric and induction units.
- Quick-Service Expansion:Breakfast-all-day menu proliferation across US fast-casual chains is driving dedicated griddle line installations in new store builds and retrofits.
- Induction Recovery Performance:Sub-60-second thermal recovery times are displacing gas in urban locations where ventilation constraints and municipal electrification ordinances restrict traditional infrastructure.
Market Restraints
- Stainless Steel Input Volatility:Fluctuations in nickel and chromium pricing compress margin predictability for polished steel surface manufacturers, particularly affecting mid-tier producers without captive metallurgy contracts.
- Gas Infrastructure Lock-In:Existing ventilation hood investments and utility connections in established US commercial kitchens create replacement friction that slows electric conversion despite operating cost advantages.
- Skilled Technician Scarcity:Induction coil and solid-state control repairs require electronics expertise that traditional foodservice equipment service networks lack, extending downtime risk for early adopters.
Strategic Opportunities
- Food Truck Electrification:Mobile operators in dense US urban corridors represent an underpenetrated channel where battery-sourced induction griddles bypass generator noise restrictions and fire code limitations.
- Zone-Level Metering Convergence:Integration of IoT-enabled energy tracking with kitchen management software creates subscription revenue potential for manufacturers positioned as utility data intermediaries.
- Municipal Decarbonization Mandates:New York and San Francisco electrification ordinances are creating regulatory tailwinds that accelerate replacement demand ahead of natural equipment end-of-life.
Industry Challenges
- NSF Certification Timelines:Surface material approval and cleanability validation under NSF International standards extend new product introduction cycles, compressing competitive response windows.
- Legacy Control System Interoperability:Kitchen display and inventory management platforms in established chain footprints require custom API development for induction zone controllers, inflating deployment costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Restaurant Griddle Market |
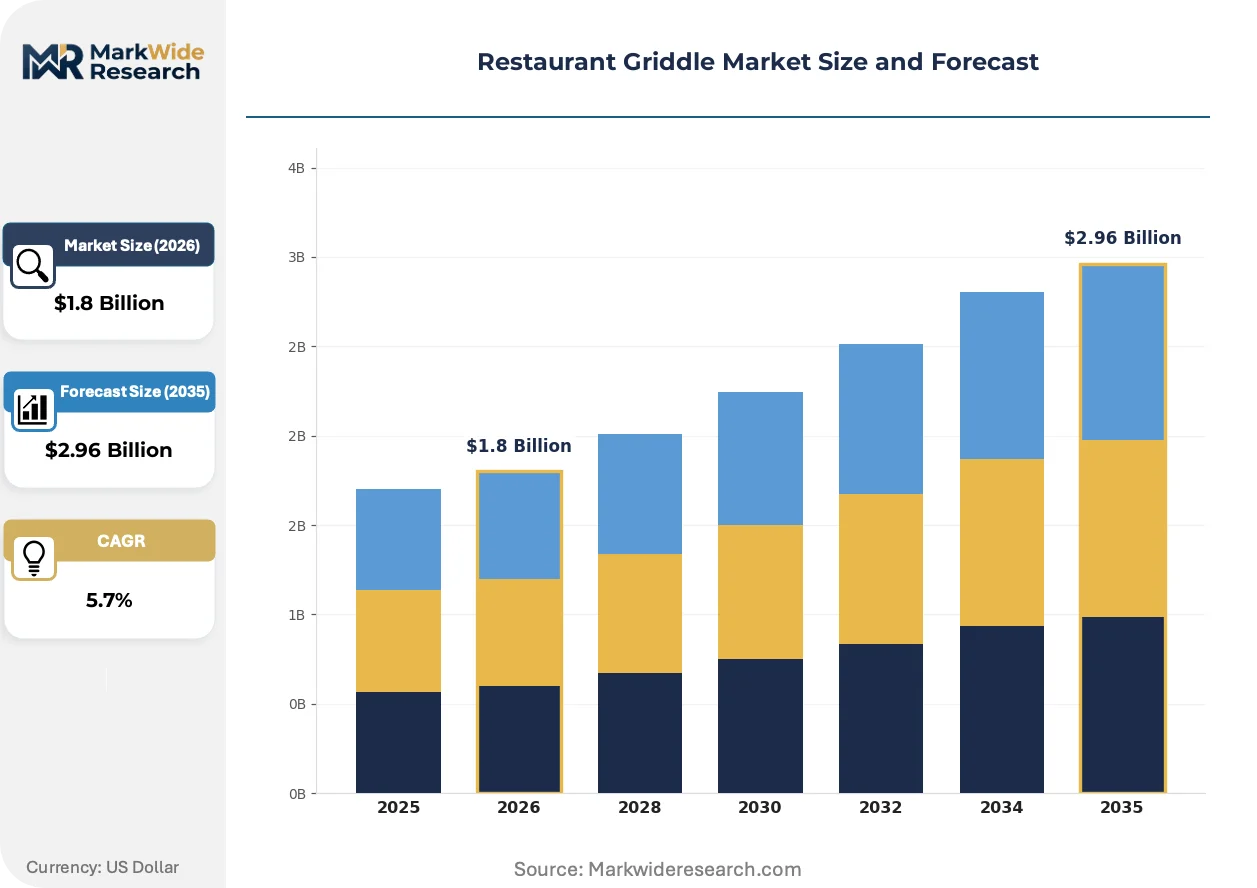
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flat Griddles, Grooved Griddles, Electric Griddles, Gas Griddles End User: Commercial Kitchens, Food Trucks, Diners, Cafés Technology: Induction Heating, Traditional Heating, Convection Technology, Radiant Heating Size: Small Griddles, Medium Griddles, Large Griddles, Extra-Large Griddles |
| Companies Covered | The Middleby Corporation, Electrolux, Illinois Tool Works Inc, The Vollrath Company, Welbilt Inc, Standex International Corporation, Ali Group Srl, AccuTemp Products Inc, Garland Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Restaurant Griddle Market Evolving Landscape
Equipment intelligence and energy accountability are converging to reshape how commercial kitchens specify, operate, and finance griddle assets across the replacement cycle.
Induction heating systems are integrating solid-state power electronics with predictive load balancing algorithms that optimize coil activation sequences based on real-time menu mix. Fast-casual chains with high breakfast throughput are adopting these units fastest, particularly in airport and university food courts where utility cost allocation is transparent. This convergence is integrating griddle operations directly into enterprise energy management platforms, compressing the traditional separation between kitchen equipment and facility infrastructure decisions.
The EPA's ENERGY STAR Version 3.0 commercial cooking equipment specification is tightening idle energy rate thresholds and mandating third-party witnessed testing for certification eligibility. Manufacturers must now document performance across simulated duty cycles rather than steady-state conditions, raising compliance costs for smaller competitors. Full-service restaurant operators in California and Massachusetts are responding fastest, driven by state-level appliance efficiency regulations that reference federal standards.
Equipment-as-a-service contracting is displacing capital purchase models among multi-unit franchisees seeking to transfer obsolescence risk to manufacturers. This shift bundles maintenance, certification renewal, and technology refresh into per-meal operational charges rather than upfront asset ownership. The model is most visible in Southeast US markets where private equity-backed restaurant platforms prioritize cash flow predictability over balance sheet control.
Restaurant Griddle Market Segmentation
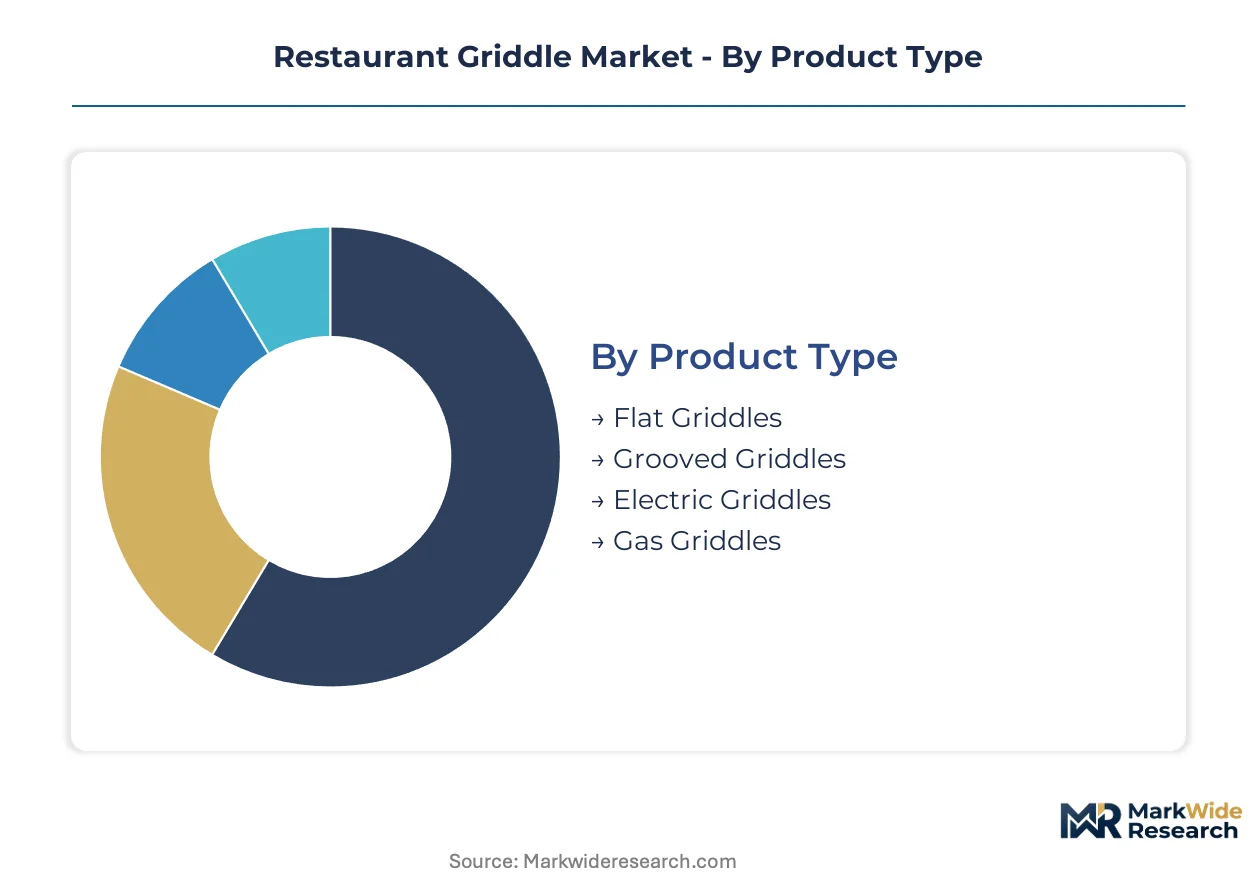
Griddle specification choices cascade through kitchen infrastructure decisions, from ventilation requirements to utility rebate eligibility. Operators segment procurement by thermal performance needs, space constraints, and regulatory compliance pathways rather than surface area alone.
Product Type:
Surface geometry and heat source configuration define operational capability and energy accountability across commercial installations.
- Flat Griddles:Polished steel or chrome composite surfaces deliver uniform heat distribution for breakfast proteins and seared items. Chain operators in the Southeast and Texas corridor specify these for high-throughput breakfast production where surface consistency drives ticket speed.
- Grooved Griddles:Ribbed surfaces create sear marks and channel grease away from proteins during cooking. Demand concentrates in fast-casual steak concepts and airport food courts where plate presentation standards are elevated.
- Electric Griddles:Heating elements embedded in thick steel plates suit urban cafés and food trucks facing ventilation constraints and municipal electrification ordinances.
- Gas Griddles:Burner systems beneath steel plates sustain the largest installed base across established commercial kitchens with existing hood infrastructure.
Flat griddles lead on scale; electric griddles lead on momentum.
End User:
Operational environment dictates specification priorities from mobility requirements to volume throughput targets.
- Commercial Kitchens:High-volume back-of-house installations in chain restaurants and institutional foodservice. Operators here prioritize ENERGY STAR certification alignment for utility rebate capture and documented efficiency performance.
- Food Trucks:Mobile operators in dense urban corridors require compact, battery-compatible induction units that bypass generator noise restrictions and fire code limitations.
- Diners:Independent full-service restaurants with breakfast-heavy menus and limited capital replacement cycles.
- Cafés:Urban coffee-forward concepts with constrained footprints and electrification mandates driving electric specification.
Commercial kitchens dominate volume concentration; food trucks represent the steepest expansion trajectory.
Technology:
Heating modality determines thermal recovery speed, energy metering precision, and service technician requirements.
- Induction Heating:Solid-state power electronics with coil-based electromagnetic heating achieve sub-60-second recovery times. Fast-casual chains with transparent utility cost allocation adopt these fastest, particularly in California and Massachusetts where state efficiency regulations tighten.
- Traditional Heating:Direct gas flame or electric resistance elements beneath steel plates. Established kitchens with legacy hood investments and utility connections maintain this installed base despite operating cost disadvantages.
- Convection Technology:Forced-air circulation systems integrated with griddle surfaces for hybrid cooking applications.
- Radiant Heating:Infrared element configurations for targeted surface heating in specialty applications.
Traditional heating anchors installed base; induction heating gains share fastest.
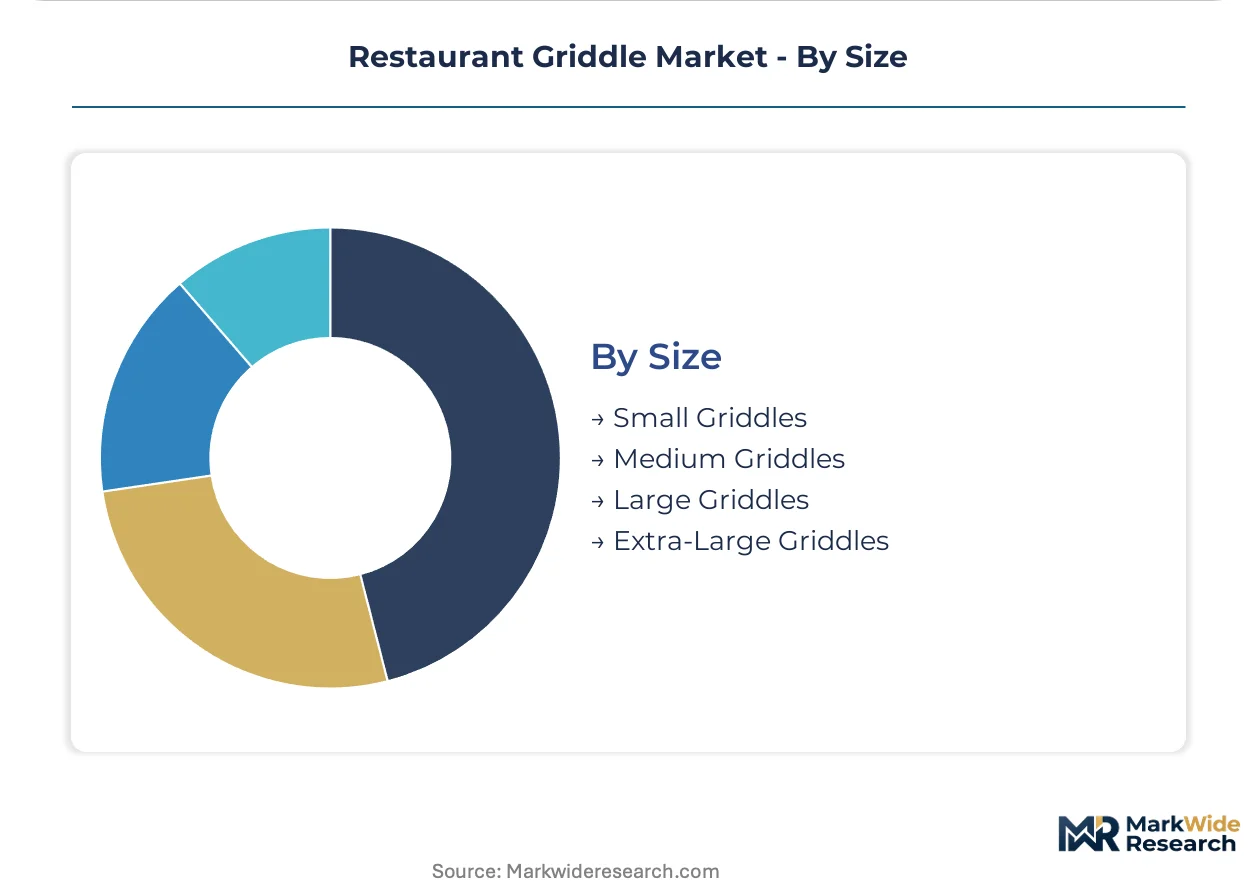
Size:
Surface dimensions correlate with menu complexity, peak hour volume targets, and available line footage.
- Small Griddles:Compact 24-inch surfaces for food trucks and cafés with constrained footprints. Mobile operators in New York and San Francisco specify these for compliance with municipal electrification ordinances.
- Medium Griddles:36-inch surfaces balancing throughput and space efficiency for mid-scale independent operators.
- Large Griddles:48-inch to 60-inch surfaces for high-volume chain production lines.
- Extra-Large Griddles:72-inch and above surfaces for institutional and airport food court installations with continuous service demands.
Medium griddles lead on unit volume; extra-large griddles lead on revenue per installation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Culinary workforce density in major metropolitan clusters drives equipment specification intensity. Chain restaurant expansion concentrates procurement decisions in corridors with established foodservice labor pools and regulatory enforcement capacity.
United States
Breakfast-all-day menu proliferation across fast-casual chains accelerates dedicated griddle line installations. The EPA's ENERGY STAR Version 3.0 specification tightens idle energy rate thresholds for commercial cooking equipment. The Southeast and Texas corridor dominates volume concentration, with Atlanta and Dallas-Fort Worth metro areas leading new store buildouts.
Germany
Precision manufacturing heritage supports demand for temperature-controlled cooking surfaces in institutional foodservice. The EU Green Deal's commercial kitchen efficiency benchmarks push operators toward documented energy performance tiers. Bavaria's Munich-Stuttgart industrial corridor anchors production of modular kitchen systems with integrated energy recovery.
China
Rapid quick-service restaurant expansion in tier-one cities creates volume demand for standardized cooking equipment. The country's national commercial appliance efficiency standards tighten testing protocols for foodservice equipment certification. The Yangtze River Delta region, centered on Shanghai, concentrates manufacturing capacity for export-oriented griddle production.
United Kingdom
Urban café density in London drives compact electric griddle specification for constrained kitchen footprints. The country's building regulations and fire safety codes restrict gas infrastructure in central business district foodservice operations. Greater Manchester and Birmingham emerging as secondary hubs for chain restaurant regional headquarters procurement decisions.
Japan
Space-constrained urban food courts prioritize induction heating systems with rapid thermal recovery. METI's commercial equipment efficiency labeling program mandates disclosed energy consumption metrics for foodservice operators. The Kanto region around Tokyo concentrates high-throughput airport and railway station foodservice installations demanding sub-60-second recovery performance.
Restaurant Griddle Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across divergent manufacturing footprints. The market structure consolidates around integrated manufacturers with captive component sourcing and specialized fabricators serving regional niches. Three archetypes dominate: vertically integrated kitchen equipment conglomerates, precision metalworking specialists, and regional fabrication houses. Competitive moves center on strategic partnerships for IoT integration and geographic expansion through distribution network densification.
Within the integrated equipment tier, The Middleby Corporation and Electrolux occupy positions exemplifying scale-driven supply chain control. Illinois Tool Works Inc represents the precision technology archetype, while The Vollrath Company and Welbilt Inc anchor mid-market fabrication capabilities. Standex International Corporation and Ali Group Srl exemplify diversified industrial holding structures with foodservice exposure. AccuTemp Products Inc and Garland Group represent specialized regional fabricators with targeted geographic footprints.
| Leading Market Players |
|---|
| The Middleby Corporation |
| Electrolux |
| Illinois Tool Works Inc |
| The Vollrath Company |
| Welbilt Inc |
| Standex International Corporation |
| Ali Group Srl |
| AccuTemp Products Inc |
| Garland Group |
| Others |
Value Network & Pricing Analysis
Nickel and chromium price volatility on the London Metal Exchange cascades through polished steel surface manufacturing into three distinct procurement tiers for chain restaurant operators, equipment-as-a-service providers, and independent fabricators.
Pricing Analysis
The bundled-versus-unbundled service split separates capital purchase models from equipment-as-a-service contracts that wrap maintenance and certification renewal into per-meal operational charges. Three-tier pricing structure across premium induction, standard electric, and economy gas levels reflects ENERGY STAR certification alignment and thermal recovery performance specifications. Cost compression in mid-tier polished steel surfaces is intensifying because nickel and chromium input volatility compresses margin predictability for producers without captive metallurgy contracts. Multi-unit franchisees in the Southeast US corridor exhibit highest price sensitivity due to private equity-backed cash flow priorities, while airport and university food court operators show lowest sensitivity given transparent utility cost allocation.
Supply Chain Analysis
Container freight rate fluctuations between the Yangtze River Delta and North American ports directly impact landed costs for induction coil assemblies and solid-state power electronics. Manufacturing gravity centers on China for export-oriented griddle production, the United States for domestic chain restaurant supply, and Germany for precision temperature control components. Stainless steel plate fabrication draws from nickel ore processing in Indonesia and chromium refining in South Africa. Single-source vulnerability concentrates in solid-state induction coil suppliers serving premium product lines. Distribution runs through manufacturer-direct channels for large chain accounts and regional foodservice equipment dealers serving independent operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The restaurant griddle market functions as a stable compounder where regulatory efficiency mandates create predictable replacement demand across chain restaurant footprints.
For Market Incumbents: Lock in component sourcing through backward integration into nickel and chromium supply contracts that buffer margin volatility from London Metal Exchange fluctuations. Deepen captive production of solid-state power electronics for induction lines to reduce single-source vulnerability as municipal electrification ordinances accelerate electric conversion. Prioritize API development for kitchen display system interoperability to defend against emerging IoT-native competitors.
For New Entrants and Emerging Players: Battery-sourced induction griddles with sub-60-second recovery performance offer a technology-first wedge into food truck electrification in New York and San Francisco where municipal ordinances restrict gas infrastructure. Target mobile operators and urban café concepts with compact 24-inch surfaces bypassing generator noise restrictions. Pursue direct-to-operator digital sales channels that circumvent established dealer networks concentrated on legacy chain accounts.
For Investors and Strategic Acquirers: Consolidation pressure builds where mid-tier fabricators lack captive metallurgy contracts and ENERGY STAR certification infrastructure to compete on documented efficiency tiers. Position for five-to-ten year horizon viability by targeting regional fabricators with established NSF International validation and Southeast US dealer relationships. Watch EPA ENERGY STAR Version 3.0 enforcement intensity as inflection indicator for premium electric and induction replacement acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Nickel Supply | Captive metallurgy contracts buffer margin volatility from London Metal Exchange price swings. |
| IoT-Enabled Zone Metering Integration | Subscription revenue potential emerges for manufacturers positioned as utility data intermediaries. |
| Equipment-as-a-Service Model Expansion | Per-meal operational charges transfer obsolescence risk from franchisees to manufacturers. |
| Food Truck Channel Penetration | Battery-sourced induction units bypass generator noise restrictions and fire code limitations. |
| API Development for Kitchen System Interoperability | Custom integration with kitchen display platforms reduces deployment friction for chain retrofits. |
Research Methodology
Direct dialogue with chain restaurant procurement directors, foodservice equipment distributors, NSF International certification specialists, and commercial kitchen facility managers grounded qualitative insights in operational reality. Secondary validation drew from EPA ENERGY STAR certification databases, US Department of Energy commercial equipment efficiency filings, SEC 10-K disclosures from publicly traded kitchen equipment manufacturers, and utility rebate program documentation across Southeast and Texas corridor markets. Bottom-up unit economics triangulated against top-down market sizing across product type, end user, technology, and size segmentation dimensions.
Bottom-up volume modeling built from chain restaurant expansion pipelines and replacement cycle analysis while top-down approaches validated against commercial kitchen equipment expenditure trends. Segmentation dimensions spanned heating modality, surface geometry, installation size, and regulatory compliance tier throughout the forecast period. CAGRs derived from weighted average of historical replacement patterns and regulatory mandate acceleration curves, with specific inputs including municipal electrification ordinance adoption timelines and ENERGY STAR Version 3.0 certification penetration rates.
The model holds under stable regulatory enforcement of federal efficiency thresholds; deviation in EPA ENERGY STAR program funding or state-level appliance efficiency regulation repeal would shift replacement demand timing. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service
Global Food Retail Market
Food Service
UAE Food Service Market
Food Service
Gourmet Street Food Market
Food Service
Onboard Rail Catering Market
Food Service
Halal Food and Beverages Market
Food Service
Commercial Beverage Dispenser Market
Food Service
Switzerland Food Service Market
Food Service
Germany Foodservice Market
Food Service
Flat Top Grills Market
Food Service
Restaurant Glassware Market
Food Service
Smoker Grill Market
Food Service
Saudi Arabia Foodservice Market
Food Service
Virtual Kitchen Market
Food Service
Saudi Arabia Pizza Restaurants Market
Food Service
Wok Market
Food Service
Middle East Smokeless Indoor Grills Market