
 Infusion Pump Market | 2026-2036
Infusion Pump Market Size, Share, and Industry Trends Forecast 2026-2036
Infusion Pump Market Intelligence
A long-standing purchasing model centered on large hospital procurement is unwinding as demand shifts toward ambulatory surgery centers and home care settings. Becton Dickinson and Company leverages its extensive portfolio of smart pumps to secure large health system contracts. Baxter International differentiates through its focus on devices for renal care and acute therapies. B. Braun Melsungen AG competes on manufacturing precision and a broad range of infusion therapy products, securing its position in diverse clinical environments.
An infusion pump is a medical device engineered to deliver fluids, such as nutrients and medications, into a patient's circulatory system in a controlled and precise manner. These devices operate with high flow rate accuracy, often within ±5%, to administer therapies including oncology drugs and anesthesia. Volumetric pumps constitute a mature, high-volume product type, whereas syringe pumps are essential for precision-dosing in critical care and pediatric applications. While hospitals remain the largest end-user, the home care setting represents the fastest-growing segment, driven by chronic disease management for conditions like diabetes.
Device approval and market access are governed by stringent regulatory frameworks, including the US FDA's 510(k) pathway and the EU's Medical Device Regulation (MDR). China's NMPA imposes its own rigorous standards for device registration and post-market surveillance. These regulations mandate extensive software validation and cybersecurity protocols to ensure patient safety and data integrity. Stakeholders must now decide on investment priorities between enhancing device interoperability with hospital EMR systems and developing standalone, next-generation smart pump platforms.
Market Dynamics
The central dynamic shaping the infusion pump market is the decentralization of healthcare delivery. This shift moves patient care away from centralized hospitals toward distributed settings like ambulatory surgery centers and home care, altering device design requirements and procurement models.
Growth Catalysts
- Chronic Disease Prevalence:The rising incidence of chronic conditions, particularly diabetes, necessitates long-term, controlled medication delivery, directly supporting demand for infusion pumps in home care and outpatient settings.
- Technological Integration:The incorporation of wireless connectivity enables remote monitoring and synchronization with Electronic Medical Records (EMR), improving patient safety and workflow efficiency in clinical environments.
- Aging Demographics:Advanced economies such as Japan and Germany face rapidly aging populations, increasing the patient pool requiring managed infusion therapies for age-related illnesses and palliative care.
Market Restraints
- Regulatory Scrutiny:Stringent and lengthy approval processes, such as the US FDA's 510(k) pathway and the EU's Medical Device Regulation (MDR), create significant barriers to entry and delay product launches.
- Cybersecurity Risks:The connectivity of smart pumps exposes them to potential cybersecurity threats, requiring substantial investment in software validation and security protocols to prevent unauthorized access or device manipulation.
- High Capital Costs:The initial investment for advanced smart pump systems and their associated software infrastructure can be prohibitive for smaller healthcare facilities, ambulatory centers, and individual home care users.
Strategic Opportunities
- Next-Generation Platforms:Developing standalone smart pump platforms with integrated analytics and user-centric interfaces offers a path to differentiate from devices dependent on hospital EMR systems.
- Pediatric and Neonatal Niches:Designing high-precision syringe pumps specifically for pediatric and neonatal intensive care units addresses a critical need for accurate, low-volume dosing in vulnerable patient populations.
- Data Monetization Services:Offering anonymized, aggregated data analytics services to pharmaceutical companies and healthcare payers can create new revenue streams based on real-world therapy adherence and outcomes.
Industry Challenges
- Interoperability Hurdles:A lack of universal communication standards between different manufacturers' pumps and various EMR systems creates significant integration challenges for hospital IT departments.
- Software Validation Complexity:Ensuring the reliability and safety of increasingly complex device software, as mandated by regulators like the NMPA in China, requires specialized expertise and extensive testing resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Infusion Pump Market |
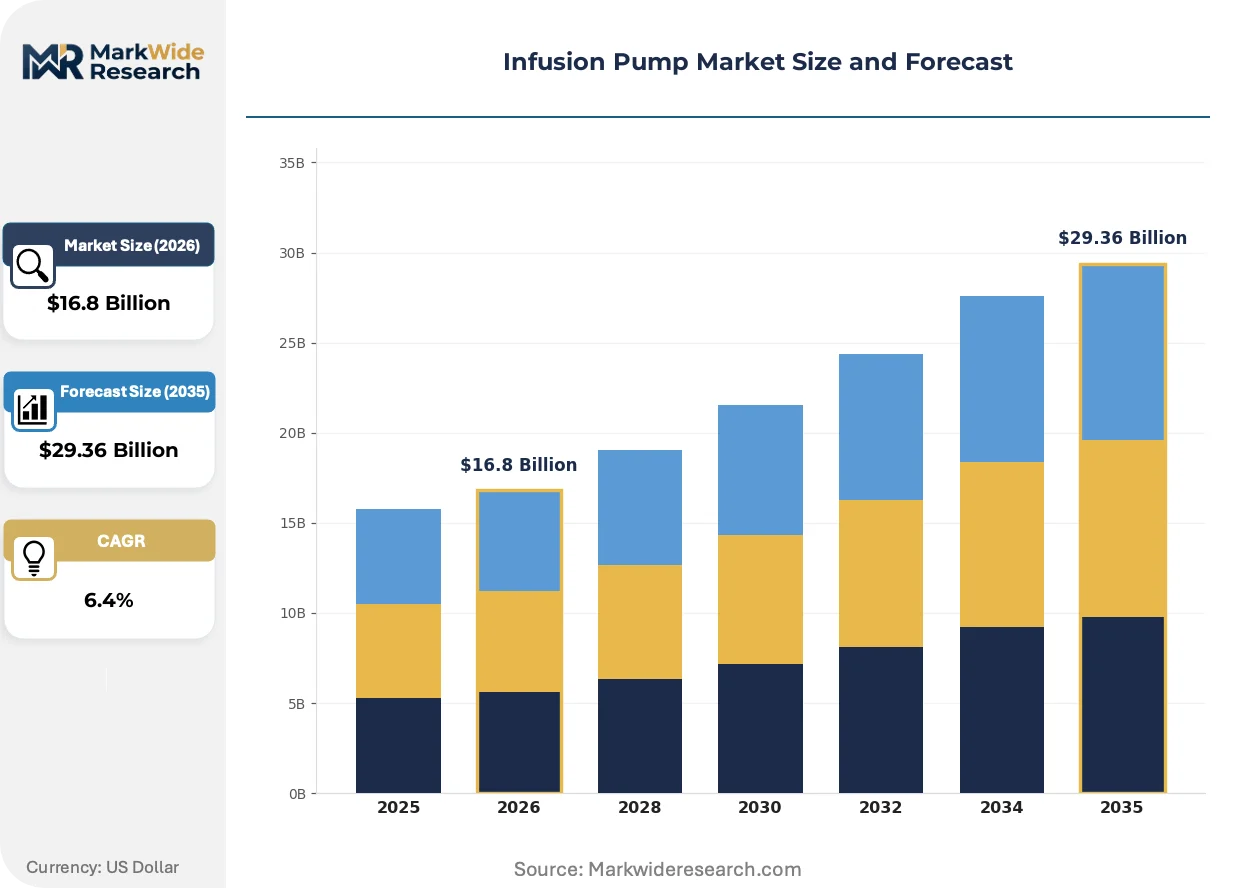
| Market Size in 2026 | $16.8 Billion |
| Market Size in 2035 | $29.36 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Volumetric, Syringe, PCA, Elastomeric, Enteral Therapy Area: Oncology, Anesthesia, Pain Management, Critical Care, Diabetes End User: Hospitals, Ambulatory Surgery Centers, Home Care, Specialty Clinics, Nursing Facilities Delivery Mode: Wireless, Wired, Battery Operated, AC Powered, Disposable |
| Companies Covered | Becton Dickinson and Company, Baxter International, Medtronic, B. Braun Melsungen AG, ICU Medical, Terumo Corporation, Fresenius Kabi, Smiths Medical, F. Hoffmann-La Roche, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Infusion Pump Market Strategic Shifts & Innovations
The market's evolution is defined by the tension between rapid software-driven feature development and the rigorous, safety-oriented demands of medical device regulation. This dynamic forces manufacturers to balance innovation with compliance, particularly around data security and system interoperability.
Standalone smart pump platforms with embedded software and analytics are gaining traction. These devices are being adopted by specialized clinics and ambulatory surgery centers seeking to avoid the complexity of full EMR integration. The move toward self-contained intelligence is fragmenting the traditional hospital-centric market, where pumps were viewed as simple peripherals of a larger network.
Europe's Medical Device Regulation (MDR) is elevating the requirements for software validation and post-market surveillance. This forces manufacturers to provide more extensive clinical evidence and maintain a living file on device performance and safety throughout its lifecycle. High-risk device categories, such as pumps for anesthesia and oncology, are most affected, compelling a renewed focus on robust software engineering and cybersecurity protocols.
A transition away from large, one-time capital purchases toward more flexible consumption models is underway. The traditional procurement cycle centered on hospital-wide contracts is being challenged by subscription or usage-based pricing, especially in non-acute settings. This shift is most prominent in the home care segment in countries like Germany, where cost-containment and operational flexibility are primary concerns for healthcare providers.
Infusion Pump Market Segmentation
The infusion pump market segments by device characteristics, clinical application, end-user environment, and operational modality. Understanding these categories is essential for manufacturers to tailor product development and market entry strategies, addressing specific clinical needs and regulatory compliance across diverse healthcare settings.
Product Type:
Regulatory bodies like the US FDA and EU MDR differentiate infusion pump categories based on their intended use and risk profile, influencing design and approval pathways for each type.
- Volumetric:These devices deliver large volumes of fluids at controlled rates, often for general hydration, nutrition, or broad medication administration in hospital settings. Their reliability and capacity make them foundational for inpatient care.
- Syringe:Syringe pumps deliver small, precise volumes of medication at very slow rates, critical for accurate dosing in sensitive populations like neonates or for potent drugs in critical care units. Their accuracy is paramount in pediatric and intensive care applications.
- PCA:Patient-Controlled Analgesia pumps allow patients to self-administer pain medication within pre-set safety limits, providing personalized pain management post-surgery or in palliative care. These devices enhance patient comfort and autonomy.
- Elastomeric:Elastomeric pumps are disposable, non-electronic devices that use a balloon-like reservoir to deliver medication at a continuous, pre-set flow rate, commonly used for outpatient antibiotic therapy or chemotherapy.
- Enteral:Enteral pumps deliver liquid nutrition or medication directly into a patient's gastrointestinal tract, supporting patients unable to consume orally due to various medical conditions.
Volumetric pumps handle the majority of throughput; syringe pumps are the fastest mover on share due to increasing critical care demands.
Therapy Area:
The application of infusion pumps spans diverse clinical domains, each requiring specific device capabilities for effective patient management and treatment protocols.
- Oncology:Infusion pumps are vital for precise and controlled delivery of chemotherapy drugs, often over extended periods, minimizing patient discomfort and ensuring therapeutic efficacy. The complexity of oncology regimens drives demand for advanced smart pump features.
- Diabetes:Insulin pumps provide continuous subcutaneous insulin infusion, offering highly personalized and flexible diabetes management, particularly in home care settings. This continuous delivery mimics physiological insulin release, improving glucose control.
- Anesthesia:Anesthesia pumps deliver anesthetic agents with high precision during surgical procedures, allowing anesthesiologists to maintain optimal sedation levels and patient safety.
- Pain Management:Beyond PCA, pumps are used for continuous regional nerve blocks or epidural infusions, offering localized pain relief for acute or chronic conditions.
- Critical Care:In intensive care units, pumps manage multiple infusions simultaneously, administering vasoactive drugs, sedatives, and nutrition with stringent accuracy for critically ill patients.
Demand for oncology therapies remains foundational, while diabetes management shows significant expansion.
End User:
Different customer types dictate varying procurement scales and device interoperability requirements, shaping market demand and technological priorities.
- Hospitals:Hospitals represent the largest end-user segment, utilizing a broad range of infusion pumps for general wards, operating rooms, and specialized critical care units. Their demand centers on robust, interoperable systems for large patient populations.
- Home Care:The home care segment is expanding rapidly, driven by chronic disease management and a preference for decentralized healthcare, requiring user-friendly, portable, and often wirelessly connected pumps. This segment values ease of use and remote monitoring capabilities.
- Ambulatory Surgery Centers:These centers require efficient, precise pumps for short-stay procedures, focusing on devices that integrate seamlessly into streamlined workflows and rapid patient turnover.
- Specialty Clinics:Clinics focusing on specific conditions like dialysis or oncology utilize pumps tailored to their unique treatment protocols and patient populations.
- Nursing Facilities:Long-term care facilities employ infusion pumps for residents requiring continuous medication or nutritional support, prioritizing reliability and ease of maintenance.
The shift from traditional settings toward home care is altering procurement models, with ambulatory surgery centers capturing new patient populations.
Delivery Mode:
Device functionality is increasingly defined by its delivery mode, impacting operational flexibility, patient mobility, and integration with broader healthcare IT systems.
- Wireless:Wireless connectivity enables remote monitoring, data transfer to EMR systems, and over-the-air software updates, enhancing safety and operational efficiency in modern healthcare environments. These pumps support decentralized care models and real-time data access.
- Disposable:Disposable infusion pumps are single-use devices, typically elastomeric or gravity-fed, offering a cost-effective and infection-control-friendly option for specific therapies, particularly in outpatient or home care settings. Their simplicity reduces setup time and cross-contamination risks.
- Wired:Wired pumps rely on physical cable connections for power and data, common in traditional hospital environments where consistent power supply and network stability are critical.
- Battery Operated:Battery-operated pumps offer portability and mobility, essential for patient transport within facilities or for home care users who require freedom of movement.
- AC Powered:AC powered pumps are stationary devices connected to wall outlets, providing continuous operation for extended infusions in clinical settings.
Connectivity features are reshaping device utility, while traditional power sources maintain operational reliability.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyer-archetype concentration for infusion pumps is strong in developed economies, where advanced healthcare infrastructure supports complex device adoption. The shift towards home care and ambulatory surgery centers is also redefining procurement priorities. These regions drive innovation and market growth.
United States
The United States market sees demand driven by a high prevalence of chronic diseases and a strong push for technological integration in healthcare. The US FDA's 510(k) pathway sets rigorous standards for device approval and market entry. Boston's medical technology cluster actively fosters innovation in smart pump platforms.
Germany
Germany's market expansion is fueled by an aging demographic and robust growth in the home care segment. The EU's Medical Device Regulation (MDR) significantly impacts market access and post-market surveillance requirements. Southern Germany's MedTech hub actively develops high-precision infusion therapy products.
Japan
Japan exhibits strong demand due to its rapidly aging population and the critical need for advanced chronic disease management solutions. The PMDA oversees rigorous device registration and post-market surveillance for medical technologies. Tokyo's healthcare innovation centers focus on developing miniaturized and portable infusion pumps.
China
China's market grows with rising chronic disease prevalence and expanding healthcare infrastructure across urban and rural areas. China's NMPA imposes stringent standards for device registration and extensive software validation. The Yangtze River Delta region sees significant investment in domestic medical device manufacturing.
France
France emphasizes patient autonomy in pain management, driving demand for PCA pumps within its robust public healthcare system. The ANSM ensures medical device compliance and safety throughout the product lifecycle. Lyon's medical technology ecosystem develops specialized devices for oncology and critical care applications.
Infusion Pump Market Key Industry Players
Player mix skews toward established global medical device conglomerates, alongside specialized manufacturers focusing on niche applications. The market exhibits a tiered structure, with a few large players dominating hospital procurement and numerous smaller entities serving specific clinical needs. These larger entities often pursue portfolio diversification to secure broad health system contracts and enhance interoperability with existing hospital systems. Strategic partnerships and technology licensing are common tactics to expand market reach and integrate new functionalities, especially for smart pump platforms.
Diversified global medical technology providers, such as Becton Dickinson and Company, exemplify broad portfolio strategies aimed at securing extensive health system contracts. Baxter International occupies a position as a specialized therapy provider, focusing on devices for renal care and acute therapies. Germany-based B. Braun Melsungen AG represents precision manufacturing, offering a broad range of infusion therapy products tailored for diverse clinical environments. These entities anchor distinct competitive vectors within the infusion pump market.
| Leading Market Players |
|---|
| Becton Dickinson and Company |
| Baxter International |
| Medtronic |
| B. Braun Melsungen AG |
| ICU Medical |
| Terumo Corporation |
| Fresenius Kabi |
| Smiths Medical |
| F. Hoffmann-La Roche |
| Others |
Cost & Logistics Intelligence
Subscription-based consumption models, particularly in home care, lock in predictable revenue streams for manufacturers and offer flexible operational costs for healthcare providers. These models influence both device pricing and supply chain planning for recurring consumables.
Pricing Analysis
Cost-plus contracts with volume-based indexation often govern large health system procurement for volumetric pumps. The dominant pricing structure is shifting towards a hybrid model, combining per-unit sales for capital equipment with subscription-based services for software and consumables. Price differentiation stems from device precision for critical care applications and advanced software features like EMR integration. Pricing pressure intensifies in the home care segment due to cost-containment initiatives, making smaller healthcare facilities and individual users highly price-sensitive compared to hospitals.
Supply Chain Analysis
Specialized microcontroller fabrication, concentrated in Taiwan, underpins critical component supply for smart infusion pumps. Key manufacturing hubs for medical devices, including Germany, Japan, and the Yangtze River Delta region in China, produce most infusion pump hardware. The supply chain relies on specialized sensors and secure software modules, creating single-source vulnerabilities for high-precision components. Distribution runs through direct sales channels for large health systems and specialized medical distributors for ambulatory centers and home care providers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The infusion pump market is experiencing high-growth disruption, driven by the decentralization of healthcare delivery. Wireless connectivity and EMR integration represent a significant technological inflection point.
For Market Incumbents: Consolidate existing market share by deeply integrating smart pump platforms with hospital EMR systems, enhancing interoperability. Expand home care device portfolios through strategic partnerships to counter the threat from standalone smart pump platforms. Invest heavily in R&D for robust cybersecurity protocols and software validation, addressing regulatory scrutiny and patient safety concerns. This strategy protects against fragmentation and strengthens long-term health system relationships.
For New Entrants and Emerging Players: Differentiate on precision and user experience, targeting underserved niches like pediatric and neonatal intensive care with high-accuracy syringe pumps. Focus on developing standalone smart pump platforms with integrated analytics for ambulatory surgery centers and specialty clinics. A go-to-market angle leveraging flexible, subscription or usage-based pricing models can overcome high capital cost barriers for smaller facilities. This approach allows rapid penetration into growing decentralized care settings.
For Investors and Strategic Acquirers: Capital is best deployed toward specialized manufacturers with strong software IP and established positions in high-growth segments like home care or critical care. Long-term viability over the next decade hinges on robust solutions for chronic disease management and decentralized care. Acquisition targets should exhibit proven capabilities in precision dosing and seamless EMR integration. A key signal to watch for inflection is increased regulatory harmonization for device interoperability and cybersecurity across major markets.
| Strategic Initiative | Industry Significance |
|---|---|
| Software Companion Development | Enhances device functionality and patient safety for Becton Dickinson's smart pumps. |
| Hospital System Partnership | Secures long-term contracts and EMR integration for Baxter International's acute therapy devices. |
| CE Marking Pathway | Ensures market access and regulatory compliance for B. Braun's precision manufacturing products in Europe. |
| Remote Monitoring Integration | Supports chronic disease management in home care settings, expanding market reach. |
| Pediatric Device Design | Addresses critical precision dosing needs for vulnerable neonatal patient populations. |
Research Approach
Operator-level perspectives from clinicians, hospital purchasing committees, and biomedical engineers anchored the qualitative base for this analysis. Primary interviews were triangulated with extensive secondary validation, drawing insights from regulatory filings like US FDA 510(k) submissions, EU MDR guidelines, and China NMPA registrations. A robust bottom-up and top-down approach ensured comprehensive data synthesis across diverse market segments.
Sensitivity analysis was applied to project market trajectories across the analysis window, integrating various macro and microeconomic variables. The analytical framework modeled segmentation dimensions including product type, therapy area, end-user environment, and regulatory approval status. Compound annual growth rates were derived from historical trends, projected technological advancements, and evolving chronic disease prevalence.
Material uncertainties — evolving regulatory frameworks and unforeseen cybersecurity breaches — sit outside the modeled envelope, influencing forecast outcomes. All forecasts reflect assumptions regarding technological adoption rates and healthcare policy shifts. Practitioners should keep alternative scenarios live as device interoperability standards and market decentralization evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Pen Needles Market
Medical Devices
Anti-Infective Endotracheal Tube Market
Medical Devices
Breast Biopsy Marker Market
Medical Devices
Venturi Mask Market
Medical Devices
Russia Viscosupplementation Market
Medical Devices
Mobile Healthcare Devices Market
Medical Devices
Hemodynamic Flow Alteration Devices Market
Medical Devices
Arthroscopy Visualization Systems Market
Medical Devices
Light Therapy Beauty Devices Market
Medical Devices
EMEA Surgical Microscopes Market
Medical Devices
Global Glucometer Market
Medical Devices
Nerve Repair and Regeneration Market
Medical Devices
Europe Artificial Organs and Bionic Implants Market
Medical Devices
Medical Pendant Market
Medical Devices
Interatrial Shunt Devices Market
Medical Devices
Dosage Unit Sampling Apparatus Market