
 Breast Biopsy Marker Market | 2026-2036
Breast Biopsy Marker Market Size, Share, and Industry Trends Forecast 2026-2036
Breast Biopsy Marker Market Insights
Asset-light leasing models for stereotactic biopsy systems is rewriting capital deployment across outpatient imaging chains. Hologic leverages captive financing programs to lock in multi-year clip marker supply contracts. Becton Dickinson and Company anchors hospital system loyalty through bundled biopsy device and marker portfolios. Merit Medical Systems differentiates via direct sales teams embedded in ambulatory surgical centers.
A breast biopsy marker is a permanent radiopaque implant placed at a biopsy site to enable future localization, typically composed of surgical-grade stainless steel, titanium, or bioabsorbable polymers with a size profile under 3 mm for ultrasound and mammographic visibility. Clip markers dominate installed base volumes due to universal compatibility with stereotactic tables, while seed markers sustain premium positioning in MRI-guided workflows where ferromagnetic safety dictates titanium composition. Mammography guidance occupies the largest technology share reflecting screening-detected lesion volumes, though MRI guidance leads growth trajectory amid rising high-risk patient surveillance protocols.
FDA 510(k) clearance requirements shape product iteration cycles and predicate device selection for clip marker manufacturers, while EU MDR technical documentation demands are extending time-to-market for European distribution. ISO 13485 quality system certification operates as a baseline qualification for contract manufacturing relationships across the supply base. Stakeholders must monitor reimbursement coding alignment between biopsy procedure RVUs and marker add-on payments as site-of-care shifts accelerate.
Market Dynamics
Site-of-care migration from inpatient to ambulatory settings is compressing procurement cycles and forcing manufacturers to reconfigure distribution networks around outpatient imaging chains and surgical centers rather than traditional hospital supply agreements.
Growth Catalysts
- FDA 510(k) clearance pathway:Predicate device frameworks accelerate clip marker iterations, reducing time-to-market for titanium and bioabsorbable variants.
- High-risk patient surveillance protocols:MRI-guided biopsy volumes expand seed marker demand across tertiary oncology centers managing hereditary cancer syndromes.
- Stereotactic table compatibility:Universal clip marker architecture locks in replacement demand as installed base of biopsy systems ages.
Market Restraints
- Titanium feedstock concentration:Aerospace and medical device competition for surgical-grade titanium creates input cost volatility.
- EU MDR technical documentation:Extended conformity assessment timelines delay European commercialization for bioabsorbable polymer markers.
- Seed marker MRI artifact limitation:Ferromagnetic safety requirements constrain material selection and manufacturing flexibility.
Strategic Opportunities
- Underpenetrated ambulatory surgical centers:Direct sales embedding captures procurement authority as biopsy volume shifts outside hospital walls.
- Dual-energy mammography convergence:Spectral imaging compatibility requirements create premium positioning for composition-optimized markers.
- IRA screening expansion provisions:Enhanced reimbursement for preventive services expands addressable patient pools in federally qualified health centers.
Industry Challenges
- ISO 13485 certification backlog:Contract manufacturer qualification delays constrain supply base expansion.
- Legacy PACS integration friction:Marker visualization protocols require software customization across heterogeneous radiology IT environments.
- Specialized sales force scaling:Embedded clinical specialists demand higher training investment than traditional distributor models.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Breast Biopsy Marker Market |
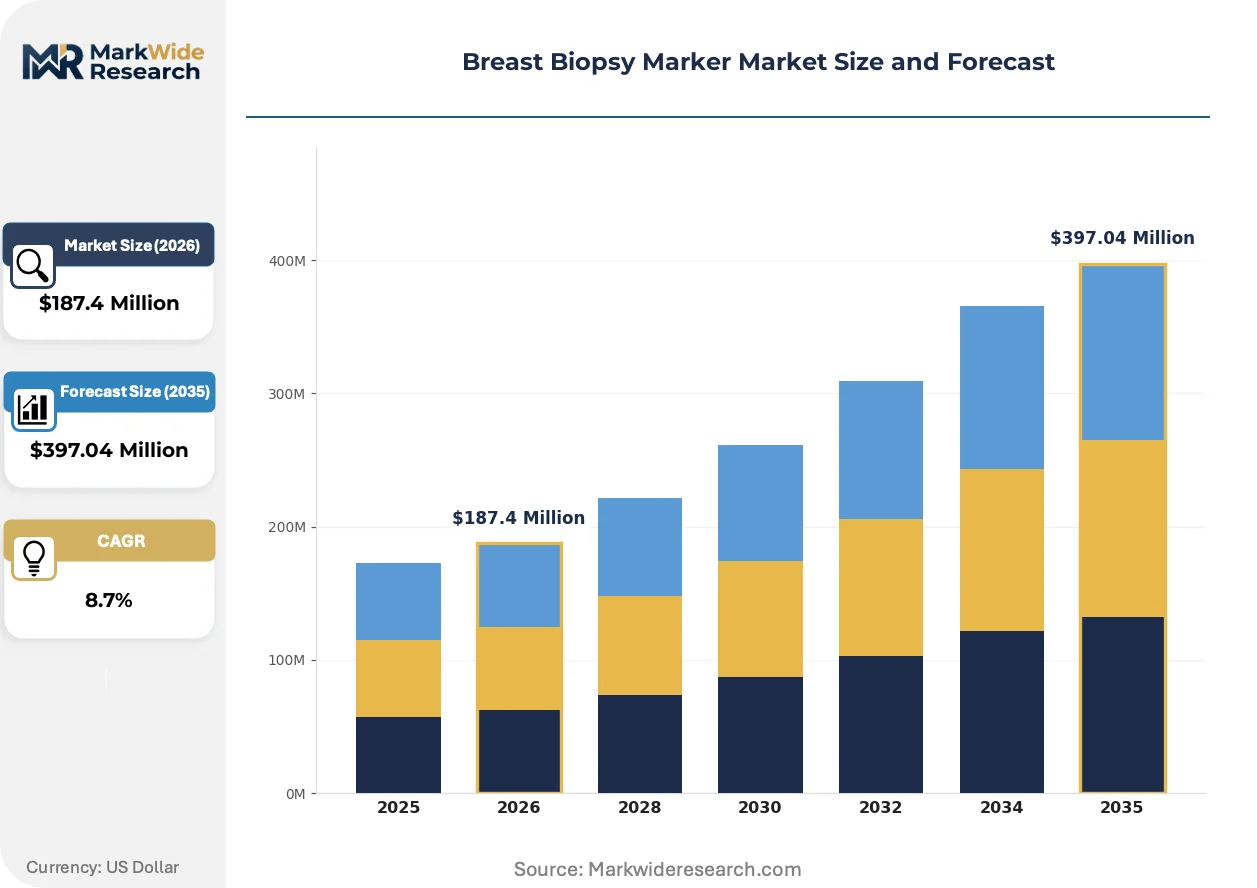
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wire Markers, Seed Markers, Clip Markers, Tattoo Markers Technology: Ultrasound Guidance, MRI Guidance, Mammography Guidance, CT Guidance End User: Hospitals, Diagnostic Centers, Cancer Treatment Facilities, Research Institutes Distribution Channel: Direct Sales, Online Stores, Medical Device Distributors, Wholesale Suppliers |
| Companies Covered | Hologic, Becton Dickinson and Company, Devicor Medical Products, Argon Medical Devices, Merit Medical Systems, Carbon Medical Technologies, Scion Medical Technologies, Mermaid Medical, SOMATEX Medical Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Breast Biopsy Marker Market Trends and Innovations
Marker technology is bifurcating between commodity clip architectures and precision-engineered seed platforms, with software integration emerging as the decisive competitive layer rather than hardware differentiation alone.
Radiofrequency identification is digitizing clip marker traceability from manufacturing through implantation. Ambulatory surgical centers are adopting RFID-enabled inventory systems to automate reorder triggers and expiration management. This convergence is digitizing supply chain visibility and compressing working capital requirements for high-volume biopsy programs.
EU MDR post-market surveillance requirements are extending clinical evidence obligations for permanent implants. Manufacturers must now maintain systematic literature reviews and periodic safety update reports across their marker portfolios. European notified bodies are prioritizing titanium-based devices with established predicate histories, disadvantaging novel bioabsorbable entrants.
Consolidated procurement by outpatient imaging chains is unbundling after-sales service from device supply contracts. Large regional radiology groups now negotiate direct technical support agreements, bypassing manufacturer field service organizations. This pattern concentrates in the United States where private equity-backed imaging platforms aggregate purchasing leverage across multisite networks.
Breast Biopsy Marker Market Segmentation
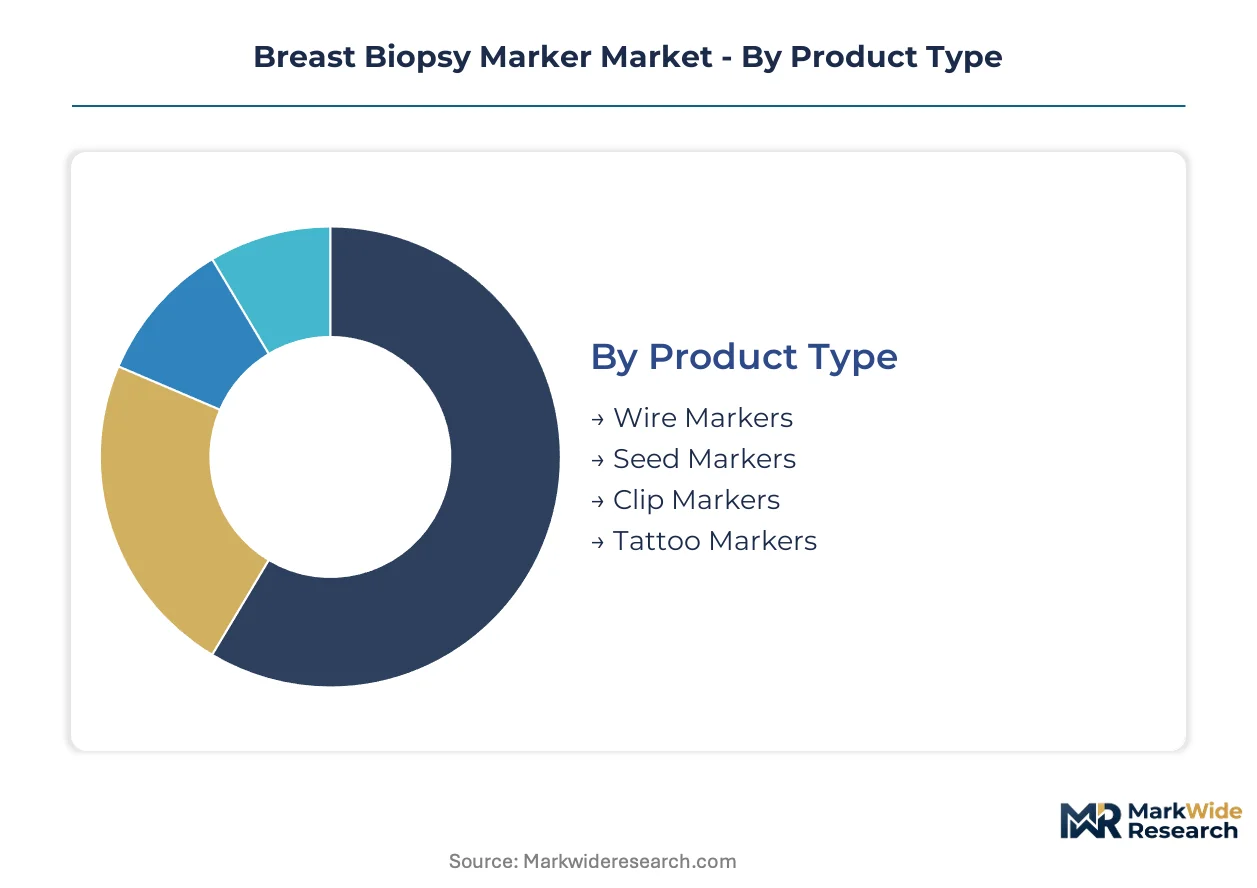
Segmentation in the breast biopsy marker market reveals how procurement authority, imaging modality preferences, and site-of-care economics reshape competitive positioning across distinct customer and technology clusters. Manufacturers must align product portfolios with the specific visibility requirements and reimbursement pathways that govern each segment's purchasing decisions.
Product Type:
Mature metallic architectures dominate current installed bases while bioabsorbable innovations attempt to carve out differentiated positions in high-risk surveillance protocols.
- Clip Markers:Surgical-grade stainless steel or titanium implants under 3 mm with universal stereotactic table compatibility. Demand concentrates in United States outpatient imaging chains where screening-detected lesion volumes sustain replacement cycles across aging biopsy system fleets.
- Seed Markers:Precision-engineered titanium micro-implants optimized for MRI-guided workflows with ferromagnetic safety profiles. Tertiary oncology centers managing hereditary cancer syndromes drive procurement as high-risk patient surveillance protocols expand seed marker utilization.
- Wire Markers:Traditional localization wires retained in select lumpectomy planning scenarios.
- Tattoo Markers:Permanent skin marking systems for post-biopsy site identification in resource-limited settings.
Clip markers retain volume leadership; seed markers hold the steepest expansion curve amid MRI-guided biopsy growth.
Technology:
Imaging modality selection directly determines marker composition specifications and the regulatory pathways manufacturers must navigate for commercial clearance.
- Mammography Guidance:The foundational technology for screening-detected lesions with established reimbursement codes and predicate device histories. United States breast cancer screening compliance rates among OECD members sustain the largest technology share.
- MRI Guidance:Expanding fastest across tertiary centers managing BRCA-positive and high-risk surveillance cohorts where ferromagnetic safety requirements dictate titanium-only marker compositions.
- Ultrasound Guidance:Real-time visualization for palpable and sonographically apparent lesions in ambulatory settings.
- CT Guidance:Specialized thoracic and deep tissue biopsy applications outside standard breast imaging protocols.
Mammography guidance commands the largest patient volume base; MRI guidance is climbing the fastest as high-risk surveillance protocols proliferate.
End User:
Site-of-care migration from inpatient to ambulatory settings fragments procurement authority and forces reconfigured distribution strategies.
- Diagnostic Centers:Outpatient imaging chains aggregating purchasing leverage across multisite networks through consolidated procurement. Private equity-backed radiology platforms in the United States bypass manufacturer field service organizations to negotiate direct technical support agreements.
- Ambulatory Surgical Centers:Embedded direct sales teams capture procurement authority as biopsy volume shifts outside hospital walls. RFID-enabled inventory systems automate reorder triggers and compress working capital requirements.
- Hospitals:Traditional inpatient settings with stereotactic biopsy program expansions across North American health systems.
- Cancer Treatment Facilities:Tertiary oncology centers with specialized high-risk patient management protocols.
- Research Institutes:Academic medical centers conducting clinical evidence generation for novel marker compositions.
Diagnostic centers capture the steepest volume gains; ambulatory surgical centers present the most concentrated expansion opportunity for embedded sales models.
Distribution Channel:
Channel strategy must align with customer scale, technical support requirements, and inventory management sophistication across the care continuum.
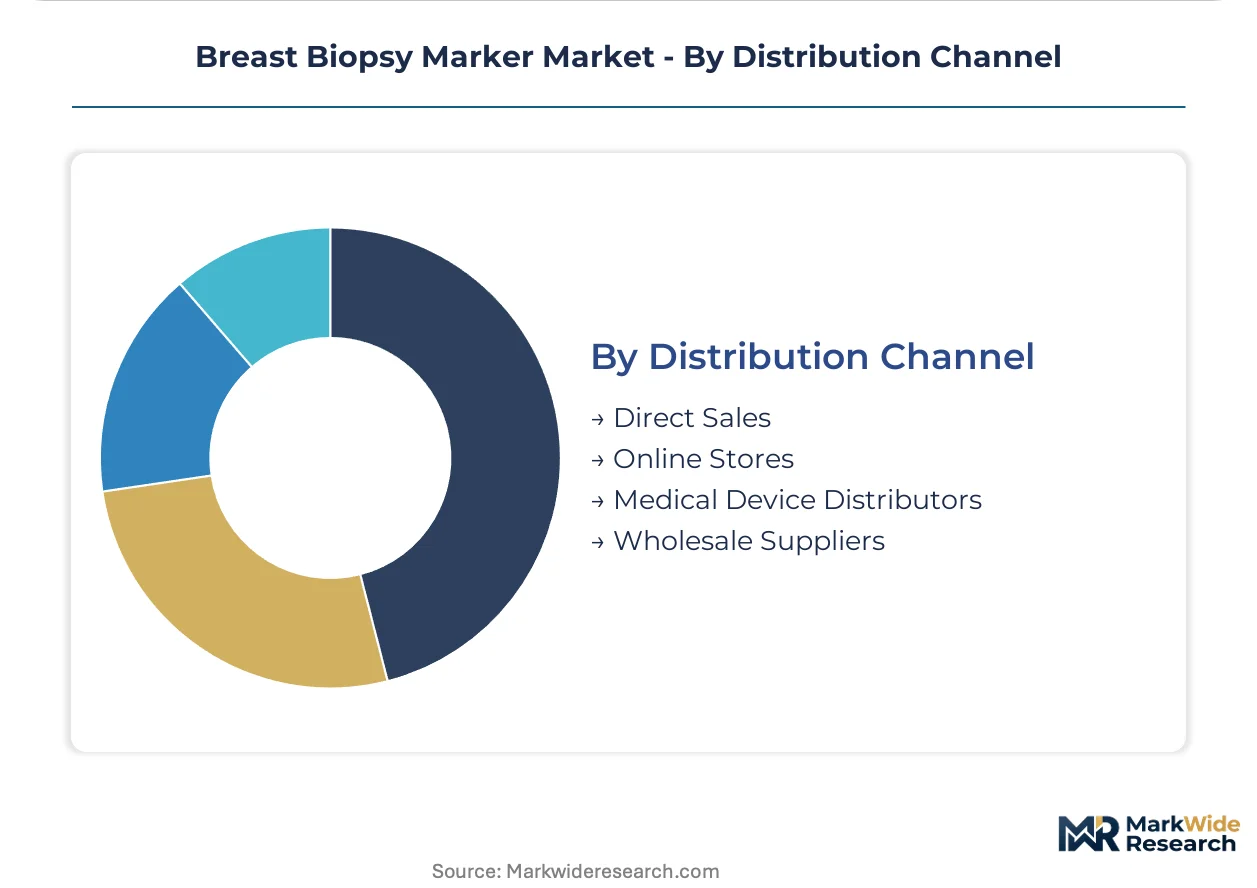
- Direct Sales:Manufacturer-controlled relationships with large regional radiology groups and hospital systems. Bundled biopsy device and marker portfolios anchor loyalty through multi-year supply contracts with captive financing programs.
- Medical Device Distributors:Traditional intermediaries serving mid-scale facilities with localized inventory and field service coverage.
- Online Stores:Emerging procurement pathway for standardized clip markers in cash-pay and international markets.
- Wholesale Suppliers:Volume aggregation for smaller diagnostic centers with limited procurement sophistication.
Direct sales commands margin leadership; medical device distributors maintain the broadest geographic footprint.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Outpatient imaging chains and hospital systems concentrate procurement authority in the United States, while tertiary oncology centers in Germany and Japan drive specialized seed marker demand. Regulatory pathways and reimbursement structures reshape competitive positioning across national markets.
United States
Private equity-backed radiology platforms aggregate purchasing leverage across multisite networks, consolidating procurement for clip markers and stereotactic biopsy systems. The FDA's 510(k) predicate device framework accelerates product iterations for titanium and bioabsorbable variants. Major metropolitan clusters in Texas, California, and the Northeast Corridor host the densest concentrations of ambulatory surgical centers adopting RFID-enabled inventory systems.
Germany
Tertiary oncology centers in Bavaria and North Rhine-Westphalia manage expanding BRCA-positive surveillance cohorts, driving seed marker procurement for MRI-guided workflows. The EU MDR technical documentation requirements extend conformity assessment timelines for novel bioabsorbable polymer entrants. The Baden-Württemberg medical technology corridor anchors manufacturing partnerships for surgical-grade titanium components.
Japan
PMDA regulatory frameworks prioritize established predicate histories for permanent implants, favoring titanium-based clip markers with systematic clinical evidence. The Kanto region around Tokyo concentrates diagnostic imaging infrastructure and high-risk patient surveillance protocols. METI industrial policy supports precision manufacturing capabilities for micro-implant production serving domestic and export markets.
China
NMPA medical device registration pathways are compressing time-to-market for domestic clip marker manufacturers serving tier-one hospital systems. The Yangtze River Delta and Pearl River Delta clusters concentrate contract manufacturing relationships for surgical-grade stainless steel components. Dual carbon policy frameworks are beginning to influence material selection discussions for bioabsorbable polymer development.
United Kingdom
NHS procurement frameworks are consolidating supplier relationships for breast biopsy markers across integrated care systems in England. The UK Medicines and Healthcare products Regulatory Agency aligns with EU MDR post-market surveillance requirements for permanent implants. The Greater Manchester and London/Southeast clusters concentrate specialized cancer treatment facilities managing hereditary cancer syndrome cohorts.
Breast Biopsy Marker Market Competitive Landscape
Channel-controlling players compete with product-specialist players across fragmented procurement authority in outpatient settings. The vendor base organizes around three strategic archetypes: diversified medical device conglomerates with bundled portfolio offerings, dedicated biopsy system manufacturers with captive marker supply, and precision implant specialists serving MRI-guided workflows. Competitive moves center on direct sales force embedding in ambulatory surgical centers and multi-year supply contract anchoring through captive financing programs.
Within the diversified conglomerate tier, Hologic and Becton Dickinson and Company exemplify channel-control strategies through bundled biopsy device and marker portfolios. Merit Medical Systems occupies a position among embedded direct sales specialists targeting ambulatory surgical center procurement authority. These three entities represent distinct competitive archetypes: financing-enabled contract lock-in, hospital system loyalty anchoring, and site-of-care migration capture.
| Leading Market Players |
|---|
| Hologic |
| Becton Dickinson and Company |
| Devicor Medical Products |
| Argon Medical Devices |
| Merit Medical Systems |
| Carbon Medical Technologies |
| Scion Medical Technologies |
| Mermaid Medical |
| SOMATEX Medical Technologies |
| Others |
Pricing and Supply Chain Analysis
Overcapacity in Chinese surgical-grade stainless steel forging is compressing margin structures for clip marker producers while simultaneously enabling aggressive pricing postures among domestic contract manufacturers seeking volume commitments from Western OEMs.
Pricing Analysis
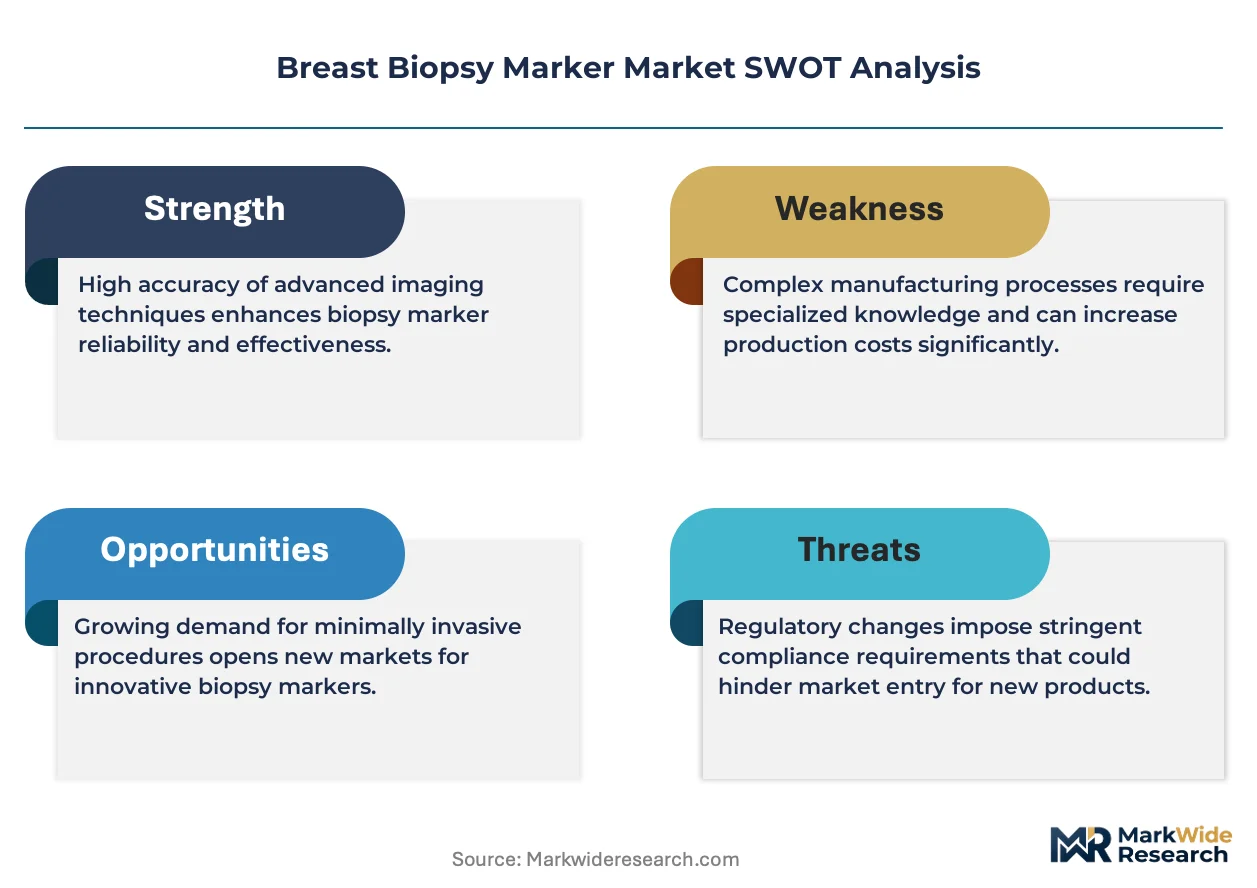
Cost-plus contracts with titanium London Metal Exchange indexation dominate procurement agreements between marker manufacturers and hospital systems. Three-tier pricing structure across premium, standard, and economy levels separates MRI-compatible titanium seeds from stainless steel clips and uncoated economy variants. Pricing pressure stems from consolidated procurement by private equity-backed radiology platforms unbundling service contracts. Ambulatory surgical centers exhibit highest price sensitivity; tertiary oncology centers managing BRCA-positive cohorts show lowest sensitivity due to ferromagnetic safety mandates.
Supply Chain Analysis
Contract manufacturing concentration sits with ISO 13485-certified precision forges in China's Yangtze River Delta, Germany's Baden-Württemberg corridor, and Japan's Kanto region. Raw material dependencies center on surgical-grade titanium sponge, bioabsorbable polylactic acid polymers, and radiopaque tantalum oxide coatings. Single-source vulnerability concentrates in aerospace-qualified titanium mills serving both aviation and medical device demand. Distribution runs through manufacturer direct sales for large hospital systems, with medical device distributors covering mid-scale diagnostic centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market requires substitution defense against liquid biopsy blood tests that threaten to displace tissue biopsy volumes and their associated marker implantation procedures.
For Market Incumbents: Entrench hospital system loyalty through captive financing programs locking in multi-year clip marker supply contracts alongside stereotactic biopsy system leases. Deepen backward integration into surgical-grade titanium forging to secure feedstock against aerospace competition. The priority threat is liquid biopsy sensitivity improvements; the priority lever is ISO 13485 certification maintenance to sustain contract manufacturing relationships. For New Entrants and Emerging Players: Pursue underpenetrated ambulatory surgical centers in Texas and California where RFID-enabled inventory systems create procurement automation demand. Target MRI-guided seed marker niches in tertiary oncology centers where ferromagnetic safety requirements constrain incumbent flexibility. The most penetrable segment is bioabsorbable polymer markers for high-risk surveillance protocols; the go-to-market angle is direct sales embedding with clinical specialist training investment. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across bioabsorbable polymer development as EU MDR clinical evidence obligations extend time-to-market and compress return horizons. Long-term viability favors precision implant specialists with established predicate device histories over novel material entrants. The acquisition target archetype is embedded direct sales organizations with ambulatory surgical center relationships. The signal to watch is FDA 510(k) clearance velocity for titanium variants versus bioabsorbable submissions.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Clearance Pathway | Predicate device frameworks accelerate titanium and bioabsorbable variant iterations for US commercialization. |
| Hospital System Partnership | Multi-year supply contracts with captive financing programs anchor loyalty against unbundled procurement. |
| CE Marking Pathway | EU MDR technical documentation demands extend conformity timelines for European bioabsorbable distribution. |
| Software Companion Development | PACS integration protocols require customization across heterogeneous radiology IT environments. |
| Reimbursement Strategy | RVU alignment between biopsy procedures and marker add-on payments determines site-of-care economics. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA 510(k) filings, CMS Medicare reimbursement databases, hospital GPO contracts, and EU MDR notified body guidance documents. Interviews with clinicians, hospital purchasing committee members, biomedical engineers, and GPO contracts managers informed demand-side dynamics. Secondary validation drew from SEC 10-K disclosures, ISO 13485 certification registries, and trade data on surgical-grade titanium imports. Bottom-up volume modeling triangulates against top-down expenditure analysis across the projection horizon.
Forecast inputs incorporate imaging modality penetration rates, site-of-care migration velocity, and regulatory clearance timelines across product type, technology, end user, and distribution channel segmentations. CAGRs derive from regression analysis against historical biopsy volume correlations with screening compliance rates. Industry-specific inputs include stereotactic table installed base aging curves and MRI-guided biopsy adoption in hereditary cancer syndrome protocols throughout the modeling period.
Sensitivities concentrate around liquid biopsy substitution thresholds, EU MDR conformity assessment delays, and titanium feedstock allocation shifts between aerospace and medical device demand. Forecasts reflect documented assumptions on screening compliance maintenance and reimbursement stability. Quarterly review of FDA 510(k) submission velocity, NMPA registration timelines, and liquid biopsy clinical trial readouts is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Vaginal Applicators Market
Medical Devices
Global Medical Suction Devices Market
Medical Devices
Global Smart Contact Lenses Market
Medical Devices
Global Gynecological Dilators Market
Medical Devices
Digital Phoropter Market
Medical Devices
Medical Oxygen Sensors Market
Medical Devices
Sperm Separation Systems Market
Medical Devices
Global Hemostasis Valves Market
Medical Devices
Mhealth (Mobile Health) Devices Market
Medical Devices
Soft Tissue Markers Market
Medical Devices
Orthokeratology Lens Market
Medical Devices
Breast Localization System Market
Medical Devices
Expandable Interbody Fusion System Market
Medical Devices
Liposuction Devices Market
Medical Devices
Global Airway Stent/Lung Stent Market
Medical Devices
Hip Kits Market