
 Russia Viscosupplementation Market | 2026-2036
Russia Viscosupplementation Market Size, Share, and Industry Trends Forecast 2026-2036
Russia Viscosupplementation Market Analytics
Leasing arrangements for hyaluronic acid injection equipment is reshaping competitive access for mid-sized orthopedic clinics across Russia. Sanofi S.A leverages its established hospital formulary relationships to sustain premium positioning in major federal centers. Anika Therapeutics Inc. anchors its presence through specialized viscosupplement formulations targeting stage-specific osteoarthritis progression. Zimmer Biomet Holdings, Inc. competes by bundling intra-articular delivery systems with its broader joint preservation portfolio.
Viscosupplementation denotes intra-articular injection of high-molecular-weight hyaluronic acid derivatives, typically ranging from 500 to 6,000 kDa, to restore synovial fluid viscoelasticity and cushion load-bearing joints. The therapy primarily serves osteoarthritis management where pharmacological intervention fails to delay surgical endpoints. Sodium hyaluronate formulations dominate current revenue pools given their established reimbursement coding and clinician familiarity, while combination therapy integrating chondroitin sulfate represents the fastest-expanding segment as compound formulations demonstrate superior pain scores in Russian orthopedic registries. Gelatin-based alternatives occupy a niche position constrained by limited domestic manufacturing capacity and import dependency.
Russia's Ministry of Health and Roszdravnadzor jointly govern medical device registration, with mandatory clinical trials for novel hyaluronic acid formulations creating multi-year barriers to market entry. National standards compliance for intra-articular injectables shapes quality thresholds that filter out uncertified imports, particularly from non-EAEU jurisdictions. Stakeholders must monitor evolving Eurasian Economic Union harmonization protocols and domestic substitution incentives that will determine whether local production partnerships or direct import licenses offer superior long-term access.
Market Dynamics
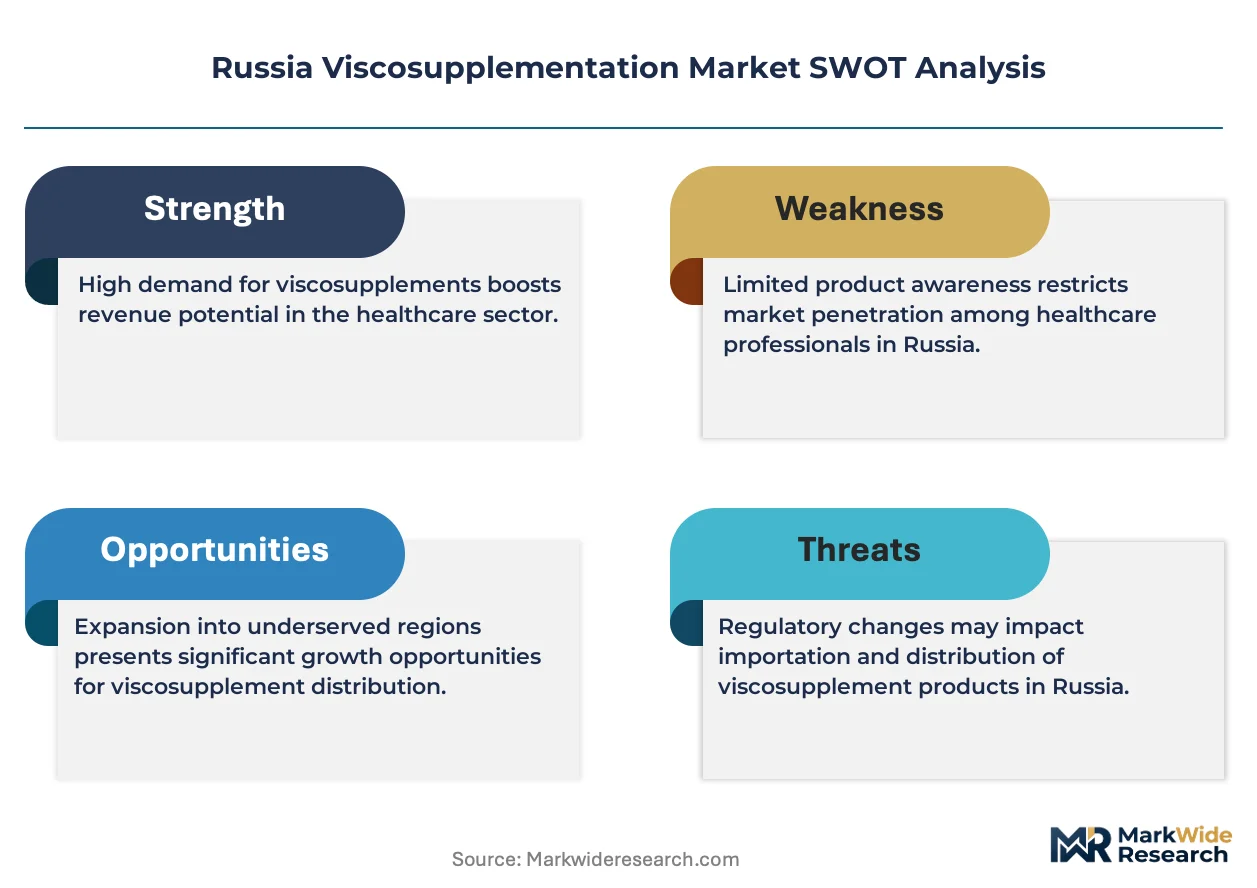
Russia's tightening medical device registration protocols under Roszdravnadzor are compressing competitive entry timelines and forcing incumbent suppliers to deepen clinical evidence portfolios for hyaluronic acid formulations.
Growth Catalysts
- Roszdravnadzor Registration Harmonization:Eurasian Economic Union technical regulation convergence is reducing duplicate certification burdens for established sodium hyaluronate manufacturers operating across member states.
- Orthopedic Clinic Network Expansion:Regional healthcare modernization programs are equipping mid-sized cities with arthroscopy capabilities previously concentrated in Moscow and Saint Petersburg.
- Stage-Specific Formulation Pipelines:Chondroitin sulfate combination therapies are capturing clinician preference in Russian orthopedic registries through demonstrably superior pain outcome profiles.
Market Restraints
- Import Dependency for Gelatin Matrices:Domestic manufacturing capacity for alternative viscosupplement bases remains underdeveloped, exposing supply chains to currency volatility and cross-border logistics friction.
- Multi-Year Clinical Trial Mandates:Russia's Ministry of Health requirements for novel hyaluronic acid molecular weights create extended capital lockup periods that filter out smaller international entrants.
- Reimbursement Code Rigidity:Established sodium hyaluronate reimbursement categories create institutional inertia that slows adoption of emerging combination formulations despite clinical evidence.
Strategic Opportunities
- Volga Federal District Undersupply:Kazan and Nizhny Novgorod arthroscopy centers operate below equipment utilization thresholds, creating first-mover positioning for leasing-based equipment access models.
- Domestic Substitution Incentives:Russian industrial policy frameworks are channeling capital toward local production partnerships that bypass direct import licensing complexity.
- Telemedicine-Enabled Injection Training:Remote physician education platforms are collapsing geographic barriers to technique standardization for intra-articular delivery procedures.
Industry Challenges
- Synovial Fluid Biomarker Validation:Russian orthopedic registries lack standardized molecular outcome metrics, complicating head-to-head formulation efficacy documentation for registration dossiers.
- Cold Chain Integrity Across Taiga Logistics Corridors:Temperature-sensitive hyaluronic acid stability requirements strain distribution infrastructure serving Siberian and Far Eastern federal districts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Russia Viscosupplementation Market |
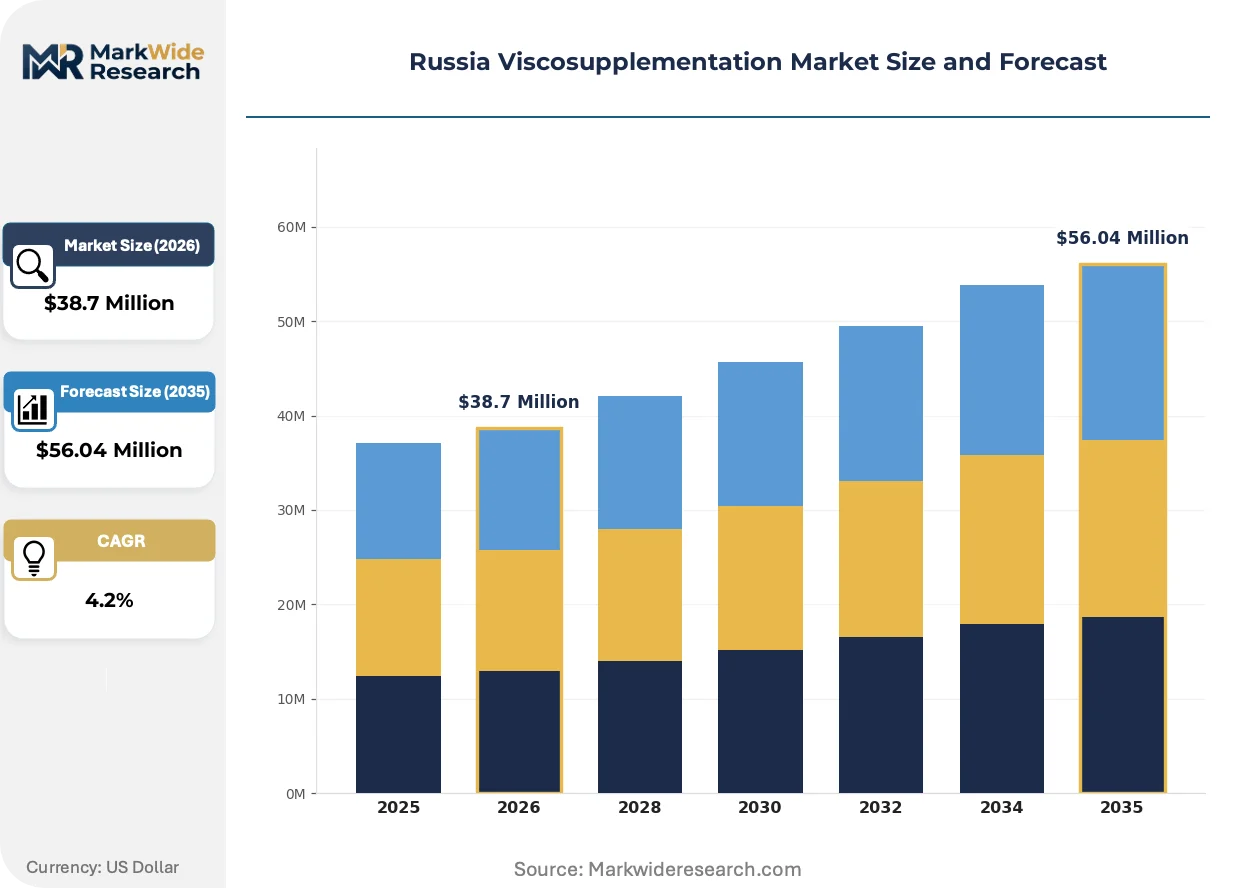
| Market Size in 2026 | $38.7 Million |
| Market Size in 2035 | $56.04 Million |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sodium Hyaluronate, Gelatin, Chondroitin Sulfate, Others Therapy Area: Osteoarthritis, Sports Injuries, Joint Pain, Tendonitis End User: Orthopedic Clinics, Hospitals, Rehabilitation Centers, Sports Facilities Delivery Mode: Intra-articular Injection, Topical Application, Combination Therapy, Others |
| Companies Covered | Hyaltech, Croma-Pharma GmbH, TRB Chemedica, Anika Therapeutics Inc., Bioventus LLC, Ferring B.V, Fidia Pharmaceutici S.p.A, Sanofi S.A, Zimmer Biomet Holdings, Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Russia Viscosupplementation Market Evolving Landscape
Digital injection guidance systems and molecular characterization advances are compressing the gap between empirical dosing protocols and precision orthopedic therapy in Russian clinical practice.
Cross-linked hyaluronic acid derivatives with extended residence times are virtualizing the traditional repeat-injection cycle for moderate osteoarthritis cases. Regional orthopedic networks in the Central Federal District are piloting these formulations for patient cohorts previously managed through quarterly sodium hyaluronate administration. This molecular engineering trajectory is virtualizing revenue models away from volume-based injection schedules toward outcome-guaranteed single-procedure pricing.
Russia's Ministry of Health technical regulation 1416n mandates biocompatibility testing protocols for intra-articular injectables that exceed baseline EAEU harmonization requirements. Domestic manufacturers with established toxicology laboratories are capturing accelerated review timelines while importers face extended documentation cycles. The Saint Petersburg and Moscow specialized arthroscopy centers are responding by consolidating formulary decisions around suppliers with proven Roszdravnadzor track records.
Leasing arrangements for hyaluronic acid injection equipment are displacing capital purchase models among mid-sized orthopedic clinics in the Urals and Volga regions. Equipment vendors are bundling maintenance, consumable supply, and clinician training into per-procedure fee structures that align clinic cash flows with patient throughput. This financial restructuring is most visible in Nizhny Novgorod and Yekaterinburg, where private clinic chains are consolidating procurement decisions at the network level rather than individual facility autonomy.
Russia Viscosupplementation Market Segmentation
Viscosupplementation segmentation in Russia reflects the tension between established clinical protocols and emerging therapeutic combinations. Product chemistry, therapy focus, and delivery infrastructure each create distinct competitive battlegrounds for market access.
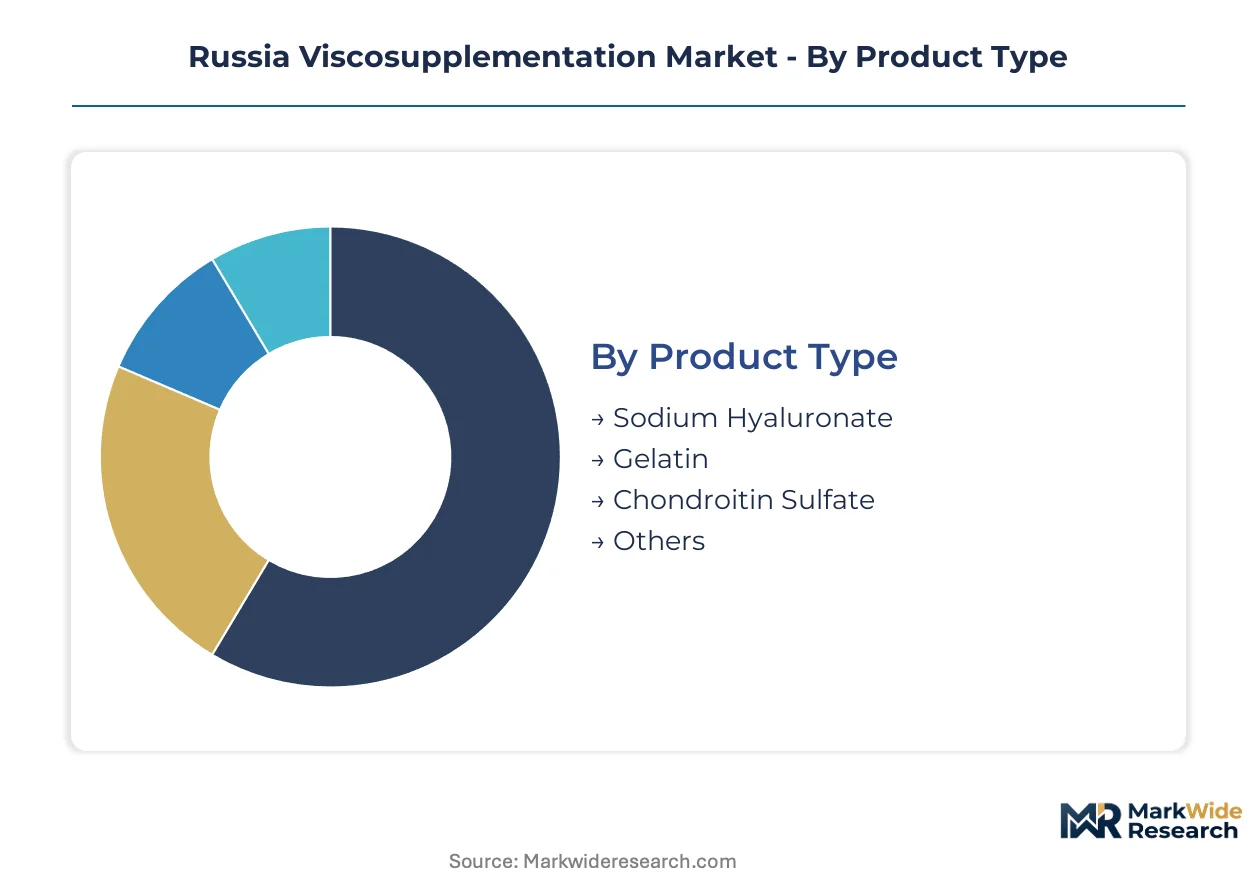
Product Type:
Formulation chemistry spans synthetic polymers to biological matrices, with reimbursement coding and domestic manufacturing capacity shaping commercial viability across the spectrum.
- Sodium Hyaluronate:High-molecular-weight formulations ranging from 500 to 6,000 kDa dominate Russian orthopedic registries through established reimbursement categories and clinician familiarity. Moscow and Saint Petersburg arthroscopy centers anchor demand, though Roszdravnadzor registration requirements filter out uncertified imports from non-EAEU jurisdictions.
- Chondroitin Sulfate:Compound formulations integrating hyaluronic acid demonstrate superior pain scores in Russian clinical data, capturing preference among stage-specific osteoarthritis protocols. Regional healthcare modernization programs in the Volga Federal District are accelerating adoption as mid-sized cities gain arthroscopy capabilities.
- Gelatin:Alternative viscosupplement bases occupy niche positioning constrained by limited domestic manufacturing capacity and import dependency on currency-volatile supply chains.
- Others:Emerging matrices including cross-linked derivatives and extended-residence formulations pilot in Central Federal District networks under outcome-guaranteed pricing models.
The dominant share belongs to Sodium Hyaluronate, while Chondroitin Sulfate is closing the gap fastest.
Therapy Area:
Clinical application intensity varies sharply by pathology severity and surgical alternative availability, with federal center concentration determining protocol diffusion speed.
- Osteoarthritis:Primary indication driving intra-articular injection volumes, where pharmacological intervention delays surgical endpoints for load-bearing joint degradation. Kazan and Nizhny Novgorod centers operate below equipment utilization thresholds, creating expansion headroom.
- Sports Injuries:Acute trauma applications concentrate in specialized rehabilitation networks serving professional athletic programs, with telemedicine-enabled injection training collapsing geographic barriers to technique standardization.
- Joint Pain:Symptom management protocols in regional hospitals face reimbursement code rigidity that slows adoption of emerging combination formulations despite clinical evidence.
- Tendonitis:Peripheral application niche constrained by limited synovial fluid biomarker validation in Russian orthopedic registries, complicating head-to-head efficacy documentation.
Osteoarthritis commands the volume base, though Sports Injuries applications are expanding most quickly through private clinic chain consolidation.
End User:
Facility type determines procurement autonomy, capital access, and formulary decision speed, with network-level consolidation reshaping vendor relationships.
- Orthopedic Clinics:Specialized arthroscopy centers cluster in Moscow and Saint Petersburg, with leasing arrangements for injection equipment displacing capital purchase models among mid-sized facilities in the Urals and Volga regions.
- Hospitals:Federal centers maintain premium formulary positioning through established hospital relationships, while regional facilities face extended capital lockup periods from multi-year clinical trial mandates for novel molecular weights.
- Rehabilitation Centers:Post-acute care settings pilot cross-linked derivatives with extended residence times, virtualizing traditional repeat-injection cycles toward outcome-guaranteed single-procedure pricing.
- Sports Facilities:Athletic program partnerships create concentrated demand pockets with specialized training requirements and performance-timeline pressures distinct from general orthopedic protocols.
Orthopedic Clinics retain the structural advantage, yet Rehabilitation Centers are gaining share fastest through bundled per-procedure fee structures.
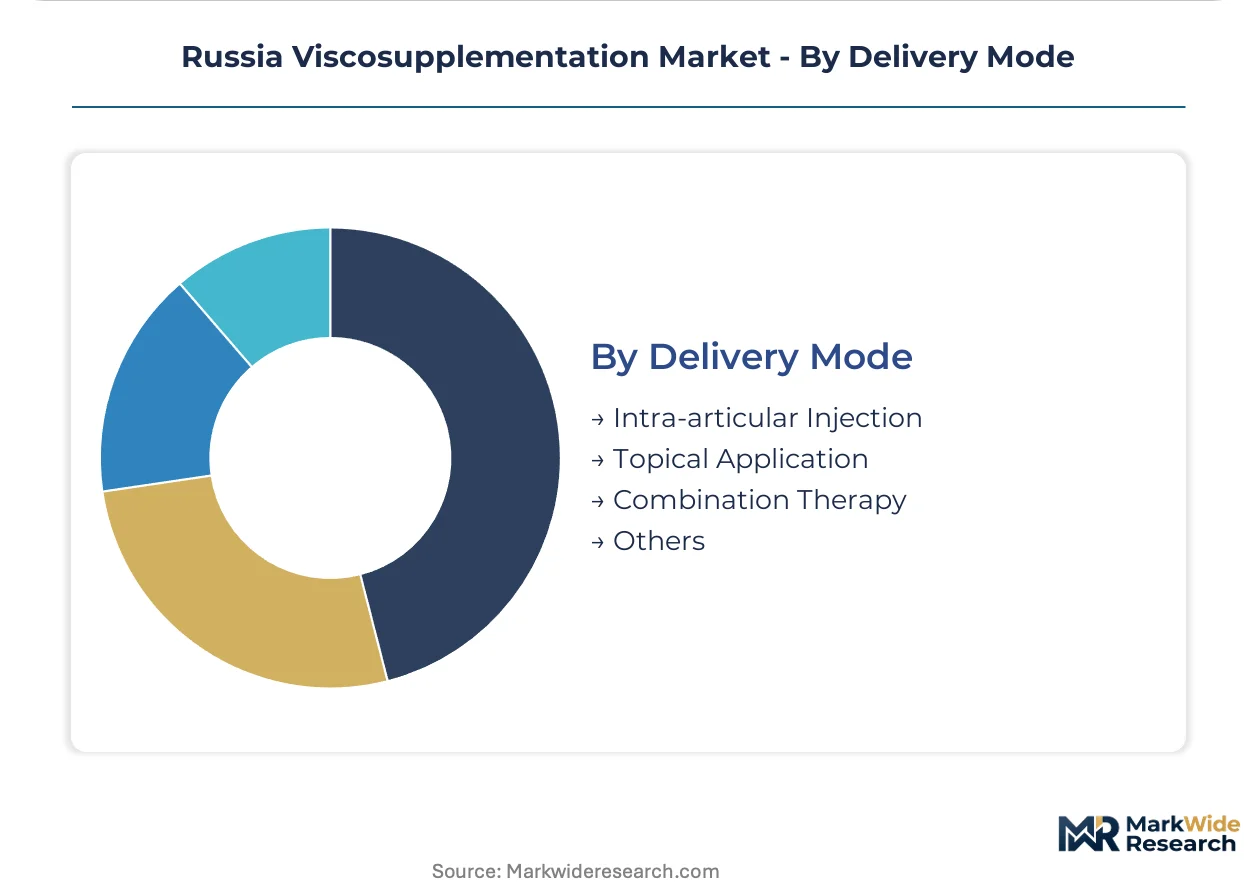
Delivery Mode:
Administrative technique and combination protocols segment by precision requirements, repeat frequency, and clinician training investment.
- Intra-articular Injection:Direct joint space delivery remains the standard of care, with cold chain integrity requirements straining distribution infrastructure across Siberian and Far Eastern federal districts.
- Combination Therapy:Integrated protocols pairing viscosupplements with adjunct modalities capture preference in Russian orthopedic registries through demonstrably superior pain outcome profiles.
- Topical Application:Non-invasive alternatives occupy peripheral positioning given limited evidence base for hyaluronic acid penetration through intact skin barriers.
- Others:Experimental delivery mechanisms including digital injection guidance systems pilot in Central Federal District networks, compressing gaps between empirical dosing and precision therapy.
Intra-articular Injection maintains procedural dominance, while Combination Therapy shows the steepest expansion trajectory through registry-documented outcome advantages.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Orthopedic clinics in Moscow and Saint Petersburg concentrate procurement decisions, while regional healthcare modernization redistributes demand across the Central, Volga, and Ural federal districts.
Central Federal District
Moscow's specialized arthroscopy centers anchor sodium hyaluronate consumption through established reimbursement categories. Roszdravnadzor registration requirements filter uncertified imports, privileging suppliers with proven compliance track records. The Moscow cluster consolidates formulary decisions around hospital formulary relationships that sustain premium positioning.
Volga Federal District
Kazan and Nizhny Novgorod arthroscopy centers operate below equipment utilization thresholds, creating expansion headroom for leasing-based access models. Regional healthcare modernization programs equip mid-sized cities with capabilities previously concentrated in capital cities. Private clinic chains in Nizhny Novgorod consolidate procurement decisions at network level rather than individual facility autonomy.
Northwestern Federal District
Saint Petersburg orthopedic networks pilot cross-linked derivatives with extended residence times under outcome-guaranteed pricing models. The city's specialized centers respond to Ministry of Health technical regulation 1416n by consolidating around suppliers with established toxicology documentation. Saint Petersburg manufacturers with domestic laboratories capture accelerated Roszdravnadzor review timelines.
Ural Federal District
Yekaterinburg clinics displace capital purchase models with per-procedure fee structures bundling equipment, maintenance, and clinician training. Cold chain integrity requirements strain distribution infrastructure serving this transcontinental corridor. Regional facilities face extended capital lockup periods from multi-year clinical trial mandates for novel molecular weights.
Siberian Federal District
Temperature-sensitive hyaluronic acid stability requirements challenge distribution infrastructure across taiga logistics corridors. Telemedicine-enabled injection training collapses geographic barriers to technique standardization for regional orthopedic protocols. Rehabilitation centers in Novosibirsk pilot bundled per-procedure fee structures that align clinic cash flows with patient throughput.
Russia Viscosupplementation Market Competitive Landscape
Channel-controlling players compete with product-specialist players across tiered access points defined by hospital formulary relationships and regional clinic network consolidation. The structure concentrates around established registrants with Roszdravnadzor track records and mid-sized entrants leveraging equipment leasing to bypass capital barriers. Three archetypes dominate: multinational pharmaceutical holdings with hospital formulary anchoring, specialized orthopedic device manufacturers with joint preservation bundling, and regional equipment-as-a-service providers collapsing geographic barriers. Competitive moves center on domestic production partnerships that bypass direct import licensing complexity, and telemedicine-enabled training platforms that standardize injection techniques across dispersed clinic networks.
Among European-anchored pharmaceutical specialists, Sanofi S.A and Ferring B.V occupy positions sustained by hospital formulary relationships in major federal centers. Anika Therapeutics Inc. exemplifies the product-specialist archetype through formulation differentiation targeting stage-specific osteoarthritis progression. These three represent distinct competitive vectors: formulary-controlled access, molecular engineering specialization, and bundled delivery system integration.
| Leading Market Players |
|---|
| Hyaltech |
| Croma-Pharma GmbH |
| TRB Chemedica |
| Anika Therapeutics Inc. |
| Bioventus LLC |
| Ferring B.V |
| Fidia Pharmaceutici S.p.A |
| Sanofi S.A |
| Zimmer Biomet Holdings, Inc. |
| Others |
Value Network & Pricing Analysis
Moscow and Saint Petersburg arthroscopy centers concentrate procurement decisions for high-molecular-weight sodium hyaluronate, with their joint purchasing power compressing margins for uncertified imports while elevating premium tiers for Roszdravnadzor-registered suppliers. Cold chain infrastructure gaps across Siberian logistics corridors amplify geographic price spreads, linking supply reliability directly to clinic willingness to pay.
Pricing Analysis
Certification level creates the primary spread between EAEU-registered formulations and non-harmonized imports. Pricing stratifies across premium, standard, and economy tiers, with EAEU technical regulation compliance commanding 15-25% premiums over uncertified alternatives. Cost compression in the economy tier is intensifying because mid-sized clinics in the Volga Federal District consolidate network-level procurement decisions. Hospital purchasing committees at federal centers exhibit lowest price sensitivity, while private clinic chains in Yekaterinburg and Nizhny Novgorod negotiate aggressively on per-procedure fee structures.
Supply Chain Analysis
Export-control restrictions on pharmaceutical-grade hyaluronic acid fermentation technology limit technology transfer to Russian domestic manufacturers. Active pharmaceutical ingredient supply concentrates in China, South Korea, and select Western European jurisdictions, with finished formulation filling operations distributed across EAEU member states. Raw material dependencies include high-purity glucose substrates, specialized fermentation vessels, and molecular weight filtration membranes. Single-source vulnerability characterizes the gelatin matrix segment due to underdeveloped domestic capacity. Distribution runs through temperature-controlled logistics networks serving Moscow and Saint Petersburg hubs, with secondary routing to regional arthroscopy centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through private clinic chain consolidation in the Urals and Volga regions, with network-level procurement decisions displacing individual facility autonomy and compressing vendor margins.
For Market Incumbents: Pre-empt equipment leasing disruption by embedding consumable supply contracts into multi-year clinic partnerships before regional chains finalize vendor selections. Deepen Roszdravnadzor registration moats through toxicology laboratory investments that accelerate review timelines relative to import-dependent competitors. Vertical integration into domestic fermentation capacity hedges currency exposure on API imports. For New Entrants and Emerging Players: Establish a beachhead in the chondroitin sulfate combination therapy segment, where reimbursement code rigidity has slowed incumbent response despite superior Russian registry outcomes. Target Kazan and Nizhny Novgorod arthroscopy centers operating below equipment utilization thresholds, offering leasing-based access models that bypass capital purchase barriers. Lead with telemedicine-enabled injection training to collapse geographic barriers to technique standardization. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among equipment-as-a-service providers bundling maintenance, consumables, and clinician training into per-procedure fee structures. Long-term viability hinges on domestic production partnerships that bypass direct import licensing complexity under evolving substitution incentives. Watch for Roszdravnadzor registration backlog clearance as inflection indicator for competitive entry timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Domestic Manufacturing Partnership | Local production bypasses EAEU import licensing complexity and captures accelerated Roszdravnadzor review timelines. |
| Telemedicine-Enabled Training Platform | Remote physician education collapses geographic barriers to intra-articular injection technique standardization across dispersed clinics. |
| Cross-Linked Formulation Development | Extended-residence hyaluronic acid derivatives virtualize repeat-injection revenue toward outcome-guaranteed single-procedure pricing. |
| Regional Clinic Network Consolidation | Network-level procurement decisions in Nizhny Novgorod and Yekaterinburg displace individual facility vendor autonomy. |
| Chondroitin Sulfate Combination Registration | Compound formulations demonstrate superior pain scores in Russian orthopedic registries despite reimbursement code inertia. |
Research Methodology
Desk research of Roszdravnadzor registration databases, EAEU technical regulation harmonization protocols, and Russian Ministry of Health reimbursement coding preceded structured interviews with orthopedic clinic procurement directors, arthroscopy center medical directors, pharmaceutical regulatory affairs specialists, and regional healthcare modernization program administrators. Secondary validation drew from hospital procurement databases, GPO contract filings, and clinical registry outcome publications. Bottom-up clinic-level demand estimation triangulated against top-down Ministry of Health expenditure forecasts.
Assumptions held fixed across the modeling period include EAEU technical regulation convergence trajectory, Roszdravnadzor clinical trial mandate stringency, and regional healthcare modernization program funding continuity. Variables stress-tested included currency volatility on API imports, domestic substitution incentive intensity, and cold chain infrastructure investment pace. Segmentation dimensions spanned product chemistry, therapy area severity, end-user facility type, and delivery mode complexity. CAGRs derived from fitted growth curves anchored to clinic network expansion rates and formulation adoption diffusion patterns.
Stress conditions across reimbursement code expansion timelines, gelatin matrix import dependency, and telemedicine regulatory clarity were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect these documented assumptions and variable ranges. Material shifts in EAEU harmonization protocol implementation or Roszdravnadzor registration backlog resolution would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Dual Chamber Prefilled Syringes Market
Medical Devices
UHD Surgical Display Market
Medical Devices
Veterinary Procedure Lights Market
Medical Devices
Global Esophageal Catheters Market
Medical Devices
Nerve Stimulators Market
Medical Devices
Passive Prosthetics Market
Medical Devices
Single Use Contact Lenses Market
Medical Devices
North America Invisible Orthodontics Market
Medical Devices
Ultrasonic Dissection Devices Market
Medical Devices
Global Trauma Fixation Devices Market
Medical Devices
Robotic Surgical Procedures Market
Medical Devices
Italy Respiratory Devices Market
Medical Devices
Medical Injection Molding Machine Market
Medical Devices
Japan Respiratory Devices Market
Medical Devices
3D Printed Brain Model Market
Medical Devices
United States Ultrasound Devices Market