
 Venturi Mask Market | 2026-2036
Venturi Mask Market Size, Share, and Industry Trends Forecast 2026-2036
Venturi Mask Market Outlook
China is narrowing its import dependence for respiratory consumables through expanded domestic molding capacity and polymer compounding investments. Fisher & Paykel Healthcare anchors its position through backward integration into precision mask assembly across Asia-Pacific manufacturing nodes. Becton, Dickinson and Co. competes on hospital system contracts in North America and Western Europe. Salter Labs specializes in disposable configurations for emergency medical services channels.
A Venturi mask is a respiratory device that delivers controlled oxygen concentrations through a fixed-performance mechanism utilizing air entrainment ports and calibrated color-coded valves. The device typically achieves precise fraction of inspired oxygen (FiO2) levels ranging from 24% to 60% depending on the flow rate and valve configuration selected. Pediatric Venturi Masks represent a concentrated margin pool due to stricter dimensional tolerances and specialized clinical validation requirements. Emergency Medical Services drives volume velocity for Disposable Venturi Masks where single-use protocols dominate field protocols. Hospitals sustain the largest absolute demand footprint across both Oxygen Therapy and Respiratory Distress applications.
FDA 510(k) clearance pathways and ISO 18562 biocompatibility standards govern market access for polymer-based respiratory interfaces in the United States. The EU MDR and REACH substance restrictions reshape material selection for Silicone and PVC variants distributed across European clinical networks. Stakeholders must monitor evolving FDA guidance on reusable device reprocessing validation as health systems weigh cost structures against infection control protocols.
Market Dynamics
Hospital oxygen therapy protocols are tightening entrainment precision requirements, forcing manufacturers to recalibrate valve tolerances and polymer formulations across entire product lines.
Growth Catalysts
- ISO 18562 biocompatibility mandates:FDA clearance pathways now require comprehensive respiratory interface testing, elevating technical barriers that favor established polymer compounders with in-house validation labs.
- Emergency Medical Services field protocols:Single-use disposable configurations are displacing reusable alternatives in pre-hospital settings across North American ambulance networks.
- Silicone elastomer advances:Improved tear strength and dimensional stability enable thinner-walled mask skirts that reduce dead space while maintaining seal integrity during high-flow oxygen delivery.
Market Restraints
- Medical-grade PVC resin concentration:Three Southeast Asian petrochemical complexes supply over sixty percent of specialized polymer feedstock, creating input cost volatility during regional supply disruptions.
- EU MDR substance restrictions:REACH Annex XVII phthalate limitations force reformulation of legacy PVC compounds, extending validation timelines by twelve to eighteen months for European market access.
- High-flow nasal cannula substitution:Heated humidified oxygen delivery systems are capturing moderate hypoxemia cases previously managed with Venturi masks in step-down units.
Strategic Opportunities
- Indian hospital infrastructure expansion:Central government health mission funding is equipping district medical colleges with respiratory therapy suites requiring calibrated oxygen delivery devices.
- Pediatric dimensional specialization:Neonatal intensive care units demand mask geometries below standard adult ranges, opening margin pools for manufacturers with micro-molding capabilities.
- Direct-to-facility e-procurement channels:Hospital system aggregators are consolidating consumable purchasing, rewarding suppliers with real-time inventory visibility and consignment stocking arrangements.
Industry Challenges
- Biocompatibility testing backlog:Contract laboratories face eighteen-month queues for ISO 18562-1 cytotoxicity assessments, delaying product launches regardless of manufacturing readiness.
- Cleanroom molding capacity scarcity:ISO Class 8 medical device production space concentrates in established industrial clusters, constraining geographic diversification for new market entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Venturi Mask Market |
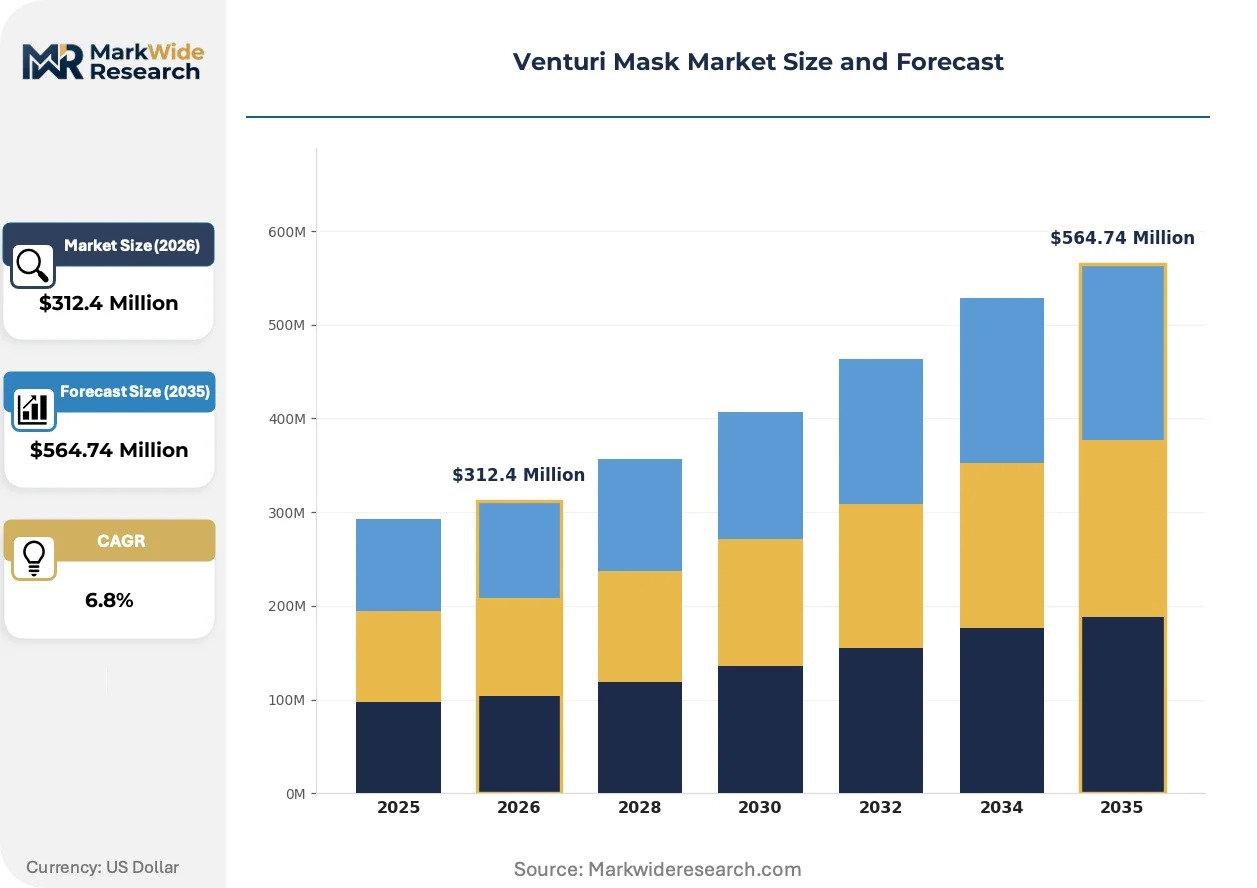
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $564.74 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Adult Venturi Masks, Pediatric Venturi Masks, Disposable Venturi Masks, Reusable Venturi Masks End User: Hospitals, Clinics, Home Care, Emergency Medical Services Application: Oxygen Therapy, Anesthesia, Respiratory Distress, Patient Transport Material: Plastic, Silicone, PVC, Latex |
| Companies Covered | Fisher & Paykel Healthcare, Besmed Health Business Corp., Becton, Dickinson and Co., For Care Enterprise Co. Ltd., Salter Labs, Medline Industries Inc., Flexicare (Group) Ltd., Terumo Corporation, Smiths Medical Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Venturi Mask Market Strategic Shifts
Material science advances and regulatory stringency are converging to redefine performance benchmarks for controlled oxygen delivery interfaces across acute care settings.
Multi-layer co-extrusion technology is hybridizing thermoplastic elastomer skins with rigid polypropylene structural cores, enabling single-piece mask geometries that previously required assembly of three distinct components. Pediatric device specialists are adopting these structures fastest, leveraging reduced part counts to meet stricter dimensional tolerance requirements. The consolidation is compressing supplier bases as compounders with film extrusion capabilities absorb molding functions from dedicated processors.
REACH substance restrictions are forcing systematic substitution of DEHP plasticizers in PVC mask formulations across European distribution networks. Manufacturers are pivoting to citrate-based alternatives or abandoning flexible PVC entirely for TPE constructions, despite higher raw material costs. German hospital procurement consortiums are now mandating phthalate-free certification as a technical qualification threshold, accelerating the transition timeline.
Consignment inventory arrangements are restructuring traditional distributor relationships in North American health systems. Large integrated delivery networks are unbundling device supply from service contracts, forcing manufacturers to maintain direct field inventory at warehouse locations. This pattern is most pronounced in United States multi-hospital systems managing oxygen therapy standardization across fifty-plus facility footprints.
Venturi Mask Market Segmentation
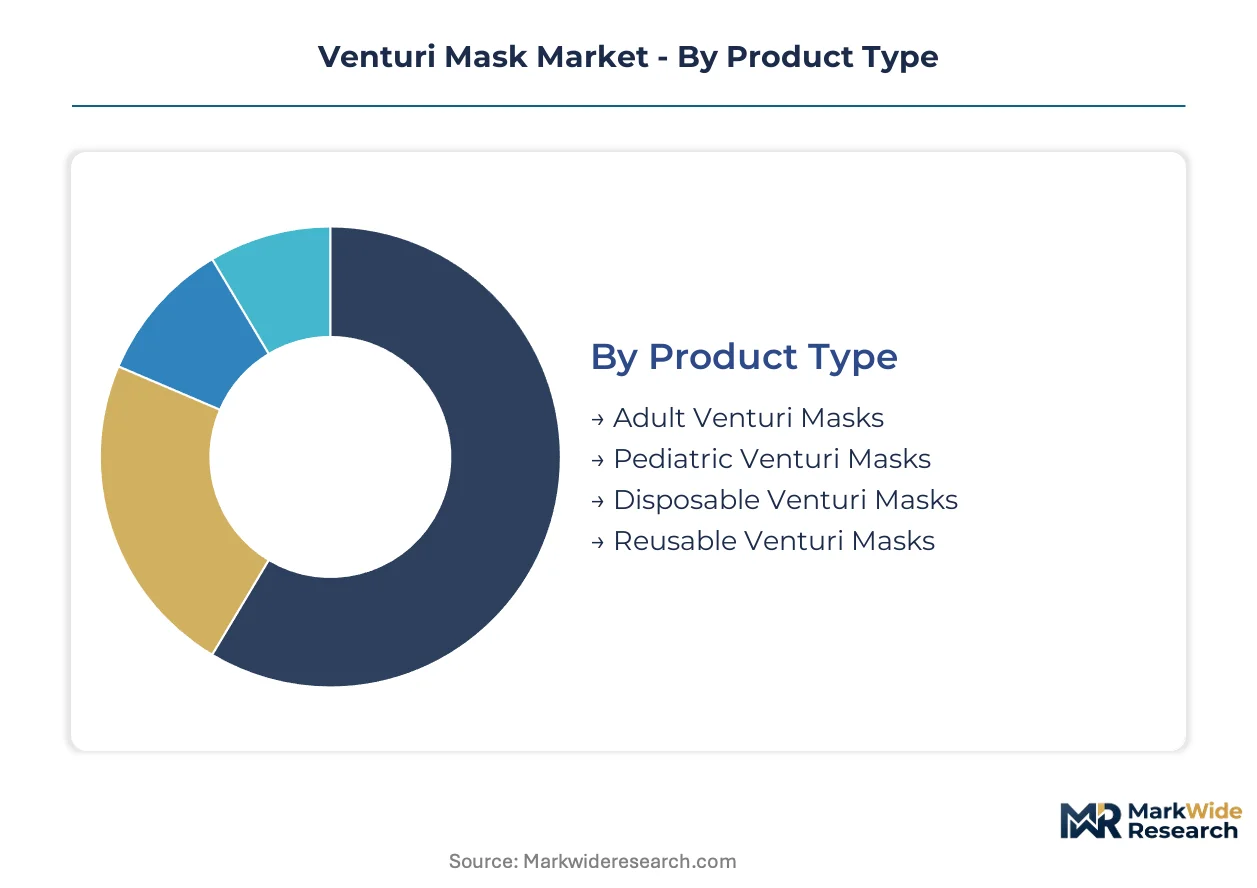
Segmentation in the Venturi Mask Market reflects divergent clinical requirements across acute care settings, transport scenarios, and home-based oxygen delivery. Manufacturers configure product portfolios around dimensional precision, sterility protocols, and material biocompatibility to capture discrete purchasing channels.
Product Type:
Cost tier differentiation separates commodity disposable configurations from precision-engineered reusable systems requiring validation infrastructure.
- Adult Venturi Masks:Standardized geometries accommodate 95% of adult facial anthropometry with polypropylene structural cores and thermoplastic elastomer seals. Demand concentrates in United States hospital systems where oxygen therapy protocol standardization drives volume purchasing through integrated delivery networks.
- Pediatric Venturi Masks:Micro-molded components achieve dimensional tolerances below 0.5 millimeters for neonatal intensive care applications. German procurement consortiums mandate phthalate-free certification for pediatric interfaces, accelerating TPE adoption despite 40% raw material cost premiums over PVC.
- Disposable Venturi Masks:Single-use polystyrene constructions dominate Emergency Medical Services field protocols across North American ambulance networks.
- Reusable Venturi Masks:Silicone elastomer formulations withstand 100-plus sterilization cycles in hospital central processing departments.
Adult Venturi Masks hold installed capacity. Pediatric Venturi Masks is rotating up the share rankings.
End User:
Customer type determines purchasing authority, with hospital procurement offices wielding consolidated contract power against fragmented home care channels.
- Hospitals:Multi-facility health systems in the United States negotiate enterprise-wide oxygen therapy standardization across 50-plus facility footprints. FDA 510(k) clearance and ISO 18562 biocompatibility documentation constitute mandatory technical qualification thresholds for vendor inclusion.
- Emergency Medical Services:Pre-hospital providers prioritize single-use disposables to eliminate field reprocessing liability. Volume velocity concentrates in municipal ambulance authorities across Germany and the United States where single-use protocols have displaced reusable alternatives.
- Clinics:Outpatient respiratory therapy suites require calibrated oxygen delivery for moderate hypoxemia management.
- Home Care:Direct-to-patient distributors serve chronic obstructive pulmonary disease populations with simplified valve configurations.
Hospitals command absolute demand footprint. Emergency Medical Services is climbing the fastest in volume velocity.
Application:
Clinical use case dictates entrainment precision requirements, with acute respiratory failure demanding tighter FiO2 control than transport scenarios.
- Oxygen Therapy:Controlled fraction of inspired oxygen delivery from 24% to 60% remains the foundational application across all care settings. United States hospital oxygen therapy protocols are tightening entrainment precision tolerances, forcing manufacturers to recalibrate valve specifications.
- Respiratory Distress:Acute hypoxemic respiratory failure requires immediate high-flow oxygen delivery with precise concentration control. Demand concentrates in step-down units where heated humidified systems are capturing moderate cases previously managed with Venturi masks.
- Anesthesia:Operating room applications require compatibility with scavenging systems and anesthetic gas delivery circuits.
- Patient Transport:Aeromedical and ground ambulance configurations prioritize lightweight construction and secure tubing attachment.
Oxygen Therapy holds installed capacity. Respiratory Distress is gaining share fastest as acute care protocols expand.
Material:
Supply concentration in Southeast Asian petrochemical complexes shapes raw material cost structures across polymer categories.
- PVC:Medical-grade formulations with DEHP plasticizers face REACH Annex XVII restrictions across European distribution networks. Manufacturers are pivoting to citrate-based alternatives or abandoning flexible PVC entirely for TPE constructions.
- Silicone:Platinum-cured elastomers deliver tear strength above 500% elongation for reusable mask skirts. German hospital procurement consortiums now mandate phthalate-free certification, accelerating silicone adoption despite higher unit costs.
- Plastic:Polypropylene and polystyrene variants dominate disposable configurations for cost-sensitive channels.
- Latex:Natural rubber applications have contracted to niche markets due to Type I hypersensitivity concerns in clinical populations.
PVC holds installed capacity. Silicone is rotating up the share rankings on biocompatibility mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA 510(k) clearance pathways anchor the United States as the dominant geography, with ISO 18562 biocompatibility standards and EU MDR substance restrictions shaping access across Germany and China respectively.
United States
Integrated delivery networks standardize oxygen therapy protocols across fifty-plus facility footprints. FDA 510(k) clearance and ISO 18562 documentation constitute mandatory technical thresholds for vendor inclusion. Manufacturing concentrates in Midwest industrial corridors serving hospital procurement offices.
Germany
Hospital procurement consortiums mandate phthalate-free certification for pediatric interfaces, accelerating TPE adoption. EU MDR and REACH Annex XVII restrictions reshape material selection for Silicone and PVC variants. Production clusters in Baden-Württemberg specialize in precision molding for reusable mask systems.
China
Central government health mission funding equips district medical colleges with respiratory therapy suites. NMPA registration requirements govern polymer-based respiratory interface market access. Domestic molding capacity expansion in the Yangtze River Delta narrows import dependence for respiratory consumables.
India
District hospital infrastructure expansion under national health missions drives calibrated oxygen delivery device procurement. CDSCO medical device regulations tighten product specifications for polymer-based interfaces. Manufacturing investments concentrate in Gujarat and Maharashtra for cost-sensitive disposable configurations.
Japan
Aging demographics expand chronic respiratory disease management requirements in acute care settings. PMDA quality management system ordinances govern market authorization timelines. Precision polymer processing capabilities in the Kansai region serve domestic hospital supply chains.
Venturi Mask Market Competitive Environment
Vertically integrated multinationals and specialized disposable fabricators split the market into distinct capability tiers. Established polymer compounders with in-house validation laboratories capture premium positions as technical barriers elevate. Three archetypes dominate: backward-integrated respiratory device specialists, contract manufacturers serving hospital system aggregators, and regional disposable suppliers targeting emergency medical services channels. Competitive moves concentrate on cleanroom molding capacity expansion and direct-to-facility e-procurement channel development.
Among Asia-Pacific-based fabricators, Fisher & Paykel Healthcare exemplifies backward integration into precision mask assembly, while Terumo Corporation occupies a position within the medical device conglomerate tier. Becton, Dickinson and Co. represents the hospital system contract specialist archetype in North American and Western European markets. Salter Labs anchors the emergency medical services disposable configuration segment.
| Leading Market Players |
|---|
| Fisher & Paykel Healthcare |
| Besmed Health Business Corp. |
| Becton, Dickinson and Co. |
| For Care Enterprise Co. Ltd. |
| Salter Labs |
| Medline Industries Inc. |
| Flexicare (Group) Ltd. |
| Terumo Corporation |
| Smiths Medical Inc. |
| Others |
Value Chain & Pricing Dynamics
Yangtze River Delta port congestion fluctuation compresses margins for polymer resin importers while amplifying price spreads between domestic Chinese molding operations and Southeast Asian contract manufacturers serving European hospital procurement consortiums.
Pricing Analysis
Price differentiation between United States and German hospital systems reaches 35% for identical silicone elastomer configurations due to FDA 510(k) validation cost recovery and REACH compliance documentation premiums. Three-tier pricing structure across premium pediatric interfaces, standard adult disposables, and economy polystyrene EMS configurations dominates contract negotiations. Pricing pressure stems from high-flow nasal cannula substitution in step-down units, forcing Venturi mask manufacturers to bundle valve recalibration services. Emergency Medical Services channels exhibit highest price sensitivity due to municipal budget constraints, while neonatal intensive care units absorb premium positioning for micro-molded tolerances.
Supply Chain Analysis
Export-control scrutiny on precision molding equipment limits technology transfer to Indian domestic manufacturers, constraining capacity expansion for district hospital respiratory therapy suites. Medical-grade PVC resin concentrates in Thailand, Malaysia, and Singapore petrochemical complexes, while silicone elastomer formulations draw from German and Japanese specialty compounders. Single-source vulnerability pervades DEHP plasticizer substitution pipelines as citrate-based alternatives await REACH validation. Distribution runs through hospital system aggregators consolidating fifty-plus facility footprints under enterprise oxygen therapy standardization protocols.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
ISO 18562 biocompatibility mandates and EU MDR substance restrictions are accelerating technical barriers that favor compounders with captive validation infrastructure over pure-play assemblers.
For Market Incumbents: Pre-empt high-flow nasal cannula displacement by embedding heated humidification compatibility into next-generation valve architectures. Expand cleanroom molding capacity in Midwest industrial corridors to capture integrated delivery network consignment contracts. Secure backward integration into platinum-cured silicone compounding before German procurement consortiums mandate phthalate-free certification as a technical qualification threshold. For New Entrants and Emerging Players: Build out micro-molding capabilities targeting neonatal intensive care dimensional tolerances below 0.5 millimeters, where established manufacturers face eighteen-month biocompatibility testing backlogs. Penetrate Indian district hospital infrastructure expansion through cost-sensitive disposable configurations qualifying under CDSCO streamlined registration pathways. Pursue direct-to-facility e-procurement partnerships with hospital system aggregators unbundling device supply from legacy service contracts. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified medical device conglomerates with underperforming respiratory consumables divisions lacking ISO 18562 in-house validation laboratories. Position holdings for sustained viability through heated humidification integration cycles and polymer formulation transitions. Monitor FDA guidance evolution on reusable device reprocessing validation as the inflection signal for health system cost-structure recalibration toward single-use protocols.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission | Clearance pathways anchor vendor inclusion in United States integrated delivery network contracts. |
| CE Marking Pathway | EU MDR compliance enables access to German procurement consortiums mandating phthalate-free certification. |
| Hospital System Partnership | Enterprise-wide oxygen therapy standardization across fifty-plus facilities locks in volume purchasing. |
| Backward Integration | In-house silicone compounding captures margin pools as REACH restrictions eliminate legacy PVC suppliers. |
| Reimbursement Strategy | Coding alignment with acute respiratory failure protocols defends positioning against high-flow nasal cannula substitution. |
Study Parameters
Operator-level perspectives from respiratory therapists, hospital purchasing committee chairs, biomedical engineers, and GPO contracts managers anchored the qualitative base. Primary fieldwork combined structured interviews with secondary validation against FDA 510(k) filings, EU MDR technical documentation, hospital procurement databases, and GPO contract repositories. Bottom-up demand modeling triangulated against top-down polymer consumption estimates from Southeast Asian petrochemical trade data.
Scenario-bracketing framed volume and value outputs across the projection horizon through sensitivity testing of high-flow substitution rates and regulatory timeline acceleration. Segmentation dimensions spanned product type, end user, application, and material grade tier alongside regional regulatory cluster differentiation. CAGRs derived from fitted growth curves incorporating NMPA registration velocity in China and central government health mission disbursement patterns in India.
Sensitivities concentrate around biocompatibility testing queue durations, REACH Annex XVII substance restriction expansion, and heated humidification technology cost curves. Forecasts reflect documented assumptions on hospital oxygen therapy protocol standardization timelines and EMS single-use adoption rates. Material shifts in FDA guidance on reusable device reprocessing validation would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Organs-On-Chips Market
Medical Devices
North America Oxygen Concentrators Market
Medical Devices
Human Anatomy Model Market
Medical Devices
Infertility Treatment Devices Market
Medical Devices
Global Medical Injection Molding Market
Medical Devices
Photopheresis Products Market
Medical Devices
Neurovascular Microcatheter Market
Medical Devices
North America Renal Denervation Devices Market
Medical Devices
Artificial Implants Market
Medical Devices
MRI Coils Market
Medical Devices
Dosage Unit Sampling Apparatus Market
Medical Devices
Global Bioabsorbable Stents Market
Medical Devices
Stent Delivery Systems Market
Medical Devices
Below-The-Knee Implants Market
Medical Devices
Asia Pacific Veterinary Equipment and Disposables Market
Medical Devices
Digital Medical Thermometers Market