
 Hemodynamic Flow Alteration Devices Market | 2026-2036
Hemodynamic Flow Alteration Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Hemodynamic Flow Alteration Devices Market Foresight
Multi-source procurement for critical hemodynamic components is expanding as health systems seek supply resilience. Medtronic leverages vertically integrated manufacturing to secure catheter supply chains. Abbott Laboratories anchors its position through electromechanical system specialization. Boston Scientific Corporation differentiates via bioreactor technology investments.
Hemodynamic flow alteration devices modulate blood circulation through mechanical, electromechanical, or biological means, typically operating at flow rates of 2–10 liters per minute depending on therapeutic indication. These systems serve primarily to restore perfusion balance in acute or chronic circulatory failure. Intravascular devices command the largest revenue pool due to recurring catheter replacement cycles, while wearable devices represent the fastest-expanding category as ambulatory monitoring protocols mature. Hospital end users absorb the majority of capital expenditure, though ambulatory surgical centers capture margin growth from same-day discharge mandates.
FDA premarket notification and EU MDR conformity assessment govern device commercialization in the two largest addressable jurisdictions, with both frameworks intensifying clinical evidence requirements. Japan's PMDA and China's NMPA impose additional localization testing that extends time-to-market for multinational submissions. Stakeholders must monitor evolving reimbursement coding for wearable hemodynamic monitors and electromechanical support systems.
Market Dynamics
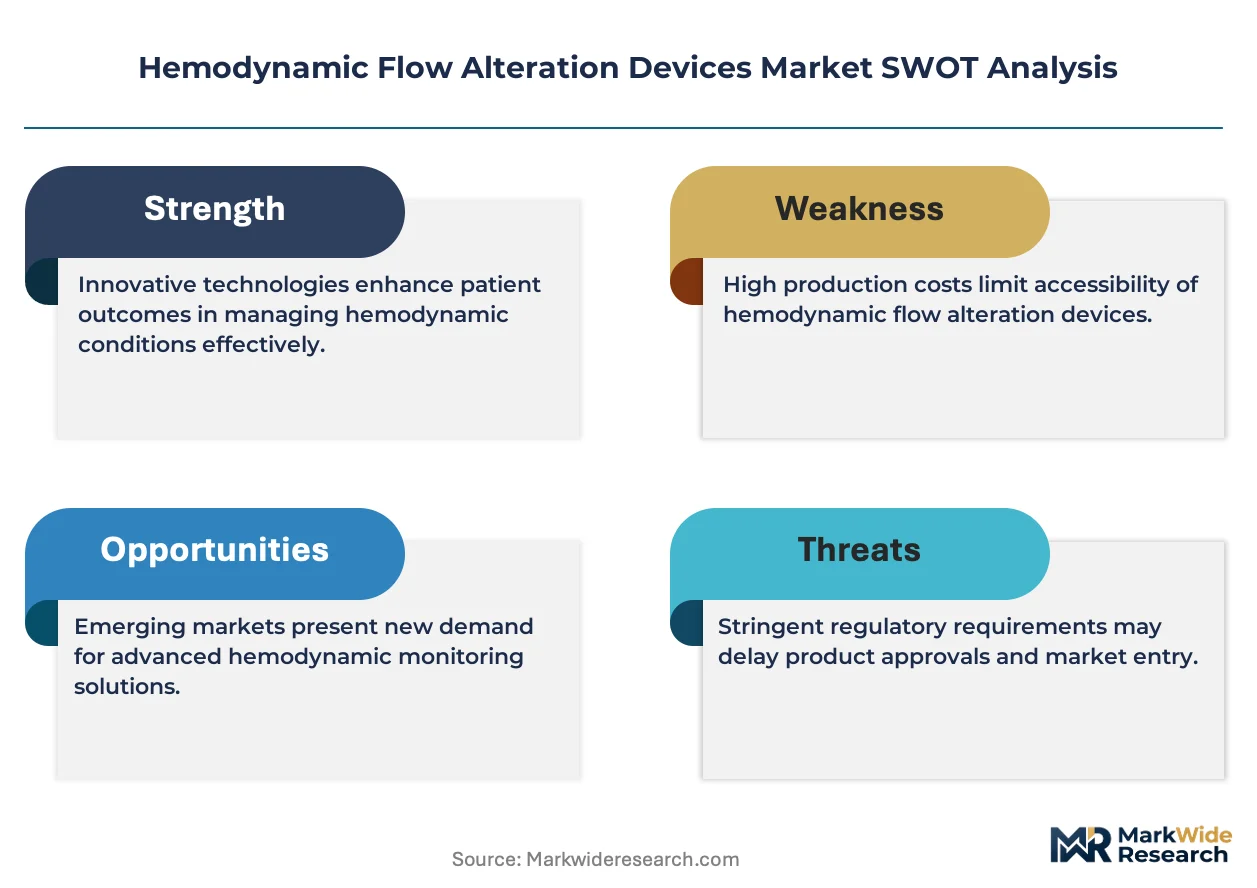
EU Medical Device Regulation clinical evidence requirements are compressing product development timelines while hospital procurement consolidation is concentrating buying power among integrated delivery networks.
Growth Catalysts
- Ambulatory monitoring protocols:Same-day discharge mandates from CMS are expanding wearable hemodynamic device deployment in outpatient settings.
- FDA breakthrough device designation:Expedited review pathways for electromechanical circulatory support systems are accelerating time-to-market for novel interventions.
- Catheter replacement cycles:Recurring consumable demand from intravascular device maintenance generates predictable revenue streams for hospital suppliers.
Market Restraints
- Silicone and polymer feedstock volatility:Medical-grade elastomer price swings compress margins on catheter manufacturing.
- Single-source component dependency:Concentrated supply of precision electromechanical actuators from German and Japanese tier-2 suppliers creates vulnerability.
- Battery energy density limitations:Current lithium-ion cell technology constrains wearable device operational duration between charges.
Strategic Opportunities
- India's tertiary hospital expansion:Greenfield cardiac center construction under Ayushman Bharat creates first-mover positioning for hemodynamic monitoring suites.
- AI-integrated predictive algorithms:Machine learning overlay on continuous flow data enables preemptive intervention before decompensation.
- Direct-to-hospital distribution:Bypassing traditional distributor markups through manufacturer-employed clinical specialists captures margin in academic medical centers.
Industry Challenges
- Biocompatibility testing bottlenecks:ISO 10993 cytotoxicity and hemocompatibility validation queues extend product launch schedules by 8-14 months.
- Electromechanical-software integration complexity:FDA scrutiny of firmware updates for implanted flow controllers demands dedicated regulatory affairs staffing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hemodynamic Flow Alteration Devices Market |
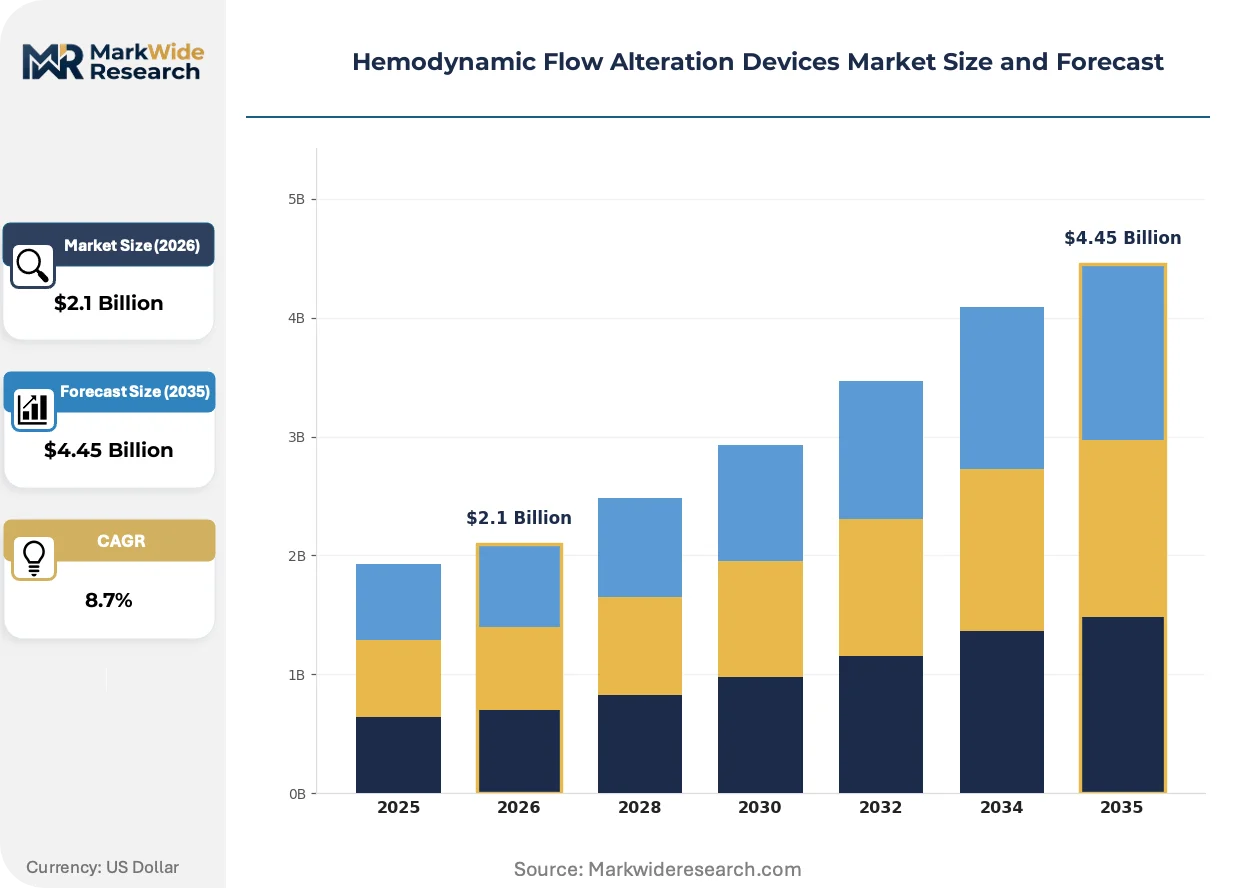
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $4.45 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Device Type: Intravascular Devices, Implantable Pumps, Stents, Catheters End User: Cardiology Clinics, Hospitals, Ambulatory Surgical Centers, Research Institutions Application: Heart Failure, Aortic Stenosis, Peripheral Artery Disease, Myocardial Infarction Technology: Mechanical Support, Bioreactor Systems, Electromechanical Systems, Wearable Devices |
| Companies Covered | Medtronic, Abbott Laboratories, Boston Scientific Corporation, Edwards Lifesciences Corporation, Terumo Corporation, Koninklijke Philips, BIOTRONIK SE & Co. KG, iVascular, LivaNova, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hemodynamic Flow Alteration Devices Market Shifts & Advancements
Digital biomarker extraction from continuous hemodynamic signals is transforming how clinicians detect circulatory deterioration before clinical symptoms manifest.
Magnetic levitation bearing technology is electrifying centrifugal pump design by eliminating mechanical wear surfaces and extending device longevity from months to years. Academic medical centers in Germany and the United States are piloting these systems for destination therapy candidates previously excluded from mechanical support. The shift is compressing the addressable market for pulsatile pneumatic devices while expanding eligibility for chronic implantation.
EU MDR Article 10 post-market surveillance requirements are mandating active implantable device registries with 15-year follow-up obligations. Manufacturers must now fund independent clinical investigations or leverage real-world evidence from existing European Health Data Space infrastructure. Hemodynamic support systems with limited long-term safety data face commercial withdrawal or costly prospective study commitments.
Health system value analysis committees have displaced individual physician preference as the primary purchasing authority for capital-intensive hemodynamic platforms. Integrated delivery networks in Texas and California now require standardized device contracts across all member facilities, replacing hospital-specific negotiations. Vendor clinical outcome guarantees and total cost-of-ownership models are supplanting upfront equipment pricing as the decisive selection criteria.
Hemodynamic Flow Alteration Devices Market Segmentation
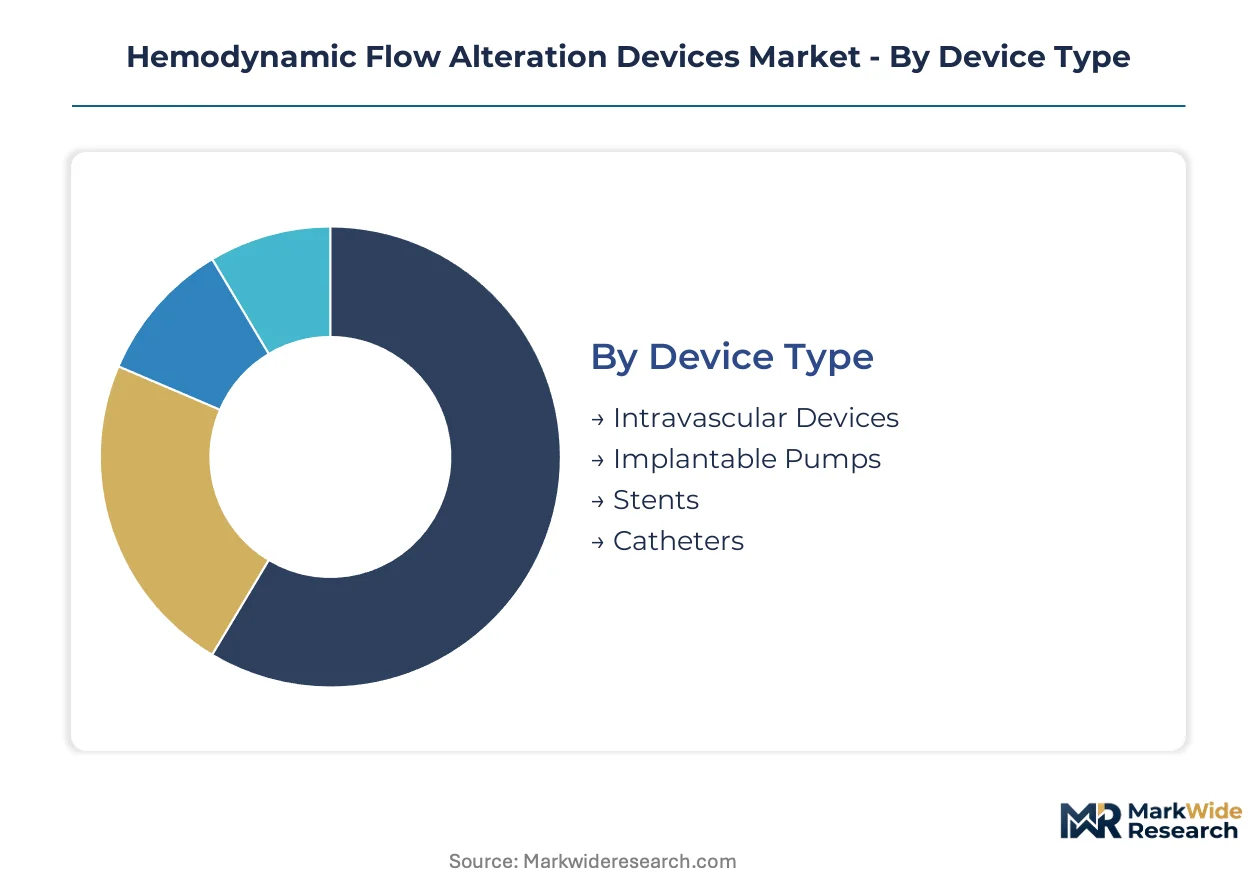
Hemodynamic flow alteration devices serve distinct clinical workflows requiring tailored specifications across invasive, implanted, and wearable modalities. Segmentation reveals how technology maturity, reimbursement pathways, and procedural settings fragment purchasing authority and margin structures.
Device Type:
Standardized intravascular platforms contrast sharply with patient-specific implantable configurations across this category.
- Intravascular Devices:Catheter-based systems deliver acute circulatory support through percutaneous insertion, typically incorporating heparin-coated lumens and pressure sensor arrays. Demand concentrates in United States academic medical centers where complex PCI volumes drive recurring catheter replacement cycles. FDA 510(k) clearance pathways favor incremental iterations of established intravascular platforms.
- Implantable Pumps:Centrifugal and axial flow pumps provide chronic mechanical circulatory support via sternotomy or less invasive thoracotomy approaches. German cardiac surgery centers lead destination therapy adoption, propelled by EU MDR Article 10 post-market surveillance requirements that favor devices with established 15-year safety registries.
- Stents:Self-expanding nitinol or balloon-expandable cobalt-chromium scaffolds restore vessel patency in obstructive hemodynamic lesions.
- Catheters:Single or multi-lumen access devices enable pressure monitoring, fluid administration, and temporary flow diversion.
Leading the category by volume: Intravascular Devices. Expanding most quickly: Implantable Pumps.
End User:
Capital intensity and reimbursement sophistication separate institutional purchasers from outpatient operators in this category.
- Hospitals:Integrated delivery networks in Texas and California consolidate procurement for hemodynamic platforms across member facilities, displacing individual physician preference with value analysis committee authority. These institutions absorb the majority of capital expenditure for electromechanical support systems and hybrid operating suite installations.
- Cardiology Clinics:Outpatient diagnostic centers deploy non-invasive hemodynamic monitoring for heart failure surveillance, constrained by CMS reimbursement coding limitations on wearable device deployment.
- Ambulatory Surgical Centers:Same-day discharge mandates expand same-day PCI volumes, capturing margin growth from streamlined catheter-based interventions.
- Research Institutions:Academic medical centers in the United States and Germany pilot magnetic levitation bearing pumps and AI-integrated predictive algorithms under investigational device exemptions.
Dominating procurement value: Hospitals. Climbing the fastest: Ambulatory Surgical Centers.
Application:
Acuity of clinical presentation and intervention reversibility define therapeutic positioning across this category.
- Heart Failure:Chronic decompensated states require durable mechanical support or bridge-to-transplant strategies, with German and United States centers leading ventricular assist device implantation volumes.
- Myocardial Infarction:Acute coronary occlusions demand rapid intravascular hemodynamic restoration, concentrating demand in United States hospitals with 24-hour cath lab activation protocols.
- Aortic Stenosis:Valve narrowing produces pressure overload requiring transcatheter or surgical intervention.
- Peripheral Artery Disease:Limb ischemia drives demand for peripheral stent and catheter-based revascularization.
Highest procedure volume: Heart Failure. Gaining share fastest: Myocardial Infarction.
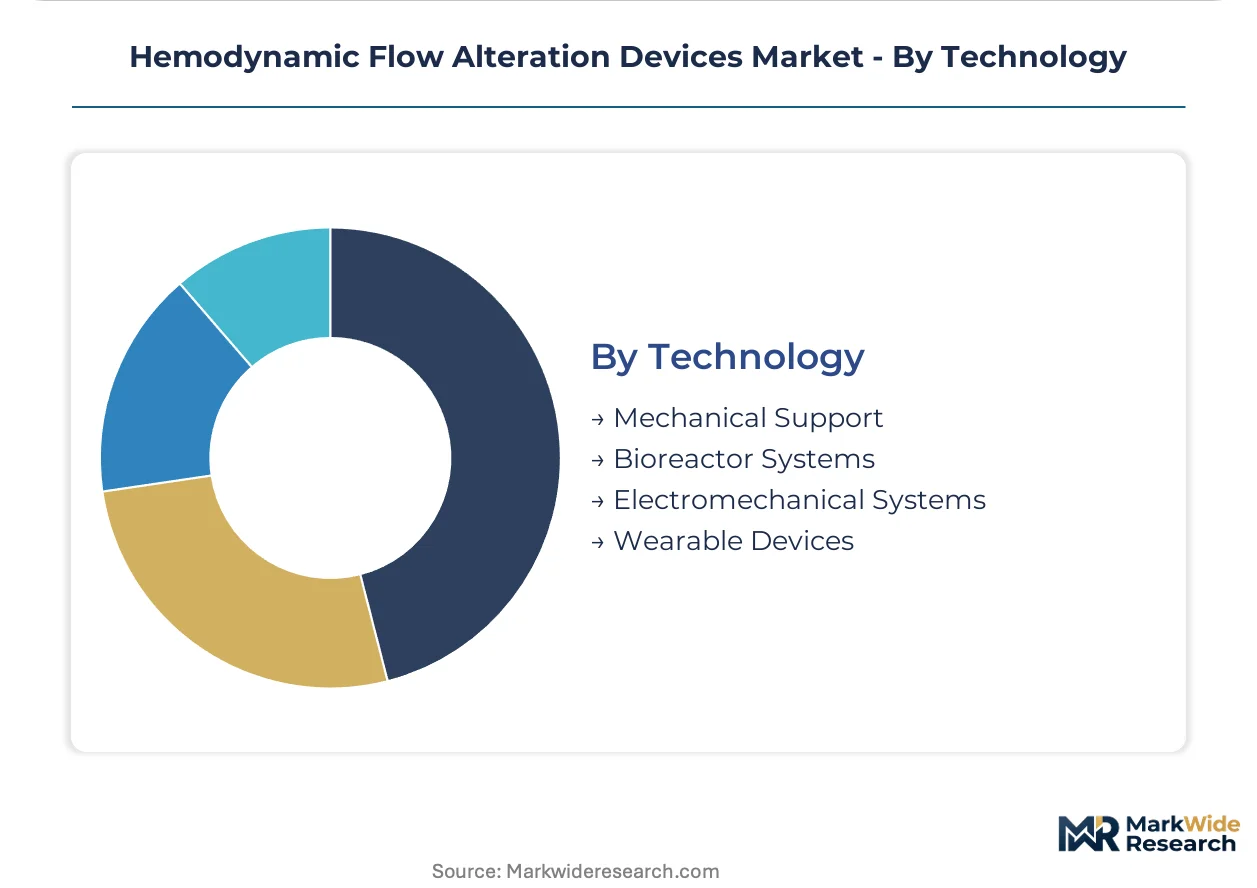
Technology:
Energy delivery mechanisms and patient mobility determine regulatory classification and commercial trajectory across this category.
- Electromechanical Systems:Motor-driven pumps and actuators modulate blood flow with programmable speed control, dominating implanted ventricular assist device architectures. Japanese PMDA and China's NMPA impose additional localization testing that extends time-to-market for multinational submissions of these active implantable devices.
- Wearable Devices:External monitors and non-invasive flow sensors enable ambulatory hemodynamic surveillance, with battery energy density limitations from current lithium-ion technology constraining operational duration between charges.
- Mechanical Support:Pneumatic or hydraulic systems provide acute circulatory assistance without electrical components.
- Bioreactor Systems:Extracorporeal cell-based platforms modify blood composition or cellular content outside the body.
Established revenue base: Electromechanical Systems. Steepest expansion trajectory: Wearable Devices.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Medical-grade silicone and polymer feedstock production in Germany anchors European supply security for catheter manufacturing. Japan's precision electromechanical actuator clusters feed component demand for active implantable devices. India's tertiary hospital construction under Ayushman Bharat is redrawing procurement geography for hemodynamic monitoring suites.
United States
Academic medical centers in Texas and California drive complex PCI volumes and ventricular assist device implantation. FDA breakthrough device designation pathways accelerate electromechanical circulatory support reviews. The Boston-Cambridge corridor hosts concentrated bioreactor technology development for next-generation flow modulation.
Germany
Cardiac surgery centers in Bavaria and North Rhine-Westphalia lead destination therapy adoption for magnetic levitation bearing pumps. EU MDR Article 10 mandates 15-year post-market surveillance registries for active implantables. The Baden-Württemberg industrial belt supplies precision electromechanical actuators to multinational device manufacturers.
Japan
PMDA localization testing requirements extend time-to-market for multinational electromechanical system submissions. METI funding priorities favor chronic implantable device development over acute intravascular platforms. The Tokyo-Osaka corridor concentrates procurement authority for university hospital hemodynamic suites.
China
NMPA regulatory harmonization efforts are streamlining approval pathways for wearable hemodynamic monitors. Dual carbon goals are pressuring battery energy density improvements for ambulatory devices. The Yangtze River Delta medical device manufacturing clusters are scaling catheter production for domestic hospital procurement.
India
Ayushman Bharat greenfield cardiac center construction is creating first-mover positioning for hemodynamic monitoring suite vendors. CDSCO medical device rules are aligning with international standards for active implantable classification. Maharashtra and Karnataka tertiary hospitals are consolidating procurement through state-level tendering authorities.
Hemodynamic Flow Alteration Devices Market Competitive Landscape
Global majors compete with regional champions across regulatory compliance and supply chain resilience dimensions. The vendor base stratifies into three tiers: integrated conglomerates with captive polymer supply, electromechanical specialists with precision actuator expertise, and emerging wearable platform developers. Strategic archetypes include vertically integrated manufacturers securing catheter feedstocks, bioreactor technology investors extending device longevity, and AI-integrated algorithm developers enabling predictive intervention. Dominant competitive moves span backward integration into medical-grade silicone production and direct-to-hospital distribution bypassing traditional markup layers.
Among the integrated device manufacturers, Medtronic exemplifies supply chain control through captive catheter production, while Abbott Laboratories occupies a position emphasizing electromechanical system architecture. Boston Scientific Corporation represents the bioreactor technology investment archetype, with Edwards Lifesciences Corporation anchoring the hemodynamic monitoring specialization tier. These entities collectively illustrate how competitive positioning fragments across upstream material control, core electromechanical competence, and downstream clinical integration capabilities.
| Leading Market Players |
|---|
| Medtronic |
| Abbott Laboratories |
| Boston Scientific Corporation |
| Edwards Lifesciences Corporation |
| Terumo Corporation |
| Koninklijke Philips |
| BIOTRONIK SE & Co. KG |
| iVascular |
| LivaNova |
| Others |
Supply & Pricing Matrix
Magnetic levitation bearing electrification in centrifugal pump design is compressing maintenance cost economics while concentrating production capability among German and United States precision electromechanical clusters. This dual shift simultaneously elevates capital equipment price points for chronic implantable systems and narrows supplier alternatives for hospital procurement committees.
Pricing Analysis
Extended warranty and remote monitoring service bundling separates premium-tier ventricular assist device contracts from unbundled acute intravascular catheter transactions. Three-tier pricing structure across premium, standard, and economy levels reflects FDA breakthrough designation status, ISO 10993 certification grade, and volume commitment scale. Cost compression in standard-tier electromechanical pumps is intensifying because silicone feedstock volatility compresses catheter manufacturing margins. Academic medical centers exhibit lowest price sensitivity due to outcome-based vendor selection criteria, while ambulatory surgical centers prioritize per-procedure disposable economics.
Supply Chain Analysis
Direct-to-hospital channels handle academic medical center demand through manufacturer-employed clinical specialists, bypassing traditional distributor markups. Medical-grade silicone production concentrates in Germany, precision electromechanical actuator manufacturing clusters in Japan and Germany, and catheter assembly scales through China's Yangtze River Delta medical device hubs. Raw material dependencies center on lithium-ion cells for wearable power systems, medical-grade polymers for catheter lumens, and rare-earth magnets for levitation bearing assemblies. Single-source vulnerability from concentrated German and Japanese tier-2 actuator suppliers creates procurement risk exposure. Distribution runs through integrated delivery network value analysis committees displacing individual hospital negotiations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Precision electromechanical actuator fabrication capacity represents the binding constraint propping pricing power for active implantable device manufacturers. Hospital procurement consolidation into integrated delivery networks further amplifies incumbent leverage over supply-constrained components.
For Market Incumbents: Lock in catheter feedstock security through backward integration into medical-grade silicone production or long-term offtake agreements with Baden-Württemberg polymer suppliers. Expand magnetic levitation bearing manufacturing capacity in German precision clusters before EU MDR Article 10 registries favor established 15-year safety data holders. Threat substitution from AI-integrated predictive algorithms demands preemptive software companion development for flow controller firmware. For New Entrants and Emerging Players: Launch via direct-to-hospital distribution targeting India's Ayushman Bharat greenfield cardiac centers before incumbent GPO contracts solidify. Focus initial penetration on wearable hemodynamic monitors where battery energy density limitations create white-space for solid-state power innovation. Cardiology clinics constrained by CMS reimbursement coding gaps represent the most penetrable outpatient segment for ambulatory monitoring platforms. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to integrated conglomerates seeking electromechanical system architecture capabilities. Long-term viability over the projection horizon hinges on post-market surveillance registry funding obligations under EU MDR Article 10. Acquisition target archetype: mid-cap specialists with captive polymer supply and FDA breakthrough designation pipeline. Signal to watch: CDSCO alignment with international standards accelerating India market entry timelines for multinational submissions.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Device Pathway | Expedited review compresses time-to-market for novel electromechanical circulatory support systems. |
| EU MDR Article 10 Compliance | Post-market surveillance registry funding mandates favor incumbents with established safety databases. |
| Hospital System Partnership | Integrated delivery network standardization contracts displace hospital-specific negotiations in Texas and California. |
| Software Companion Development | FDA firmware update scrutiny for implanted flow controllers demands dedicated regulatory affairs infrastructure. |
| Reimbursement Strategy | CMS coding evolution for wearable hemodynamic monitors determines ambulatory deployment economics. |
Research Methodology
Independent corroboration across hospital purchasing committee interviews, biomedical engineer surveys, and GPO contracts managers underwrites the qualitative findings. Primary fieldwork engaged cardiac surgeons, cath lab directors, regulatory affairs specialists at multinational device manufacturers, and value analysis committee chairs. Secondary validation drew from FDA 510(k) and PMA filings, EU MDR notified body documentation, CMS reimbursement coding databases, and hospital procurement platform records. Bottom-up catheter volume modeling and top-down electromechanical system revenue triangulation anchored market size estimation.
Comparable-period anchoring to historical intravascular procedure volumes and ventricular assist device implantation trends established baseline trajectory assumptions across the analysis window. Segmentation modeling incorporated device type, end user channel, clinical application acuity, and energy delivery technology dimensions. CAGRs derived from procedure volume elasticity to aging demographics, cath lab construction pipelines, and destination therapy eligibility expansion. Forecast inputs included magnetic levitation bearing adoption curves and AI-integrated predictive algorithm regulatory clearance timelines.
The model assumes a particular technology adoption path; alternative pathways for solid-state battery chemistry would alter the outlook for wearable device operational duration. Forecasts reflect base-case assumptions regarding EU MDR implementation timelines and FDA breakthrough designation throughput capacity. Regulatory harmonization delays, silicone feedstock price spikes, or electromechanical actuator supply disruptions could materially revise projections. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Ultrasound Probe Market
Medical Devices
US Nebulizer Market
Medical Devices
At-Home Vaginal Ph Test Kit Market
Medical Devices
India Respiratory Devices Market
Medical Devices
Global Retinoscopes Market
Medical Devices
Global Robotic Flight Simulator Surgery Market
Medical Devices
Spain Artificial Organs and Bionic Implants Market
Medical Devices
Transportable Ventilator Market
Medical Devices
Laparoscopic Surgical Robot Market
Medical Devices
Medical Machine Battery Market
Medical Devices
Europe 3D Printing in Healthcare Market
Medical Devices
Global Dermatome Device Market
Medical Devices
Global Medical Drones Market
Medical Devices
United States Implantable Medical Devices Market
Medical Devices
Alexandrite Gemstone Lasers Market
Medical Devices
Ventricle Assist Device Market