
 Interatrial Shunt Devices Market | 2026-2036
Interatrial Shunt Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Interatrial Shunt Devices Market Insights
Buyer concentration among hospital systems and integrated delivery networks is restructuring how interatrial shunt devices reach patients. Edwards Lifesciences Corporation anchors its position through deep cardiac surgery relationships. Corvia Medical, Inc. specializes in minimally invasive shunt technologies for heart failure. Abbott Laboratories extends its electrophysiology infrastructure into structural heart procedures.
Interatrial shunt devices are implantable cardiac constructs that create a controlled atrial septal communication, typically manufactured from nitinol or polymer composites and delivered via transcatheter access to reduce left atrial pressure in heart failure patients. Self-expandable devices capture the dominant share due to conformability against septal tissue, while balloon-expandable alternatives occupy niches requiring precise diameter control. Transcatheter delivery methods lead volume as outpatient surgical centers build catheterization capabilities.
FDA breakthrough device pathways and EMA MDR compliance requirements shape clinical trial design and commercial access timelines for manufacturers. The EU AI Act and GDPR frameworks increasingly govern connected monitoring systems paired with implantable devices. Stakeholders must monitor evolving reimbursement decisions from CMS and private payers that determine whether shunt procedures shift from inpatient to outpatient settings.
Market Dynamics
Integrated delivery networks in the United States are consolidating procurement authority for interatrial shunt procedures, compressing vendor access points and forcing manufacturers to restructure sales coverage around health system headquarters rather than individual catheterization laboratories.
Growth Catalysts
- FDA Breakthrough Device Designation:Expedited review pathways compress clinical validation timelines from five years to eighteen months for qualifying shunt technologies. Manufacturers gain earlier revenue recognition and faster payer evidence accumulation.
- Transcatheter Delivery Infrastructure:Outpatient surgical centers across the United States are building dedicated catheterization capabilities. This expansion creates procedure volume outside traditional hospital inpatient settings.
- Left Atrial Pressure Reduction Protocols:Cardiology societies are embedding hemodynamic monitoring into heart failure management guidelines. Device-eligible patient identification is systematizing through electronic health record integration.
Market Restraints
- Nitinol Raw Material Concentration:Superelastic alloy supply concentrates among three primary metallurgical suppliers. Price volatility in nickel-titanium feedstock directly impacts device manufacturing economics.
- EMA MDR Compliance Burden:European notified body capacity constraints extend technical documentation review timelines. Market access delays of twenty-four to thirty-six months disadvantage smaller manufacturers against established players with regulatory affairs scale.
- Pharmacologic Heart Failure Management:SGLT2 inhibitors and ARNIs are improving medical therapy outcomes. Device-eligible patient pools face compression as pharmaceutical alternatives delay structural intervention thresholds.
Strategic Opportunities
- Japan Structural Heart Expansion:PMDA is streamlining approval pathways for devices with prior FDA clearance. Domestic catheterization laboratory networks are underpenetrated relative to Western European density.
- Connected Monitoring Convergence:Implantable shunts paired with remote hemodynamic sensors enable outpatient pressure management. EU AI Act governance frameworks are creating compliant architecture for algorithm-driven patient triage.
- India Private Hospital Chains:Apollo Hospitals and Fortis Healthcare are building cardiac structural programs in tier-two cities. Reimbursement innovation through procedure-based health packages is unlocking self-pay volume.
Industry Challenges
- Interventional Cardiology Fellowship Pipeline:Training program expansion lags device approval velocity. Health systems face twelve-to-eighteen month recruitment timelines for transseptal puncture specialists.
- Payer Evidence Generation:CMS national coverage determinations require randomized trial data against optimal medical therapy. Trial enrollment competition with pharmaceutical studies constrains site activation.
- Device-Related Thrombosis Surveillance:Post-market registries mandate extended anticoagulation protocols. Real-world outcome variation complicates standardized care pathway development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Interatrial Shunt Devices Market |
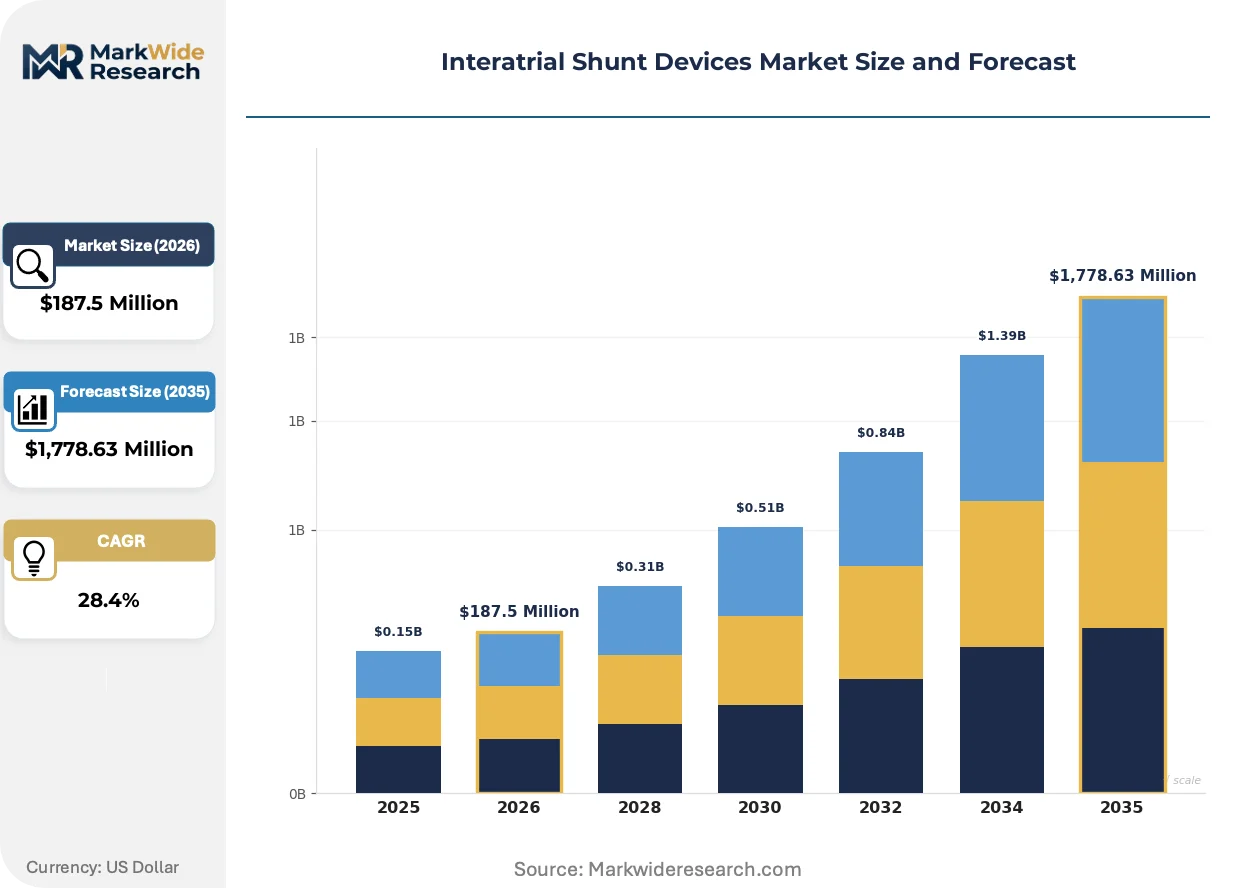
| Market Size in 2026 | $187.5 Million |
| Market Size in 2035 | $1,778.63 Million |
| CAGR (2026 – 2036) | 28.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Self-Expandable Device, Balloon-Expandable Device, Non-Expandable Device, Hybrid Device End User: Cardiology Clinics, Hospitals, Outpatient Surgical Centers, Research Institutions Delivery Method: Transcatheter, Surgical, Percutaneous, Hybrid Approach Indication: Atrial Septal Defect, Patent Foramen Ovale, Cardiogenic Shock, Others |
| Companies Covered | Edwards Lifesciences Corporation, Medtronic plc, Boston Scientific Corporation, Johnson & Johnson, Corvia Medical, Inc., Abbott Laboratories, Occlutech International AB, W.L. Gore & Associates, Inc., Lepu Medical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Interatrial Shunt Devices Market Trends and Innovations
Interatrial shunt technology is converging with digital health infrastructure, creating pressure-responsive implant ecosystems that extend clinical monitoring beyond the index procedure. This integration is reshaping how manufacturers capture lifetime patient value.
Self-expandable nitinol frameworks with shape-memory activation are rewriting procedural workflow requirements. Interventional cardiologists at high-volume United States centers are adopting same-day discharge protocols for stable patients. The technology is compressing length-of-stay metrics and shifting economic value toward outpatient facility fees.
EU MDR Article 117 requirements for device-drug combination products are elevating clinical evidence standards for polymer-coated shunt surfaces. Manufacturers must demonstrate biocompatibility through extended follow-up registries. Transcatheter delivery system suppliers face the steepest documentation burden as notified bodies scrutinize sterilization validation protocols.
Health system procurement committees are consolidating vendor contracts across cardiac service lines. Integrated delivery networks in the Midwestern United States are demanding bundled pricing for shunt devices alongside electrophysiology and structural heart portfolios. Sales organizations are reorganizing around system-level contracting rather than individual physician relationships.
Interatrial Shunt Devices Market Segmentation
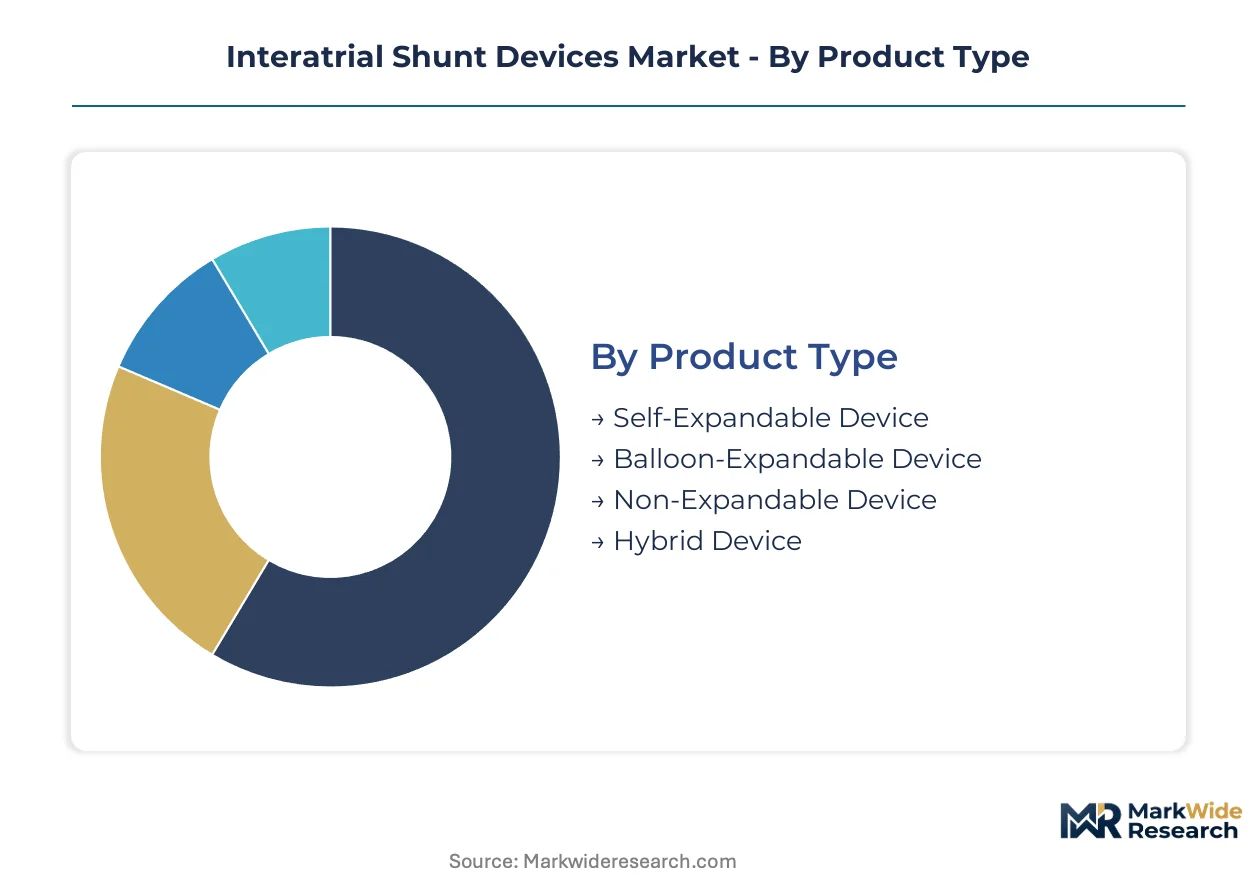
Interatrial shunt devices fragment across four structural dimensions that determine reimbursement pathways, procedural economics, and manufacturer competitive positioning. Each segmentation axis reveals distinct integration patterns between implant technology and care delivery infrastructure.
Product Type:
Standalone implantable constructs dominate acute procedural volumes, while embedded system architectures are emerging in connected monitoring ecosystems.
- Self-Expandable Device:Nitinol frameworks with shape-memory activation deploy against atrial septal tissue without balloon assistance. Demand concentrates in United States integrated delivery networks where same-day discharge protocols reduce length-of-stay metrics.
- Balloon-Expandable Device:Polymer or metallic constructs requiring controlled inflation for precise diameter calibration. German catheterization laboratories favor this architecture for complex anatomies requiring exact sizing.
- Non-Expandable Device:Fixed-diameter constructs delivered through dedicated sheaths.
- Hybrid Device:Modular platforms combining expandable frameworks with integrated pressure sensors.
Self-expandable devices lead volumes today; hybrid platforms are gaining share fastest.
End User:
Cost tier stratification separates capital-intensive inpatient settings from lean outpatient facilities.
- Hospitals:Comprehensive cardiac surgery programs capture complex cases requiring hybrid operating room infrastructure. United States academic medical centers anchor implant volumes through fellowship-trained transseptal specialists.
- Outpatient Surgical Centers:Dedicated catheterization suites built for same-day discharge protocols. Texas and Florida ambulatory surgery centers are expanding structural heart capabilities fastest.
- Cardiology Clinics:Office-based diagnostic and referral functions without implant capability.
- Research Institutions:Clinical trial sites generating payer evidence for national coverage determinations.
Hospitals retain the highest absolute procedure counts; outpatient surgical centers are expanding most quickly.
Delivery Method:
Application maturity separates established transcatheter workflows from emerging percutaneous refinements.
- Transcatheter:Femoral venous access with fluoroscopic and intracardiac echocardiographic guidance. Cleveland Clinic and Mayo Clinic catheterization laboratories standardize this approach for heart failure patient populations.
- Percutaneous:Minimally modified access techniques reducing vascular complication profiles.
- Surgical:Sternotomy or thoracotomy approaches for concomitant cardiac procedures.
- Hybrid Approach:Combined surgical and interventional techniques in hybrid operating rooms.
Transcatheter delivery leads volumes today; percutaneous refinements are climbing the fastest.
Indication:
Customer type differentiation separates heart failure volume from congenital defect niches.
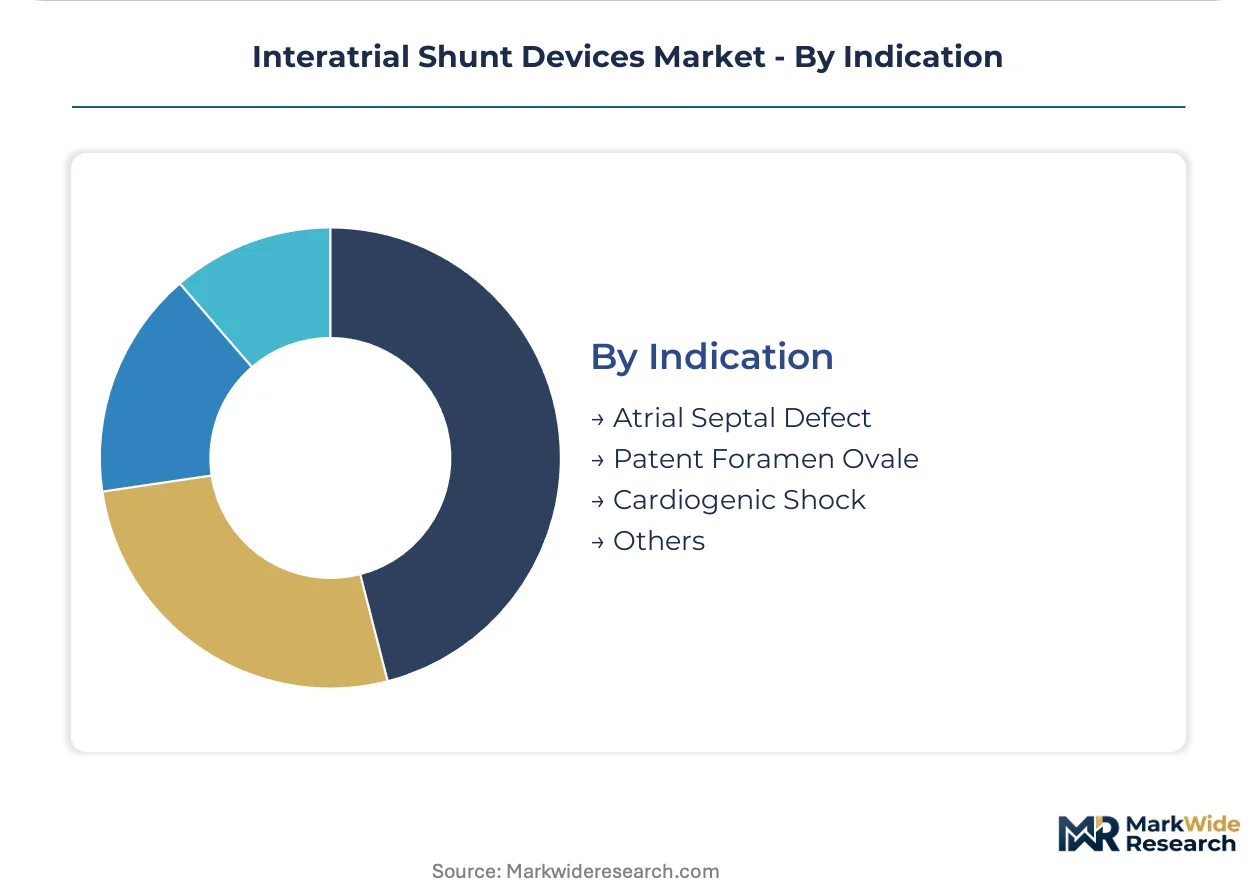
- Atrial Septal Defect:Congenial septal communications requiring closure or unidirectional shunting. Pediatric cardiology programs at Boston Children's Hospital and Children's Hospital of Philadelphia concentrate demand.
- Cardiogenic Shock:Acute hemodynamic collapse requiring immediate left atrial decompression. United States cardiac intensive care units drive emergency utilization.
- Patent Foramen Ovale:Persistent fetal communication associated with cryptogenic stroke.
- Others:Pulmonary hypertension and diastolic heart failure variants.
Cardiogenic shock indications lead emergency volumes today; atrial septal defect applications show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cardiac intervention specialists cluster in metropolitan medical centers across five countries where catheterization laboratory density and reimbursement frameworks determine procedural access. These concentrations shape where interatrial shunt technology achieves commercial traction first.
United States
Integrated delivery networks in Texas and Florida are building dedicated structural heart programs at ambulatory surgery centers. FDA breakthrough device pathways accelerate market entry for qualifying manufacturers. Cleveland Clinic and Mayo Clinic catheterization laboratories anchor clinical trial enrollment and physician training pipelines.
Germany
Balloon-expandable device preferences concentrate in Baden-Württemberg and Bavaria catheterization laboratories serving complex anatomies. EMA MDR compliance requirements extend technical documentation review timelines for notified body certification. Heidelberg and Munich academic medical centers generate payer-relevant outcome data through extended follow-up registries.
Japan
PMDA streamlines approval pathways for devices with prior FDA clearance, reducing regulatory duplication for transcatheter delivery systems. METI funding supports domestic catheterization laboratory expansion in secondary cities. Tokyo and Osaka metropolitan hospitals anchor physician training for transseptal puncture specialists.
India
Apollo Hospitals and Fortis Healthcare chains are building cardiac structural programs in tier-two cities across Maharashtra and Karnataka. CDSCO regulatory frameworks govern import licensing for nitinol-based implantable devices. Mumbai and Bangalore private hospital clusters pioneer procedure-based health packages unlocking self-pay volume.
United Kingdom
NHS England specialized commissioning frameworks concentrate interatrial shunt procedures at designated cardiac centers in London and Manchester. MHRA post-Brexit regulatory autonomy maintains alignment with MDR technical standards. Imperial College Healthcare and Manchester University NHS Foundation Trust anchor clinical evidence generation for NICE technology appraisals.
Interatrial Shunt Devices Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across the interatrial shunt device market. The vendor base separates into three tiers: large cardiovascular conglomerates with electrophysiology and structural heart portfolios, mid-cap device specialists with nitinol manufacturing capabilities, and emerging entrants pursuing connected monitoring integration. Consolidated procurement authority among United States hospital systems favors scale-driven players with integrated sales coverage. Competitive positioning hinges on regulatory affairs bandwidth and health system contracting relationships.
Among diversified cardiovascular conglomerates, Edwards Lifesciences Corporation and Abbott Laboratories occupy positions spanning surgical and transcatheter heart valve portfolios into shunt technologies. Medtronic plc exemplifies the scale-driven archetype with electrophysiology infrastructure extending into structural heart procedures. Corvia Medical, Inc. represents the focused specialist model concentrating exclusively on minimally invasive shunt technologies for heart failure management.
| Leading Market Players |
|---|
| Edwards Lifesciences Corporation |
| Medtronic plc |
| Boston Scientific Corporation |
| Johnson & Johnson |
| Corvia Medical, Inc. |
| Abbott Laboratories |
| Occlutech International AB |
| W.L. Gore & Associates, Inc. |
| Lepu Medical |
| Others |
Pricing and Supply Chain Analysis
EU MDR Article 117 sustainability and biocompatibility mandates gate qualified nitinol supply and premium-tier device pricing access. Manufacturers demonstrating extended follow-up registry compliance capture pricing power with United States integrated delivery networks.
Pricing Analysis
Bundled service contracts dominate United States procurement while unbundled device-plus-procedure pricing persists in European markets. Three-tier pricing structure across FDA breakthrough-designated, CE-marked MDR-compliant, and standard-tier devices differentiates based on regulatory certification level and clinical evidence depth. Pricing pressure stems from pharmacologic heart failure management improvements compressing eligible patient pools. Outpatient surgical centers exhibit highest price sensitivity; academic medical centers with fellowship training pipelines demonstrate lowest sensitivity.
Supply Chain Analysis
Workforce availability constraints in United States nitinol metallurgy hubs and German precision manufacturing clusters tighten component lead times. Superelastic alloy feedstock concentrates among United States, German, and Japanese metallurgical suppliers. Nitinol raw material, polymer composite coatings, and transcatheter delivery system components anchor device manufacturing. Single-source vulnerability in nickel-titanium feedstock creates supply continuity exposure. Distribution runs through integrated delivery network procurement committees consolidating cardiac service line contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Interatrial shunt devices constitute a late-cycle quality story as heart failure management guidelines embed hemodynamic monitoring and systematize device-eligible patient identification through electronic health record integration.
For Market Incumbents: Deploy backward integration into nitinol metallurgy to secure feedstock cost position against superelastic alloy price volatility. Consolidate vendor contracts across electrophysiology and structural heart portfolios to defend procurement committee relationships from emerging connected-monitoring specialists. FDA breakthrough designation velocity and EMA MDR compliance scale represent critical defensive levers. For New Entrants and Emerging Players: Capture Japan's underpenetrated catheterization laboratory networks in secondary cities where METI funding expands infrastructure and PMDA streamlines approval for prior FDA-cleared devices. Target India's tier-two private hospital chains building cardiac structural programs through procedure-based health packages. Lead with remote hemodynamic sensor integration as differentiated go-to-market positioning. For Investors and Strategic Acquirers: Roll-up economics work for mid-cap device specialists with nitinol manufacturing capabilities because integrated delivery network procurement consolidation compresses vendor access points and rewards scale-driven regulatory affairs bandwidth. Five-to-ten year viability hinges on connected monitoring ecosystem integration. Watch FDA national coverage determination timelines as inflection signal for outpatient procedure volume acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Device Pathway | Expedited review compresses clinical validation timelines from five years to eighteen months for qualifying manufacturers. |
| Hospital System Partnership | Integrated delivery network procurement committees demand bundled pricing across cardiac service lines. |
| Connected Monitoring Integration | EU AI Act governance frameworks enable compliant algorithm-driven patient triage for outpatient pressure management. |
| Reimbursement Strategy | CMS national coverage determinations require randomized trial data against optimal medical therapy. |
| CE Marking Pathway | EMA MDR Article 117 elevates clinical evidence standards for polymer-coated shunt surfaces. |
Research Methodology
Multiple input streams — primary interviews with interventional cardiologists, hospital purchasing committee members, and regulatory affairs specialists; secondary validation through FDA filings, EMA MDR submission databases, and hospital procurement records; and supply chain documentation — were reconciled through bottom-up and top-down triangulation.
Data-stream reconciliation anchored volume and value outputs across product type, end user facility tier, delivery method, and indication segmentation dimensions. CAGRs were derived from procedure volume modeling and average selling price trajectories over the projection horizon. Forecast inputs incorporated catheterization laboratory expansion rates, payer coverage determination timelines, and nitinol raw material cost indices.
Regulatory approval delays, reimbursement policy reversals, and pharmacologic therapy outcome improvements are the dominant revision risks to modeled assumptions. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
General Surgery Devices Market
Medical Devices
Allografts Market
Medical Devices
India Drug Delivery Devices Market
Medical Devices
Global Infusion Pumps and Accessories Market
Medical Devices
Latin America Insulin Syringes Market
Medical Devices
Global Artificial Organ Market
Medical Devices
Support Surfaces Market
Medical Devices
Global Hydrocephalus Shunts Market
Medical Devices
Augmented Bone Graft Market
Medical Devices
Medical Device Regulatory Affairs Market
Medical Devices
Multi-Channel Infusion Pumps Market
Medical Devices
United Kingdom Ultrasound Devices Market
Medical Devices
I.V. Fluid Warmer Market
Medical Devices
France Anesthesia Devices Market
Medical Devices
Intravascular Warming Systems Market
Medical Devices
Home Sleep Apnea Testing Devices Market