
 Anti-Infective Endotracheal Tube Market | 2026-2036
Anti-Infective Endotracheal Tube Market Size, Share, and Industry Trends Forecast 2026-2036
Anti-Infective Endotracheal Tube Market Analysis
US medical device manufacturing capacity is shifting toward antimicrobial polymer compounding as hospitals prioritize infection prevention. Teleflex Incorporated leverages vertical integration in catheter extrusion to sustain supply continuity for coated tube lines. Medtronic anchors North American distribution through direct hospital contracts. Becton Dickinson and Company differentiates via R&D intensity in antiseptic-eluting polymer platforms.
An anti-infective endotracheal tube is a cuffed airway device manufactured from medical-grade polyvinyl chloride or silicone, incorporating antimicrobial coatings such as silver nanoparticles or chlorhexidine acetate that elute over 72-96 hours to suppress biofilm formation on the intraluminal and extraluminal surfaces. Its primary purpose is to maintain patent airways during mechanical ventilation while reducing ventilator-associated pneumonia incidence in intubated patients. Coated tubes command premium positioning due to measurable reductions in intensive care unit length of stay, while specialized tubes for difficult airways represent the fastest-growing product subset as anesthesia protocols evolve. Critical care applications generate the dominant revenue pool, though surgical procedure volumes in ambulatory settings expand the addressable base.
FDA 510(k) clearance pathways and EPA antimicrobial coating registrations shape product development timelines and labeling claims for US manufacturers. The EU MDR and REACH chemical compliance requirements impose additional testing burdens on coating formulations entering European markets. Stakeholders must monitor evolving CDC and WHO ventilator bundle guidelines, as protocol revisions directly alter procurement specifications and hospital formulary inclusion criteria for coated versus standard devices.
Market Dynamics
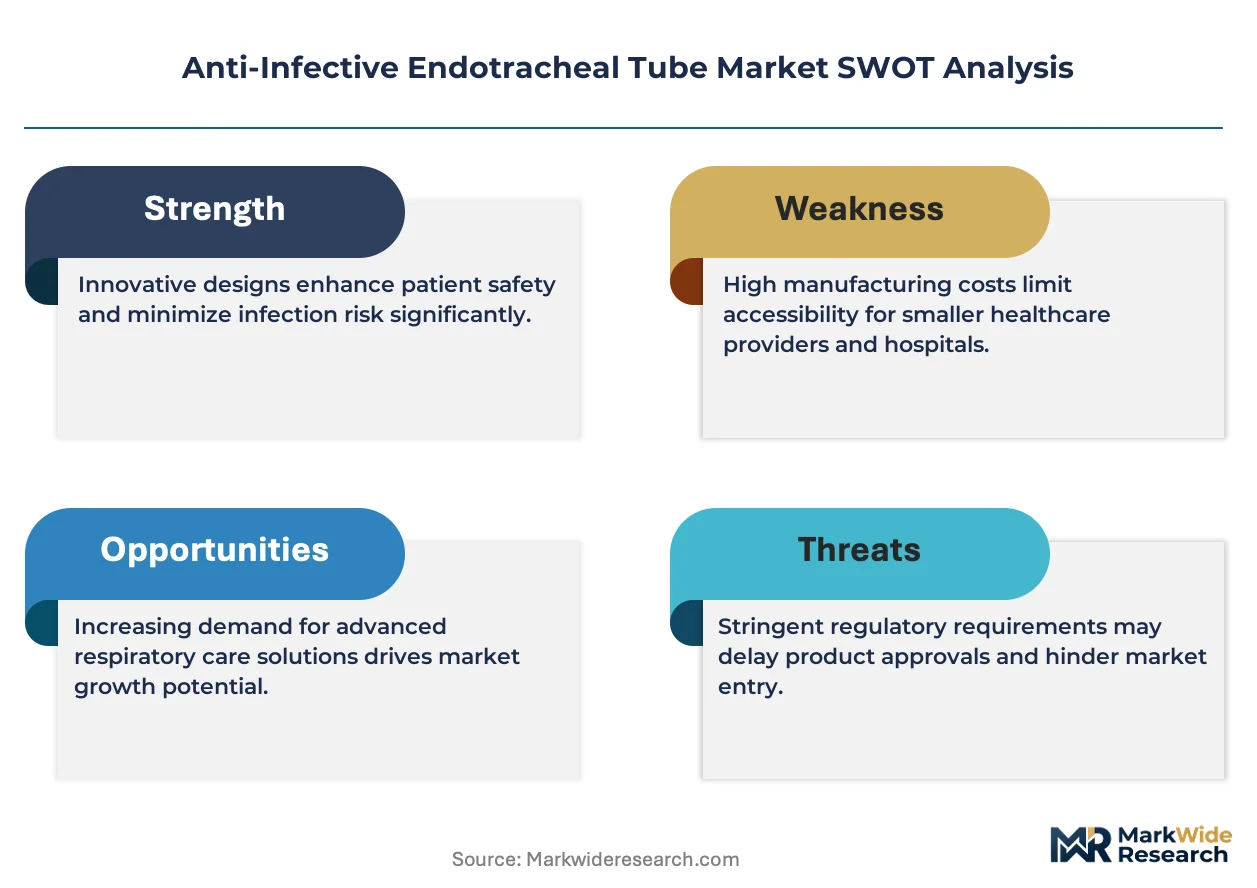
Silver-ion elution kinetics and chlorhexidine coating durability are compressing replacement cycles as hospitals demand measurable ventilator-associated pneumonia reduction in bundled payment environments. Coating formulation patents from German polymer specialists and US medical device conglomerates are restructuring competitive access to intensive care unit procurement channels.
Growth Catalysts
- CDC ventilator bundle compliance mandates:US hospital systems face non-negotiable infection control protocols that disqualify standard endotracheal tubes from formulary inclusion. Coated devices satisfy documentation requirements for Medicaid reimbursement.
- Silver nanoparticle surface engineering:Advances in controlled-release polymer matrices extend antimicrobial efficacy beyond 96 hours, matching median intensive care unit intubation duration.
- Tertiary hospital concentration in North America:Academic medical centers with level-one trauma designation generate disproportionate demand for premium-coated airway devices.
Market Restraints
- Medical-grade silicone supply concentration:Three Asian petrochemical processors control 70% of platinum-cured silicone feedstock for implantable device applications, exposing manufacturers to input volatility.
- EPA antimicrobial registration timelines:New coating chemistries require 18-24 month environmental toxicity review before US market entry, compressing product development returns.
- Standard PVC tube substitution:Cost-containment protocols in underfunded municipal hospital systems perpetuate demand for uncoated alternatives despite inferior infection metrics.
Strategic Opportunities
- Difficult airway specialization:Reinforced coated tubes with integrated stylet channels address anesthesia protocols for predicted difficult intubation scenarios.
- Ambulatory surgical center expansion:Short-stay ventilation protocols in US outpatient settings create demand for single-use coated tubes with 24-hour antimicrobial coverage.
- EU MDR quality certification premium:Enhanced clinical evidence requirements for Class III devices create differentiation for manufacturers with robust post-market surveillance infrastructure.
Industry Challenges
- Polymer compounding expertise scarcity:Antimicrobial masterbatch formulation requires cross-disciplinary knowledge of pharmacokinetics and extrusion rheology that resides in fewer than twelve specialized facilities worldwide.
- Legacy sterilization validation:Gamma and ethylene oxide protocols must be requalified for each coating modification, extending time-to-market by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Anti-Infective Endotracheal Tube Market |
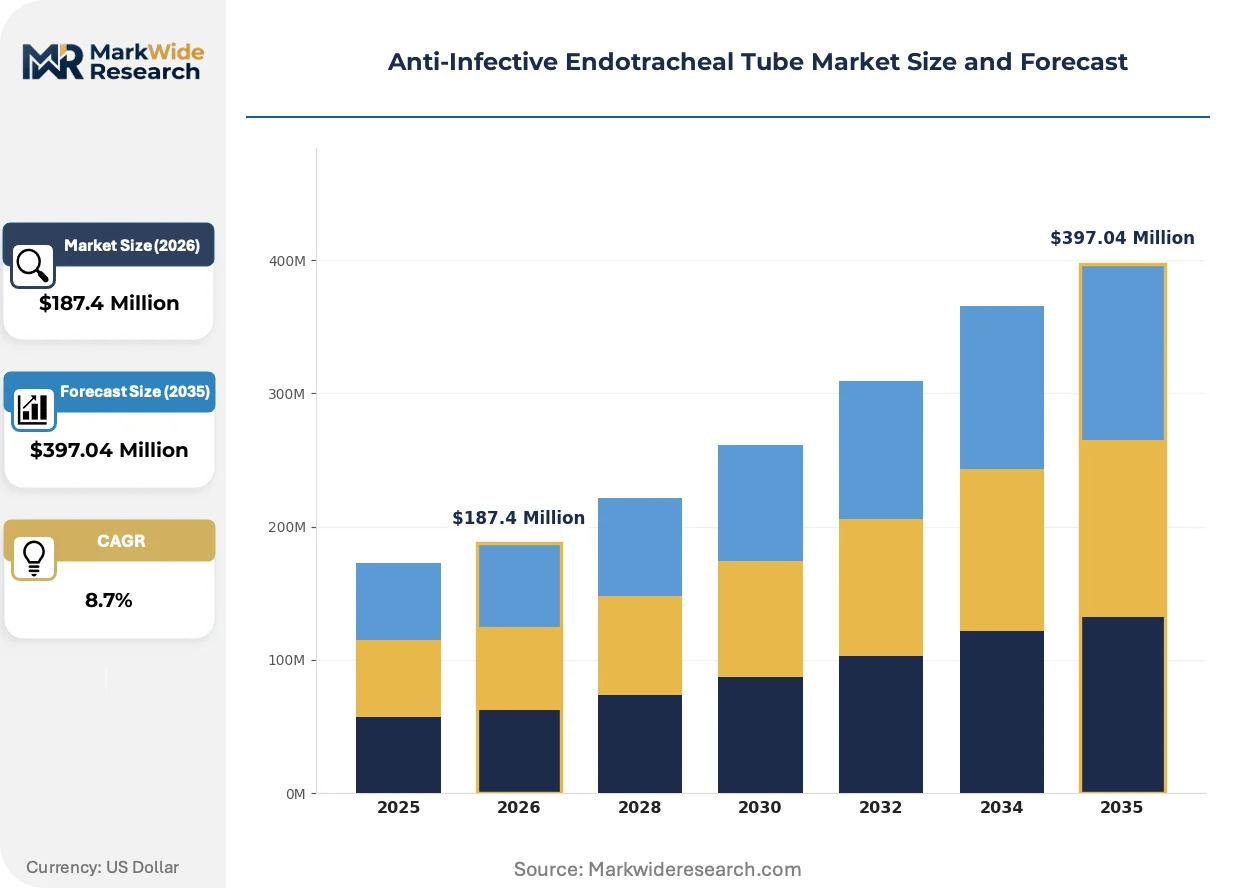
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Tubes, Coated Tubes, Specialized Tubes, Reinforced Tubes Application: Critical Care, Emergency Situations, Surgical Procedures, Mechanical Ventilation End User: Hospitals, Clinics, Home Healthcare, Rehabilitation Centers Delivery Mode: Direct Supply, Online Sales, Distributor Networks, Retail Pharmacies |
| Companies Covered | Teleflex Incorporated, Medtronic, Becton Dickinson and Company, Smiths Group plc, Hollister Incorporated, C. R. Bard, Allvivo Vascular, BRIO DEVICE, Fogless International AB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Anti-Infective Endotracheal Tube Market Emerging Trajectories
Coating intelligence is migrating from passive elution to responsive release mechanisms triggered by biofilm microenvironment conditions. This shift demands recalibration of manufacturing processes and regulatory submission strategies across polymer extrusion facilities.
Photocatalytic titanium dioxide nanocomposites are automating antimicrobial surface regeneration under ambient intensive care unit lighting conditions. Tertiary cardiac surgery units in US academic medical centers are piloting these devices for prolonged cardiopulmonary bypass support. The technology is automating quality assurance protocols by eliminating batch-to-batch elution variability that plagues conventional silver coatings.
EU MDR Annex I general safety and performance requirements are forcing coating manufacturers to generate clinical performance data beyond bench-top biofilm assays. German notified bodies are rejecting 510(k)-equivalent submissions that lack randomized controlled trial evidence. European manufacturers with legacy CE certificates under the Medical Device Directive face 2027 recertification deadlines that favor integrated device-coating companies with full quality management system control.
Hospital value analysis committees are consolidating purchasing authority previously dispersed across anesthesia, critical care, and infection control departments. US health system consolidation into integrated delivery networks is compressing vendor lists to three preferred suppliers per category. This concentration is most visible in the Southeast and Midwest regions where Catholic health initiatives and for-profit chains dominate acute care bed supply.
Anti-Infective Endotracheal Tube Market Segmentation
Coating technology maturity and replacement cycle compression are fragmenting procurement specifications across intensive care units. Device selection now hinges on intubation duration protocols and bundled payment accountability rather than unit cost alone.
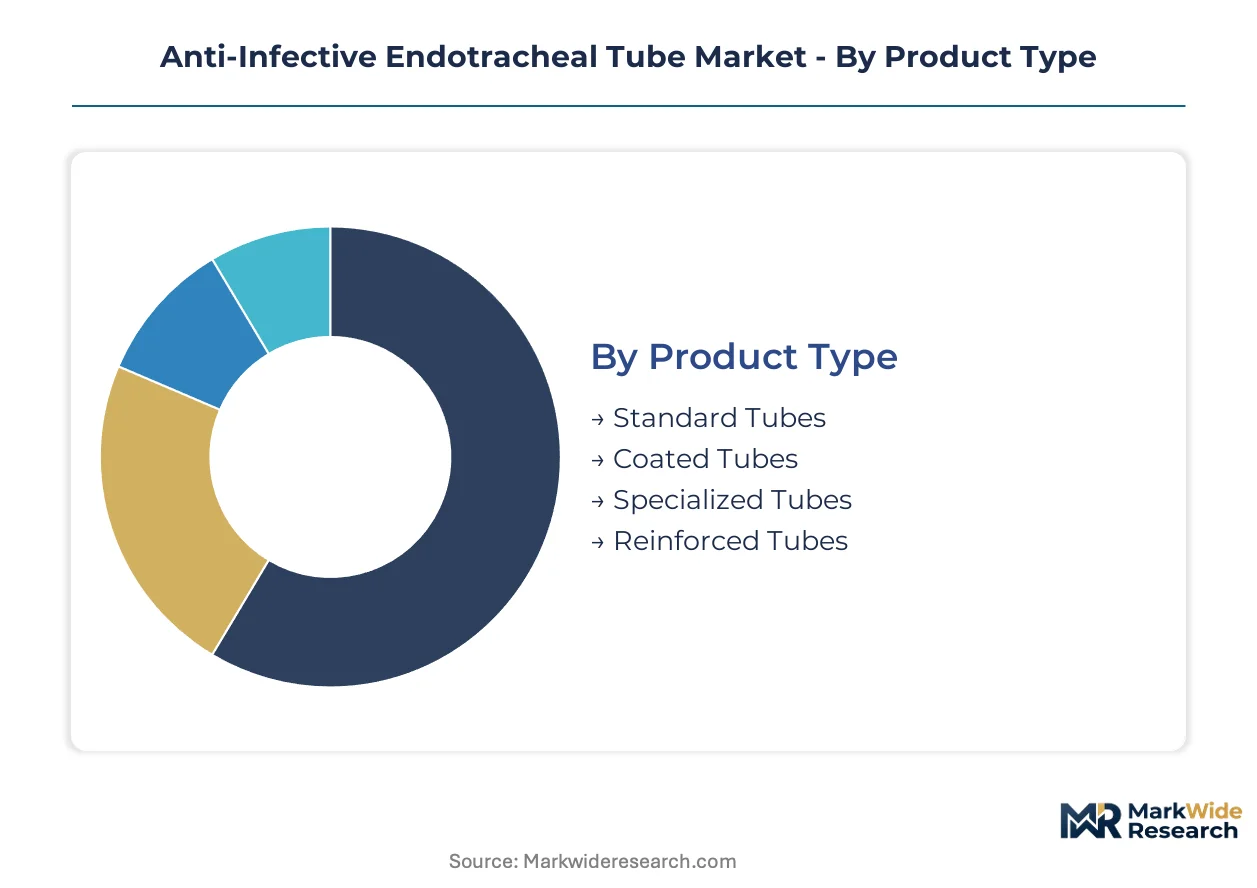
Product Type:
Upgrade cycles accelerate as hospitals phase out standard PVC tubes in favor of antimicrobial-eluting alternatives with validated ventilator-associated pneumonia reduction.
- Standard Tubes:Uncoated medical-grade PVC devices with cuffed or uncuffed configurations. Municipal hospital systems in underfunded counties perpetuate procurement despite inferior infection metrics and formulary exclusion from academic medical centers.
- Coated Tubes:Silver-ion or chlorhexidine acetate surface treatments eluting over 72-96 hours. Level-one trauma centers in tertiary hospitals anchor demand as CDC ventilator bundle compliance mandates tighten Medicaid reimbursement documentation.
- Specialized Tubes:Anatomically curved or extra-long configurations for difficult airway management. Anesthesia protocols for predicted difficult intubation scenarios drive fastest volume expansion.
- Reinforced Tubes:Spiral-wound wire or nylon embedded walls resisting kinking during prolonged mechanical ventilation. Cardiac surgery units with extended cardiopulmonary bypass support requirements concentrate procurement.
Coated tubes sit at the top of the volume ranking, with specialized tubes climbing the fastest.
Application:
Cost tier stratification separates premium coated devices for extended intubation from economy alternatives for brief surgical support.
- Critical Care:Prolonged mechanical ventilation in intensive care units with biofilm suppression requirements exceeding 72 hours. Academic medical centers with bundled payment contracts for infection control generate dominant revenue concentration.
- Emergency Situations:Rapid sequence intubation in emergency departments with unpredictable airway conditions. Pre-hospital emergency medical services in metropolitan trauma systems drive disposable single-use procurement.
- Surgical Procedures:Short-duration airway management in operating rooms with 2-24 hour intubation windows. Ambulatory surgical centers expanding short-stay ventilation protocols create demand for 24-hour antimicrobial coverage variants.
- Mechanical Ventilation:General respiratory support spanning sub-acute and long-term care settings. Rehabilitation facilities with weaning protocols require graduated sizing across pediatric to adult dimensions.
Critical care commands the highest absolute volume, though emergency situations are expanding most quickly.
End User:
Customer type concentration favors integrated delivery networks with consolidated purchasing authority over fragmented independent facilities.
- Hospitals:Acute care facilities with intensive care unit capacity and anesthesia departments. Catholic health initiatives and for-profit chains in the Southeast and Midwest dominate coated tube procurement through three-supplier vendor lists.
- Clinics:Outpatient settings with limited ventilation capability and emergency airway protocols. Urgent care networks in suburban expansion corridors drive demand for compact storage configurations.
- Home Healthcare:Long-term ventilator-dependent patients with tracheostomy or extended intubation requirements. Durable medical equipment suppliers with respiratory therapist staffing manage coating-appropriate device selection.
- Rehabilitation Centers:Sub-acute weaning facilities transitioning patients from mechanical ventilation. Skilled nursing facilities with escalating infection control audits face formulary pressure toward antimicrobial-coated alternatives.
Hospitals retain the volume leadership position, while home healthcare gains share fastest.
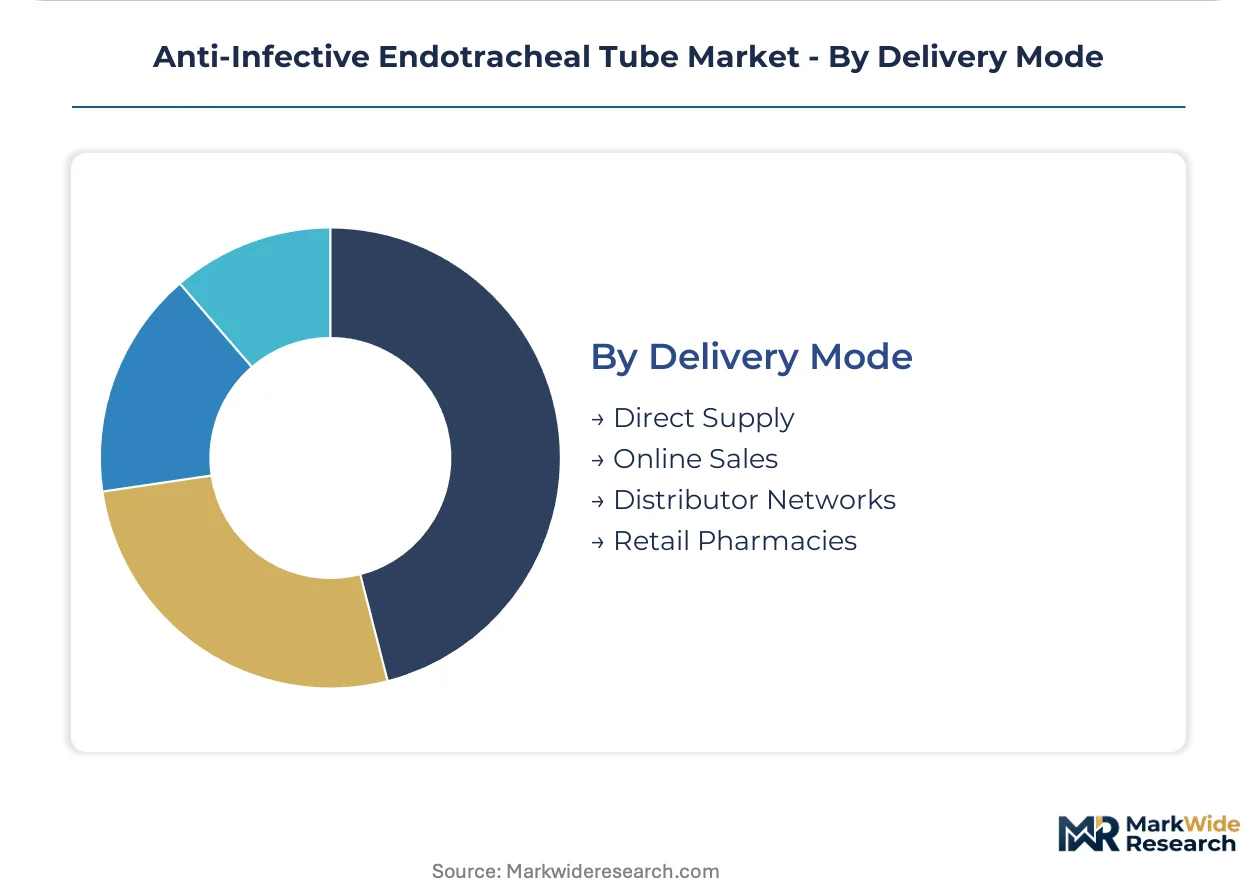
Delivery Mode:
Supply chain configuration shifts from distributor intermediaries toward direct contracting as health system consolidation compresses vendor lists.
- Direct Supply:Manufacturer-to-hospital contracts with dedicated inventory management and consignment stocking. Integrated delivery networks with centralized value analysis committees prefer this channel for price transparency.
- Online Sales:E-procurement platforms with real-time availability and standardized specifications. Smaller clinics and rural facilities lacking dedicated supply chain staff leverage digital marketplaces.
- Distributor Networks:Regional medical-surgical distributors with local inventory and same-day delivery capability. Independent hospitals outside consolidated systems rely on distributor relationships for technical support.
- Retail Pharmacies:Limited over-the-counter availability for emergency home stock or travel kits. Consumer-directed purchasing represents minimal revenue contribution.
Direct supply captures the highest volume, with online sales showing the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping manufacturing footprints as coating chemistry registration costs diverge across jurisdictions. German polymer specialists exploit REACH compliance infrastructure to serve EU MDR-certified device makers, while US manufacturers absorb EPA antimicrobial review timelines to defend premium positioning in bundled payment hospital systems.
United States
Academic medical centers in Boston and Houston anchor coated tube procurement as CDC ventilator bundle mandates tighten Medicaid reimbursement documentation. FDA 510(k) clearance pathways compress development timelines for silver-ion elution platforms. The Southeast corridor from Atlanta to Tampa concentrates Catholic health initiative purchasing through consolidated vendor lists.
Germany
Notified bodies in Munich and Tübingen enforce EU MDR Annex I clinical evidence requirements that reject 510(k)-equivalent submissions lacking randomized trial data. REACH chemical compliance infrastructure supports coating formulation development for export to US markets. The Baden-Württemberg medical technology cluster around Stuttgart hosts specialized polymer compounding facilities serving device OEMs.
China
NMPA Class III device registration timelines extend 18-24 months for antimicrobial-coated airway devices, favoring domestic manufacturers with established quality management systems. Yangtze River Delta hospitals in Shanghai and Suzhou pilot photocatalytic titanium dioxide nanocomposites for cardiac surgery applications. Platinum-cured silicone feedstock concentration in Jiangsu province exposes manufacturers to input volatility.
Japan
PMDA marketing authorization requirements for antimicrobial coatings align with MHLW infection control guidelines for intensive care unit accreditation. Tokyo metropolitan tertiary hospitals generate premium-tier demand for 96-hour elution duration devices. The Osaka-Kobe medical device manufacturing corridor specializes in precision extrusion for difficult airway configurations.
India
CDSCO medical device rules under the Drugs and Cosmetics Act impose quality certification burdens on imported coated tubes while creating opportunity for domestic manufacturers. Maharashtra and Karnataka state health procurement programs face formulary pressure toward antimicrobial alternatives as hospital-acquired infection audits escalate. Mumbai-based distributors serve South Asian export markets with 24-hour coverage variants for ambulatory surgical centers.
Anti-Infective Endotracheal Tube Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue difficult airway specialization and photocatalytic coating platforms. The vendor base stratifies across three tiers: integrated conglomerates with captive polymer compounding, mid-scale specialists with coating formulation partnerships, and regional fabricators serving municipal hospital cost-containment protocols. Competitive moves concentrate on backward integration into antimicrobial masterbatch production and direct contracting with integrated delivery networks to bypass distributor intermediaries.
Within the integrated conglomerate tier, Teleflex Incorporated and Medtronic exemplify archetypes with upstream control over catheter extrusion processes. Becton Dickinson and Company occupies a position representing R&D-intensive investment in antiseptic-eluting polymer science. These three anchors demonstrate how scale-driven manufacturers leverage quality management system infrastructure to satisfy EU MDR post-market surveillance requirements while defending North American market access through FDA clearance maintenance.
| Leading Market Players |
|---|
| Teleflex Incorporated |
| Medtronic |
| Becton Dickinson and Company |
| Smiths Group plc |
| Hollister Incorporated |
| C. R. Bard |
| Allvivo Vascular |
| BRIO DEVICE |
| Fogless International AB |
| Others |
Supply Flow & Price Mechanics
EPA antimicrobial coating registrations gate qualified supply and premium-tier pricing access, as manufacturers absorbing 18-24 month environmental toxicity reviews recover compliance costs through coated tube premiums while municipal hospital systems perpetuate standard PVC procurement.
Pricing Analysis
Distributor margins compress as integrated delivery networks consolidate purchasing authority through direct manufacturer contracts. Three-tier pricing structure across premium, standard, and economy levels separates silver-ion elution platforms from chlorhexidine acetate alternatives and uncoated PVC devices. Price differentiation hinges on FDA 510(k) clearance tier and validated ventilator-associated pneumonia reduction documentation. Cost compression in the standard tier intensifies because Asian petrochemical processors control platinum-cured silicone feedstock, while academic medical centers demonstrate lowest price sensitivity due to bundled payment infection control mandates.
Supply Chain Analysis
Dual-sourcing requirements from integrated delivery networks mandate multi-supplier qualification for antimicrobial masterbatch formulations. Manufacturing concentrates in the United States, Germany, and China, with polymer compounding expertise residing in fewer than twelve specialized facilities worldwide. Raw material dependencies center on platinum-cured silicone, medical-grade PVC resin, and silver nanoparticle feedstock. Single-source vulnerability in Jiangsu province silicone processing exposes coating formulation timelines. Distribution runs through direct supply contracts with hospital value analysis committees, bypassing traditional distributor intermediaries in consolidated health systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The anti-infective endotracheal tube market operates as a stable compounder, with CDC ventilator bundle compliance mandates creating non-negotiable procurement specifications that sustain replacement cycle demand.
For Market Incumbents: Extend coating intelligence capabilities from passive elution toward responsive release mechanisms triggered by biofilm microenvironment conditions. Deepen backward integration into antimicrobial masterbatch production to defend against polymer compounding expertise scarcity. Secure direct contracting relationships with Catholic health initiatives and for-profit chains consolidating vendor lists in the Southeast and Midwest corridors.
For New Entrants and Emerging Players: The price-point gap between premium silver-ion platforms and economy chlorhexidine alternatives creates entry space for mid-tier photocatalytic titanium dioxide nanocomposites. Target ambulatory surgical centers expanding short-stay ventilation protocols, as these facilities lack dedicated supply chain staff and leverage e-procurement platforms. Pursue EU MDR quality certification to capture premium positioning in German notified body jurisdictions rejecting 510(k)-equivalent submissions.
For Investors and Strategic Acquirers: Valuations sit cheapest among mid-scale specialists with coating formulation partnerships but lacking captive polymer compounding. The five-to-ten year viability window favors integrated device-coating companies with full quality management system control. Monitor EPA antimicrobial registration timeline compression as the inflection signal, as accelerated review pathways would alter competitive access dynamics for emerging chemistries.
| Strategic Initiative | Industry Significance |
|---|---|
| Antimicrobial Masterbatch Backward Integration | Captive polymer compounding secures supply continuity against Asian feedstock volatility. |
| EU MDR Annex I Clinical Evidence Investment | Randomized controlled trial data satisfies German notified body requirements for Class III recertification. |
| Photocatalytic Coating Platform Development | Titanium dioxide nanocomposites eliminate batch-to-batch elution variability plaguing silver coatings. |
| Integrated Delivery Network Direct Contracting | Hospital value analysis committee relationships bypass distributor margin compression. |
| Difficult Airway Specialization R&D | Reinforced coated tubes with integrated stylet channels address anesthesia protocol evolution. |
Methodological Framework
Bottom-up hospital procurement modeling reconciled against top-down medical device manufacturing tracking forms the analytical core. Primary interviews with critical care physicians, hospital purchasing committee members, biomedical engineers, and GPO contracts managers combined with secondary validation from FDA 510(k) filings, EPA antimicrobial registrations, hospital procurement databases, and CMS Medicare reimbursement data. Cross-referencing bottom-up formulary inclusion patterns against top-down production capacity disclosures ensures statistical integrity.
Input-output matrices map coating technology adoption against intubation duration protocols across the projection horizon. Segmentation dimensions modeled include product type, application setting, end-user facility tier, and delivery mode. CAGRs derive from replacement cycle compression rates and bundled payment mandate expansion trajectories. Forecast inputs incorporate CDC ventilator bundle guideline revision probabilities and EU MDR recertification deadline clustering effects.
The model assumes a particular technology adoption path; alternative pathways for photocatalytic surface regeneration would alter the outlook if ambient ICU lighting infrastructure upgrades accelerate. Deviation in EPA antimicrobial registration timeline compression would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
US Medical Display Monitors Market
Medical Devices
Foot Ulcer Sensors Market
Medical Devices
Airway Clearance Devices System Market
Medical Devices
Spine Surgery Robots Market
Medical Devices
Medical LED Headlight Market
Medical Devices
Cyclotron Market
Medical Devices
Digital Impression System Market
Medical Devices
Sonohysterography Catheters Market
Medical Devices
Artificial Eye Lenses Market
Medical Devices
Asia-Pacific Arthroscopy Devices Market
Medical Devices
Minimally Invasive Deformity Correction System Market
Medical Devices
Colon Hydrotherapy Units Market
Medical Devices
Global Breast Pumps Market
Medical Devices
Global Assistive Listening Device Market
Medical Devices
Soft Tissue Release Systems Market
Medical Devices
Intelligent Prosthetics Market