
 Elastomeric Infusion Pump Market | 2026-2036
Elastomeric Infusion Pump Market Size, Share, and Industry Trends Forecast 2026-2036
Elastomeric Infusion Pump Market Intelligence
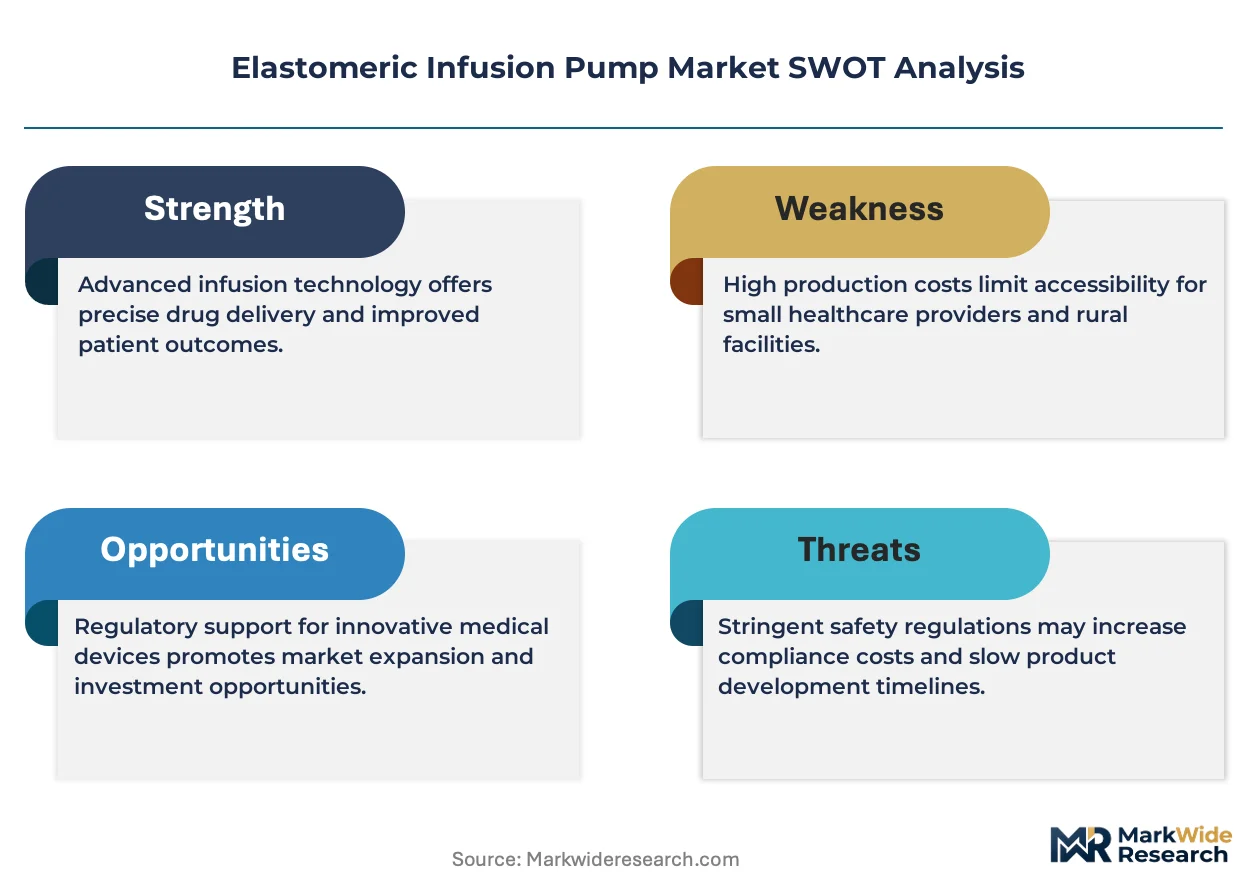
The capital-intensity divergence between fully integrated manufacturers and assembly-only competitors is unwinding competitive stability in the elastomeric infusion pump sector. Baxter International Inc. leverages captive silicone molding capabilities to control raw material costs across its disposable pump portfolio. Fresenius Kabi AG anchors its European manufacturing footprint with automated elastomer testing lines that reduce batch rejection rates. Nipro Corporation competes through specialized balloon reservoir geometries that extend flow-rate precision in chemotherapy applications.
An elastomeric infusion pump is a disposable, non-electronic drug delivery device that uses a pressurized silicone or latex balloon reservoir to administer fluids at a predetermined flow rate through an inline flow restrictor, typically calibrated for rates between 0.5 and 500 mL per hour. These devices serve primarily in ambulatory and home-based settings where portability, silent operation, and elimination of battery dependency outweigh the need for programmable electronic control. Continuous infusion pumps dominate hospital procurement volumes due to standardized protocols for post-operative analgesia, while disposable pumps capture the fastest expansion as home care providers prioritize single-use infection control and simplified inventory logistics. Pain management applications sustain premium pricing through dedicated epidural delivery configurations, whereas antibiotic therapy segments compete on volume throughput and unit cost minimization.
The FDA enforces biocompatibility and sterility standards under 21 CFR Part 820 quality system regulations, while ISO 28620 sets dimensional and performance benchmarks for non-electronic infusion devices that shape export eligibility for Asian manufacturers. The EU Medical Device Regulation (MDR) intensifies clinical evidence requirements for Class IIa devices, extending certification timelines and favoring incumbents with established notified body relationships. Stakeholders must monitor evolving home reimbursement codes from CMS and parallel European health technology assessment bodies, as ambulatory payment structures increasingly determine whether elastomeric systems displace electronic alternatives in outpatient protocols.
Market Dynamics
The FDA's tightened biocompatibility requirements for silicone-based reservoirs are compressing product design cycles and forcing manufacturers to revalidate material formulations across entire pump portfolios.
Growth Catalysts
- Outpatient chemotherapy protocols:Ambulatory surgery centers in the United States are standardizing disposable elastomeric systems for post-operative analgesia, replacing reusable electronic pumps in same-day discharge pathways.
- ISO 28620 harmonization:Dimensional and performance benchmarks for non-electronic infusion devices are enabling Asian manufacturers to enter European supply chains without redundant certification testing.
- Silent operation requirement:Home care patients managing chronic pain are rejecting battery-dependent alternatives, pulling demand toward elastomeric balloon reservoirs that operate without electronic noise.
Market Restraints
- Medical-grade silicone price volatility:Raw material costs fluctuate with semiconductor foundry demand for the same silicone precursors, squeezing margins on disposable pump production.
- EU MDR clinical evidence requirements:Class IIa device certification timelines have extended by 12-18 months, freezing new entrants from European hospital procurement cycles until notified body relationships mature.
- Electronic infusion pump substitution:Smart pumps with dose-error reduction software are recapturing hospital segments where programmable control outweighs portability advantages.
Strategic Opportunities
- Rural home care expansion:Medicare reimbursement code revisions for remote infusion services are opening patient populations beyond urban hospital catchment areas.
- Antibiotic therapy protocols:Outpatient parenteral antimicrobial therapy programs are adopting elastomeric systems for 24-hour continuous infusion, displacing gravity-fed IV bags in infectious disease clinics.
- Bioresorbable flow restrictor development:Convergence of polymer chemistry and micro-molding is enabling single-material pumps that eliminate separate silicone-latex component sourcing.
Industry Challenges
- Biocompatibility testing talent scarcity:ISO 10993-1 cytotoxicity and sensitization studies require specialized toxicologists that medical device manufacturers struggle to recruit against pharmaceutical competitors.
- Legacy electronic health record integration:Home care agencies deploying elastomeric pumps face workflow friction connecting non-networked devices to centralized patient monitoring platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Elastomeric Infusion Pump Market |
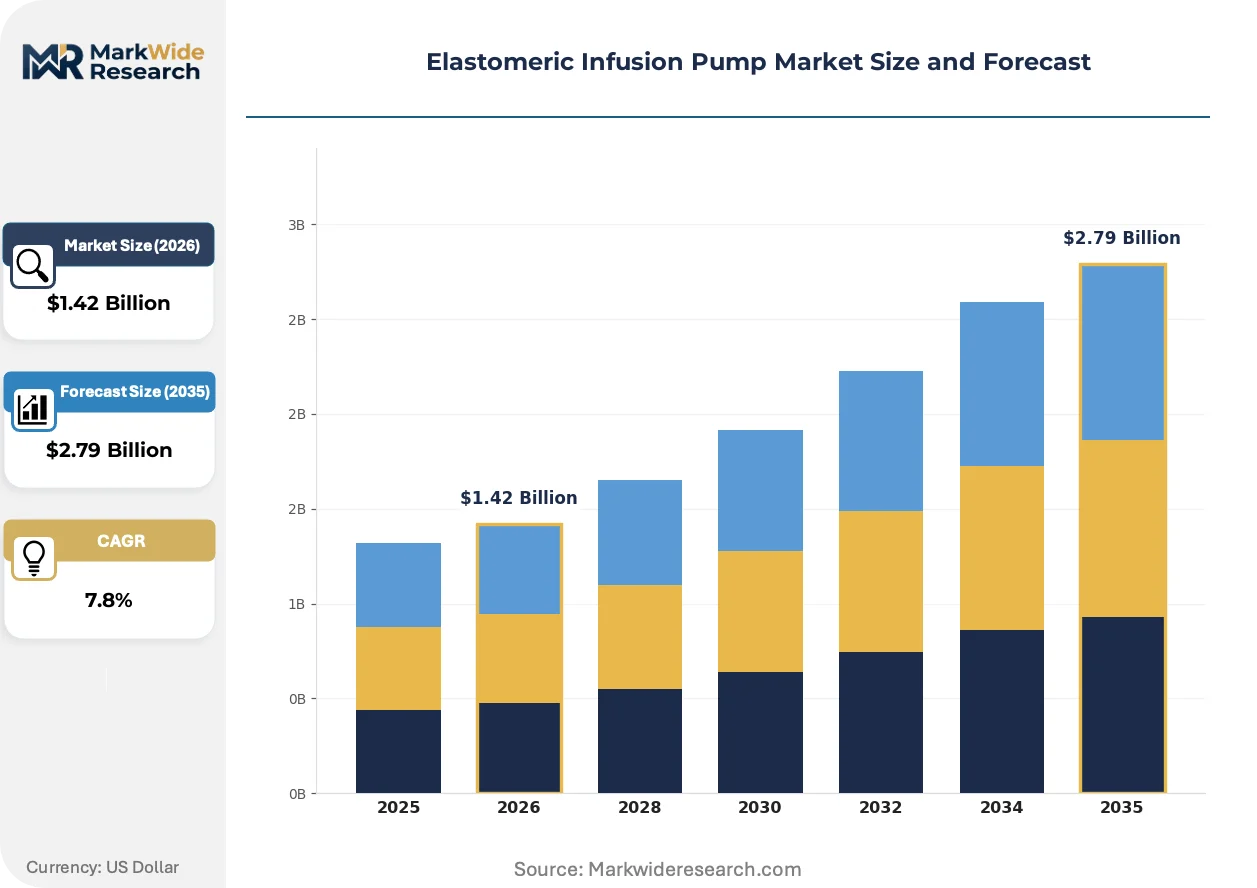
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.79 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Continuous Infusion Pumps, Intermittent Infusion Pumps, Large Volume Pumps, Disposable Pumps End User: Hospitals, Healthcare Facilities, Home Care, Long-term Care Centers Application: Pain Management, Chemotherapy, Antibiotic Therapy, Anesthesia Delivery Mode: Subcutaneous, Intravenous, Epidural, Intrapleural |
| Companies Covered | Ambu A/S, Nipro Corporation, Baxter International Inc., Terumo Corporation, Avanos Medical Inc., Fresenius Kabi AG, Leventon S.A.U., Smiths Medical, B. Braun Melsungen AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Elastomeric Infusion Pump Market Strategic Shifts & Innovations
Material science advances and regulatory harmonization are converging to reshape how elastomeric pumps are specified, manufactured, and deployed across care settings.
Multi-layer co-extrusion balloon technology is fragmenting the traditional single-reservoir design paradigm. Oncology clinics are adopting these structures for chemotherapy applications where dose precision across variable back-pressure conditions is critical. The technology is fragmenting procurement specifications as hospitals rewrite tender documents to require flow-rate accuracy bands that only advanced geometries can satisfy.
EU MDR intensified scrutiny of clinical evidence for Class IIa devices is extending certification timelines for manufacturers without established notified body relationships. European hospital procurement departments are narrowing supplier lists to incumbents with pre-existing technical documentation packages. German and French distributors report that Asian manufacturers are withdrawing from tender processes rather than absorbing MDR compliance costs.
Home care agencies are consolidating purchasing through group purchasing organizations that demand standardized pump configurations across multi-state service territories. Regional distributors that previously stocked specialty geometries are being displaced by national contracts specifying single-SKU disposable systems. The consolidation is most visible in Texas and Florida, where large home infusion providers have captured sufficient volume to dictate manufacturer product roadmaps.
Elastomeric Infusion Pump Market Segmentation
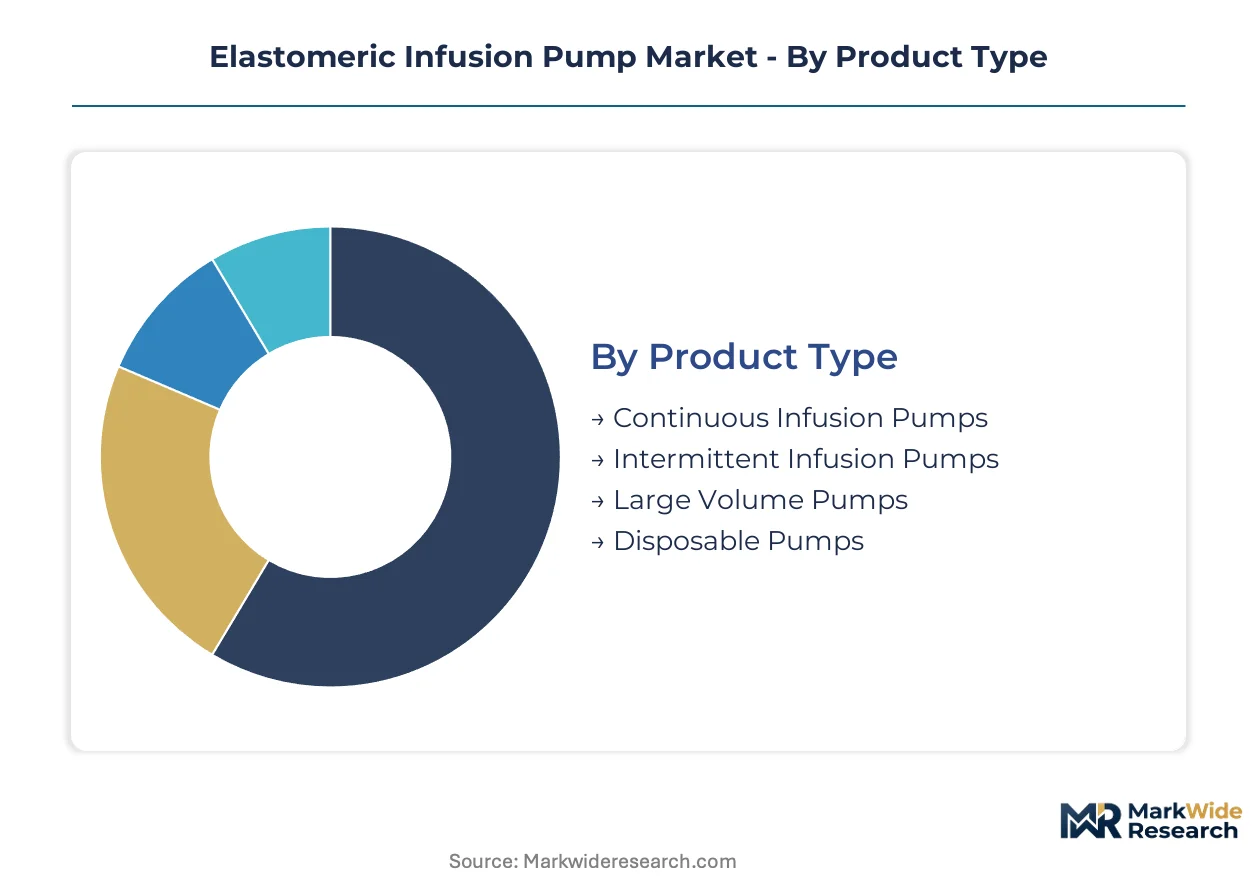
Elastomeric infusion pump procurement channels fragment sharply between institutional buyers with negotiated formulary contracts and home care agencies purchasing through group purchasing organizations. Understanding segment-channel alignment reveals where pricing power concentrates and where commoditization pressures dominate.
Product Type:
Hospital procurement channels favor reusable systems with validated sterilization protocols, while home care distributors push single-use disposables that eliminate reverse logistics.
- Continuous Infusion Pumps:These devices deliver fluids at fixed rates through calibrated flow restrictors without electronic components. Post-operative analgesia protocols in United States ambulatory surgery centers specify these systems for same-day discharge pathways where silent operation and portability outweigh programmable features.
- Disposable Pumps:Single-use elastomeric reservoirs with integrated flow restrictors eliminate cross-contamination risks. Medicare reimbursement code expansions for remote infusion services are pulling these systems into rural home care markets beyond traditional hospital catchment areas.
- Intermittent Infusion Pumps:Designed for scheduled dosing intervals rather than continuous flow, these systems serve antibiotic therapy programs requiring precise bolus timing.
- Large Volume Pumps:Extended-duration reservoirs exceeding 500 mL capacity address chemotherapy regimens requiring 24-hour infusion cycles.
Continuous infusion pumps dominate installed base. Disposable pumps are where expansion concentrates.
End User:
Reimbursement structures determine cost tier alignment, with CMS fee schedules creating three distinct pricing bands across patient settings.
- Hospitals:Acute care facilities with centralized pharmacy operations and electronic health record integration requirements. These buyers prioritize FDA-validated devices with established biocompatibility documentation under 21 CFR Part 820 quality system regulations.
- Home Care:Patients managing chronic pain or infectious disease outside institutional settings. Silent balloon reservoir operation and elimination of battery dependency drive preference for elastomeric systems over electronic alternatives in this segment.
- Healthcare Facilities:Outpatient clinics and ambulatory surgery centers with standardized protocols for post-operative analgesia.
- Long-term Care Centers:Skilled nursing facilities with limited on-site pharmacy capabilities and simplified inventory logistics requirements.
Hospitals anchor volume procurement. Home care is climbing the fastest as reimbursement codes shift toward ambulatory models.
Application:
Clinical evidence requirements under EU MDR intensify margin pressure in segments where Class IIa device certification demands extended notified body engagement.
- Pain Management:Epidural and subcutaneous delivery configurations for post-operative and chronic pain. Dedicated reservoir geometries with flow-rate precision bands command premium pricing through specialized oncology clinic procurement.
- Chemotherapy:Outpatient parenteral protocols requiring dose accuracy across variable back-pressure conditions. Multi-layer co-extrusion balloon technology is fragmenting tender specifications as hospitals rewrite requirements for advanced geometries.
- Antibiotic Therapy:Continuous infusion for infectious disease clinics displacing gravity-fed IV bags.
- Anesthesia:Intraoperative and recovery room applications with rapid turnover requirements.
Pain management sustains premium positioning. Chemotherapy is gaining share fastest through precision dosing demands.
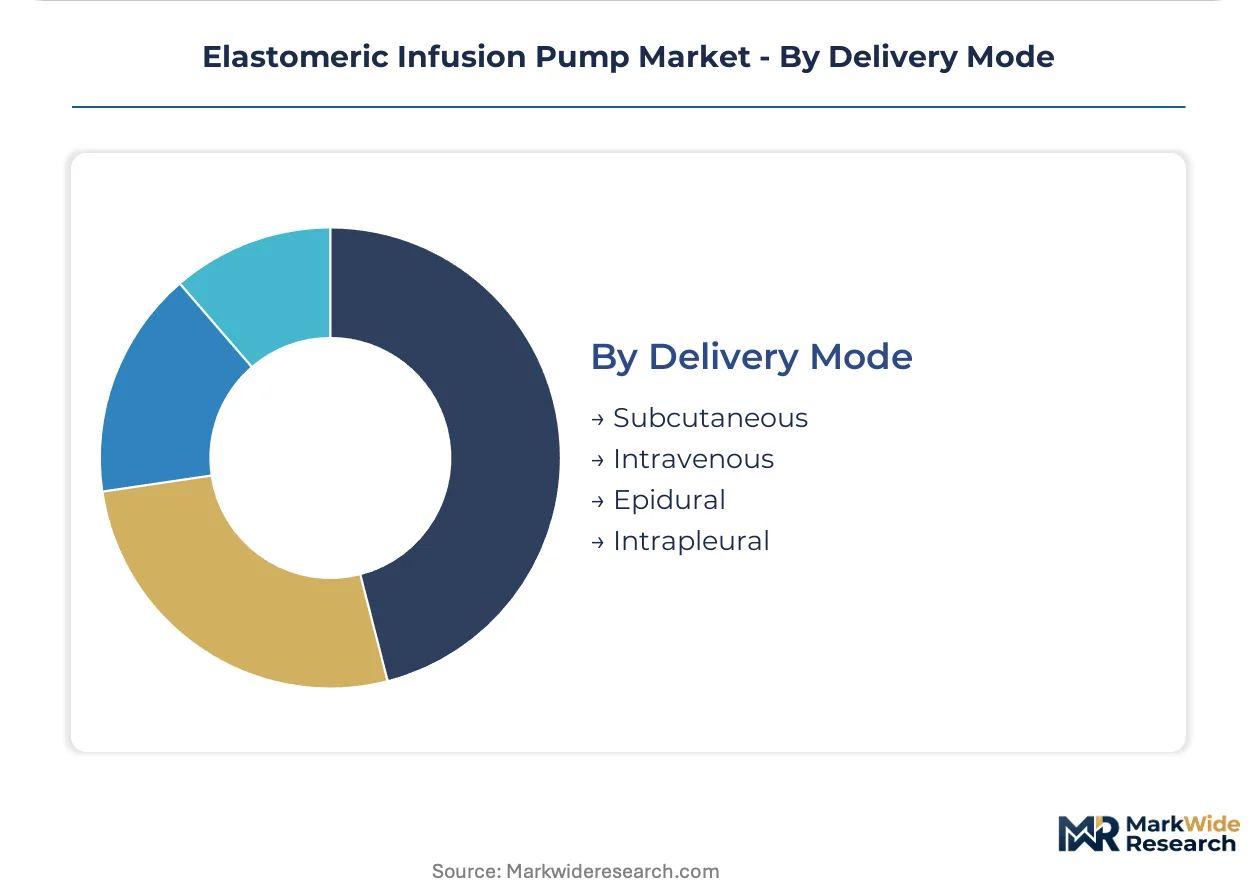
Delivery Mode:
Route-specific reservoir designs create supply concentration around specialized molding capabilities that smaller competitors cannot replicate.
- Intravenous:Direct vascular access through peripheral or central lines represents the standard delivery pathway for antibiotic and chemotherapy applications. ISO 28620 dimensional benchmarks enable Asian manufacturers to enter European supply chains for this delivery mode without redundant certification.
- Epidural:Space-specific catheter placement for regional anesthesia and analgesia. Baxter International's captive silicone molding capabilities control raw material costs for these specialized reservoir configurations.
- Subcutaneous:Tissue-layer delivery for insulin and biologic administration in home settings.
- Intrapleural:Pleural cavity access for post-thoracotomy pain management with limited manufacturer participation.
Intravenous delivery anchors procedure volume. Epidural configurations command the steepest expansion trajectory through ambulatory surgery standardization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States buyers command pricing premiums through ambulatory surgery standardization, while German procurement offices extract cost concessions via centralized hospital group purchasing. This asymmetry fragments manufacturer margin structures across Atlantic markets.
United States
Ambulatory surgery centers in Texas and Florida drive replacement rates for disposable elastomeric systems through same-day discharge protocols. CMS reimbursement code expansions for remote infusion services pull demand into rural home care markets beyond traditional hospital catchment areas. The FDA enforces biocompatibility standards under 21 CFR Part 820 quality system regulations, compressing design cycles for silicone-based reservoir revalidation.
Germany
Automated elastomer testing lines in Baden-Württemberg reduce batch rejection rates for manufacturers serving European hospital networks. The EU Medical Device Regulation intensifies clinical evidence requirements for Class IIa devices, extending certification timelines by 12-18 months and freezing new entrants from procurement cycles. Bavarian distributors report Asian manufacturers withdrawing from tender processes rather than absorbing MDR compliance costs.
Japan
Specialized balloon reservoir geometries extend flow-rate precision for chemotherapy applications in Tokyo and Osaka metropolitan clinics. METI standards harmonization with ISO 28620 enables streamlined export eligibility for domestic manufacturers. The Kansai industrial corridor concentrates precision molding capabilities that supply reservoir components across Asia-Pacific markets.
China
NMPA regulatory alignment with international biocompatibility benchmarks accelerates market access for domestic elastomeric pump producers. Yangtze River Delta manufacturing clusters scale silicone molding capacity to serve both domestic hospital procurement and European export channels. Shanghai-based distributors report growing adoption in outpatient parenteral antimicrobial therapy programs.
United Kingdom
London and Southeast England healthcare facilities prioritize silent-operation devices for home care pain management applications. The Medicines and Healthcare products Regulatory Agency enforces post-Brexit conformity assessment procedures that diverge from EU MDR timelines. Midlands-based distributors consolidate purchasing through group purchasing organizations demanding standardized pump configurations across multi-region service territories.
Elastomeric Infusion Pump Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes, with integrated manufacturers controlling material formulations while assembly-focused competitors compete on volume throughput. The vendor base stratifies into three tiers: multinational healthcare conglomerates with captive silicone supply chains, regional specialists in precision balloon geometries, and contract manufacturers serving private-label distributors. Consolidation pressures favor incumbents with established notified body relationships under EU MDR. Dominant competitive moves include backward integration into medical-grade silicone sourcing and geographic expansion through distributor acquisition.
Among diversified healthcare conglomerates, Baxter International Inc. and Fresenius Kabi AG exemplify integrated manufacturing archetypes with European and North American production footprints. Nipro Corporation occupies a specialist position in precision reservoir geometries for oncology applications. These three entities anchor competitive dynamics through contrasting approaches to material control, regulatory navigation, and segment focus.
| Leading Market Players |
|---|
| Ambu A/S |
| Nipro Corporation |
| Baxter International Inc. |
| Terumo Corporation |
| Avanos Medical Inc. |
| Fresenius Kabi AG |
| Leventon S.A.U. |
| Smiths Medical |
| B. Braun Melsungen AG |
| Others |
Cost & Logistics Intelligence
Bioresorbable flow restrictor substitution for silicone-latex components is relocating manufacturing gravity from traditional elastomer clusters to polymer chemistry hubs, collapsing the historical premium commanded by medical-grade silicone formulations while opening cost arbitrage for integrated compounders.
Pricing Analysis
Configured-to-order pricing for multi-layer co-extrusion balloon reservoirs commands spreads of 40-60% above standard single-reservoir configurations. Pricing stratifies across premium, standard, and economy tiers anchored by FDA biocompatibility certification grade and flow-rate precision bands. Cost compression in the standard tier is intensifying because Yangtze River Delta manufacturers are scaling silicone molding capacity for European export channels. Home care agencies purchasing through group purchasing organizations exhibit the highest price sensitivity, while oncology clinics with dedicated chemotherapy protocols show the least.
Supply Chain Analysis
China, Germany, and the United States concentrate elastomeric pump manufacturing through distinct capability anchors. Medical-grade silicone precursors draw from semiconductor foundry suppliers, creating feedstock competition with chip fabrication. Single-source vulnerability concentrates in Japanese precision molding equipment required for multi-layer balloon geometries. Distribution runs through national group purchasing organizations that displace regional specialty distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service-attach revenue from remote infusion monitoring and patient compliance platforms is expanding faster than hardware unit sales, repositioning manufacturer economics toward recurring-revenue models.
For Market Incumbents: Secure captive supply of medical-grade silicone through backward integration or long-term offtake agreements with precursors suppliers, insulating margins from semiconductor foundry demand cycles. Deepen FDA 21 CFR Part 820 quality system documentation packages to extend EU MDR certification timelines as a competitive moat against Asian entrants lacking notified body relationships.
For New Entrants and Emerging Players: Patient training and compliance monitoring services represent an under-served layer where incumbents prioritize hardware volume over service attachment. Rural home care markets in Texas and Florida offer the most penetrable geography given Medicare reimbursement code expansions for remote infusion services. Pursue white-label partnerships with regional distributors displaced by national group purchasing organization consolidation.
For Investors and Strategic Acquirers: Capital is best deployed toward mid-cap specialists with established ISO 10993-1 biocompatibility testing capabilities and pre-existing European notified body relationships. The five-to-ten year viability window favors targets with differentiated reservoir geometries for chemotherapy precision dosing rather than commodity antibiotic therapy configurations. Monitor FDA biocompatibility revalidation timelines as an inflection signal for incumbent margin pressure and acquisition opportunity windows.
| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Certification Investment | Extended notified body engagement freezes new entrants from German and French hospital procurement cycles. |
| Silicone Precursor Supply Agreement | Long-term offtake contracts with semiconductor-grade silicone suppliers insulate margins from foundry demand volatility. |
| Multi-layer Balloon R&D Program | Co-extrusion technology enables flow-rate precision bands that command premium pricing in oncology tenders. |
| Remote Monitoring Platform Launch | Software companion services capture recurring revenue from Medicare-reimbursed home infusion protocols. |
| Rural Home Care Distribution Partnership | Regional distributor relationships access patient populations beyond urban hospital catchment areas in Texas and Florida. |
Research Approach
Cross-validation between primary interviews with hospital purchasing committees, GPO contracts managers, biomedical engineers, and home care agency operations directors anchors the qualitative findings against secondary validation through FDA 510(k) filings, CMS Medicare reimbursement databases, hospital procurement tender documents, and EU MDR technical documentation packages. Bottom-up triangulation aggregates unit shipment estimates by product configuration and end-use setting, while top-down approaches cross-check against aggregate manufacturer revenue disclosures.
Sensitivity analysis frames the analytical approach across the projection horizon, modeling volume and value outputs through segmentation dimensions spanning product type, application, delivery mode, end user, and regional regulatory cluster. CAGRs derive from logarithmic interpolation of segment-specific growth trajectories, with inputs including ambulatory surgery center discharge protocol adoption curves and Medicare reimbursement code expansion schedules for remote infusion services.
Underlying assumptions cover FDA biocompatibility revalidation timelines and EU MDR notified body capacity constraints, with deviation risk concentrated in medical-grade silicone precursor price volatility and electronic infusion pump substitution rates in hospital segments. Recalibration cycles align with material shifts in CMS reimbursement policy and MDR certification timeline developments.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Wearable Injectors Market
Medical Devices
ECG Telemetry Devices Market
Medical Devices
Intracranial Pressure Monitors Market
Medical Devices
Global Peripheral IV Catheters Market
Medical Devices
Tubeless Insulin Pump Market
Medical Devices
Focused Ultrasound System Market
Medical Devices
Digital Respiratory Devices Market
Medical Devices
Cardiac Rhythm Management (CRM) Devices Batteries Market
Medical Devices
Subcutaneous Drug Delivery Devices Market
Medical Devices
Global Limb Prosthetics Market
Medical Devices
Vascular Guidewires Market
Medical Devices
Japan Artificial Organs and Bionic Implants Market
Medical Devices
Radiofrequency (RF) Ablation System Market
Medical Devices
Cholesterol Management Devices Market
Medical Devices
Middle East and Africa C-Arms Market
Medical Devices
Organ Preservation Market