
 Dosage Unit Sampling Apparatus Market | 2026-2036
Dosage Unit Sampling Apparatus Market Size, Share, and Industry Trends Forecast 2026-2036
Dosage Unit Sampling Apparatus Market Analysis
Automated inline sampling integration with process analytical technology is reshaping how pharmaceutical manufacturers verify dosage uniformity during production rather than relying solely on post-batch testing. Copley Scientific leverages its deep specialization in inhaler and aerosol testing equipment to anchor European demand for precision sampling apparatus. ERWEKA competes through extensive R&D intensity in dissolution and sampling automation, while TSI extends its particle measurement expertise into pharmaceutical air sampling applications.
A dosage unit sampling apparatus is a mechanical or electromechanical device engineered to extract representative aliquots from solid oral dosage forms, typically achieving extraction precision within milligram tolerances to support content uniformity and assay validation per pharmacopeial methods. Its primary commercial purpose is enabling pharmaceutical manufacturers to demonstrate batch compliance with regulatory content uniformity specifications while minimizing analytical variability. Automatic devices command the dominant share of value as manufacturers replace manual throat deposition studies with programmable cascade impactor automation, while powder sampling applications lead volume due to the prevalence of dry powder inhaler development programs. Contract manufacturing organizations represent the fastest-growing end user category as outsourcing of inhaler and nasal spray development accelerates capacity investments at CDMO sites.
FDA content uniformity requirements under USP Chapter 905 and EMA stability testing guidelines under ICH Q1A(R2) collectively mandate rigorous sampling protocols that directly determine apparatus specification thresholds and validation documentation burdens. The EU MDR and REACH chemical safety frameworks further constrain material selection for apparatus wetted components, favoring stainless steel and inert polymer constructions over legacy brass or aluminum designs. Stakeholders must monitor evolving pharmacopeial harmonization between USP, EP and JP methods to anticipate specification drift that could obsolete installed sampling platforms or trigger replacement cycles.
Market Dynamics
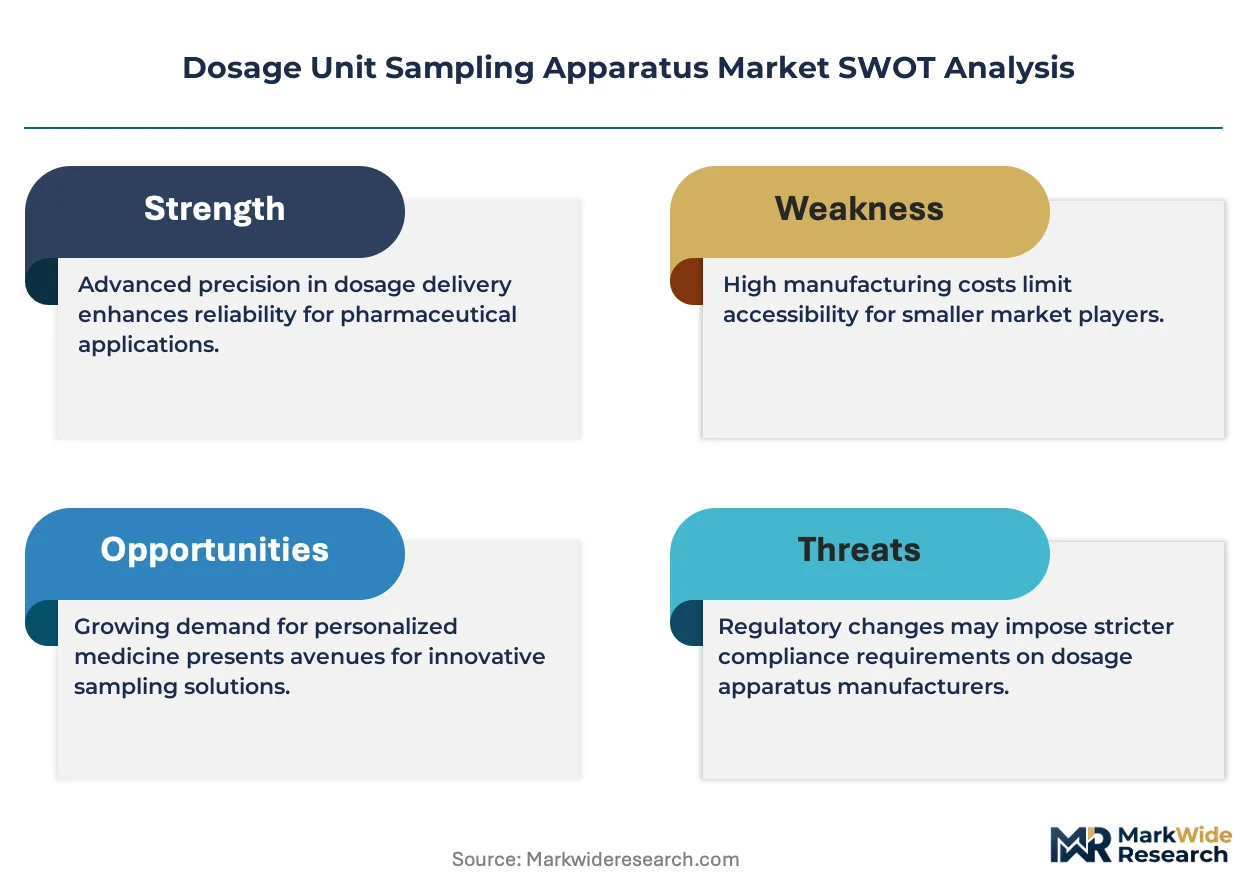
Pharmaceutical manufacturers face intensifying pressure to validate dosage uniformity in real time rather than retrospectively, forcing capital reallocation toward automated inline sampling systems that integrate with process analytical technology platforms.
Growth Catalysts
- FDA USP Chapter 905:Content uniformity mandates now require statistically robust sampling protocols that manual methods cannot reliably deliver, accelerating replacement of legacy throat deposition studies with programmable cascade impactor automation.
- Contract manufacturing organizations:CDMO capacity expansion for inhaler and nasal spray development creates concentrated demand for validated sampling apparatus at outsourced production sites.
- Dry powder inhaler development:Powder sampling applications lead volume as pharmaceutical R&D pipelines prioritize respiratory drug delivery formats requiring precise aliquot extraction.
Market Restraints
- Stainless steel input costs:EU REACH and MDR frameworks mandate inert wetted component materials, exposing manufacturers to commodity price volatility that compresses margin on mid-tier apparatus lines.
- European supplier concentration:Precision machining capabilities for pharmacopeial-grade sampling mechanisms cluster in southern Germany and northern Italy, creating geographic supply vulnerability.
- Technical limitation:Current automated systems struggle with friable tablet formulations and moisture-sensitive APIs, restricting addressable product categories.
Strategic Opportunities
- India CDMO expansion:CDSCO regulatory alignment with ICH standards creates opening for sampling apparatus vendors to capture capacity investments at emerging pharmaceutical manufacturing clusters in Hyderabad and Ahmedabad.
- Continuous manufacturing integration:Real-time release testing architectures require sampling apparatus that interfaces directly with PAT sensors, enabling new system-of-systems revenue models.
- EMA stability testing harmonization:Convergence between EMA ICH Q1A(R2) and FDA guidelines reduces validation documentation burden for apparatus qualified across both jurisdictions.
Industry Challenges
- Validation engineer scarcity:Pharmaceutical manufacturers report acute shortage of personnel capable of executing IQ/OQ/PQ protocols for automated sampling platforms, extending deployment timelines.
- Legacy LIMS integration:Sampling apparatus must interface with decade-old laboratory information management systems, requiring custom middleware development that inflates total cost of ownership.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dosage Unit Sampling Apparatus Market |
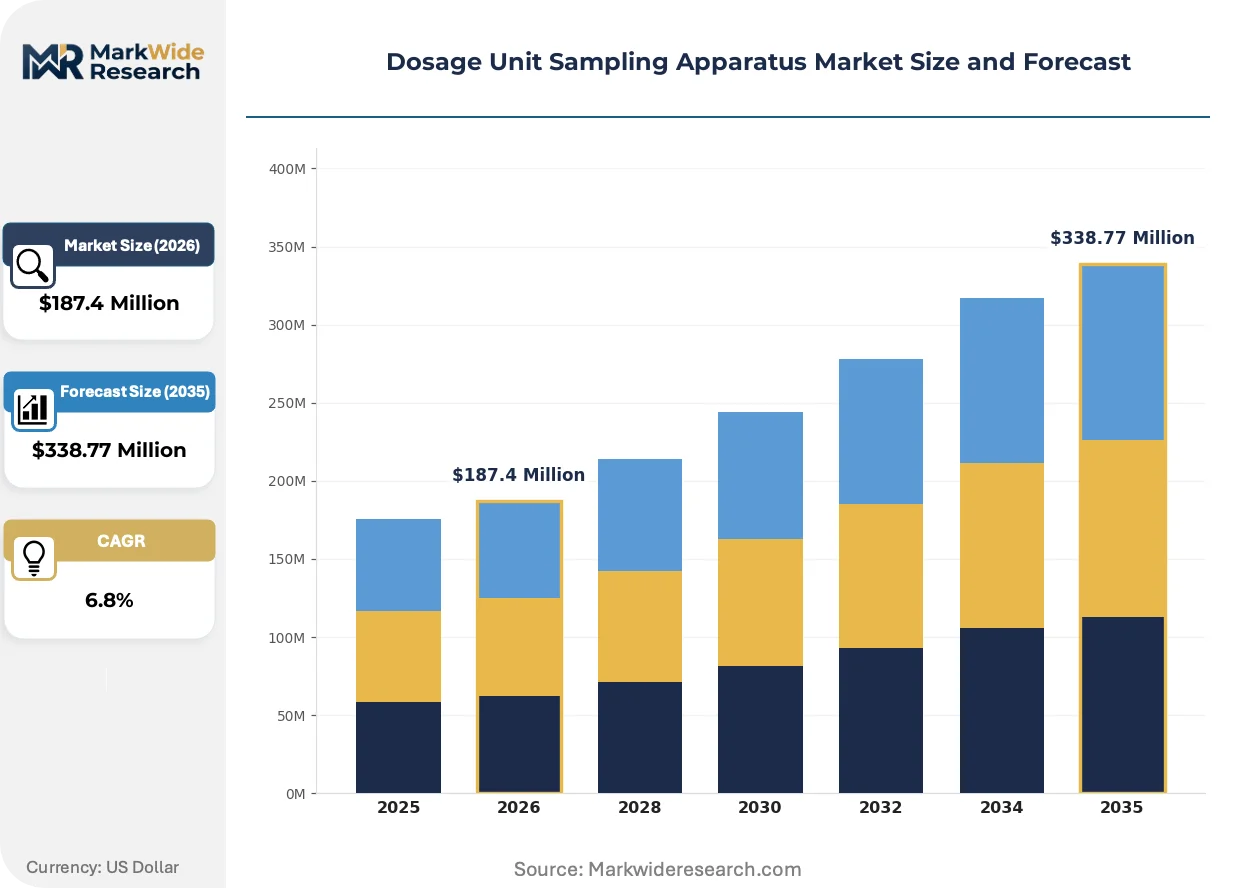
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual Devices, Automatic Devices, Semi-Automatic Devices, Portable Units End User: Pharmaceutical Companies, Research Laboratories, Quality Control Departments, Contract Manufacturing Organizations Capacity: Small Scale, Medium Scale, Large Scale, Custom Capacity Application: Liquid Sampling, Powder Sampling, Granular Sampling, Others |
| Companies Covered | Copley Scientific, 3M, ERWEKA, Analytical Technologies, Westech Scientific Instruments, TSI, Nuova Tecnogalenica, Analytical Technologies AGOC, Proveris Scientific, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dosage Unit Sampling Apparatus Market Emerging Trajectories
Inline sampling architectures are displacing offline batch testing as the default quality verification mode, compressing analytical cycle times from hours to minutes while raising apparatus specification thresholds.
Micro-dosing precision mechanisms is migrating from laboratory-scale developmental equipment toward production-line deployment. Large molecule formulation groups at biopharmaceutical manufacturers are adopting these systems to support low-dose high-potency tablet programs. The technology is migrating from analytical service laboratories into manufacturing suites, collapsing the organizational boundary between QC and production functions.
EMA's evolving interpretation of ICH Q14 analytical procedure development guidelines now explicitly recognizes process analytical technology as a primary validation pathway. This regulatory accommodation reduces the documentation burden for manufacturers deploying automated sampling with embedded spectroscopic detection. European respiratory drug specialists are responding by requalifying legacy apparatus ahead of formal guideline adoption.
CDMO procurement committees now unbundle capital equipment acquisition from multi-year service contracts, forcing apparatus vendors to compete on hardware margin alone. This pattern concentrates in Germany and Switzerland where contract manufacturing for inhaler products has scaled most aggressively. Established suppliers are responding with modular platform architectures that permit incremental capability expansion without full system replacement.
Dosage Unit Sampling Apparatus Market Segmentation
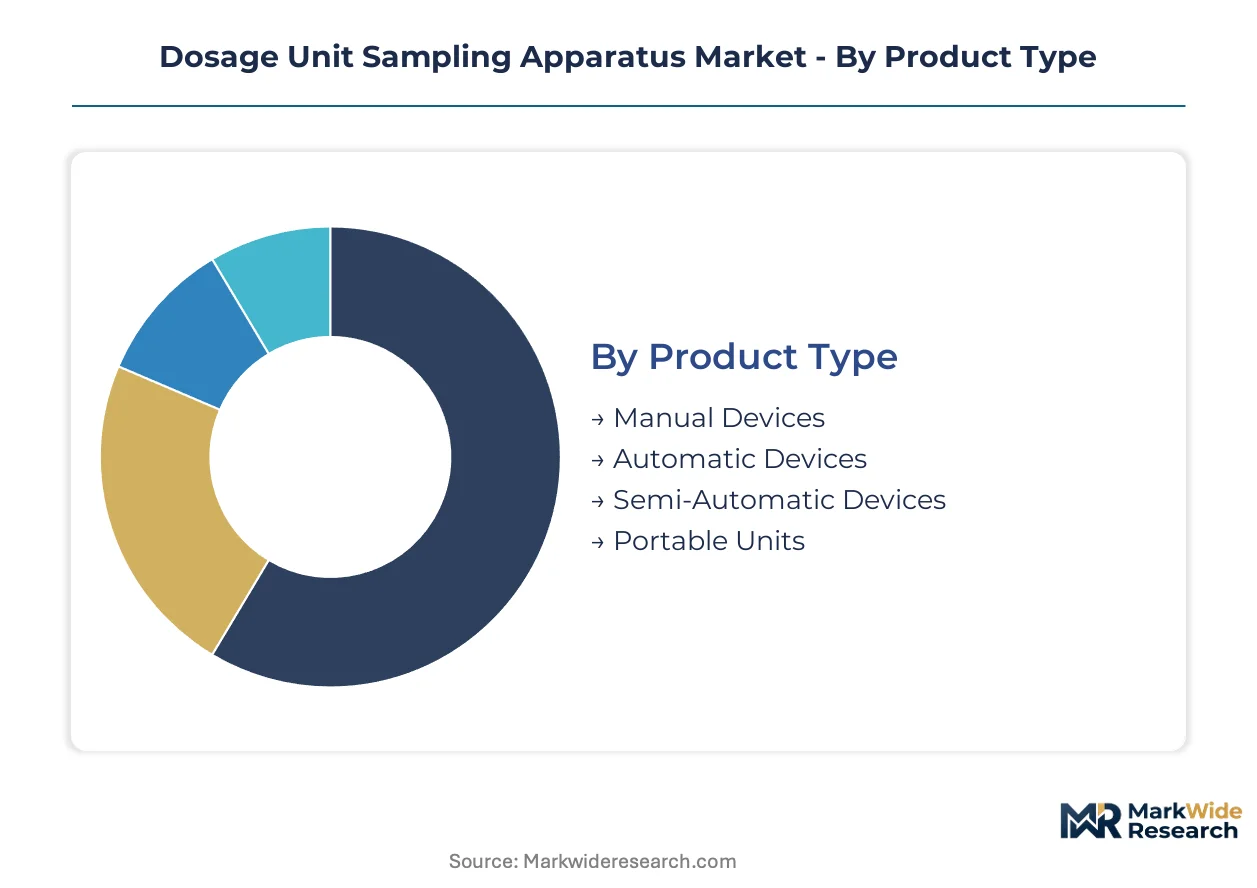
Segmentation in the dosage unit sampling apparatus market reveals how regulatory complexity and manufacturing scale reshape procurement priorities. Equipment specifications diverge sharply between high-volume oral solid dose facilities and specialized inhaler development sites.
Product Type:
Mature automation platforms dominate capital allocation while portable and semi-automatic formats occupy emerging niches requiring flexible deployment.
- Automatic Devices:Programmable cascade impactor systems integrate with process analytical technology for real-time content uniformity verification. Pharmaceutical manufacturers in Germany and the United States prioritize these configurations to satisfy FDA USP Chapter 905 statistical sampling requirements.
- Manual Devices:Basic mechanical extractors serve validation laboratories and educational institutions with limited throughput demands. Demand concentrates in India and Eastern Europe where CDMOs maintain legacy equipment for cost-sensitive generic tablet programs.
- Semi-Automatic Devices:Hybrid configurations bridge offline and inline workflows for mid-scale facilities transitioning toward full automation.
- Portable Units:Battery-powered field samplers enable at-line testing during technology transfer campaigns and contract manufacturing site qualifications.
Automatic devices retain volume leadership; portable units hold the steepest expansion curve.
End User:
Customer type determines specification intensity, with outsourcing economics reshaping purchasing authority across the value chain.
- Contract Manufacturing Organizations:CDMO procurement committees unbundle hardware from service contracts, forcing apparatus vendors to compete on equipment margin alone. Capacity investments at Hyderabad and Ahmedabad clusters accelerate demand for validated sampling platforms.
- Pharmaceutical Companies:Large molecule formulation groups adopt micro-dosing precision mechanisms for low-dose high-potency tablet programs. Internal manufacturing suites in Switzerland and Massachusetts lead integration with continuous manufacturing architectures.
- Quality Control Departments:Analytical service laboratories validate apparatus per pharmacopeial methods before deployment to production environments.
- Research Laboratories:Development-scale facilities prioritize modularity for rapid reconfiguration across inhaler, nasal spray, and conventional solid dose programs.
Pharmaceutical companies retain volume leadership; contract manufacturing organizations are expanding most quickly.
Capacity:
Scale tiering reflects batch size economics and regulatory filing strategies rather than simple throughput metrics.
- Large Scale:High-throughput systems process thousands of dosage units per hour for blockbuster oral solid dose products. Facilities in Germany and the United States deploy these configurations to support FDA and EMA stability testing protocols.
- Custom Capacity:Engineered-to-order platforms address specialized respiratory delivery formats requiring non-standard aliquot volumes. Dry powder inhaler specialists in Switzerland specify these systems for moisture-sensitive API handling.
- Medium Scale:Standardized platforms serve commercial batches for niche therapeutic categories and regional market supply.
- Small Scale:Benchtop units support formulation development and clinical trial material production with minimal validation documentation.
Large scale configurations retain volume leadership; custom capacity holds the steepest expansion trajectory.
Application:
Material state dictates extraction mechanism design, with respiratory delivery formats driving the most specialized engineering requirements.
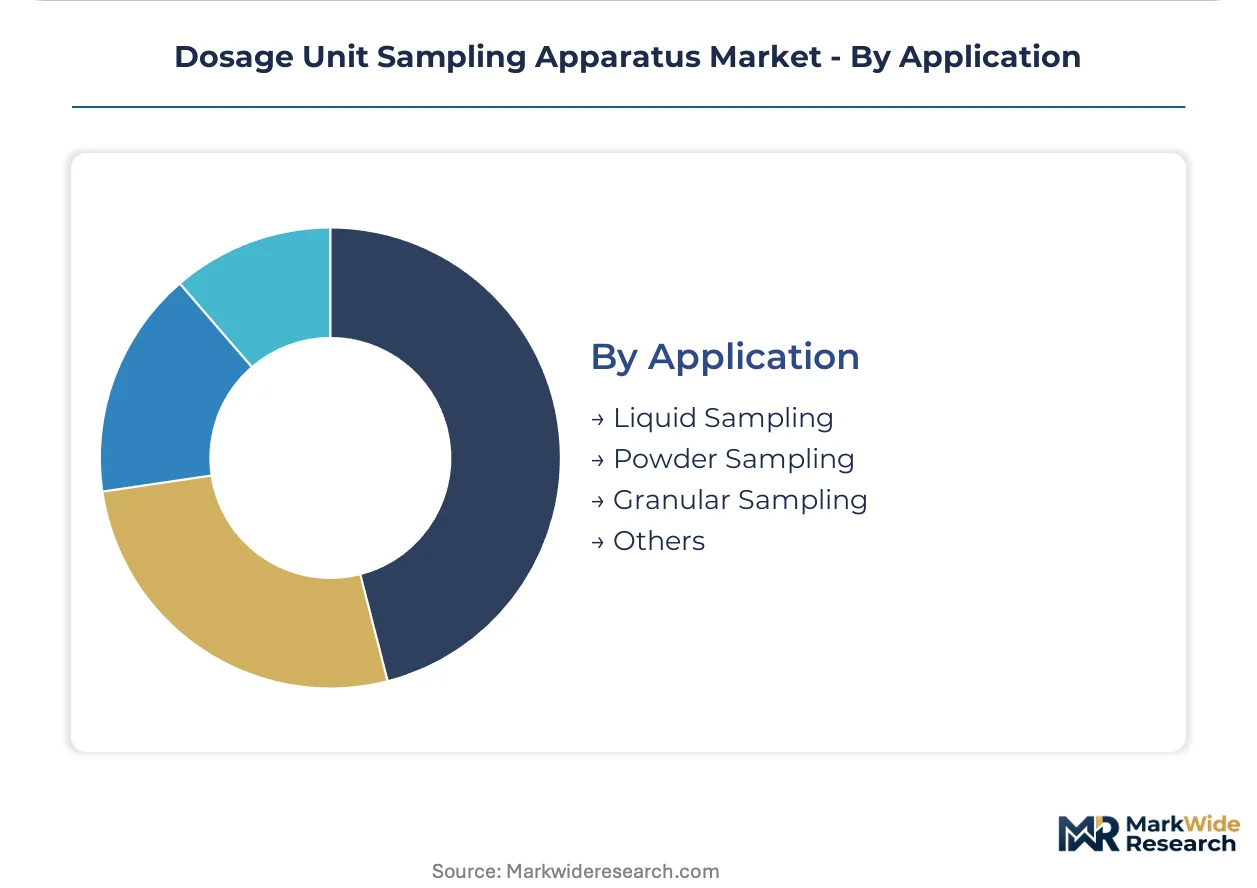
- Powder Sampling:Precision aliquot extraction systems handle cohesive and free-flowing powders for dry powder inhaler development. R&D pipelines in the United Kingdom and Denmark prioritize these applications as respiratory drug delivery expands.
- Liquid Sampling:Automated pipetting modules support oral solution and suspension content uniformity testing. Quality control departments in Japan deploy these for high-viscosity pediatric formulations.
- Granular Sampling:Rotary dividers and riffle splitters process intermediate granulations prior to tablet compression.
- Others:Specialized configurations address semisolid dosage forms, lyophilized cakes, and novel drug-device combination products.
Powder sampling retains volume leadership; liquid sampling gains share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German precision engineering firms export dosage unit sampling apparatus to pharmaceutical manufacturers across the United States, Switzerland, and India, establishing a dominant trade corridor in high-specification equipment.
United States
FDA enforcement of USP Chapter 905 content uniformity mandates drives pharmaceutical manufacturers toward automated cascade impactor systems. The agency's Office of Pharmaceutical Quality tightened statistical sampling requirements for abbreviated new drug applications in 2023. Massachusetts and North Carolina manufacturing clusters deploy these platforms for real-time release testing in continuous manufacturing suites.
Germany
EMA stability testing guidelines under ICH Q1A(R2) converge with FDA protocols, reducing dual-validation burdens for apparatus qualified across jurisdictions. The EU MDR framework mandates stainless steel wetted components for respiratory device testing equipment. Southern German machining centers in Baden-Württemberg and Bavaria concentrate pharmacopeial-grade mechanism production for European CDMO networks.
Switzerland
Swissmedic alignment with ICH Q14 analytical procedure development guidelines accelerates process analytical technology adoption for biopharmaceutical tablet programs. Large molecule formulation groups in Basel and Zürich specify micro-dosing precision mechanisms for low-dose high-potency applications. Contract manufacturing sites along the Rhine corridor requalify legacy apparatus ahead of formal guideline implementation.
India
CDSCO regulatory harmonization with ICH standards creates procurement openings at emerging pharmaceutical manufacturing clusters. The country's national pharmaceutical regulator accelerated stability testing protocol alignment with USP and EP methods during 2022-2024. Hyderabad and Ahmedabad CDMOs expand validated sampling platform capacity to capture outsourced inhaler development contracts from European sponsors.
United Kingdom
MHRA post-Brexit regulatory continuity maintains EP pharmacopeial method recognition for dosage uniformity verification. Respiratory drug delivery R&D pipelines in Cambridge and Oxford prioritize powder sampling systems for dry powder inhaler development programs. Analytical service laboratories in the Southeast validate apparatus per harmonized USP-EP-JP specifications before technology transfer to manufacturing sites.
Dosage Unit Sampling Apparatus Market Vendor Landscape
On the supply side, the industry is moderately consolidated around specialized precision engineering firms with deep pharmacopeial method expertise. Three strategic archetypes dominate: European inhaler testing specialists, dissolution automation engineers, and particle measurement technology extenders. Competitive moves concentrate on modular platform architectures that permit incremental capability expansion, and strategic partnerships with CDMO procurement committees to secure multi-year service contract attachments.
Within the European specialist tier, Copley Scientific and ERWEKA occupy positions defined by respiratory and dissolution application focus respectively. TSI anchors the particle measurement extension archetype, migrating air sampling expertise into pharmaceutical quality control applications. These three firms exemplify how geographic concentration in southern Germany and northern Italy couples with regulatory intimacy to sustain premium positioning against emerging Asian competitors.
| Leading Market Players |
|---|
| Copley Scientific |
| 3M |
| ERWEKA |
| Analytical Technologies |
| Westech Scientific Instruments |
| TSI |
| Nuova Tecnogalenica |
| Analytical Technologies AGOC |
| Proveris Scientific |
| Others |
Supply Flow & Price Mechanics
The Rotterdam-Antwerp pharmaceutical logistics corridor channels precision-machined sampling components from southern Germany to CDMO sites across the Netherlands and Belgium, with freight cost volatility amplifying margin compression on mid-tier apparatus lines while reinforcing price premiums for pharmacopeial-grade stainless steel systems.
Pricing Analysis
Current-generation programmable cascade impactor systems command substantial premiums over prior-generation manual extractors and next-generation PAT-integrated architectures still in validation phases. Three-tier pricing structure across premium, standard, and economy levels reflects FDA certification tier and volume scale, with CDMO procurement committees in India exhibiting highest price sensitivity and Swiss biopharmaceutical manufacturers showing lowest. Cost compression in standard-tier lines is intensifying because stainless steel input volatility under EU REACH frameworks squeezes mid-market vendors.
Supply Chain Analysis
Export-control restrictions on precision machining software and high-tolerance measurement equipment limit technology transfer to emerging Asian manufacturers, preserving southern Germany and northern Italy as dominant supply nodes. Pharmacopeial-grade mechanism production draws from specialized stainless steel foundries in Baden-Württemberg, Bavaria, and Lombardy, with component sourcing tethered to nickel alloy and inert polymer feedstocks. Single-source vulnerability concentrates in Baden-Württemberg machining centers, while distribution runs through authorized European distributors serving CDMO networks directly.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The dosage unit sampling apparatus market is entering a cyclical recovery phase as CDMO capacity investments rebound following post-pandemic normalization, with respiratory drug outsourcing serving as the named cyclical driver accelerating replacement demand.
For Market Incumbents: Harden defensive positions by deepening backward integration into stainless steel component machining to offset REACH-mandated material cost volatility, while accelerating CE marking and FDA dual-qualification investments to capture EMA-FDA harmonization benefits. Threats from emerging Asian competitors with CDSCO-aligned platforms demand preemptive channel control at Hyderabad and Ahmedabad CDMO clusters. For New Entrants and Emerging Players: Establish a beachhead in portable battery-powered field samplers for technology transfer campaigns, where incumbents maintain limited presence and price elasticity permits competitive entry. White-space targets include liquid sampling modules for high-viscosity pediatric formulations in Japan and modular platforms enabling incremental capability expansion without full system replacement. A service-first go-to-market angle bundling IQ/OQ/PQ validation support addresses acute validation engineer scarcity. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial measurement parent companies with undermonetized pharmaceutical air sampling divisions, where respiratory application specialization could unlock premium positioning. Long-term viability centers on continuous manufacturing integration and PAT sensor interfacing capabilities, with the signal to watch being EMA formal adoption of ICH Q14 PAT recognition guidelines as inflection indicator for platform replacement cycles.| Strategic Initiative | Industry Significance |
|---|---|
| PAT Sensor Integration Partnership | Enables real-time release testing architectures demanded by FDA Office of Pharmaceutical Quality guidance. |
| Modular Platform Architecture Launch | Permits CDMOs to expand capabilities incrementally without full system replacement amid unbundled procurement. |
| CDSCO-Aligned Validation Package | Captures capacity investments at Hyderabad and Ahmedabad clusters as Indian regulatory harmonization accelerates. |
| Stainless Steel Backward Integration | Secures inert wetted component supply against EU REACH commodity price volatility compressing mid-tier margins. |
| Micro-Dosing Precision Mechanism Development | Addresses biopharmaceutical low-dose high-potency tablet programs in Basel and Zürich formulation suites. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted across pharmaceutical quality control departments, CDMO procurement committees, validation engineering teams, and precision machining equipment specialists. Secondary validation incorporated FDA guidance documents, EMA ICH Q1A(R2) stability testing protocols, USP Chapter 905 content uniformity standards, and CDSCO regulatory harmonization circulars. Bottom-up apparatus shipment data triangulated against top-down pharmaceutical capital expenditure disclosures across the analysis window.
Calibration anchored volume and value outputs to installed base depreciation cycles, regulatory filing timelines, and CDMO capacity expansion announcements. Segmentation dimensions modeled encompassed product automation tier, end-user category, application material state, and regional regulatory cluster. CAGRs were derived from slope analysis of historical replacement rates projected against pharmacopeial harmonization milestones and continuous manufacturing adoption curves, with forecast inputs including dry powder inhaler pipeline density and ICH Q14 guideline implementation velocity.
Macroeconomic conditions sit as an overlay; deviation in stainless steel commodity indices, pharmaceutical R&D funding flows, or CDMO outsourcing contract velocity would shift the trajectory. Material shifts in FDA-EMA pharmacopeial method divergence or REACH chemical safety framework expansion would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Bone Power Tools Market
Medical Devices
Pipette Controllers Market
Medical Devices
Reusable Medical Battery Market
Medical Devices
Endodontic Devices Market
Medical Devices
Chile Ultrasound Devices Market
Medical Devices
South Africa General Surgical Devices Market
Medical Devices
Global Transradial Access Market
Medical Devices
Global Extremities Market
Medical Devices
Pulmonology Lasers Market
Medical Devices
Batteries for Skin Patches Market
Medical Devices
Global Robotic Flight Simulator Surgery Market
Medical Devices
North America Biopsy Devices Market
Medical Devices
Asia-Pacific Digital Dentistry Market
Medical Devices
Contraceptive Rings Market
Medical Devices
Endoprosthesis Market
Medical Devices
Wearable Bioelectronic Skin Patches Market