
 Vietnam Insulin Infusion Pump Market | 2026-2036
Vietnam Insulin Infusion Pump Market Size, Share, and Industry Trends Forecast 2026-2036
Vietnam Insulin Infusion Pump Market Insights
Hospital procurement networks is reconfiguring around integrated diabetes technology bundles rather than standalone pump sales. Medtronic Viet Nam Ltd. leverages its established clinical training infrastructure to sustain recurring revenue from consumable sales. Roche Vietnam Co. Ltd competes through diagnostic-to-therapy workflow integration, while Getz Healthcare (Vietnam) anchors its position in provincial hospital tenders where price sensitivity dominates purchasing decisions.
An insulin infusion pump is a programmable electromechanical device that delivers rapid-acting insulin through a subcutaneous catheter at calibrated basal rates and patient-triggered bolus doses, typically with delivery precision of 0.025 to 25 units per hour depending on the model. Its primary purpose is to replace multiple daily injection regimens with continuous subcutaneous insulin infusion, thereby reducing glycemic variability and enabling tighter hemoglobin A1c control for insulin-dependent patients. Basal Insulin Pumps and Hybrid Closed-Loop Systems capture the deepest margin pools as hospitals prioritize automated glucose-responsive delivery over manual programming, while Home Care as an end-user segment expands fastest among urban middle-income households seeking to avoid frequent clinic visits. Continuous Glucose Monitoring as a technology layer increasingly determines pump selection, with devices lacking real-time sensor integration facing relegation to price-tier tenders.
Vietnam's Ministry of Health and the national pharmaceutical regulator govern medical device registration through circulars aligned with ASEAN Medical Device Directive harmonization, creating compliance barriers for uncertified imports while accelerating pathways for manufacturers with established ASEAN Common Submission Dossiers. The country's national health insurance agency shapes demand through reimbursement eligibility lists that currently cover conventional pumps but exclude premium hybrid closed-loop systems, pressuring manufacturers to demonstrate cost-effectiveness against pen-based therapy. Stakeholders must monitor whether the Ministry of Health expands reimbursement to sensor-augmented pump therapy before private out-of-pocket spending saturates the addressable urban population.
Market Dynamics
Hospital procurement networks in Vietnam are reconfiguring around integrated diabetes technology bundles rather than standalone pump sales, as the Ministry of Health tightens medical device registration pathways aligned with ASEAN Medical Device Directive harmonization.
Growth Catalysts
- ASEAN Common Submission Dossiers:Manufacturers with established dossiers gain accelerated registration pathways through Vietnam's national pharmaceutical regulator, compressing time-to-market for new entrants.
- Continuous Glucose Monitoring integration:Endocrinology infrastructure in Ho Chi Minh City and Hanoi is deepening adoption of sensor-augmented pump systems as standard-of-care protocols.
- Urban middle-income households:Home Care as an end-user segment is expanding fastest among these households seeking to avoid frequent clinic visits and reduce glycemic variability.
Market Restraints
- Reimbursement exclusion of hybrid closed-loop systems:Vietnam's national health insurance agency currently covers conventional pumps but excludes premium automated systems, pressuring manufacturers to demonstrate cost-effectiveness against pen-based therapy.
- Provincial hospital price sensitivity:Tender decisions outside Hanoi and Ho Chi Minh City favor lower-cost alternatives, fragmenting demand concentration and compressing margin pools.
- Consumable dependency:Recurring revenue from infusion sets and reservoirs locks patients into specific vendor ecosystems, creating switching friction that slows competitive churn.
Strategic Opportunities
- Provincial expansion:Underpenetrated secondary cities in the Mekong Delta and Central Highlands present whitespace for diagnostic-to-therapy workflow integration.
- Sensor-augmented pump reimbursement expansion:Stakeholders must monitor whether the Ministry of Health extends national health insurance eligibility to real-time sensor-integrated devices before private out-of-pocket spending saturates the addressable urban population.
- Telemedicine convergence:Remote glucose data transmission and algorithm-driven insulin adjustment are creating new service revenue streams for diabetes management centers.
Industry Challenges
- Clinical training infrastructure gaps:Certified diabetes educators capable of programming hybrid closed-loop systems remain concentrated in tertiary hospitals, limiting deployment to provincial facilities.
- Registration compliance timelines:Circulars governing medical device imports create documentation barriers for uncertified manufacturers, extending market entry cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vietnam Insulin Infusion Pump Market |
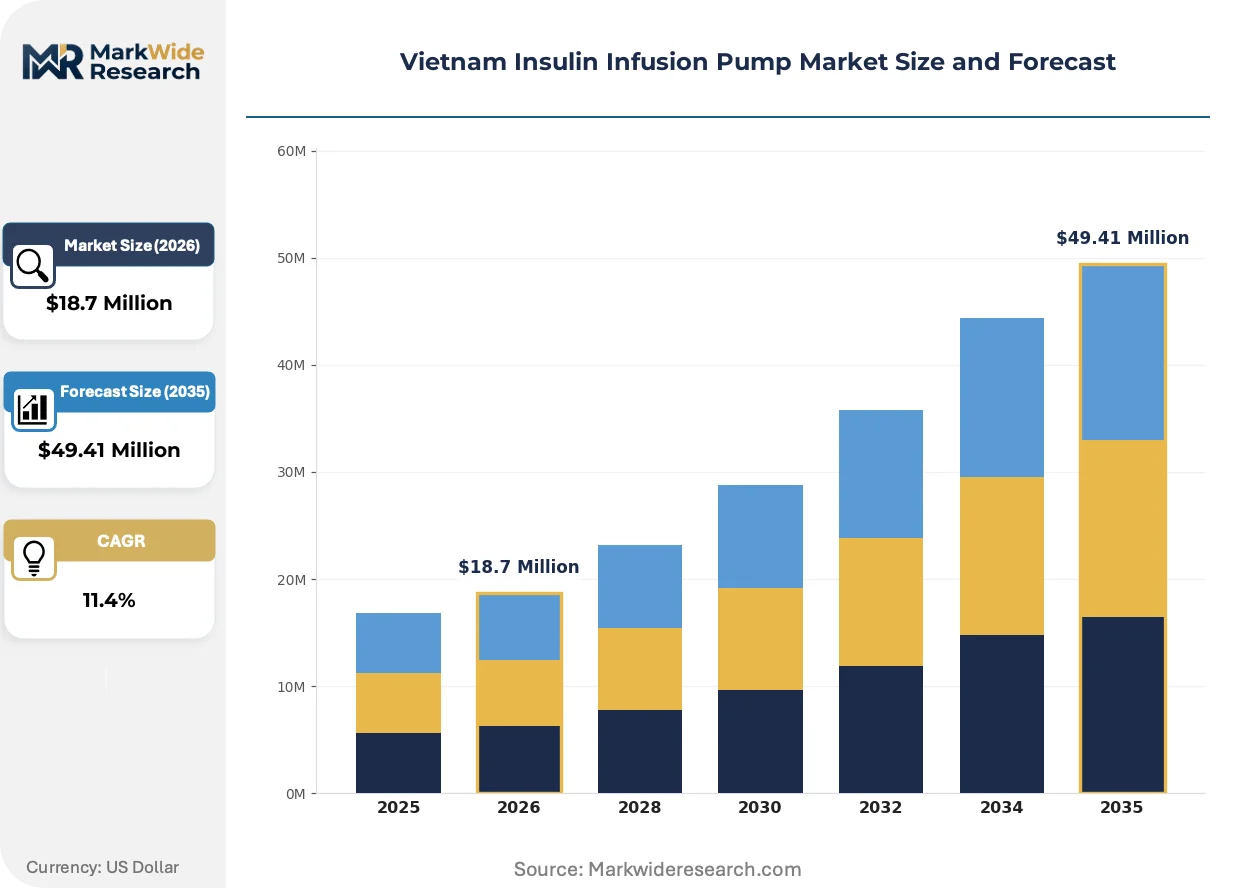
| Market Size in 2026 | $18.7 Million |
| Market Size in 2035 | $49.41 Million |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Basal Insulin Pumps, Bolus Insulin Pumps, Hybrid Closed-Loop Systems, Traditional Insulin Pumps End User: Hospitals, Home Care, Clinics, Diabetes Management Centers Technology: Insulin Delivery Systems, Continuous Glucose Monitoring, Mobile Applications, Remote Monitoring Solutions Application: Type 1 Diabetes, Type 2 Diabetes, Pediatric Care, Pregnancy Management |
| Companies Covered | Ascensia Diabetes Care, Medtronic Viet Nam Ltd., Medtronic, Terumo Vietnam Co., Ltd., Roche Vietnam Co. Ltd, Insulet Corporation, Tandem Diabetes Care, Getz Healthcare (Vietnam), Ypsomed, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vietnam Insulin Infusion Pump Market Trends and Innovations
Software-defined insulin delivery architectures are displacing hardware-centric pump designs across Vietnam's diabetes management infrastructure, compressing product lifecycles and shifting value capture toward algorithm licensing.
Cloud-connected pump ecosystems are virtualizing the traditional patient-clinic relationship by enabling real-time glucose data streaming and remote dose adjustment. Urban diabetes management centers in Hanoi are adopting these platforms fastest, consolidating patient monitoring into centralized command structures that reduce face-to-face consultation requirements.
Vietnam's Ministry of Health circulars aligned with ASEAN Medical Device Directive harmonization are elevating compliance barriers for uncertified imports while accelerating pathways for manufacturers with established regional dossiers. This regulatory reconfiguration favors incumbent suppliers with existing clinical training infrastructure and compresses market access for new entrants lacking ASEAN regulatory history.
Subscription-based consumable bundling is displacing transactional pump sales in private diabetes management centers. Ho Chi Minh City endocrinology clinics are pioneering all-inclusive monthly fees covering device, sensors, and remote monitoring, shifting buyer preference from capital expenditure toward operational expenditure models that align provider incentives with patient outcome continuity.
Vietnam Insulin Infusion Pump Market Segmentation
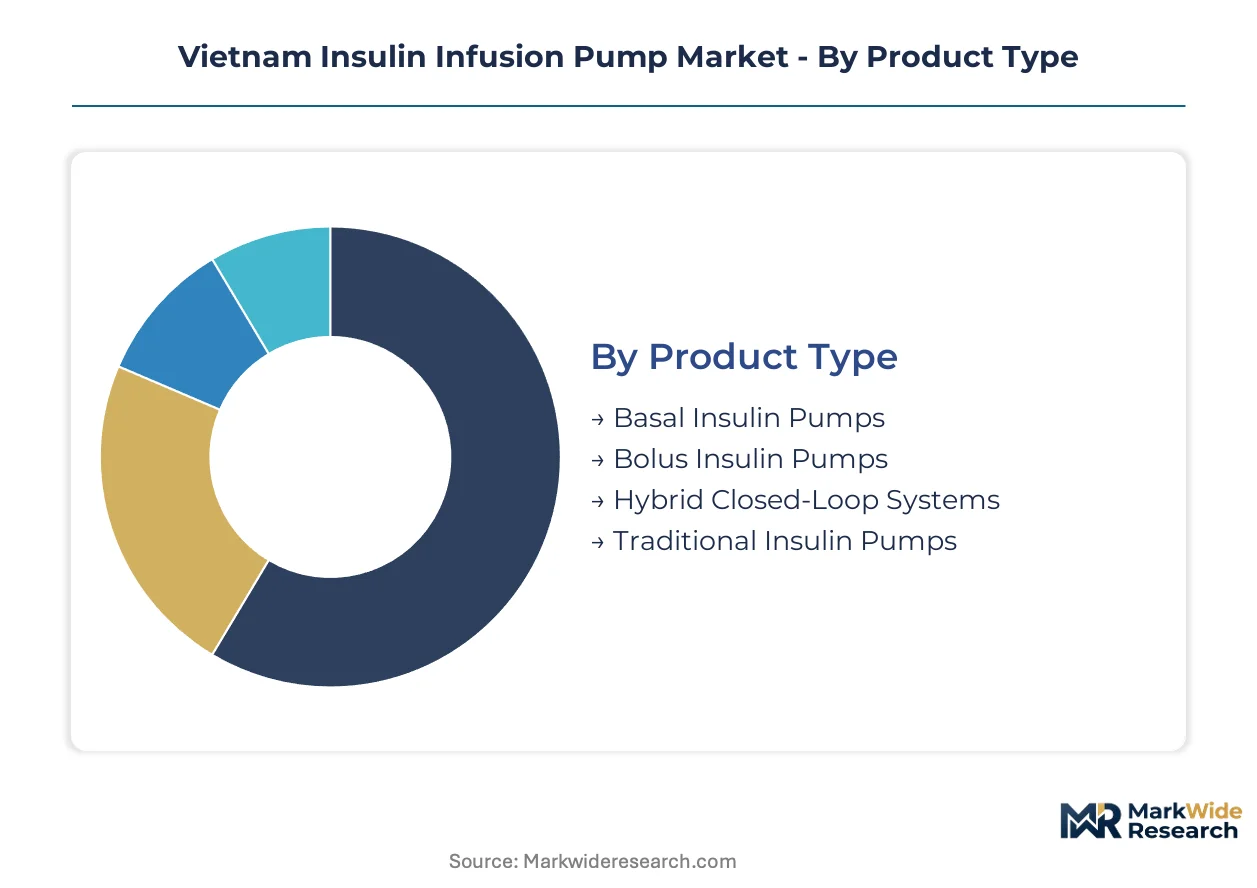
Device configuration and care setting fundamentally determine procurement pathways and margin structures in Vietnam's insulin infusion pump landscape. Each segmentation dimension reveals distinct competitive dynamics between tertiary hospital networks and emerging home-based diabetes management.
Product Type:
Cost tier differentiation separates devices by automation sophistication and consumable dependency, creating divergent reimbursement eligibility and patient out-of-pocket exposure.
- Basal Insulin Pumps:Programmable devices deliver background insulin at preset rates through subcutaneous infusion sets with 0.025-unit precision. Hanoi and Ho Chi Minh City endocrinology departments prioritize these systems for established Type 1 patients, though national health insurance coverage limits feature expansion. Basal Insulin Pumps command the established base. The steepest expansion runs through Hybrid Closed-Loop Systems.
- Hybrid Closed-Loop Systems:Automated glucose-responsive architectures integrate real-time sensor data with algorithm-driven basal adjustment, reducing manual intervention. Private diabetes management centers in urban corridors drive adoption despite exclusion from national reimbursement lists, pressuring manufacturers toward outcome-based contracting. These systems capture premium pricing through consumable bundling and remote monitoring subscriptions.
- Bolus Insulin Pumps:Patient-triggered delivery devices focus on mealtime correction doses without continuous basal automation.
- Traditional Insulin Pumps:First-generation programmable units lacking sensor integration dominate provincial hospital tenders where procurement budgets constrain technology selection.
Basal Insulin Pumps command the established base. The steepest expansion runs through Hybrid Closed-Loop Systems.
End User:
Application setting determines device complexity requirements, training infrastructure needs, and revenue model structure across Vietnam's diabetes care continuum.
- Hospitals:Tertiary facilities in Hanoi and Ho Chi Minh City anchor procurement volume through integrated diabetes technology bundles that pair pumps with continuous glucose monitoring infrastructure. Ministry of Health registration compliance and clinical educator certification requirements concentrate advanced system deployment at this tier.
- Home Care:Urban middle-income households in Vietnam's major metropolitan areas drive the fastest adoption trajectory as patients seek to reduce clinic visit frequency and achieve tighter glycemic control through self-management. Subscription-based consumable models are displacing capital expenditure approaches in this segment.
- Clinics:Private endocrinology practices serve as technology demonstration sites before hospital procurement decisions.
- Diabetes Management Centers:Specialized facilities pioneer telemedicine convergence with remote glucose data transmission capabilities.
Hospitals anchor current procurement volume. Home Care is climbing the fastest as urban households shift toward operational expenditure models.
Technology:
Customer type segmentation reveals how software-defined architectures are displacing hardware-centric value capture across device ecosystems.
- Continuous Glucose Monitoring:Real-time interstitial glucose sensing with predictive alerting capabilities increasingly determines pump selection criteria. Sensor-augmented therapy is becoming standard-of-care in Ho Chi Minh City endocrinology protocols, with devices lacking integration facing relegation to price-tier tenders.
- Remote Monitoring Solutions:Cloud-connected platforms enable centralized patient command structures that reduce face-to-face consultation requirements. Hanoi diabetes management centers are adopting these systems fastest, creating new service revenue streams through algorithm-driven dose adjustment.
- Insulin Delivery Systems:Core electromechanical pumping mechanisms with programmable basal-bolus functionality.
- Mobile Applications:Smartphone interfaces for dose logging, carbohydrate counting, and data visualization.
Continuous Glucose Monitoring dominates technology investment priorities. Remote Monitoring Solutions are gaining share fastest through telemedicine convergence.
Application:
Volume concentration varies sharply by patient population complexity and clinical outcome sensitivity, shaping device feature requirements and prescriber specialization.
- Type 1 Diabetes:Absolute insulin deficiency mandates continuous subcutaneous infusion for glycemic survival, creating the deepest addressable need. Vietnamese pediatric and adult endocrinology infrastructure concentrates advanced pump deployment for this population, though reimbursement gaps limit penetration.
- Pediatric Care:Smaller insulin requirements and caregiver oversight needs drive demand for precision dosing and remote monitoring capabilities. Family willingness to pay out-of-pocket for hybrid closed-loop systems runs highest in this segment due to hypoglycemia anxiety.
- Type 2 Diabetes:Progressive beta-cell failure creates emerging pump candidacy as oral agents lose efficacy.
- Pregnancy Management:Tight glycemic targets during gestation create specialized temporary pump use cases.
Type 1 Diabetes anchors the clinical indication base. Pediatric Care shows the steepest trajectory as caregiver-driven technology investment outpaces other segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Vietnam's Ministry of Health reimbursement policies and provincial hospital procurement frameworks are concentrating insulin infusion pump adoption in metropolitan corridors while leaving secondary markets underpenetrated. The national pharmaceutical regulator's ASEAN Medical Device Directive alignment creates divergent market access timelines across sub-regions.
Ho Chi Minh City
Private diabetes management centers and tertiary hospital networks drive demand for hybrid closed-loop systems despite national health insurance exclusion. The city's endocrinology infrastructure anchors clinical training programs that propagate advanced pump programming southward. Sensor-augmented therapy adoption concentrates in District 1 and District 7 medical corridors where out-of-pocket spending capacity runs highest.
Hanoi
National hospital procurement decisions originating in the capital prioritize integrated diabetes technology bundles over standalone devices. Bach Mai Hospital and Viet Duc Hospital serve as reference sites that shape provincial tender specifications. Cloud-connected remote monitoring platforms are penetrating fastest here, enabling centralized patient command structures that reduce consultation frequency.
Mekong Delta
Provincial hospital price sensitivity fragments demand toward traditional insulin pumps lacking continuous glucose monitoring integration. Can Tho City represents the southern anchor where diagnostic-to-therapy workflow integration is emerging slowly. Tender decisions in An Giang and Dong Thap provinces favor lower-cost alternatives that compress manufacturer margin pools.
Central Highlands
Da Lat and Buon Ma Thuot host nascent endocrinology infrastructure with limited certified diabetes educator availability. The Ministry of Health's clinical training gaps constrain hybrid closed-loop deployment to occasional patient referrals northward. Underpenetration creates whitespace for consumable bundling models if provincial reimbursement pathways expand.
Vietnam Insulin Infusion Pump Market Competitive Landscape
On the supply side, the industry is tiered between multinational device manufacturers with established ASEAN regulatory dossiers and regional distributors competing on provincial tender participation. Two strategic archetypes dominate: integrated diabetes technology platforms that bundle pumps with continuous glucose monitoring ecosystems, and distribution-focused entities that anchor provincial hospital procurement networks. Competitive moves center on consumable subscription bundling and clinical training infrastructure expansion rather than device price competition alone.
Among Vietnam-based distribution specialists, Getz Healthcare (Vietnam) occupies a position anchoring provincial tender participation where price sensitivity dictates purchasing outcomes. Medtronic Viet Nam Ltd. and Roche Vietnam Co. Ltd exemplify the integrated platform archetype, leveraging established clinical training infrastructure and diagnostic-to-therapy workflow integration respectively. These entities represent contrasting approaches to market access—one through geographic breadth in secondary cities, the other through vertical capability stacking in metropolitan corridors.
| Leading Market Players |
|---|
| Ascensia Diabetes Care |
| Medtronic Viet Nam Ltd. |
| Medtronic |
| Terumo Vietnam Co., Ltd. |
| Roche Vietnam Co. Ltd |
| Insulet Corporation |
| Tandem Diabetes Care |
| Getz Healthcare (Vietnam) |
| Ypsomed |
| Others |
Pricing and Supply Chain Analysis
Ho Chi Minh City's concentration of private diabetes management centers creates asymmetric pricing power for consumable-integrated platforms, while provincial hospital procurement networks in the Mekong Delta fragment demand toward lower-cost alternatives. This geographic bifurcation compresses margins in secondary cities while sustaining premium capture in metropolitan corridors.
Pricing Analysis
Certification level (ISO 13485/CE/FDA-grade) creates the primary spread between premium hybrid closed-loop systems and economy-tier traditional pumps. Three-tier pricing structure across premium, standard, and economy levels dominates procurement, with sensor-augmented bundles commanding subscription-based operational expenditure models. Cost compression in provincial tenders is intensifying because national health insurance excludes automated glucose-responsive devices. Provincial hospital purchasing committees exhibit highest price sensitivity, while pediatric caregivers in urban private centers show lowest sensitivity due to hypoglycemia anxiety.
Supply Chain Analysis
Export-control regimes on semiconductor components and precision electromechanical assemblies limit flows from USA, Switzerland, and Germany into Vietnamese device assembly operations. Manufacturing draws from Malaysian and Thai component hubs for infusion sets, plus South Korean and Japanese sources for glucose sensor membranes. Single-source vulnerability concentrates in algorithm licensing for closed-loop control systems. Distribution runs through hospital procurement networks and specialized diabetes management center partnerships rather than retail pharmacy channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vietnam's insulin infusion pump sector sits at a platform-economics inflection where continuous glucose monitoring interoperability determines competitive survival, with software-defined architectures displacing hardware-centric value capture.
For Market Incumbents: Harden consumable subscription lock-in through predictive algorithm refinements that increase switching costs for existing patients. Expand certified diabetes educator training capacity in provincial hubs before regulatory pathways open reimbursement for sensor-augmented therapy. Defensive consolidation around telemedicine convergence platforms will neutralize remote-monitoring entrants threatening metropolitan command structures. For New Entrants and Emerging Players: Build out diagnostic-to-therapy workflow integration in Mekong Delta provincial hospitals where incumbent clinical training infrastructure remains sparse. Target Can Tho City and Da Nang as penetrable anchors before expanding toward tertiary referral networks. Go-to-market through provincial tender participation with price-competitive traditional pump offerings that establish consumable recurring revenue foundations. For Investors and Strategic Acquirers: Long-term, this sits as a recurring-revenue platform play because subscription bundling of sensors and remote monitoring is displacing transactional device sales. Acquisition targets should emphasize clinical training infrastructure assets and established ASEAN Common Submission Dossiers rather than hardware IP alone. Watch for Ministry of Health reimbursement expansion to sensor-augmented therapy as the signal for accelerated market access.| Strategic Initiative | Industry Significance |
|---|---|
| ASEAN Common Submission Dossier Investment | Accelerates Vietnam market entry through harmonized regulatory pathways with established regional dossiers. |
| Provincial Clinical Training Infrastructure | Extends hybrid closed-loop deployment beyond Hanoi and Ho Chi Minh City tertiary concentrations. |
| Sensor-Augmented Reimbursement Strategy | Positions manufacturers for national health insurance eligibility expansion before private spending saturates urban demand. |
| Telemedicine Platform Integration | Enables remote glucose data transmission and algorithm-driven dose adjustment service revenue streams. |
| Consumable Subscription Bundling | Shifts buyer preference from capital expenditure toward operational expenditure models aligning provider-patient incentives. |
Research Methodology
A standing panel of endocrinologists, hospital procurement managers, biomedical engineers, and GPO contracts managers provided ongoing calibration against primary field observations. Secondary validation drew from Ministry of Health circulars, ASEAN Medical Device Directive harmonization documents, hospital procurement databases, and national health insurance reimbursement eligibility lists. Bottom-up patient population modeling and top-down device shipment estimates were triangulated to anchor volume projections.
Scenario-bracketing framed projections across the analysis window, with segmentation dimensions spanning product automation tier, end-user setting, technology integration level, and patient population. CAGRs were derived from fitted growth curves against historical adoption patterns and policy trajectory assumptions. Forecast inputs incorporated provincial hospital tender participation rates and urban household out-of-pocket spending capacity indices.
The forecast holds incumbent behavior within observed patterns; aggressive moves by software-defined pump entrants or telemedicine platform consolidators would shift outcomes. Material shifts in Ministry of Health reimbursement policy or ASEAN regulatory harmonization timelines would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diabetes Care
Oman Diabetes Drugs Market
Diabetes Care
Global Continuous Subcutaneous Insulin Infusion Market
Diabetes Care
Pet Diabetes Care Devices Market
Diabetes Care
Australia Insulin Infusion Pump Market
Diabetes Care
Germany Insulin Infusion Pump Market
Diabetes Care
Australia Continuous Glucose Monitoring Devices Market
Diabetes Care
Continuous Glucose Monitoring Market
Diabetes Care
Global Blood Glucose Monitoring Systems Market
Diabetes Care
North America Diabetes Care Devices Market
Diabetes Care
North America Oral Anti-Diabetic Drug Market
Diabetes Care
Global Diabetic Ulcers Treatment Market
Diabetes Care
BRIC Diabetes Care Devices Market
Diabetes Care
China Self-Monitoring Blood Glucose Devices Market
Diabetes Care
Insulin Patch Pumps Market
Diabetes Care
Middle East and Africa Diabetes Care Devices Market
Diabetes Care
Global Diabetes Pen Market