
 Global Infusion Pump Software Market | 2026-2036
Global Infusion Pump Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global Infusion Pump Software Market Foresight
Hospital procurement consortiums is reshaping how infusion pump software vendors secure enterprise contracts across multi-site health systems. BD leverages its installed base of hardware devices to bundle software subscriptions and lock in long-term agreements. Baxter anchors its position through deep integration with proprietary pump fleets used in critical care settings. Fresenius Kabi competes by specializing in oncology-focused workflow tools that align with chemotherapy administration protocols.
Infusion pump software encompasses the embedded and networked programs that control fluid delivery rates, calculate drug dosages, manage device interoperability, and generate clinical alerts in acute and ambulatory settings. These systems typically process real-time sensor data with millisecond response thresholds to prevent free-flow events and air-in-line errors, serving the core purpose of reducing adverse drug events during parenteral therapy. Cloud-based deployment is gaining share as health systems prioritize remote fleet monitoring and centralized security patching over on-premise infrastructure maintenance. Within the solution layer, device integration and alert notification modules command premium positioning because they directly influence Joint Commission compliance scores and liability exposure.
FDA software-as-a-medical-device guidance, EU MDR cybersecurity annexes, and HIPAA interoperability rules collectively determine which platforms gain market access and which face delayed clearances. The FDA now requires documented evidence of machine-learning algorithm robustness for any dosing automation that adapts to patient physiology. Stakeholders must monitor how rapidly regulators harmonize post-market surveillance requirements across jurisdictions, as divergence will fragment certification costs and slow vendor expansion timelines.
Market Dynamics
Cloud-based deployment architectures are compressing the competitive moat between established pump hardware vendors and pure-play software specialists, forcing legacy manufacturers to unbundle subscription pricing from device sales.
Growth Catalysts
- FDA Software-as-a-Medical-Device framework:The FDA's premarket validation requirements for algorithm-driven dosing systems are accelerating investment in clinical evidence generation, raising barriers for undercapitalized entrants.
- Integrated EHR compatibility mandates:United States health systems now require bidirectional data exchange with Epic and Cerner environments, creating procurement pull for interoperable platforms.
- Critical care settings:ICU and anesthesia departments are expanding smart infusion adoption to reduce adverse drug events during high-risk parenteral therapy.
Market Restraints
- Cybersecurity certification costs:EU MDR cybersecurity annexes and FDA post-market surveillance requirements are extending validation timelines by 12-18 months for new algorithm submissions.
- Input concentration in semiconductor components:Custom ASICs for real-time sensor processing face single-source dependencies from Taiwanese foundries.
- Legacy infrastructure lock-in:Hospitals with 10-15 year pump fleet depreciation cycles cannot justify full-stack replacement for software-only upgrades.
Strategic Opportunities
- Home infusion services:Ambulatory settings in Germany and Japan are adopting remote monitoring platforms to shift chemotherapy and immunoglobulin administration outside acute facilities.
- AI Act compliance tooling:European vendors can capture premium positioning by pre-certifying machine-learning dosing modules under the EU AI Act's high-risk system requirements.
- Oncology workflow specialization:Chemotherapy administration protocols present white space for purpose-built drug library management and nurse verification workflows.
Industry Challenges
- Embedded systems engineering talent:Millisecond-latency firmware development for air-in-line detection and free-flow prevention requires scarce real-time programming expertise.
- Multi-jurisdiction harmonization:Divergent post-market surveillance requirements between FDA, Health Canada, and TGA are fragmenting certification costs and slowing vendor expansion timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Infusion Pump Software Market |
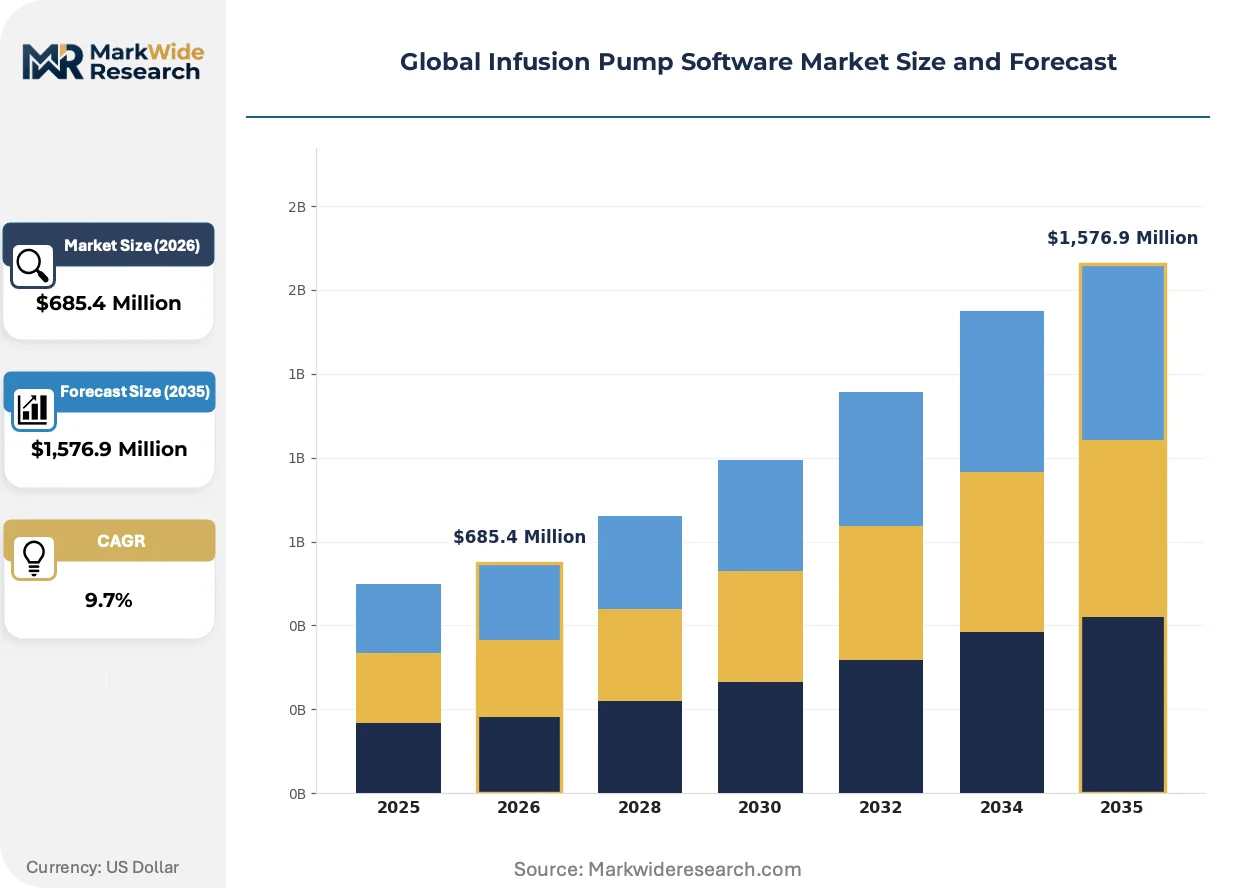
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,576.9 Million |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premise, Cloud-Based, Hybrid, Hosted, Managed Services Solution/Offering: Dosage Calculation, Data Management, Device Integration, Alert Notification, Reporting & Analytics Application: Medication Delivery, Pain Management, Chemotherapy, Neonatal Care, Intensive Care End User: Hospitals, Ambulatory Centers, Home Healthcare, Long-Term Care Facilities, Specialty Clinics |
| Companies Covered | BD, Baxter, B. Braun, ICU Medical, Fresenius Kabi, Medtronic, Terumo Corporation, Moog, Ypsomed, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Infusion Pump Software Market Shifts & Advancements
Algorithmic dosing automation is rewriting the boundary between device control software and clinical decision support, with regulators struggling to classify adaptive systems that learn from patient physiology in real time.
Machine-learning dosing modules are migrating from experimental pilots to production deployments in academic medical centers. Anesthesiology departments at Johns Hopkins and Mayo Clinic are validating adaptive propofol titration algorithms. This technology is migrating from research consortiums to commercial liability frameworks, compressing the validation window for vendors seeking 510(k) clearance.
EU MDR cybersecurity annexes now mandate documented evidence of threat mitigation for networked infusion platforms. Manufacturers must submit software bill of materials and vulnerability management protocols as part of technical documentation. Class III devices with wireless connectivity face the most stringent scrutiny, with notified bodies in Germany and the Netherlands experiencing 6-month review backlogs.
Hospital procurement consortiums are consolidating vendor evaluation authority across multi-site health systems. Premier and Vizient in the United States now negotiate enterprise software licenses on behalf of 4,000-plus member hospitals. This concentration is displacing individual facility purchasing autonomy, favoring vendors with dedicated national accounts infrastructure over regional distributors.
Global Infusion Pump Software Market Segmentation
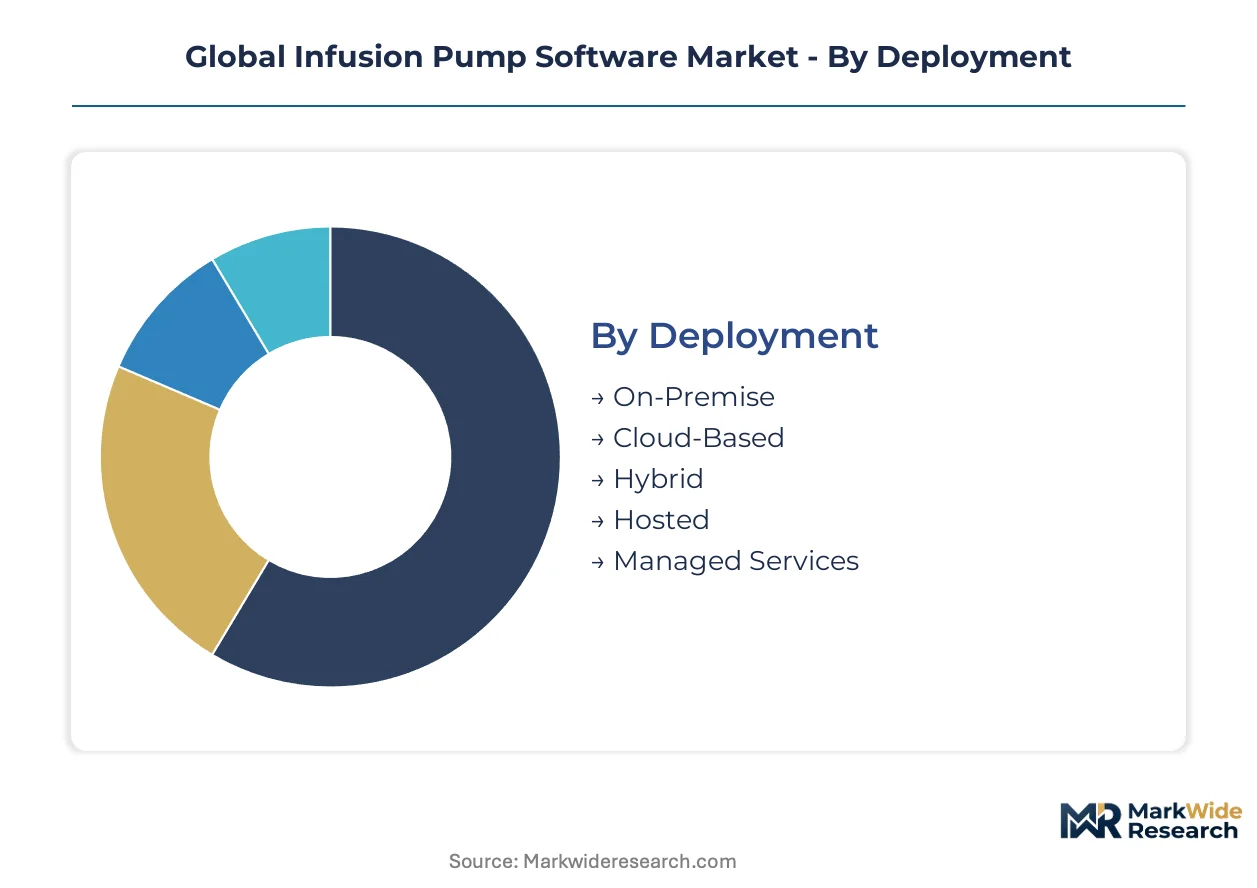
Infusion pump software vendors must navigate four distinct segmentation axes simultaneously. Deployment architecture determines recurring revenue economics. Solution modules dictate regulatory clearance pathways. Application focus shapes clinical evidence requirements. End-user concentration influences sales channel design.
Deployment:
Cost tier separates capex-heavy infrastructure from opex-optimized subscription models.
- Cloud-Based:Multi-tenant architectures enable centralized fleet monitoring across distributed hospital networks. United States health systems in Texas and California are migrating here to offload security patching burdens. This segment is climbing the fastest as procurement teams prioritize remote access and automatic updates over on-premise control.
- On-Premise:Air-gapped installations persist in military medical facilities and certain academic medical centers with legacy IT governance. German university hospitals in Bavaria maintain these deployments for data sovereignty compliance. Installed base here generates maintenance renewals but limited expansion revenue.
- Hybrid:Edge-computing configurations process latency-critical alerts locally while streaming analytics to cloud dashboards. Japanese tertiary centers favor this architecture for ICU applications.
- Hosted:Single-tenant private cloud deployments serve mid-sized hospital chains seeking customization without infrastructure ownership. Australian regional health districts have adopted this model.
- Managed Services:Full outsourcing of software operations including 24/7 monitoring and regulatory reporting. United Kingdom NHS trusts use this for chemotherapy infusion suites.
Cloud-based holds installed capacity. Hybrid is rotating up the share rankings.
Solution/Offering:
Application depth determines which modules command premium positioning versus commoditized functionality.
- Device Integration:Bidirectional interoperability with EHR systems and pump hardware fleets requires HL7 FHIR certification and manufacturer-specific protocols. United States hospitals now mandate Epic and Cerner compatibility as a procurement gate. This segment anchors enterprise contract values.
- Dosage Calculation:Algorithm-driven drug library management with weight-based and body-surface-area protocols. FDA now requires documented machine-learning robustness for adaptive dosing systems. Critical care departments at Johns Hopkins and Mayo Clinic are validating these modules.
- Alert Notification:Real-time clinical decision support for air-in-line detection, occlusion pressure thresholds, and free-flow prevention. EU MDR cybersecurity annexes mandate threat mitigation documentation for networked alert pathways.
- Data Management:Centralized logging of infusion events for Joint Commission compliance and liability documentation. Long-term care facilities in Florida use these modules for regulatory audit trails.
- Reporting & Analytics:Post-hoc analysis of medication error rates and pump utilization patterns. Ambulatory infusion centers in Germany deploy these for quality improvement initiatives.
Device integration holds installed capacity. Dosage calculation is rotating up the share rankings.
Application:
Clinical risk profile shapes validation intensity and pricing power across use cases.
- Intensive Care:Multi-channel smart infusion with vasopressor and sedation coordination demands millisecond-latency firmware. Academic medical centers in Massachusetts and Minnesota drive specification requirements here. This application commands the steepest pricing premiums due to liability exposure.
- Chemotherapy:Oncology-specific drug libraries with vesicant protocols and nurse verification workflows. Fresenius Kabi has specialized here with purpose-built tools aligned to European oncology administration standards.
- Medication Delivery:General-purpose infusion across medical-surgical floors with standardized drug libraries. Community hospitals in Ohio and Pennsylvania represent volume demand.
- Pain Management:Patient-controlled analgesia with lockout intervals and cumulative dose tracking. Ambulatory surgery centers in Texas favor these modules for same-day discharge protocols.
- Neonatal Care:Micro-volume delivery with precision requirements down to 0.1 mL/hour. Children's hospitals in California and Illinois maintain specialized procurement criteria.
Intensive care holds installed capacity. Chemotherapy is rotating up the share rankings.
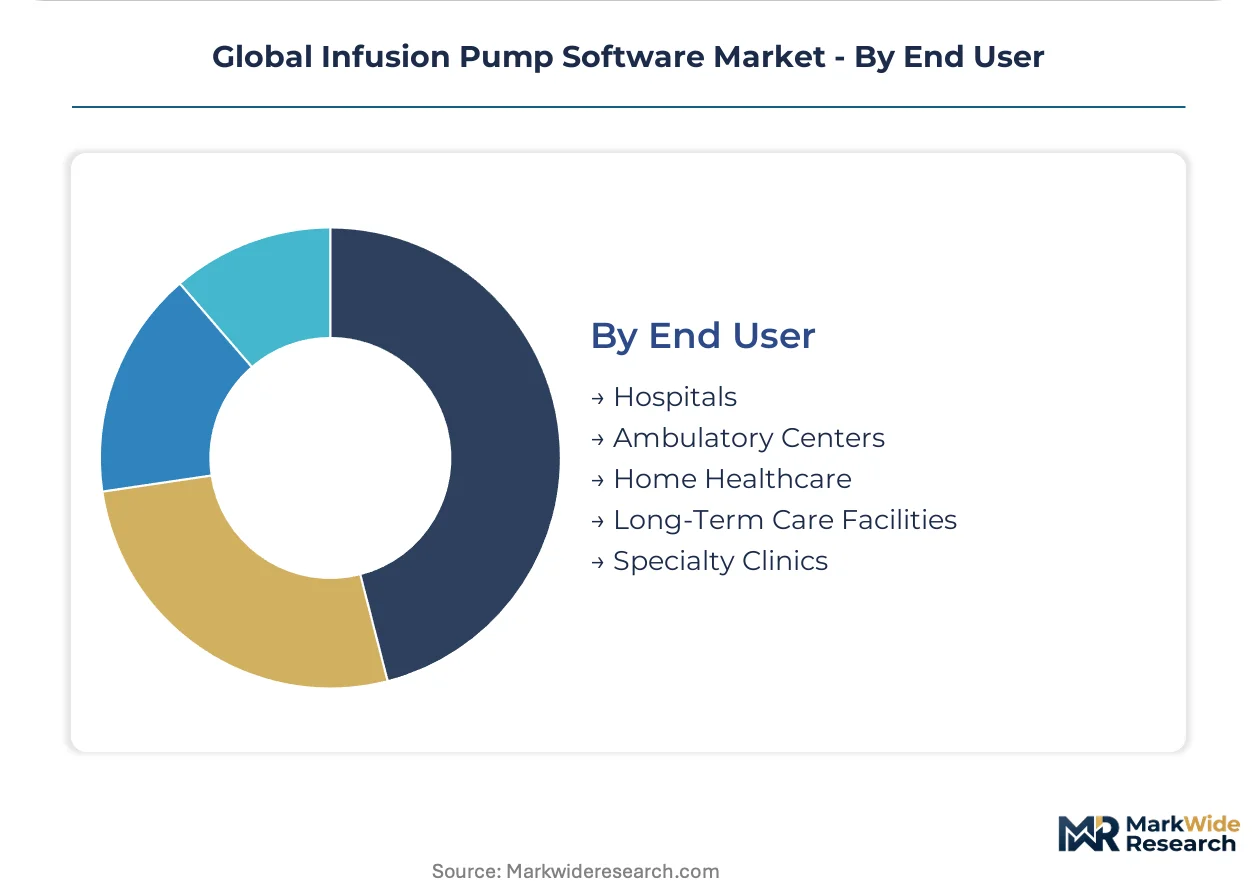
End User:
Customer type concentration determines whether vendors pursue enterprise contracts or point solutions.
- Hospitals:Multi-site health systems with centralized procurement through Premier and Vizient consortiums. These customers require bidirectional EHR integration and enterprise license structures. United States hospital networks in the Southeast and Midwest anchor vendor revenue.
- Home Healthcare:Remote monitoring platforms for chemotherapy and immunoglobulin administration outside acute facilities. German and Japanese ambulatory settings are expanding adoption here.
- Ambulatory Centers:Same-day surgery and infusion clinics with simplified workflow needs. Standalone oncology clinics in France prioritize ease of use over advanced analytics.
- Long-Term Care Facilities:Skilled nursing environments with lower acuity but heightened regulatory documentation requirements. State-level Medicaid programs in New York and Illinois influence procurement.
- Specialty Clinics:Pain management and dialysis centers with narrow therapeutic focus. Independent nephrology practices in Florida represent fragmented demand.
Hospitals hold installed capacity. Home healthcare is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States maintains the dominant position in infusion pump software adoption, anchored by its integrated health system infrastructure and the FDA's software-as-a-medical-device premarket validation framework. Germany and Japan represent mature secondary markets with specialized oncology and critical care demand clusters. China's hospital digitization programs and India's expanding medical device manufacturing base are emerging as significant volume centers.
United States
Premier and Vizient procurement consortiums now negotiate enterprise software licenses for over 4,000 member hospitals, concentrating vendor evaluation authority at the national level. The FDA requires documented machine-learning algorithm robustness for adaptive dosing systems seeking 510(k) clearance. Academic medical centers in Massachusetts and Minnesota drive specification requirements for ICU multi-channel smart infusion platforms.
Germany
Bavarian university hospitals maintain on-premise deployments for data sovereignty compliance, while ambulatory settings adopt remote monitoring platforms for home chemotherapy administration. EU MDR cybersecurity annexes mandate software bill of materials submission for networked infusion platforms, with notified bodies experiencing six-month review backlogs. The Eindhoven-to-Munich medical technology corridor anchors device integration module development.
Japan
Japanese tertiary centers favor hybrid edge-computing architectures that process latency-critical alerts locally while streaming analytics to cloud dashboards. METI's medical device cybersecurity guidelines align with EU MDR annexes, creating harmonized compliance pathways for vendors. The Kanto region around Tokyo concentrates demand for neonatal care micro-volume delivery systems with precision requirements down to 0.1 mL/hour.
United Kingdom
NHS trusts utilize managed services outsourcing for chemotherapy infusion suite operations, including 24/7 monitoring and regulatory reporting. The Medicines and Healthcare products Regulatory Agency enforces post-market surveillance requirements that fragment certification timelines alongside FDA and Health Canada divergence. Greater London's hospital networks prioritize bidirectional Epic and Cerner EHR compatibility as a procurement prerequisite.
China
Hospital digitization programs under the 14th Five-Year Plan are accelerating smart infusion platform procurement across tertiary medical centers. NMPA's evolving medical device software classification framework is tightening premarket validation requirements for algorithm-driven dosing systems. The Yangtze River Delta region, particularly Shanghai and surrounding provinces, concentrates demand for integrated electronic health record compatibility.
Global Infusion Pump Software Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream with narrower module scope. The market structure consolidates around pump hardware incumbents who leverage installed device bases to bundle software subscriptions, while pure-play software vendors compete on interoperability specialization. Three archetypes dominate: legacy manufacturers with captive hardware fleets, EHR-integrated platform specialists, and oncology-focused workflow tool developers. Competitive moves center on unbundling subscription pricing from device sales and securing enterprise contracts through national accounts infrastructure.
Within the legacy manufacturer tier, BD and Baxter anchor positions through deep integration with proprietary pump fleets and critical care specialization. Fresenius Kabi occupies a distinct archetype as an oncology-focused workflow tool developer aligned to European chemotherapy administration protocols. These three represent the dominant competitive positioning patterns: hardware-leveraged platform bundling, critical care device integration, and therapeutic-area specialization.
| Leading Market Players |
|---|
| BD |
| Baxter |
| B. Braun |
| ICU Medical |
| Fresenius Kabi |
| Medtronic |
| Terumo Corporation |
| Moog |
| Ypsomed |
| Others |
Supply & Pricing Matrix
Taiwanese foundry concentration for custom ASICs determines both the premium commanded by real-time firmware vendors and the geographic distribution of final assembly. FDA software-as-a-medical-device validation timelines compress margins for algorithm-driven dosing systems while extending procurement cycles.
Pricing Analysis
Volume-discount tiering structures separate enterprise health system contracts from mid-sized hospital purchases and ambulatory clinic point solutions. Pricing stratifies across FDA-validated premium modules, CE-marked standard interoperability layers, and economy alert-notification packages. Cost compression in the standard tier is intensifying because GPO consortiums negotiate centralized licenses across 4,000-plus member hospitals. Community hospitals in Ohio and Pennsylvania exhibit the highest price sensitivity, while academic medical centers in Massachusetts prioritize liability reduction over procurement cost.
Supply Chain Analysis
Upstream feedstock for real-time sensor processing draws from Taiwanese semiconductor foundries, German precision component manufacturers, and Chinese PCB assembly clusters. Custom ASICs, millisecond-latency firmware modules, and wireless connectivity chipsets constitute critical input dependencies. Single-source vulnerability in Taiwanese foundry capacity creates exposure for vendors seeking FDA clearance for adaptive dosing algorithms. Distribution runs through GPO consortiums and regional medical device distributors serving hospital procurement committees.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Software subscription attach rates for infusion pump platforms are expanding faster than hardware replacement cycles, transforming vendor economics toward recurring revenue models anchored by fleet monitoring and regulatory compliance services.
For Market Incumbents: Pre-empt pure-play interoperability specialists by unbundling subscription pricing from legacy device sales and accelerating cloud-native platform development. Vertical integration into firmware development for millisecond-latency alert systems defends against talent scarcity in embedded systems engineering. Securing dedicated national accounts infrastructure preserves enterprise contract access as Premier and Vizient consolidate procurement authority. For New Entrants and Emerging Players: Home healthcare remote monitoring platforms in Germany and Japan represent the most penetrable entry point given ambulatory chemotherapy administration expansion outside acute facilities. Oncology-focused drug library management tools aligned to EU chemotherapy protocols present white-space opportunity with lower FDA validation barriers than critical care applications. Partnership with mid-sized hospital chains seeking customization without infrastructure ownership accelerates initial referenceability. For Investors and Strategic Acquirers: EU AI Act high-risk system pre-certification reshapes the acquisition landscape toward European vendors with documented machine-learning robustness. Five-to-ten year viability favors platform integrators with installed device bases over component specialists vulnerable to hardware commoditization. The signal to watch is harmonization progress between FDA post-market surveillance and EU MDR cybersecurity annexes, which would compress certification costs for cross-border expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Native Platform Migration | Enables remote fleet monitoring across distributed hospital networks in Texas and California. |
| FDA 510(k) Algorithm Validation | Accelerates clearance timelines for adaptive dosing systems at Johns Hopkins and Mayo Clinic. |
| EHR Integration Certification | Secures procurement eligibility through Epic and Cerner bidirectional data exchange mandates. |
| EU MDR Cybersecurity Pre-Certification | Captures premium positioning under notified body review pathways in Germany and Netherlands. |
| Home Healthcare Remote Monitoring | Expands addressable market into German and Japanese ambulatory chemotherapy administration. |
Research Methodology
A standing panel of hospital procurement managers, biomedical engineers, GPO contracts specialists, and ICU clinical directors provided ongoing calibration throughout the study period. Primary interview data combined with secondary validation from FDA 510(k) filings, EU MDR technical documentation, hospital procurement databases, and GPO contract disclosures. Bottom-up segment sizing and top-down market triangulation anchored volume and value estimates.
Scenario-bracketing framed analytical outputs across the projection horizon, modeling deployment architecture, solution module depth, clinical application risk profile, and end-user concentration dimensions. CAGRs derived from segment-level growth trajectory analysis incorporating EHR interoperability mandate adoption curves and cloud migration patterns in United States health systems.
Practitioners should monitor regulatory harmonization progress between FDA, Health Canada, and TGA for early signals of certification cost fragmentation or convergence. Forecasts reflect assumptions about machine-learning algorithm validation timelines and semiconductor supply availability. Cross-checking against CMS Medicare reimbursement data and hospital capital expenditure surveys is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Pre-Filled Hemostasis Agents Market
Medical Devices
Bone Power Tools Market
Medical Devices
Global Extracorporeal Shock Wave Lithotripsy Market
Medical Devices
Life Science and Chemical Instruments Market
Medical Devices
PET-CT Scanner Device Market
Medical Devices
Pharmaceutical Robots Market
Medical Devices
Global Self-Injection Device Market
Medical Devices
DLIF and XLIF Implants Market
Medical Devices
Pancreatic and Biliary Stents Market
Medical Devices
Deep Brain Stimulator Market
Medical Devices
Medical Device Trays Market
Medical Devices
Versatile Cryosurgical Devices Market
Medical Devices
Implant Handpiece Market
Medical Devices
MRI Compatible IV Infusion Pumps Market
Medical Devices
Asia-Pacific Medical Suction Device Market
Medical Devices
3D Printing for Surgical Procedures Market