
 Light Therapy Beauty Devices Market | 2026-2036
Light Therapy Beauty Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Light Therapy Beauty Devices Market Insights
Price-performance logic is decoupling between premium and commodity tiers in the light therapy beauty devices space. Koninklijke Philips N.V. leverages its clinical heritage to anchor professional-channel credibility, while Home Skinovations Ltd competes through direct-to-consumer accessibility at lower price points. L'Oréal Group differentiates by integrating light therapy into its broader beauty-tech ecosystem, blurring the line between cosmetics and medical aesthetics.
Light therapy beauty devices employ specific wavelengths—typically 630–700 nm for red light and 405–420 nm for blue light—to stimulate cellular processes or suppress bacterial activity, with output power and treatment duration calibrated to dermatological endpoints. LED masks dominate unit volume due to their hands-free format and social-media compatibility, though near-infrared panels command superior margins in professional settings where deeper tissue penetration justifies premium pricing. Blue light therapy for acne treatment remains the most clinically validated application, while mood enhancement represents an emerging functional claim with less established regulatory precedent.
FDA 510(k) clearance requirements and EU MDR classification rules are reshaping market access timelines, particularly for devices making wrinkle-reduction or collagen-stimulation claims. ISO 13485 certification is becoming a baseline procurement filter for dermatology clinics and spa chains evaluating supplier partnerships. Stakeholders must monitor how evolving photobiomodulation evidence standards affect permissible marketing language and reimbursement positioning across jurisdictions.
Market Dynamics
FDA 510(k) clearance documentation requirements are tightening around photobiomodulation efficacy claims, forcing manufacturers to recalibrate clinical validation budgets and extend market access timelines for wrinkle-reduction and collagen-stimulation indications.
Growth Catalysts
- EU MDR classification rules:CE marking under stricter medical device regulations is filtering out low-quality competitors, creating procurement advantages for ISO 13485-certified suppliers in dermatology clinic channels.
- Med-spa chain consolidation:Large US aesthetic clinic networks are standardizing on professional-grade LED systems, generating volume procurement contracts that favor suppliers with clinical heritage credibility.
- Near-infrared wavelength expansion:800-900 nm panels delivering deeper tissue penetration are opening premium pricing tiers in professional settings where dermal remodeling endpoints justify higher equipment investment.
Market Restraints
- Blue light phototoxicity documentation:ECHA scrutiny of cumulative ocular exposure risks is complicating marketing claims for high-intensity acne treatment devices, particularly in EU member states with stricter photobiological safety enforcement.
- LED chip supply concentration:Epitaxial wafer production clusters in East Asia create vulnerability to geopolitical trade friction and raw material allocation constraints for device assemblers elsewhere.
- Topical retinoid substitution:Prescription adapalene and tretinoin formulations retain dermatologist preference for moderate acne cases, limiting addressable market expansion for blue light monotherapy devices.
Strategic Opportunities
- Mood enhancement claims:Circadian rhythm modulation applications lack established FDA clearance precedents, creating first-mover advantage for manufacturers that assemble photobiomodulation evidence packages targeting seasonal affective disorder adjacent markets.
- Direct-to-consumer subscription bundling:Device-plus-serum recurring revenue models are penetrating younger demographic segments previously inaccessible through professional channel distribution.
- India BIS certification pathway:Formal adoption of IEC 60601-2-57 standards for light therapy equipment is streamlining import registration, reducing time-to-market for international manufacturers targeting aesthetic clinic expansion in Mumbai and Delhi clusters.
Industry Challenges
- Photobiology specialist scarcity:Device manufacturers struggle to recruit sufficient clinical research staff capable of designing irradiance-dose studies that satisfy FDA reviewer expectations for 510(k) substantive equivalence demonstrations.
- Multi-jurisdiction labeling divergence:Separate packaging and instruction requirements for US prescription-grade versus EU consumer-grade classifications inflate inventory complexity and compliance overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Light Therapy Beauty Devices Market |
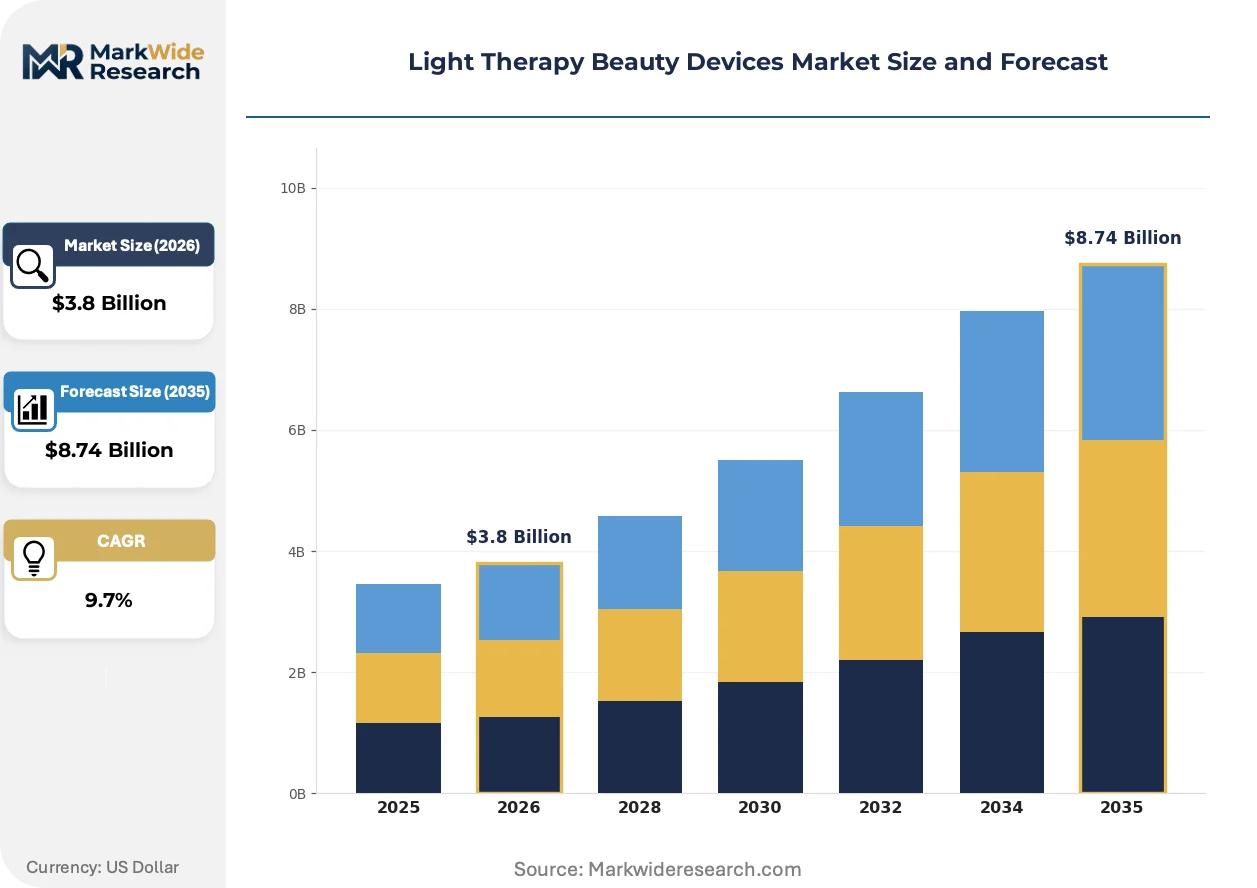
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.74 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: LED Masks, Handheld Devices, Light Panels, Light Strips Technology: Red Light Therapy, Blue Light Therapy, Near Infrared, Pulsed Light End User: Home Users, Professional Estheticians, Dermatology Clinics, Spas Application: Anti-Aging, Acne Treatment, Skin Rejuvenation, Mood Enhancement |
| Companies Covered | Koninklijke Philips N.V., Home Skinovations Ltd, L'Oréal Group, PhotoMedex Inc., TRIA Beauty Inc., Nu Skin Enterprises, Syneron Medical Ltd, Lumenis Ltd., Panasonic Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Light Therapy Beauty Devices Market Trends and Innovations
Light therapy beauty devices are undergoing functional expansion beyond dermatological endpoints into wellness adjacencies, with hardware form factors and wavelength protocols adapting to home-use convenience requirements and social media content creation behaviors.
Multi-wavelength mask systems combining red, blue, and near-infrared emitters in programmable sequences are overtaking single-function devices in unit economics. Aesthetic clinic procurement managers favor these flexible platforms for treatment menu expansion without incremental capital expenditure. The technology is compressing average revenue per device for standalone blue-light or red-light-only manufacturers while expanding total addressable session volume for adopters.
REACH restrictions on heavy metals in electrical equipment are forcing LED substrate and solder composition changes across EU-bound product lines. Manufacturers reformulating with lead-free alternatives face temporary yield degradation and thermal management redesign costs. Professional-grade mask producers serving German and French med-spa chains are absorbing these compliance investments fastest, creating regulatory moats against lower-cost competitors.
Social media content creator partnerships are displacing traditional dermatologist endorsement as the primary demand generation channel for premium home-use devices. Younger consumer segments in the United States discover LED mask brands through TikTok tutorial content rather than clinic recommendation. This shift concentrates marketing spend on influencer seeding programs and unboxing-optimized packaging design, with performance metrics tied to shareable before-and-after documentation rather than clinical citation.
Light Therapy Beauty Devices Market Segmentation
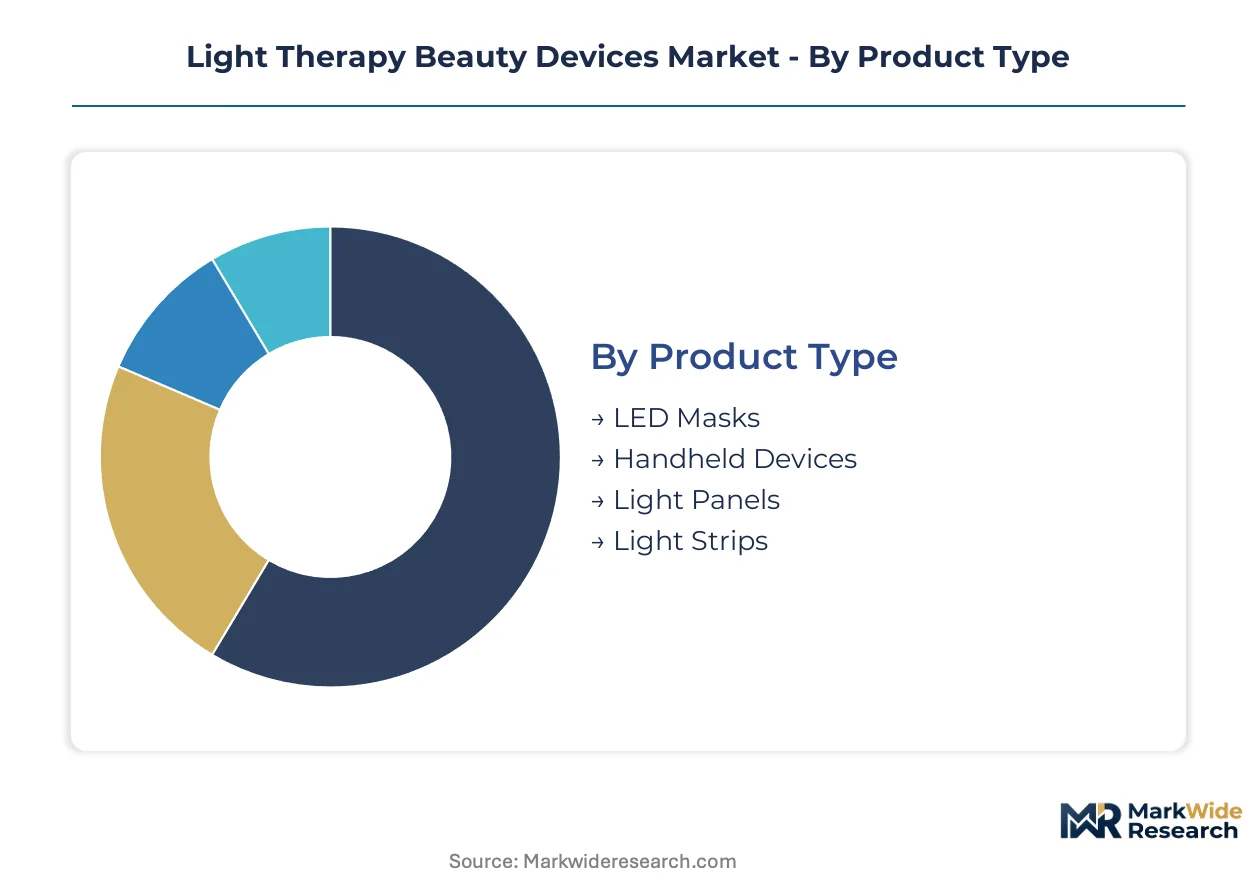
Product architecture in light therapy beauty devices determines channel economics and regulatory pathway complexity. Form factor choices directly constrain wavelength delivery mechanisms, power output ceilings, and FDA classification thresholds that separate professional-grade systems from consumer-accessible alternatives.
Product Type:
Wavelength delivery architecture varies fundamentally across physical formats, with hands-free designs commanding distinct manufacturing cost structures versus directed-application devices.
- LED Masks:Full-face arrays with 100-200 embedded diodes enable concurrent multi-zone treatment. Demand concentrates in United States direct-to-consumer channels where TikTok-native brands convert social proof into subscription bundling revenue.
- Handheld Devices:Portable wand and pen formats target spot-treatment precision with lower diode counts and battery-dependent power profiles. Professional estheticians in German med-spa chains favor these for add-on service flexibility without capital equipment overhead.
- Light Panels:Wall-mounted or stand-based systems deliver higher irradiance levels with expanded treatment surface area. Dermatology clinics in Mumbai and Delhi clusters deploy these for back and décolletage applications beyond facial endpoints.
- Light Strips:Flexible diode arrays conform to body contours for targeted zone therapy. Niche positioning in home-use wellness segments emphasizes portability and storage convenience over clinical efficacy claims.
Mature deployment sits with LED Masks. Newer deployment is concentrated in Light Strips.
Technology:
Spectral specificity determines cellular interaction mechanisms, with each wavelength band carrying distinct evidentiary requirements for permissible marketing claims across FDA and EU MDR jurisdictions.
- Red Light Therapy:630-700 nm wavelengths stimulate mitochondrial ATP production and fibroblast collagen synthesis. Anti-aging applications in United States med-spa chains drive premium pricing where wrinkle-reduction claims require 510(k) substantiation.
- Blue Light Therapy:405-420 nm emission targets Cutibacterium acnes porphyrin activation for bacterial suppression. Acne treatment remains the most clinically validated indication, though ECHA scrutiny of cumulative ocular exposure constrains high-intensity device marketing in EU member states.
- Near Infrared:800-900 nm penetration reaches subcutaneous tissue layers for dermal remodeling endpoints. Professional settings in Dubai aesthetic clinics justify equipment investment through premium session pricing tied to deeper tissue efficacy.
- Pulsed Light:Modulated emission patterns claim enhanced cellular response through duty-cycle variation. Emerging positioning lacks established clearance precedents, creating first-mover advantage for manufacturers assembling photobiomodulation evidence packages.
Established clinical validation concentrates in Blue Light Therapy. Steepest expansion trajectory is occurring in Near Infrared.
End User:
Channel segmentation separates regulated medical environments from consumer-accessible distribution, with procurement authority and reimbursement positioning diverging sharply across these boundaries.
- Home Users:Direct-to-consumer purchasers prioritize convenience, price accessibility, and social media content compatibility. Subscription bundling with topical serums penetrates younger United States demographics previously inaccessible through professional channels.
- Professional Estheticians:Licensed practitioners operating in med-spa and salon environments require portable, multi-function equipment for service menu expansion. ISO 13485 certification functions as a baseline procurement filter in French and German clinic networks.
- Dermatology Clinics:Physician-supervised settings demand FDA 510(k) cleared or EU MDR Class IIa compliant systems with documented efficacy for insurance reimbursement positioning. Large United States aesthetic clinic networks generate volume procurement contracts favoring suppliers with clinical heritage credibility.
- Spas:Wellness-focused operators emphasize experiential differentiation over clinical outcomes, creating demand for multi-wavelength programmable systems with luxury positioning and ambient design elements.
Volume concentration rests with Home Users. Margin expansion is strongest in Dermatology Clinics.
Application:
Functional claim categories map directly to regulatory pathway complexity, with dermatological endpoints facing stricter evidentiary requirements than wellness-adjacent positioning.
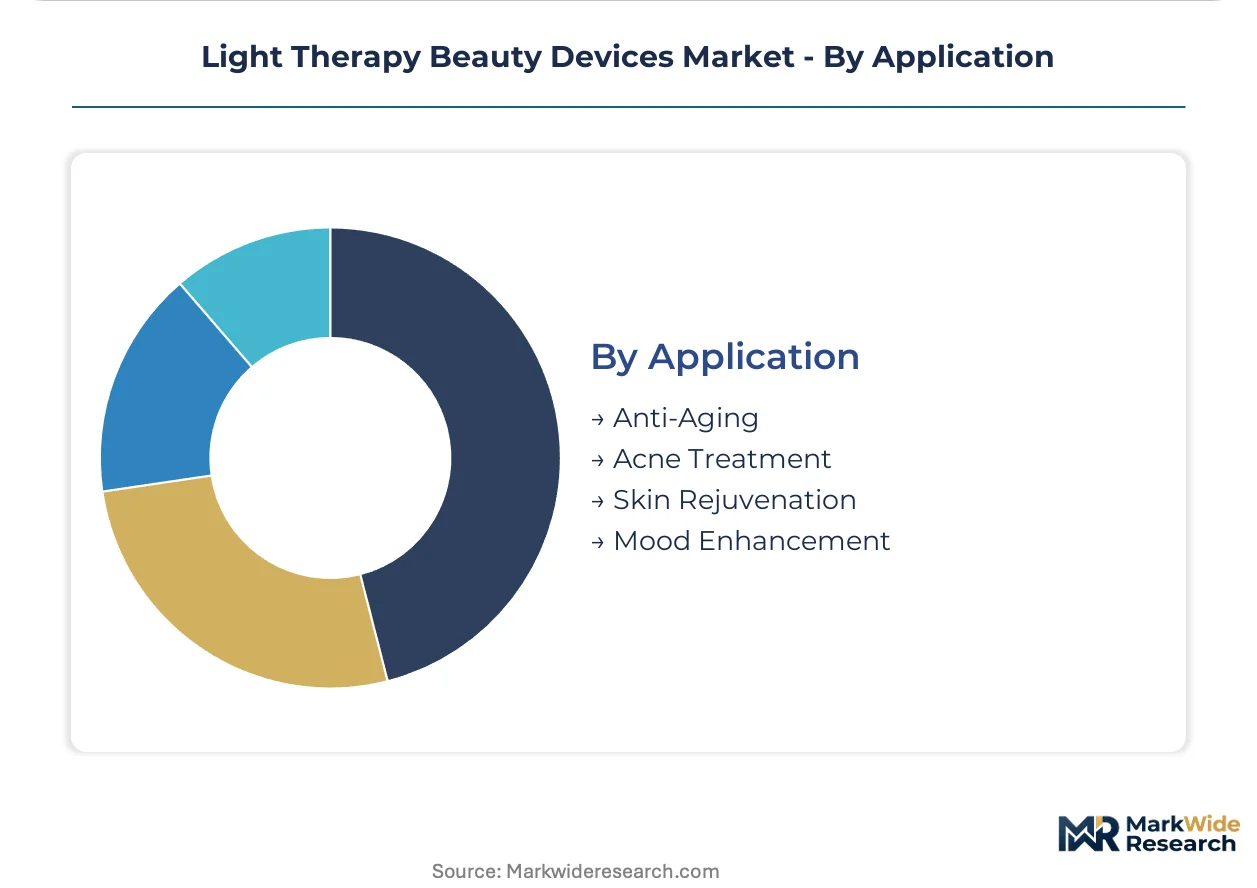
- Anti-Aging:Collagen stimulation and wrinkle reduction claims trigger FDA 510(k) clearance requirements with substantive equivalence demonstrations. Manufacturers face extended timelines and elevated clinical validation budgets for permissible marketing language.
- Acne Treatment:Blue light bacterial suppression enjoys the strongest clinical validation and broadest regulatory acceptance. Prescription adapalene and tretinoin formulations retain dermatologist preference for moderate cases, constraining addressable market expansion for monotherapy devices.
- Skin Rejuvenation:Generalized improvement claims occupy a regulatory gray zone between cosmetic and medical device classification, with jurisdiction-specific interpretation variation affecting market access strategy.
- Mood Enhancement:Circadian rhythm modulation and seasonal affective disorder adjacent applications lack established FDA clearance precedents. Evidence package assembly for photobiomodulation effects on melatonin and cortisol cycles creates first-mover positioning opportunity.
Regulatory clarity is deepest in Acne Treatment. Emerging positioning concentrates in Mood Enhancement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Los Angeles anchors professional device deployment through med-spa chain consolidation and celebrity-backed brand headquarters, while FDA clearance pathways shape manufacturer market access timelines across domestic distribution channels.
United States
Med-spa chain standardization on professional-grade LED systems generates volume procurement contracts concentrated in California and Florida aesthetic clinic networks. FDA 510(k) clearance requirements for wrinkle-reduction claims extend market access timelines, forcing manufacturers to recalibrate clinical validation budgets. New York and Miami clusters drive premium segment velocity through influencer marketing integration and subscription bundling models.
Germany
ISO 13485 certification functions as baseline procurement filter for dermatology clinic networks concentrated in Bavaria and North Rhine-Westphalia. EU MDR classification rules filter low-quality competitors, creating procurement advantages for compliant suppliers. REACH restrictions on heavy metals in electrical equipment force LED substrate reformulation, with Berlin and Frankfurt med-spa chains absorbing compliance investments fastest.
China
Epitaxial wafer production clusters in East Asia create LED chip supply concentration that device assemblers elsewhere depend upon. NMPA regulatory pathways for imported aesthetic devices require local clinical trial documentation, extending registration timelines for international manufacturers. Shanghai and Shenzhen technology zones concentrate domestic device assembly capacity serving Asia-Pacific distribution networks.
India
BIS certification pathway adoption of IEC 60601-2-57 standards streamlines import registration for international manufacturers targeting aesthetic clinic expansion. Mumbai and Delhi clusters concentrate dermatology clinic procurement of professional-grade systems. CDSCO medical device classification rules create parallel registration requirements for devices making collagen-stimulation claims versus cosmetic positioning.
United Arab Emirates
Dubai aesthetic clinics justify near-infrared panel equipment investment through premium session pricing tied to deeper tissue efficacy endpoints. MOHAP medical device registration requirements create Gulf Cooperation Council market access gateway for manufacturers targeting regional expansion. Abu Dhabi wellness tourism infrastructure generates demand for multi-wavelength programmable systems with luxury positioning elements.
Light Therapy Beauty Devices Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across tiered market positions, with clinical heritage credibility separating professional-channel suppliers from direct-to-consumer accessibility players. The vendor base organizes around three strategic archetypes: diversified electronics conglomerates leveraging manufacturing scale, pure-play aesthetic device specialists concentrating photobiomodulation expertise, and beauty-tech integrators blurring cosmetics-medical boundaries. M&A activity concentrates on photobiology research capabilities and ISO 13485-certified manufacturing assets, while strategic partnerships with med-spa chains lock in volume procurement commitments.
Among diversified electronics conglomerates, Koninklijke Philips N.V. and Panasonic Corporation anchor professional-channel credibility through clinical heritage positioning and regulatory compliance infrastructure. Pure-play specialists exemplified by Home Skinovations Ltd occupy direct-to-consumer accessibility tiers with lower price-point penetration. L'Oréal Group represents beauty-tech integration archetype, embedding light therapy within broader cosmetic ecosystem strategies that merge medical aesthetics with consumer brand loyalty mechanics.
| Leading Market Players |
|---|
| Koninklijke Philips N.V. |
| Home Skinovations Ltd |
| L'Oréal Group |
| PhotoMedex Inc. |
| TRIA Beauty Inc. |
| Nu Skin Enterprises |
| Syneron Medical Ltd |
| Lumenis Ltd. |
| Panasonic Corporation |
| Others |
Pricing and Supply Chain Analysis
Epitaxial wafer costs originating in East Asian foundries cascade through three distinct pricing tiers, with FDA 510(k) clearance status separating professional-grade equipment from direct-to-consumer alternatives and raw material allocation constraints compressing margins at the commodity end.
Pricing Analysis
Session-throughput pricing anchors professional-channel contracts, where dermatology clinics in Los Angeles and Miami recover equipment investment via per-treatment revenue models. Certification-grade differentiation separates FDA-cleared near-infrared panels from uncertified home-use masks, while brand heritage premiums command position in German med-spa networks. Cost compression in the handheld device tier intensifies as Home Skinovations Ltd and comparable direct-to-consumer competitors scale volume procurement. Home users exhibit highest price sensitivity, whereas Dubai aesthetic clinics demonstrate lowest sensitivity given premium session pricing power.
Supply Chain Analysis
ISO 13485 certification gating filters supplier eligibility for dermatology clinic procurement in Germany, France, and the United States, creating compliance moats against uncertified competitors. Epitaxial wafer production concentrates in China, South Korea, and Taiwan, with LED chip assembly feeding device manufacturers in Shenzhen and Seoul clusters. Gallium nitride substrates and phosphor coatings constitute critical input dependencies. Single-source vulnerability in East Asian wafer supply creates tariff exposure risk for European and North American assemblers. Distribution runs through med-spa chain procurement offices and direct-to-consumer e-commerce platforms with divergent margin structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race, with control over LED chip supply and photobiology research capabilities determining pricing power and clearance timeline acceleration.
For Market Incumbents: Cement professional-channel position by acquiring ISO 13485-certified manufacturing assets in Germany or the United States, insulating against emerging pure-play specialists with direct-to-consumer scale. Lock in multi-year procurement contracts with consolidating Los Angeles and Florida med-spa chains before EU MDR classification rules fully filter competitor access. Near-infrared wavelength IP serves as the priority defensive lever against commoditization in red-light and blue-light segments. For New Entrants and Emerging Players: BIS certification pathway adoption in India opens a window for streamlined import registration targeting Mumbai and Delhi aesthetic clinic expansion with professional-grade light panels. Mood enhancement claims lack established FDA clearance precedents, creating first-mover positioning opportunity for photobiomodulation evidence packages targeting seasonal affective disorder adjacent markets. Subscription bundling with topical serums penetrates younger United States demographics previously inaccessible through professional channels. For Investors and Strategic Acquirers: First FDA 510(k) clearance for wrinkle-reduction claims in the mood enhancement category is the leading indicator that photobiomodulation evidence standards have matured sufficiently for reimbursement positioning. Target acquisition profiles center on photobiology research teams capable of designing irradiance-dose studies and ISO 13485-certified manufacturing footprints in Bavaria or North Rhine-Westphalia clusters. Capability scarcity in clinical research staff capable of satisfying FDA reviewer expectations signals inflection timing for specialist firm valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Photobiology Research Acquisition | Builds FDA 510(k) clearance capability for collagen-stimulation claims ahead of competitor timelines. |
| Med-Spa Chain Partnership | Locks volume procurement commitments with Los Angeles and Florida aesthetic clinic networks. |
| EU MDR Compliance Investment | Creates regulatory moat against low-quality competitors in German and French dermatology channels. |
| Direct-to-Consumer Subscription Launch | Captures younger United States demographics through device-plus-serum recurring revenue models. |
| Near-Infrared Wavelength Expansion | Opens premium pricing tiers in Dubai and Abu Dhabi aesthetic clinics through deeper tissue efficacy. |
Research Methodology
Document review covered FDA 510(k) clearance filings, EU MDR classification guidance, and BIS certification standards, complemented by interviews with dermatology clinic procurement managers, professional estheticians in German med-spa chains, biomedical engineers at LED device manufacturers, and regulatory affairs specialists navigating photobiomodulation evidence requirements. Secondary validation drew from hospital procurement databases, GPO contracts, and customs records for epitaxial wafer trade flows. Bottom-up segment sizing triangulated against top-down market boundary checks.
Cross-referencing historical adoption patterns with expert panel input shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product architecture, wavelength technology, end-user channel, and application claim category with associated regulatory pathway complexity. CAGRs derived from installed base growth rates and replacement cycle assumptions. Near-infrared wavelength expansion trajectory and med-spa chain consolidation pace served as key forecast sensitivity inputs.
The model assumes a particular technology adoption path; alternative pathways for pulsed light modulation or circadian rhythm applications would alter the outlook. Forecasts reflect assumptions regarding FDA reviewer consistency for photobiomodulation claims and REACH enforcement continuity for heavy metal restrictions. A model refresh is warranted upon material change in LED chip supply allocation from East Asian foundries or EU MDR classification interpretation for wellness-adjacent positioning.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Military Wearable Medical Device Market
Medical Devices
Volumetric Arc Therapy Market
Medical Devices
Cryosurgery Devices Market
Medical Devices
Soft Tissue Market
Medical Devices
Diode Laser Hair Removal Equipment Market
Medical Devices
Global Electrosurgery Generator Market
Medical Devices
Germany Minimally Invasive Surgery Devices Market
Medical Devices
GCC Biopsy Devices Market
Medical Devices
Ultrasonic Diathermy Market
Medical Devices
Global Surgical/Operating Microscopes Market
Medical Devices
Phakic Intraocular Lenses (IOL) Market
Medical Devices
Asia-Pacific Single-Use Medical Device Reprocessing Market
Medical Devices
Global Glaucoma Surgery Devices Market
Medical Devices
Australia Spinal Surgery Devices Market
Medical Devices
Global Gait Analysis System Market
Medical Devices
Global Surgical Microscopes Market