
 Nerve Repair and Regeneration Market | 2026-2036
Nerve Repair and Regeneration Market Size, Share, and Industry Trends Forecast 2026-2036
Nerve Repair and Regeneration Market Intelligence
Switzerland is rewriting competitive dynamics in nerve repair through concentrated biopolymer manufacturing and precision medical device engineering. Medtronic PLC leverages its deep neuromodulation infrastructure to sustain leadership across implantable neurostimulation platforms. AxoGen Inc. anchors the peripheral nerve allograft segment with specialized processing capabilities for human tissue nerve grafts. Boston Scientific Corporation competes through differentiated electrode designs that extend its reach into spinal cord stimulation adjacencies.
Nerve repair and regeneration encompasses surgical interventions, biologics, and electroceutical devices that restore structural continuity and functional signaling in damaged neural tissue. Biodegradable scaffolds fabricated from collagen, polyglycolic acid, or chitosan provide temporary extracellular matrix support while host axons elongate across lesion gaps. Conduits and wraps dominate current procedural volumes due to established reimbursement and surgeon familiarity, though stem cell therapy captures the fastest-growing investment flow as clinical pipelines mature. Neurosurgery centers represent the highest-margin end-user channel, while rehabilitation facilities expand as sites for adjunctive electrical stimulation protocols.
FDA breakthrough device designation and EU MDR conformity assessments shape product development timelines and market access trajectories for novel nerve repair technologies. ISO 14155 clinical investigation standards and FDA 21 CFR Part 820 quality system requirements govern trial design and manufacturing compliance across major commercial jurisdictions. Stakeholders must monitor evolving CMS coverage determinations for bioengineered nerve constructs and anticipate how Japan PMDA sakigake fast-track pathways will redistribute regional launch sequencing.
Market Dynamics
FDA breakthrough device designations and accelerated EU MDR pathways are compressing commercialization timelines for bioengineered nerve conduits while trauma centers consolidate procurement around fewer high-volume suppliers.
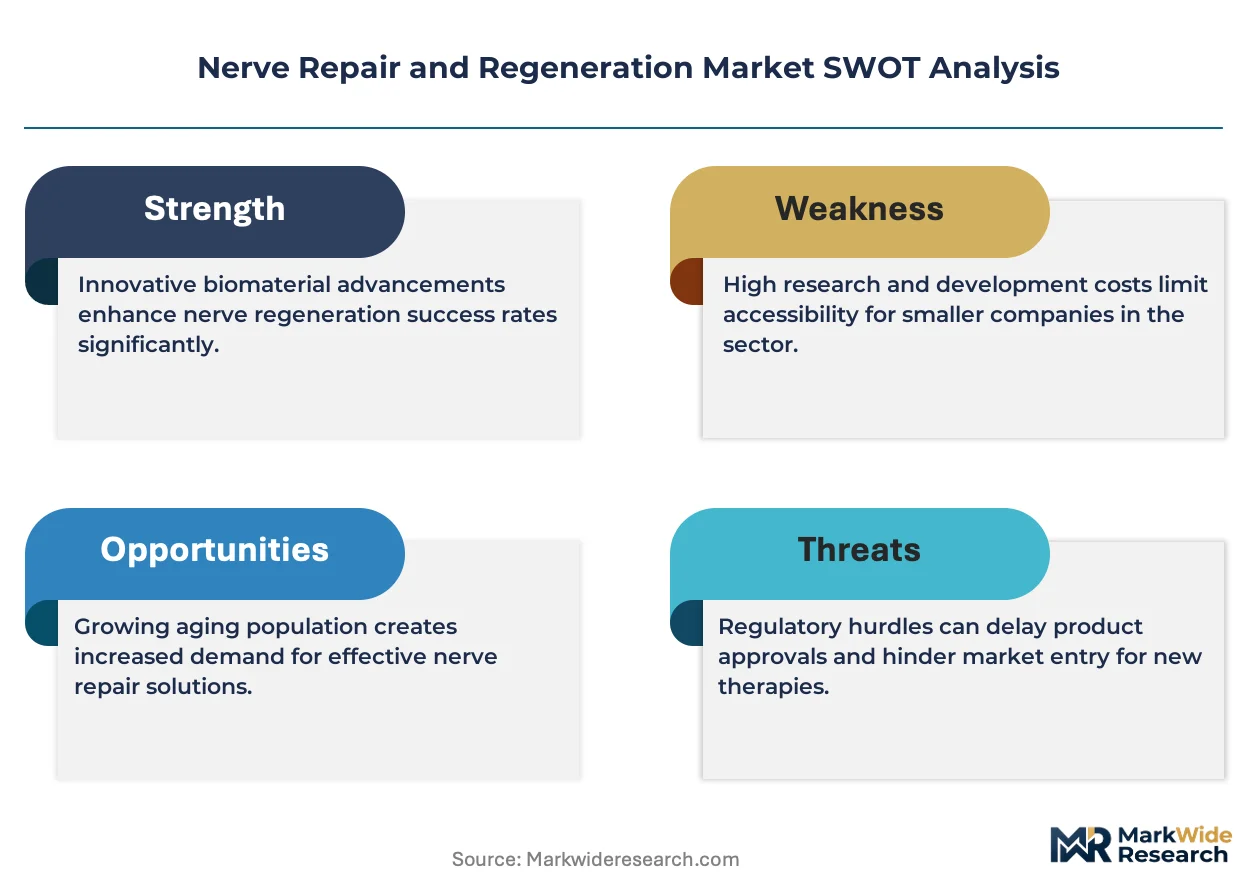
Growth Catalysts
- Accelerated Regulatory Pathways:FDA breakthrough device designation and EU MDR fast-track assessments reduce time-to-market for novel conduit materials. Switzerland's precision medical device engineering cluster attracts development-stage investment.
- Reimbursement Expansion:CMS coverage determinations now include bioengineered nerve grafts in the United States. Germany's statutory health insurance framework extends similar coverage, broadening patient access to advanced repair modalities.
- Trauma Center Consolidation:Academic medical centers and Level I trauma facilities are standardizing on advanced repair protocols. These institutions drive procedural volume concentration and technology adoption curves.
Market Restraints
- Human Tissue Supply Constraints:Peripheral nerve allograft processing depends on cadaveric tissue availability. Donor pool limitations create batch-to-batch variability and supply intermittency.
- Biopolymer Raw Material Concentration:Medical-grade collagen and chitosan production concentrates in Swiss and German chemical manufacturing corridors. Geographic supply density creates price volatility and sourcing risk.
- Technical Limitation in Gap Bridging:Autograft remains the clinical standard for nerve gaps exceeding 30 millimeters. Synthetic conduits face functional ceiling effects in large-diameter motor nerve reconstruction.
Strategic Opportunities
- Stem Cell Therapy Maturation:Clinical pipelines for Schwann cell and induced pluripotent stem cell applications are advancing through Phase II trials. These biologics target the fastest-growing investment category in peripheral nerve repair.
- Japan PMDA Sakigake Pathway:Japan's regenerative medicine fast-track designation offers priority review for novel nerve repair products. Early entrants gain regulatory precedent and pricing advantages in the world's third-largest medical device market.
- Rehabilitation Facility Channel:Adjunctive electrical stimulation protocols are migrating from hospital outpatient departments to specialized rehabilitation centers. This channel expansion creates new device placement opportunities.
Industry Challenges
- ISO 14155 Compliance Burden:Clinical investigation standards for medical devices demand extensive documentation and site qualification. Trial design complexity extends development timelines and consumes technical resources.
- Neurosurgical Skill Specialization:Microsurgical nerve repair requires fellowship-trained expertise. Talent pipeline constraints limit procedural capacity at community hospitals and smaller academic centers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nerve Repair and Regeneration Market |
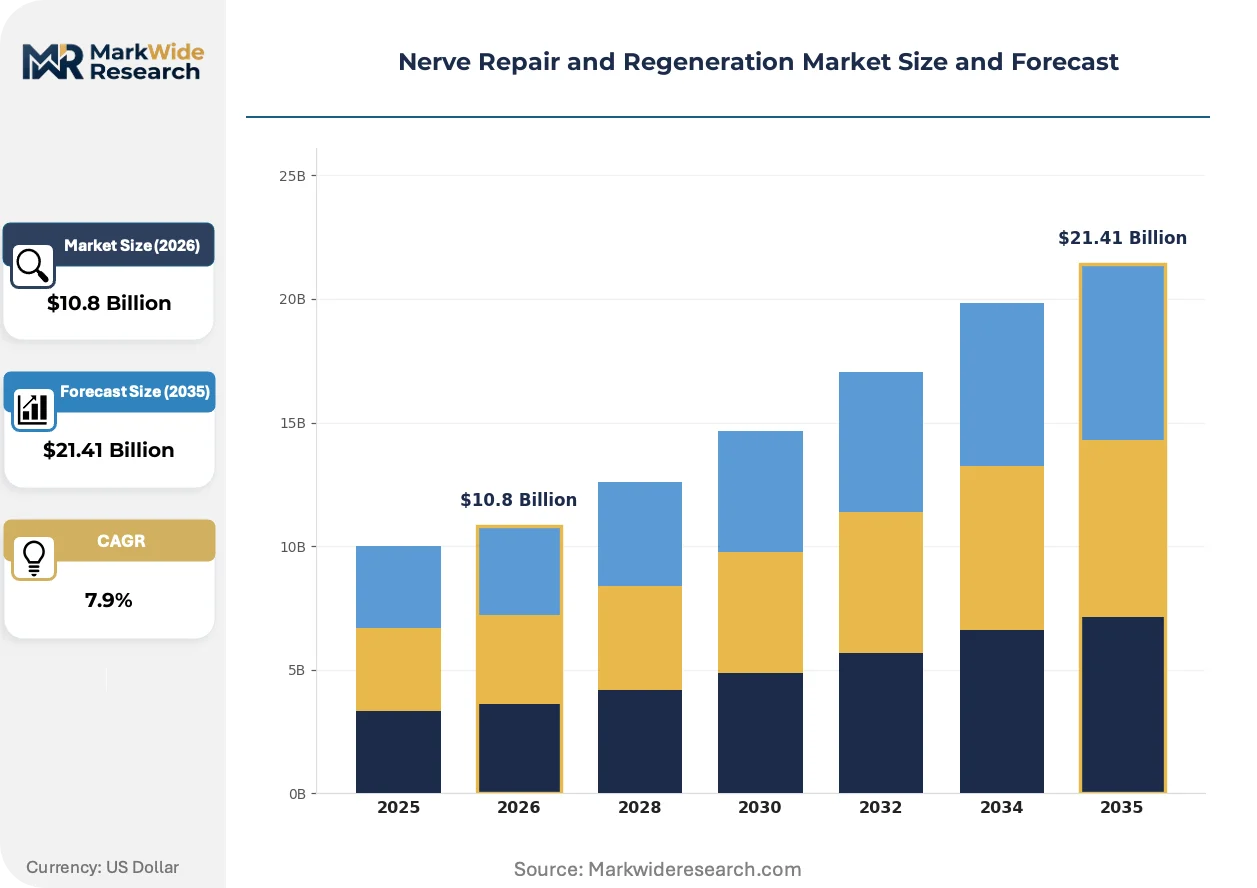
| Market Size in 2026 | $10.8 Billion |
| Market Size in 2035 | $21.41 Billion |
| CAGR (2026 – 2036) | 7.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Neurotrophic Factors, Conduits & Wraps, Stem Cell Therapy, Growth Factors, Biodegradable Scaffolds Application: Peripheral Nerve Injuries, Central Nervous System Disorders, Spinal Cord Injury, Neurodegenerative Conditions, Cranial Nerve Repair End User: Neurosurgery Centers, Rehabilitation Facilities, Research Institutes, Specialty Clinics, Academic Hospitals Delivery Mode: Injectable Formulations, Implantable Devices, Topical Applications, Bioprinting Techniques, Scaffold-Based Systems |
| Companies Covered | Integra LifeSciences Holdings Corporation, LivaNova PLC, Medtronic PLC, NeuroPace Inc., Nevro Corporation, Abbott Laboratories, AxoGen Inc., Stryker, Boston Scientific Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nerve Repair and Regeneration Market Strategic Shifts & Innovations
Digital integration is transforming how nerve repair outcomes are measured and reimbursed, while regulatory convergence and buyer consolidation reshape competitive positioning across the value chain.
Electrical stimulation monitoring systems are digitizing postoperative functional assessment protocols. Neurosurgery centers and rehabilitation facilities deploy these platforms to capture real-time nerve conduction metrics. The technology is digitizing outcome documentation for payor reporting and enabling value-based contracting structures that tie reimbursement to verified functional recovery.
EU MDR conformity assessment requirements for Class III implantable devices have intensified clinical evidence standards. Manufacturers must now submit extended follow-up data and post-market surveillance plans. The regulation most affects bioengineered nerve conduit producers, who are responding by consolidating notified body relationships and front-loading clinical trial investment.
Hospital procurement committees are consolidating vendor rosters around full-line suppliers capable of delivering conduits, wraps, and electroceutical devices under single-source agreements. This concentration displaces niche single-product vendors from formulary access. The United States exhibits this pattern most acutely, where integrated delivery networks command purchasing leverage across multiple states.
Nerve Repair and Regeneration Market Segmentation
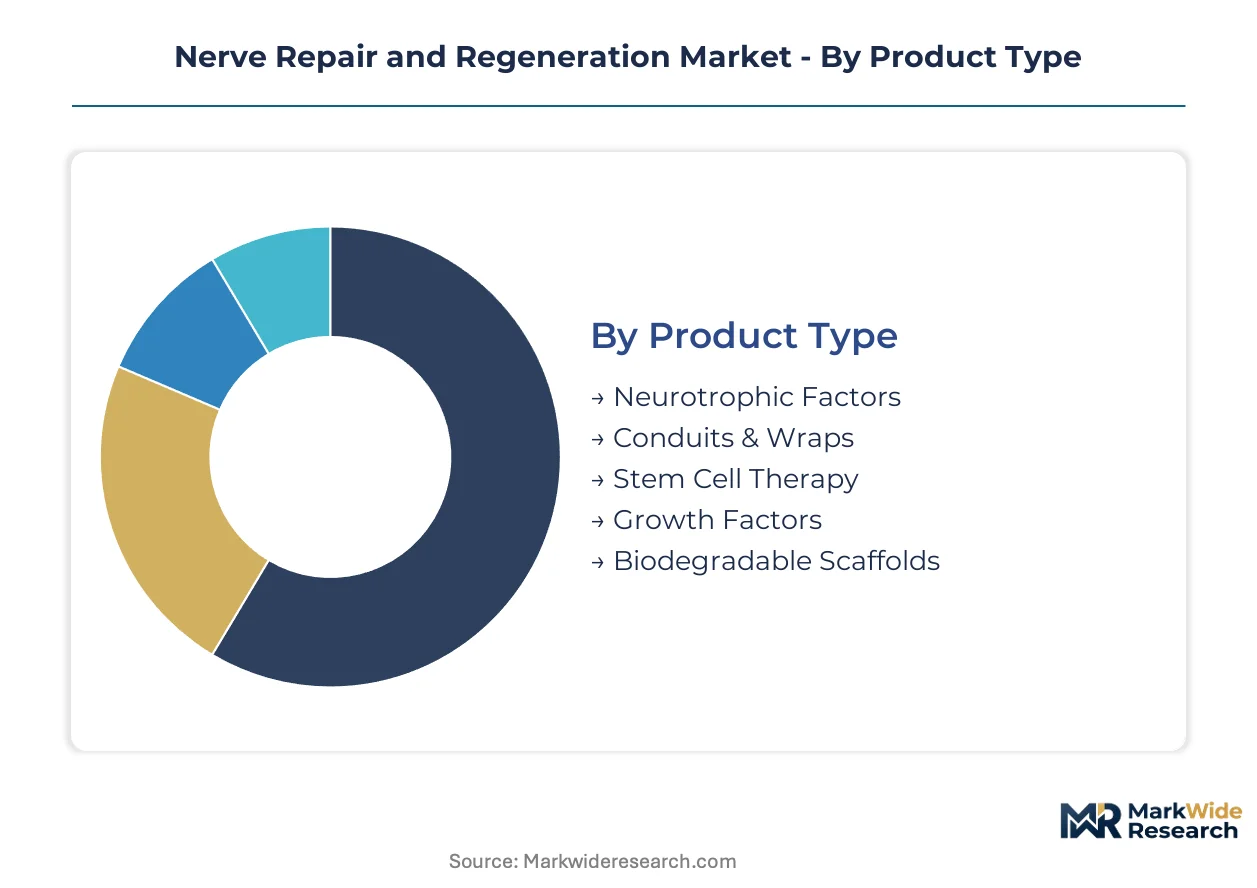
Nerve repair segmentation reveals how procedural economics and technology readiness diverge across therapeutic modalities. Product maturity ranges from established conduit systems to experimental stem cell platforms, while delivery complexity spans simple topical applications to precision implantable neurostimulation hardware.
Product Type:
Mature mechanical solutions dominate procedural volumes, though emerging biologics command premium pricing and development investment.
- Conduits & Wraps:Collagen and polyglycolic acid tubes provide temporary extracellular matrix guidance for axonal elongation across lesion gaps. Trauma centers in the United States and Germany standardize procurement around these devices due to established CMS and statutory health insurance reimbursement codes.
- Stem Cell Therapy:Schwann cell and induced pluripotent stem cell applications target functional regeneration beyond passive bridging. Clinical pipelines advancing through Phase II trials concentrate investment flows in Switzerland's precision medical device engineering cluster and Japan's regenerative medicine fast-track pathway.
- Neurotrophic Factors:Protein-based signaling molecules promote neuronal survival and axonal outgrowth through localized delivery.
- Growth Factors:Biologically active peptides accelerate nerve regeneration kinetics when incorporated into scaffold matrices.
- Biodegradable Scaffolds:Chitosan and medical-grade collagen constructs degrade in vivo as host tissue integrates.
Conduits & Wraps retain volume leadership; Stem Cell Therapy holds the steepest expansion curve.
Application:
Peripheral nerve reconstruction commands the majority of commercial activity, while central nervous system indications represent higher technical barriers and longer development horizons.
- Peripheral Nerve Injuries:Traumatic lacerations and compression neuropathies constitute the addressable surgical population. Level I trauma facilities and academic medical centers drive procedural standardization around microsurgical repair protocols with adjunctive electroceutical stimulation.
- Spinal Cord Injury:Complete and incomplete lesions require multimodal intervention combining structural grafting with neurostimulation. Japan PMDA sakigake designation attracts developers targeting this high-unmet-need population with novel regenerative constructs.
- Central Nervous System Disorders:Stroke and traumatic brain injury applications face blood-brain barrier delivery challenges.
- Neurodegenerative Conditions:Amyotrophic lateral sclerosis and multiple sclerosis represent chronic disease modification opportunities.
- Cranial Nerve Repair:Facial nerve and optic nerve reconstruction demands specialized surgical expertise.
Peripheral Nerve Injuries anchor commercial revenue; Spinal Cord Injury shows the most rapid investment acceleration.
End User:
Channel economics stratify sharply between high-acuity surgical centers and lower-intensity rehabilitation settings.
- Neurosurgery Centers:Fellowship-trained microsurgeons perform complex nerve transfers and brachial plexus reconstruction. These facilities capture the highest margins per procedure and drive adoption of advanced biologics and implantable neurostimulation platforms.
- Rehabilitation Facilities:Postoperative electrical stimulation protocols migrate to specialized centers for functional recovery optimization. CMS coverage determinations for adjunctive device therapy are expanding placement opportunities outside hospital outpatient departments.
- Academic Hospitals:Research-active institutions participate in clinical trials and early technology evaluation.
- Specialty Clinics:Hand surgery and peripheral nerve focused practices concentrate elective procedural volumes.
- Research Institutes:Preclinical development and mechanism-of-study investigations advance pipeline candidates.
Neurosurgery Centers maintain margin leadership; Rehabilitation Facilities are gaining share fastest through channel expansion.
Delivery Mode:
Route of administration determines manufacturing complexity, regulatory pathway, and reimbursement categorization.
- Implantable Devices:Electrode arrays and conduit systems require ISO 14155 clinical investigation standards and FDA 21 CFR Part 820 quality system compliance. EU MDR conformity assessments for Class III devices intensify evidence requirements and consolidate notified body relationships among manufacturers.
- Injectable Formulations:Cell suspensions and growth factor depots enable minimally precise delivery to lesion sites. Japan's regenerative medicine framework offers priority review advantages for novel injectable biologics targeting peripheral nerve gaps.
- Scaffold-Based Systems:Preformed matrices integrate structural support with bioactive payload release.
- Bioprinting Techniques:Patient-specific construct fabrication remains developmental with limited commercial penetration.
- Topical Applications:Surface delivery limits penetration depth to superficial nerve structures.
Implantable Devices dominate revenue concentration; Injectable Formulations demonstrate the sharpest upward trajectory in development pipelines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States deploys bioengineered nerve grafts at trauma centers with established CMS reimbursement, while Japan concentrates investment in regenerative medicine fast-tracks and Switzerland anchors precision manufacturing for conduit materials.
United States
Level I trauma facilities and academic medical centers drive procedural standardization for microsurgical nerve repair. FDA breakthrough device designation compresses time-to-market for novel conduit materials. The Greater Boston and San Francisco Bay Area clusters host development-stage companies advancing electrode array technologies.
Germany
Statutory health insurance coverage for bioengineered nerve grafts broadens patient access to advanced repair modalities. EU MDR conformity assessments intensify clinical evidence requirements for Class III implantable devices. The Baden-Württemberg precision engineering corridor concentrates medical-grade collagen and chitosan production capacity.
Switzerland
Concentrated biopolymer manufacturing and precision medical device engineering attract development-stage investment flows. Swissmedic regulates novel nerve conduit materials through accelerated assessment pathways. The Basel-Zurich corridor integrates chemical manufacturing with medical technology commercialization infrastructure.
Japan
PMDA sakigake fast-track designation offers priority review for regenerative medicine products targeting peripheral nerve gaps. METI coordinates national investment in stem cell therapy clinical pipelines. The Kansai region anchors induced pluripotent stem cell research translation into commercial nerve repair applications.
Nerve Repair and Regeneration Market Key Industry Players
Capability concentration sits with specialized tissue processors and precision engineering clusters; scale advantage sits with diversified medical technology conglomerates with neuromodulation infrastructure. The market structure tiers between full-line suppliers capable of delivering conduits, wraps, and electroceutical devices under single-source agreements, and niche single-product vendors facing procurement committee consolidation. Strategic archetypes include diversified medtech conglomerates with neurostimulation platforms, specialized allograft processors with cadaveric tissue supply chains, and precision engineering firms with biopolymer manufacturing capabilities. Competitive moves concentrate on M&A to secure tissue processing capabilities and strategic partnerships to access Japan's regenerative medicine fast-track pathway.
Within the diversified medtech tier, Medtronic PLC and Boston Scientific Corporation exemplify scale-driven positioning through neuromodulation infrastructure. AxoGen Inc. represents the specialized allograft processing archetype, anchoring the peripheral nerve graft segment with human tissue nerve graft capabilities. These three companies illustrate the capability-scale spectrum: conglomerate neuromodulation platforms versus focused tissue engineering specialization.
| Leading Market Players |
|---|
| Integra LifeSciences Holdings Corporation |
| LivaNova PLC |
| Medtronic PLC |
| NeuroPace Inc. |
| Nevro Corporation |
| Abbott Laboratories |
| AxoGen Inc. |
| Stryker |
| Boston Scientific Corporation |
| Others |
Cost & Logistics Intelligence
The Rhine-Alpine freight corridor's cost dynamics amplify supply concentration effects across medical-grade biopolymer sourcing while downstream price differentiation stratifies between trauma center procurement committees and rehabilitation facility buyers. Switzerland and Germany anchor collagen and chitosan production, compressing margins for conduit manufacturers distant from these chemical manufacturing clusters.
Pricing Analysis
Long-term offtake agreements dominate procurement between trauma centers and full-line suppliers, though spot purchasing persists for experimental stem cell platforms. Three-tier pricing structure across premium, standard, and economy levels differentiates by FDA breakthrough designation status and ISO 14155 compliance tier. Cost compression in standard-grade conduits intensifies because procurement committees consolidate vendor rosters. Rehabilitation facilities exhibit highest price sensitivity; neurosurgery centers absorb premium pricing for advanced biologics.
Supply Chain Analysis
Tariff exposure between Switzerland and Germany dominates supply chain risk planning for medical-grade collagen feedstocks. Raw material sourcing draws from Swiss biopolymer manufacturers, German chemical processors, and Japanese regenerative medicine suppliers. Single-source vulnerability concentrates in cadaveric tissue processing for peripheral nerve allografts. Distribution runs through integrated delivery networks commanding multi-state purchasing leverage.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The nerve repair and regeneration market is exiting a regulatory compliance cycle that compressed development timelines, with FDA breakthrough designations and EU MDR pathways now enabling cyclical recovery in product launch velocity.
For Market Incumbents: Harden notified body relationships against EU MDR conformity assessment bottlenecks while securing captive supply of medical-grade chitosan through backward integration into Swiss chemical manufacturing. Consolidate procurement committee access by bundling conduits, wraps, and electroceutical devices under single-source agreements that displace niche competitors. For New Entrants and Emerging Players: Build out Japan PMDA sakigake pathway expertise to capture priority review advantages for novel injectable biologics targeting peripheral nerve gaps. Rehabilitation facilities represent the most penetrable channel for adjunctive electrical stimulation protocols. Partner with academic medical centers for clinical trial site qualification under ISO 14155 standards. For Investors and Strategic Acquirers: Specialized allograft processors with secured cadaveric tissue supply chains offer acquisition targets with defensible processing capabilities. Long-term viability centers on stem cell therapy maturation across the analysis window. Monitor CMS coverage determinations for bioengineered nerve constructs as the inflection signal for reimbursement-driven volume expansion.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Designation Pursuit | Compresses time-to-market for novel conduit materials against standard PMA pathways. |
| EU MDR Notified Body Consolidation | Front-loads clinical evidence investment for Class III implantable device conformity. |
| Japan PMDA Sakigake Registration | Secures priority review and pricing advantages in regenerative medicine categories. |
| Trauma Center Procurement Integration | Captures volume concentration through single-source agreements with Level I facilities. |
| Rehabilitation Facility Channel Expansion | Places adjunctive electrical stimulation devices outside hospital outpatient departments. |
Research Approach
Initial hypotheses were tested against primary input from microsurgical nerve repair specialists, hospital purchasing committee directors, biomedical engineers at trauma centers, and regulatory affairs leads at conduit manufacturers, then refined through secondary validation across FDA 510(k) filings, EU MDR notified body assessment reports, CMS coverage determination databases, and hospital procurement contract repositories. Bottom-up procedural volume estimates triangulated against top-down market sizing from reimbursement code analysis.
Demand-supply-balance framing anchored the analytical framework across the projection horizon, modeling segmentation by product type, application, end user, and delivery mode alongside regulatory pathway tier. CAGRs derived from procedure volume trajectories and pricing elasticity by channel. Industry-specific inputs included cadaveric tissue supply forecasts and PMDA sakigake approval velocity assumptions.
Stress conditions across donor pool variability, biopolymer raw material price volatility, and reimbursement coverage expansion timelines were modeled; outcomes outside those bands fall beyond the analytical envelope. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Epilepsy Devices Market
Medical Devices
Vaginal Inserts Market
Medical Devices
Global Intraosseous Devices Market
Medical Devices
Smart Syringe Pumps Market
Medical Devices
ECG Telemetry Devices Market
Medical Devices
Syringe Scale Magnifiers Market
Medical Devices
Breathing Circuits Market
Medical Devices
Needle-Free Injectors Market
Medical Devices
Asia-Pacific Bathroom and Toilet Assist Devices Market
Medical Devices
Fluorescence-Guided Surgery Systems Market
Medical Devices
Polyethersulfone Dialyzer Market
Medical Devices
Spinal Fusion Market
Medical Devices
North America Biopsy Devices Market
Medical Devices
Pet Mobility Aids Market
Medical Devices
Transcatheter Aortic Valve Implantation (TAVI) Market
Medical Devices
Ultrasound Biometry Devices Market