
 Global Glucometer Market | 2026-2036
Global Glucometer Market Size, Share, and Industry Trends Forecast 2026-2036
Global Glucometer Market Analysis
The glucometer market is decoupling into premium continuous glucose monitoring ecosystems and commodity strip-based devices. Abbott Laboratories leverages vertically integrated sensor manufacturing to sustain leadership in factory-calibrated systems. Dexcom differentiates through algorithm-intensive real-time glucose prediction, while Sinocare competes aggressively on cost-optimized electrochemical strip production for price-sensitive markets.
A glucometer measures blood glucose concentration through electrochemical or optical analysis of capillary blood samples, typically requiring sample volumes between 0.3 and 1.0 microliters and producing results within five seconds for clinical decision-making. Continuous glucose monitoring systems lead technology growth due to reimbursement expansion and reduced fingerstick burden, while enzymatic electrochemical strips anchor volume in emerging markets where cost constraints dominate purchasing. Homecare channels capture the fastest expansion as pharmacy and online distribution enable direct patient procurement without clinic visits.
FDA premarket notification requirements and EMA medical device regulation enforce accuracy standards that filter out subperforming entrants, while ISO 15197 compliance mandates minimum precision thresholds for over-the-counter sales. India's CDSCO and China's NMPA have tightened local manufacturing audits, redirecting supply chain investment toward certified domestic facilities. Stakeholders must monitor evolving reimbursement codes for non-adjunctive CGM use and prepare for interoperability mandates that will determine which platforms capture integrated health system contracts.
Market Dynamics
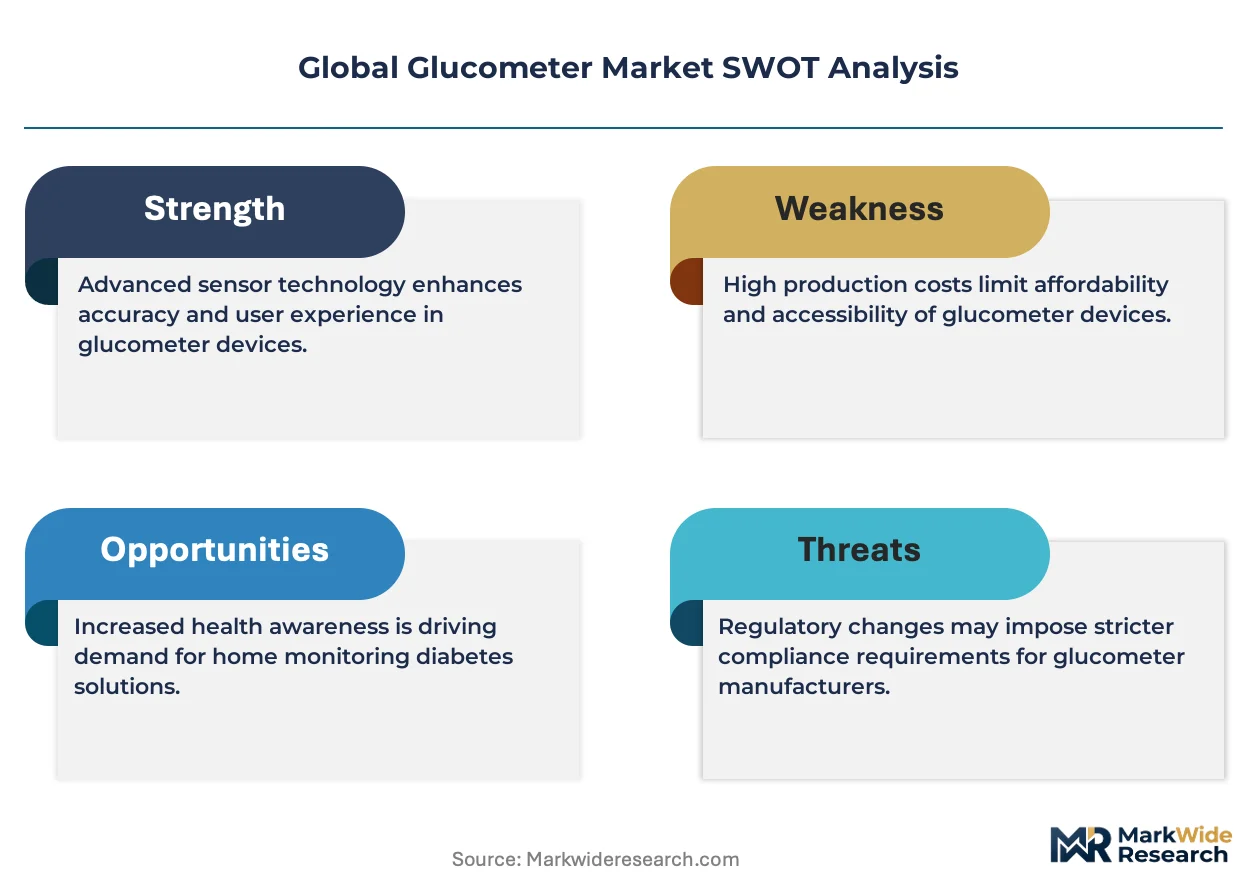
The glucometer market is fragmenting into two incompatible supply chains: factory-calibrated continuous glucose monitoring systems requiring pharmaceutical-grade sensor manufacturing, and electrochemical strip production optimized for high-volume, low-margin distribution through pharmacy retail.
Growth Catalysts
- Non-adjunctive CGM reimbursement:CMS and private payers in the United States now cover real-time glucose data for insulin dosing decisions without confirmatory fingersticks, expanding the addressable patient population beyond Type 1 diabetes.
- Electrochemical strip cost engineering:Automated screen-printing of enzyme electrodes onto polymer substrates has reduced per-test manufacturing costs below $0.05 in certified Indian and Chinese facilities, unlocking mass-market penetration.
- Homecare channel expansion:Direct-to-patient e-commerce platforms and pharmacy self-selection are eliminating clinic-based distribution layers, shortening replenishment cycles for consumable strips.
Market Restraints
- Precious metal input volatility:Palladium and silver prices in electrode formulations create margin compression for strip manufacturers unable to pass through commodity swings.
- Sensor supply concentration:Factory-calibrated CGM systems depend on three specialized polymer substrate suppliers in Germany and the United States, creating single-source vulnerability.
- Accuracy ceiling in hypoglycemic range:Electrochemical enzymatic methods lose precision below 70 mg/dL, limiting clinical trust for intensive insulin management.
Strategic Opportunities
- Underpenetrated rural India:CDSCO streamlined medical device registration for Class B glucometers, reducing time-to-market for domestic manufacturers targeting tier-3 cities and village health centers.
- Interoperability mandates:FDA guidance on integrated continuous glucose monitoring and automated insulin delivery systems creates platform lock-in potential for ecosystem providers.
- Subscription-based replenishment:Connected meter platforms with automatic strip reordering are capturing recurring revenue streams and patient adherence data previously lost to retail pharmacy.
Industry Challenges
- Biocompatibility certification timelines:ISO 10993 testing for implantable CGM sensors extends development cycles by 18-24 months, delaying competitive response.
- Algorithm validation complexity:Machine learning-based glucose prediction requires retrospective clinical studies across diverse glycemic phenotypes, straining regulatory submission resources.
- Legacy meter data migration:Health systems consolidating onto interoperable platforms face technical friction extracting historical readings from proprietary closed systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Glucometer Market |
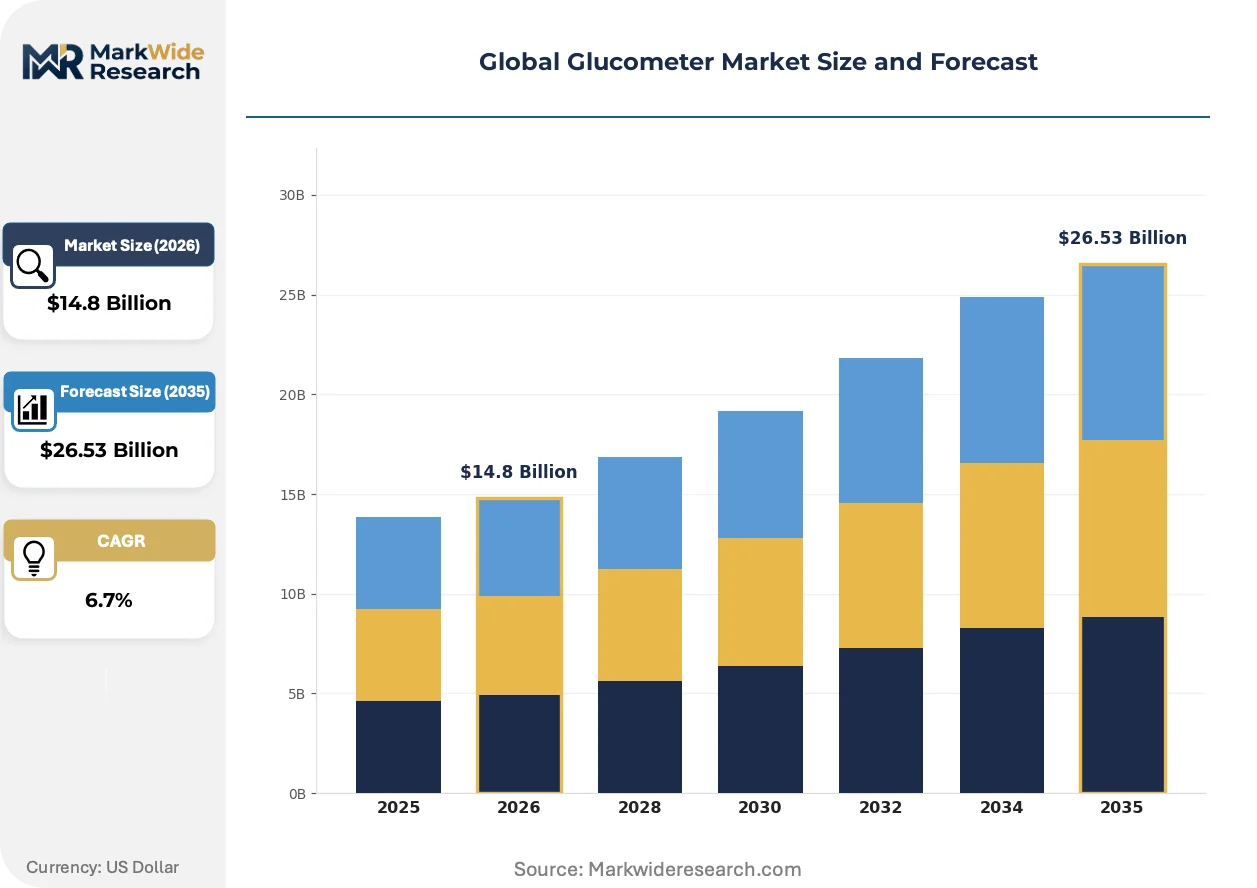
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $26.53 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automatic, Manual, Continuous Glucose Monitoring, Smart Glucometers Technology: Enzymatic, Non-Enzymatic, Optical, Capacitive End User: Hospitals, Homecare, Diabetes Clinics, Pharmacies Distribution Channel: Retail, Online, Direct Sales, Wholesalers |
| Companies Covered | Abbott Laboratories, Dexcom, Inc., Medtronic, F. Hoffmann-La Roche Ltd, Ascensia Diabetes Care, LifeScan, Inc., Sinocare, Arkray, Inc., i-SENS, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Glucometer Market Emerging Trajectories
Sensor architecture and data infrastructure are converging to enable closed-loop diabetes management, while distribution models compress toward patient-direct fulfillment. Three developments are restructuring competitive position.
Factory-calibrated continuous glucose monitoring is modularizing the traditional glucometer value chain by separating sensor production, algorithm development, and data platform operation into distinct competitive arenas. Endocrinology practices and integrated health systems are adopting these systems at replacement rates exceeding legacy meter obsolescence cycles. This modularity is compressing margins for standalone strip manufacturers while enabling software-centric entrants to capture value through predictive analytics layers.
EMA Medical Device Regulation and FDA software-as-medical-device guidance are tightening clinical evidence requirements for glucose prediction algorithms. Manufacturers must now submit prospective validation data across diverse demographic glycemic patterns before securing clearance. Class III CGM systems face the steepest compliance burden, while Class IIb strip-based meters navigate streamlined conformity assessment pathways in Europe.
Patients are consolidating purchasing decisions onto pharmacy benefit manager formularies and employer-sponsored digital health platforms, displacing discretionary retail selection. This channel compression concentrates volume with contracted suppliers capable of integrated data reporting and population health analytics. The United States exhibits the most pronounced consolidation, where three national PBMs control reimbursement access for connected monitoring devices.
Global Glucometer Market Segmentation
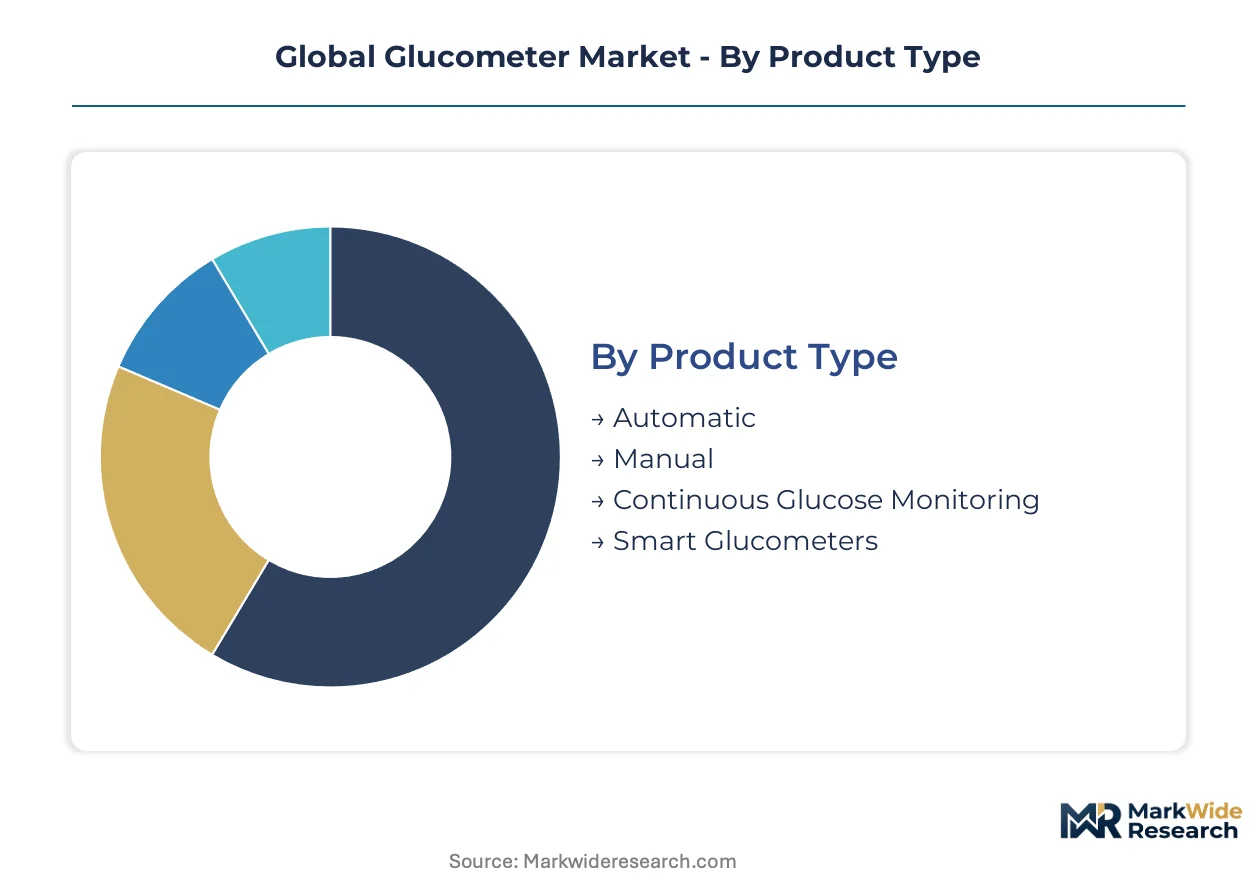
Glucometer segmentation reveals divergent commercial logics between precision-intensive hospital procurement and volume-driven patient-direct channels. Manufacturers must align R&D investment and regulatory strategy to the specific performance thresholds and price elasticity of each segment cluster.
Product Type:
Price sensitivity and reimbursement status determine device selection across patient populations and care settings.
- Continuous Glucose Monitoring:Factory-calibrated sensors transmit interstitial glucose readings every 1-5 minutes without fingerstick calibration. CMS non-adjunctive coverage in the United States and EMA Medical Device Regulation clearance in Germany are expanding patient eligibility beyond Type 1 diabetes into intensive Type 2 insulin management.
- Smart Glucometers:Bluetooth-enabled strip meters sync with mobile applications for pattern recognition and automatic logbook generation. Pharmacy benefit manager formularies in the United States and direct-to-patient e-commerce in India are capturing recurring revenue through subscription replenishment models.
- Automatic:Electrochemical strip meters with coded chip calibration dominate retail pharmacy distribution.
- Manual:Basic digital readouts without connectivity serve price-sensitive markets with minimal reimbursement.
Volume sits with automatic strip-based systems; growth tilts toward continuous glucose monitoring.
Technology:
Accuracy requirements and manufacturing scale shape competitive positioning across detection methodologies.
- Enzymatic:Glucose oxidase or glucose dehydrogenase electrodes catalyze electron transfer proportional to blood glucose concentration. Automated screen-printing in certified Indian and Chinese facilities has driven per-test costs below five cents, unlocking mass-market penetration in tier-3 cities and village health centers.
- Optical:Near-infrared spectroscopy and colorimetric methods enable non-invasive measurement approaches. Research programs at METI-funded institutes in Japan and FDA breakthrough device designations in the United States are advancing clinical validation for transdermal glucose estimation.
- Non-Enzymatic:Direct electrochemical detection using metal nanoparticles eliminates enzyme degradation and temperature sensitivity.
- Capacitive:Impedance-based sensing enables label-free glucose detection for emerging wearable formats.
Enzymatic methods command current volume leadership; optical platforms are climbing the fastest toward commercial viability.
End User:
Care setting determines accuracy specifications, connectivity requirements, and procurement authority structures.
- Homecare:Patients self-monitor through pharmacy, online, or direct-to-consumer channels without clinical intermediation. India's CDSCO streamlined Class B device registration, reducing domestic manufacturer time-to-market for direct patient procurement in tier-2 and tier-3 urban centers.
- Hospitals:Acute care settings demand laboratory-grade precision with integrated electronic health record connectivity. FDA premarket notification and ISO 15197 compliance filter out subperforming entrants from institutional purchasing contracts in the United States and Germany.
- Diabetes Clinics:Specialist endocrinology practices drive continuous glucose monitoring adoption through integrated insulin delivery ecosystems.
- Pharmacies:Retail dispensing captures walk-in replenishment for strip-based meter consumables.
Pharmacy and clinic channels anchor current volume; homecare is gaining share fastest as direct-to-patient platforms eliminate distribution layers.
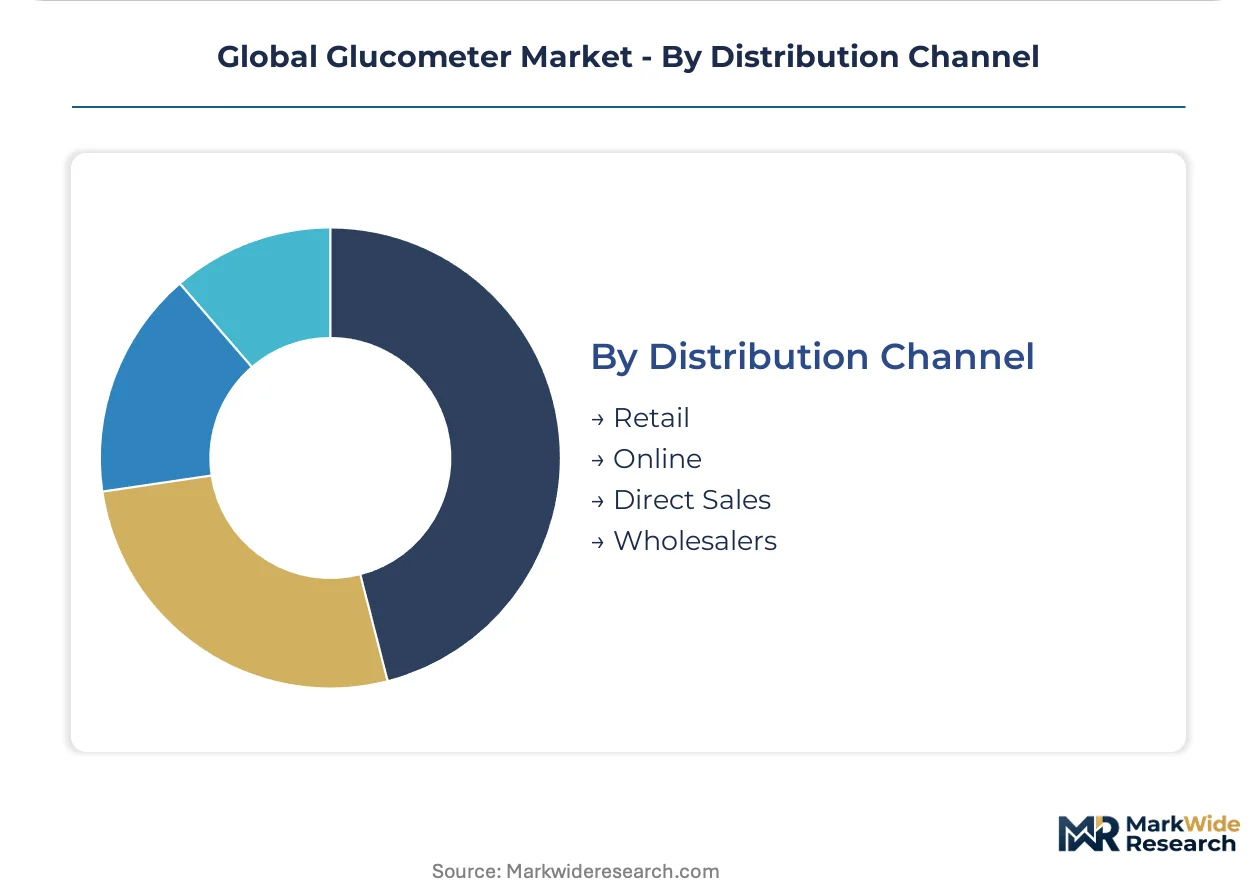
Distribution Channel:
Channel selection determines margin structure, patient adherence data capture, and competitive moat durability.
- Online:Direct-to-patient e-commerce platforms enable automatic replenishment, subscription pricing, and integrated health data services. China's NMPA tightened cross-border e-commerce medical device rules, redirecting supply chain investment toward certified domestic fulfillment centers.
- Retail:Pharmacy self-selection dominates emerging market volume through immediate availability and pharmacist counseling. Wholesaler consolidation in Germany and the United States concentrates volume with three national distributors capable of cold-chain logistics and inventory financing.
- Direct Sales:Manufacturer field forces serve integrated health systems with population health analytics and interoperability commitments.
- Wholesalers:Regional distributors bridge fragmented pharmacy networks in underpenetrated rural markets.
Retail pharmacy commands present volume concentration; online channels show the steepest expansion trajectory as platform lock-in replaces transactional purchasing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
San Diego anchors continuous glucose monitoring development through Dexcom's algorithm-intensive operations and adjacent sensor manufacturing clusters. FDA non-adjunctive reimbursement rulings and CMS coverage determinations radiate from Washington regulatory corridors, shaping competitive access across North American markets.
United States
Pharmacy benefit manager formularies concentrate procurement decisions with three national PBMs controlling connected device reimbursement. FDA premarket notification pathways and software-as-medical-device guidance enforce clinical evidence standards for glucose prediction algorithms. The Minneapolis medical device corridor hosts integrated insulin delivery ecosystem development.
Germany
EMA Medical Device Regulation clearance pathways filter market entry for factory-calibrated systems destined for hospital procurement. ISO 15197 compliance mandates shape over-the-counter electrochemical strip distribution through pharmacy networks. The Baden-Württemberg polymer substrate cluster supplies specialized sensor materials to CGM manufacturers.
India
CDSCO streamlined Class B device registration accelerates domestic manufacturer time-to-market for tier-3 cities and village health centers. Government diabetes screening program expansion drives volume demand for cost-optimized electrochemical strips. Ahmedabad and Hyderabad industrial zones concentrate automated screen-printing operations for enzyme electrode production.
China
NMPA tightened cross-border e-commerce medical device rules redirect supply chain investment toward certified domestic fulfillment centers. Dual carbon goals influence manufacturing facility energy sourcing for high-volume strip production. The Yangtze River Delta cluster integrates polymer substrate processing with downstream meter assembly.
Japan
METI-funded research institutes advance optical non-invasive glucose measurement toward clinical validation. PMDA consultation pathways guide breakthrough device designations for transdermal sensing technologies. The Kansai corridor maintains precision electrochemical manufacturing for laboratory-grade hospital meters.
Global Glucometer Market Vendor Landscape
Premium-margin players sit above commodity-margin players across algorithm sophistication and sensor manufacturing integration. The market structures into three tiers: pharmaceutical-grade CGM ecosystems, connected strip-based platforms, and basic electrochemical devices. Strategic archetypes include vertically integrated sensor manufacturers, algorithm-specialist software platforms, and high-volume strip fabricators. Dominant competitive moves encompass M&A for sensor substrate supply security and strategic partnerships for automated insulin delivery interoperability.
Within the premium CGM tier, Abbott Laboratories and Dexcom occupy positions defined by factory-calibrated manufacturing scale and predictive analytics depth. Among diversified health technology conglomerates, Medtronic anchors integrated diabetes management ecosystem development. F. Hoffmann-La Roche Ltd exemplifies the diagnostic-focused archetype with established laboratory and point-of-care glucose testing heritage.
| Leading Market Players |
|---|
| Abbott Laboratories |
| Dexcom, Inc. |
| Medtronic |
| F. Hoffmann-La Roche Ltd |
| Ascensia Diabetes Care |
| LifeScan, Inc. |
| Sinocare |
| Arkray, Inc. |
| i-SENS, Inc. |
| Others |
Supply Flow & Price Mechanics
Private-equity-rolled-up strip manufacturers in India and China anchor volume-tier supply while compressing per-test economics below five cents, forcing factory-calibrated CGM producers to defend premium positioning through algorithm lock-in and sensor substrate ownership rather than cost competition.
Pricing Analysis
Value-based pricing anchors on clinical outcomes and insulin-dosing confidence rather than hardware cost, with subscription models for continuous glucose monitoring capturing recurring revenue through automatic sensor replenishment. Price differentiation rests on FDA clearance tier, factory-calibration capability, and predictive algorithm sophistication. Cost compression in electrochemical strip tiers intensifies as automated screen-printing scales in certified Indian facilities. Homecare patients in tier-3 cities exhibit highest price sensitivity; integrated health systems in Germany and the United States show lowest sensitivity due to reimbursement insulation.
Supply Chain Analysis
Single-source vulnerability sits with specialized polymer substrate suppliers in Germany and the United States that feed factory-calibrated CGM sensor production. Manufacturing concentrates in China for high-volume strip fabrication, India for cost-optimized enzyme electrode printing, and Germany for precision substrate processing. Raw material dependencies include palladium and silver for electrode formulations, glucose oxidase enzymes, and pharmaceutical-grade polymers. Commodity price volatility in precious metals creates margin compression for strip manufacturers. Distribution runs through pharmacy benefit manager formularies in the United States, direct-to-patient e-commerce platforms in India, and retail pharmacy networks in Germany.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Continuous glucose monitoring systems are displacing legacy strip-based meters as the clinical standard for intensive insulin management, creating asymmetric pressure on commoditized manufacturers.
For Market Incumbents: Lock in sensor substrate supply through captive production or long-term offtake agreements with Baden-Württemberg polymer specialists to defend against single-source disruption. Secure FDA interoperability clearance for automated insulin delivery integration before rival platforms capture health system contracts, as algorithm-validated prediction becomes the primary switching cost for endocrinology practices.
For New Entrants and Emerging Players: Tier-3 cities and village health centers in India represent the most penetrable buyer archetype, with CDSCO's streamlined Class B registration reducing regulatory friction for domestic manufacturers. Target cost-optimized electrochemical strips with Bluetooth connectivity for pharmacy-direct procurement, leveraging subscription replenishment models to capture patient adherence data absent from retail transactions.
For Investors and Strategic Acquirers: CMS non-adjunctive reimbursement expansion is the leading indicator that factory-calibrated CGM addressable population is broadening beyond Type 1 diabetes into intensive Type 2 management. Over the medium-term horizon, vertically integrated sensor manufacturers with algorithm development capabilities present superior acquisition profiles. Watch for FDA breakthrough device designations in optical non-invasive sensing as the signal that transdermal glucose estimation is approaching commercial viability.
| Strategic Initiative | Industry Significance |
|---|---|
| Reimbursement Strategy | CMS non-adjunctive coverage decisions determine patient eligibility expansion for factory-calibrated systems. |
| Sensor Substrate Backward Integration | Captive polymer processing in Germany or the United States eliminates single-source supply vulnerability. |
| Interoperability Certification | FDA clearance for integrated CGM-insulin pump systems creates platform lock-in with health system purchasers. |
| Direct-to-Patient E-Commerce Launch | Subscription replenishment models in India capture recurring revenue and adherence data from pharmacy displacement. |
| Algorithm Validation Investment | Prospective clinical studies across diverse glycemic phenotypes satisfy EMA MDR and FDA software-as-medical-device requirements. |
Methodological Framework
Multi-period observation of regulatory clearance timelines, reimbursement code expansions, and sensor manufacturing capacity buildouts anchored the trend analysis, supplemented by interviews with biomedical engineers at CGM manufacturers, hospital purchasing committee members, formulary directors at pharmacy benefit managers, and regulatory affairs leads navigating FDA premarket notification pathways. Secondary validation drew from FDA 510(k) filings, EMA medical device regulation submissions, CMS national coverage determinations, ISO 15197 compliance databases, and hospital procurement contract disclosures. Bottom-up patient population modeling and top-down manufacturer revenue triangulation converged on segment estimates.
Segment-weighting across product type, technology platform, end-user setting, and distribution channel shaped the analytical framework, with continuous glucose monitoring, smart glucometers, automatic strip meters, and manual devices each carrying distinct growth profiles over the projection horizon. CAGRs were derived from installed base expansion rates, replacement cycle compression, and reimbursement elasticity modeling. Forecast inputs included sensor manufacturing yield curves, electrochemical strip cost-down trajectories, and algorithm validation study completion rates.
Revisions become necessary when FDA interoperability guidance shifts, CMS reimbursement determinations alter coverage criteria, or precious metal commodity spikes disrupt electrode cost structures. Forecasts reflect documented assumptions about regulatory pathway durations and manufacturing scale-up timelines. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Transcranial Magnetic Stimulation System Market
Medical Devices
Global Hydrocephalus Shunts Market
Medical Devices
Electrosurgery Devices Market
Medical Devices
Injectable Drug Delivery Market
Medical Devices
Cannula Market
Medical Devices
Middle East and Africa Orthotic Devices Market
Medical Devices
Vortex Mixer Market
Medical Devices
Global Infusion Pump Software Market
Medical Devices
Medical Germicidal Lamps Market
Medical Devices
Vein Illumination Devices Market
Medical Devices
North America Sperm Separation Devices Market
Medical Devices
Concentrator O2 Devices Market
Medical Devices
Digital X-Ray Devices Market
Medical Devices
MRI Compatible IV Infusion Pumps Market
Medical Devices
Vaginal Specula Market
Medical Devices
Bone Fixation Plates Market