
 Smart Syringe Pumps Market | 2026-2036
Smart Syringe Pumps Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Syringe Pumps Market Outlook
ISO 80601-2-24 certification for infusion pump safety is redrawing competitive boundaries, forcing smaller manufacturers to absorb substantial compliance costs before entering commercial channels. Fresenius Kabi AG leverages its European manufacturing footprint to sustain dual-continent certification efficiency. BD anchors its position through deep integration with hospital electronic medical record systems, while B. Braun Melsungen differentiates via specialization in anesthesia workstation compatibility.
A smart syringe pump is a precision electromechanical device that delivers controlled volumes of medication or fluid through a syringe mechanism, typically achieving flow accuracy within plus or minus two percent across microliter-to-milliliter ranges. The instrument serves critical therapeutic functions in settings requiring exact dosing, including chemotherapy administration, pediatric nutrition, and intraoperative drug delivery. Syringe pumps command premium positioning within the product type taxonomy due to their indispensability in neonatal and anesthesia applications where volumetric precision prevents adverse events. Wireless connectivity represents the fastest-expanding technology segment, though smart monitoring functionality captures disproportionate margin pools as hospitals prioritize alarm management and dose error reduction software. Pediatric care and chemotherapy applications generate the highest replacement velocity, driven by institutional risk management protocols and liability exposure.
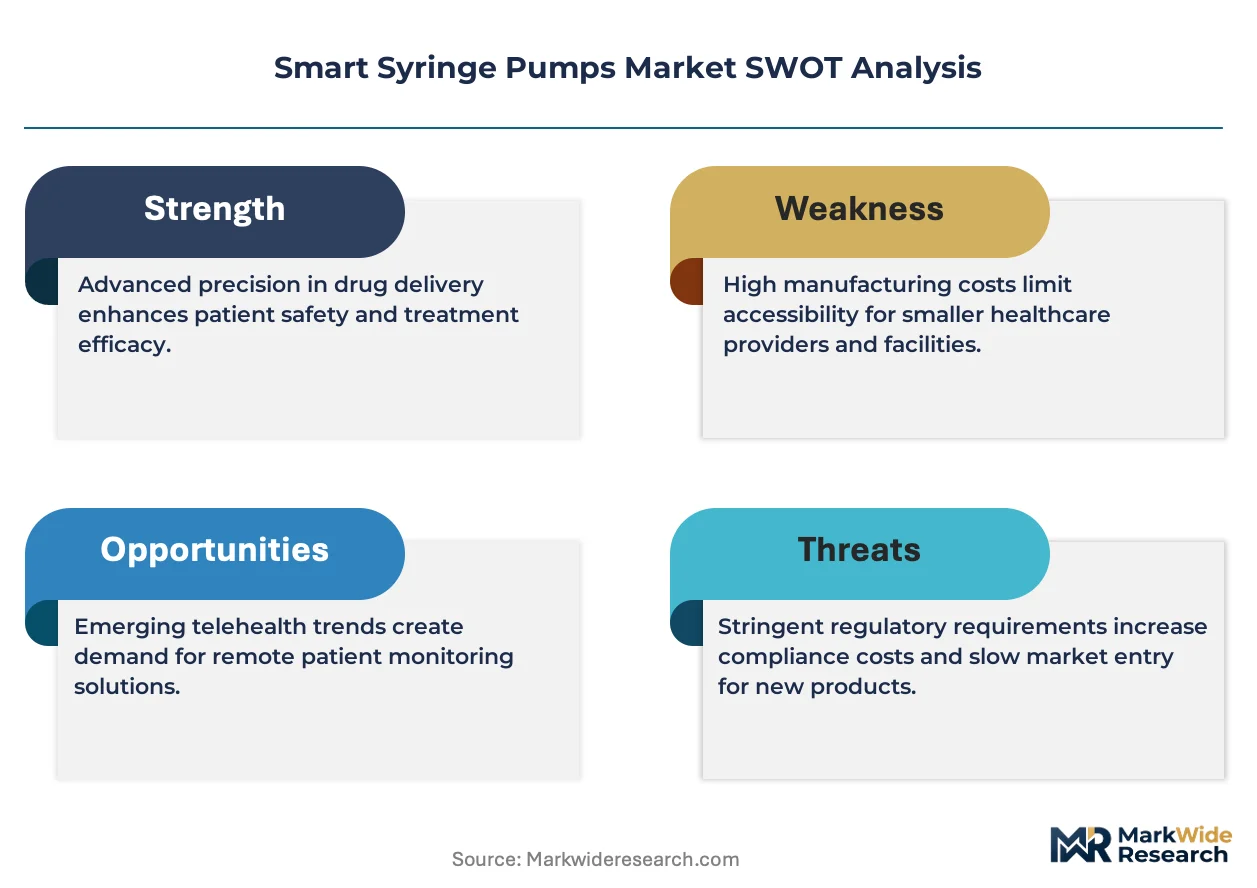
FDA 510(k) clearance timelines and EU MDR technical documentation requirements are extending product development cycles, advantaging established registrants with dedicated regulatory affairs infrastructure. The FDA's emphasis on cybersecurity premarket submissions under its 2014 and subsequent guidance documents is forcing architectural redesigns of wireless-enabled pump platforms. Stakeholders must evaluate whether to absorb escalating compliance costs internally or exit connectivity features that trigger enhanced scrutiny, as this choice will determine competitive viability in hospital procurement decisions over the coming decade.
Market Dynamics
Hospital consolidation across integrated delivery networks is compressing procurement cycles and privileging vendors with enterprise-scale service infrastructure over point-product specialists. This concentration dynamic is redrawing competitive boundaries faster than raw technology differentiation.
Growth Catalysts
- EU MDR technical documentation mandates:Stricter post-market surveillance requirements are accelerating replacement of legacy pump fleets in German and French tertiary centers, creating upgrade windows for certified suppliers.
- Neonatal intensive care units:Microliter-precision dosing requirements in preterm infant nutrition protocols are expanding syringe pump deployment beyond traditional anesthesia applications.
- Wireless connectivity modules:Real-time alarm integration with nurse call systems is becoming a non-negotiable specification in United States hospital RFPs.
Market Restraints
- Specialized stepper motor supply:Precision motor manufacturing concentrates in East Asian component suppliers, exposing OEMs to single-source vulnerability and extended lead times.
- FDA 510(k) software validation:Cybersecurity premarket submission requirements under 2014 and subsequent guidance documents are extending development timelines by 12-18 months for wireless-enabled platforms.
- Volumetric infusion pumps:Lower-cost peristaltic alternatives retain share in general medicine wards where microliter precision is not clinically mandated.
Strategic Opportunities
- Home-based chemotherapy:Outpatient infusion protocols in the United States are creating demand for portable, battery-backed syringe pumps with remote monitoring capabilities.
- ISO 80601-2-24 harmonization:Convergence of electrical safety and alarm standards across jurisdictions is enabling single-SKU global product strategies for compliant manufacturers.
- Artificial intelligence dosing libraries:Machine learning integration with drug error reduction software represents unclaimed margin pools in high-acuity settings.
Industry Challenges
- Embedded systems cybersecurity expertise:Shortage of firmware engineers with FDA-validated secure coding experience is constraining connected product roadmaps.
- Legacy EMR interoperability:Proprietary communication protocols in installed hospital information systems demand costly adapter development for seamless pump integration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Syringe Pumps Market |
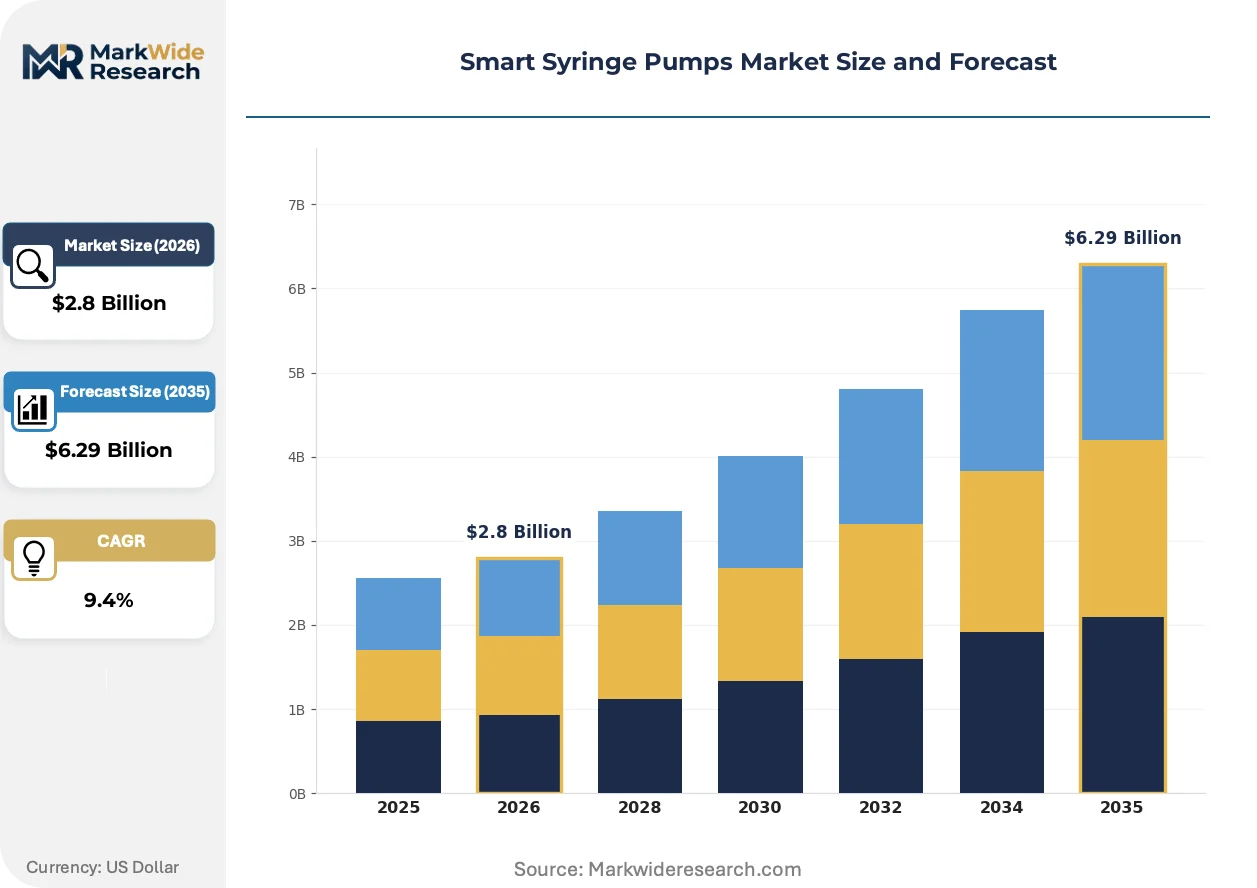
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $6.29 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Infusion Pumps, Sequential Pumps, Syringe Pumps, Ambulatory Pumps End User: Hospitals, Home Care, Clinics, Research Laboratories Technology: Infusion Therapy, Automated Delivery, Wireless Connectivity, Smart Monitoring Application: Pediatric Care, Anesthesia, Chemotherapy, Pain Management |
| Companies Covered | Terumo, IRadimed, Baxter, ICU Medical, Fresenius Kabi AG, BD, B. Braun Melsungen, Becton Dickinson and Company, Smiths Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Syringe Pumps Market Strategic Shifts
Digital infusion ecosystems are displacing standalone mechanical precision as the primary value anchor, with software-defined dosing and remote oversight capabilities commanding procurement preference over raw flow accuracy specifications.
Closed-loop anesthetic delivery systems are supplanting open-loop manual titration in European and North American operating theaters. Academic medical centers in Switzerland and the Netherlands are piloting these platforms for propofol administration, compressing the addressable market for conventional syringe pumps in anesthesia workstations while expanding demand for integrated pump-sensor-controller architectures.
FDA premarket notification pathways are tightening software validation standards for connected devices under 2014 and subsequent cybersecurity guidance documents. The agency's emphasis on threat modeling and secure update mechanisms is forcing architectural redesigns of wireless-enabled platforms, with infusion pump manufacturers most affected in their mid-cycle product refreshes.
Outcome-based service contracting is displacing capital equipment purchasing in United States integrated delivery networks. Hospital systems in Texas and California are unbundling device acquisition from preventive maintenance and dose library updates, shifting vendor relationships toward recurring revenue models and compressing upfront equipment margins.
Smart Syringe Pumps Market Segmentation
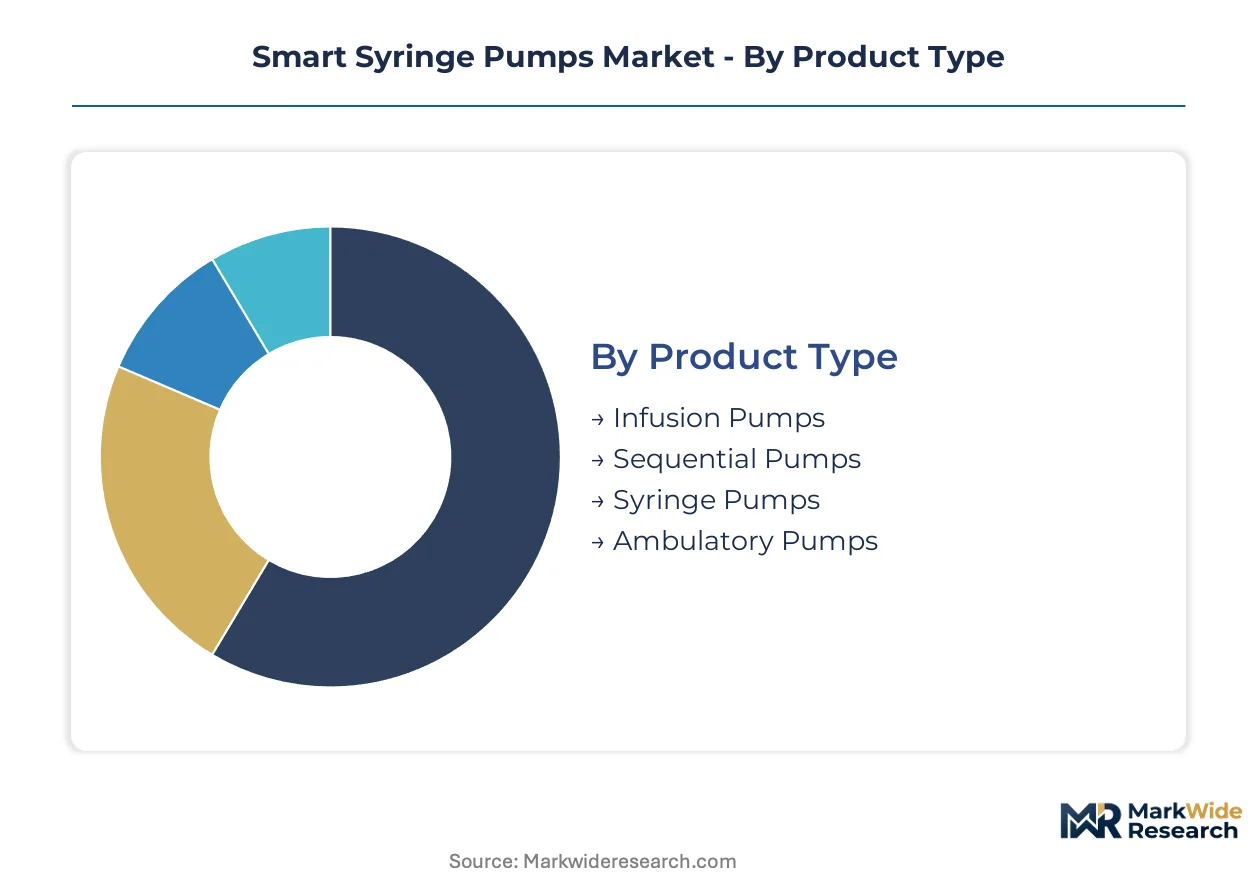
Smart syringe pump procurement patterns diverge sharply across clinical settings, with high-acuity hospitals demanding precision-engineered platforms while home care segments prioritize portability and remote oversight. Understanding these segment boundaries enables suppliers to align certification investments with addressable margin pools.
Product Type:
Domestic production concentrates syringe and infusion pump assembly in Germany and the United States, while ambulatory platforms increasingly source final integration from contract manufacturers in South Korea and Taiwan to serve export markets.
- Syringe Pumps:Electromechanical devices achieving flow accuracy within plus or minus two percent across microliter-to-milliliter ranges, indispensable for neonatal nutrition and intraoperative drug delivery. Tertiary hospitals in Switzerland and the Netherlands are expanding fleets for closed-loop anesthetic delivery pilots, though this same automation trend threatens to compress conventional pump demand in operating theaters.
- Infusion Pumps:Peristaltic or cassette-based volumetric delivery systems serving general medicine wards where microliter precision is not clinically mandated. United States integrated delivery networks are standardizing on enterprise-scale fleets across consolidated hospital systems, privileging vendors with deep electronic medical record integration.
- Sequential Pumps:Multi-channel platforms enabling programmed alternating infusions for complex therapeutic protocols.
- Ambulatory Pumps:Portable battery-backed devices with remote monitoring capabilities for outpatient chemotherapy protocols.
Syringe pumps hold the largest share; momentum sits with ambulatory pumps.
End User:
Cost tiers separate capital-intensive tertiary centers from price-sensitive outpatient facilities, with procurement authority concentrating at enterprise level for hospitals and fragmenting to individual physicians for clinic settings.
- Hospitals:Tertiary and academic medical centers commanding premium positioning through risk management protocols and liability exposure. Oncology departments across United States, German, and French tertiary centers are driving replacement velocity for certified pump fleets under stricter post-market surveillance mandates.
- Home Care:Outpatient infusion protocols creating demand for portable platforms with wireless connectivity and remote alarm integration. United States reimbursement pathways for home-based chemotherapy are expanding addressable volume fastest in Texas and California hospital systems.
- Clinics:Outpatient surgical and pain management facilities prioritizing lower-cost peristaltic alternatives where precision dosing is secondary.
- Research Laboratories:Preclinical and clinical trial settings requiring programmable dosing libraries for experimental therapeutic protocols.
Hospitals command the dominant revenue share; home care is expanding most quickly.
Technology:
Application requirements in high-acuity settings are forcing architectural trade-offs between connectivity features and regulatory compliance timelines, with wireless modules triggering enhanced FDA scrutiny.
- Smart Monitoring:Dose error reduction software and alarm management systems capturing disproportionate margin pools. Alarm integration with nurse call systems has become non-negotiable in United States hospital requests for proposal, with machine learning dosing libraries representing unclaimed premium positioning.
- Wireless Connectivity:Real-time data transmission modules enabling remote oversight and electronic medical record synchronization. FDA cybersecurity premarket submission requirements are extending development timelines by 12-18 months for platforms with these capabilities.
- Automated Delivery:Closed-loop sensor-controller architectures for propofol and anesthetic administration.
- Infusion Therapy:Basic programmable flow control without connectivity features, avoiding enhanced regulatory scrutiny.
Smart monitoring holds the largest share; wireless connectivity is climbing the fastest.
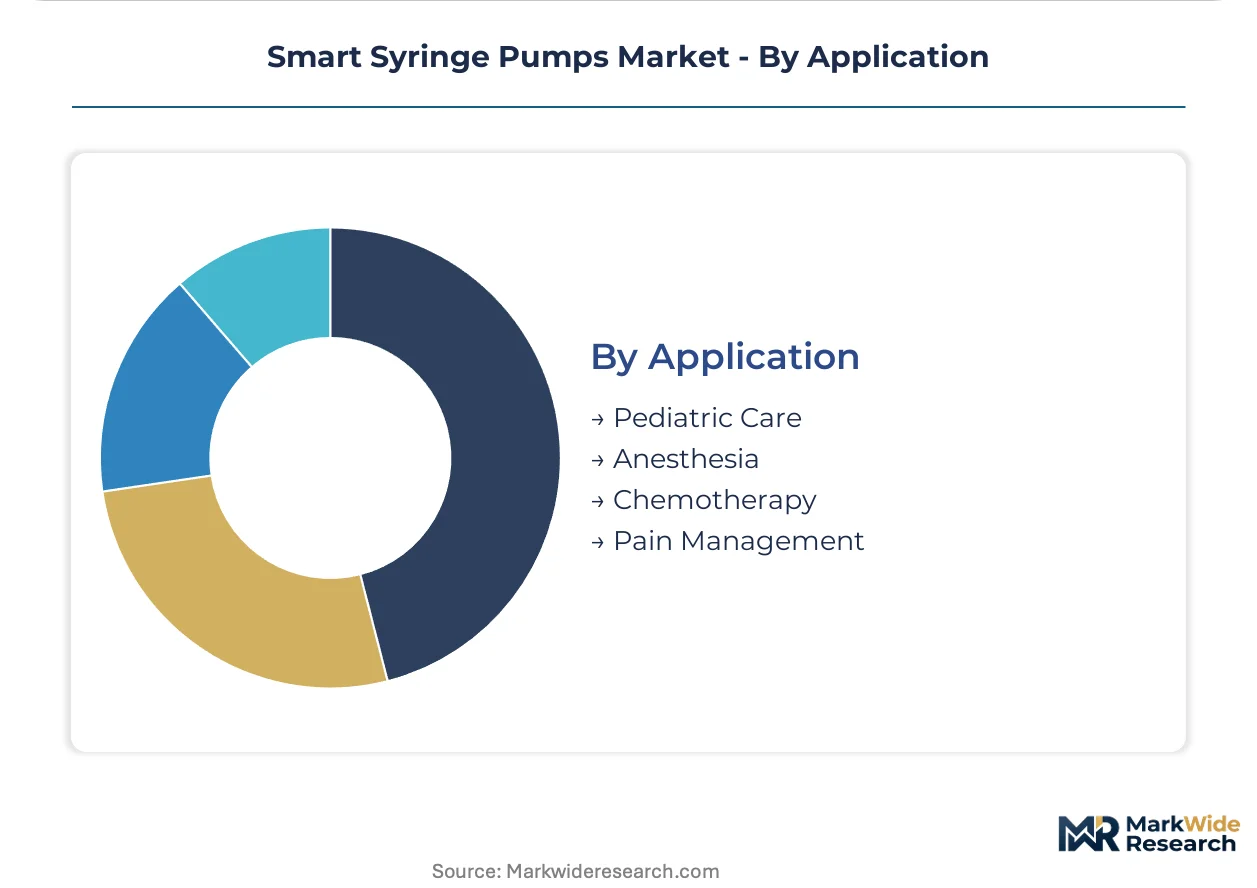
Application:
Pediatric and chemotherapy segments generate replacement velocity through institutional risk management, while anesthesia faces automation displacement from integrated delivery systems.
- Pediatric Care:Neonatal intensive care unit applications demanding microliter-precision dosing for preterm infant nutrition protocols. Preterm infant care standards in academic medical centers are expanding syringe pump deployment fastest in this segment.
- Chemotherapy:High-risk cytotoxic infusion requiring dose error reduction software and institutional liability protocols. Home-based chemotherapy expansion in the United States is creating parallel demand for portable remote-monitored platforms.
- Anesthesia:Intraoperative drug delivery facing compression from closed-loop automated systems in European and North American operating theaters.
- Pain Management:Chronic and post-surgical analgesic delivery with lower precision requirements than neonatal or oncology applications.
Pediatric care holds the largest share; chemotherapy is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA cybersecurity guidance and EU MDR technical documentation mandates are accelerating fleet replacement cycles across tertiary hospital networks. Hospital consolidation in integrated delivery networks is compressing procurement timelines toward enterprise-scale standardization.
United States
Oncology departments in Texas and California hospital systems are expanding smart pump fleets for home-based chemotherapy protocols. FDA 510(k) premarket notification requirements under 2014 and subsequent cybersecurity guidance documents are extending development timelines for wireless-enabled platforms. The Greater Boston academic medical cluster is piloting closed-loop anesthetic delivery systems for propofol administration.
Germany
Tertiary centers in Bavaria and North Rhine-Westphalia are replacing legacy pump fleets under stricter EU MDR post-market surveillance mandates. The BfArM national regulator enforces harmonized electrical safety standards alongside ISO 80601-2-24 certification requirements. Fresenius Kabi AG leverages its Bad Homburg manufacturing footprint to sustain dual-continent certification efficiency.
Switzerland
Academic medical centers in Zurich and Basel are deploying closed-loop sensor-controller architectures for anesthesia workstation integration. Swissmedic maintains alignment with EU MDR technical documentation requirements while preserving independent market authorization pathways. The Basel pharmaceutical-industrial corridor is driving demand for precision dosing platforms in clinical trial settings.
Netherlands
Amsterdam and Rotterdam hospital networks are standardizing enterprise-scale pump procurement across consolidated integrated delivery networks. The Health and Youth Care Inspectorate enforces medication safety protocols that privilege dose error reduction software capabilities. Dutch operating theaters are piloting automated delivery systems that compress conventional syringe pump demand.
France
Paris and Lyon tertiary centers are accelerating replacement of pre-MDR pump inventories under ANSM post-market surveillance directives. The Île-de-France hospital authority is consolidating procurement authority across public hospital networks. French neonatal intensive care units in academic medical centers are expanding microliter-precision syringe pump deployment for preterm infant nutrition protocols.
Smart Syringe Pumps Market Competitive Environment
Listed leaders compete with private specialists across regulatory compliance infrastructure and enterprise service scale. The vendor base concentrates around manufacturers with dedicated FDA and EU MDR regulatory affairs divisions capable of absorbing extended certification timelines. Three archetypes dominate: diversified medical technology conglomerates with deep EMR integration capabilities, European specialists leveraging dual-continent manufacturing footprints, and precision anesthesia workstation integrators. Competitive moves center on outcome-based service contracting unbundling and artificial intelligence dosing library development.
Among diversified medical technology conglomerates, Becton Dickinson and Company and BD anchor positions through enterprise-scale service infrastructure and electronic medical record system integration. Fresenius Kabi AG exemplifies the European specialist archetype with manufacturing efficiency across German and transatlantic certification pathways. B. Braun Melsungen occupies a position within the anesthesia workstation integration tier, differentiating through compatibility with closed-loop delivery architectures.
| Leading Market Players |
|---|
| Terumo |
| IRadimed |
| Baxter |
| ICU Medical |
| Fresenius Kabi AG |
| BD |
| B. Braun Melsungen |
| Becton Dickinson and Company |
| Smiths Group |
| Others |
Value Chain & Pricing Dynamics
Eighteen-to-twenty-four-month component lead times for precision stepper motors concentrate supply leverage in East Asian contract manufacturers, compressing OEM pricing power while elevating certified assembly premiums. This inventory exposure forces European and North American pump vendors to absorb working capital costs or cede margin to distributors holding safety stock.
Pricing Analysis
Certification level creates the primary spread between ISO 80601-2-24-compliant platforms and uncertified alternatives. Three-tier pricing structure across FDA-validated wireless systems, CE-marked connected devices, and basic infusion therapy units reflects software validation burden and cybersecurity documentation depth. Cost compression in the wireless-enabled tier intensifies because FDA 510(k) timelines extend development cycles without corresponding price elasticity. Home care segments demonstrate highest price sensitivity due to reimbursement pressure, while tertiary oncology departments accept premium positioning for dose error reduction software.
Supply Chain Analysis
Port congestion on transpacific lanes elevates inbound logistics costs for German and United States assembly facilities sourcing precision motors from Taiwan and South Korea. Final pump integration draws from specialized stepper motor manufacturing in East Asia, medical-grade polymer syringe barrels from Germany, and firmware development clusters in Switzerland and the Netherlands. Single-source vulnerability concentrates in precision motor supply, exposing OEMs to allocation risk during semiconductor cycle upturns. Distribution runs through integrated delivery network procurement offices in Texas and California hospital systems, with GPO contracts consolidating volume for enterprise-scale vendors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory entrenchment constructs durable defensive moats around established smart syringe pump vendors, as FDA cybersecurity validation and EU MDR technical documentation create multi-year barriers to commercial entry. Switching costs for hospital electronic medical record integration further cement incumbent positioning.
For Market Incumbents: Secure FDA-validated wireless connectivity architectures before mid-cycle product refreshes force architectural redesigns. Deepen backward integration into precision motor supply through captive partnerships with Taiwanese component specialists, insulating against allocation risk that could cede share to Fresenius Kabi's dual-continent manufacturing footprint. Fortify enterprise service infrastructure across Texas and California integrated delivery networks to defend against outcome-based contracting displacement. For New Entrants and Emerging Players: Ambulatory pump remote monitoring services represent the most penetrable white-space target, as incumbents under-serve home-based chemotherapy protocols with hospital-calibrated platforms. Target portable battery-backed systems with simplified FDA 510(k) pathways avoiding wireless cybersecurity scrutiny. Pursue reimbursement strategy alignment with United States outpatient infusion billing codes as the primary go-to-market angle. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified medical technology conglomerates seeking to divest non-core infusion therapy assets amid enterprise software pivot pressures. Five-to-ten-year viability favors vendors with dedicated regulatory affairs infrastructure capable of absorbing extended EU MDR certification timelines. Monitor FDA cybersecurity guidance revision velocity as the critical inflection signal for wireless-enabled platform valuations.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Cybersecurity Submission | Accelerates 510(k) clearance for wireless-enabled pumps in Texas oncology networks. |
| EU MDR Technical Documentation | Unlocks German and French tertiary hospital replacement cycles under post-market surveillance mandates. |
| Hospital System Partnership | Secures enterprise-scale procurement across California integrated delivery network standardization. |
| Software Companion Development | Enables machine learning dosing libraries for dose error reduction software premium positioning. |
| Reimbursement Strategy | Aligns ambulatory pump pricing with United States home-based chemotherapy billing pathways. |
Study Parameters
Initial hypotheses were tested against primary input from hospital biomedical engineers, GPO contracts managers, regulatory affairs leads at infusion pump OEMs, and oncology department clinicians, then refined against secondary validation. FDA 510(k) premarket notification databases, EU MDR technical documentation filings, hospital procurement records from Texas and California systems, and CMS reimbursement code analyses anchored quantitative inputs. Bottom-up volume estimates across product type, end user, technology, and application segments were triangulated with top-down market sizing.
Variance decomposition across the projection horizon isolates volume drivers by segmentation dimension: syringe versus infusion versus ambulatory pump architectures; hospital versus home care versus clinic end users; smart monitoring versus wireless connectivity versus automated delivery technologies; pediatric care versus chemotherapy versus anesthesia applications. CAGRs were derived from replacement cycle analysis, fleet expansion rates in consolidated hospital networks, and regulatory mandate timing. Forecast inputs incorporated ISO 80601-2-24 certification adoption curves and FDA cybersecurity guidance implementation phases.
Underlying assumptions cover sustained hospital consolidation in United States integrated delivery networks and stable EU MDR enforcement intensity, with deviation risk concentrated in FDA cybersecurity guidance revision scope and precision motor supply allocation volatility. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Sonohysterography Catheters Market
Medical Devices
Adult Water Flosser Market
Medical Devices
Global Laparoscopy Devices Market
Medical Devices
Bedwetting Alarm Market
Medical Devices
Pharma Robots Market
Medical Devices
IOL Delivery Systems Market
Medical Devices
Gastric Space-Occupying Devices Market
Medical Devices
Europe Breast Implant Market
Medical Devices
Osmotic Pumps Market
Medical Devices
Saudi Arabia Minimally Invasive Surgery Devices Market
Medical Devices
Zygomatic and Pterygoid Implants Market
Medical Devices
Italy Medical Device Regulatory Affairs Market
Medical Devices
Electrosurgical Generators Market
Medical Devices
Global Pulmonary Drug Delivery Systems Market
Medical Devices
Inferior Vena Cava Filters Market
Medical Devices
Veterinary Stereotactic Radiosurgery System Market