
 Europe Anesthesia Drugs Market | 2026-2036
Europe Anesthesia Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Anesthesia Drugs Market Foresight
The gap between premium patent-protected intravenous agents and commoditized inhalational generics is expanding across European procurement channels. AbbVie leverages its specialty injectable portfolio to sustain pricing power in hospital formularies. Baxter International competes through backward integration into sterile manufacturing, while Fresenius SE anchors distribution via its captive hospital pharmacy networks.
Europe anesthesia drugs comprise pharmacological compounds that induce reversible loss of sensation or consciousness, with intravenous propofol emulsions typically formulated at 10 mg/mL and inhalational sevoflurane vaporized at 2-8% concentration for surgical maintenance. These agents serve to enable painless operative intervention, control physiological stress responses, and facilitate mechanical ventilation across inpatient and outpatient settings. Intravenous agents command the deepest margin pools due to complex emulsion stability requirements and limited qualified manufacturers. Inhalational agents remain volume-heavy but face price erosion from multiple European generic entrants. Local anesthetics represent the fastest-growing structural category as ultrasound-guided regional blocks displace general anesthesia in orthopedic day-case units.
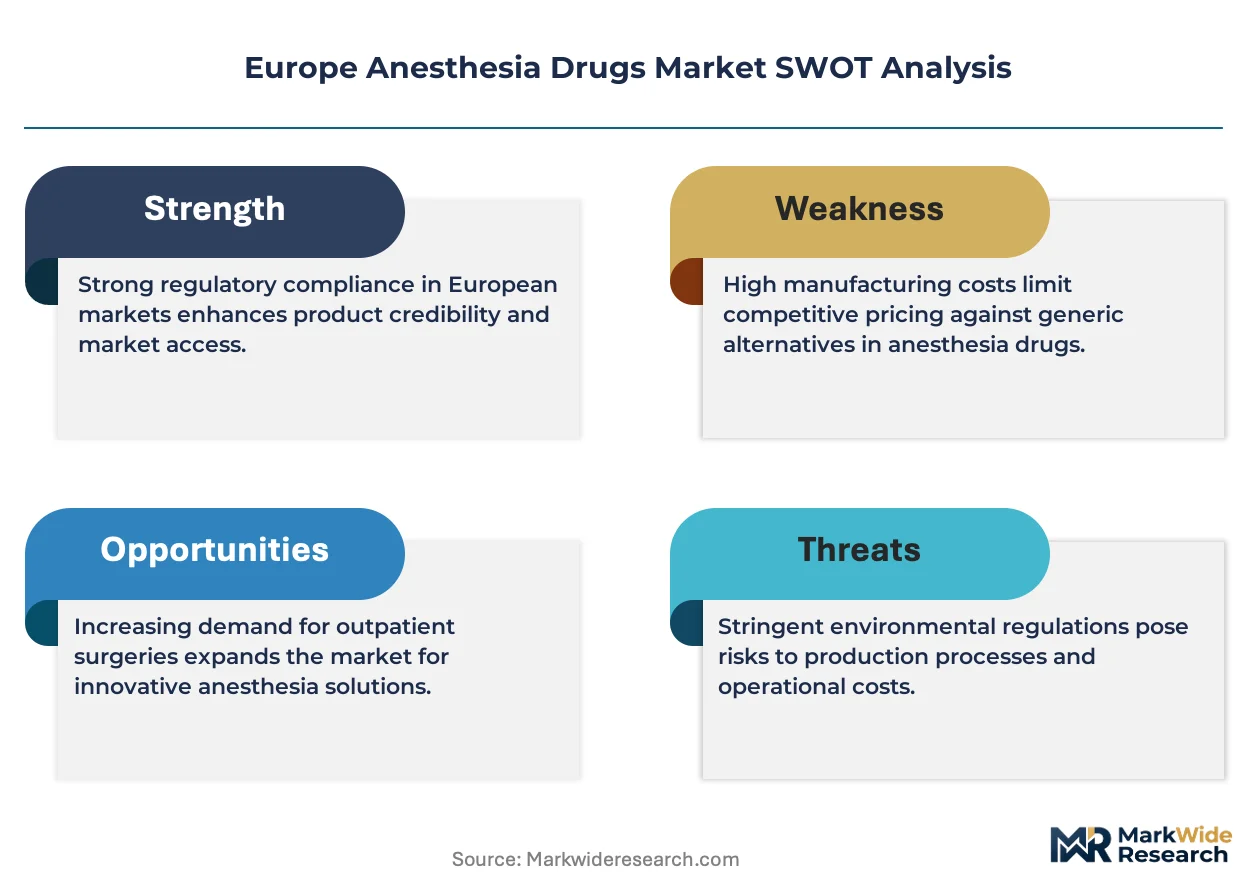
EMA centralized marketing authorizations and the EU Medical Device Regulation shape product standards for anesthesia delivery systems and their drug compatibility requirements. The F-Gas Regulation progressively restricts hydrofluorocarbon propellants used in metered-dose anesthetic delivery, forcing reformulation investments. National health technology assessment bodies in France, Germany, and England increasingly condition reimbursement on comparative effectiveness against lower-cost regional alternatives. Stakeholders must monitor how decentralized hospital procurement alliances reshape tender dynamics for multi-source molecules.
Market Dynamics
EMA centralized marketing authorizations and the EU Medical Device Regulation are tightening pharmacovigilance requirements for neuromuscular blockers and sedative-hypnotics, forcing manufacturers to restructure clinical data packages and post-market surveillance systems. This regulatory compression is accelerating consolidation among qualified manufacturers capable of sustaining compliance costs.
Growth Catalysts
- Ambulatory surgical center expansion:Same-day procedure volumes are scaling across German, French, and Dutch outpatient networks, driving demand for rapid-onset, short-acting intravenous agents.
- Ultrasound-guided regional anesthesia:Orthopedic day-case units are displacing general anesthesia with peripheral nerve blocks, expanding local anesthetic utilization.
- F-Gas Regulation phase-down:Hydrofluorocarbon propellant restrictions are forcing sevoflurane reformulation investments that favor manufacturers with captive sterile manufacturing infrastructure.
Market Restraints
- API supply concentration:Propofol active pharmaceutical ingredient production clusters in India and China, exposing European formulators to geopolitical supply interruptions.
- EMA pharmacovigilance burden:Centralized approval holders must maintain costly EU-wide risk management systems and periodic safety update reporting.
- Regional anesthesia substitution:Ultrasound-guided nerve blocks and spinal anesthesia are cannibalizing general anesthesia cases in lower-limb orthopedic surgery.
Strategic Opportunities
- Poland and Romania hospital modernization:EU cohesion fund investments are upgrading surgical suites in Eastern European markets with limited qualified anesthesia drug suppliers.
- Target-controlled infusion systems:Integration of pharmacokinetic software with smart pumps is creating demand for device-compatible propofol formulations.
- Green anesthetic positioning:Low-global-warming-potential volatile agents and intravenous alternatives are gaining preference in Nordic sustainability-procurement frameworks.
Industry Challenges
- Qualified formulation chemist scarcity:Complex lipid emulsion stability expertise is concentrated among aging specialist workforces in Germany and Switzerland.
- EMA certification timeline compression:Accelerated assessment pathways for generic intravenous anesthetics are compressing development-to-launch cycles below 18 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Anesthesia Drugs Market |
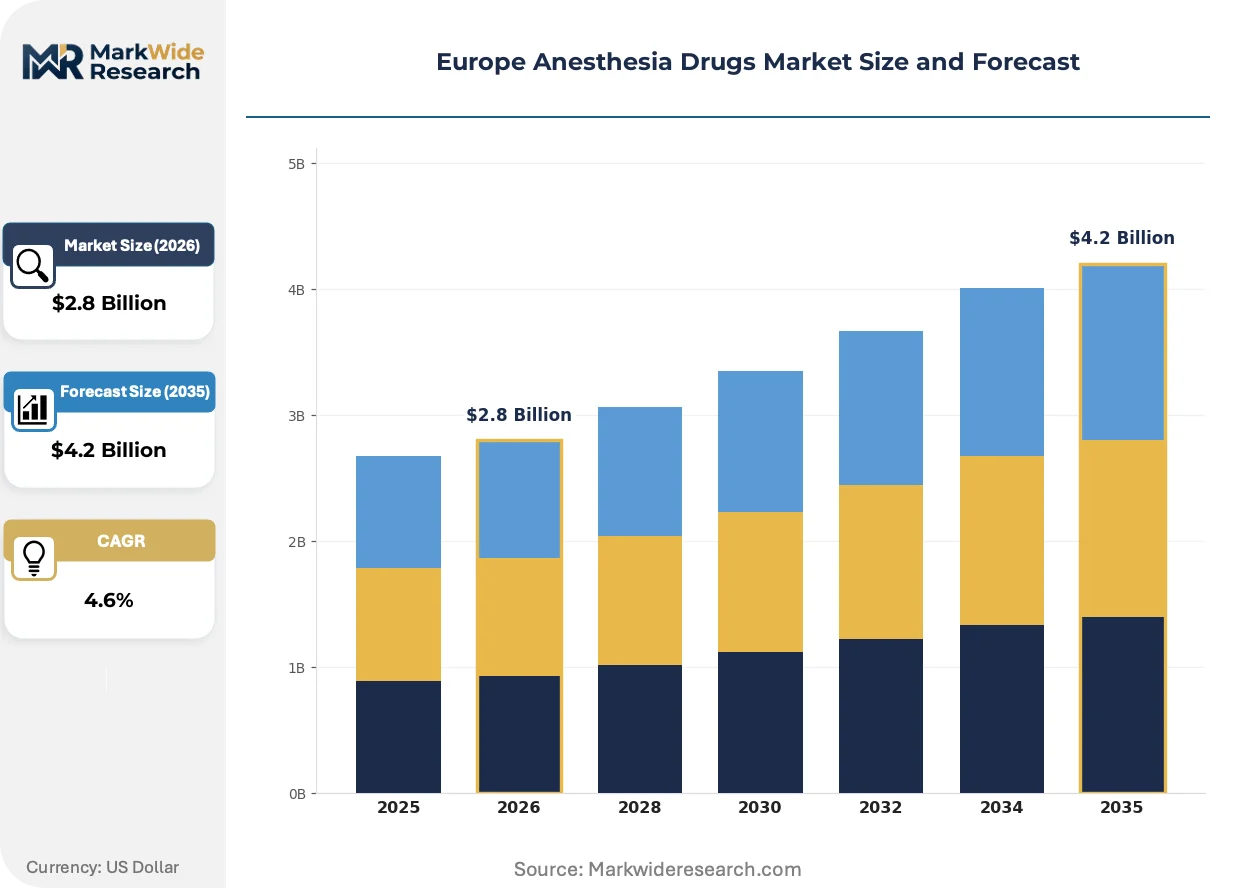
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.2 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Inhalational Agents, Intravenous Agents, Local Anesthetics, Adjunctive Drugs Application: General Surgery, Orthopedic Procedures, Obstetrics, Diagnostic Procedures End User: Hospitals, Ambulatory Surgical Centers, Clinics, Diagnostic Laboratories Distribution Channel: Pharmacies, Hospital Pharmacies, Online Retailers, Wholesale Distributors |
| Companies Covered | AbbVie Inc., Baxter International Inc., B. Braun Melsungen AG, Fresenius SE & Co. KGaA, Pfizer Inc., Aspen Pharmacare Holdings Limited, Piramal Group, Viatris Inc., Hikma Pharmaceuticals PLC, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Anesthesia Drugs Market Shifts & Advancements
Smart pump integration and closed-loop anesthesia delivery systems are compressing the gap between pharmacological agent and delivery device, requiring drug-device compatibility certification that reshapes competitive positioning.
Closed-loop anesthesia systems using bispectral index monitoring and automated propofol titration are expanding into German and Dutch university hospital networks at pilot scale. Academic medical centers in Heidelberg and Rotterdam are deploying these platforms for cardiac and neurosurgical procedures. The technology is expanding into high-complexity surgical segments where precise depth-of-control reduces emergence delirium and accelerates recovery room throughput.
The EU F-Gas Regulation mandates progressive hydrofluorocarbon phase-down for metered-dose inhalational delivery systems, forcing sevoflurane and desflurane manufacturers toward alternative propellant chemistries or intravenous formulation pivots. Pharmaceutical sponsors must submit updated environmental risk assessments to EMA as part of marketing authorization maintenance. German and French health technology assessment bodies are beginning to weight carbon footprint metrics in hospital tender evaluations, disadvantaging high-GWP volatile agents.
Decentralized hospital procurement alliances in France, Germany, and the Benelux are consolidating purchasing power for multi-source molecules, compressing price differentiation between originator and generic intravenous anesthetics. Regional purchasing cooperatives in Bavaria and Rhône-Alpes now negotiate three-year framework agreements that bundle propofol, rocuronium, and sugammadex volumes. The shift is most visible in Germany, where university hospital networks and private Klinik chains are migrating from brand-loyal formularies to tender-driven multi-source protocols.
Europe Anesthesia Drugs Market Segmentation
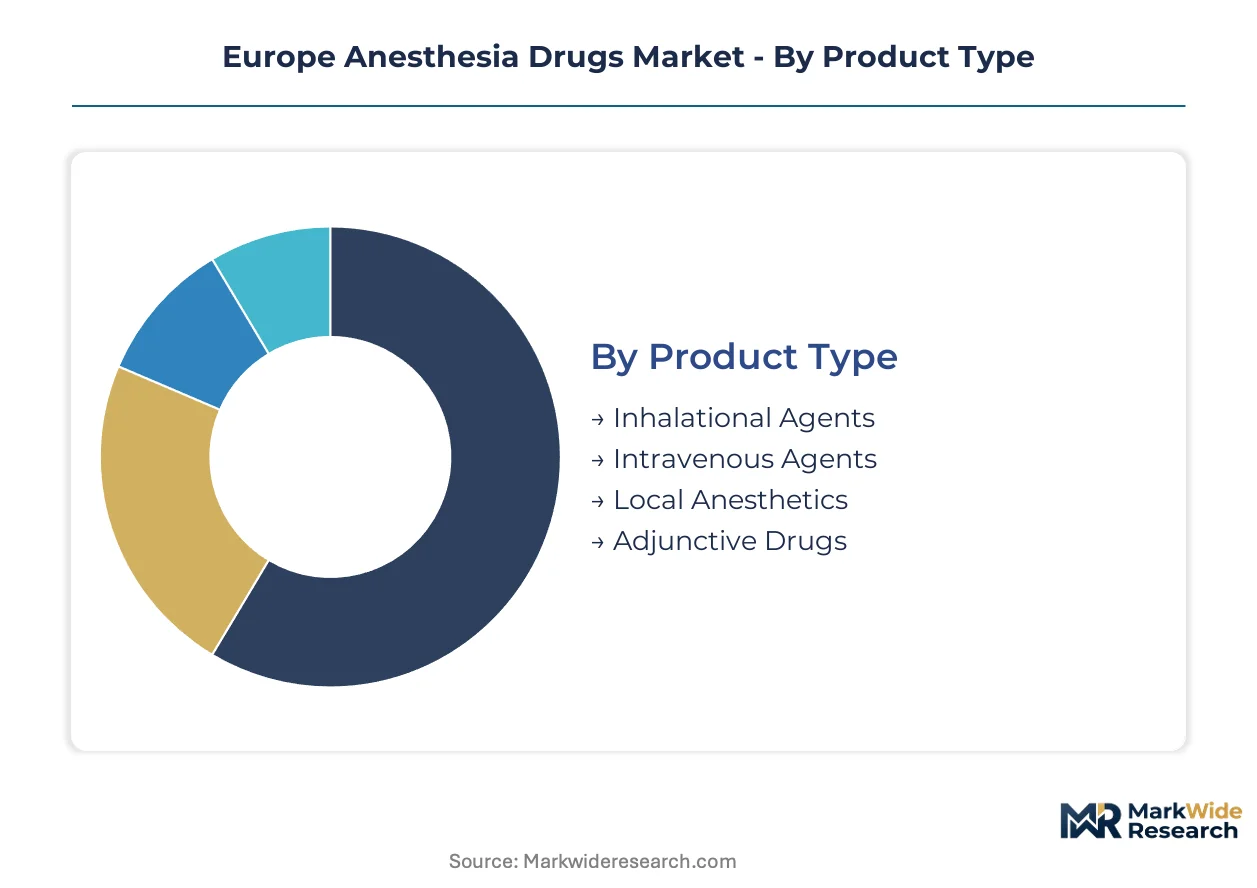
Segmentation in European anesthesia drugs reveals how formulation complexity, procedure setting, and procurement channel each reshape margin structures differently. Manufacturers must align portfolio depth against the specific technical and logistical demands of each slice.
Product Type:
Customization intensity spans from commodity inhalational gases to precision-engineered lipid emulsions requiring sterile manufacturing infrastructure.
- Intravenous Agents:Propofol emulsions formulated at 10 mg/mL demand complex lipid stability expertise concentrated among German and Swiss manufacturers. University hospital networks in Heidelberg and Rotterdam drive demand for device-compatible formulations that integrate with target-controlled infusion systems.
- Local Anesthetics:Ropivacaine and bupivacaine formulations enable ultrasound-guided peripheral nerve blocks displacing general anesthesia in orthopedic day-case units across Bavaria and Rhône-Alpes. French and German health technology assessment bodies increasingly condition reimbursement on comparative effectiveness against intravenous alternatives.
- Inhalational Agents:Sevoflurane vaporized at 2-8% concentration faces EMA environmental risk assessments under F-Gas Regulation hydrofluorocarbon phase-down mandates.
- Adjunctive Drugs:Neuromuscular blockers and reversal agents complete balanced anesthesia protocols in cardiac and neurosurgical suites.
Leading the category by volume: Intravenous Agents. Growing fastest: Local Anesthetics.
Application:
Procedure complexity determines agent selection, with high-acuity surgeries commanding premium formulations and day-case procedures driving commoditization.
- Orthopedic Procedures:Knee and hip arthroplasties in German outpatient networks are shifting toward spinal anesthesia and peripheral nerve blocks. Ultrasound-guided regional techniques reduce recovery room stays and accelerate discharge protocols.
- General Surgery:Laparoscopic and open abdominal procedures in university hospital networks require deep neuromuscular blockade and precise depth-of-control. Dutch academic centers pilot closed-loop propofol delivery for these high-complexity cases.
- Obstetrics:Epidural analgesia protocols in French maternity units prioritize amide-type local anesthetics with favorable placental transfer profiles.
- Diagnostic Procedures:Colonoscopy and endoscopy suites in ambulatory settings favor short-acting intravenous sedatives with rapid clearance.
Orthopedic Procedures command the steepest shift in technique preference. Diagnostic Procedures are expanding most quickly as screening volumes rise.
End User:
Procurement sophistication varies from centralized hospital pharmacy committees to decentralized clinic purchasing.
- Hospitals:German university hospital networks and private Klinik chains maintain the highest per-capita surgical throughput on the continent. EMA pharmacovigilance requirements and EU Medical Device Regulation compliance costs favor suppliers with established EU-wide risk management systems.
- Ambulatory Surgical Centers:Same-day procedure volumes are scaling across Dutch and French outpatient networks. These facilities prioritize rapid-onset, short-acting agents that minimize post-anesthesia care unit stays.
- Clinics:Smaller orthopedic and ophthalmic practices in Poland and Romania concentrate demand for local anesthetic kits with single-use delivery systems.
- Diagnostic Laboratories:Endoscopy and imaging centers in Benelux markets source sedative protocols through group purchasing organizations.
Hospitals retain dominant volume share. Ambulatory Surgical Centers are gaining share fastest as procedure migration accelerates.
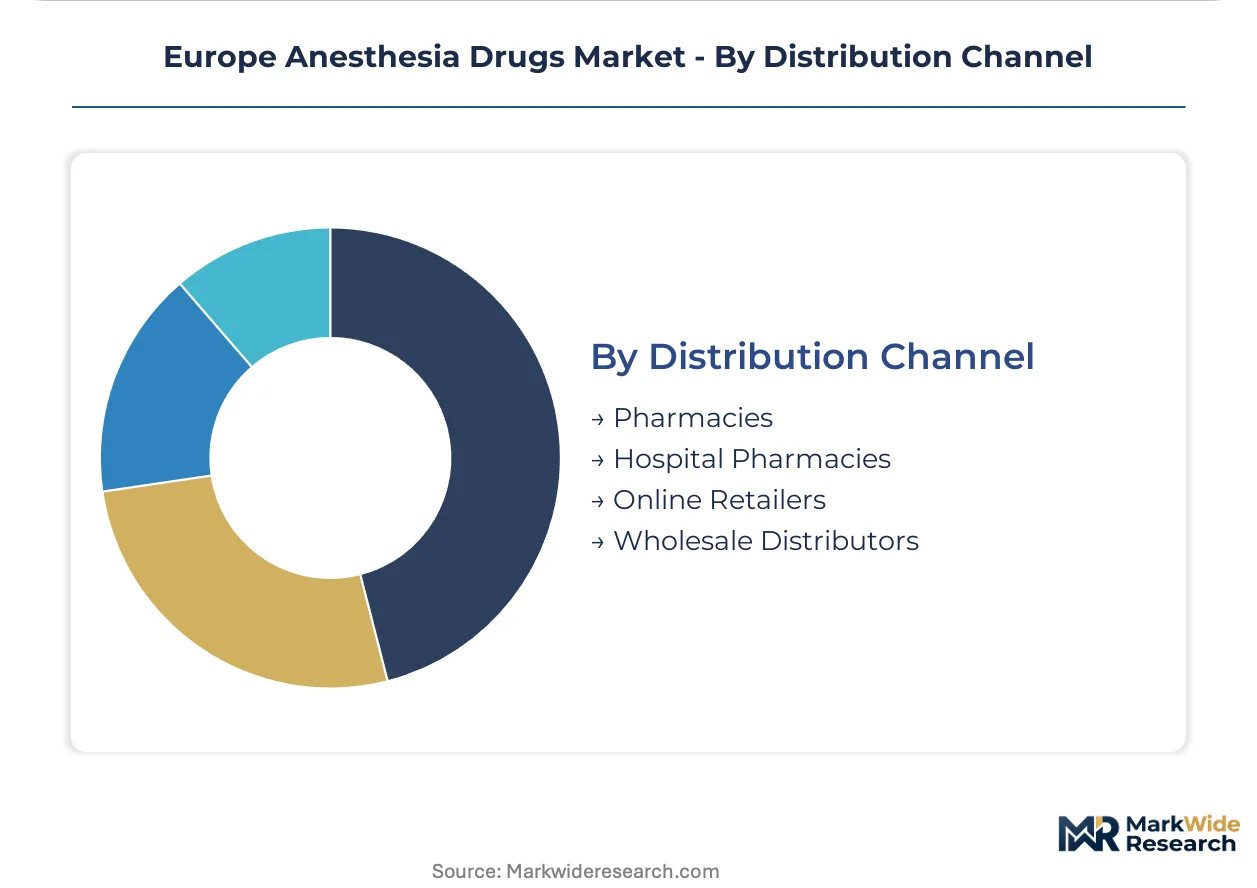
Distribution Channel:
Channel concentration reflects the tension between captive vertical integration and open-market procurement.
- Hospital Pharmacies:Fresenius SE anchors distribution through captive pharmacy networks serving its owned and affiliated facilities. Regional purchasing cooperatives in Bavaria and Rhône-Alpes negotiate multi-source framework agreements bundling propofol, rocuronium, and sugammadex volumes.
- Wholesale Distributors:Independent hospital systems in France and the Benelux rely on specialized pharmaceutical wholesalers for just-in-time delivery of temperature-sensitive emulsions.
- Pharmacies:Community pharmacy channels serve outpatient post-operative pain management with oral and topical local anesthetic formulations.
- Online Retailers:Limited penetration for anesthesia drugs due to cold-chain requirements and controlled substance regulations.
Hospital Pharmacies dominate value capture. Wholesale Distributors are expanding most quickly as independent systems consolidate procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Heidelberg anchors European anesthesia drug demand through its university hospital network's pioneering adoption of closed-loop delivery systems and target-controlled infusion protocols. German Klinik chains and Dutch academic centers drive per-capita surgical throughput that exceeds continental averages.
Germany
University hospital networks in Heidelberg and Berlin pilot closed-loop propofol systems for cardiac procedures. The EMA centralized approval pathway mandates EU-wide pharmacovigilance systems that favor established manufacturers. Bavarian purchasing cooperatives negotiate three-year framework agreements bundling intravenous anesthetics and reversal agents.
France
Rhône-Alpes regional purchasing cooperatives consolidate procurement for multi-source molecules across Lyon and Grenoble hospital systems. The French National Authority for Health conditions reimbursement on comparative effectiveness against regional anesthesia alternatives. Parisian maternity units prioritize amide-type local anesthetics with favorable placental transfer profiles.
Netherlands
Rotterdam academic medical centers deploy automated propofol titration platforms for neurosurgical cases. Dutch outpatient networks scale same-day orthopedic procedures driving demand for rapid-onset intravenous agents. The Benelux group purchasing organizations source sedative protocols for endoscopy and imaging centers.
Poland
EU cohesion fund investments upgrade surgical suites in Warsaw and Kraków with limited qualified anesthesia drug suppliers. Polish orthopedic and ophthalmic practices concentrate demand for local anesthetic kits with single-use delivery systems. The national pharmaceutical regulator enforces cold-chain compliance for temperature-sensitive emulsions.
Switzerland
Swissmedic maintains stringent marketing authorization requirements that limit generic intravenous anesthetic entrants. Basel and Zurich hospital pharmacies source complex lipid emulsion formulations from neighboring German manufacturers. Swiss specialist workforces retain concentrated expertise in sterile emulsion stability engineering.
Europe Anesthesia Drugs Market Competitive Landscape
Premium-margin players sit above commodity-margin players across formulation complexity and sterile manufacturing capability. Intravenous emulsion specialists command deepest margin pools due to limited qualified chemists and complex stability requirements. Three archetypes dominate: integrated hospital-pharmacy networks, backward-integrated sterile manufacturers, and specialty injectable portfolio holders. Consolidation accelerates through M&A among EMA-compliant manufacturers and capacity expansion into captive sterile production.
Within the specialty injectable tier, AbbVie Inc. and Baxter International Inc. exemplify divergent competitive positions. AbbVie anchors premium pricing through hospital formulary loyalty sustained by complex emulsion portfolios. Baxter occupies a position emphasizing sterile manufacturing infrastructure integration. Fresenius SE & Co. KGaA represents the integrated distribution archetype through captive pharmacy networks serving affiliated facilities. B. Braun Melsungen AG and Pfizer Inc. sit within the diversified pharmaceutical conglomerate tier with anesthesia as one vertical among broader hospital supply portfolios.
| Leading Market Players |
|---|
| AbbVie Inc. |
| Baxter International Inc. |
| B. Braun Melsungen AG |
| Fresenius SE & Co. KGaA |
| Pfizer Inc. |
| Aspen Pharmacare Holdings Limited |
| Piramal Group |
| Viatris Inc. |
| Hikma Pharmaceuticals PLC |
| Others |
Supply & Pricing Matrix
Backward integration into sterile lipid emulsion manufacturing anchors pricing power for European anesthesia drug suppliers, as captive production of complex propofol formulations insulates margin structures from API volatility and EMA compliance cost inflation. German and Swiss manufacturers with in-house sterile capabilities command premium positioning against commodity inhalational generic entrants, while hospital procurement alliances compress spreads for multi-source molecules.
Pricing Analysis
Throughput-based pricing anchors hospital formulary negotiations, with rapid-recovery agents commanding premiums against standard formulations in high-volume ambulatory settings. Three-tier pricing structure across premium device-compatible emulsions, standard hospital-grade formulations, and economy generic alternatives reflects certification grade and sterile manufacturing pedigree. Cost compression in the inhalational segment intensifies as multiple European generic entrants erode originator positioning. Ambulatory surgical centers exhibit acute price sensitivity due to fixed reimbursement rates, while university hospital networks prioritize clinical performance over unit cost.
Supply Chain Analysis
Propofol API supply rests on Indian and Chinese specialty chemical producers, with European formulators dependent on imported active pharmaceutical ingredients for emulsion production. Soybean oil and egg lecithin feedstocks for lipid formulations, alongside hydrofluorocarbon propellants for inhalational delivery, constitute critical input dependencies. Single-source vulnerability in API supply exposes formulators to geopolitical interruption and customs clearance delays. Distribution runs through captive hospital pharmacy networks and specialized pharmaceutical wholesalers with cold-chain capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Closed-loop anesthesia delivery systems are displacing conventional manual titration across German and Dutch academic centers, compressing demand for standalone agents and elevating device-compatible formulation requirements.
For Market Incumbents: Deepen sterile manufacturing infrastructure in Germany and Switzerland to defend against EMA pharmacovigilance cost escalation and API supply disruption. Secure backward integration into lipid emulsion production capabilities. Expand device-compatibility certification for target-controlled infusion systems to capture closed-loop adoption in Heidelberg and Rotterdam university networks. For New Entrants and Emerging Players: Begin with ultrasound-guided regional anesthesia kits for Polish and Romanian orthopedic clinics, where EU cohesion fund investments are modernizing surgical suites with limited qualified supplier presence. Target local anesthetic formulations with single-use delivery systems. Pursue distribution partnerships with specialized pharmaceutical wholesalers serving independent hospital systems in France and the Benelux. For Investors and Strategic Acquirers: Exit pathways concentrate in EMA-compliant sterile manufacturing assets with captive lipid emulsion expertise, as regulatory barriers compound acquisition premiums for qualified capacity. Long-term viability favors suppliers with integrated device-drug compatibility portfolios. Watch closed-loop anesthesia pilot scale-up in German cardiac and neurosurgical suites as inflection indicator for formulation demand shifts.| Strategic Initiative | Industry Significance |
|---|---|
| EMA Centralized Approval Pathway | Marketing authorization maintenance mandates EU-wide risk management systems for neuromuscular blockers. |
| Device-Drug Compatibility Certification | Smart pump integration requirements reshape competitive positioning for propofol formulations in Dutch academic centers. |
| Green Anesthetic Formulation Pivot | F-Gas Regulation hydrofluorocarbon phase-down forces sevoflurane reformulation investments favoring captive sterile infrastructure. |
| Regional Purchasing Cooperative Engagement | Bavarian and Rhône-Alpes framework agreements bundle volumes across propofol, rocuronium, and sugammadex procurement. |
| Target-Controlled Infusion System Partnership | Pharmacokinetic software integration with smart pumps creates demand for compatible emulsion formulations in German networks. |
Research Methodology
Multi-period observation of EMA approval timelines, hospital procurement tender awards, and ambulatory surgical center procedure volumes anchored the trend analysis, supplemented by interviews with hospital pharmacy directors, anesthesia department heads, regulatory affairs specialists, and GPO contracts managers. Secondary validation drew from EMA centralized marketing authorization databases, EU Medical Device Regulation guidance documents, national health technology assessment body reimbursement decisions, and hospital procurement cooperative framework agreements. Bottom-up volume modeling triangulated against top-down market sizing across formulation type and end-use setting.
Input-output matrices mapped propofol emulsion demand against surgical throughput projections, inhalational agent consumption against F-Gas Regulation phase-down schedules, and local anesthetic growth against ultrasound-guided regional anesthesia adoption curves across the analysis window. Segmentation dimensions included product type complexity tier, application acuity level, end-user procurement sophistication, and distribution channel integration depth. CAGRs derived from surgical volume elasticity to demographic aging, procedure migration patterns, and reimbursement policy shifts.
Underlying measurement precision varies by segment; intravenous agent forecasts carry tighter precision due to concentrated manufacturer disclosure, while local anesthetic projections reflect greater uncertainty in ultrasound adoption trajectories. Forecasts reflect assumptions regarding EMA regulatory stability, API supply continuity, and hospital procurement alliance consolidation. Regulatory timeline delays, geopolitical API disruption, and accelerated regional anesthesia substitution warrant ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Monkeypox Vaccine and Treatment Market
Pharmaceuticals
Cancer Therapeutics and Biotherapeutics Market
Pharmaceuticals
Germany Pharmaceutical Warehousing Market
Pharmaceuticals
North America Small Molecule Sterile Injectable Drugs Market
Pharmaceuticals
US Plasma Fractionation Market
Pharmaceuticals
Dipeptide Peptidase 4 Inhibitors Market
Pharmaceuticals
Alirocumab Market
Pharmaceuticals
Chemotherapy Induced Anemia Market
Pharmaceuticals
Lidocaine Ointment Market
Pharmaceuticals
Microparticle Injectables Market
Pharmaceuticals
Meperidine Market
Pharmaceuticals
Middle East and Africa Obsessive-Compulsive Disorder (OCD) Drugs Market
Pharmaceuticals
Antiepilepsy Drugs Market
Pharmaceuticals
Global Gastroparesis Drug Market
Pharmaceuticals
Pharmaceutical Wholesale & Distribution Market
Pharmaceuticals
Fibromyalgia Antidepressant Market