
 Europe Artificial Organs and Bionic Implants Market | 2026-2036
Europe Artificial Organs and Bionic Implants Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Artificial Organs and Bionic Implants Market Foresight
Project finance and hospital leasing models for high-value implant procurement is fragmenting competitive dynamics across Europe. Medtronic plc leverages long-term service contracts with university hospitals to sustain recurring revenue streams. Ottobock anchors its position in Germany through specialized rehabilitation center partnerships for bionic limb fitting. Cochlear Limited differentiates via direct-to-audiologist training programs that lock in device selection protocols across Nordic markets.
Artificial organs and bionic implants comprise electromechanical and biological substitute systems engineered to restore physiological function through materials such as titanium alloys, pyrolytic carbon heart valves, and platinum-iridium electrode arrays. These devices replace or augment failing organs and sensory-motor systems in patients with end-stage organ disease, traumatic injury, or congenital defects. Artificial joints and pacemakers dominate current revenue pools due to established reimbursement pathways and high procedure volumes across European hospital networks. Cochlear implants represent the fastest-growing product category as pediatric screening mandates expand and adult candidacy criteria broaden. Robotics-enabled surgical placement systems are concentrating margin capture among technology-integrated providers.
The EU Medical Device Regulation (MDR) and CE marking framework govern market access, with notified bodies in Germany and the Netherlands experiencing backlogs that delay product certification timelines. The EMA coordinates with national health technology assessment bodies such as NICE in the United Kingdom and HAS in France to align clinical evidence requirements with reimbursement decisions. Switzerland's Swissmedic maintains autonomous standards that create parallel compliance obligations for manufacturers serving Alpine markets. Stakeholders must monitor evolving MDR guidance on implantable device post-market surveillance to anticipate compliance cost escalations.
Market Dynamics
EU MDR compliance timelines are compressing product certification cycles and forcing manufacturers to consolidate clinical evidence portfolios ahead of notified body capacity constraints.
Growth Catalysts
- Pediatric cochlear screening mandates:Nordic health ministries now mandate universal newborn hearing screening, expanding addressable patient pools for auditory implant systems.
- REACH-compliant biomaterials:Pyrolytic carbon and titanium-niobium alloys certified under EU chemical safety frameworks accelerate regulatory pathway approvals for heart valve and orthopedic manufacturers.
- Germany's cardiac implant centers:Concentrated clusters in Berlin, Munich, and Hamburg generate procedure volume density that sustains specialized device procurement at scale.
Market Restraints
- Notified body backlog:German and Dutch certification bodies face 12-18 month queue times under MDR, freezing new product launches for implantable device portfolios.
- Platinum-iridium electrode scarcity:Concentrated refining capacity in South Africa and Russia exposes cochlear and neurostimulation manufacturers to supply interruption risk.
- Biofilm colonization thresholds:Persistent infection rates above 3% in transcutaneous bionic interfaces limit candidacy expansion for limb prosthetic integration.
Strategic Opportunities
- Poland and Czech Republic:Underpenetrated orthopedic implant penetration relative to Western European procedure rates creates expansion corridors for joint replacement systems.
- Robotics-enabled surgical placement:Convergence of haptic feedback systems with pre-operative imaging is collapsing revision rates for artificial joint positioning.
- Swissmedic parallel pathways:Autonomous Alpine certification routes allow manufacturers to de-risk EU MDR delays through early Swiss market entry.
Industry Challenges
- Biocompatibility testing capacity:ISO 10993-compliant laboratory slots face 6-month booking delays, throttling pre-clinical validation throughput for new implant coatings.
- Cross-border reimbursement harmonization:Divergent NICE, HAS, and G-BA evidence requirements force manufacturers to maintain parallel health technology assessment dossiers.
- Electromechanical integration complexity:Legacy hospital IT infrastructure in France and Italy resists seamless connectivity with next-generation implant monitoring systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Artificial Organs and Bionic Implants Market |
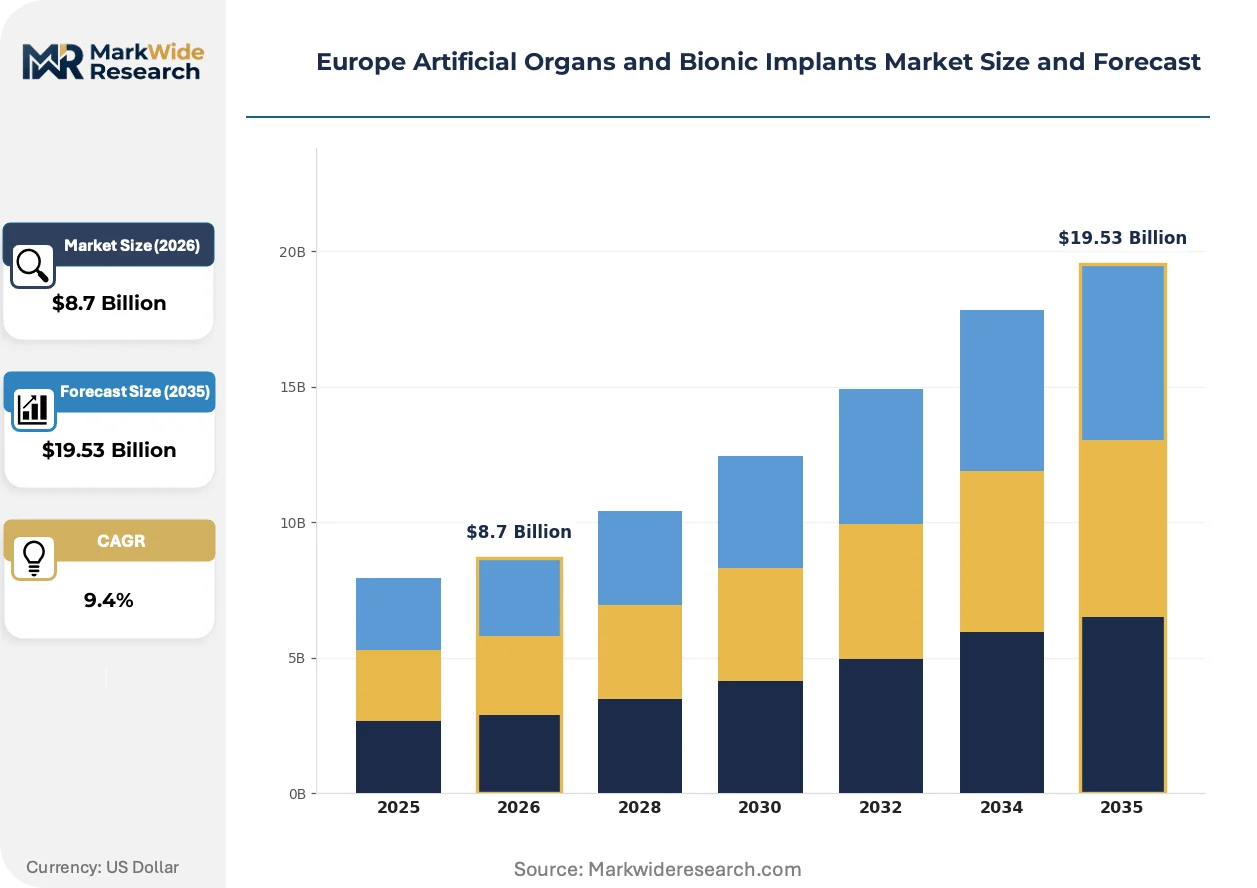
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Heart Valves, Artificial Joints, Pacemakers, Cochlear Implants Technology: Biomaterials, Robotics, 3D Printing, Bioengineering End User: Hospitals, Specialty Clinics, Research Institutes, Rehabilitation Centers Application: Cardiology, Orthopedic, Neurology, Urology |
| Companies Covered | Medtronic plc, Zimmer Biomet Holdings Inc., Ottobock, Sonova, Ossur hf, Edwards Lifesciences Corporation, Ekso Bionics Holdings Inc., Boston Scientific Corporation, Cochlear Limited, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Artificial Organs and Bionic Implants Market Shifts & Advancements
Neural interface miniaturization and biomimetic material science are converging to redefine performance benchmarks for sensory-motor restoration devices across European clinical networks.
Closed-loop neurostimulation architectures is collapsing the latency between physiological signal detection and therapeutic response in cardiac and cochlear systems. Implantable pulse generators with embedded machine learning algorithms now process local data without external telemetry delays. Cardiac resynchronization therapy centers in Rotterdam and Stockholm are prioritizing these devices for heart failure patient cohorts with atrial fibrillation comorbidities.
MDR post-market surveillance mandates now require annual safety update reports and implantable device registries with 15-year follow-up obligations. Manufacturers must fund independent clinical investigations for legacy products seeking renewed CE certification. High-risk device categories including total artificial hearts and ventricular assist systems face the steepest compliance cost escalations as notified bodies apply enhanced scrutiny to biocompatibility documentation.
Hospital leasing consortia are displacing capital purchase models for high-value bionic systems. Procurement committees in Paris and Milan now prioritize total cost-of-ownership contracts spanning device lifespan, surgical training, and rehabilitation services. This restructuring concentrates supplier selection authority among integrated health networks with balance sheet capacity to absorb long-term service commitments.
Europe Artificial Organs and Bionic Implants Market Segmentation
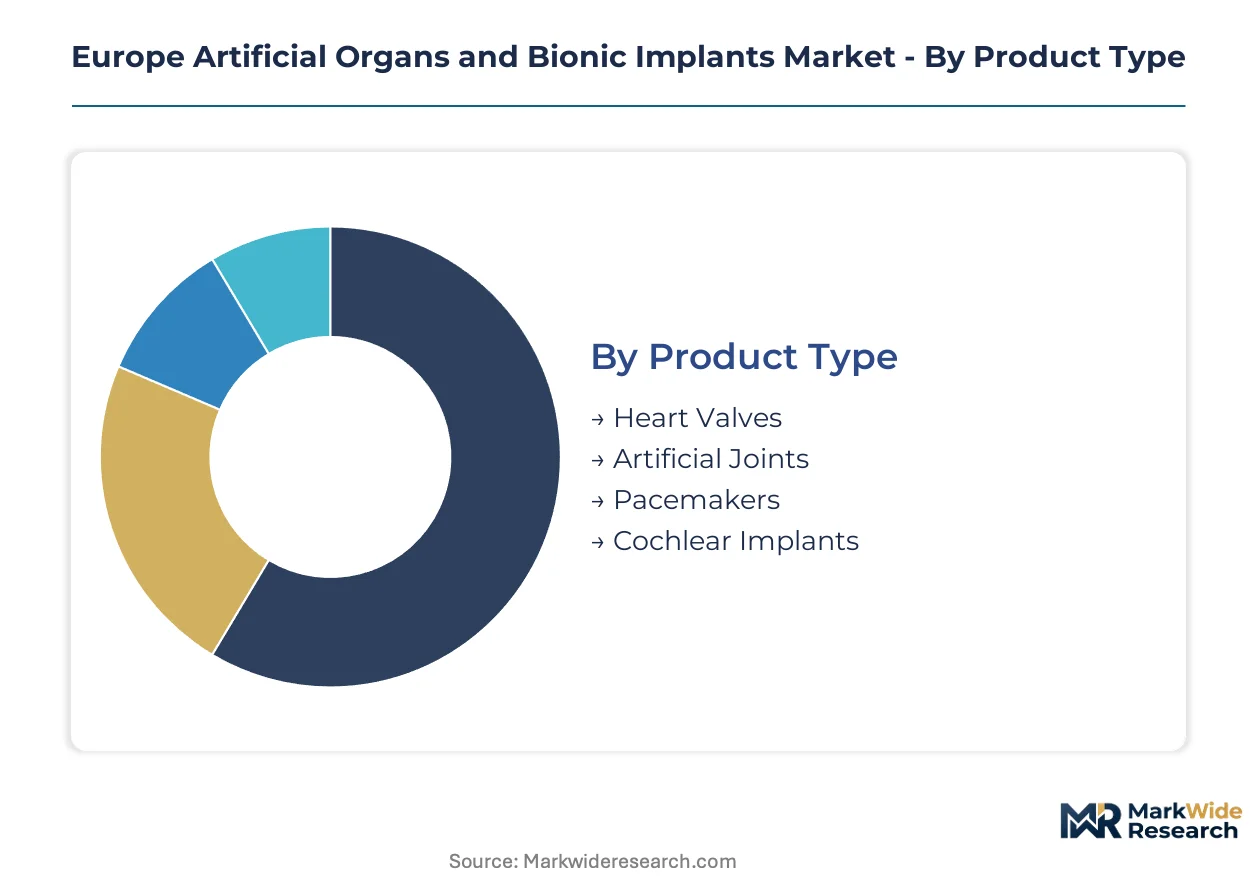
Segmentation reveals how procurement authority, reimbursement pathways, and clinical evidence requirements fragment across distinct stakeholder ecosystems in European implant markets. Understanding these divides exposes where margin concentrates and where compliance costs escalate.
Product Type:
Use-case spectrum spans elective orthopedic restoration to life-sustaining cardiac support, with reimbursement intensity and regulatory scrutiny scaling accordingly.
- Artificial Joints:Titanium and cobalt-chrome alloy constructs replace hip, knee, and shoulder articulations in aging European populations. German orthopedic clusters in Tuttlingen and Solothurn drive procurement volume for cementless fixation systems.
- Cochlear Implants:Platinum-iridium electrode arrays restore auditory function through direct neural stimulation. Nordic universal newborn screening mandates in Sweden and Denmark are expanding pediatric candidacy pools faster than adult segments.
- Heart Valves:Pyrolytic carbon and biological tissue constructs replace diseased native valves. Mechanical durability requirements favor polymer-composite designs in younger French and Italian patient cohorts.
- Pacemakers:Lithium-iodine powered pulse generators regulate cardiac rhythm through transvenous lead systems. Berlin and Munich cardiac centers concentrate dual-chamber device implantation volumes.
The dominant share belongs to artificial joints, while cochlear implants are closing the gap fastest.
Technology:
Cost tier stratification separates mature material platforms from capital-intensive robotics and additive manufacturing systems requiring dedicated surgical infrastructure.
- Biomaterials:Titanium-niobium alloys, pyrolytic carbon, and platinum-iridium composites constitute the foundational material layer. REACH compliance certification in German manufacturing accelerates regulatory clearance for heart valve and orthopedic producers.
- Robotics:Haptic feedback surgical systems enable sub-millimeter precision in joint placement and cochlear electrode insertion. Rotterdam and Stockholm university hospitals are prioritizing these platforms for revision-sensitive procedures.
- 3D Printing:Patient-specific implant geometries fabricated from titanium powder reduce operative time and bone removal requirements. Swiss orthopedic manufacturers leverage Alpine precision engineering clusters for porous scaffold production.
- Bioengineering:Tissue-engineered constructs and bioresorbable scaffolds represent emerging platforms. EMA scrutiny of living-cell-containing products extends development timelines beyond electromechanical alternatives.
Biomaterials command the installed base, though robotics is gaining share fastest among high-volume implant centers.
End User:
Customer type determines procurement modality, with capital-constrained rehabilitation centers favoring lease structures against hospitals' direct purchase authority.
- Hospitals:Academic medical centers and district general hospitals perform the majority of cardiac and orthopedic implant procedures. German cardiac implant centers in Berlin, Munich, and Hamburg generate procedure density that sustains specialized device procurement.
- Specialty Clinics:Focused orthopedic and ophthalmic ambulatory centers concentrate elective joint and lens replacement volumes. French and Italian clinic networks resist IT integration with next-generation implant telemetry systems.
- Rehabilitation Centers:Post-surgical fitting and training facilities for bionic limbs and auditory processors. Ottobock's German rehabilitation partnerships anchor limb-prosthetic market positioning through specialized fitting protocols.
- Research Institutes:Preclinical validation and clinical trial execution for novel implant platforms. ISO 10993-compliant biocompatibility testing slots face six-month booking delays, throttling validation throughput.
Hospitals retain procurement dominance, while rehabilitation centers are expanding fastest as bionic limb integration protocols mature.
Application:
Clinical specialty alignment dictates reimbursement coding, with cardiology and orthopedic procedures commanding established DRG pathways against neurology's emerging coverage.
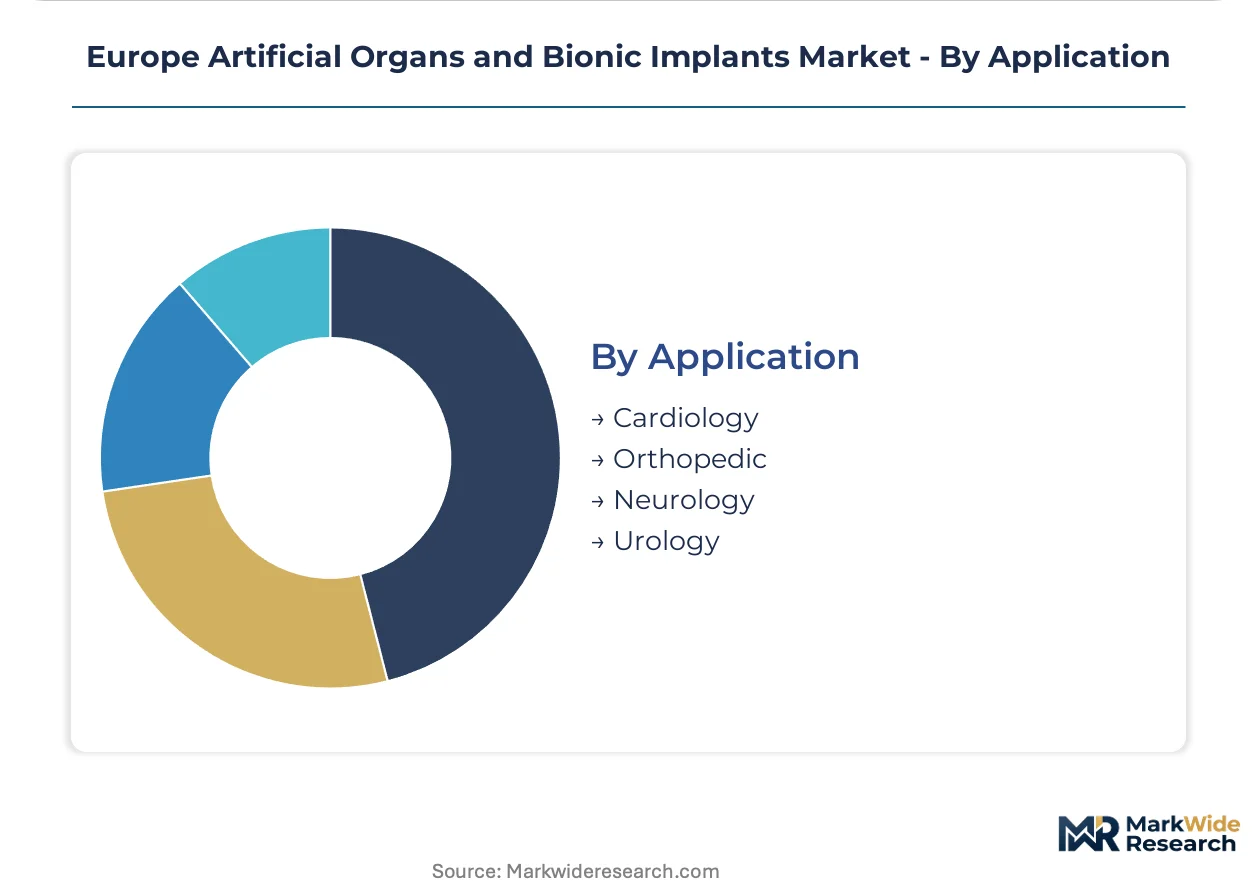
- Orthopedic:Joint replacement and spinal fixation procedures dominate procedure volumes across European hospital networks. Poland and Czech Republic present expansion corridors given underpenetrated implant penetration relative to Western European rates.
- Cardiology:Pacemaker, defibrillator, and heart valve interventions serve heart failure and arrhythmia patient cohorts. MDR post-market surveillance mandates with fifteen-year follow-up obligations impose steep compliance cost escalations on cardiac device manufacturers.
- Neurology:Cochlear implants and deep brain stimulation systems address sensory and movement disorders. Pediatric screening mandate expansion across Nordic health ministries is broadening addressable patient pools.
- Urology:Artificial urinary sphincters and penile prostheses serve functional restoration indications. Smaller addressable populations limit dedicated manufacturing scale relative to cardiac and orthopedic segments.
Orthopedic applications hold volume leadership, though neurology is expanding most quickly through cochlear implant candidacy broadening.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU MDR implementation timelines and national reimbursement frameworks are redistributing procurement authority across European implant markets. Germany's cardiac centers and Switzerland's orthopedic manufacturers anchor current supply capacity. Nordic pediatric screening mandates and Eastern European procedure rate gaps define expansion vectors.
Germany
Berlin, Munich, and Hamburg cardiac implant centers generate procedure density that sustains specialized device procurement at scale. The Federal Joint Committee (G-BA) maintains stringent health technology assessment requirements that filter market access for novel cardiac and orthopedic systems. Tuttlingen and Solothurn manufacturing clusters concentrate cementless fixation system production for European distribution.
France
Paris hospital leasing consortia now prioritize total cost-of-ownership contracts spanning device lifespan and rehabilitation services. The Haute Autorité de Santé (HAS) applies divergent evidence requirements compared to German and UK counterparts, forcing parallel dossier maintenance. Île-de-France academic medical centers concentrate heart valve procedure volumes for younger patient cohorts favoring polymer-composite designs.
Switzerland
Swissmedic maintains autonomous certification standards that create parallel compliance obligations for Alpine market entry. Zurich and Basel precision engineering clusters anchor porous scaffold production for patient-specific orthopedic implants. The regulatory pathway allows manufacturers to de-risk EU MDR delays through early Swiss market establishment.
Sweden
Universal newborn hearing screening mandates expand pediatric cochlear implant candidacy pools faster than adult segments. The Swedish Medical Products Agency (MPA) coordinates with Nordic health ministries on harmonized reimbursement coding for auditory devices. Stockholm university hospitals prioritize closed-loop neurostimulation architectures for cardiac resynchronization therapy.
Poland
Underpenetrated orthopedic implant procedure rates relative to Western European benchmarks create expansion corridors for joint replacement systems. The Office for Registration of Medicinal Products, Medical Devices and Biocidal Products processes CE-marked device registrations with shorter queues than German notified bodies. Warsaw and Kraków hospital networks are consolidating procurement authority to negotiate volume-based contracts with multinational suppliers.
Europe Artificial Organs and Bionic Implants Market Competitive Landscape
On the supply side, the industry is consolidating around integrated health networks with balance sheet capacity to absorb long-term service commitments. Tiered competitive dynamics separate multinational platform players from specialized rehabilitation-focused operators and emerging robotics-integrated challengers. Dominant competitive moves include hospital leasing consortium formation and M&A targeting surgical robotics capabilities.
Within the multinational platform tier, Medtronic plc and Zimmer Biomet Holdings Inc. exemplify scale-driven operators with diversified implant portfolios spanning cardiac, orthopedic, and neurological applications. Ottobock occupies a distinct position among rehabilitation-anchored specialists focused on bionic limb fitting protocols. Cochlear Limited represents the auditory implant archetype with direct-to-clinician training programs that influence device selection protocols.
| Leading Market Players |
|---|
| Medtronic plc |
| Zimmer Biomet Holdings Inc. |
| Ottobock |
| Sonova |
| Ossur hf |
| Edwards Lifesciences Corporation |
| Ekso Bionics Holdings Inc. |
| Boston Scientific Corporation |
| Cochlear Limited |
| Others |
Supply & Pricing Matrix
Tuttlingen and Solothurn orthopedic manufacturing clusters anchor European cementless fixation system production, translating concentrated precision-engineering capacity into pricing power for German and Swiss suppliers serving hospital procurement committees.
Pricing Analysis
Certification level (MDR/CE-grade) creates the primary spread between premium and standard tiers across European implant markets. Three-tier pricing structure across premium, standard, and economy levels segments by biocompatibility documentation depth and notified body prestige. Pricing pressure stems from hospital leasing consortia in Paris and Milan negotiating total cost-of-ownership contracts spanning device lifespan and rehabilitation services. Public hospital networks in Poland and the Czech Republic exhibit highest price sensitivity, while German cardiac implant centers prioritize performance metrics over unit cost.
Supply Chain Analysis
Platinum-iridium electrode scarcity concentrated in South African and Russian refining capacity dominates supply risk exposure for cochlear and neurostimulation manufacturers. Raw material dependencies center on titanium-niobium alloys from German metallurgical processors, pyrolytic carbon substrates from specialized French coating facilities, and lithium-iodine battery cells from Swiss precision chemical suppliers. Single-source vulnerability in noble metal electrode supply chains threatens production continuity for auditory implant producers. Distribution runs through authorized dealer networks serving hospital purchasing committees and specialized rehabilitation center consortia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a defensive-moat arena where MDR regulatory entrenchment and hospital switching costs protect incumbent positions against disruption.
For Market Incumbents: Pre-empt emerging robotics-integrated challengers by anchoring hospital system partnerships through long-term service contracts spanning surgical training, device maintenance, and rehabilitation protocol integration. Secure backward integration into REACH-compliant biomaterial supply chains to de-risk platinum-iridium electrode scarcity exposure. Prioritize notified body relationship investment to compress certification queue times relative to competitor portfolios.
For New Entrants and Emerging Players: Mid-market orthopedic implants in Poland and the Czech Republic represent the most penetrable entry point given underpenetrated procedure rates relative to Western European benchmarks. Robotics-enabled surgical placement systems for revision-sensitive joint procedures offer white-space positioning against established cementless fixation suppliers. Pursue direct-to-clinician training programs that lock in device selection protocols before incumbent contract renewals.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specialized rehabilitation-anchored operators with proprietary fitting protocols over diversified platform players facing MDR compliance cost escalations. Acquisition targets with established Swissmedic certification pathways offer de-risked EU market entry vehicles. Monitor notified body capacity expansion announcements as inflection signal for new product launch velocity recovery.
| Strategic Initiative | Industry Significance |
|---|---|
| MDR Certification Pathway Investment | Notified body capacity constraints in Germany and the Netherlands create first-mover advantage for prepared dossiers. |
| Hospital System Partnership | Paris and Milan leasing consortia concentrate procurement authority among integrated health networks with balance sheet capacity. |
| Biomaterial Backward Integration | REACH-compliant titanium-niobium alloy supply anchors regulatory pathway acceleration for heart valve producers. |
| Robotics-Enabled Surgical Platform | Rotterdam and Stockholm university hospitals prioritize haptic feedback systems for revision-sensitive orthopedic procedures. |
| Reimbursement Strategy | Divergent NICE, HAS, and G-BA evidence requirements demand parallel health technology assessment dossier maintenance. |
Research Methodology
Cross-validation between hospital procurement database analysis and clinical stakeholder interviews anchors the qualitative findings in this study. Primary fieldwork engaged cardiac implant center directors, orthopedic purchasing committee members, biomedical engineers, GPO contracts managers, and rehabilitation center administrators across Germany, France, Switzerland, and Nordic markets. Secondary validation drew from EMA MDR guidance documents, notified body certification records, hospital procurement registries, and national health technology assessment publications. Bottom-up procedure volume modeling triangulates against top-down manufacturer revenue segmentation.
Calibration against historical certification timelines and reimbursement decision lags shapes the analytical framework across the projection horizon. Segmentation dimensions span product type, technology platform, end-user category, and application specialty, with regional regulatory cluster as an additional modeling layer. CAGRs derive from procedure volume elasticity to screening mandate expansion, aging demographic penetration, and robotics adoption curves. Forecast inputs incorporate platinum-iridium supply chain disruption scenarios and MDR post-market surveillance cost trajectories.
Macroeconomic conditions sit as an overlay; deviation in eurozone healthcare expenditure growth and noble metal commodity volatility would shift the trajectory. Forecasts reflect assumptions around notified body capacity normalization and cross-border reimbursement harmonization progress. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Injectable Drug Delivery Devices Market
Medical Devices
Capsulorhexis Forceps Market
Medical Devices
Handheld Ultrasound Devices Market
Medical Devices
Global Contrast Media Injector Market
Medical Devices
Subcutaneous Drug Delivery Devices Market
Medical Devices
ECG Sensor Patch Market
Medical Devices
Global Acetabular Prostheses Market
Medical Devices
Veterinary Glucometers Market
Medical Devices
Global Angiography Devices Market
Medical Devices
Surgical Loupes and Cameras Market
Medical Devices
Artificial Eye Lenses Market
Medical Devices
Baby Thermometer Market
Medical Devices
Heart Defect Closure Devices Market
Medical Devices
Sinus Irrigation Systems Market
Medical Devices
Global Anesthesia Gas Blender Market
Medical Devices
Medical Cyclotron Market