
 India Fetal and Neonatal Care Equipment Market | 2026-2036
India Fetal and Neonatal Care Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
India Fetal and Neonatal Care Equipment Market Foresight
India's medical device manufacturing corridors in Gujarat and Karnataka are reconfiguring supply patterns for neonatal equipment. Medtronic leverages its cardiac monitoring heritage to anchor high-end fetal monitor positioning in tertiary hospitals. Koninklijke Philips sustains R&D intensity across digital phototherapy and wireless monitoring platforms. Phoenix Medical Systems dominates indigenous warmer production, competing aggressively on price in government tenders across Tier-2 cities.
Fetal and neonatal care equipment encompasses incubators, radiant warmers, cardiorespiratory monitors, and mechanical ventilators engineered for thermoregulation within 36.5°C to 37.5°C, oxygen titration, and continuous vital sign surveillance in premature or compromised newborns. These systems serve the clinical imperative of stabilizing low-birth-weight infants during the first hours and days of extrauterine life. Among device types, incubators and warmers occupy the volume core due to universal NICU requirements, while ventilators command premium positioning given technical complexity and import dependence. Digital technology leads the technology split as hospitals phase out analog interfaces, though wireless adoption remains constrained by hospital IT infrastructure gaps in smaller facilities.
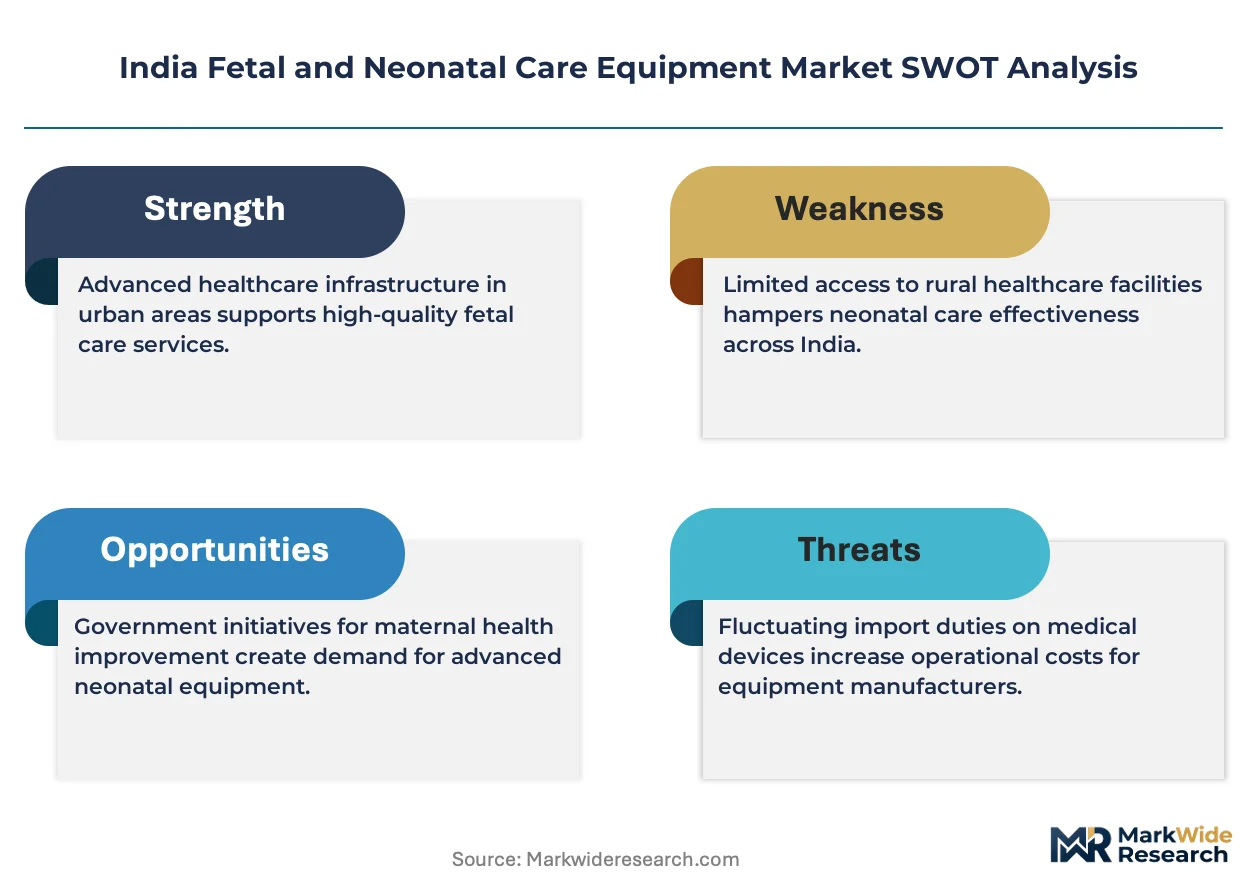
CDSCO mandates medical device registration under the Drugs and Cosmetics Act, while BIS certification governs electrical safety standards for infant warmers and incubators sold domestically. The PLI scheme for medical devices is channeling capital toward local ventilator and monitor assembly, tightening quality benchmarks for participants. Stakeholders must monitor how Ayushman Bharat reimbursement rate revisions affect procurement specifications at district hospitals, as these facilities represent the fastest-expanding addressable base.
Market Dynamics
Ayushman Bharat's district hospital expansion is compressing procurement cycles and forcing equipment specifications toward BIS-certified domestic sourcing, rewiring traditional import-dependent supply channels.
Growth Catalysts
- Ayushman Bharat NICU Expansion:District hospitals in Uttar Pradesh, Bihar, and Madhya Pradesh are adding neonatal intensive care capacity under government reimbursement frameworks, creating sustained equipment demand at the Tier-2 level.
- CDSCO Quality Norm Tightening:Stricter registration requirements for imported warmers and ventilators are redirecting hospital procurement toward BIS-certified domestic manufacturers with verified component traceability.
- Digital Interface Migration:Hospitals are phasing out analog monitoring systems in favor of touchscreen-integrated platforms that enable centralized data logging and remote telemetry.
Market Restraints
- Import Dependence for Ventilators:High-complexity mechanical ventilators remain concentrated among foreign suppliers, exposing procurement budgets to currency fluctuation and extended lead times.
- Copper and Semiconductor Input Volatility:Electrical components and sensor chipsets face price instability, compressing margins for domestic warmer and incubator assembly operations.
- Wireless Infrastructure Gaps:Smaller district hospitals lack IT backbone for continuous monitoring data transmission, constraining adoption of connected neonatal platforms regardless of clinical utility.
Strategic Opportunities
- PLI Scheme Medical Device Assembly:Production-linked incentive capital is flowing toward ventilator and monitor manufacturing, enabling local players to bridge quality gaps with import substitutes.
- Maharashtra Corridor Export Hub:Mumbai-Pune medical device clusters are developing outbound supply capability to serve neighboring South Asian markets with BIS-certified equipment.
- Phototherapy-Wireless Convergence:Integration of LED phototherapy with cloud-based jaundice monitoring protocols opens premium positioning in tertiary hospital chains seeking protocol standardization.
Industry Challenges
- Biomedical Engineer Talent Scarcity:District hospitals struggle to recruit technicians capable of maintaining digital monitoring platforms, forcing manufacturers to absorb training costs or risk equipment downtime.
- CDSCO Registration Timeline Compression:Expedited approval demands for Ayushman Bharat tenders strain regulatory affairs teams, delaying market entry for modified product lines.
- Legacy Analog System Interoperability:Hybrid environments where new digital monitors must interface with existing hospital information systems create integration failures and data fragmentation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Fetal and Neonatal Care Equipment Market |
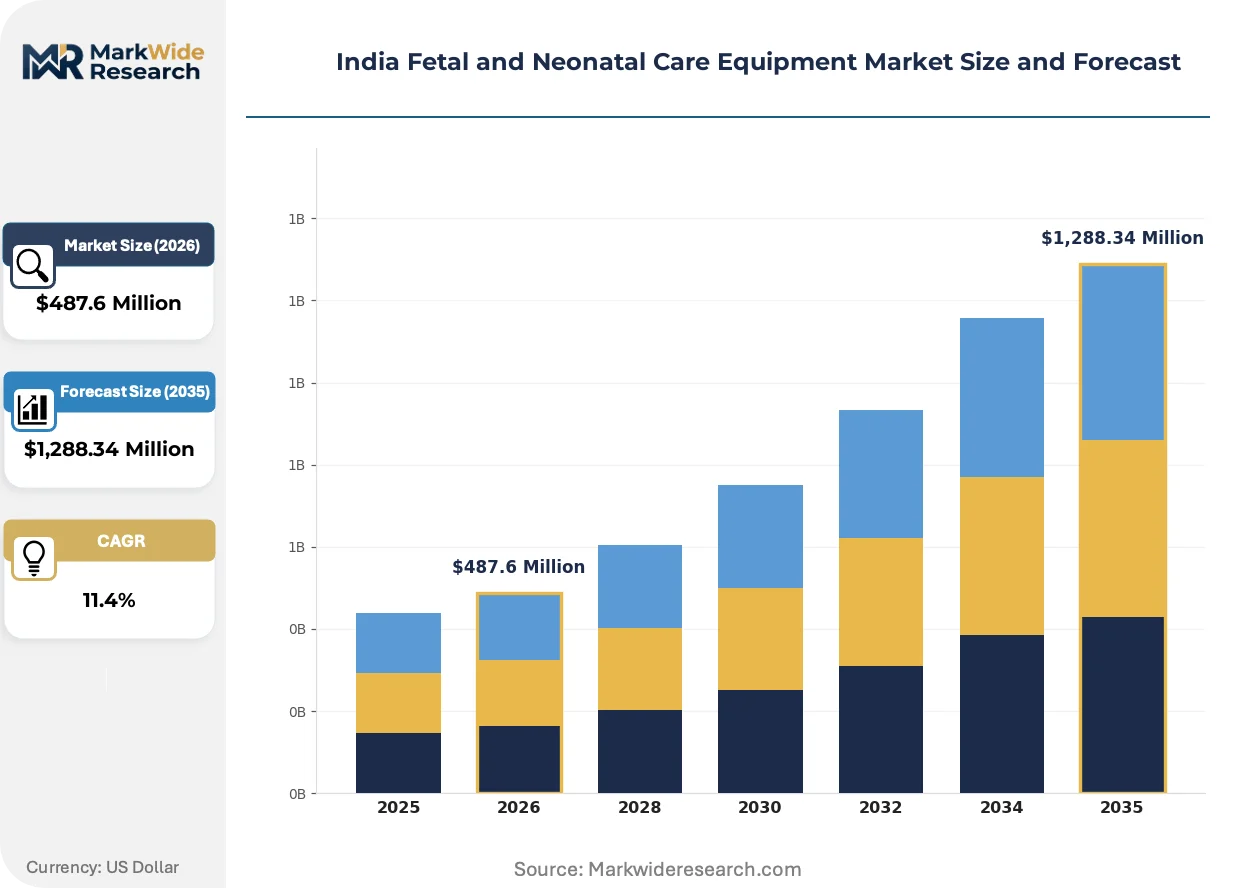
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,288.34 Million |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Device Type: Incubators, Warmers, Monitors, Ventilators Application: Neonatal Intensive Care Unit, Home Care, Hospitals, Clinics End User: Health Care Facilities, Pediatricians, Obstetricians, Emergency Departments Technology: Digital, Analog, Wireless, Standalone |
| Companies Covered | Medtronic, Drägerwerk, Becton Dickinson, Getinge, Atom Medical Corporation, Masimo, Koninklijke Philips, Phoenix Medical Systems, GE Healthcare, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Fetal and Neonatal Care Equipment Market Shifts & Advancements
Equipment specifications are pivoting toward integrated digital ecosystems, with thermoregulation and monitoring functions converging on unified platforms that reduce bedside device proliferation.
Phototherapy systems with embedded irradiance sensors and automatic dose-logging capabilities are rendering obsolete standalone phototherapy units that require manual timer management and paper-based treatment records. Tertiary hospital chains in Maharashtra and Gujarat are specifying these integrated platforms in bulk procurement tenders. The shift is compressing supplier margins on conventional phototherapy hardware while elevating software-enabled service contracts.
CDSCO's 2023 medical device registration amendments now mandate adverse event reporting for Class C and D neonatal equipment, including ventilators and incubators. Domestic manufacturers are restructuring quality management systems to accommodate post-market surveillance obligations previously absent from the regulatory framework. Imported device holders face compressed timelines for establishing India-based pharmacovigilance infrastructure, favoring local assembly operations with embedded compliance capabilities.
District hospital buying committees are consolidating vendor relationships around single-source equipment contracts that bundle installation, training, and multi-year maintenance. This pattern displaces the prior fragmented procurement model where separate purchases for warmers, monitors, and phototherapy units went to competing suppliers. The consolidation is most visible in Madhya Pradesh and Bihar, where Ayushman Bharat implementation teams prioritize vendor stability over lowest-bidder selection to ensure operational continuity in remote facilities.
India Fetal and Neonatal Care Equipment Market Segmentation
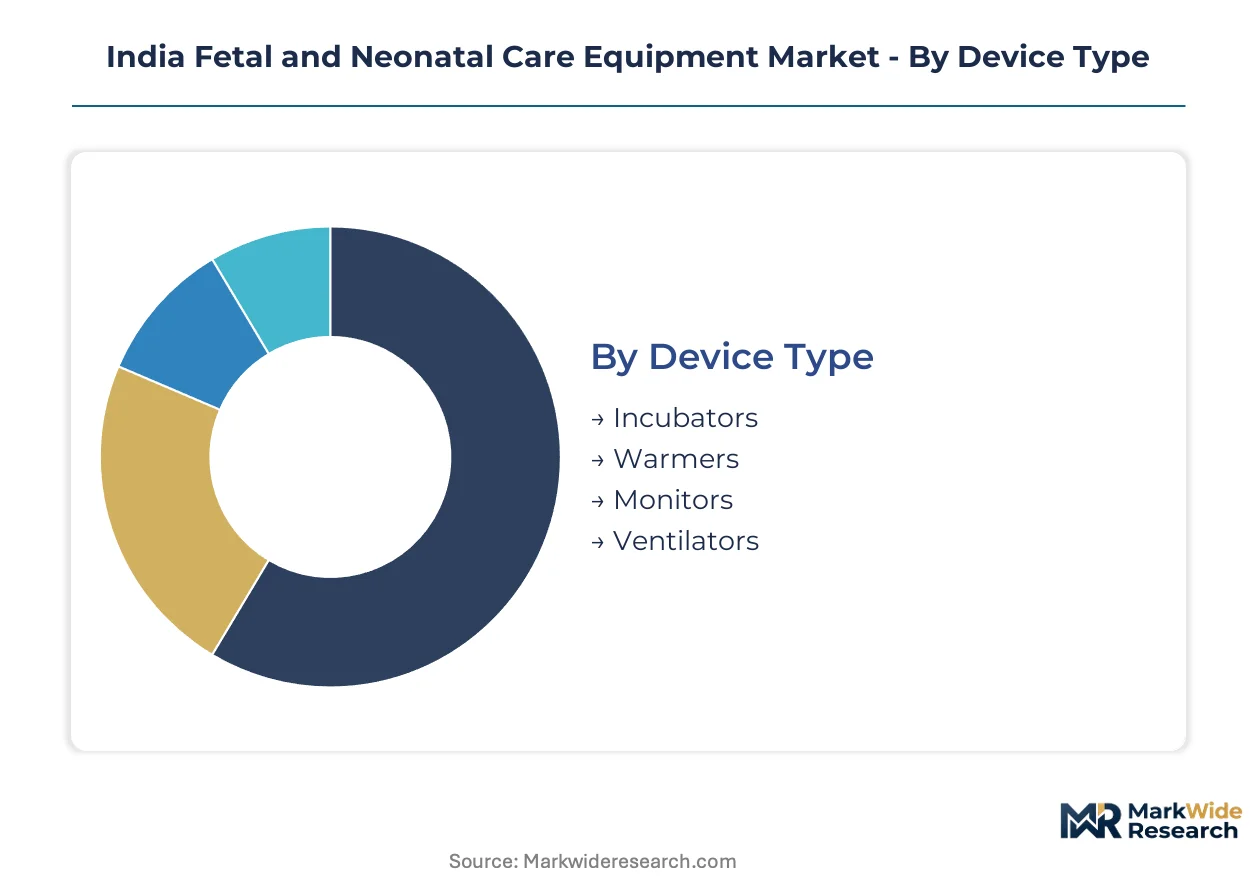
Segmentation of India's fetal and neonatal care equipment market reveals how procurement priorities diverge across facility tiers and care settings. Understanding these splits enables manufacturers to align product portfolios with the distinct technical and budgetary constraints governing tertiary hospitals versus district-level NICU expansions.
Device Type:
Use cases span thermoregulation, continuous surveillance, and respiratory support, with each device category carrying distinct certification burdens and import dependency profiles.
- Incubators:Enclosed microclimate systems maintain humidity and temperature for premature infants below 2kg birth weight. Demand concentrates in Maharashtra's Mumbai-Pune corridor where private hospital chains specify BIS-certified units with servo-controlled oxygen blending for high-acuity NICUs.
- Warmers:Radiant heat platforms with phototherapy integration serve delivery rooms and step-down units requiring rapid thermal stabilization. Government tenders across Uttar Pradesh and Bihar favor Phoenix Medical Systems and comparable domestic suppliers meeting compressed procurement cycles under Ayushman Bharat.
- Monitors:Cardiorespiratory surveillance devices track heart rate, SpO2, and apnea events through integrated sensor arrays.
- Ventilators:Mechanical respiratory support systems for neonates remain import-dependent, exposing procurement budgets to currency fluctuation and extended CDSCO registration timelines.
The dominant share belongs to incubators and warmers, while ventilators are closing the gap fastest as district hospitals upgrade respiratory capabilities.
Application:
Care settings range from centralized high-acuity units to distributed home-based monitoring, with reimbursement frameworks determining equipment specifications at each tier.
- Neonatal Intensive Care Unit:Centralized units in tertiary hospitals deploy full-spectrum equipment including mechanical ventilation and multi-parameter monitoring. Maharashtra and Gujarat facilities specify integrated digital platforms enabling centralized data logging for quality accreditation.
- Hospitals:General medical facilities with maternity wards require intermediate-capability warmers and basic monitoring for stabilized newborns.
- Clinics:Outpatient and primary care settings utilize portable phototherapy and basic vital sign measurement for screening and referral.
- Home Care:Emerging segment for post-discharge monitoring of low-birth-weight infants in rural areas with limited NICU access.
NICU applications command the highest equipment value per bed, though hospital general ward deployments are expanding most quickly as Ayushman Bharat broadens coverage.
End User:
Procurement authority sits with distinct clinical and administrative stakeholders whose priorities diverge on upfront cost versus total cost of ownership.
- Health Care Facilities:Hospital administrators and biomedical engineering departments drive bulk purchasing decisions, increasingly consolidating vendor relationships around single-source contracts bundling installation, training, and maintenance across Madhya Pradesh and Bihar.
- Pediatricians:Specialist physicians influence specifications for monitoring accuracy and alarm algorithms in tertiary settings.
- Obstetricians:Maternity service leaders prioritize delivery-room resuscitation equipment and immediate thermoregulation capabilities.
- Emergency Departments:Trauma and acute care units require portable stabilization equipment for unexpected deliveries and neonatal transport.
Health care facilities control volume procurement, while pediatricians are gaining influence fastest as clinical outcome metrics penetrate purchasing criteria.
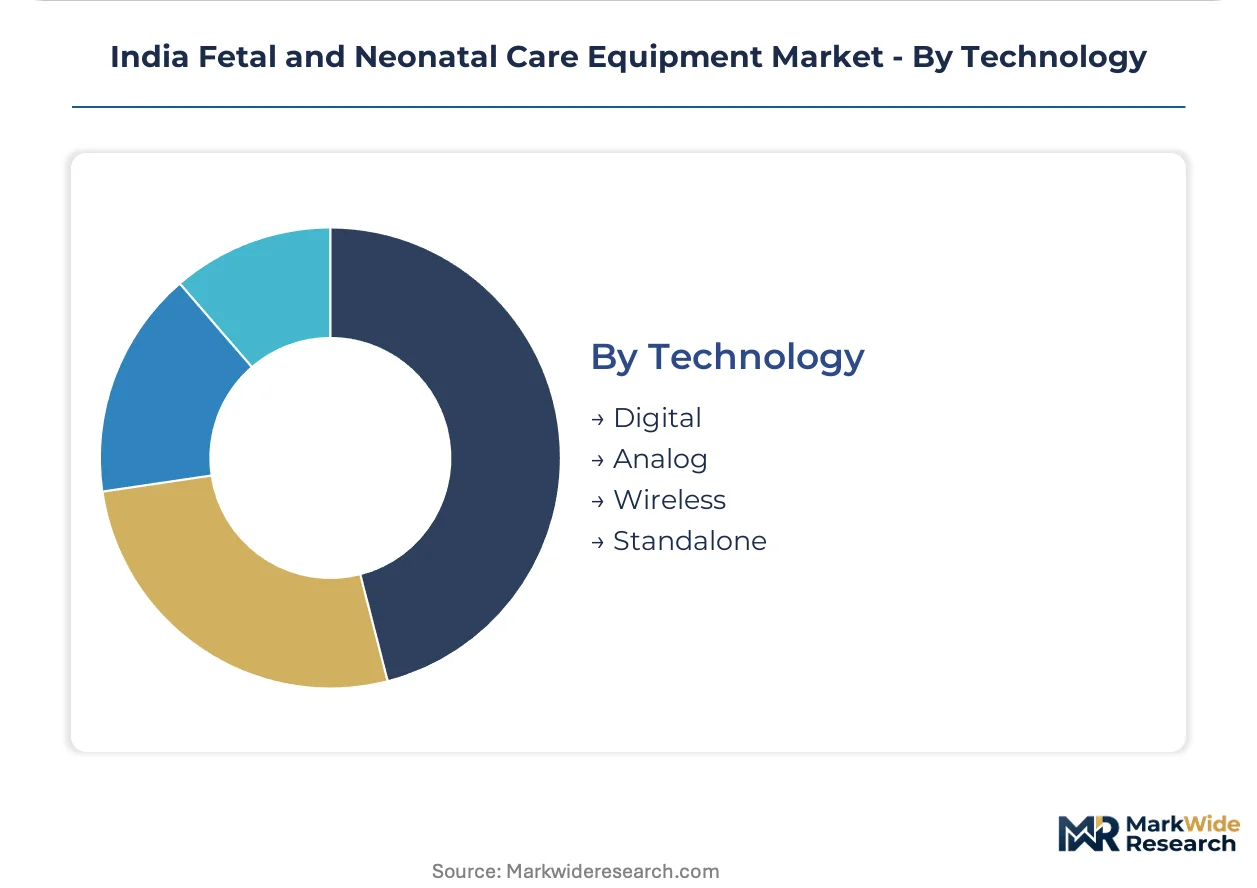
Technology:
Interface architecture determines integration potential with hospital information systems and remote telemetry capabilities.
- Digital:Touchscreen-integrated platforms with centralized data logging and automated alarm management. District hospitals in Tier-2 cities are phasing out analog interfaces, though IT infrastructure gaps constrain full functionality deployment.
- Wireless:Cloud-connected monitoring enabling remote surveillance and protocol standardization across hospital chains.
- Analog:Legacy standalone devices with physical displays and manual record-keeping requirements.
- Standalone:Non-networked equipment operating independently of hospital IT backbone, prevalent in smaller facilities with limited technical support.
Digital platforms hold the dominant installed base position, while wireless configurations are climbing fastest as tertiary chains pursue centralized quality management.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Domestic manufacturing clusters in Gujarat and Karnataka are reconfiguring procurement flows for neonatal equipment, while government reimbursement frameworks redirect demand toward district hospitals in the northern and central states. CDSCO registration requirements and BIS certification standards now govern equipment sourcing decisions across all major consumption zones.
Maharashtra
Mumbai-Pune corridor hosts the densest concentration of private hospital chains and medical device procurement networks in western India. CDSCO's tightened quality norms for imported ventilators are pushing tertiary facilities toward BIS-certified domestic alternatives. The state's medical device clusters are developing outbound supply capability to serve neighboring markets with certified equipment.
Gujarat
Ahmedabad-Vadodara industrial belt anchors indigenous production of infant warmers and basic monitoring systems for government tenders. PLI scheme capital is flowing toward ventilator assembly operations, enabling local players to bridge quality gaps with import substitutes. Pharmaceutical and chemical engineering infrastructure supports component sourcing for device manufacturers.
Uttar Pradesh
Ayushman Bharat's district hospital expansion is compressing procurement cycles across Lucknow, Kanpur, and Varanasi medical zones. State health departments are consolidating vendor relationships around single-source contracts bundling installation, training, and multi-year maintenance. BIS-certified domestic suppliers compete aggressively on price in compressed tender timelines.
Karnataka
Bengaluru's medical technology corridor integrates software development capability with hardware assembly for digital monitoring platforms. The state's electronics manufacturing infrastructure supports sensor chipset sourcing for indigenous monitor production. Biomedical engineer talent scarcity constrains full deployment of connected neonatal platforms in smaller district facilities.
Madhya Pradesh
Indore-Bhopal medical zones represent the fastest-expanding addressable base for basic NICU equipment under central government reimbursement programs. Procurement committees prioritize vendor stability over lowest-bidder selection to ensure operational continuity in remote facilities. Legacy analog system interoperability challenges create hybrid environments where new digital monitors must interface with existing hospital information systems.
India Fetal and Neonatal Care Equipment Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying sensors, heating elements, and control modules. The market structure tilts toward consolidation among foreign-origin system vendors while fragmenting across domestic assembly operations for standard warmers and monitors. Three archetypes dominate: multinational platform vendors with cardiac monitoring heritage, indigenous price-competitive fabricators, and component suppliers pivoting toward finished device assembly. Competitive moves concentrate on PLI-linked capacity expansion and single-source contract consolidation for district hospital tenders.
Among multinational platform vendors, Medtronic and Koninklijke Philips occupy positions reflecting cardiac monitoring and digital phototherapy heritage respectively. Phoenix Medical Systems represents the indigenous fabricator archetype competing on price in government procurement. Drägerwerk and GE Healthcare sit within the premium system tier serving tertiary hospital chains with integrated platform specifications.
| Leading Market Players |
|---|
| Medtronic |
| Drägerwerk |
| Becton Dickinson |
| Getinge |
| Atom Medical Corporation |
| Masimo |
| Koninklijke Philips |
| Phoenix Medical Systems |
| GE Healthcare |
| Others |
Supply & Pricing Matrix
Ahmedabad-Vadodara industrial belt capacity additions are compressing domestic warmer pricing while elevating BIS-certified component premiums, redistributing margin capture between fabricators and upstream suppliers.
Pricing Analysis
CDSCO dictates the pricing tier structure across the India fetal and neonatal care equipment market, separating import-registered ventilators from BIS-certified domestic warmers. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and after-sales bundling intensity. Price erosion runs through economy-tier warmers as Phoenix Medical Systems and comparable domestic fabricators compete on compressed government tender cycles. District hospital procurement committees demonstrate highest price sensitivity, while Maharashtra tertiary chains prioritize total cost of ownership over upfront unit economics.
Supply Chain Analysis
Extended payment terms from 60 to 90 days are becoming standard for domestic warmer manufacturers supplying government tenders, straining working capital and favoring larger fabricators with supply-chain finance facilities. Component sourcing draws from China for sensor chipsets, Germany for precision heating elements, and domestic Gujarat-Karnataka clusters for electrical assemblies. Copper and semiconductor input volatility constitutes the primary supply chain risk, exposing margin structures to commodity price swings. Distribution runs through Mumbai-Pune medical device procurement networks serving western and central India, with direct-to-hospital contracts displacing traditional distributor intermediation in Madhya Pradesh and Bihar.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Domestic manufacturers face substitution pressure from refurbished import equipment circulating through informal channels, requiring incumbents to harden quality differentiation and service bundling to defend positioning.
For Market Incumbents: Harden BIS certification moats by embedding pharmacovigilance infrastructure ahead of CDSCO's adverse event reporting mandates. Absorb biomedical engineer training costs to lock district hospitals into multi-year maintenance contracts, neutralizing price competition from refurbished ventilator imports. Vertical integration into sensor chipset sourcing mitigates copper and semiconductor volatility exposure. For New Entrants and Emerging Players: Madhya Pradesh and Bihar district hospitals represent the most penetrable entry point, where vendor consolidation under Ayushman Bharat has displaced fragmented procurement without fully satisfying service coverage gaps. Single-source contract bundling—installation, training, and five-year maintenance—offers the strongest go-to-market angle against incumbent price leaders. For Investors and Strategic Acquirers: Carve-out targets emerge from pharmaceutical conglomerates with dormant medical device divisions holding dormant CDSCO registrations and dormant Maharashtra distribution relationships. Five-to-ten year viability hinges on PLI scheme qualification and Ayushman Bharat reimbursement rate stability. Monitor CDSCO registration timeline compression as the critical inflection signal for domestic assembly valuation multiples.| Strategic Initiative | Industry Significance |
|---|---|
| BIS Certification Investment | CDSCO's tightened norms redirect procurement toward domestically certified alternatives with verified component traceability. |
| Biomedical Engineer Training Programs | District hospital talent scarcity forces manufacturers to absorb onboarding costs, creating vendor lock-in through capability dependency. |
| PLI Scheme Capacity Expansion | Production-linked incentive capital enables local ventilator assembly to bridge quality gaps with import substitutes. |
| Single-Source Contract Consolidation | Ayushman Bharat implementation teams in Madhya Pradesh and Bihar prioritize vendor stability over lowest-bidder selection. |
| Cloud-Integrated Phototherapy Development | Maharashtra tertiary chains specify LED phototherapy with automatic dose-logging for protocol standardization across hospital networks. |
Research Methodology
The analysis maps incubators, warmers, monitors, and ventilators, each validated through hospital procurement committees, biomedical engineering departments, and GPO contracts managers. Primary interviews with CDSCO regulatory affairs leads and PLI scheme administrators combined with secondary validation from hospital procurement databases, BIS certification records, and CMS Medicare comparable data. Bottom-up equipment unit economics triangulated against top-down reimbursement flow analysis.
Assumptions held Ayushman Bharat expansion rates and CDSCO registration timelines fixed while varying copper and semiconductor input cost trajectories across the projection horizon. Segmentation modeling spanned device type, application setting, end-user authority, and technology interface architecture. CAGRs derived from equipment replacement cycles, NICU bed expansion rates, and digital migration penetration curves through district hospital IT infrastructure assessments.
Macroeconomic conditions sit as an overlay; deviation in rupee-dollar exchange rates or central government health expenditure allocation would shift the trajectory. Forecasts reflect documented assumptions regarding PLI scheme continuity and CDSCO regulatory intensity. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Neonatal Care
Neonatal Dialysis Market
Neonatal Care
North America Fetal and Neonatal Care Equipment Market
Neonatal Care
Necrotising Enterocolitis (NEC) Market
Neonatal Care
India Neonatal and Prenatal Devices Market
Neonatal Care
Global Preterm Birth and PROM Testing Market
Neonatal Care
Neonatal Intensive Care Market
Neonatal Care
Neonatal Phototherapy Market
Neonatal Care
Japan Neonatal and Prenatal Devices Market
Neonatal Care
Neonatal Phototherapy Devices Market
Neonatal Care
Neonatal and Prenatal Devices Market
Neonatal Care
Global Neonatal Thermoregulation Market
Neonatal Care
Germany Neonatal and Prenatal Devices Market
Neonatal Care
Neonatal Ventilators Market
Neonatal Care
Neonatal Respiratory Distress Syndrome Market
Neonatal Care
Perinatal Software Market
Neonatal Care
Neonatal Respiratory Distress Syndrome Treatment Market