
 Infrastructure Monitoring Market | 2026-2036
Infrastructure Monitoring Market Size, Share, and Industry Trends Forecast 2026-2036
Infrastructure Monitoring Market Intelligence
The traditional channel of direct sales and large-scale system integrators is fragmenting as cloud-based platforms gain traction. Siemens AG leverages its extensive industrial portfolio to embed monitoring solutions within large-scale energy and transportation projects. Schneider Electric SE specializes in data center infrastructure management, offering integrated power and cooling monitoring. Trimble Inc. dominates the geospatial segment, providing solutions for civil and structural health monitoring.
Infrastructure monitoring involves deploying sensors and software to continuously assess the operational health of physical and IT systems. These solutions often utilize IoT-enabled devices to capture real-time data on parameters like vibration, temperature, and network latency for predictive maintenance. While network monitoring represents a mature solution category, demand for application performance monitoring grows with the complexity of modern software stacks. Cloud-based deployment models are supplanting on-premises solutions, particularly for monitoring distributed assets like telecom infrastructure and energy grids.
Regulatory mandates for critical infrastructure resilience directly shape market requirements. In the United States, FERC enforces grid reliability standards, while the EU's NIS2 Directive imposes stringent cybersecurity obligations on operators of essential services. In parallel, China's MIIT sets performance benchmarks for its national telecommunications networks. Stakeholders must now decide how to integrate AI-driven analytics to move from reactive alerts to proactive, automated remediation.
Market Dynamics
The convergence of operational technology (OT) from physical systems with information technology (IT) platforms defines the market's structure. This integration, powered by IoT sensors and AI analytics, is creating a unified view of infrastructure health across previously siloed domains.
Growth Catalysts
- Regulatory Mandates:Directives such as the EU's NIS2 and FERC grid reliability standards in the US compel operators of critical infrastructure to adopt continuous monitoring solutions to ensure resilience and report on cybersecurity posture.
- Predictive Maintenance Adoption:The expansion of IoT devices in telecom and energy sectors enables the collection of real-time performance data, which is essential for implementing predictive maintenance strategies and minimizing downtime.
- Infrastructure Modernization:Technology-forward economies, including Germany and Japan, are undertaking large-scale upgrades of public transit, energy grids, and water systems, embedding advanced monitoring capabilities from the project outset.
Market Restraints
- High Implementation Costs:The significant upfront capital expenditure required for deploying sensor networks across vast infrastructure, coupled with software integration costs, presents a substantial barrier for many organizations.
- Data Interoperability:A lack of standardization between proprietary legacy OT systems and modern IT monitoring platforms creates significant technical hurdles, complicating the creation of a single, unified data view.
- Cybersecurity Vulnerabilities:Connecting previously isolated critical infrastructure to the internet for remote monitoring introduces new attack vectors, increasing the risk of sophisticated cyber threats against essential services.
Strategic Opportunities
- Digital Twin Integration:Combining real-time sensor data with digital twin models offers an opportunity to simulate stress, predict failure points, and optimize the performance of complex assets like bridges and power plants.
- Environmental Compliance Monitoring:Solutions can be extended to monitor emissions, water usage, and energy consumption, helping organizations meet sustainability reporting requirements under frameworks like the CSRD.
- Monitoring-as-a-Service (MaaS):Developing managed service offerings allows providers to absorb the initial capital costs and technical complexity, offering monitoring capabilities to clients through a subscription-based operational expense model.
Industry Challenges
- Specialized Talent Scarcity:The market faces a shortage of professionals who possess dual expertise in domain-specific engineering (civil, electrical) and the data science or cybersecurity skills needed to analyze monitoring data effectively.
- Legacy System Integration:The process of retrofitting modern monitoring technologies onto aging infrastructure without disrupting essential public services is complex, risky, and requires extensive planning and phased deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Infrastructure Monitoring Market |
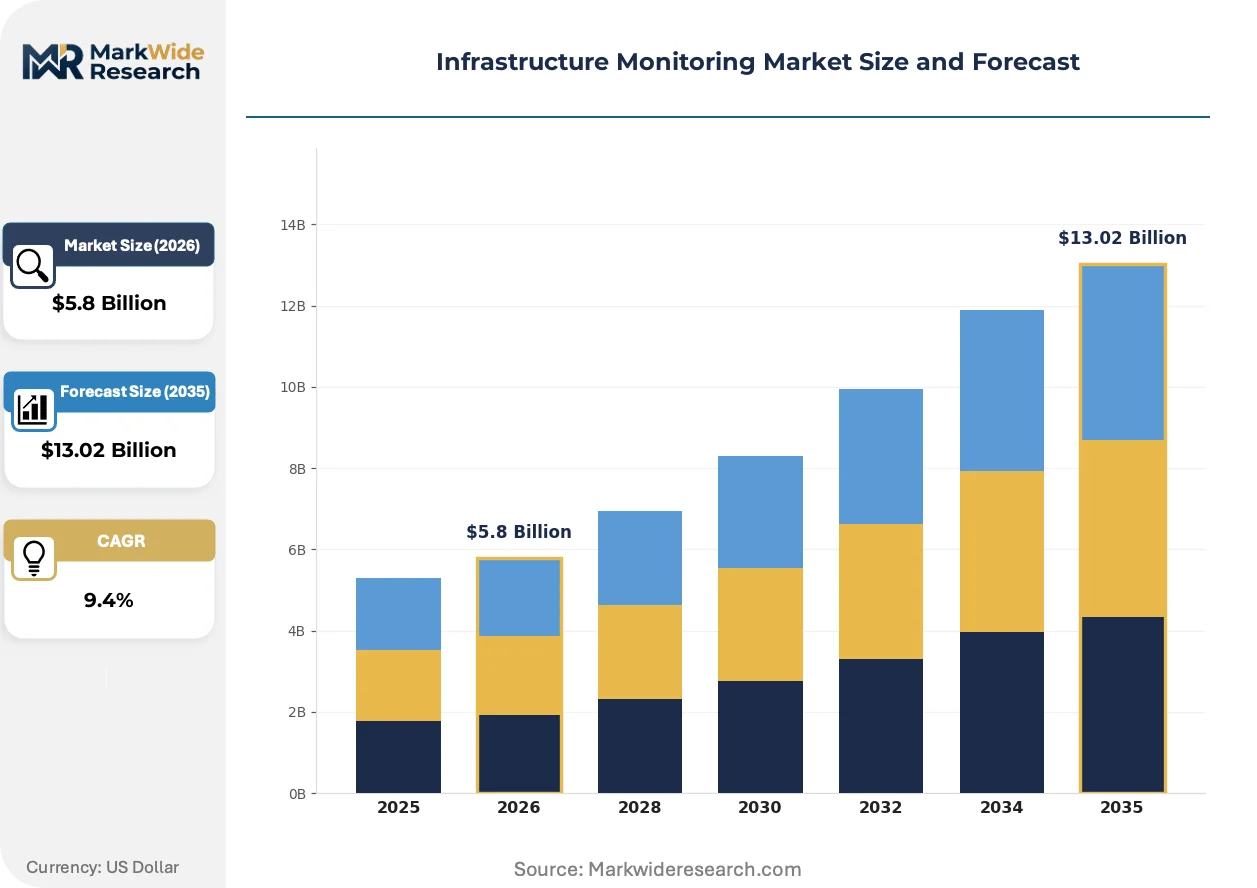
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $13.02 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premises, Cloud-Based, Hybrid, Edge, Multi-Cloud Solution Type: Network Monitoring, Server Monitoring, Application Performance, Security Monitoring, Database Monitoring Application: Data Centers, Telecom Infrastructure, Transportation Hubs, Smart Cities, Energy Grids End User Industry: Telecommunications, Energy Production, Transportation Services, Public Sector, Financial Institutions |
| Companies Covered | Honeywell International Inc., Siemens AG, Schneider Electric SE, Trimble Inc., National Instruments Corporation, Campbell Scientific, Inc., Acellent Technologies, Inc., Emerson Electric, Rockwell Automation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Infrastructure Monitoring Market Strategic Shifts & Innovations
The market's evolution is defined by a decisive shift away from reactive, alarm-based monitoring toward proactive, intelligent systems. This transition is driven by advancements in AI that enable predictive analytics and automated responses to potential system failures before they occur.
Digital twin technology provides a virtual representation of a physical asset or system, updated in real time with sensor data. The energy and aerospace industries are leading adopters, with civil infrastructure management accelerating its use for assets like bridges and tunnels. This technology is virtualizing the process of lifecycle management and failure analysis, enabling engineers to test scenarios without physical risk or service interruption.
Mandates for critical infrastructure resilience directly influence technology requirements and investment priorities. The EU's NIS2 Directive, for example, imposes strict cybersecurity and operational continuity obligations on essential service operators across sectors like transport and energy. This forces affected entities to deploy comprehensive monitoring solutions, particularly elevating demand for integrated network security and physical asset health platforms.
A transition from perpetual on-premises software licenses to flexible, cloud-based subscription models is gaining momentum. This change disrupts the traditional large-scale system integrator channel, favoring platform providers who offer scalable, pay-as-you-go services. The trend is most visible in sectors with distributed assets, such as telecommunications and renewable energy, where operators need to adjust monitoring capacity based on fluctuating asset portfolios.
Infrastructure Monitoring Market Segmentation
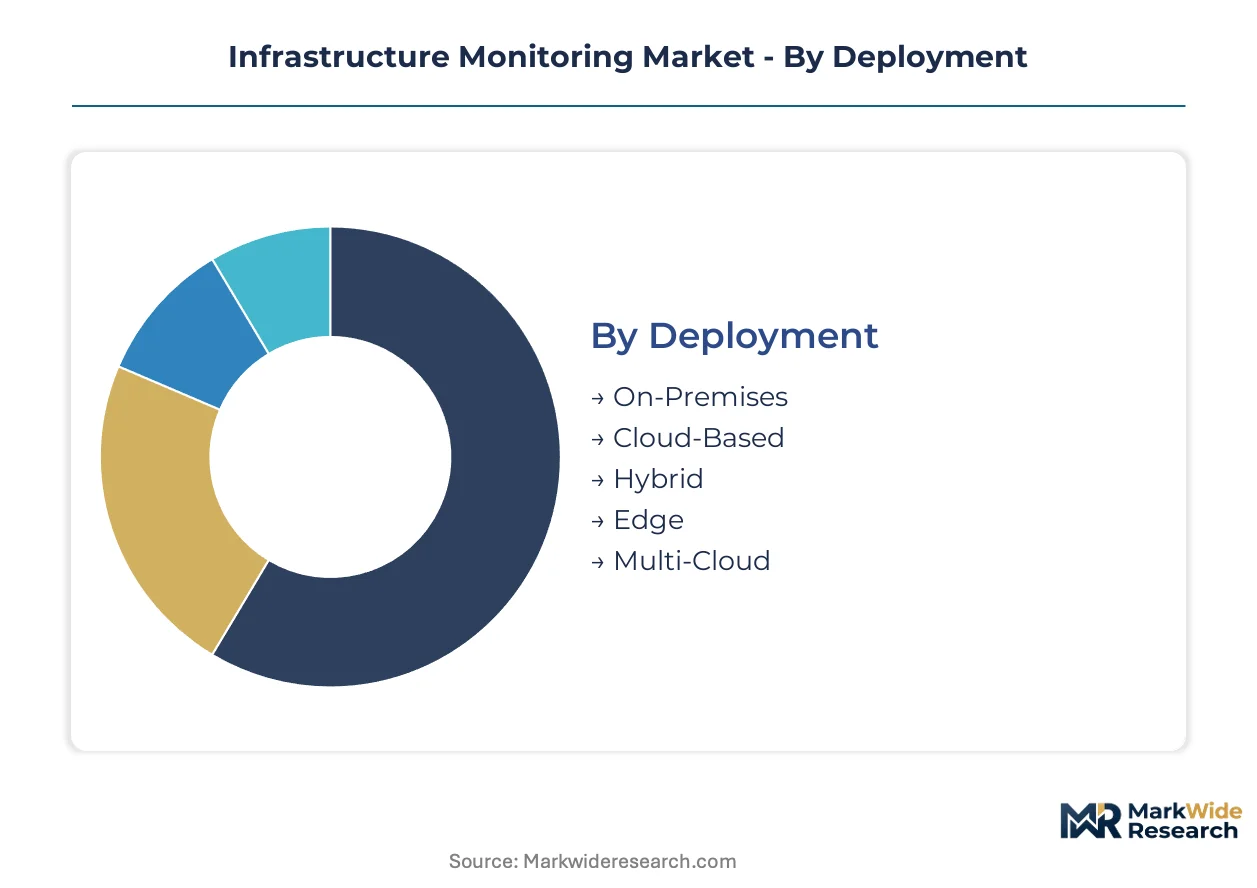
Infrastructure monitoring solutions are categorized to reflect diverse deployment strategies, specialized functionalities, and varied end-user requirements across critical sectors. Understanding these distinctions helps stakeholders identify specific market opportunities and tailor offerings to address unique operational challenges. This segmentation highlights the complexity and breadth of the infrastructure monitoring landscape.
Deployment:
After-sales service intensity varies significantly across deployment models, influencing long-term operational costs and support requirements for infrastructure monitoring. Each model presents distinct advantages regarding control, scalability, and data sovereignty for organizations.
- Cloud-Based:These solutions leverage remote servers and internet connectivity to deliver monitoring services, offering high scalability and reduced on-premises hardware management. Demand concentrates in sectors with distributed assets, such as telecommunications and renewable energy, driven by the need for flexible capacity.
- On-Premises:Deployments involve installing and running monitoring software and hardware directly within an organization's own data center or infrastructure. This model is preferred by entities with stringent security or regulatory compliance needs, such as financial institutions or government agencies, due to enhanced control over data.
- Hybrid:This model combines elements of both on-premises and cloud-based deployments, allowing organizations to maintain sensitive data locally while leveraging cloud resources for scalability. It caters to enterprises transitioning to cloud environments or managing mixed IT/OT infrastructure.
- Edge:Monitoring solutions are deployed close to the data source, such as sensors on a factory floor or remote energy grid components, enabling real-time processing and reduced latency.
- Multi-Cloud:Organizations utilize services from multiple cloud providers, enhancing resilience and avoiding vendor lock-in for their monitoring infrastructure.
On-Premises holds the largest share; momentum sits with Cloud-Based.
Solution Type:
The maturity of different solution types dictates their market penetration and the level of standardization observed in their implementation. Specialized solutions address distinct facets of infrastructure health and performance.
- Application Performance:These solutions monitor the performance and availability of software applications, tracking metrics like response times, error rates, and user experience. Demand is high in sectors reliant on complex software stacks, including financial services and telecommunications, to ensure continuous service delivery.
- Network Monitoring:This category involves tracking network traffic, device health, and connectivity to ensure optimal performance and identify bottlenecks or outages. It remains a foundational requirement for all enterprises, especially those managing extensive telecom infrastructure, to maintain uptime.
- Server Monitoring:Solutions focus on the health and performance of physical and virtual servers, including CPU usage, memory, disk I/O, and process activity. Enterprises with significant data center operations rely on this for resource optimization.
- Security Monitoring:These solutions continuously analyze system logs, network traffic, and user behavior to detect, prevent, and respond to cyber threats and vulnerabilities. Regulatory mandates like the EU's NIS2 Directive drive demand in critical infrastructure sectors.
- Database Monitoring:Tools specifically designed to track the performance, availability, and security of database systems, including query execution times and storage utilization.
Network Monitoring solutions maintain a foundational presence, while Application Performance monitoring is expanding most quickly.
Application:
Volume requirements for infrastructure monitoring differ considerably by application, reflecting the scale and criticality of the assets being managed. Each application area presents unique challenges for data collection and analysis.
- Telecom Infrastructure:Monitoring solutions ensure the uptime and performance of cellular networks, fiber optic cables, and data transmission equipment across vast geographical areas. The need for continuous service quality and rapid fault detection drives significant investment in this segment.
- Energy Grids:These applications involve monitoring power generation, transmission lines, and distribution networks to ensure reliability, efficiency, and compliance with grid stability standards enforced by bodies like FERC. Modernization efforts in Germany and Japan are integrating advanced monitoring.
- Data Centers:Monitoring systems track environmental conditions, power consumption, server performance, and network connectivity within data center facilities. Schneider Electric SE specializes in integrated power and cooling monitoring for these environments.
- Transportation Hubs:Solutions monitor the operational status of critical systems within airports, railway stations, and ports, including signaling, security, and passenger flow infrastructure.
- Smart Cities:This encompasses monitoring various urban systems, from public utilities and traffic management to environmental sensors, to enhance efficiency and livability.
Telecom Infrastructure represents a significant volume of deployments, with Smart Cities showing considerable growth potential.
End User Industry:
Customer types across end-user industries exhibit distinct procurement patterns and regulatory compliance needs for infrastructure monitoring solutions. Sector-specific requirements often dictate the adoption of specialized technologies.
- Telecommunications:Operators require comprehensive monitoring for network performance, service quality, and infrastructure health across their distributed assets. China's MIIT sets performance benchmarks for its national telecommunications networks, compelling advanced monitoring.
- Energy Production:This industry deploys monitoring for power plants, renewable energy installations, and transmission infrastructure to ensure operational efficiency, safety, and regulatory compliance. Siemens AG leverages its industrial portfolio for embedded monitoring in large-scale energy projects.
- Transportation Services:Monitoring solutions are critical for managing fleets, logistics, and physical infrastructure like roads, bridges, and railways. Trimble Inc. provides solutions for civil and structural health monitoring in this sector.
- Public Sector:Government entities utilize monitoring for critical public infrastructure, including water treatment facilities, public safety networks, and municipal buildings, often driven by resilience mandates.
- Financial Institutions:These organizations require robust monitoring of IT infrastructure, data centers, and network security to ensure transaction integrity and compliance with stringent data protection regulations.
Telecommunications remains a dominant end-user, but the Public Sector is increasingly adopting advanced monitoring capabilities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
In the United States, FERC enforces grid reliability standards, directly influencing demand for infrastructure monitoring solutions. This regulatory impetus extends across key global economies, driving investment in advanced monitoring technologies. Nations modernize critical systems, responding to both operational efficiency needs and resilience mandates.
United States
Demand for infrastructure monitoring in the United States stems from critical infrastructure resilience needs and energy grid stability. FERC grid reliability standards and the US Inflation Reduction Act (IRA) compel significant upgrades to energy and transportation systems. Technology hubs like Silicon Valley and the Texas energy corridor drive innovation in monitoring solutions for diverse assets.
Germany
Germany actively modernizes public and private infrastructure, including energy grids and transportation networks. The EU's Corporate Sustainability Reporting Directive (CSRD) and the EU Green Deal encourage sustainable infrastructure development with integrated monitoring. Industrial centers like the Ruhr area and Bavaria are implementing advanced monitoring for manufacturing and energy assets.
Japan
Japan addresses aging infrastructure challenges through advanced monitoring solutions for civil and public works. METI industrial policies support the integration of IoT and AI in infrastructure management. The Tokyo metropolitan area and the Kansai region are focal points for smart city deployments and resilient infrastructure projects.
China
China's extensive telecommunications network expansion and smart grid development drive substantial infrastructure monitoring demand. MIIT sets performance benchmarks for national telecommunications, while dual carbon goals push energy efficiency monitoring. The Yangtze River Delta and Pearl River Delta regions lead in deploying integrated monitoring for urban and industrial infrastructure.
India
India’s rapid urbanization and digital infrastructure growth create significant demand for monitoring solutions across new projects. The PLI scheme encourages domestic manufacturing of telecom equipment, requiring performance oversight, and the CEA enforces power sector reliability. Major tech hubs like Bengaluru and financial centers such as Mumbai are integrating advanced monitoring into their smart city initiatives.
Infrastructure Monitoring Market Key Industry Players
Diversified industrial conglomerates and specialized technology providers split the market for infrastructure monitoring solutions, each leveraging distinct core competencies. The market exhibits a tiered structure, with established players offering broad portfolios encompassing IT and OT monitoring, while niche firms focus on specific applications like civil structural health. Strategic partnerships are common for technology integration, alongside portfolio diversification to address converging IT/OT requirements and expanding geographic footprints.
Specialists in critical infrastructure management include Siemens AG, a German-based conglomerate that anchors solutions within large-scale energy and transportation projects, representing a broad industrial portfolio approach. Schneider Electric SE, a French-headquartered corporation, exemplifies expertise in data center infrastructure management, offering integrated power and cooling monitoring capabilities. Trimble Inc., a US-based technology company, occupies a strong position in the geospatial segment, providing solutions for civil and structural health monitoring across diverse physical assets.
| Leading Market Players |
|---|
| Honeywell International Inc. |
| Siemens AG |
| Schneider Electric SE |
| Trimble Inc. |
| National Instruments Corporation |
| Campbell Scientific, Inc. |
| Acellent Technologies, Inc. |
| Emerson Electric |
| Rockwell Automation |
| Others |
Cost & Logistics Intelligence
Under-utilized monitoring infrastructure capacity in some regions drives both supplier behavior and pricing posture. Pricing strategies are evolving as cloud-based solutions challenge traditional on-premises models, influencing how providers structure their offerings.
Pricing Analysis
Geographic price spreads reflect varying regulatory compliance costs and local infrastructure investment levels. Pricing primarily follows a subscription-based model for cloud services and a project-based approach for large-scale on-premises deployments. Price differentiation stems from the level of customization required for OT integration and the depth of AI-driven analytics provided. Pricing pressure stems from increasing competition among platform providers and the commoditization of basic network monitoring. The public sector often exhibits higher price sensitivity due to budget constraints, while financial institutions prioritize advanced security monitoring regardless of cost.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities support the deployment of complex monitoring systems. Geographic supply concentration for specialized sensors and hardware centers on China and Germany, while advanced software platforms often originate from the USA. Raw material dependencies include IoT sensors, high-performance computing components, and specialized software licenses. Single-source vulnerability for niche OT components represents a structural risk within the supply chain. Distribution runs through direct sales channels for major infrastructure projects and cloud marketplaces for scalable software-as-a-service offerings.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The market requires a strong substitution defense. Incumbents must navigate the threat posed by in-house IT teams developing bespoke monitoring scripts.
For Market Incumbents: Harden core offerings by integrating AI-driven predictive analytics and automated remediation capabilities. Consolidate market share through strategic acquisitions of niche technology providers specializing in OT/IT convergence. This addresses the threat from specialized cloud-native solutions that offer superior agility. Leverage vertical integration into data analytics platforms to own the full monitoring stack.
For New Entrants and Emerging Players: Underpenetrated regional critical infrastructure in emerging economies represents the most penetrable entry point. Target mid-sized enterprises with a Monitoring-as-a-Service (MaaS) offering that simplifies deployment and management. Focus on specific regulatory compliance niches like environmental monitoring under the EU Green Deal. Offer flexible, pay-as-you-go models to reduce upfront capital expenditure for clients.
For Investors and Strategic Acquirers: Capital is best deployed toward platform providers with strong recurring revenue models and deep AI integration capabilities. Long-term viability depends on acquiring companies offering unified IT/OT visibility across diverse infrastructure types. The signal to watch is successful deployments in multi-cloud environments that demonstrate interoperability. Prioritize targets with established regulatory compliance frameworks.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Consolidates diverse monitoring data for comprehensive infrastructure health views. |
| AI Analytics Development | Enables proactive problem identification and automated remediation in critical systems. |
| Cybersecurity Hardening | Protects remote monitoring systems from advanced persistent threats and data breaches. |
| MaaS Expansion | Lowers adoption barriers for smaller operators and expands recurring revenue streams. |
| Digital Twin Partnership | Enhances predictive maintenance capabilities and lifecycle management for complex assets. |
Research Approach
Findings reconcile primary fieldwork against secondary review of government reports, industry association publications, and technology vendor whitepapers. Primary interviews included infrastructure operators, IT security managers, regulatory compliance officers, and system integrators. Bottom-up and top-down triangulation ensures data consistency across all market segments.
Forecast inputs consider technology adoption rates, infrastructure investment cycles, regulatory enforcement trends, and economic development across the analysis window. Segmentation dimensions include deployment model, solution type, application, and end-user industry, alongside regional infrastructure maturity. CAGRs derive from historical growth analysis and projected market shifts, with infrastructure modernization projects in Germany and Japan serving as key inputs.
Macroeconomic conditions sit as an overlay; deviation in global infrastructure spending or critical infrastructure cybersecurity incidents would shift the trajectory. Forecasts reflect assumptions regarding technological advancements and regulatory stability. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Automation Systems
Residential Electric Underfloor Heating Market
Building Automation Systems
Collapsible Gates Market
Building Automation Systems
Global Operating Equipment Room Market
Building Automation Systems
Smart Passenger Elevators Market
Building Automation Systems
Smart Building Solutions Market
Building Automation Systems
Europe HVAC Controls Market
Building Automation Systems
Global Building Information Modeling (BIM) Market
Building Automation Systems
Commercial Building Automation Systems Market
Building Automation Systems
Building Technologies Market
Building Automation Systems
Tunnel Automation Market
Building Automation Systems
Elevator Modernization Market
Building Automation Systems
Europe Building Automation Systems Market
Building Automation Systems
Building-To-Grid Technology Market
Building Automation Systems
China Revolving Doors Market
Building Automation Systems
Building Analytics Market
Building Automation Systems
Platform Lifts Market