
 South Korea Infrastructure Market | 2026-2036
South Korea Infrastructure Market Size, Share, and Industry Trends Forecast 2026-2036
South Korea Infrastructure Market Analytics
South Korea's Green New Deal is consolidating infrastructure procurement around net-zero construction standards. Samsung C&T leverages its integrated engineering capabilities to dominate large-scale energy and transit projects. Hyundai E&C anchors the residential and commercial building segment through manufacturing scale and domestic brand strength. GS E&C specializes in sustainable construction methods, differentiating its project portfolio amid tightening environmental compliance.
South Korea infrastructure encompasses the physical systems and facilities enabling economic activity, including transportation networks, water treatment plants, energy generation and distribution assets, and digital telecommunications backbones built to seismic-resistant specifications and smart-grid interoperability standards. The primary purpose is to sustain industrial competitiveness, urban connectivity, and public welfare across a densely populated, export-dependent economy. Transportation and energy project types command the largest share of current investment flows, reflecting decades of state-led development prioritization. Modular and sustainable construction methods are gaining share fastest as labor costs rise and MFDS-adjacent building codes tighten material traceability requirements.
The Ministry of Environment enforces wastewater and emissions standards that shape material selection and project approval timelines for water supply and energy infrastructure. METI-aligned industrial policy directs R&D subsidies toward domestic steel and composite material innovation, reinforcing local supply chain control over critical inputs. KOSHA workplace safety mandates influence labor deployment models across traditional and precast construction sites. Stakeholders must monitor how evolving carbon accounting rules will reshape contractor qualification criteria and long-dated project returns.
Market Dynamics
The Green New Deal policy framework is redirecting public procurement toward net-zero construction standards while compressing project approval timelines for contractors lacking carbon accounting capabilities.
Growth Catalysts
- Seoul Smart City Initiative:Municipal transit authorities in the capital region are expanding integrated mobility corridors, creating sustained demand for digital telecommunications backbone upgrades and intelligent traffic management systems.
- Green New Deal Procurement Mandates:Central government infrastructure tenders now require lifecycle carbon disclosure, accelerating contractor investment in low-carbon concrete and modular prefabrication methods.
- Busan Port Expansion:Maritime logistics modernization is driving demand for seismic-resistant container handling facilities and hydrogen fueling infrastructure for vessel operations.
Market Restraints
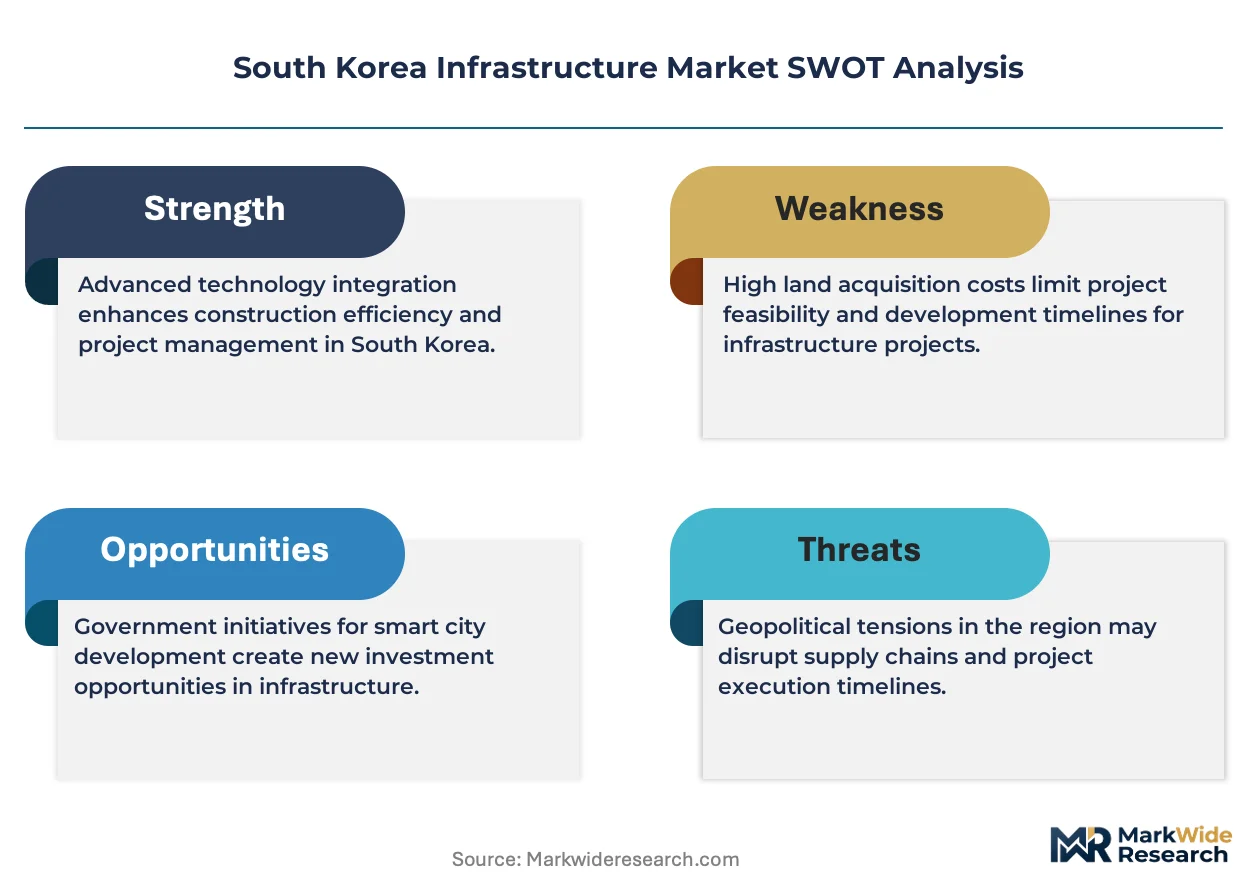
- Domestic Steel Supply Concentration:Heavy reliance on POSCO and Hyundai Steel for structural-grade materials creates input cost volatility when global iron ore prices fluctuate.
- KOSHA Compliance Burden:Workplace safety mandates extend project timelines by 8-15% as contractors deploy additional site supervisors and automated monitoring equipment.
- Labor Pool Constraints:Aging construction workforce and restrictive foreign worker visa quotas limit project scaling capacity during peak demand periods.
Strategic Opportunities
- Offshore Wind Installation:The Ministry of Trade, Industry and Energy's renewable energy targets create white space for specialized marine construction contractors in the West Sea region.
- Digital Twin Integration:Convergence of BIM platforms with IoT sensor networks enables predictive maintenance contracts for transportation and water treatment assets.
- Gyeonggi Province Logistics Hubs:E-commerce fulfillment center construction is concentrating demand for automated material handling systems and cold-chain infrastructure.
Industry Challenges
- MFDS-Adjacent Material Traceability:Building code amendments require batch-level documentation for structural composites, extending procurement cycles and certification timelines.
- Legacy System Integration:Smart grid interoperability standards force utilities to bridge analog substation equipment with digital control architectures, complicating brownfield project execution.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Korea Infrastructure Market |
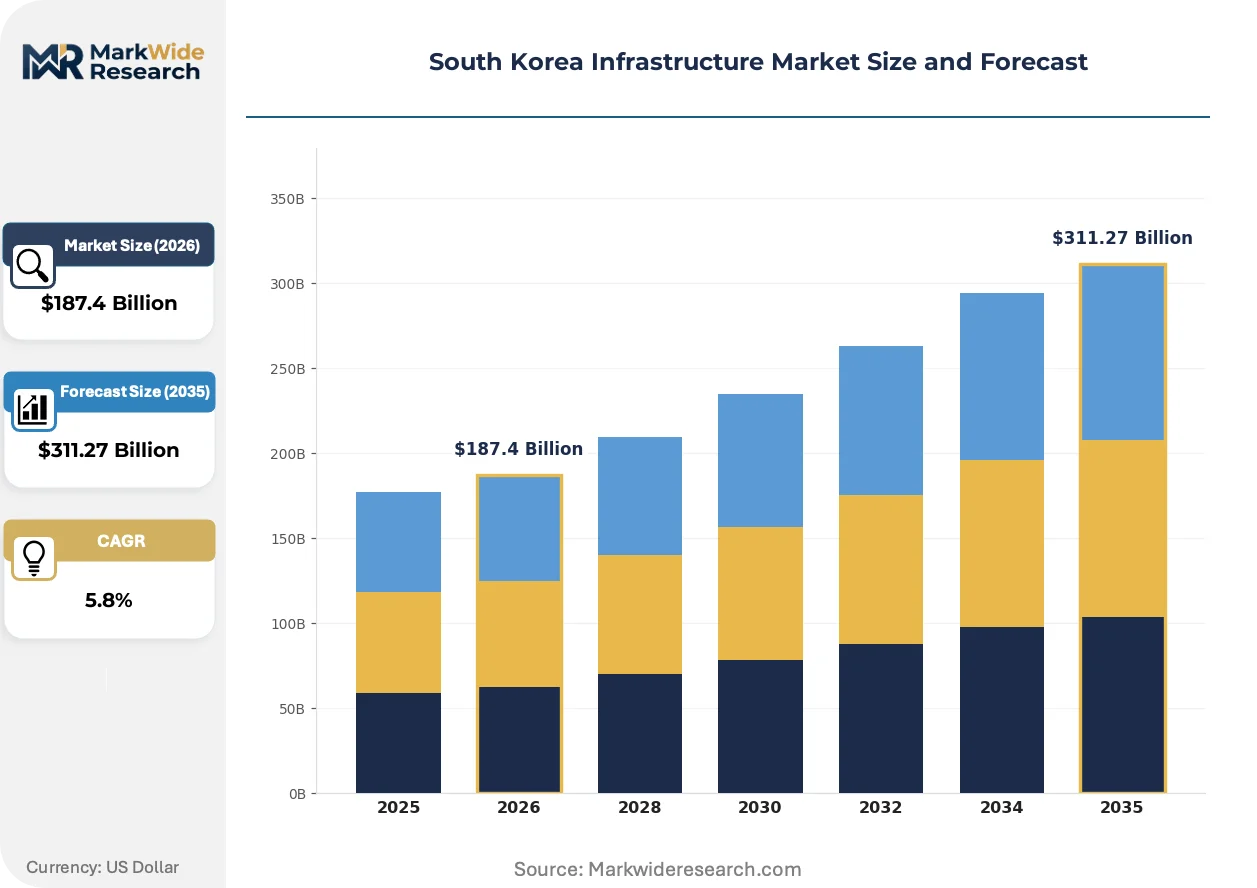
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $311.27 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Project Type: Transportation, Water Supply, Energy, Telecommunications End User: Government, Private Sector, Utilities, Contractors Construction Method: Traditional, Modular, Precast, Sustainable Material Type: Steel, Concrete, Asphalt, Composite |
| Companies Covered | Samsung C&T, Hyundai E&C, GS E&C, DL E&C, Daewoo E&C, POSCO E&C, Lotte E&C, HDC, Hoban Construction, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Korea Infrastructure Market Evolving Landscape
Modular construction methods and digital twin technologies are compressing project delivery timelines while MFDS-aligned building codes tighten material provenance requirements across residential and commercial segments.
Prefabricated structural components are modularizing high-rise construction workflows. Seoul municipal housing authorities now specify volumetric modules for public rental projects, compressing on-site assembly from months to weeks. This shift is modularizing contractor business models toward manufacturing-style production with captive supply chains.
The Green New Deal's carbon accounting rules now require embodied emissions disclosure for steel and concrete inputs. Project developers must submit lifecycle assessments to the Ministry of Environment before groundbreaking, extending pre-construction phases by 20-30%. Heavy civil contractors are responding by securing exclusive sourcing agreements with domestic low-carbon steel producers.
Municipal buyers are consolidating vendor relationships around integrated design-build-operate contracts. Seoul Metro and Busan Transit Corporation now bundle rolling stock procurement with 15-year maintenance agreements, displacing traditional segmented tendering. This concentration is most visible in urban rail extensions where single-source accountability reduces interface risk.
South Korea Infrastructure Market Segmentation
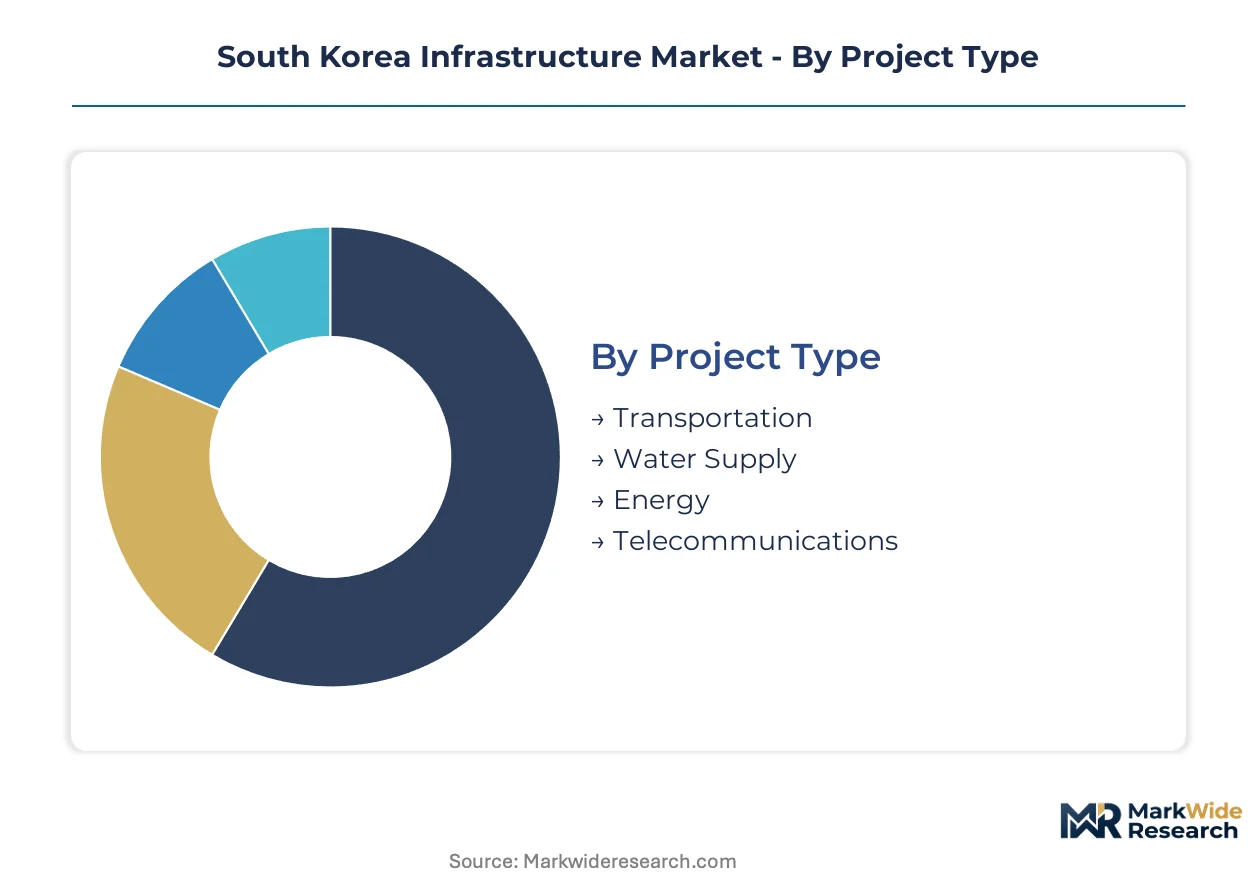
South Korea's infrastructure market segments reflect competing pressures from Green New Deal mandates, seismic engineering standards, and smart-city integration requirements. Each segmentation dimension captures distinct procurement patterns and contractor specialization strategies.
Project Type:
Standalone megaprojects dominate capital allocation, while embedded system upgrades absorb recurring operational budgets across municipal networks.
- Transportation:Highway expansions, urban rail corridors, and intelligent traffic management systems absorb the largest share of public procurement. Seoul Metro extensions and Busan port modernization concentrate demand for seismic-resistant viaducts and digital signaling infrastructure under the Ministry of Land, Infrastructure and Transport oversight.
- Energy:Renewable generation assets and grid modernization command priority funding under Green New Deal targets. Offshore wind installations in the West Sea and hydrogen fueling networks drive specialized marine and industrial construction demand.
- Water Supply:Wastewater treatment plants and smart metering infrastructure expand under Ministry of Environment compliance timelines. Desalination and reuse facilities gain traction in water-stressed coastal industrial zones.
- Telecommunications:5G backbone densification and data center construction support digital economy priorities. Fiber-optic trunk lines and edge computing facilities integrate with municipal smart-city platforms in Seoul and Busan.
Transportation leads volumes today; energy is gaining share fastest.
End User:
Public procurement concentration shapes contractor qualification requirements, while private demand introduces performance-based contracting models.
- Government:Central and municipal agencies control infrastructure tendering through the Public Procurement Service. Green New Deal mandates now require lifecycle carbon disclosure for all major civil works.
- Utilities:Korea Electric Power Corporation and Korea Water Resources Corporation drive standardization in grid and water asset specifications. These state-owned entities bundle design-build-operate contracts to reduce interface risk.
- Private Sector:Industrial conglomerates and logistics operators fund captive port, rail, and energy facilities. E-commerce fulfillment networks in Gyeonggi Province generate cold-chain and automated handling construction demand.
- Contractors:Large construction groups self-develop speculative commercial and residential projects. Integrated engineering capabilities enable Samsung C&T and Hyundai E&C to capture turnkey opportunities.
Government tenders dominate current award values; private sector projects are expanding most quickly.
Construction Method:
Cost tier stratification separates labor-intensive traditional approaches from capital-intensive industrialized alternatives with shorter on-site durations.
- Modular:Volumetric prefabrication compresses high-rise assembly timelines from months to weeks. Seoul municipal housing authorities now specify modular units for public rental projects, forcing contractor business models toward manufacturing-style production.
- Sustainable:Low-carbon concrete mixes and renewable material sourcing satisfy Green New Deal procurement mandates. Lifecycle assessment submission to the Ministry of Environment extends pre-construction phases but secures preferential tender scoring.
- Precast:Standardized structural components reduce on-site labor requirements and improve quality control. Bridge and tunnel projects adopt precast segments to minimize traffic disruption in dense urban corridors.
- Traditional:Cast-in-place concrete and steel erection persist in bespoke architectural projects and remote sites lacking modular supply chain access. Aging workforce constraints limit scalability during peak demand periods.
Traditional methods retain the largest project count; modular approaches are climbing the fastest.
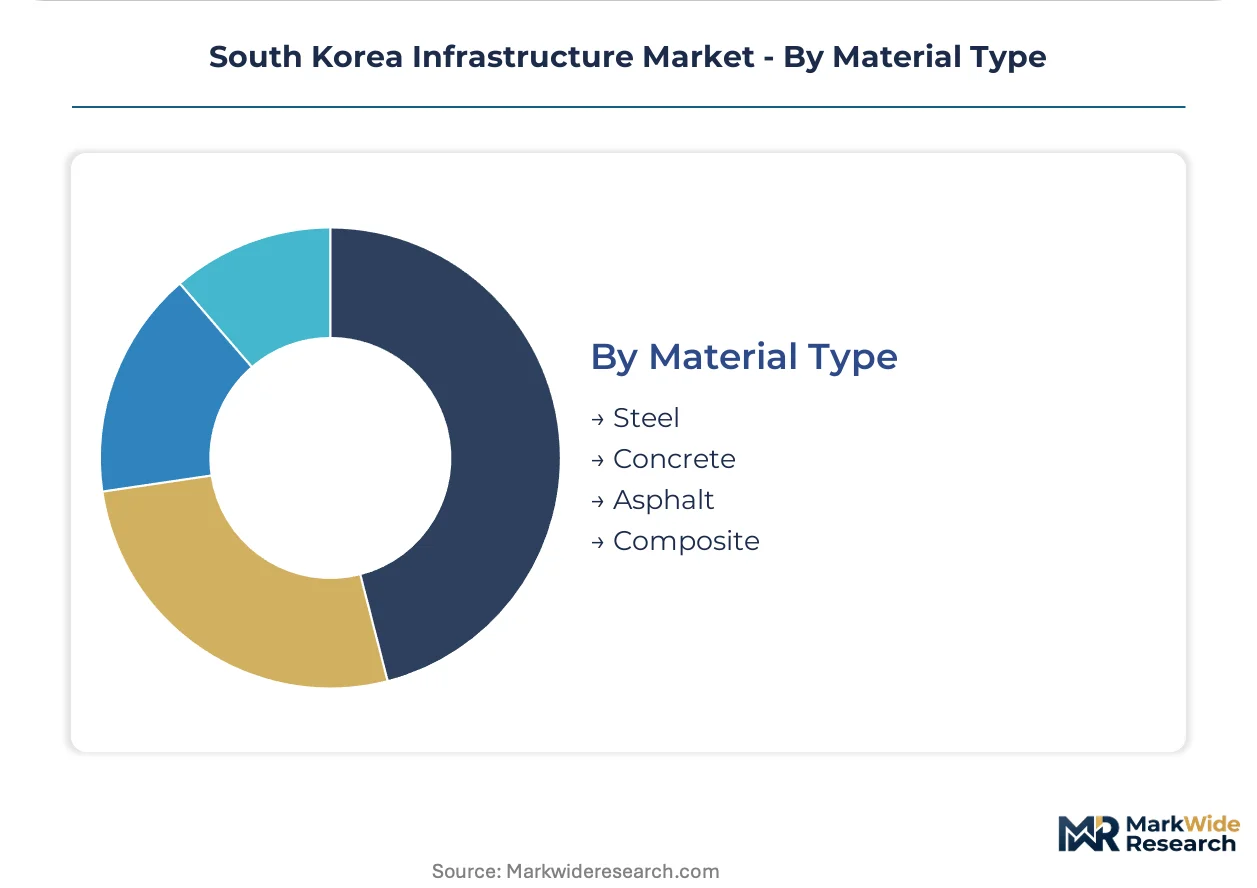
Material Type:
Supply concentration around POSCO and Hyundai Steel creates input cost volatility, while composite innovation responds to MFDS-adjacent traceability requirements.
- Steel:Structural grades from domestic mills dominate heavy civil and high-rise construction. Contractors secure exclusive low-carbon steel sourcing agreements to satisfy embodied emissions disclosure rules.
- Concrete:Ready-mix and precast concrete absorb the largest material volume across transportation and building projects. Green New Deal carbon accounting accelerates adoption of supplementary cementitious materials and carbon capture curing.
- Composite:Fiber-reinforced polymers and advanced composites penetrate bridge decks and seismic retrofit applications. Batch-level documentation requirements under amended building codes extend procurement cycles.
- Asphalt:Pavement materials concentrate in highway maintenance and expansion programs. Warm-mix technologies reduce energy consumption and emissions during production and placement.
Concrete and steel together dominate material tonnage; composites show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
South Korea's infrastructure industry traces its modern lineage to the 1960s state-led heavy industrialization drives that transformed the war-torn economy into an export powerhouse through concentrated capital allocation in transportation and energy corridors.
Seoul Capital Area
The metropolitan region generates the largest share of smart city investment demand through Seoul Metro extensions and intelligent traffic management deployments. Ministry of Land, Infrastructure and Transport oversight shapes procurement standards for seismic-resistant viaducts and digital signaling infrastructure. Bundang and Songdo districts concentrate experimental 5G backbone densification and edge computing facility construction.
Busan-Ulsan
Maritime logistics modernization drives specialized demand for hydrogen fueling infrastructure and container handling facility upgrades. Green New Deal procurement mandates require lifecycle carbon disclosure for all port-related civil works. The Busan Newport expansion anchors West Sea offshore wind installation supply chain development.
Daegu-Gyeongbuk
Industrial corridor revitalization focuses on renewable energy component manufacturing and supporting logistics infrastructure. Korea Electric Power Corporation standardization requirements influence grid asset specifications across the region. Pohang steelworks proximity enables low-carbon steel sourcing agreements for regional contractors.
Daejeon-Sejong
Administrative capital relocation has concentrated government facility construction and public research campus development. Public Procurement Service tendering protocols require embodied emissions documentation for structural materials. Sejong City smart grid pilot zones test brownfield integration of analog substation equipment with digital control architectures.
Gwangju-Honam
Water-stressed coastal industrial zones drive desalination and wastewater reuse facility construction under Ministry of Environment compliance timelines. MFDS-adjacent building code amendments extend procurement cycles for structural composite certification. The Saemangeum reclamation area hosts experimental modular construction deployment for public rental housing.
South Korea Infrastructure Market Competitive Landscape
Premium-margin players sit above commodity-margin players across integrated engineering capability and carbon accounting sophistication. The market structure concentrates around three domestic conglomerate-affiliated contractors controlling large-scale energy and transit awards, with mid-tier specialists competing for modular and sustainable construction niches. Strategic archetypes include integrated engineering giants, manufacturing-scale residential specialists, and sustainable method innovators. Dominant competitive moves involve exclusive low-carbon material sourcing agreements and design-build-operate contract bundling to reduce interface risk.
Within the integrated engineering tier, Samsung C&T and Hyundai E&C occupy positions that exemplify turnkey project capture through conglomerate-affiliated supply chain control. GS E&C represents the sustainable construction archetype, differentiating around low-carbon method specialization amid tightening environmental compliance requirements.
| Leading Market Players |
|---|
| Samsung C&T |
| Hyundai E&C |
| GS E&C |
| DL E&C |
| Daewoo E&C |
| POSCO E&C |
| Lotte E&C |
| HDC |
| Hoban Construction |
| Others |
Value Network & Pricing Analysis
Public Procurement Service tenders concentrate demand among three domestic conglomerate-affiliated contractors, locking in project-based pricing with lifecycle cost disclosure premiums. Green New Deal carbon accounting mandates now embed material provenance costs into bid structures, compressing margins for contractors lacking exclusive low-carbon steel sourcing agreements.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates integrated design-build-operate bundles from traditional segmented tenders. Price differentiation rests on carbon certification tier and after-sales maintenance bundling. Cost compression in standard-tier civil works is intensifying because domestic steel supply concentration amplifies input volatility. Municipal transit authorities exhibit highest price sensitivity, while industrial conglomerates captive-funding port and energy facilities accept premium engineering premiums.
Supply Chain Analysis
Direct-to-contractor channels handle megaproject demand from Korea Electric Power Corporation and Korea Water Resources Corporation. Geographic supply concentrates in South Korea for structural steel from POSCO and Hyundai Steel, with supplementary cementitious materials drawn from China and Japan. Raw material dependencies center on iron ore, low-carbon cement blends, and fiber-reinforced polymer composites. Single-source vulnerability around domestic steel mills creates procurement risk during global commodity spikes. Distribution runs through Ministry of Land, Infrastructure and Transport-certified contractor networks with batch-level MFDS traceability documentation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
South Korea's infrastructure market compounds regulatory value through Green New Deal procurement mandates that now require embodied emissions disclosure before groundbreaking. The Ministry of Environment's tightening carbon accounting rules create sustained demand for certified low-carbon construction methods.
For Market Incumbents: Acquire exclusive low-carbon material sourcing agreements with POSCO and domestic composite producers to defend against modular construction specialists eroding traditional cast-in-place market share. Secure design-build-operate contract bundling capabilities to reduce interface risk in Seoul Metro and Busan Transit Corporation tenders. Invest in BIM-to-digital-twin integration platforms to capture predictive maintenance revenue streams. For New Entrants and Emerging Players: Launch via specialized marine construction capabilities targeting West Sea offshore wind installation demand under Ministry of Trade, Industry and Energy renewable targets. Penetrate Gyeonggi Province logistics hub construction for automated material handling and cold-chain infrastructure serving e-commerce fulfillment networks. Differentiate through MFDS-aligned batch-level documentation systems that accelerate composite material certification timelines. For Investors and Strategic Acquirers: Domestic industrial conglomerates are the most active acquirers in this space, consolidating contractor capabilities to secure integrated engineering margins. Target sustainable construction method innovators with established Ministry of Environment lifecycle assessment submission workflows. Watch for inflection signals in Public Procurement Service tender scoring weights shifting toward carbon-negative material specifications.| Strategic Initiative | Industry Significance |
|---|---|
| Exclusive Low-Carbon Material Sourcing Agreement | Secures preferential tender scoring under Green New Deal procurement mandates from the Ministry of Environment. |
| Design-Build-Operate Contract Bundling | Reduces interface risk for Korea Electric Power Corporation and municipal transit authority megaprojects. |
| Digital Twin Platform Integration | Enables predictive maintenance revenue from Seoul Metro and Busan Transit Corporation rolling stock assets. |
| Modular Manufacturing Capability Buildout | Compresses on-site assembly timelines for Seoul municipal housing authority public rental specifications. |
| MFDS-Aligned Traceability System Investment | Accelerates composite material procurement cycles under amended building code documentation requirements. |
Research Methodology
Direct dialogue with EPC contractors, procurement officers at Korea Electric Power Corporation, Ministry of Land, Infrastructure and Transport planning officials, and composite material suppliers grounded qualitative findings. Secondary validation drew from Public Procurement Service tender databases, Ministry of Environment emissions disclosure filings, KOSHA workplace safety compliance records, and Korea Water Resources Corporation capital expenditure disclosures. Bottom-up project pipeline assessment and top-down macroeconomic triangulation shaped market sizing.
Bottom-up segment modeling tracked transportation, energy, water supply, and telecommunications project types across government, utility, and private sector end users. Construction method segmentation captured modular, sustainable, precast, and traditional approaches with material type splits across steel, concrete, composite, and asphalt. CAGRs derived from weighted project award trajectories and Green New Deal procurement velocity assumptions. Forecast inputs incorporated seismic engineering standard upgrade cycles and smart-grid interoperability investment schedules.
Forecast precision tightens around the base case; tail outcomes carry wider variance under sudden iron ore price spikes or foreign worker visa quota restrictions. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Infrastructure Construction
Transmission and Distribution Infrastructure Market
Infrastructure Construction
South America Repair and Rehabilitation Market
Infrastructure Construction
India Transportation Infrastructure Construction Market
Infrastructure Construction
Brazil Infrastructure Sector Market
Infrastructure Construction
New Zealand Infrastructure Market
Infrastructure Construction
Oman Transportation Infrastructure Construction Market
Infrastructure Construction
Latin America Data Center Construction Market
Infrastructure Construction
Switzerland Transportation Infrastructure Construction Market
Infrastructure Construction
Pipeline Network Market
Infrastructure Construction
Vietnam Data Center Construction Market
Infrastructure Construction
Italy Infrastructure Investment Market
Infrastructure Construction
Japan Transportation Infrastructure Construction Market
Infrastructure Construction
Middle East Pipeline Construction Market
Infrastructure Construction
Russia Transportation Infrastructure Construction Market
Infrastructure Construction
Mexico Data Center Construction Market
Infrastructure Construction
Global Port Infrastructure Market