
 China HVAC Field Device Market | 2026-2036
China HVAC Field Device Market Size, Share, and Industry Trends Forecast 2026-2036
China HVAC Field Device Market Insights
Commercial building operators is collapsing the historical dominance of industrial facility buyers as the primary revenue archetype for HVAC field devices. Siemens AG leverages its automation portfolio to anchor large-scale commercial retrofit contracts across tier-one Chinese cities. Honeywell International Inc. competes through localized controller production and deep channel partnerships with state-owned construction enterprises. Johnson Controls International PLC sustains its position via building management system integration that bundles sensors, actuators, and software into single-source contracts.
HVAC field devices encompass thermostats, sensors, actuators, and controllers that regulate temperature, airflow, and energy consumption through electromechanical or digital signal processing, typically operating across 24V AC control circuits or BACnet and Modbus communication protocols. These instruments serve the core industrial purpose of maintaining environmental setpoints while minimizing energy expenditure in climate-controlled spaces. Smart technology is displacing analog architectures as the fastest-expanding dimension, driven by IoT-enabled predictive maintenance and cloud-based energy analytics that command premium pricing. Wired installations still dominate absolute volume in legacy building stock, though wireless deployment accelerates in new commercial construction where cabling costs prove prohibitive. Actuators capture concentrated margin pools due to precision motor and valve integration requirements that limit supplier proliferation.
China's MIIT enforces GB standards for building automation interoperability, while MEE implements dual carbon goals that mandate energy efficiency disclosures for commercial properties exceeding specified floor areas. SAMR certification requirements for measurement instruments create compliance barriers that favor established suppliers with in-country testing capabilities. Stakeholders must monitor how provincial interpretations of national efficiency codes vary, as Shanghai and Beijing frequently pilot stricter local amendments before broader rollout.
Market Dynamics
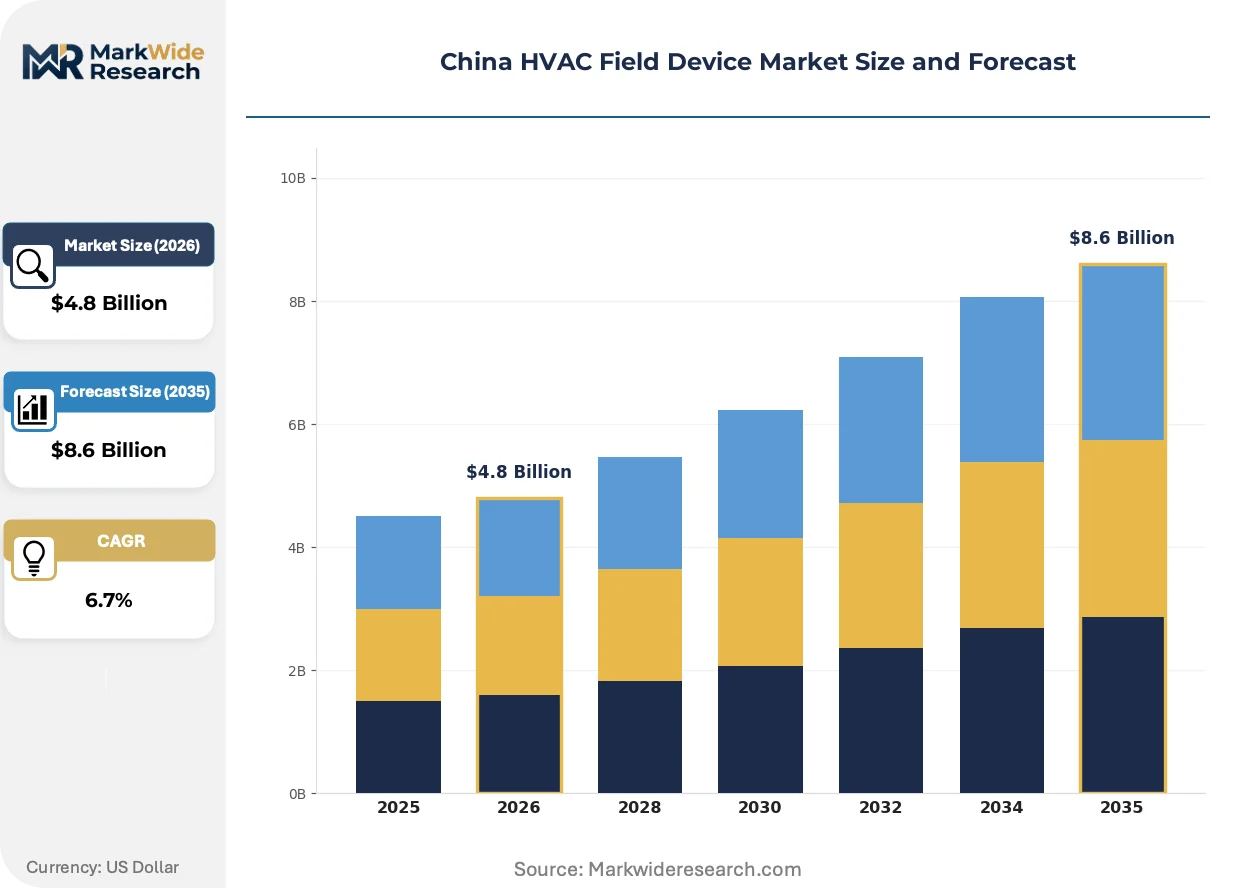
China's dual carbon goals are compressing payback periods for building automation investments, forcing facility operators to replace analog HVAC controls with networked sensor-actuator systems ahead of physical equipment end-of-life. This regulatory pressure is restructuring procurement priorities across commercial real estate portfolios.
Growth Catalysts
- MIIT GB Standards Mandate:Interoperability requirements for building automation systems are accelerating controller replacement cycles in commercial properties exceeding specified floor areas. Facility managers must upgrade to certified devices to maintain operating licenses.
- Yangtze River Delta Cluster Concentration:Shanghai and Jiangsu province anchor manufacturing ecosystems and pilot smart city deployments, creating dense reference sites that reduce adoption risk for late-moving building operators.
- Wireless Sensor Proliferation:IoT-enabled predictive maintenance capabilities are commanding premium pricing in new commercial construction where retrofit cabling costs prove prohibitive.
Market Restraints
- SAMR Certification Barriers:Measurement instrument testing requirements favor established suppliers with in-country laboratories, limiting new entrant proliferation and concentrating margin capture among incumbent players.
- Legacy Building Stock Inertia:Wired analog installations dominate absolute volume in existing structures, compressing near-term addressable market for wireless architectures despite their technical superiority.
- Precision Motor Supply Concentration:Actuator manufacturing depends on specialized valve integration capabilities that concentrate among a narrow supplier base, creating input bottlenecks during demand surges.
Strategic Opportunities
- Provincial Efficiency Code Pilots:Shanghai and Beijing frequently implement stricter local amendments before national rollout, creating first-mover advantage for suppliers with regulatory intelligence capabilities in these municipalities.
- Cloud-Based Energy Analytics Convergence:Integration of BACnet protocols with edge computing platforms is enabling subscription revenue models that decouple hardware margins from software value capture.
- State-Owned Construction Channel Partnerships:Deep distribution relationships with central government-backed developers provide preferential specification access in large-scale commercial retrofit programs.
Industry Challenges
- Integration Complexity with Modbus Legacy:Facility engineers face skill gaps bridging 24V AC control circuits with digital communication protocols, extending commissioning timelines and eroding project margins.
- Provincial Interpretation Variance:National MEE efficiency disclosure mandates generate inconsistent local enforcement, complicating compliance architecture for multi-province building portfolios.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China HVAC Field Device Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Thermostats, Sensors, Actuators, Controllers Technology: Wired, Wireless, Smart, Analog End User: Commercial Buildings, Residential Properties, Industrial Facilities, Educational Institutions Application: Heating, Ventilation, Air Conditioning, Energy Management |
| Companies Covered | Siemens AG, Honeywell International Inc., Johnson Controls International PLC, Rotork Plc, Dwyer Instruments Inc, Belimo Holding AG, Robert Bosch GmbH, Danfoss A/S, Advanced Flow Control Group Co Ltd (AFC), Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China HVAC Field Device Market Trends and Innovations
Digital signal processing architectures are actively restructuring competitive advantage in China's HVAC field device market. Three convergent developments are compressing technology refresh cycles and redrawing supplier positioning.
Edge-enabled actuators with embedded motor control algorithms are supplanting electromechanical relay systems in precision airflow applications. High-end commercial developers in Shanghai and Shenzhen are specifying these devices for 90% of new Class A office construction. The shift is compressing hardware margins while expanding software and service attach rates for integrated building management providers.
MEE dual carbon disclosure mandates are forcing energy efficiency transparency for commercial properties above threshold floor areas. Building operators must install certified measurement instruments and report consumption data, creating compliance-driven replacement demand independent of equipment failure. The policy most affects retail and hospitality verticals in tier-one cities where enforcement capacity concentrates.
Facility managers are unbundling after-sales service contracts from initial hardware procurement, compressing supplier switching costs. State-owned construction enterprises and private commercial developers alike are separating maintenance obligations across multi-year frameworks rather than single-source bundled agreements. This pattern is most visible in Jiangsu province manufacturing clusters where reference site density enables competitive benchmarking.
China HVAC Field Device Market Segmentation
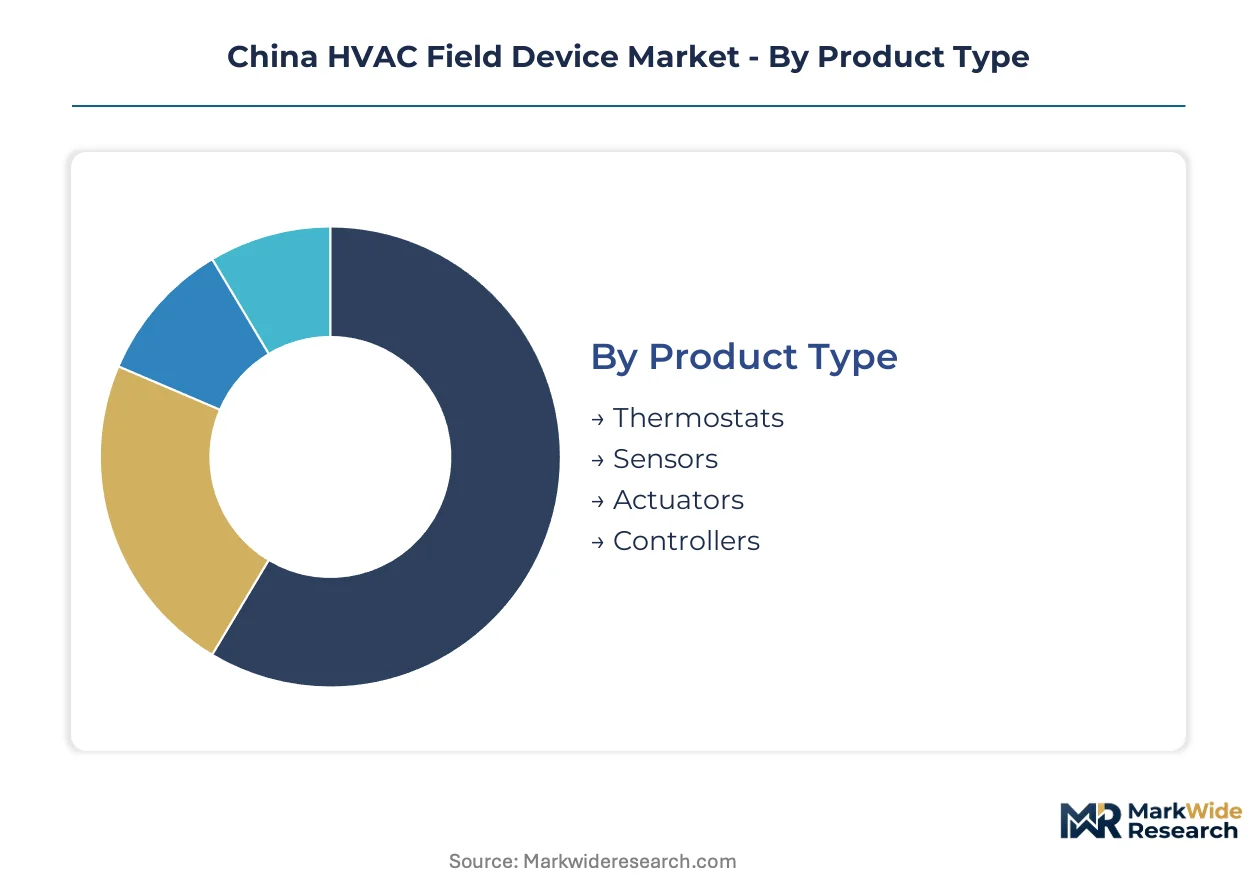
HVAC field device segmentation in China reflects divergent compliance pressures across product architectures, connectivity standards, and building typologies. Procurement patterns fragment sharply between legacy analog retrofits mandated by MIIT GB standards and greenfield smart deployments favored by Yangtze River Delta developers.
Product Type:
MIIT GB certification requirements create tiered barriers across device categories, concentrating margin capture among suppliers with in-country testing capabilities for measurement instruments and motor-integrated assemblies.
- Actuators:Precision motor and valve integration systems that modulate damper positions and fluid flow rates through electromechanical or digital control signals. Demand concentrates in Shanghai Class A office retrofits where MEE dual carbon disclosure mandates force replacement of pneumatic legacy systems ahead of equipment end-of-life.
- Sensors:Temperature, humidity, pressure, and air quality transducers operating across 24V AC circuits or BACnet/Modbus networks. Jiangsu province manufacturing clusters anchor procurement volume for wireless CO2 and occupancy sensors piloted in smart city deployments.
- Controllers:Programmable logic devices that aggregate sensor inputs and command actuator outputs to maintain environmental setpoints. Commercial building operators in Beijing specify these for centralized building management system integration.
- Thermostats:Wall-mounted temperature control interfaces spanning basic electromechanical dial units to touchscreen-enabled IoT endpoints. Residential property developers in tier-two cities favor cost-optimized wired variants.
Established volume favors controllers; emerging adoption favors actuators.
Technology:
Cost tier differentiation separates premium smart architectures from economy analog legacy, with wireless positioning as a mid-market bridge technology for retrofit-constrained budgets.
- Smart:IoT-enabled devices with embedded edge computing, predictive maintenance algorithms, and cloud analytics integration. High-end commercial developers in Shenzhen specify these for 90% of new construction, accepting premium pricing for energy optimization subscriptions.
- Wireless:Battery-powered or energy-harvesting sensors and actuators using Zigbee, LoRaWAN, or proprietary protocols to eliminate cabling infrastructure. Demand accelerates in hospitality verticals where SAMR-certified measurement instruments must deploy without disturbing occupied guest floors.
- Wired:Hardwired 24V AC control circuits and BACnet MS/TP installations dominating existing building stock. Industrial facilities in Hebei province retain these for electromagnetic interference immunity in heavy manufacturing environments.
- Analog:Electromechanical relay systems and pneumatic controls without digital communication capabilities. MEE efficiency disclosure mandates are forcing accelerated replacement in commercial properties exceeding threshold floor areas.
Legacy wired infrastructure dominates current installed base; smart architectures are climbing the fastest.
End User:
Customer type maturity separates compliance-driven replacement cycles from discretionary upgrade decisions, with state-backed procurement channels concentrating volume in specific verticals.
- Commercial Buildings:Class A offices, retail centers, and hospitality properties subject to MEE dual carbon energy disclosure mandates. Shanghai and Beijing enforcement capacity drives concentrated replacement demand for certified measurement instruments.
- Industrial Facilities:Manufacturing plants and process industries requiring robust environmental control for production quality. Analog architectures persist here due to 24V AC circuit reliability in high-electromagnetic environments.
- Educational Institutions:Universities and K-12 facilities with extended procurement cycles tied to government budget allocations. Jiangsu province pilots smart campus deployments with state-owned construction enterprise partnerships.
- Residential Properties:Multi-family housing and single-family homes with cost-sensitive procurement patterns. Tier-two and tier-three cities favor basic thermostats over integrated building automation.
Commercial buildings anchor revenue concentration; educational institutions are gaining share fastest.
Application:
Geography of enforcement shapes application-level demand, with tier-one city energy codes privileging integrated energy management over discrete heating or cooling functions.
- Energy Management:Integrated consumption monitoring, demand response, and optimization systems spanning multiple HVAC subsystems. Shanghai developers bundle these with smart city infrastructure investments to meet dual carbon disclosure requirements.
- Air Conditioning:Cooling-specific control systems for compressor staging, chilled water distribution, and terminal unit modulation. Southern provinces with extended cooling seasons specify precision actuators for variable refrigerant flow systems.
- Ventilation:Outdoor air delivery and exhaust control for indoor air quality compliance. Post-pandemic building codes in Beijing mandate upgraded sensor density for CO2 and particulate monitoring.
- Heating:Boiler control, radiant system modulation, and district heat interface management. Northern provinces retain substantial wired analog infrastructure in legacy district heating connections.
Discrete heating and cooling functions retain volume dominance; energy management integration shows steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing ecosystems for HVAC field devices concentrate in the Yangtze River Delta, where precision motor supply chains and MIIT-certified testing laboratories anchor production. Provincial efficiency codes in Shanghai and Jiangsu pilot stricter amendments ahead of national rollout, compressing adoption timelines for smart building automation.
Yangtze River Delta
Shanghai Class A office developers specify edge-enabled actuators for 90% of new construction, accepting premium pricing for energy optimization subscriptions. MIIT GB standards mandate interoperability certification for controllers exceeding specified floor areas. Jiangsu province manufacturing clusters anchor wireless sensor procurement volume for smart city pilot deployments.
Beijing-Tianjin-Hebei
MEE dual carbon disclosure mandates force replacement of pneumatic legacy systems in commercial properties above threshold floor areas. Beijing municipal amendments frequently pilot stricter energy codes before broader national implementation. State-owned construction enterprises in Tianjin bundle building management system integration into large-scale retrofit contracts.
Pearl River Delta
Shenzhen high-end commercial developers drive smart architecture specification at 90% penetration for new Class A offices. SAMR certification requirements for measurement instruments favor established suppliers with in-country testing capabilities. Guangdong province electronics manufacturing clusters supply precision motor components for actuator assembly.
Sichuan-Chongqing
Western China infrastructure investment accelerates procurement of wired BACnet controllers for electromagnetic interference immunity in heavy industrial environments. Provincial interpretations of MEE efficiency codes vary from coastal enforcement patterns. Chongqing manufacturing facilities retain analog architectures for district heating interface management in legacy building stock.
Shandong Peninsula
Northern province district heating connections sustain substantial wired analog infrastructure despite national smart building mandates. Local amendments to MIIT GB standards lag Shanghai and Beijing pilot timelines. Qingdao industrial facilities specify 24V AC control circuits for reliability in high-electromagnetic manufacturing environments.
China HVAC Field Device Market Competitive Landscape
Concentration sits with diversified industrial conglomerates and building automation specialists that command in-country certification capabilities and state-owned enterprise channel access. The supplier base tiers between premium-tier integrated building management providers, mid-market controller manufacturers with localized production, and precision actuator specialists with captive motor supply relationships. Market structure rewards backward integration into precision motor manufacturing and deep distribution partnerships with central government-backed developers. Strategic moves center on unbundling after-sales service contracts from hardware procurement and converging BACnet protocols with edge computing platforms for subscription revenue models.
Within the diversified industrial conglomerate tier, Siemens AG and Honeywell International Inc. exemplify archetypes that leverage automation portfolios and localized production respectively. Johnson Controls International PLC occupies a position representing building management system integration specialists that bundle sensors, actuators, and software into single-source contracts. Among precision actuator specialists, Belimo Holding AG and Rotork Plc represent suppliers with concentrated margin capture from valve integration capabilities. Danfoss A/S and Robert Bosch GmbH anchor the tier of component manufacturers with captive precision motor supply relationships. Chinese market presence includes Zhengzhou-based Advanced Flow Control Group Co Ltd alongside diversified instrumentation providers such as Dwyer Instruments Inc.
| Leading Market Players |
|---|
| Siemens AG |
| Honeywell International Inc. |
| Johnson Controls International PLC |
| Rotork Plc |
| Dwyer Instruments Inc |
| Belimo Holding AG |
| Robert Bosch GmbH |
| Danfoss A/S |
| Advanced Flow Control Group Co Ltd (AFC) |
| Others |
Pricing and Supply Chain Analysis
Project-based bundled contracts for building automation retrofits lock in multi-year supply commitments for precision motor assemblies while anchoring price visibility against MIIT GB certification cost volatility. Facility operators in Shanghai and Beijing negotiate these structures to secure actuator availability ahead of provincial efficiency code amendments.
Pricing Analysis
MIIT GB standards dictate the pricing tier structure across China's HVAC field device market. Three-tier pricing structure across premium, standard, and economy levels separates edge-enabled smart actuators with predictive maintenance subscriptions from basic wired controllers and legacy analog thermostats. Cost compression in the economy tier is intensifying because residential developers in tier-two cities prioritize procurement volume over performance specifications. State-owned construction enterprises demonstrate lowest price sensitivity due to bundled building management system integration requirements.
Supply Chain Analysis
Precision motor manufacturing for actuator valve integration represents the critical chokepoint constraining output scalability across the Yangtze River Delta. Production draws from Jiangsu province electronics clusters, Guangdong component foundries, and specialized Japanese bearing suppliers. Neodymium magnet supply from Chinese rare earth processors and copper winding stock from domestic smelters feed assembly lines. Single-source vulnerability concentrates in high-torque stepper motor controllers sourced from a narrow tier of certified suppliers. Distribution runs through state-owned construction enterprise procurement channels and authorized system integrator networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
China's HVAC field device market is crossing a platform-economics inflection where BACnet interoperability transforms hardware vendors into recurring-revenue software platforms. The convergence of edge computing with cloud-based energy analytics is redefining competitive moats around data integration rather than device manufacturing alone.
For Market Incumbents: Compound defensive positioning through backward integration into precision motor manufacturing and captive SAMR certification laboratory capacity. Siemens AG and Honeywell International Inc. anchor this strategy by securing exclusive supply agreements with Jiangsu province system integrators. Threat of wireless sensor commoditization from low-cost entrants demands accelerated software subscription attach rates.
For New Entrants and Emerging Players: SAMR certification fast-track partnerships with Shanghai testing laboratories unlock tier-one city commercial building access before national code rollouts. White-space concentrates in wireless CO2 sensors for hospitality retrofits where cabling costs exclude incumbent wired architectures. Jiangsu province educational institution pilots offer reference site density for competitive benchmarking against established suppliers.
For Investors and Strategic Acquirers: Capital is best deployed toward precision actuator specialists with captive valve integration capabilities and existing MIIT GB certification portfolios. Long-term viability hinges on software service revenue multiples decoupled from hardware margin compression. Signal to watch is provincial efficiency code amendment velocity in Beijing and Shanghai as leading indicators of national adoption timelines.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precision Motor Manufacturing | Captive supply of stepper motor assemblies insulates margin capture from Jiangsu province input bottlenecks during demand surges. |
| SAMR Certification Laboratory Investment | In-country testing capabilities for measurement instruments accelerate product launch timelines ahead of MEE dual carbon disclosure mandates. |
| Cloud-Based Energy Analytics Platform Launch | Subscription revenue models decouple hardware margins from software value capture through BACnet protocol convergence. |
| State-Owned Construction Enterprise Channel Partnership | Preferential specification access in large-scale commercial retrofit programs bundles sensors, actuators, and building management systems. |
| Wireless Sensor Product Line Expansion | Battery-powered Zigbee and LoRaWAN architectures address hospitality verticals where retrofit cabling costs prove prohibitive. |
Research Methodology
Initial hypotheses were tested against primary input from building automation system integrators, facility management directors at Class A commercial properties, procurement leads at state-owned construction enterprises, and MIIT certification laboratory technical staff, then refined against secondary validation from customs trade data, SAMR regulatory filings, Shanghai municipal building energy disclosure records, and SEC 10-K segment disclosures from listed building automation providers. Bottom-up installation volume estimates triangulated with top-down addressable building stock calculations.
Variance decomposition across product type, technology architecture, building typology, and geographic enforcement cluster shaped the analytical framework over the projection horizon. CAGRs were derived from segment-level demand elasticity modeling against regulatory mandate implementation curves. Forecast inputs incorporated provincial efficiency code amendment timelines and precision motor supply capacity constraints from Jiangsu manufacturing cluster surveys.
Underlying assumptions cover MIIT GB standard enforcement consistency and SAMR certification processing throughput, with deviation risk concentrated in provincial interpretation variance of MEE dual carbon disclosure thresholds. Practitioners should keep alternative scenarios live as Beijing and Shanghai pilot amendment timelines evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
HVAC Equipment
India Chillers Market
HVAC Equipment
US HVAC Services Market
HVAC Equipment
North America Bus HVAC Market
HVAC Equipment
Modular Refrigeration Unit Market
HVAC Equipment
North America, Europe, and Asia Pacific Air Compressor Market
HVAC Equipment
Global Portable Evaporative Air Cooler Market
HVAC Equipment
Tubular Heater Market
HVAC Equipment
Commercial RAC PD Compressor Market
HVAC Equipment
Heating and Cooling Market
HVAC Equipment
Global Air-To-Air Heat Pumps Market
HVAC Equipment
South America Compressor Market
HVAC Equipment
Linear Slot Diffuser Market
HVAC Equipment
Global Variable Refrigerant Flow (VRF) Market
HVAC Equipment
Industrial Heating Equipment Market
HVAC Equipment
Dedicated Outdoor Air System Market
HVAC Equipment
Utility and Industrial Boilers Market