
 Automated Infrastructure Management (AIM) Solutions Market | 2026-2036
Automated Infrastructure Management (AIM) Solutions Market Size, Share, and Industry Trends Forecast 2026-2036
Automated Infrastructure Management (AIM) Solutions Market Analysis
North American data center infrastructure producers is consolidating around intelligent cabling platforms that embed sensor networks directly into copper and fiber assemblies. Cisco Systems Inc. leverages its networking heritage to bundle AIM software with switch hardware, creating captive demand for its discovery protocols. CommScope Holding Company Inc. anchors the physical layer segment through deep manufacturing scale in structured cabling systems. Panduit Corporation specializes in industrial-grade patch cord identification technologies that sustain premium positioning in factory automation environments.
Automated Infrastructure Management Solutions encompass software platforms, integration tools, and sensor-enabled hardware that discover, document, and monitor physical IT infrastructure assets across enterprise networks. These systems typically employ real-time location tracking with patch cord-level granularity to eliminate manual spreadsheet dependency and reduce mean-time-to-repair in critical facilities. Cloud-based deployment configurations now capture the fastest expansion trajectory as multi-site enterprises prefer centralized visibility without on-premises server overhead. The telecommunications end-user segment leads absolute spend because 5G fiber densification demands precise documentation of millions of new strand terminations. AI and machine learning technology layers are deepening fastest within predictive maintenance modules that flag degradation before service interruption occurs.
FCC equipment authorization requirements shape hardware design for AIM sensor modules deployed in US telecommunications facilities, while EU GDPR and CSRD frameworks compel European operators to maintain auditable infrastructure records with personal data isolation. Germany's KBA and France's ANSM have issued no direct AIM mandates, though national building codes in both jurisdictions increasingly reference automated documentation for critical infrastructure certification. Stakeholders must weigh cloud dependency against sovereign data requirements as regulatory fragmentation intensifies across jurisdictions.
Market Dynamics
The CSRD mandate is forcing European facility managers to abandon manual documentation, creating immediate replacement demand for sensor-enabled AIM platforms that can generate auditable infrastructure records in real time.
Growth Catalysts
- EU Corporate Sustainability Reporting Directive:Granular infrastructure disclosure requirements now compel automated asset tracking systems for compliance verification. German industrial complexes face the densest cable management verification obligations.
- 5G fiber densification:Telecommunications operators must document millions of new strand terminations with patch-level precision, eliminating spreadsheet-based methods entirely.
- Cloud-based deployment preference:Multi-site enterprises are consolidating visibility through centralized SaaS configurations rather than maintaining fragmented on-premises servers.
Market Restraints
- Copper and optical sensor module costs:Embedded intelligence in structured cabling assemblies carries material premiums that compress margins for price-sensitive mid-market buyers.
- GDPR data isolation complexity:European operators must architect physical layer monitoring systems that segregate personal data flows, adding integration overhead to cross-border deployments.
- Legacy spreadsheet inertia:Smaller facility management teams maintain manual documentation habits despite compliance risks, delaying platform adoption timelines.
Strategic Opportunities
- France and Netherlands industrial corridors:Manufacturing automation investments in these jurisdictions lack mature AIM penetration compared to German benchmarks, creating first-mover expansion potential.
- Predictive maintenance module convergence:Machine learning layers atop physical layer data streams enable degradation flagging before service interruption, commanding premium positioning.
- Industrial-grade patch cord identification:Factory automation environments require hardened identification technologies that withstand temperature cycling and chemical exposure.
Industry Challenges
- Cross-protocol integration complexity:AIM platforms must harmonize discovery protocols from multiple networking hardware vendors without creating vendor lock-in.
- Physical layer technician scarcity:Enterprises struggle to source personnel capable of deploying sensor-enabled copper and fiber assemblies with calibration precision.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automated Infrastructure Management (AIM) Solutions Market |
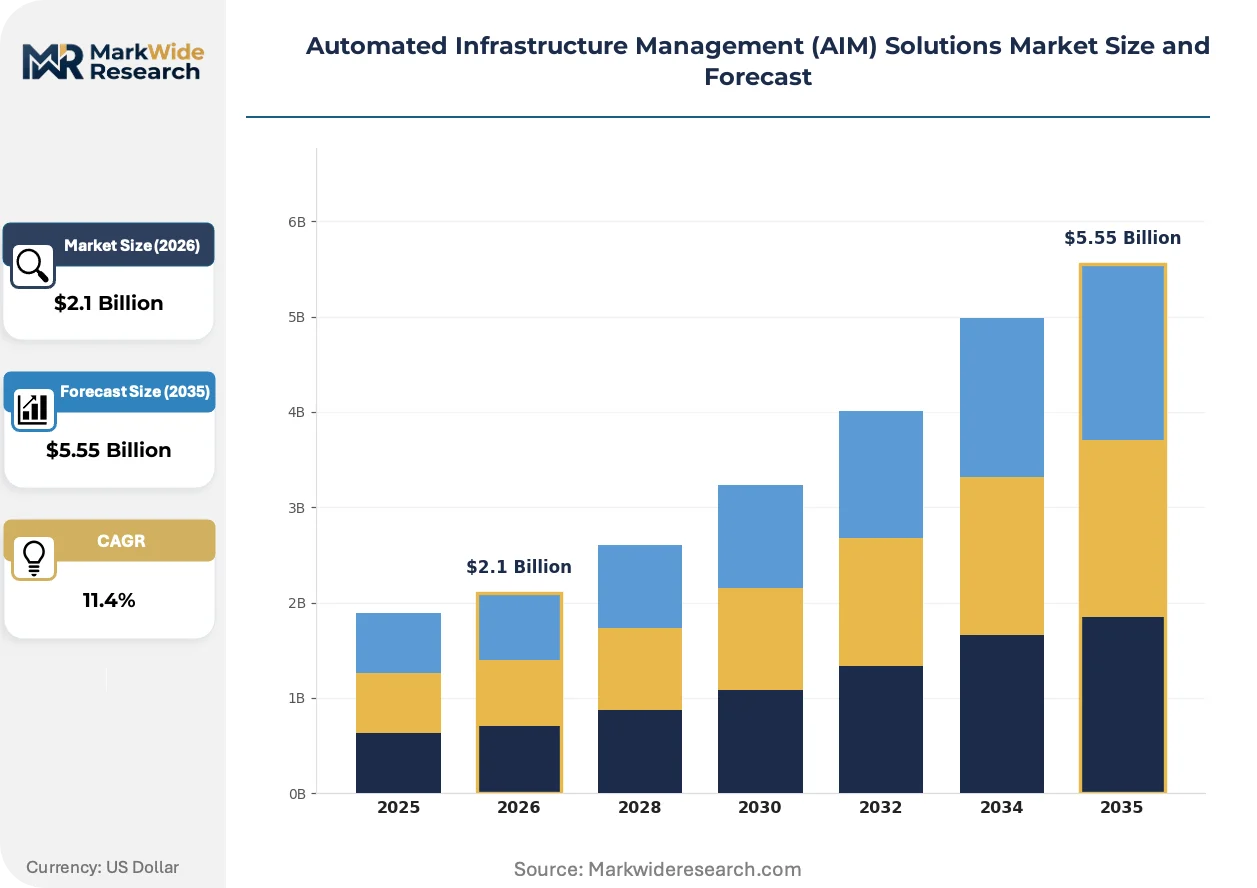
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $5.55 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Software, Platform, Integration Tools, Hardware Deployment: On-Premises, Cloud-Based, Hybrid, Managed Services End User: Telecommunications, Energy, Manufacturing, Healthcare Technology: AI, Machine Learning, IoT, Automation |
| Companies Covered | Cisco Systems Inc., CommScope Holding Company Inc., Panduit Corporation, TE Connectivity Ltd., The Siemon Company, Rittal GmbH & Co. KG, Hewlett Packard Enterprise Company, IBM Corporation, Fujitsu Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automated Infrastructure Management (AIM) Solutions Market Emerging Trajectories
Real-time location tracking is electrifying competitive positioning across the AIM landscape. Vendors race to embed granularity deeper into physical infrastructure while regulatory pressure accelerates replacement cycles.
Sensor-embedded structured cabling is electrifying how data centers document asset states. Copper and fiber assemblies now ship with integrated intelligence that reports patch cord presence and degradation without external probes. Hyperscale operators in Virginia and Texas are standardizing these smart assemblies for new builds. The technology is electrifying procurement criteria, as facility managers now specify embedded sensing as a baseline requirement rather than an upgrade option.
CSRD disclosure mandates are reshaping European deployment patterns. Facility managers must generate granular infrastructure records with audit trails that manual systems cannot satisfy. German industrial certification bodies now reference automated documentation in critical infrastructure assessments. French and Dutch operators are accelerating platform evaluations to meet disclosure deadlines.
Centralized SaaS visibility is compressing procurement decision cycles. Multi-site enterprises now reject on-premises server requirements in favor of cloud-native platforms that eliminate geographic IT overhead. Telecommunications operators with distributed 5G fiber footprints are driving this preference most acutely. Channel partners report that subscription economics now dominate RFP evaluations over perpetual license structures.
Automated Infrastructure Management (AIM) Solutions Market Segmentation
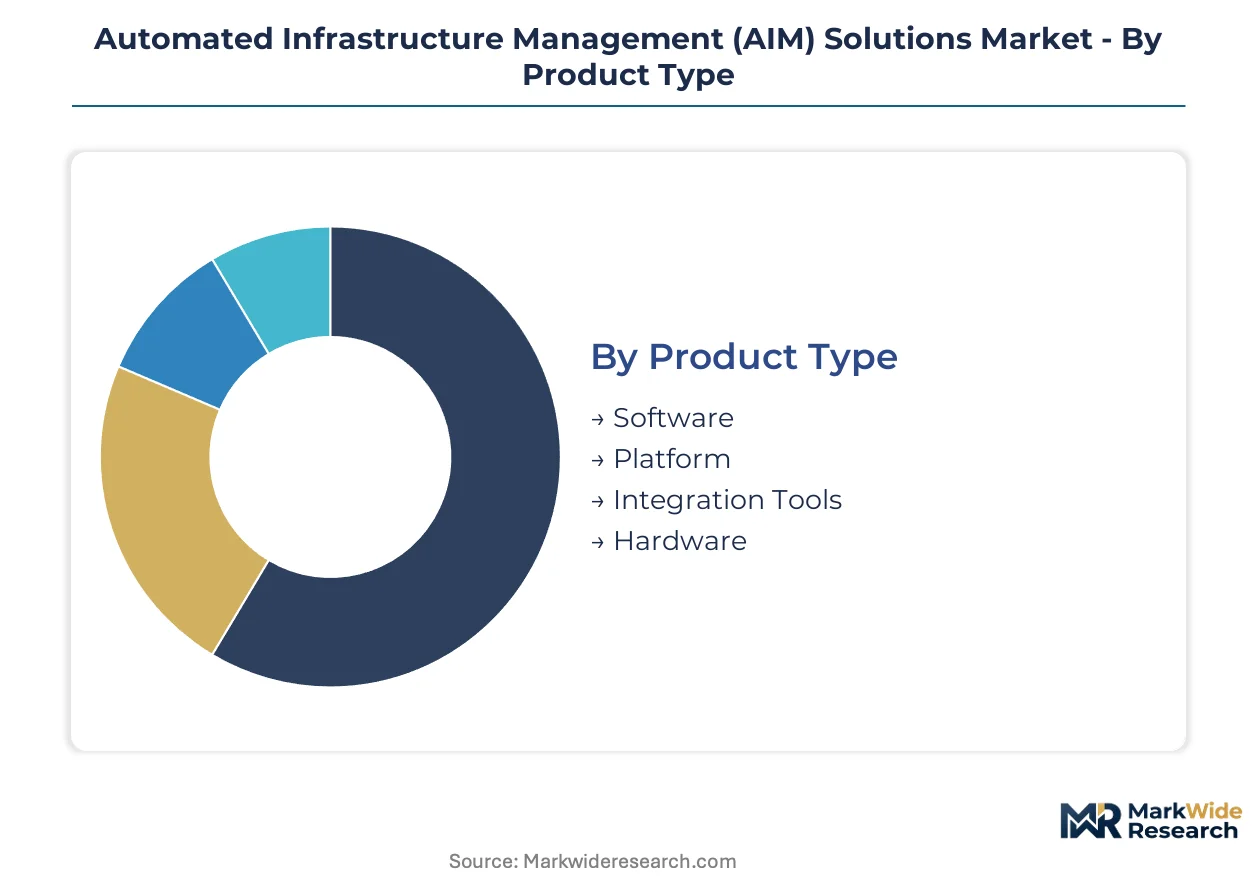
AIM Solutions segment across four critical dimensions that determine procurement patterns and vendor positioning. Product architecture, deployment topology, end-user vertical, and underlying technology stack each create distinct competitive battlegrounds with divergent margin structures and growth trajectories.
Product Type:
Software platforms command premium pricing through recurring license economics, while hardware sensors compete on manufacturing scale and integration density.
- Software:Discovery engines and documentation platforms that map physical layer assets through automated scanning protocols. Telecommunications operators in Germany and France are consolidating procurement around cloud-native software stacks that eliminate on-premises maintenance overhead.
- Platform:Unified systems combining discovery, monitoring, and reporting modules with API extensibility for third-party integration. Manufacturing complexes across the Netherlands and Belgium are driving platform consolidation as they seek single-vendor accountability for multi-site cable management.
- Integration Tools:Middleware connectors that harmonize AIM data streams with DCIM, BMS, and CMDB systems.
- Hardware:Sensor-embedded patch panels, intelligent copper assemblies, and fiber termination units with embedded intelligence.
Mature deployment sits with Hardware. Newer deployment is concentrated in Platform.
Deployment:
Cloud configurations are displacing on-premises infrastructure as multi-site enterprises prioritize centralized visibility over data sovereignty control.
- Cloud-Based:SaaS-delivered AIM platforms with browser-based dashboards and API access for enterprise integration. Distributed telecommunications operators with 5G fiber footprints spanning multiple European jurisdictions are driving the steepest expansion trajectory here.
- On-Premises:Self-hosted server deployments maintaining complete data control within facility boundaries. German industrial certification bodies and France's critical infrastructure operators favor on-premises for CSRD audit trail isolation.
- Hybrid:Split configurations with sensitive discovery data on-premises and analytics processing in cloud environments.
- Managed Services:Outsourced AIM operations where vendors assume responsibility for documentation accuracy and system maintenance.
Established procurement favors On-Premises. Accelerating migration targets Cloud-Based.
End User:
Telecommunications verticals generate absolute revenue concentration through fiber densification mandates, while manufacturing and energy present fragmented but expanding opportunity.
- Telecommunications:Mobile network operators and fixed-line carriers documenting millions of strand terminations across 5G and fiber-to-the-home builds. German and French operators face the most acute documentation pressure from national broadband targets.
- Manufacturing:Industrial automation facilities tracking dense cable plant across production lines, robotics, and control systems. The Netherlands' high-tech manufacturing corridor and Belgium's chemical processing clusters are expanding fastest in this segment.
- Energy:Power generation and distribution utilities monitoring critical infrastructure cabling in substations and control centers.
- Healthcare:Hospital networks and medical device manufacturers maintaining infrastructure documentation for patient data system reliability.
Volume concentration rests with Telecommunications. Emerging penetration is strongest in Manufacturing.
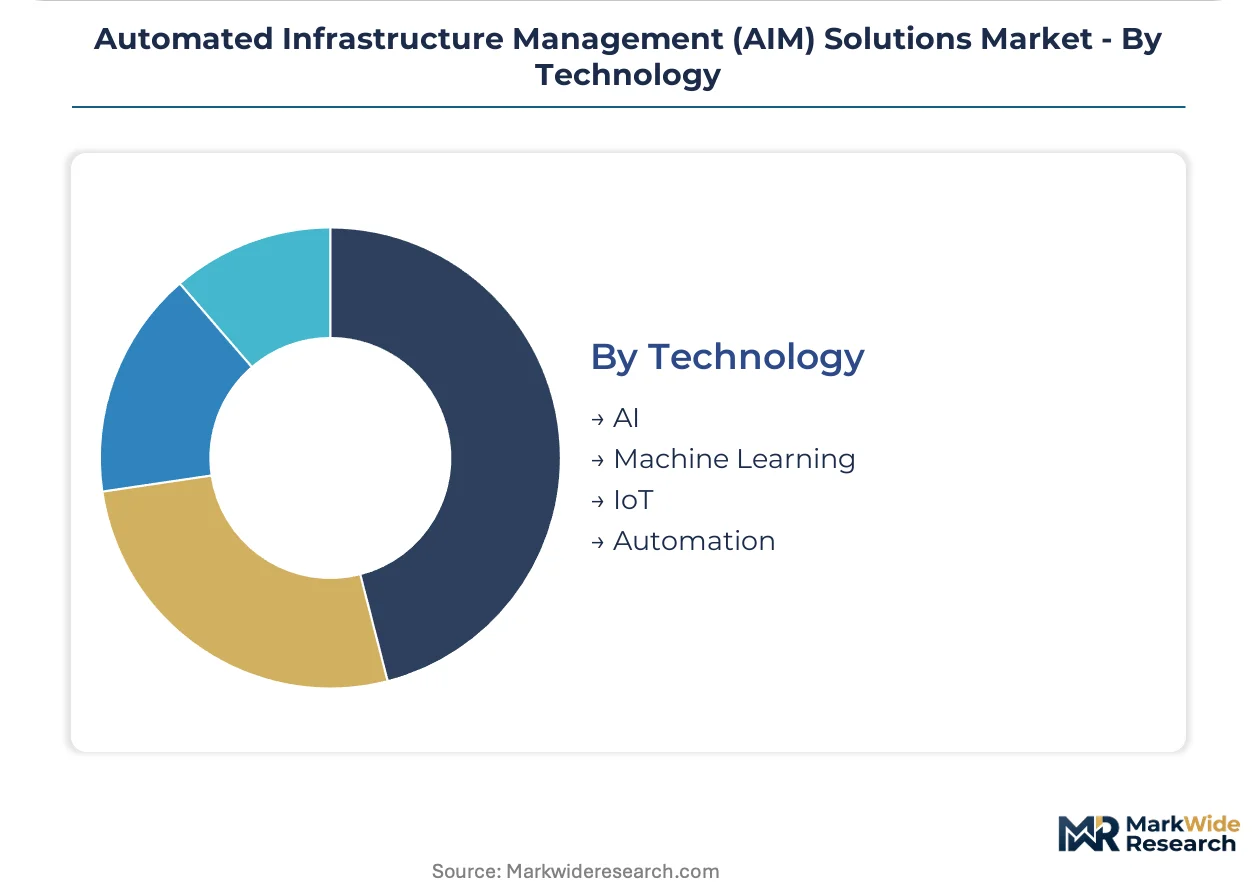
Technology:
AI and machine learning layers are commanding premium positioning through predictive capabilities, while IoT sensor networks enable granular physical layer visibility.
- AI:Neural network models analyzing infrastructure data patterns to predict degradation and optimize maintenance scheduling. German data center operators are deploying AI modules for predictive cable failure detection ahead of CSRD-mandated reliability disclosures.
- IoT:Distributed sensor networks embedded in copper and fiber assemblies reporting real-time presence, temperature, and connection state. French industrial facilities are standardizing IoT-enabled patch cord identification for automated inventory reconciliation.
- Machine Learning:Supervised and unsupervised learning algorithms refining asset discovery accuracy and anomaly detection thresholds.
- Automation:Robotic process automation for documentation generation, audit report compilation, and change management workflow execution.
Production-grade deployment centers on IoT. Capability investment is flowing fastest into AI.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Copper and fiber sensor module fabrication concentrates in Germany's industrial heartland, anchoring European supply chains for intelligent cabling assemblies. Facility managers across four major economies now confront divergent regulatory timelines for infrastructure disclosure mandates.
United States
Virginia and Texas hyperscale campuses drive embedded-sensor procurement for new data center builds. FCC equipment authorization requirements shape hardware design for telecommunications sensor modules. Northern Virginia's Ashburn corridor standardizes smart copper and fiber assemblies as baseline procurement.
Germany
Industrial manufacturing complexes in Bavaria and Baden-Württemberg generate the densest cable management verification obligations under national building codes. KBA certification bodies reference automated documentation for critical infrastructure assessments. Munich automotive clusters deploy patch-level tracking across robotics and control systems.
France
ANSM and CNIL frameworks compel data isolation architectures for physical layer monitoring systems. Île-de-France telecommunications operators accelerate platform evaluations to meet CSRD disclosure deadlines. Paris-region data centers favor hybrid deployments with sensitive discovery data retained on-premises.
Netherlands
Eindhoven's high-tech manufacturing corridor expands fastest in industrial-grade patch cord identification. National broadband targets pressure operators to document fiber terminations with precision. Rotterdam port logistics facilities adopt cloud-native visibility platforms for multi-site consolidation.
United Kingdom
London financial services data centers prioritize predictive maintenance modules for reliability assurance. Post-Brexit regulatory divergence creates procurement complexity for cross-border deployments. Slough's enterprise campus clusters standardize API-extensible platforms for third-party integration.
Automated Infrastructure Management (AIM) Solutions Market Vendor Landscape
Global majors compete with regional champions across protocol standardization and manufacturing scale, producing a tiered structure with consolidated leadership at the top and fragmentation in specialized hardware. Networking heritage players anchor software-platform revenue through bundled hardware-software stacks. Physical-layer specialists command premium positioning in industrial-grade sensor assemblies. Two dominant competitive moves are reshaping positioning: strategic partnerships to harmonize discovery protocols across vendor ecosystems, and backward integration into captive sensor manufacturing to compress hardware margins.
Within the networking-platform tier, Cisco Systems Inc. exemplifies bundled ecosystem strategies that create captive demand for proprietary discovery protocols. CommScope Holding Company Inc. and Panduit Corporation anchor physical-layer specialization, with the former representing manufacturing-scale consolidation in structured cabling systems and the latter occupying premium positioning in factory-automation identification technologies. These three companies collectively illustrate how competitive advantage separates software-centric platform economics from hardware-centric manufacturing scale.
| Leading Market Players |
|---|
| Cisco Systems Inc. |
| CommScope Holding Company Inc. |
| Panduit Corporation |
| TE Connectivity Ltd. |
| The Siemon Company |
| Rittal GmbH & Co. KG |
| Hewlett Packard Enterprise Company |
| IBM Corporation |
| Fujitsu Limited |
| Others |
Supply Flow & Price Mechanics
Hyperscale data center operators in Virginia and Texas concentrate procurement power, anchoring subscription-based SaaS pricing as the dominant commercial model across the AIM landscape.
Pricing Analysis
Warranty and calibration service bundling separates premium platform vendors from unbundled hardware suppliers. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and deployment complexity. Price differentiation hinges on CSRD audit-trail compliance and predictive maintenance module inclusion. Mid-market manufacturing buyers exhibit acute price sensitivity, while telecommunications operators with 5G densification mandates absorb premium positioning.
Supply Chain Analysis
Domestic-content mandates in Germany's KBA certification framework and France's critical infrastructure codes are reshaping sourcing patterns for sensor-embedded assemblies. Manufacturing concentrates in Germany, China, and Mexico for copper termination units and fiber patch panels. Supply chains rest on rare-earth magnet availability for sensor modules, specialized semiconductor foundry capacity, and halogen-free compound formulations. Single-source vulnerability runs through Taiwanese chip fabrication for intelligent patch cord controllers. Distribution runs through authorized system integrators and direct OEM procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The AIM market functions as a cost-of-compliance arena where the EU CSRD mandate erects a regulatory moat, advantaging vendors with pre-built audit-trail architectures over spreadsheet-dependent competitors.
For Market Incumbents: Lock in CSRD-compliant platform deployments across German industrial clusters before disclosure deadlines harden switching costs. Deepen backward integration into captive sensor manufacturing to compress hardware margins against CommScope-scale competitors. Prioritize API extensibility investments that harmonize discovery protocols across Cisco, Hewlett Packard Enterprise, and IBM networking stacks, neutralizing vendor lock-in threats. For New Entrants and Emerging Players: French and Dutch industrial corridors with manufacturing automation investments present the most penetrable white-space targets, lacking mature AIM penetration versus German benchmarks. Mid-sized manufacturing facilities with 500-2,000 port cable plants face acute technician scarcity, creating managed service attachment opportunities. Lead with cloud-native SaaS configurations that eliminate on-premises server overhead, matching procurement preferences of multi-site enterprises. For Investors and Strategic Acquirers: The window for entry favors vertically integrated sensor-hardware specialists with CE marking and FCC authorization already secured. Long-term viability centers on predictive maintenance AI layers that command recurring revenue premiums. Watch for hyperscale data center build-out announcements in Northern Virginia and Texas as inflection indicators for embedded-sensor assembly demand.| Strategic Initiative | Industry Significance |
|---|---|
| CSRD Compliance Certification | Pre-built audit-trail modules create switching-cost moats against manual-documentation competitors. |
| Sensor Hardware Backward Integration | In-house copper and fiber assembly production compresses margins against CommScope manufacturing scale. |
| AI Predictive Maintenance Launch | Neural network degradation flagging commands premium positioning ahead of reliability-mandated disclosures. |
| API Ecosystem Partnership | Protocol harmonization with Cisco and Hewlett Packard Enterprise reduces cross-vendor integration friction. |
| Managed Services Expansion | Outsourced documentation operations capture mid-market buyers facing physical-layer technician scarcity. |
Methodological Framework
Multi-period observation of CSRD implementation timelines, 5G fiber densification capex cycles, and hyperscale data center build-out rates anchored the trend analysis, supplemented by interviews with data center infrastructure directors, telecommunications network planners, industrial facility managers, and AIM platform engineering leads. Secondary validation drew from FCC equipment authorization databases, EU CSRD directive implementation guidance, SEC filings of structured cabling manufacturers, and hyperscaler capital expenditure disclosures. Bottom-up segment sizing triangulated against top-down macroeconomic indicators.
Segment-weighting across deployment topology, end-user vertical, and technology stack dimensions structured the analytical framework. Modeled dimensions included cloud versus on-premises configuration, telecommunications versus manufacturing vertical concentration, and IoT sensor versus AI capability investment intensity. CAGRs derived from regression analysis of historical adoption curves and regulatory deadline acceleration effects. Forecast inputs incorporated CSRD disclosure phase-in schedules and national broadband target commitments.
Revisions become necessary when CSRD implementation deadlines shift, hyperscale data center construction pauses, or semiconductor supply constraints disrupt sensor module availability. Forecasts reflect documented assumptions about regulatory enforcement consistency and enterprise cloud-migration velocity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Automation Systems
Signage Market
Building Automation Systems
Building Information Management System Market
Building Automation Systems
US Commercial Building Automation Market
Building Automation Systems
Building Analytics Market
Building Automation Systems
Rotary Sprinkler System Market
Building Automation Systems
Infrastructure Monitoring Market
Building Automation Systems
Automated Daylight Harvesting Systems Market
Building Automation Systems
Europe Commercial Refrigeration Market
Building Automation Systems
Vinyl Strip Door and Curtains Market
Building Automation Systems
Integrated Building Management Systems Market
Building Automation Systems
AEC Market
Building Automation Systems
Europe Smart Windows Market
Building Automation Systems
Platform Lifts Market
Building Automation Systems
Underfloor Heating Actuator Market
Building Automation Systems
Architecture Smart Glass Market
Building Automation Systems
Smart Passenger Elevators Market