
 Smart Passenger Elevators Market | 2026-2036
Smart Passenger Elevators Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Passenger Elevators Market Insights
Chinese elevator component manufacturing is hardening as domestic producers scale linear motor and permanent magnet synchronous machine output. Otis Worldwide Corporation leverages its global service network to sustain long-term maintenance revenue streams. KONE Corporation anchors its competitive stance through deep R&D investment in ropeless elevator architectures. Schindler Group differentiates via digital platform integration across commercial building portfolios.
Smart passenger elevators integrate electromechanical vertical transportation with sensor networks, destination control algorithms, and regenerative drive systems capable of recovering up to thirty percent of consumed energy during descent. These systems serve primarily to optimize passenger throughput, reduce wait times, and enable predictive maintenance in high-occupancy structures. Machine Room-Less configurations now dominate new construction bids across mid-rise segments due to their reduced shaft footprint and lower structural load requirements. IoT-Enabled technology leads retrofit spending as building operators prioritize real-time fault detection and remote diagnostics over full system replacement.
The EU Machinery Directive and EN 81-20 standards enforce mandatory safety clearances and accessibility features across European installations, while China's GB 7588 national standard governs brake systems and door protection mechanisms in the world's largest new-build market. In the United States, ASME A17.1 and ADA compliance requirements shape product specifications for public and commercial buildings, effectively filtering non-compliant suppliers from federal and municipal procurement channels. Stakeholders must weigh capital allocation between AI-powered predictive maintenance platforms and physical modernization of aging installed bases across diverging regulatory timelines.
Market Dynamics
Destination dispatch algorithms and regenerative drive architectures are compressing installation footprints while mandating new skill sets across service networks. China's tier-one vertical density requirements and the EU Machinery Directive's safety mandates are forcing synchronous upgrades to electromechanical and digital subsystems.
Growth Catalysts
- Permanent magnet synchronous machines:These motors reduce energy consumption by eliminating gearbox losses. High-rise residential towers in Shanghai and Shenzhen now specify them as baseline.
- EN 81-20 accessibility mandates:European standards require wider door clearances and tactile controls. New installations across Germany, France, and Italy must comply, accelerating modernization cycles.
- Smart building integration:Building management systems in Dubai and Singapore now require API-compatible elevator controllers. This specification is expanding procurement beyond traditional MEP contractors.
Market Restraints
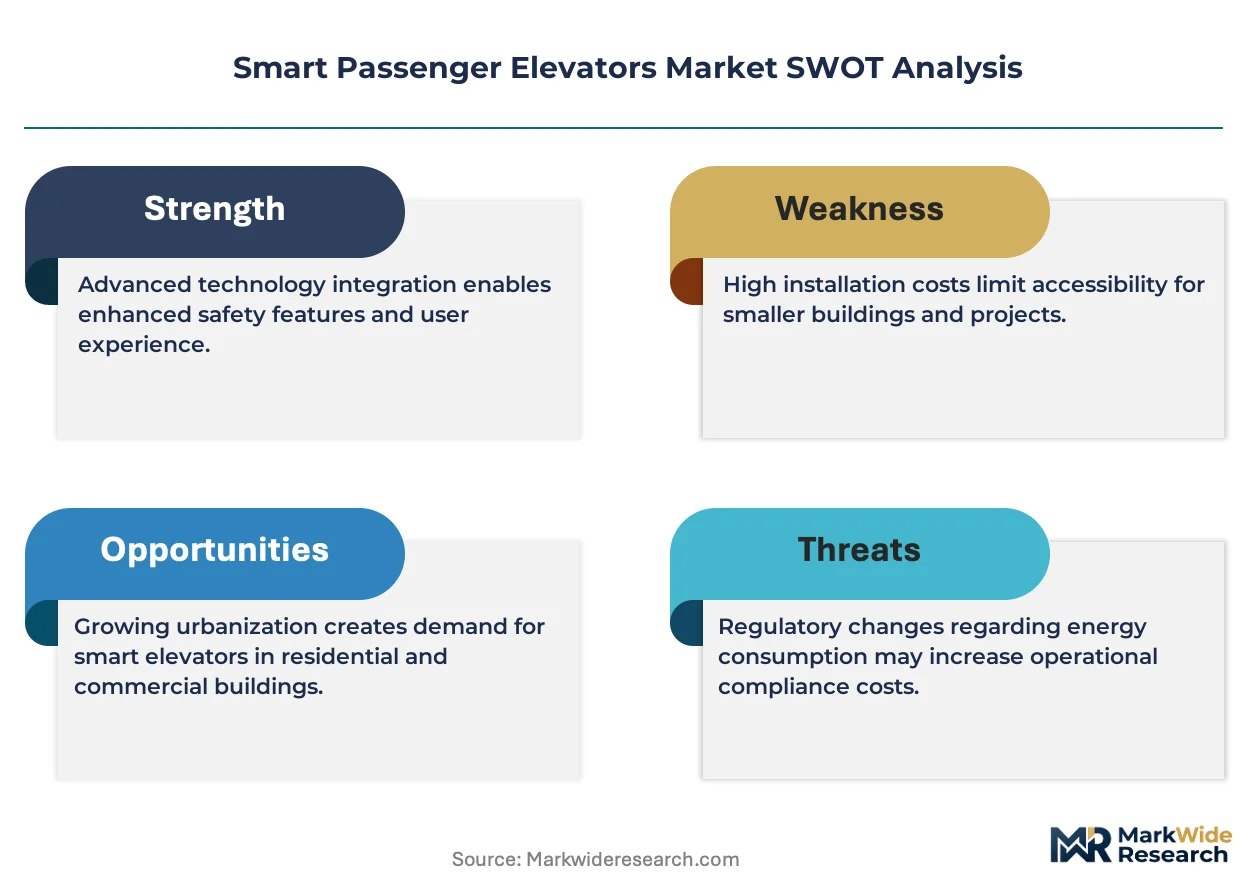
- Rare earth magnet supply concentration:Neodymium and dysprosium processing concentrates in Chinese refineries. Price volatility for permanent magnet synchronous machines follows export quota fluctuations.
- Machine room-less structural loads:Existing buildings from the 1980s and 1990s lack the shaft tolerance for MRL retrofits. Technical limitation excludes roughly forty percent of the installed base from upgrade paths.
- CE marking timeline friction:EU conformity assessment for AI-enabled predictive maintenance modules extends certification cycles by eight to fourteen months.
Strategic Opportunities
- Ropeless elevator architectures:Linear motor platforms eliminate cable length constraints. KONE Corporation and Japanese developers are piloting systems for supertall structures exceeding six hundred meters.
- India's PLI scheme for component manufacturing:Production-linked incentives for electromechanical equipment are attracting motor and controller assembly to Gujarat and Tamil Nadu.
- IoT-Enabled retrofit channels:Sensor retrofit kits sold through facility management platforms bypass traditional OEM service contracts. This channel innovation captures mid-rise commercial buildings with limited capex budgets.
Industry Challenges
- Predictive maintenance algorithm validation:AI fault detection requires labeled failure datasets that OEMs withhold. Independent service providers face data scarcity when training models.
- ASME A17.1 compliance integration:US jurisdictions enforce varying adoption timelines for the latest safety code editions. Manufacturers maintain parallel certification tracks for state-by-state market access.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Passenger Elevators Market |
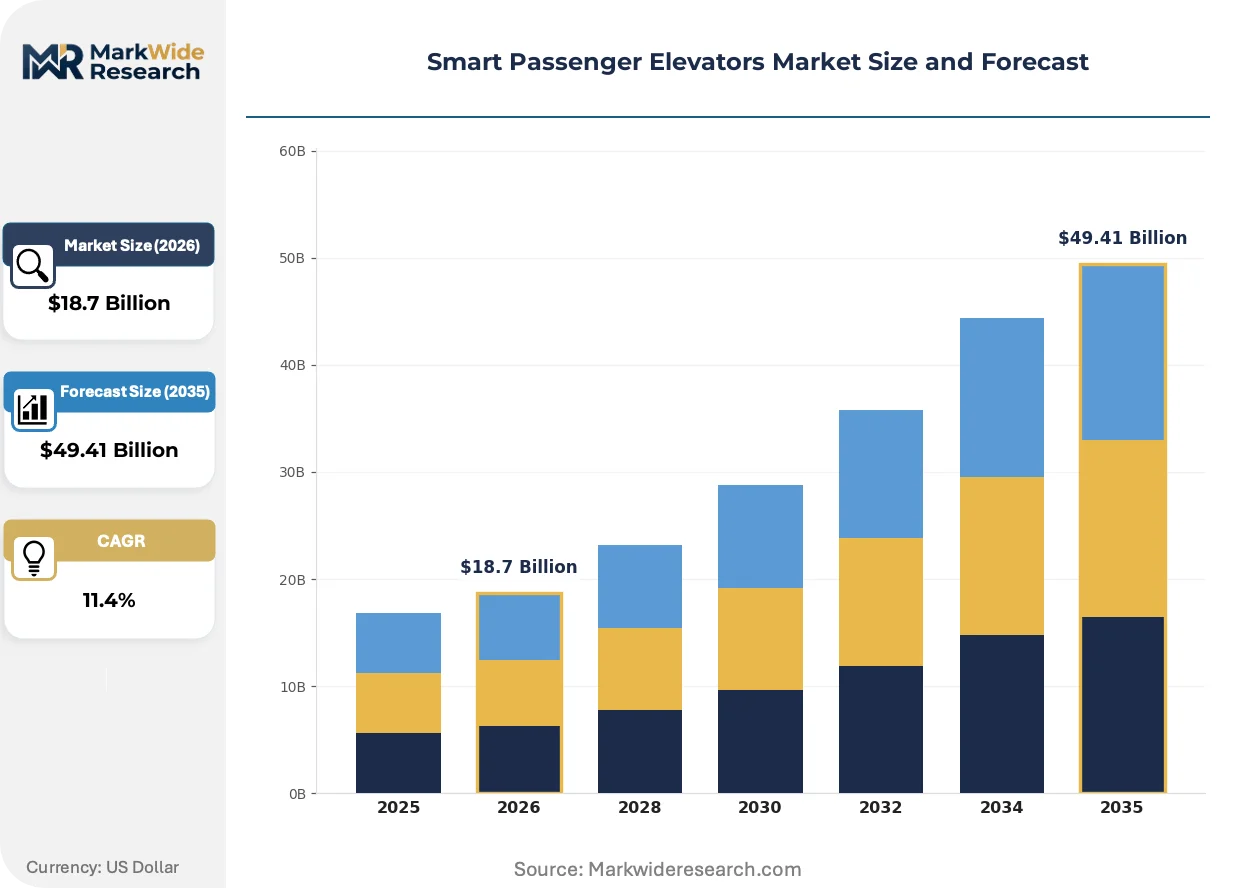
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $49.41 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ropeless Elevators, Machine Room-Less, Hydraulic, Traditional Technology: IoT-Enabled, AI-Powered, Touchless Controls, Energy Recovery End User: Residential Complexes, Commercial Buildings, Healthcare Facilities, Airports Installation Type: New Installations, Modernization Projects, Retrofitting, Maintenance Services |
| Companies Covered | Otis Worldwide Corporation, KONE Corporation, Schindler Group, thyssenkrupp AG, Mitsubishi Electric Corporation, Hitachi Ltd., Fujitec Co., Ltd., Hyundai Elevator Ltd, Robert Bosch GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Passenger Elevators Market Trends and Innovations
Digital twin architectures and edge computing nodes are embedding intelligence directly into hoistway equipment. These shifts are compressing the boundary between electromechanical hardware and software-defined service layers.
Regenerative drive systems capture kinetic energy during descent and feed it back into building grids. High-rise commercial developers in New York and Chicago now specify them as standard for LEED certification pathways. The technology is expanding into mid-rise residential segments as component costs decline and utility interconnection standards harmonize.
The EU F-Gas Regulation is phasing down hydrofluorocarbon refrigerants used in elevator machine room cooling. Manufacturers are retrofitting magnetic bearing systems and oil-free compressors to maintain thermal performance. European new-build projects face accelerated compliance deadlines in 2027, compressing procurement timelines for compliant equipment.
Facility managers are unbundling maintenance contracts from original equipment purchases. Third-party service platforms in London and Sydney now bid on multi-brand portfolios using standardized diagnostic protocols. This buying-pattern change is fragmenting the aftermarket and pressuring OEM service margins in commercial building verticals.
Smart Passenger Elevators Market Segmentation
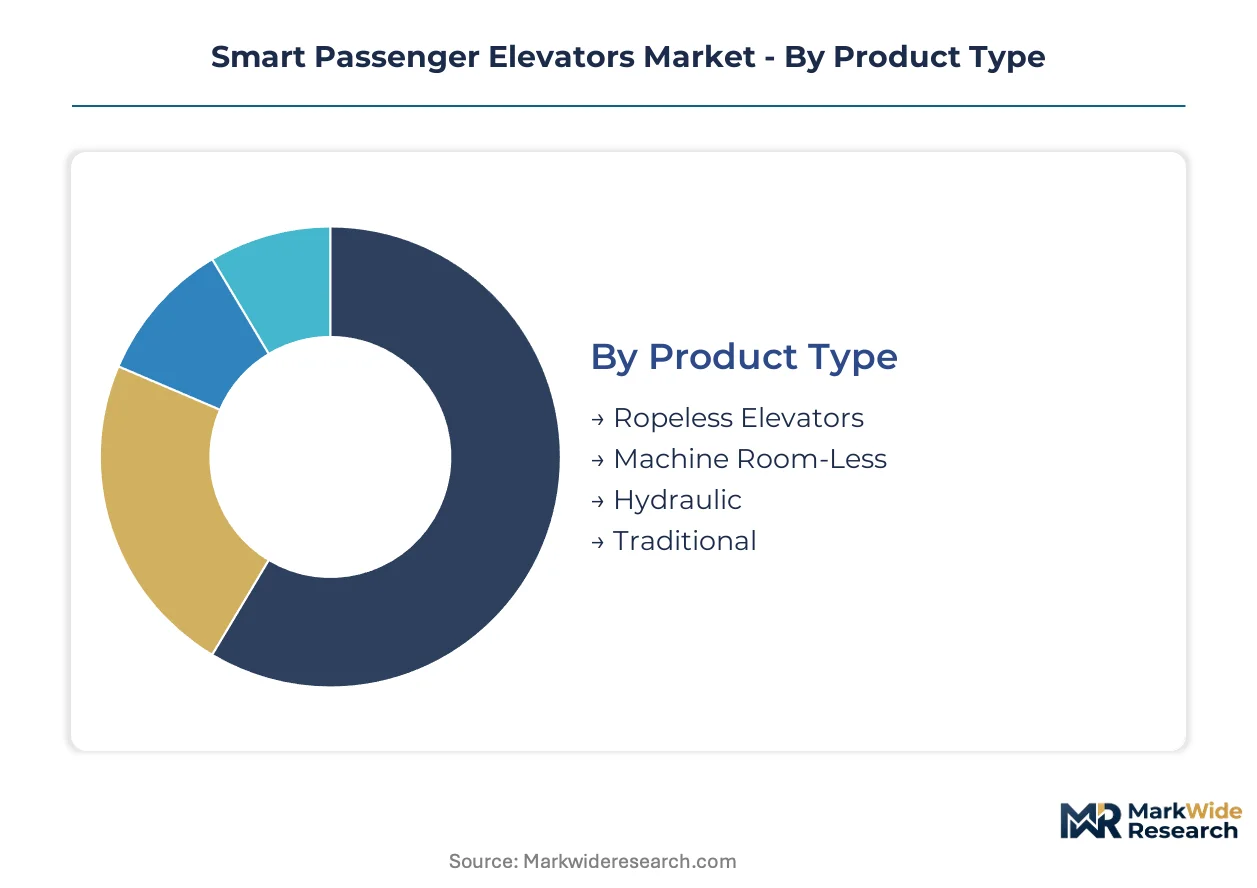
Segmentation in smart passenger elevators reveals how capital allocation, regulatory compliance, and building lifecycle position diverge across electromechanical architectures. Procurement patterns cluster around shaft constraints in dense urban cores versus retrofit economics in aging commercial stock.
Product Type:
Capital intensity peaks where magnetic levitation and linear motor systems displace conventional cable mechanics, while mid-rise developers optimize around structural load reductions.
- Machine Room-Less:Permanent magnet synchronous machines eliminate gearbox assemblies and reduce overhead structural requirements. Shanghai and Shenzhen high-rise residential towers specify MRL as baseline procurement, driven by floor plate efficiency mandates and reduced construction timelines.
- Ropeless Elevators:Linear motor platforms suspend cabins via magnetic guidance, removing cable length constraints entirely. Supertall developments exceeding six hundred meters in Dubai and Singapore pilot these systems, constrained by electromagnetic interference shielding costs and unproven long-term maintenance protocols.
- Hydraulic:Piston-driven systems dominate low-rise commercial retrofits where shaft headroom is unavailable. Building operators in Chicago and London maintain installed bases despite higher energy consumption profiles.
- Traditional:Traction elevators with machine rooms persist in institutional buildings with predictable traffic patterns. Procurement concentrates in government and educational facilities with extended capital planning cycles.
Most installed capacity flows through Machine Room-Less configurations. Expansion is steepest in Ropeless Elevators.
Technology:
Software-defined functionality now commands premium positioning, with sensor density and algorithmic capability separating price tiers.
- IoT-Enabled:Sensor networks transmit vibration, temperature, and door-cycle data to cloud analytics platforms. Facility managers in London and Sydney unbundle these retrofit kits from OEM service contracts, capturing mid-rise commercial buildings with constrained capital expenditure.
- Energy Recovery:Regenerative drives capture kinetic energy during descent and feed surplus power into building electrical grids. New York and Chicago commercial developers specify these for LEED certification pathways, with utility interconnection standards harmonizing across North American jurisdictions.
- AI-Powered:Predictive maintenance algorithms analyze operational patterns to forecast component failures. Independent service providers face data scarcity when training models, as OEMs withhold labeled failure datasets.
- Touchless Controls:Gesture and mobile-app interfaces reduce surface contact in healthcare and airport environments. Post-pandemic specification persists in Dubai and Singapore despite higher per-unit controller costs.
Technology procurement concentrates in IoT-Enabled retrofit channels. AI-Powered systems are climbing the fastest as building operators prioritize uptime guarantees over hardware replacement.
End User:
Traffic pattern volatility and accessibility mandates create divergent specification requirements across verticals.
- Commercial Buildings:Destination dispatch algorithms optimize passenger throughput during peak arrival and departure windows. EN 81-20 accessibility mandates in Germany, France, and Italy require wider door clearances and tactile controls, accelerating modernization cycles in European office stock.
- Healthcare Facilities:Stretcher-compatible cabins and emergency power systems govern procurement. ASME A17.1 compliance integration varies across US state jurisdictions, forcing manufacturers to maintain parallel certification tracks.
- Residential Complexes:Noise reduction and space efficiency dominate specification in China's tier-one cities. GB 7588 national standards govern brake systems and door protection mechanisms in the world's largest new-build market.
- Airports:High-capacity shuttle systems with baggage cart accommodation require reinforced platform edges. Dubai and Singapore hub expansions drive demand for API-compatible controllers integrated with building management systems.
Commercial Buildings absorb the largest share of new technology deployment. Healthcare Facilities are expanding most quickly as aging infrastructure meets accessibility retrofit deadlines.
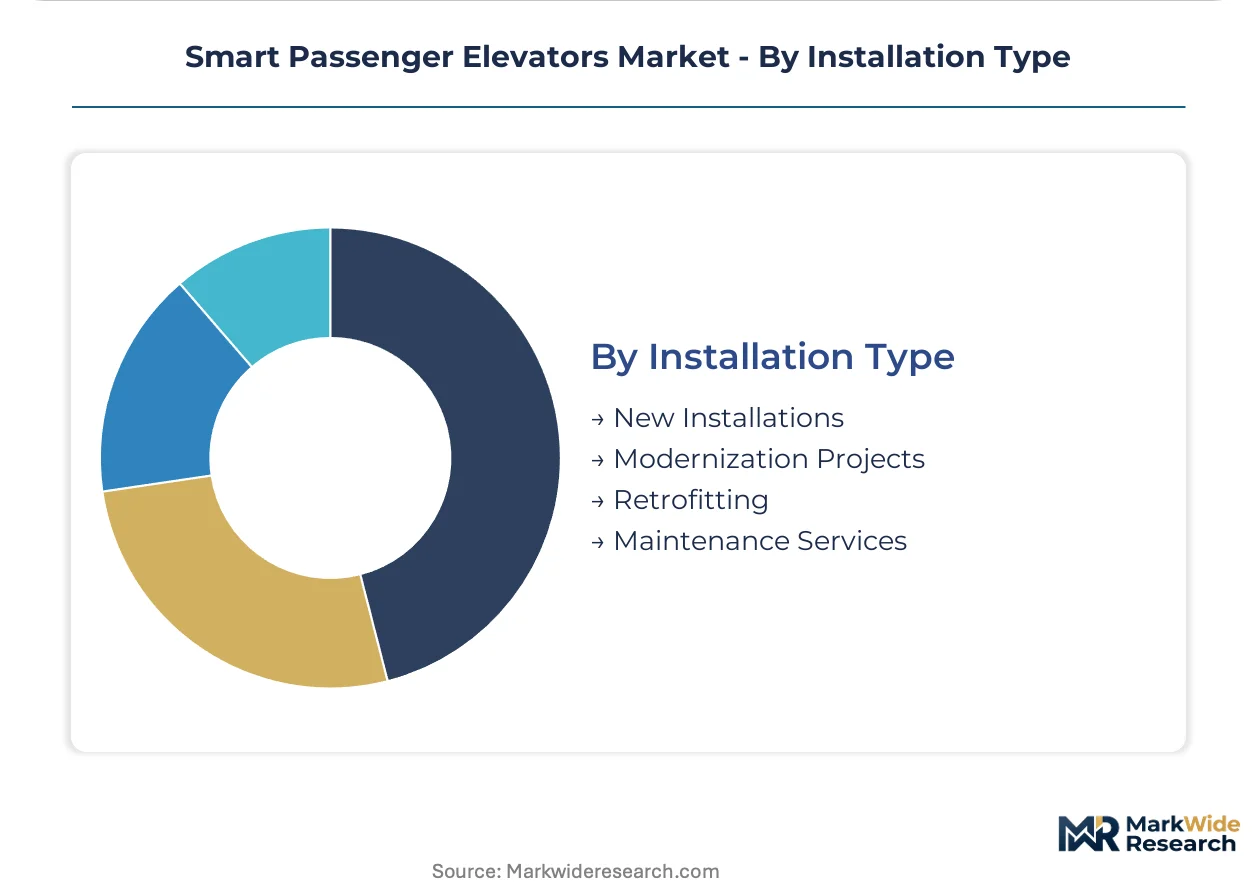
Installation Type:
Revenue recurrence and margin structure separate one-time construction economics from service contract annuities.
- New Installations:Complete electromechanical systems specified during construction benefit from integrated smart building design. China's tier-one vertical density requirements and smart building mandates converge to accelerate procurement.
- Modernization Projects:Controller and drive system upgrades extend operational life without full replacement. EU Machinery Directive safety clearances and EN 81-20 accessibility requirements force synchronous electromechanical and digital subsystem upgrades.
- Maintenance Services:Predictive maintenance platforms and remote diagnostics reduce emergency call frequency. Third-party service platforms fragment the aftermarket by bidding on multi-brand portfolios using standardized diagnostic protocols.
- Retrofitting:Sensor and controller additions to legacy systems bypass full replacement costs. Machine room-less structural load requirements exclude roughly forty percent of 1980s and 1990s installed bases from upgrade paths.
Maintenance Services generate the highest recurring revenue share. Modernization Projects are gaining share fastest as regulatory compliance deadlines compress procurement timelines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redirecting component manufacturing toward jurisdictions with production-linked incentives, while compliance-heavy markets accelerate modernization cycles to meet accessibility mandates. Elevator producers now balance supply-chain cost optimization against the premium pricing power that EU and North American safety certifications command.
China
GB 7588 national standards governing brake systems and door protection mechanisms are tightening across new-build specifications. Shanghai and Shenzhen high-rise residential towers now mandate destination dispatch systems as baseline procurement. The Yangtze River Delta cluster concentrates permanent magnet synchronous machine output as domestic producers scale linear motor manufacturing.
Germany
EN 81-20 accessibility mandates requiring wider door clearances and tactile controls are forcing synchronous electromechanical and digital subsystem upgrades. The EU Machinery Directive's safety clearances compress procurement timelines for compliant equipment. Bavaria and North Rhine-Westphalia host the densest concentration of modernization project contracting across European office stock.
United States
ASME A17.1 compliance integration varies across state jurisdictions, compelling manufacturers to maintain parallel certification tracks. New York and Chicago commercial developers specify regenerative drive systems as standard for LEED certification pathways. The Northeast Corridor absorbs the largest share of predictive maintenance platform deployment in aging commercial infrastructure.
India
The PLI scheme for electromechanical equipment attracts motor and controller assembly to Gujarat and Tamil Nadu. Central Electricity Authority guidelines on building energy codes are accelerating specification of energy recovery systems in commercial developments. Maharashtra and Karnataka urban clusters drive demand for machine room-less configurations in mid-rise residential construction.
United Arab Emirates
Dubai and Singapore hub expansions require API-compatible controllers integrated with building management systems. MOHAP technical regulations on healthcare facility vertical transportation govern stretcher-compatible cabin specifications. Dubai's supertall developments exceeding six hundred meters pilot ropeless elevator architectures with electromagnetic interference shielding.
Smart Passenger Elevators Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue IoT-enabled retrofit channels and third-party service platform aggregation. The vendor base organizes around three archetypes: integrated electromechanical manufacturers with captive service networks, component specialists supplying motors and controllers to multiple OEMs, and digital-native platforms unbundling predictive maintenance from hardware sales. Dominant competitive moves include strategic partnerships for smart building API integration and geographic expansion through acquisition of regional installation contractors.
Within the integrated manufacturer tier, Otis Worldwide Corporation and KONE Corporation anchor positions through global service network scale and ropeless architecture R&D respectively. Schindler Group exemplifies the digital platform differentiation archetype. Among Japanese electromechanical producers, Mitsubishi Electric Corporation and Hitachi Ltd. occupy positions tied to permanent magnet synchronous machine supply chains. Hyundai Elevator Ltd represents the Korea-based specialist fabricator segment. These named entities collectively illustrate how competitive positioning fragments across hardware manufacturing depth, software integration capability, and aftermarket service contract retention.
| Leading Market Players |
|---|
| Otis Worldwide Corporation |
| KONE Corporation |
| Schindler Group |
| thyssenkrupp AG |
| Mitsubishi Electric Corporation |
| Hitachi Ltd. |
| Fujitec Co., Ltd. |
| Hyundai Elevator Ltd |
| Robert Bosch GmbH |
| Others |
Pricing and Supply Chain Analysis
Neodymium and dysprosium processing costs cascade through permanent magnet synchronous machine pricing tiers, with Chinese refinery export quotas compressing margins for European and North American OEMs while domestic producers in the Yangtze River Delta capture cost advantages. This input-cost geography directly stratifies final system pricing across certification-grade boundaries.
Pricing Analysis
Distributor margins on IoT-enabled retrofit kits range from fifteen to twenty-five points above direct-OEM contract pricing for equivalent sensor hardware. Three-tier pricing structure across premium, standard, and economy levels separates AI-powered predictive maintenance bundles from basic destination dispatch controllers. Pricing pressure stems from third-party service platforms fragmenting aftermarket revenue pools. Mid-rise commercial building operators exhibit highest price sensitivity, while supertall developers in Dubai and Singapore absorb premium positioning for ropeless architectures.
Supply Chain Analysis
Refurbishment flows for legacy traction motors and gearbox assemblies concentrate in Gujarat and Tamil Nadu under India's PLI scheme incentives, creating secondary supply channels for modernization contractors. Permanent magnet synchronous machines draw from Chinese rare earth processing and Japanese precision winding operations. Single-source vulnerability in neodymium refining exposes European and North American producers to quota-driven input cost spikes. Distribution runs through captive OEM service networks and emerging facility-management platform channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Smart passenger elevators constitute a late-cycle quality story as building operators prioritize predictive uptime guarantees over lowest-first-cost procurement, with EN 81-20 accessibility mandates accelerating premium specification share.
For Market Incumbents: Extend predictive maintenance data moats by acquiring independent IoT platform operators before labeled failure datasets become widely available. Deepen backward integration into permanent magnet synchronous machine winding operations in Tamil Nadu to offset Chinese rare earth price volatility. CE marking timeline friction for AI-enabled modules represents the most immediate regulatory threat to service revenue retention. For New Entrants and Emerging Players: Facility-management platform partnerships offer the lowest customer-acquisition-cost route into mid-rise commercial portfolios where OEM service contracts expire. Target India's Maharashtra and Karnataka urban clusters for machine room-less controller assembly under PLI scheme coverage. White-space availability concentrates in standardized diagnostic protocol aggregation across multi-brand maintenance bidding. For Investors and Strategic Acquirers: Roll-up economics work for regional installation contractors with deep municipal permitting relationships because smart building integration mandates are fragmenting procurement beyond traditional MEP channels. Five-to-ten year viability hinges on aftermarket service contract retention as hardware margins compress. Monitor EN 81-20 compliance deadline acceleration across Germany, France, and Italy as the signal for modernization project backlog inflection.| Strategic Initiative | Industry Significance |
|---|---|
| API-Compatible Controller Development | Enables integration with Dubai and Singapore building management systems procurement specifications. |
| Rare Earth Magnet Supply Diversification | Reduces quota exposure from Chinese refineries for permanent magnet synchronous machine production. |
| Predictive Maintenance Platform Acquisition | Captures labeled failure datasets that OEMs currently withhold from independent service providers. |
| Regional Installation Contractor Roll-Up | Consolidates municipal permitting capabilities fragmented across local MEP specialists. |
| CE Marking Acceleration Investment | Compresses eight-to-fourteen-month AI module certification cycles ahead of EU compliance deadlines. |
Research Methodology
Multiple input streams — elevator OEM product managers, facility management platform engineers, smart building systems integrators, and aftermarket service directors — were reconciled against customs data for permanent magnet synchronous machine trade flows, EU Machinery Directive implementation guidance, and ASME A17.1 jurisdictional adoption records. Bottom-up project pipeline tracking across Shanghai, Shenzhen, Dubai, and Singapore developments was cross-validated with top-down equipment procurement estimates from construction industry databases.
Historical installation volumes were benchmarked against expert panel assessments of ropeless elevator pilot adoption and IoT retrofit penetration rates across the projection horizon. Segmentation modeling incorporated product type, technology tier, end-user vertical, and installation category dimensions. CAGRs were derived from regression analysis of regulatory compliance deadline impacts and component cost curves for regenerative drive systems.
Rare earth export quota volatility, CE marking timeline extensions for AI-enabled modules, and state-level ASME A17.1 adoption divergence are the dominant revision risks to forecast assumptions. Practitioners should monitor Chinese Ministry of Commerce rare earth policy announcements and EU F-Gas Regulation compliance acceleration signals for early indicators of supply cost and procurement timeline shifts.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Automation Systems
Europe Commercial Refrigeration Market
Building Automation Systems
Smart Building Solutions Market
Building Automation Systems
Building-To-Grid Technology Market
Building Automation Systems
Global Building Information Modeling (BIM) Market
Building Automation Systems
Signage Market
Building Automation Systems
US Commercial Building Automation Market
Building Automation Systems
Residential Electric Underfloor Heating Market
Building Automation Systems
Global Nordic Building Automation and Control Market
Building Automation Systems
Building Automation and Control System Market
Building Automation Systems
Global Door Closers Market
Building Automation Systems
LAMEA Building Automation System Market
Building Automation Systems
Commercial Building Automation Systems Market
Building Automation Systems
Smart Window Film Market
Building Automation Systems
Intelligent Building Automation Technologies Market
Building Automation Systems
Platform Lifts Market
Building Automation Systems
Architecture Smart Glass Market