
 Europe HVAC Controls Market | 2026-2036
Europe HVAC Controls Market Size, Share, and Industry Trends Forecast 2026-2036
Europe HVAC Controls Market Intelligence
European manufacturing capacity for advanced building automation components is hardening around integrated system providers. This shift benefits large-scale players with extensive portfolios. Siemens AG leverages its deep integration with building management systems across the continent. Schneider Electric specializes in energy management solutions for commercial and industrial clients, while Johnson Controls competes with its comprehensive suite of connected equipment and digital services.
Europe HVAC controls are networked devices and software algorithms that regulate heating, ventilation, and air conditioning systems to optimize energy use and maintain occupant comfort. These systems utilize communication protocols like BACnet and Modbus to integrate sensors, actuators, and programmable controllers. Wireless controls represent the fastest-growing technology segment, driven by retrofit projects in existing commercial buildings. Within control types, advanced thermostats and sensors are seeing high adoption by facility managers seeking granular data.
The European regulatory environment, particularly the EU Green Deal and its associated F-Gas Regulation, mandates significant improvements in building energy efficiency. Compliance with these directives necessitates the adoption of modern, intelligent HVAC controls. CE marking remains a fundamental requirement for market access, ensuring product safety and performance standards. The key decision for building owners is how to phase investments in these upgrades to meet both regulatory deadlines and financial objectives.
Market Dynamics
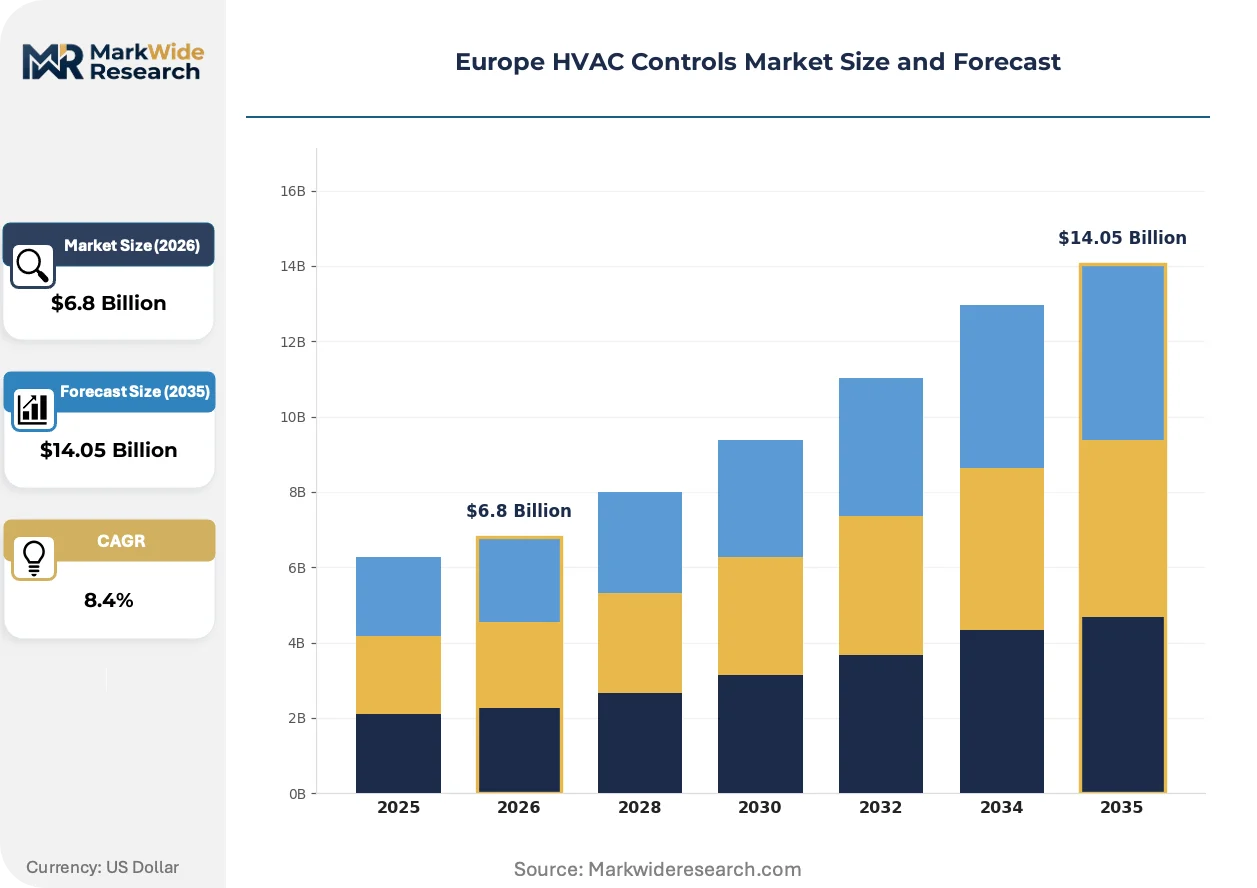
The European HVAC controls market is shaped by the regulatory imperative for decarbonization under the EU Green Deal. This pressure forces building owners to upgrade legacy systems, creating a direct pull for intelligent, energy-efficient control solutions across the continent.
Growth Catalysts
- F-Gas Regulation Mandates:The EU's F-Gas Regulation requires phase-downs of high-GWP refrigerants, compelling upgrades to HVAC systems and their associated controls. This creates a non-discretionary replacement cycle for control hardware and software.
- Data Center Thermal Management:The proliferation of data centers across Europe, particularly in FLAP-D (Frankfurt, London, Amsterdam, Paris, Dublin) hubs, necessitates precise and reliable HVAC controls to manage intense heat loads and ensure uptime.
- Wireless Technology for Retrofits:Wireless communication protocols enable cost-effective upgrades in existing buildings where running new wires is impractical. This technology is critical for modernizing Europe's extensive stock of older commercial and public buildings.
Market Restraints
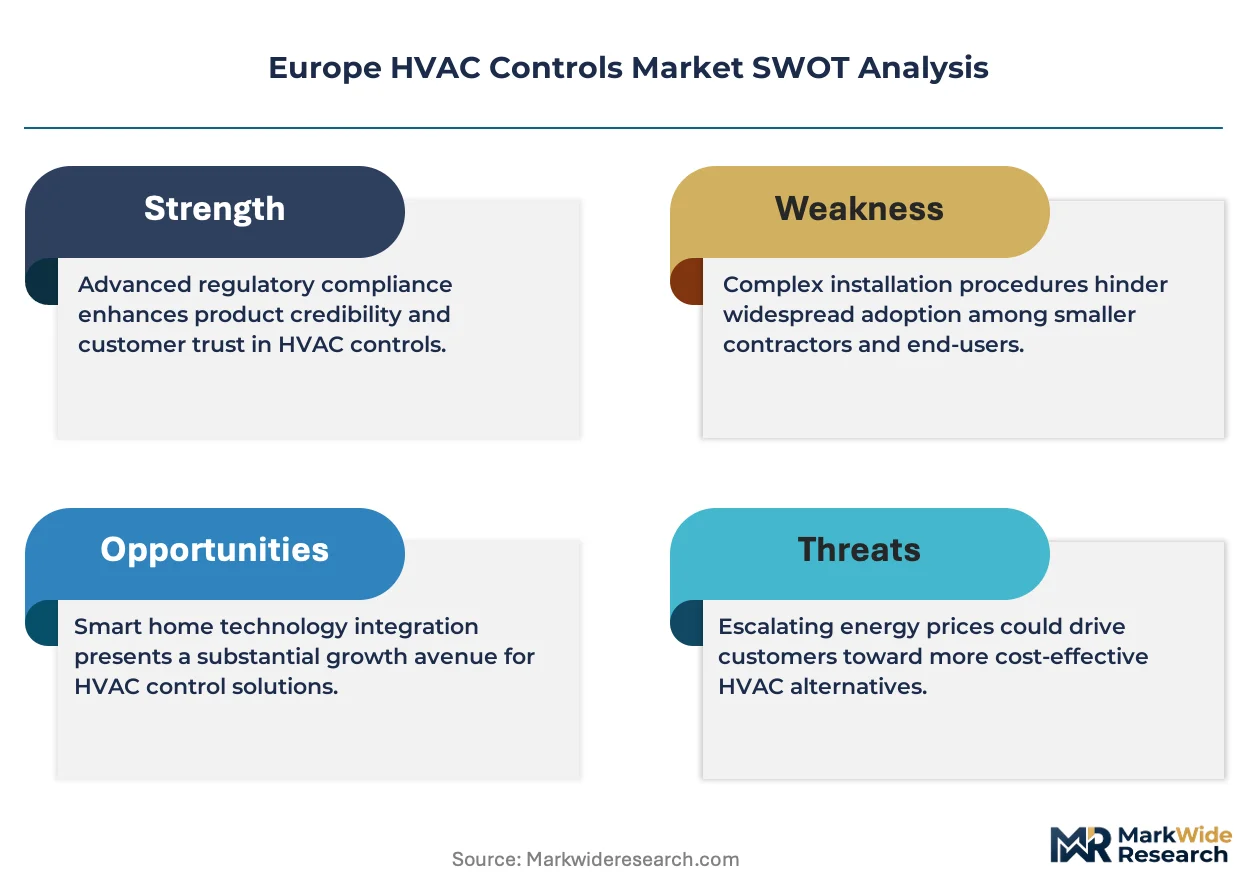
- High Upfront Investment:The significant capital expenditure required to retrofit entire buildings with modern, integrated control systems is a major barrier for many building owners, particularly in the fragmented small-to-medium enterprise sector.
- System Interoperability:A lack of standardization between proprietary communication protocols from different manufacturers creates integration challenges. This can lock customers into a single vendor ecosystem and complicate multi-system management.
- Legacy Building Infrastructure:The architectural and mechanical constraints of older European buildings can make the installation of modern sensors, actuators, and controllers technically complex and expensive, slowing adoption rates.
Strategic Opportunities
- Predictive Maintenance Services:Leveraging AI and machine learning on sensor data offers an opportunity to provide predictive maintenance as a service. This shifts revenue from one-time hardware sales to recurring software and service contracts.
- Eastern Europe Modernization:Countries in Central and Eastern Europe represent an underpenetrated market. As their building codes align with broader EU energy efficiency targets, demand for advanced HVAC controls is set to accelerate.
- Integrated Smart Building Platforms:There is a significant opportunity in converging HVAC controls with lighting, security, and fire safety systems onto a single platform. This provides a holistic view of building performance and unlocks greater energy savings.
Industry Challenges
- Technical Skills Gap:A shortage of technicians and engineers with the expertise to design, install, and manage complex, IP-based building automation systems hampers market growth and project execution across Europe.
- Cybersecurity Vulnerabilities:As HVAC controls become increasingly connected to the internet, they present new attack vectors for cyber threats. Ensuring the security of building management systems is a critical and growing challenge for facility managers.
- Legacy System Integration:Integrating new, open-protocol controls with existing proprietary or analog systems in older buildings is a significant technical hurdle. This complexity can lead to project delays and performance issues.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe HVAC Controls Market |
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $14.05 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Control Type: Thermostats, Programmable Controllers, Sensors, Actuators, Dampers Technology: Wired Controls, Wireless Controls, BACnet, Modbus, LonWorks Application: Commercial Buildings, Industrial Facilities, Public Institutions, Data Centers, Educational Facilities End User: Facility Managers, Building Contractors, Energy Service Companies, System Integrators |
| Companies Covered | Schneider Electric, Fr. Sauter AG, Siemens AG, Regin Controls Sverige AB, PrivaHolding B.V., Honeywell International Inc., Kieback&Peter GmbH & Co. KG, Danfoss AS, Johnson Controls, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe HVAC Controls Market Strategic Shifts & Innovations
The market is transitioning from isolated, mechanical controls to integrated, data-driven ecosystems. This shift prioritizes system intelligence and connectivity over simple component functionality, reshaping how buildings in Europe manage energy and comfort.
AI-powered predictive algorithms analyze sensor data to forecast equipment needs. Facility managers in commercial and industrial settings adopt these systems to preempt failures. This technology is automating fault detection and diagnostic processes, minimizing downtime and optimizing maintenance schedules.
The EU's Energy Performance of Buildings Directive (EPBD) mandates advanced energy monitoring capabilities. This directive requires non-residential buildings to install or upgrade their Building Automation and Control Systems (BACS). The commercial real estate sector, especially in Germany and France, is most impacted, accelerating control system retrofits.
A preference for service-based energy management contracts is emerging over traditional equipment purchases. This model alters the role of distributors, as building owners engage Energy Service Companies (ESCOs) for guaranteed performance outcomes. The trend is most prominent in large commercial buildings across Western Europe seeking long-term operational efficiencies.
Europe HVAC Controls Market Segmentation
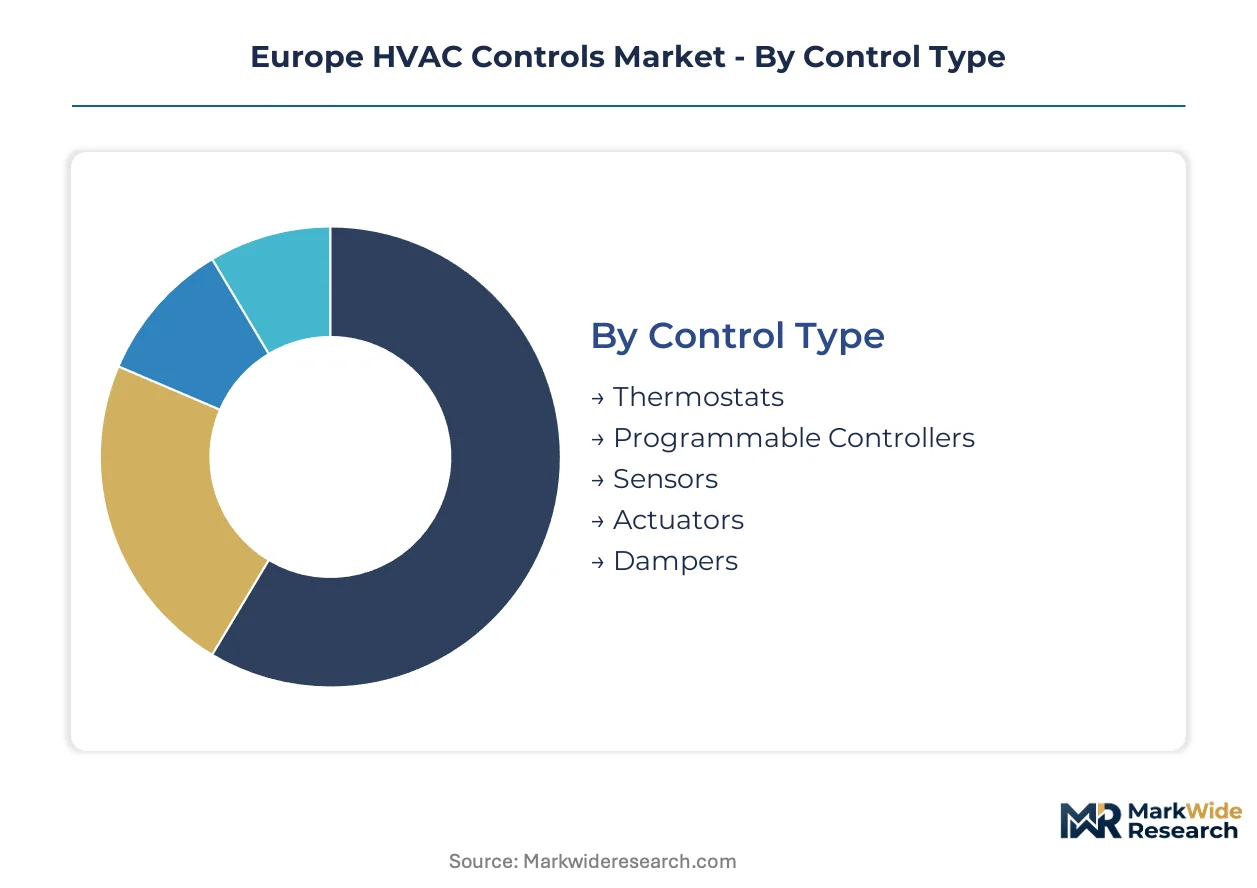
Understanding the segmentation of the European HVAC controls market is essential for identifying specific demand drivers and technological preferences. This detailed breakdown highlights how diverse needs across control types, technologies, applications, and end-users shape market dynamics, particularly in response to stringent energy efficiency mandates and modernization imperatives.
Control Type:
The upgrade cycle for European HVAC systems directly influences the demand for specific control types, as building owners replace outdated components with more energy-efficient and intelligent solutions.
- Sensors:These devices collect real-time data on temperature, humidity, CO2 levels, and occupancy, forming the input layer for intelligent HVAC operation. Demand for granular data collection in commercial and industrial settings across Germany and the UK drives sensor adoption for predictive maintenance.
- Programmable Controllers:These electronic devices execute predefined logic to manage HVAC equipment based on sensor inputs and scheduling. Modernization efforts in older commercial buildings across France and Italy are accelerating the replacement of legacy pneumatic or analog controllers.
- Thermostats:These user interfaces allow occupants or facility managers to set desired temperature points for localized climate control within European office spaces.
- Actuators:These mechanical devices convert electrical or pneumatic signals from controllers into physical movement, regulating dampers and valves in European HVAC systems.
- Dampers:These adjustable plates control airflow within ductwork, crucial for zone-specific climate management and energy efficiency in European public institutions.
Sensors sits at the top of the volume ranking, with Programmable Controllers climbing the fastest.
Technology:
Technology choices for HVAC controls are primarily driven by the need for cost-effective installation and integration capabilities across diverse European building types.
- Wireless Controls:These systems utilize radio frequency communication, eliminating the need for extensive wiring, which simplifies installation in existing European commercial buildings. Retrofit projects throughout the Netherlands and Belgium specifically leverage wireless technology for minimal disruption and faster deployment.
- BACnet:This open communication protocol facilitates interoperability between different manufacturers' HVAC control devices and building management systems. Its widespread adoption in new commercial constructions across Scandinavia ensures seamless integration and data exchange.
- Wired Controls:These traditional systems rely on physical cabling for communication between devices, providing robust and secure connections in critical European industrial facilities.
- Modbus:This serial communication protocol offers a simple and reliable method for connecting industrial electronic devices, common in smaller European industrial automation applications.
- LonWorks:This networking platform provides distributed control capabilities for building automation, often found in older, integrated European building management systems requiring specialized expertise.
Wireless Controls are gaining significant market share, while BACnet solidifies its position as a standard for interoperable systems.
Application:
Regulatory mandates for energy efficiency and carbon reduction significantly influence the deployment of advanced HVAC controls across various application sectors in Europe.
- Commercial Buildings:This segment encompasses offices, retail spaces, and hotels, where occupant comfort and energy optimization are paramount. The EU's EPBD directive directly drives the adoption of sophisticated control systems in commercial properties across Germany and France.
- Data Centers:These facilities require extreme precision in thermal management to maintain optimal operating temperatures for IT equipment and ensure continuous uptime. The proliferation of data centers in FLAP-D hubs demands highly reliable and redundant HVAC control solutions.
- Industrial Facilities:Manufacturing plants and warehouses utilize HVAC controls for process temperature regulation, air quality management, and worker comfort in European industrial zones.
- Public Institutions:Government buildings, hospitals, and libraries implement HVAC controls to manage large, complex environments while meeting public sector energy targets across Europe.
- Educational Facilities:Schools and universities deploy these systems to optimize learning environments and reduce operational costs through efficient energy use across European campuses.
Commercial Buildings attract the largest investment in HVAC control upgrades, with Data Centers demonstrating the most intensive demand for high-performance solutions.
End User:
The value proposition of HVAC controls varies significantly across different end-user segments, each prioritizing distinct benefits like operational efficiency or project management.
- Facility Managers:These professionals oversee the day-to-day operation and maintenance of buildings, directly benefiting from controls that offer granular data, remote access, and predictive insights. European facility managers in large corporate campuses leverage these systems to optimize energy consumption and reduce maintenance costs.
- System Integrators:These specialists design, install, and commission complex building management systems, often combining HVAC controls with other building technologies. Their expertise is crucial for seamless integration in multi-vendor environments across major European urban centers.
- Building Contractors:These firms incorporate HVAC control systems into new construction projects and major renovations, focusing on installation efficiency and compliance with European building codes.
- Energy Service Companies (ESCOs):These organizations deliver guaranteed energy savings through performance-based contracts, utilizing advanced HVAC controls to achieve efficiency targets for their European clients.
Facility Managers exert substantial influence on control system selection, while Energy Service Companies represent a rapidly expanding client base for outcome-based solutions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The European HVAC controls market experiences regulatory-driven shifts, particularly with the EU Green Deal and F-Gas Regulation. These directives compel building owners to upgrade legacy systems, creating a strong pull for intelligent, energy-efficient control solutions. This environment sometimes sees production or technology development migrate to regions with less stringent or different compliance pathways.
Germany
Demand for granular data collection in commercial and industrial settings drives sensor adoption for predictive maintenance. The EU's F-Gas Regulation specifically impacts Germany's commercial and industrial building stock, necessitating system upgrades. Major industrial hubs like North Rhine-Westphalia are experiencing concentrated efforts in modernizing HVAC infrastructure.
France
Modernization efforts in older commercial buildings accelerate the replacement of legacy pneumatic or analog controllers. The EU's Energy Performance of Buildings Directive (EPBD) directly drives the adoption of sophisticated control systems in French commercial properties. Paris and its surrounding Île-de-France region see significant investment in BACS retrofits for large commercial real estate.
United Kingdom
Granular data collection in commercial and industrial settings drives sensor adoption for predictive maintenance. The UK's net-zero targets and building regulations, though no longer directly tied to the EU, align with energy efficiency mandates. London's extensive commercial property market requires advanced controls for both new builds and complex retrofit projects.
Netherlands
Retrofit projects throughout the Netherlands specifically leverage wireless technology for minimal disruption and faster deployment in existing commercial buildings. The Dutch government's energy transition policies encourage smart building technologies to reduce carbon emissions. The Randstad region, encompassing Amsterdam, Rotterdam, and The Hague, is a hotspot for integrated smart building platforms.
Poland
Countries in Central and Eastern Europe represent an underpenetrated market for advanced HVAC controls. As Polish building codes align with broader EU energy efficiency targets, demand for intelligent solutions will accelerate. Warsaw's rapidly developing commercial sector presents a significant opportunity for modern BACS installations.
Europe HVAC Controls Market Key Industry Players
Established producers occupy the standard tier, while emerging entrants pursue integrated smart building platforms and predictive maintenance services. The market structure is tiered, with large conglomerates offering comprehensive solutions and specialized firms focusing on niche technologies like wireless controls. Strategic archetypes include diversified industrial giants, energy management specialists, and pure-play building automation providers. Dominant competitive moves include strategic partnerships for technology integration and portfolio diversification into software-as-a-service offerings.
Among the large, integrated system providers, Siemens AG and Schneider Electric exemplify broad portfolios spanning building management systems and energy management solutions across Europe. These firms leverage their deep integration capabilities to serve commercial and industrial clients, offering solutions that optimize energy use and maintain comfort. Honeywell International Inc. also occupies a significant position, anchoring comprehensive suites of connected equipment and digital services that support smart building initiatives. These companies collectively represent the archetype of extensive integration with existing building infrastructure and a strategic focus on recurring software and service contracts, moving beyond one-time hardware sales towards outcome-based solutions.
| Leading Market Players |
|---|
| Schneider Electric |
| Fr. Sauter AG |
| Siemens AG |
| Regin Controls Sverige AB |
| PrivaHolding B.V. |
| Honeywell International Inc. |
| Kieback&Peter GmbH & Co. KG |
| Danfoss AS |
| Johnson Controls |
| Others |
Cost & Logistics Intelligence
Advanced integrated building automation solutions command premium pricing, reflecting their complex software and service bundles, which contrasts with transactional component sales. This divergence shapes distinct supply chains for high-value systems versus commodity parts across Europe.
Pricing Analysis
Distributor margins for HVAC controls are influenced by product complexity and service bundling. Project-based pricing dominates integrated system installations, while transactional sales characterize component replacements, with subscription models emerging for predictive maintenance services. Price differentiation stems from customization levels for specific building requirements and the inclusion of comprehensive after-sales service packages. Pricing pressure stems from the commoditization of basic control components, making small-to-medium enterprises highly price-sensitive compared to large commercial clients.
Supply Chain Analysis
Microcontroller and specialized sensor supply for advanced HVAC controls draws from East Asian manufacturers and European component specialists. Finished goods production concentrates in Germany for high-end systems and Eastern Europe for assembly of more standard units. The supply chain faces single-source vulnerability for certain proprietary communication modules, impacting system interoperability. Distribution runs through direct sales channels for major commercial and industrial projects, alongside a network of value-added resellers for smaller retrofit installations across Europe.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The European HVAC controls market acts as a regulatory compounder, with the EU Green Deal and F-Gas Regulation mandating system upgrades. These directives create a continuous demand for intelligent, energy-efficient solutions across the continent.
For Market Incumbents:Acquire specialist software firms to deepen vertical integration into building management system platforms. Incumbents must invest heavily in cybersecurity solutions for connected HVAC controls to counter growing cyber threats. Expanding software-as-a-service offerings for predictive maintenance transforms one-time hardware sales into recurring revenue streams, mitigating margin pressure from commoditized components.
For New Entrants and Emerging Players:Capture market share in Central and Eastern European commercial buildings by offering cost-effective wireless retrofit solutions. Emerging players can target the integration of HVAC controls with broader smart building platforms, providing holistic energy management. Focusing on open communication protocols facilitates easier adoption and avoids vendor lock-in for facility managers.
For Investors and Strategic Acquirers:Consolidation pressure builds where specialized technology providers offer distinct competitive advantages in predictive analytics. The market presents strong long-term viability over the next decade, driven by ongoing decarbonization mandates. Investors should target mid-sized specialists in AI-powered analytics or robust wireless control technology. The signal to watch is the accelerated alignment of Eastern European building codes with broader EU energy efficiency targets.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in AI-powered predictive maintenance | Automates fault detection and optimizes maintenance schedules for European facility managers. |
| Expand wireless control product lines | Facilitates cost-effective retrofits in Europe's extensive older commercial building stock. |
| Develop integrated smart building platforms | Provides holistic energy management by converging HVAC with lighting and security systems. |
| Pursue strategic partnerships for cybersecurity | Strengthens defenses against cyber threats targeting connected building management systems. |
| Target Eastern European market expansion | Addresses underpenetrated regions aligning with EU energy efficiency mandates. |
Research Approach
Bottom-up commercial building and data center modeling reconciled against top-down component supplier tracking forms the analytical core of this study. Primary interviews with facility managers, system integrators, HVAC engineers, and energy service company executives provided critical qualitative insights. Secondary validation drew from EU Commission reports, national energy agency statistics, and building automation industry association publications. This approach ensured robust triangulation of market data.
An input-output matrix framework underpinned the quantitative market projections across the analysis window. Segmentation dimensions modeled include control type, technology, application, end-user, and regional regulatory impact. Compound annual growth rates were derived from historical trends and projected regulatory impacts from the EU Green Deal. Key forecast inputs included F-Gas compliance deadlines and European data center expansion rates.
Geopolitical instability, supply chain disruptions, and unforeseen technological breakthroughs are the dominant revision risks impacting market forecasts. These projections reflect assumptions regarding regulatory enforcement and economic conditions. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Automation Systems
China Revolving Doors Market
Building Automation Systems
Automated Daylight Harvesting Systems Market
Building Automation Systems
Zero Energy Buildings Market
Building Automation Systems
Building-To-Grid Technology Market
Building Automation Systems
Smart Window Film Market
Building Automation Systems
Asia-Pacific Building Automation System Market
Building Automation Systems
Global Enterprise Building Solutions Market
Building Automation Systems
Europe Building Automation Systems Market
Building Automation Systems
Dumbwaiter Lifts Market
Building Automation Systems
Smart Building Solutions Market
Building Automation Systems
Intelligent Building Automation Technologies Market
Building Automation Systems
Elevator Modernization Market
Building Automation Systems
Global Operating Equipment Room Market
Building Automation Systems
Integrated Building Management Systems Market
Building Automation Systems
Building Automation and Control System Market
Building Automation Systems
Building Automation System Market