
 Building Analytics Market | 2026-2036
Building Analytics Market Size, Share, and Industry Trends Forecast 2026-2036
Building Analytics Market Intelligence
North American systems integrators and European engineering firms is rebalancing capacity toward software-heavy service models. Schneider Electric leverages its EcoStruxure platform to anchor building automation-to-analytics pipelines across multiple continents. Johnson Controls sustains R&D intensity in predictive HVAC diagnostics through its OpenBlue digital suite. Honeywell International competes on channel control, embedding analytics within its Forge platform for enterprise facility managers.
Building analytics encompasses the collection, processing, and visualization of operational data from building systems—temperature setpoints, airflow rates, occupancy counts, and equipment runtimes—to optimize energy consumption, indoor environmental quality, and asset longevity. Cloud-based platforms now dominate new deployments, though on-premise architectures persist in financial services and defense facilities where data sovereignty governs procurement. Energy Management leads product-type revenue due to utility rebate structures and mandatory benchmarking laws, while Edge Computing represents the fastest-growing technology segment as latency-sensitive applications like fault detection expand. Commercial Buildings anchor end-user demand, with Energy Optimization and Performance Monitoring capturing the largest application share.
EPA Energy Star certification requirements, the EU Energy Performance of Buildings Directive, and China's GB standards for building energy consumption together elevate baseline analytics adoption across three continents. Bodies including the US Department of Energy, the European Committee for Standardization, and China's Ministry of Housing and Urban-Rural Development continuously tighten reporting granularity, forcing platform upgrades. Stakeholders must monitor which jurisdictions next mandate continuous commissioning versus static annual audits, as this distinction determines subscription pricing power and integration depth.
Market Dynamics
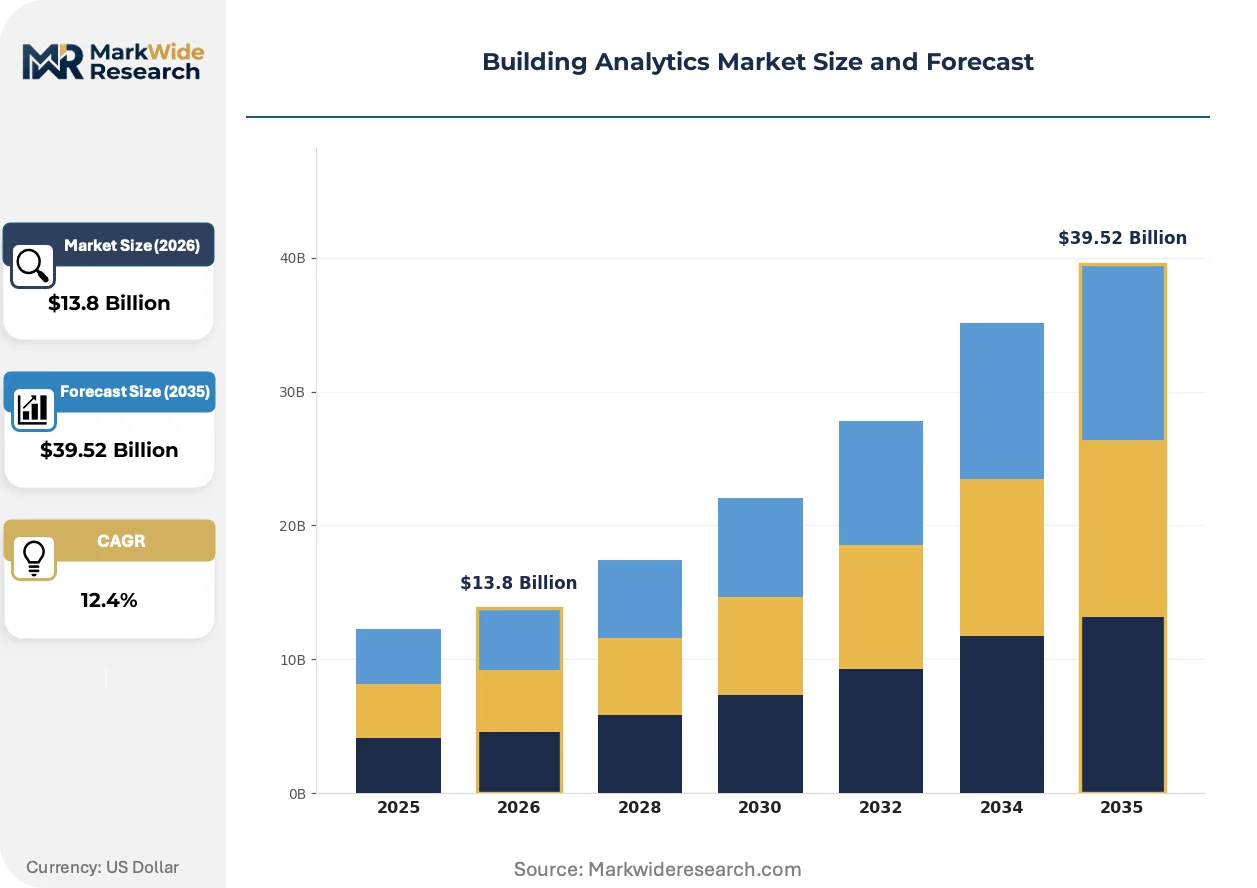
The convergence of mandatory benchmarking laws and cloud platform maturation is compressing deployment cycles for building analytics, forcing vendors to restructure service delivery around continuous commissioning rather than episodic audits.
Growth Catalysts
- EU Energy Performance of Buildings Directive:The directive's escalating efficiency thresholds compel commercial landlords across Germany, France, and Italy to install real-time monitoring systems. Retrofit deadlines in 2030 and 2033 are pulling forward platform procurement.
- Edge computing architectures:Latency-sensitive fault detection applications in healthcare and data center verticals are accelerating hardware deployment at the building level. On-premise processing satisfies data sovereignty requirements in financial services.
- Utility rebate structures:Demand response programs in California, New York, and Texas directly subsidize analytics software licensing. These incentives lower effective customer acquisition costs for platform vendors.
Market Restraints
- Semiconductor supply concentration:Edge device production depends on fabrication capacity concentrated in Taiwan and South Korea. Geopolitical friction elevates lead times for IoT sensors and gateway hardware.
- Technical debt in building automation:BACnet and Modbus protocol fragmentation across installed HVAC systems complicates data normalization. Integration engineering consumes 30-40% of project budgets.
- Data sovereignty regulations:China's GB standards and the EU's GDPR impose conflicting data localization requirements. Multi-national facility operators face architectural duplication costs.
Strategic Opportunities
- India's Smart Cities Mission:Municipal building portfolios in Mumbai, Delhi, and Bangalore remain underpenetrated by analytics platforms. Central government efficiency mandates create procurement windows.
- Digital twin convergence:Integration of BIM models with live operational data enables predictive maintenance at the component level. Engineering firms in Singapore and Dubai are piloting unified workflows.
- Performance contracting channels:Energy Service Companies in the United States are embedding analytics as a bundled service. This shifts customer relationships from capital expenditure to operational expenditure models.
Industry Challenges
- Systems integration talent scarcity:Proficiency in both HVAC engineering and data science remains rare. Salaries for commissioning engineers with Python and SQL capabilities have escalated 25% annually.
- Cybersecurity certification timelines:IEC 62443 compliance for building automation networks requires 12-18 month validation cycles. Product roadmaps must freeze specifications early, limiting feature responsiveness.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Building Analytics Market |
| Market Size in 2026 | $13.8 Billion |
| Market Size in 2035 | $39.52 Billion |
| CAGR (2026 – 2036) | 12.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Energy Management, HVAC Controls, Lighting Management, Occupancy Sensors End User: Commercial Buildings, Residential Buildings, Industrial Facilities, Government Buildings Technology: Cloud-Based, On-Premise, Edge Computing, Data Analytics Application: Asset Management, Energy Optimization, Performance Monitoring, Space Management |
| Companies Covered | Schneider Electric, Honeywell International, Johnson Controls, Siemens, IBM Corporation, General Electric Company, ENGIE Insight Services, Lucid, CopperTree Analytics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Building Analytics Market Strategic Shifts & Innovations
Building analytics is pivoting from descriptive dashboards toward autonomous control systems, with artificial intelligence and distributed computing architectures rewriting competitive requirements for platform vendors.
Edge AI inference engines are decentralizing decision-making authority from cloud data centers to local building controllers. Hospital and laboratory operators in Switzerland and the Netherlands are deploying these systems for sub-second environmental adjustments. This architecture is decentralizing vendor power away from hyperscale cloud providers toward specialized edge hardware manufacturers.
The EU F-Gas Regulation's phasedown of hydrofluorocarbon refrigerants is forcing refrigerant leak detection into standard analytics packages. Equipment manufacturers must now integrate continuous monitoring to maintain warranty coverage. Commercial refrigeration in Germany and cold storage logistics in Spain are absorbing compliance costs fastest, driving demand for multi-sensor fusion platforms.
Facility managers are unbundling software subscriptions from hardware procurement, separating analytics licensing from BMS installation. This purchasing pattern disrupts traditional channel relationships where controls distributors bundled both. The split is most visible in United States K-12 education and municipal government verticals, where public procurement rules favor SaaS separation.
Building Analytics Market Segmentation
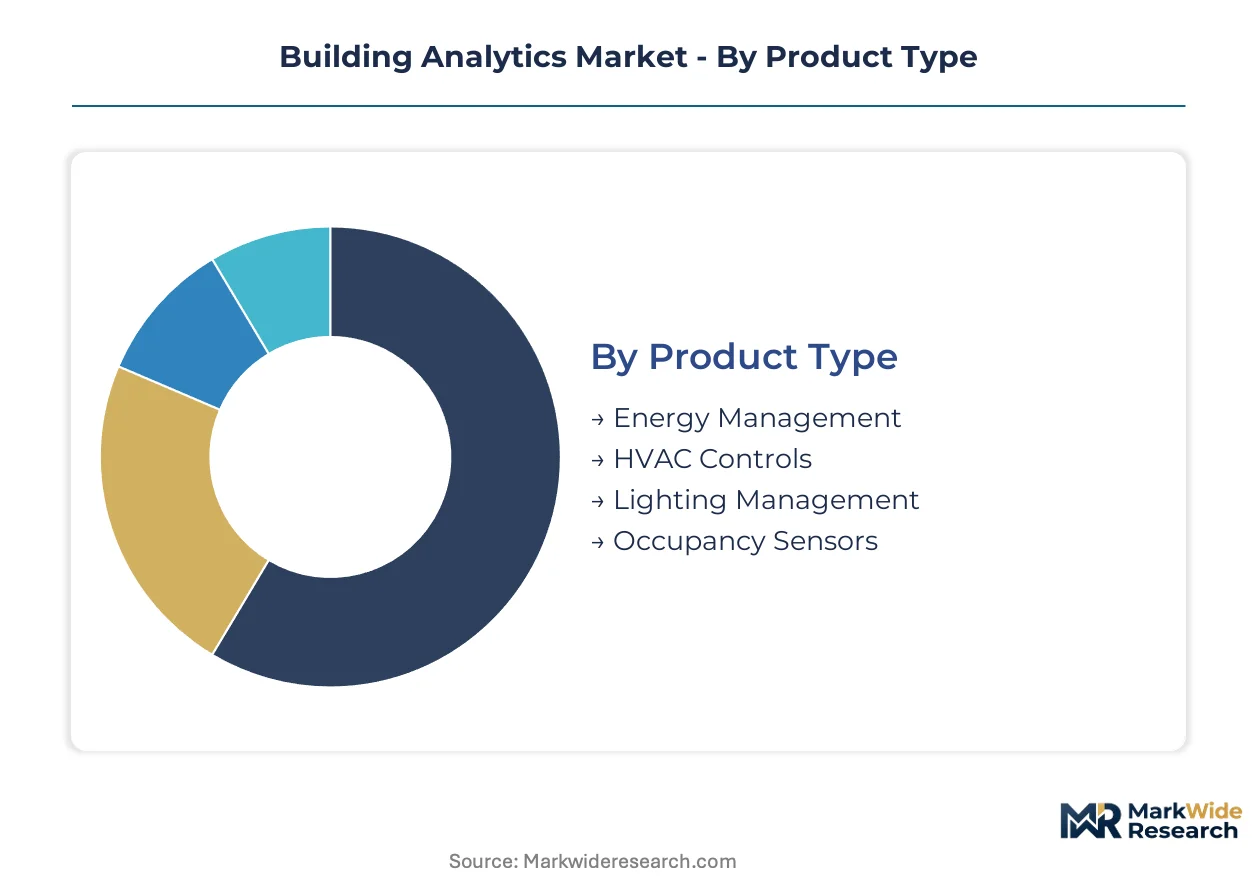
Building analytics platforms fragment across four intersecting dimensions that determine integration architecture and procurement patterns. Product type governs whether systems deploy as standalone modules or embed within broader automation stacks. Technology choice shapes latency, sovereignty, and subscription economics. End user verticals impose distinct compliance and operational requirements. Application focus determines whether vendors compete on energy savings, asset longevity, or spatial efficiency.
Product Type:
Standalone deployments dominate retrofit scenarios where legacy BMS infrastructure remains operational; embedded systems prevail in new construction with unified specification cycles.
- Energy Management:Comprehensive platforms that aggregate utility interval data, submetering feeds, and demand response signals into unified dashboards. Demand concentrates in United States commercial office towers and German manufacturing facilities where EU Energy Performance of Buildings Directive mandates drive procurement. Utility rebate structures in California and Texas directly subsidize licensing costs.
- HVAC Controls:Advanced algorithms that optimize chiller staging, air handling unit sequencing, and variable air volume terminal responses. Healthcare campuses in Switzerland and data center operators in Singapore prioritize these systems for their sub-second environmental stability requirements. BACnet protocol fragmentation complicates integration engineering.
- Lighting Management:Daylight harvesting and occupancy-dimming circuits that reduce electrical load through automated luminaire control. These systems deploy widely in United States K-12 education facilities.
- Occupancy Sensors:PIR, ultrasonic, and computer vision devices that feed real-time headcount data to space optimization algorithms. Corporate headquarters in London and Tokyo deploy these for hybrid work transition planning.
Volume placements concentrate in Energy Management; the faster expansion belongs to HVAC Controls.
End User:
Procurement authority and budget cycles vary sharply across verticals, with commercial real estate favoring operational expenditure models and government buildings remaining tied to capital appropriations.
- Commercial Buildings:Office towers, retail centers, and hospitality properties where asset managers prioritize tenant satisfaction metrics alongside utility cost reduction. United States Class A office portfolios in New York and Chicago lead deployment intensity. EPA Energy Star certification requirements elevate baseline adoption.
- Residential Buildings:Multifamily apartments and condominium towers where property technology platforms integrate analytics with access control and resident apps. China's GB standards for building energy consumption accelerate smart home convergence in Shanghai and Shenzhen.
- Industrial Facilities:Heavy manufacturing and process plants where predictive maintenance overlays extend equipment lifecycles. German automotive plants and South Korean semiconductor fabs drive demand.
- Government Buildings:Municipal offices, courthouses, and military installations where data sovereignty requirements favor on-premise architectures. India's Smart Cities Mission creates procurement windows in Mumbai and Delhi.
Commercial Buildings anchor current revenue; Industrial Facilities are climbing the fastest as predictive maintenance capabilities mature.
Technology:
Deployment architecture determines latency characteristics, recurring revenue potential, and compliance posture across regulated verticals.
- Cloud-Based:Multi-tenant SaaS platforms that centralize data processing and algorithm training at hyperscale facilities. These systems dominate new United States commercial deployments where internet connectivity is reliable and IT security teams accept external hosting.
- On-Premise:Single-tenant installations within facility data centers that satisfy data localization mandates. Financial services in Frankfurt and defense installations in Virginia require these architectures.
- Edge Computing:Distributed inference engines that process sensor streams locally before transmitting aggregated insights. Healthcare laboratories in the Netherlands and cold storage logistics in Spain adopt these for sub-second response requirements.
- Data Analytics:Pure software layers that normalize and visualize operational data without direct control authority. Engineering consultancies in Singapore bundle these with commissioning services.
Cloud-Based systems capture the largest current deployment base; Edge Computing shows the steepest expansion trajectory as latency-sensitive applications multiply.
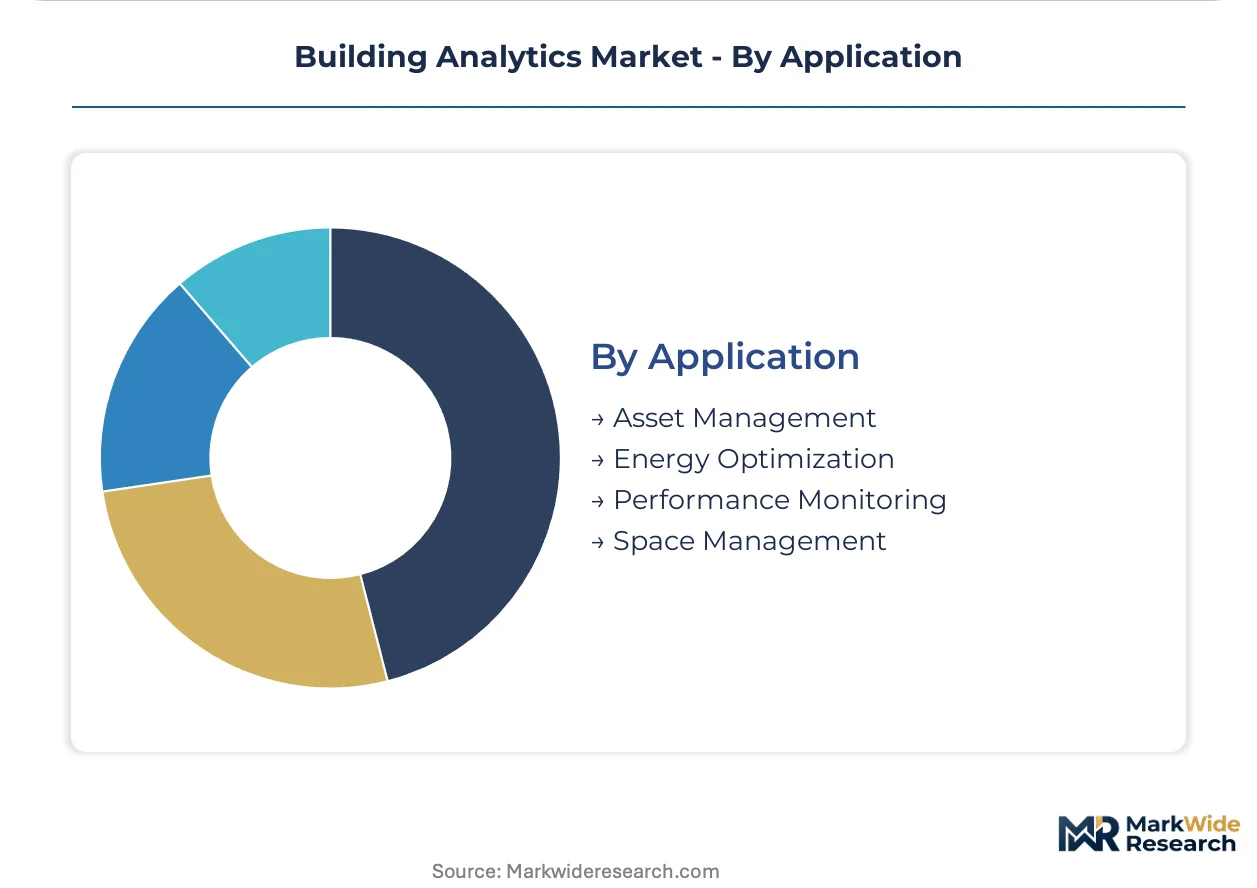
Application:
Use case prioritization determines feature roadmaps and pricing power, with energy-focused applications commanding mature markets and space optimization emerging as a differentiation vector.
- Energy Optimization:Algorithms that reduce consumption through setpoint adjustment, equipment scheduling, and demand peak shaving. Mandatory benchmarking laws in France and Italy pull forward platform procurement ahead of 2030 retrofit deadlines.
- Performance Monitoring:Continuous commissioning workflows that flag drift from design specifications and trigger maintenance interventions. United States hospital systems deploy these to maintain Joint Commission accreditation.
- Asset Management:Equipment lifecycle tracking that integrates runtime data with manufacturer warranty conditions and replacement forecasting. EU F-Gas Regulation refrigerant leak detection requirements embed these capabilities in commercial refrigeration.
- Space Management:Occupancy pattern analysis that informs lease restructuring, hot-desking ratios, and cleaning schedules. Hybrid work transition in London and New York financial services drives recent demand.
Energy Optimization maintains the deepest market penetration; Space Management is gaining share fastest as corporate real estate reconfigures for flexible work.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German engineering standards and California energy codes anchor the geographic spread of building analytics procurement, with data sovereignty requirements and utility rebate structures creating divergent deployment patterns across national markets.
United States
EPA Energy Star certification mandates and California Title 24 efficiency standards drive platform adoption across commercial office portfolios. Utility demand response programs in Texas and New York directly subsidize analytics licensing costs. Class A office towers in Chicago and New York Metro deploy continuous commissioning systems at the highest intensity.
Germany
The EU Energy Performance of Buildings Directive compels commercial landlords to install real-time monitoring ahead of 2030 retrofit deadlines. The F-Gas Regulation's refrigerant phasedown embeds leak detection in standard analytics packages. Industrial facilities in Bavaria and Baden-Württemberg lead predictive maintenance deployments for HVAC assets.
China
GB standards for building energy consumption accelerate smart building convergence in Tier-1 cities. The Ministry of Housing and Urban-Rural Development mandates granular consumption reporting for public structures. Shanghai and Shenzhen municipal portfolios represent the largest concentrated procurement for cloud-based energy management platforms.
India
The Smart Cities Mission creates procurement windows for municipal building analytics across underpenetrated portfolios. Central government efficiency targets for government buildings favor on-premise architectures for data localization. Mumbai and Delhi metro corporations issue bundled tenders combining BMS installation with analytics subscriptions.
Switzerland
Healthcare and laboratory operators prioritize sub-second environmental stability through edge computing deployments. Swissmedic-aligned facilities require IEC 62443 cybersecurity certification for building automation networks. Hospital campuses in Zurich and Geneva pioneer autonomous control systems for critical environmental zones.
Building Analytics Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue edge-native architectures and vertical-specific compliance modules. The vendor base stratifies across three tiers: diversified industrial conglomerates with automation heritage, pure-play software vendors with SaaS delivery models, and regional systems integrators with commissioning expertise. Competitive positioning depends on channel control depth and protocol normalization capabilities. Consolidation activity concentrates in edge hardware manufacturers and cybersecurity certification services.
Within the diversified industrial tier, Schneider Electric, Honeywell International, and Johnson Controls occupy positions defined by building automation-to-analytics pipeline integration. Schneider Electric leverages its French industrial heritage across multiple continents through platform standardization. Honeywell International represents the channel-control archetype with embedded analytics for enterprise facility managers. Johnson Controls exemplifies predictive diagnostics specialization through digital suite investments. These three conglomerates anchor competitive dynamics by combining hardware distribution networks with recurring software revenue models.
| Leading Market Players |
|---|
| Schneider Electric |
| Honeywell International |
| Johnson Controls |
| Siemens |
| IBM Corporation |
| General Electric Company |
| ENGIE Insight Services |
| Lucid |
| CopperTree Analytics |
| Others |
Cost & Logistics Intelligence
Utility demand response program requirements in California, Texas, and New York are forcing platform vendors to unbundle software licensing from hardware procurement, compressing margins on standalone analytics modules while elevating subscription pricing power for continuous commissioning services.
Pricing Analysis
Warranty coverage bundled with refrigerant leak detection capabilities now separates premium analytics tiers from standard offerings under EU F-Gas Regulation compliance mandates. Pricing stratifies across premium, standard, and economy tiers based on IEC 62443 cybersecurity certification status and predictive maintenance algorithm sophistication. Cost compression in the standard tier is intensifying because BACnet protocol normalization engineering consumes disproportionate implementation budgets. Municipal government verticals exhibit highest price sensitivity due to capital appropriation constraints, while healthcare campuses in Switzerland show lowest sensitivity given Swissmedic-aligned operational requirements.
Supply Chain Analysis
Edge AI inference chip supply rests on fabrication capacity concentrated in Taiwan and South Korea, with sensor gateway assembly anchored in China and Vietnam. Critical inputs include MEMS occupancy sensors, LoRaWAN communication modules, and industrial-grade solid-state storage. Single-source vulnerability around Taiwan semiconductor foundries elevates procurement risk for latency-sensitive healthcare deployments. Distribution runs through building automation distributors and systems integrators, though direct SaaS procurement is displacing traditional channel relationships in United States K-12 education.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around platform vendors with integrated automation-to-analytics pipelines, as protocol fragmentation and certification timelines force smaller pure-play software vendors toward acquisition or exit.
For Market Incumbents: Deploy predictive HVAC diagnostics R&D intensity to defend against edge-native entrants targeting healthcare and laboratory verticals. Acquire specialized cybersecurity certification services to compress IEC 62443 validation cycles. Channel control through embedded Forge-style platform architectures protects enterprise facility manager relationships from SaaS unbundling trends.
For New Entrants and Emerging Players: Energy Service Companies in the United States represent the most accessible channel partners for operational expenditure model penetration. Target India's Smart Cities Mission municipal portfolios in Mumbai and Delhi, where bundled BMS-analytics tenders remain underpenetrated by established global vendors. Lead with digital twin convergence pilots in Singapore and Dubai to differentiate from descriptive dashboard incumbents.
For Investors and Strategic Acquirers: The window for entry favors edge hardware manufacturers with healthcare vertical certifications. Five-to-ten year viability hinges on cloud-to-edge architectural transition completion. Acquisition targets should demonstrate BACnet/Modbus protocol normalization IP and recurring revenue concentration above project-based implementation. Watch for continuous commissioning mandate expansions beyond Germany and France as the inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unifies building automation and analytics pipelines for Schneider Electric-style continental scale. |
| Acquisition of Specialist Firm | Compresses IEC 62443 certification timelines for healthcare and defense vertical entry. |
| Geographic Expansion | Captures India's Smart Cities Mission procurement windows in underpenetrated municipal portfolios. |
| Product Launch | Deploys edge AI inference engines for sub-second environmental control in Swissmedic-aligned facilities. |
| Strategic Partnership | Embeds analytics within Energy Service Company performance contracting channels across Texas and California. |
Research Approach
SEC 10-K filings, utility demand response program disclosures, and EU Energy Performance of Buildings Directive regulatory filings formed the secondary backbone for market sizing validation. Primary interviews with building automation systems integrators, facility management executives at Class A office portfolios, HVAC commissioning engineers, and municipal procurement officers in Mumbai and Delhi combined with secondary triangulation. Bottom-up segment modeling across product type, technology architecture, end-user vertical, and application use case was cross-validated against top-down macroeconomic indicators.
Bottom-up deployment modeling tracked cloud-based, on-premise, and edge computing architecture adoption patterns across the projection horizon. Segmentation dimensions included energy management versus HVAC controls product types, commercial versus industrial end-user verticals, and energy optimization versus space management applications. CAGRs were derived from installed base growth rates and replacement cycle acceleration under mandatory benchmarking laws. Forecast inputs incorporated utility rebate structure changes and EU F-Gas Regulation compliance cost absorption curves.
Caveats apply where semiconductor supply concentration disruptions or cybersecurity certification timeline extensions could materially shift the outlook. Forecasts reflect assumptions around continuous commissioning mandate geographic expansion and cloud-to-edge architectural transition velocity. A small set of named triggers warrants ongoing watch: Taiwan foundry capacity allocation, BACnet protocol standardization progress, and India's Smart Cities Mission tender issuance cadence.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Automation Systems
Global Enterprise Building Solutions Market
Building Automation Systems
Electrochromic Glass Market
Building Automation Systems
Smart Passenger Elevators Market
Building Automation Systems
Global Nordic Building Automation and Control Market
Building Automation Systems
Global Building Information Modeling (BIM) Market
Building Automation Systems
United States Smart Windows Market
Building Automation Systems
Underfloor Heating Actuator Market
Building Automation Systems
Building Information Management System Market
Building Automation Systems
Zero Energy Buildings Market
Building Automation Systems
Intelligent Building Automation Technologies Market
Building Automation Systems
Tunnel Automation Market
Building Automation Systems
Building Management System Market
Building Automation Systems
Flushing Systems Market
Building Automation Systems
LAMEA Building Automation System Market
Building Automation Systems
Global Platform Screen Doors for Subway Lines Market
Building Automation Systems
Building Automation and Control System Market