
 Smart Building Solutions Market | 2026-2036
Smart Building Solutions Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Building Solutions Market Outlook
Singapore is narrowing its smart building deployment gap through government-backed district cooling and digital twin pilots. Johnson Controls leverages its Metasys platform to dominate integrated HVAC and security management across Asia-Pacific commercial towers. Schneider Electric anchors its position with EcoStruxure architecture, extending edge-to-cloud control over energy distribution and power quality. Siemens competes through Desigo CC, specializing in open-protocol automation that interoperates across multi-vendor sensor networks.
Smart building solutions encompass networked hardware and software systems that monitor, automate, and optimize building operations through real-time data exchange, typically operating across BACnet, Modbus, or LonWorks protocols with sub-second response thresholds for critical environmental controls. Their primary purpose is to reduce energy consumption, extend equipment life cycles, and ensure occupant safety and comfort through centralized command interfaces. Energy Management applications currently capture the deepest margin pools as utility tariffs rise and carbon accounting tightens, while Security Systems integration grows fastest through AI-enhanced video analytics and biometric access convergence. Cloud-Based deployment leads in new construction, though Hybrid architectures gain traction among owners seeking local data sovereignty with remote analytics capability.
The EU Energy Performance of Buildings Directive and the US EPA ENERGY STAR certification program shape product roadmaps by mandating measurable efficiency thresholds and disclosed performance benchmarking. China's MIIT dual carbon goals and GB standards for intelligent building design further constrain market access for non-compliant foreign suppliers. Stakeholders must monitor regulatory divergence between jurisdictions to avoid certification fragmentation that inflates R&D overhead and delays deployment timelines.
Market Dynamics
The EU Energy Performance of Buildings Directive is compressing deployment timelines across commercial real estate portfolios, forcing asset owners to accelerate retrofit investments ahead of mandatory disclosure deadlines.
Growth Catalysts
- EU EPBD mandates:Member states must achieve zero-emission building stock by 2050, triggering wave procurement of integrated energy management platforms.
- Corporate net-zero commitments:Multinational tenants now require LEED Platinum or BREEAM Outstanding certification as lease preconditions, pulling building automation upgrades forward.
- Heat pump electrification:Building operators are replacing gas-fired boilers with variable refrigerant flow systems that demand native digital controls.
Market Restraints
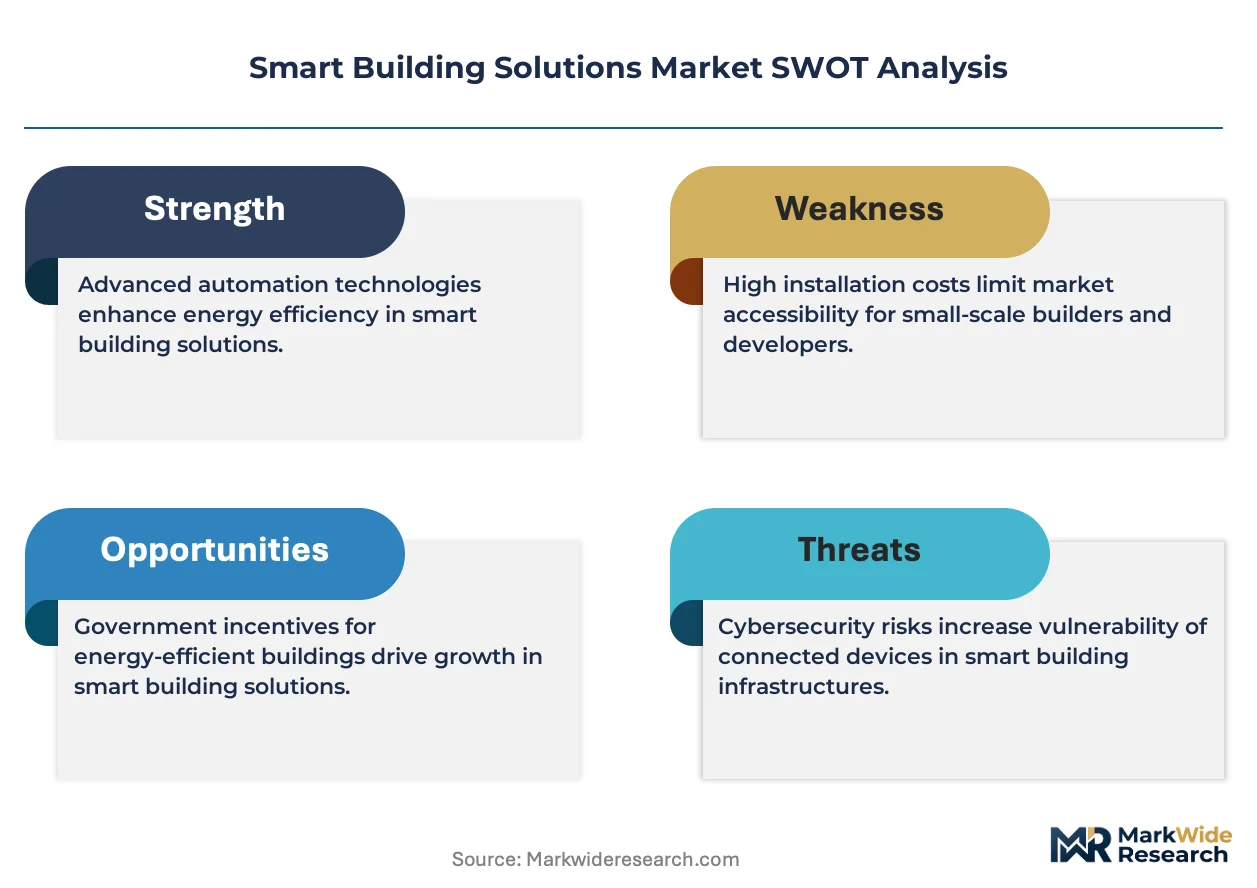
- Semiconductor supply concentration:Edge controller and sensor chip fabrication concentrates in Taiwan and South Korea, exposing project timelines to geopolitical disruption.
- Copper and rare earth input costs:Power distribution components and permanent magnet motors face volatile commodity pricing that erodes fixed-price contract margins.
- Cybersecurity compliance fragmentation:Divergent national critical infrastructure standards between Germany's BSI, France's ANSSI, and US NIST frameworks inflate certification overhead.
Strategic Opportunities
- India's Smart Cities Mission:Tier-2 municipal governments seek district-level building automation for new commercial zones in Pune, Ahmedabad, and Kochi.
- Digital twin convergence:Integration of BIM 3D modeling with live IoT telemetry creates predictive maintenance revenue streams beyond hardware sales.
- US IRA commercial efficiency tax credits:The Inflation Reduction Act's 179D deduction structure now covers up to five dollars per square foot for qualifying smart building retrofits.
Industry Challenges
- OT-IT skill convergence:Facilities teams lack cybersecurity and cloud architecture expertise to manage hybrid edge-cloud deployments.
- Multi-protocol integration complexity:BACnet, Modbus, and proprietary legacy systems require custom middleware that extends commissioning timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Building Solutions Market |
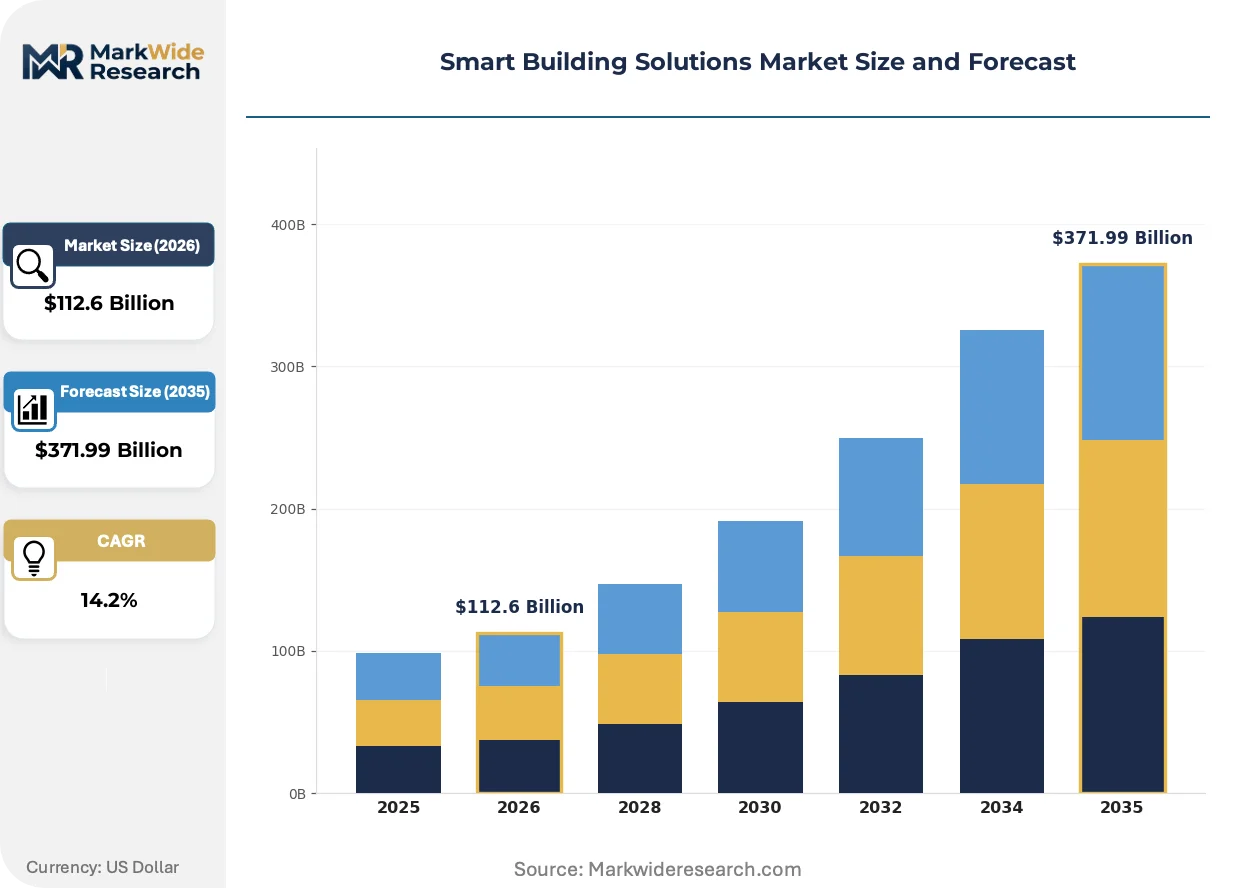
| Market Size in 2026 | $112.6 Billion |
| Market Size in 2035 | $371.99 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: IoT, AI, Automation, Sensors Application: Energy Management, Security Systems, HVAC Control, Lighting Control End User: Commercial Buildings, Residential Spaces, Industrial Facilities, Educational Institutions Deployment: Cloud-Based, On-Premises, Hybrid, Edge Computing |
| Companies Covered | Johnson Controls, Schneider Electric, Honeywell International, Siemens, Cisco Systems, ABB, Hitachi, IBM, Bosch, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Building Solutions Market Strategic Shifts
Digital infrastructure is virtualizing physical building operations, compressing the boundary between automation hardware and software-defined control planes.
Digital twin platforms are virtualizing building performance simulation through real-time sensor fusion and physics-based modeling. Large commercial developers in Singapore and the UAE are deploying these systems during pre-construction to optimize HVAC sizing and reduce change orders. This virtualization is compressing capital planning cycles and enabling outcome-based energy performance guarantees.
The EU AI Act's risk classification framework is reshaping procurement criteria for automated building systems. High-risk applications including biometric access control and predictive fire safety systems now require conformity assessments and algorithmic transparency documentation. German and Dutch property managers are prioritizing vendors with pre-certified AI components to avoid deployment delays.
Facility management outsourcing is consolidating around integrated service contracts that bundle hardware, software, and energy optimization. European REITs and US university endowments are replacing fragmented vendor relationships with single-accountability partners. This consolidation is most visible in London and New York, where trophy assets now specify decade-long performance contracts with guaranteed efficiency outcomes.
Smart Building Solutions Market Segmentation
Smart building solutions fragment across technology stacks, operational domains, and infrastructure maturity levels. Procurement patterns diverge sharply between new construction and retrofit contexts, while regulatory pressure reshapes priority rankings across application areas.
Technology:
The use-case spectrum spans sensing infrastructure through autonomous decision systems, with integration complexity rising at each layer.
- IoT:Networked sensor arrays and edge gateways form the foundational connectivity layer, transmitting environmental and occupancy data over low-power wireless protocols. Demand concentrates in Germany's commercial retrofit programs, where the EU EPBD mandates granular energy monitoring as a compliance precondition.
- AI:Machine learning models optimize HVAC scheduling, predict equipment failures, and automate anomaly detection in security feeds. Singapore's district cooling pilots and UAE commercial towers are deploying these systems for outcome-based energy guarantees.
- Automation:Rule-based control systems execute pre-programmed responses to sensor triggers across lighting, climate, and access domains.
- Sensors:Temperature, occupancy, air quality, and power metering devices provide the raw data stream for upstream analytics platforms.
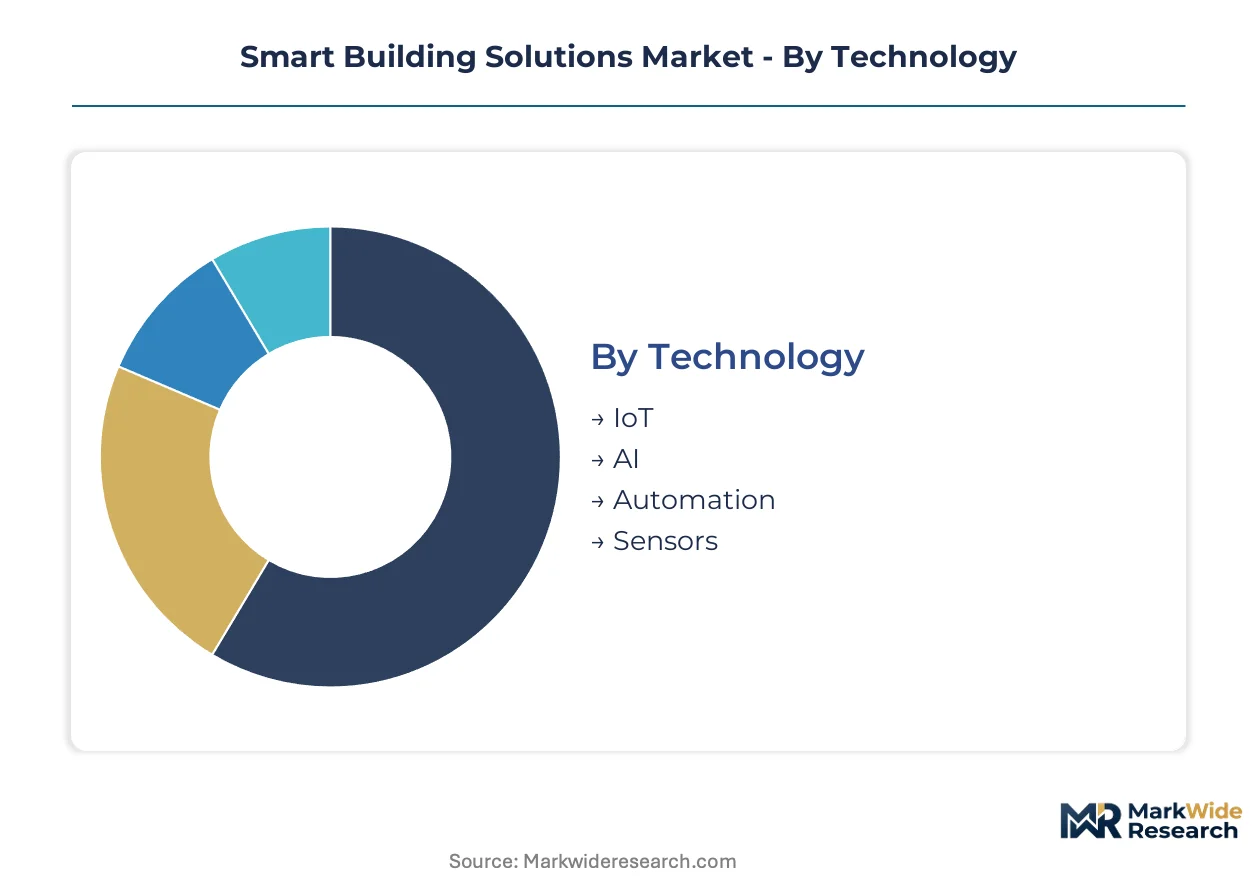
The dominant share belongs to IoT infrastructure, while AI is closing the gap fastest as performance contracting models mature.
Application:
Cost tier segmentation separates compliance-driven deployments from premium performance optimization.
- Energy Management:Utility-grade metering, demand response interfaces, and carbon accounting dashboards track consumption patterns against regulatory baselines. Frankfurt and Munich's large-scale retrofit programs are accelerating procurement of integrated platforms that consolidate multi-site portfolios under single reporting structures.
- Security Systems:AI-enhanced video analytics, biometric access control, and integrated fire safety command centers converge physical and cyber protection. The EU AI Act's high-risk classification framework is forcing algorithmic transparency documentation for biometric applications in German and Dutch commercial properties.
- HVAC Control:Variable refrigerant flow systems and heat pump electrification demand native digital controls that replace legacy pneumatic infrastructure.
- Lighting Control:Daylight harvesting and occupancy-based dimming systems reduce electrical load in high-density commercial floors.
Energy Management commands the deepest margin pools, with Security Systems expanding most quickly through AI-video convergence.
End User:
Volume concentration tracks construction cycle timing and regulatory enforcement intensity across building typologies.
- Commercial Buildings:Corporate office complexes and trophy assets specify decade-long performance contracts with guaranteed efficiency outcomes. London and New York REITs are consolidating fragmented vendor relationships around single-accountability partners.
- Residential Spaces:Multi-family developers integrate basic automation during pre-construction, with premium towers adding predictive maintenance layers.
- Industrial Facilities:Manufacturing plants deploy environmental monitoring for process control and worker safety compliance.
- Educational Institutions:US university endowments bundle hardware, software, and optimization services under integrated facility management contracts.
Commercial Buildings anchor procurement volume, while Educational Institutions are gaining share fastest through endowment-driven sustainability mandates.
Deployment:
Customer type and data sovereignty requirements determine architecture selection between centralized and distributed processing models.
- Cloud-Based:Fully hosted platforms dominate new construction, offering scalable analytics without on-site infrastructure investment.
- On-Premises:Air-gapped systems serve critical infrastructure and defense-adjacent facilities with strict data localization requirements.
- Hybrid:Local edge processing with remote analytics capability gains traction among owners seeking operational continuity during connectivity outages. European operators prioritize this architecture to satisfy GDPR data residency constraints while retaining cloud-scale computational resources.
- Edge Computing:Sub-second response thresholds for fire safety and environmental controls demand localized processing independent of wide-area network latency.
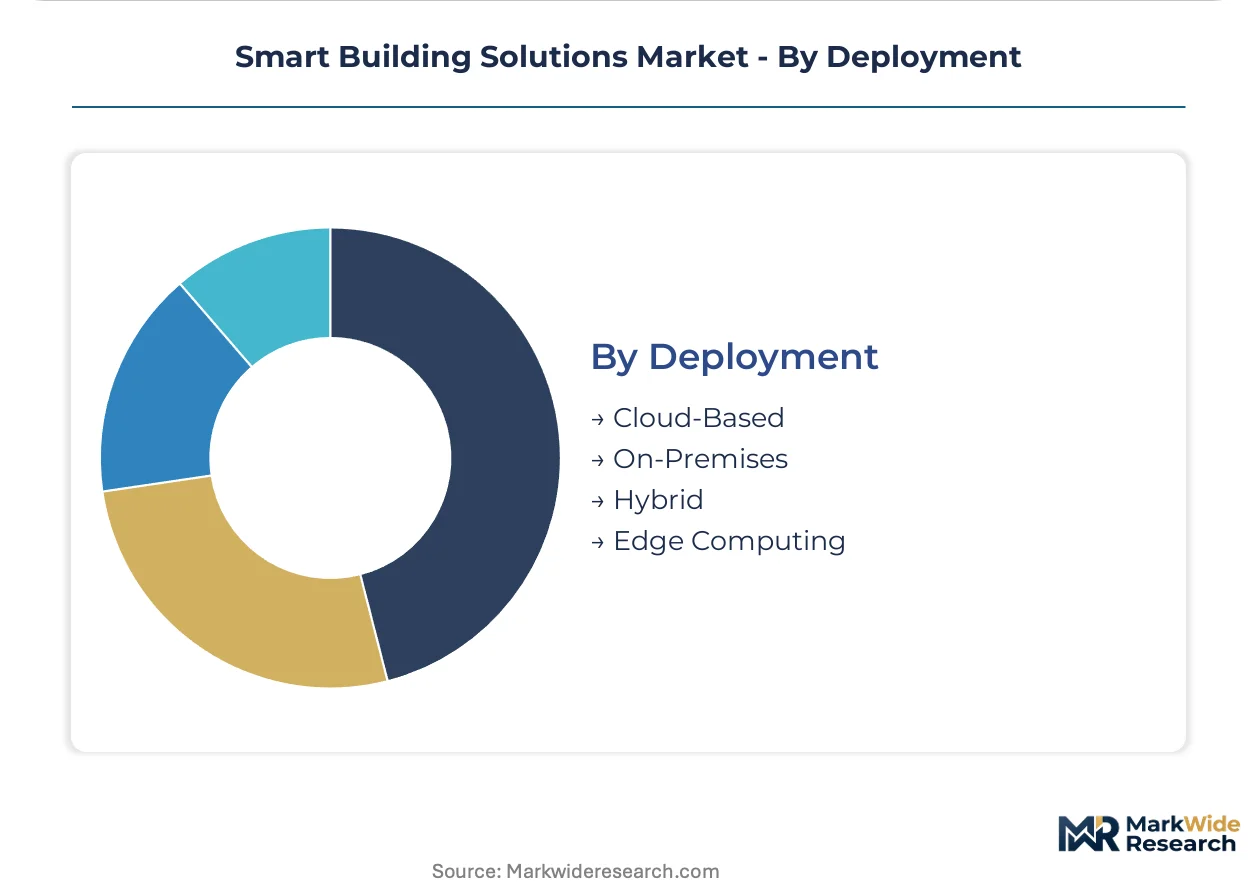
Cloud-Based architectures hold the largest installed base, though Hybrid deployments are climbing the fastest as data sovereignty frameworks tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Controller and sensor chip fabrication concentrates in Taiwan and South Korea, exposing project timelines to geopolitical disruption while procurement decisions in Germany, Singapore, and the United States reshape deployment patterns across commercial real estate portfolios.
United States
Corporate net-zero commitments and university endowment sustainability mandates accelerate procurement of integrated building management platforms. The EPA ENERGY STAR certification program and Inflation Reduction Act 179D tax credits up to five dollars per square foot shape retrofit investment decisions. Trophy assets in New York and Chicago specify decade-long performance contracts with guaranteed efficiency outcomes.
Germany
Frankfurt and Munich lead large-scale retrofit programs driven by the EU Energy Performance of Buildings Directive zero-emission building stock mandate for 2050. The BSI cybersecurity framework and algorithmic transparency requirements under the EU AI Act constrain vendor selection for biometric access systems. Property managers in Berlin and Hamburg prioritize pre-certified AI components to avoid deployment delays.
Singapore
Government-backed district cooling pilots and digital twin deployment narrow the smart building deployment gap across commercial towers. The Building and Construction Authority Green Mark scheme mandates measurable efficiency thresholds for new construction. Marina Bay and Jurong Lake District developments integrate BIM modeling with live IoT telemetry for predictive maintenance revenue streams.
China
MIIT dual carbon goals and GB standards for intelligent building design constrain market access for non-compliant foreign suppliers. Yangtze River Delta and Pearl River Delta commercial zones accelerate native digital control adoption for heat pump electrification replacing gas-fired boilers. Shanghai and Shenzhen municipal governments require disclosed performance benchmarking across multi-site portfolios.
India
Tier-2 municipal governments under the Smart Cities Mission seek district-level building automation for new commercial zones in Pune, Ahmedabad, and Kochi. The Bureau of Indian Standards and CEA grid integration codes shape procurement specifications for demand response interfaces. Hyderabad and Bangalore technology parks specify cloud-based energy management platforms with local edge processing for data sovereignty compliance.
Smart Building Solutions Market Competitive Environment
Integrated platform providers and automation specialists split the market between consolidated multi-system portfolios and fragmented single-domain solutions. Johnson Controls, Schneider Electric, and Siemens anchor the top tier through proprietary building management architectures that bundle HVAC, security, and energy optimization. Mid-tier players compete on protocol interoperability and retrofit-specific commissioning speed. Dominant competitive moves include strategic partnerships for digital twin convergence and geographic expansion into India's Smart Cities Mission municipalities.
Within the integrated platform tier, Johnson Controls and Schneider Electric exemplify archetype dominance through Metasys and EcoStruxure architectures that extend edge-to-cloud control. Siemens occupies a position emphasizing open-protocol automation across multi-vendor sensor networks. Honeywell International and ABB sit within the industrial-automation crossover segment, leveraging power distribution expertise for building energy applications. Cisco Systems and IBM represent the IT infrastructure convergence archetype, anchoring network security and cloud analytics layers without native environmental control hardware. Hitachi and Bosch exemplify diversified industrial conglomerates with building systems as one vertical among manufacturing and mobility portfolios.
| Leading Market Players |
|---|
| Johnson Controls |
| Schneider Electric |
| Honeywell International |
| Siemens |
| Cisco Systems |
| ABB |
| Hitachi |
| IBM |
| Bosch |
| Others |
Value Chain & Pricing Dynamics
Taiwan and South Korea's dominance in edge controller and sensor chip fabrication concentrates upstream margin capture, while downstream pricing power accrues to system integrators bundling hardware with outcome-based energy guarantees. This asymmetry forces component buyers to absorb volatility through indexed contracts while competing on software-defined service differentiation.
Pricing Analysis
The EU Energy Performance of Buildings Directive dictates the pricing tier structure across commercial retrofit markets, separating certified compliance-grade platforms from premium performance-optimization bundles. Three-tier pricing structure across premium, standard, and economy levels tracks BREEAM Outstanding, LEED Platinum, and baseline regulatory certification respectively. Cost compression in standard tiers is intensifying because heat pump electrification mandates are commoditizing basic digital control modules. Small and mid-size property owners in India's tier-2 cities exhibit highest price sensitivity, while trophy asset REITs in London and New York prioritize guaranteed efficiency outcomes over unit economics.
Supply Chain Analysis
Foundry capacity at TSMC and Samsung anchors semiconductor supply for building automation controllers, with backend assembly concentrated in Malaysia and Vietnam. Power distribution components draw from copper processing in Chile and rare earth magnet supply chains anchored in China. Single-source vulnerability around Taiwan Strait logistics exposes project timelines to geopolitical disruption. Distribution runs through authorized system integrators and OEM-direct channels for large commercial portfolios, with cloud-hosted software delivered through hyperscaler marketplaces.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Open-source building automation platforms and low-code IoT middleware threaten incumbent proprietary architectures by reducing switching costs for asset owners. Incumbents must defend through ecosystem lock-in and certification pre-positioning.
For Market Incumbents: Entrench platform stickiness by embedding digital twin capabilities that virtualize building performance simulation, raising substitution costs for portfolio managers. Deepen backward integration into edge controller design to secure chip allocation priority during supply constraints. Pre-certify AI components under the EU AI Act's high-risk framework before mandatory disclosure deadlines compress vendor selection windows.
For New Entrants and Emerging Players: India's Smart Cities Mission municipalities present the most penetrable white-space, where tier-2 governments in Pune, Ahmedabad, and Kochi seek district-level automation without legacy system migration burdens. Target hybrid cloud-edge architectures that satisfy GDPR data residency constraints while undercutting incumbents on commissioning speed. Lead with protocol interoperability as the primary go-to-market angle, eliminating custom middleware costs that extend project timelines for established vendors.
For Investors and Strategic Acquirers: Capital is best deployed toward mid-tier automation specialists with pre-certified AI components and established channel relationships in Germany's retrofit corridors. Long-term viability hinges on outcome-based contracting capabilities that align revenue with measured energy reduction. Monitor BSI and ANSSI cybersecurity compliance fragmentation as the inflection indicator—vendors with multi-framework certification will command acquisition premiums as regulatory divergence intensifies.
| Strategic Initiative | Industry Significance |
|---|---|
| Digital Twin Platform Integration | Virtualizes building performance simulation for predictive maintenance revenue streams beyond hardware sales. |
| EU AI Act Pre-Certification | Algorithmic transparency documentation for biometric access systems avoids deployment delays in German markets. |
| Backward Integration into Edge Controllers | In-house controller design secures semiconductor allocation priority during Taiwan Strait supply disruptions. |
| Hybrid Cloud-Edge Architecture Launch | Local processing with remote analytics satisfies GDPR constraints while retaining cloud-scale computational resources. |
| Smart Cities Mission Geographic Expansion | District-level automation contracts in Pune and Kochi capture procurement wave from India's municipal infrastructure buildout. |
Study Parameters
Desk research of regulatory filings, hyperscaler capex disclosures, and building automation technical standards preceded structured interviews with facilities management directors, REIT portfolio managers, system integrators, and energy procurement officers. Primary fieldwork across Germany, Singapore, and the United States validated secondary data from EPA ENERGY STAR databases, EU EPBD implementation reports, and BSI cybersecurity frameworks. Bottom-up project pipeline analysis triangulated against top-down market sizing across technology, application, and deployment segmentation dimensions.
Assumptions held fixed include continued EU EPBD enforcement intensity, IRA 179D tax credit stability, and Taiwan semiconductor fabrication continuity. Variables tested across the analysis window encompass heat pump electrification penetration rates, AI Act compliance timeline acceleration, and copper commodity price volatility. Segmentation modeling tracked IoT infrastructure, AI analytics, automation systems, and sensor hardware across energy management, security, HVAC, and lighting applications. CAGRs derived from installed base growth, replacement cycle compression, and new construction penetration curves, with edge computing latency requirements and cloud sovereignty regulations as industry-specific forecast inputs.
Practitioners should monitor EU member state EPBD transposition deadlines, BSI-ANSSI-NIST cybersecurity framework divergence, and Taiwan Strait logistics indicators for early signals of forecast revision. Quarterly review of semiconductor lead times, copper futures curves, and municipal smart city procurement announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Automation Systems
Global Building Information Modeling (BIM) Market
Building Automation Systems
Global Operating Equipment Room Market
Building Automation Systems
Platform Screen Door System Market
Building Automation Systems
Rotary Sprinkler System Market
Building Automation Systems
Automated Daylight Harvesting Systems Market
Building Automation Systems
Building Analytics Market
Building Automation Systems
Global Modularization Market
Building Automation Systems
Global Solar Shading Systems Market
Building Automation Systems
Commercial Building Automation Systems Market
Building Automation Systems
Platform Lifts Market
Building Automation Systems
Collapsible Gates Market
Building Automation Systems
Global Platform Screen Doors for Subway Lines Market
Building Automation Systems
China Revolving Doors Market
Building Automation Systems
Smart Garage Door Opener and Controller Market
Building Automation Systems
Integrated Building Management Systems Market
Building Automation Systems
Global Door Closers Market