
 Global Building Information Modeling (BIM) Market | 2026-2036
Global Building Information Modeling (BIM) Market Size, Share, and Industry Trends Forecast 2026-2036
Global Building Information Modeling (BIM) Market Intelligence
The ISO 19650 standard for information management is collapsing the traditional separation between the design, construction, and operational phases of a project. Autodesk Inc. dominates the architectural design software space with its Revit platform. Trimble Inc. specializes in connecting office-to-field workflows with integrated hardware and software solutions. Bentley Systems competes by focusing on large-scale infrastructure and industrial projects, offering specialized tools for civil engineering.
Building Information Modeling is a process for creating and managing a digital representation of a built asset. These models contain intelligent objects and data, enabling functionalities beyond 3D visualization, such as 4D scheduling and 5D cost estimation. Within the product landscape, software and SaaS-based cloud platforms are displacing legacy on-premise solutions. Architectural firms and construction management companies represent the largest end-user segments, driving requirements for design visualization and project management applications.
Government procurement policies are a significant market driver, exemplified by the UK's BIM Mandate and requirements from the US General Services Administration. In Asia, initiatives like Singapore's CORENET X platform standardize digital submission and approval processes, requiring BIM adoption. The next critical decision for stakeholders involves selecting platforms that ensure long-term data interoperability and support for future digital twin integration across the asset lifecycle.
Market Dynamics
The convergence of government procurement mandates and the ISO 19650 standard for information management is the central force shaping the market. This dual pressure compels adoption across public and private sectors, standardizing digital workflows from design through to operation.
Growth Catalysts
- Government Mandates:Policies like the UK's BIM Mandate and Singapore's CORENET X platform require the use of BIM for public infrastructure and digital regulatory submissions, creating non-negotiable demand.
- Technology Accessibility:The proliferation of cloud-based SaaS platforms lowers the initial investment barrier for smaller architectural and construction firms, enabling broader participation in collaborative digital workflows.
- Project Complexity:Increasing complexity in commercial and industrial building design necessitates BIM for clash detection, visualization, and coordination among multiple engineering disciplines, reducing costly rework.
Market Restraints
- High Implementation Cost:The initial investment in software licenses, high-performance hardware, and comprehensive staff training represents a significant financial barrier for small and medium-sized enterprises (SMEs).
- Interoperability Deficiencies:Persistent data exchange issues between proprietary software formats from different vendors create workflow friction and risk data loss across project phases.
- Skilled Labor Scarcity:A global shortage of architects, engineers, and project managers with proven expertise in advanced BIM software and integrated project delivery methods limits expansion capacity.
Strategic Opportunities
- Digital Twin Integration:Expanding BIM models with real-time operational data from IoT sensors offers a significant opportunity to create dynamic digital twins for asset management and predictive maintenance.
- Geographic Expansion:Developing economies in Latin America and the Middle East represent underpenetrated markets where future government infrastructure programs could trigger rapid BIM adoption.
- Sustainability and ESG Reporting:BIM can be leveraged for lifecycle carbon assessment and energy performance analysis, aligning with growing ESG requirements for real estate and infrastructure assets under regulations like the CSRD.
Industry Challenges
- Legacy System Integration:Connecting modern BIM platforms with entrenched, decades-old enterprise resource planning (ERP) and facility management systems presents a significant technical and operational challenge for asset owners.
- Data Standardization:Despite the ISO 19650 framework, a lack of universal data classification and object library standards complicates collaboration on international projects and hinders data reuse.
- Contractual Framework Adaptation:Traditional construction contracts often fail to adequately address intellectual property rights, data ownership, and liability in a collaborative BIM environment, creating legal ambiguity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Building Information Modeling (BIM) Market |
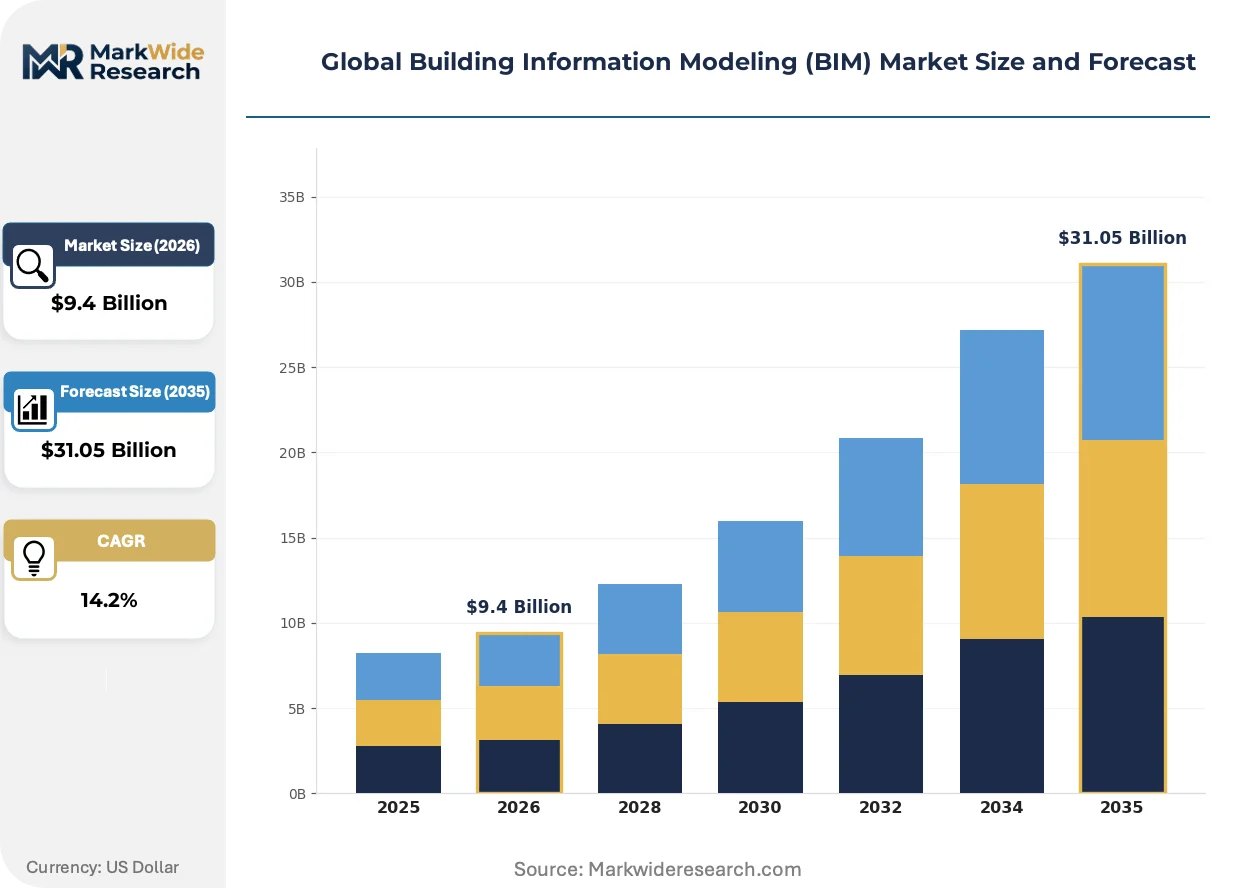
| Market Size in 2026 | $9.4 Billion |
| Market Size in 2035 | $31.05 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Software, Cloud Platforms, Mobile Applications, APIs, Desktop Solutions Deployment: On-premise, Web-based, Hybrid, SaaS Application: Design Visualization, Project Management, Structural Analysis, Cost Estimation, Facility Management End User: Architectural Firms, Construction Management, Engineering Consultants, Facility Operators, Urban Planning Agencies |
| Companies Covered | Trimble Inc., Procore Technologies, Autodesk Inc., Hexagon AB, Schneider Electric, Nemetschek Group, Dassault Systèmes, Asite, Bentley Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Building Information Modeling (BIM) Market Strategic Shifts & Innovations
The market is evolving from a focus on 3D visualization to the creation of data-rich digital assets that serve the entire lifecycle of a building or infrastructure project. This shift transforms BIM from a design tool into a foundational platform for digital twins and long-term asset management.
Cloud-based Common Data Environments (CDEs) provide a centralized repository for all project information, accessible by all stakeholders. Architectural firms and large general contractors are adopting these platforms to manage the immense data volumes generated on complex projects. The proliferation of specialized CDEs and ancillary applications is fragmenting the software ecosystem away from monolithic, single-vendor suites toward a more diverse, API-driven landscape.
European Union directives, such as the Energy Performance of Buildings Directive (EPBD), are indirectly compelling the use of digital building models. The directive's emphasis on lifecycle energy efficiency requires detailed analysis that is most effectively performed using data-rich BIM. Consequently, the building design and engineering segments in EU member states are integrating energy simulation tools directly into their BIM workflows to ensure compliance.
A notable behavioral change involves asset owners demanding BIM data as a contractual deliverable for facility operations and maintenance. This disrupts the traditional handover process, which previously relied on paper-based drawings and manuals, by requiring contractors to provide a structured digital asset information model. This pattern is most pronounced in the development of hospitals, airports, and universities in North America and Europe, where operational efficiency is paramount.
Global Building Information Modeling (BIM) Market Segmentation
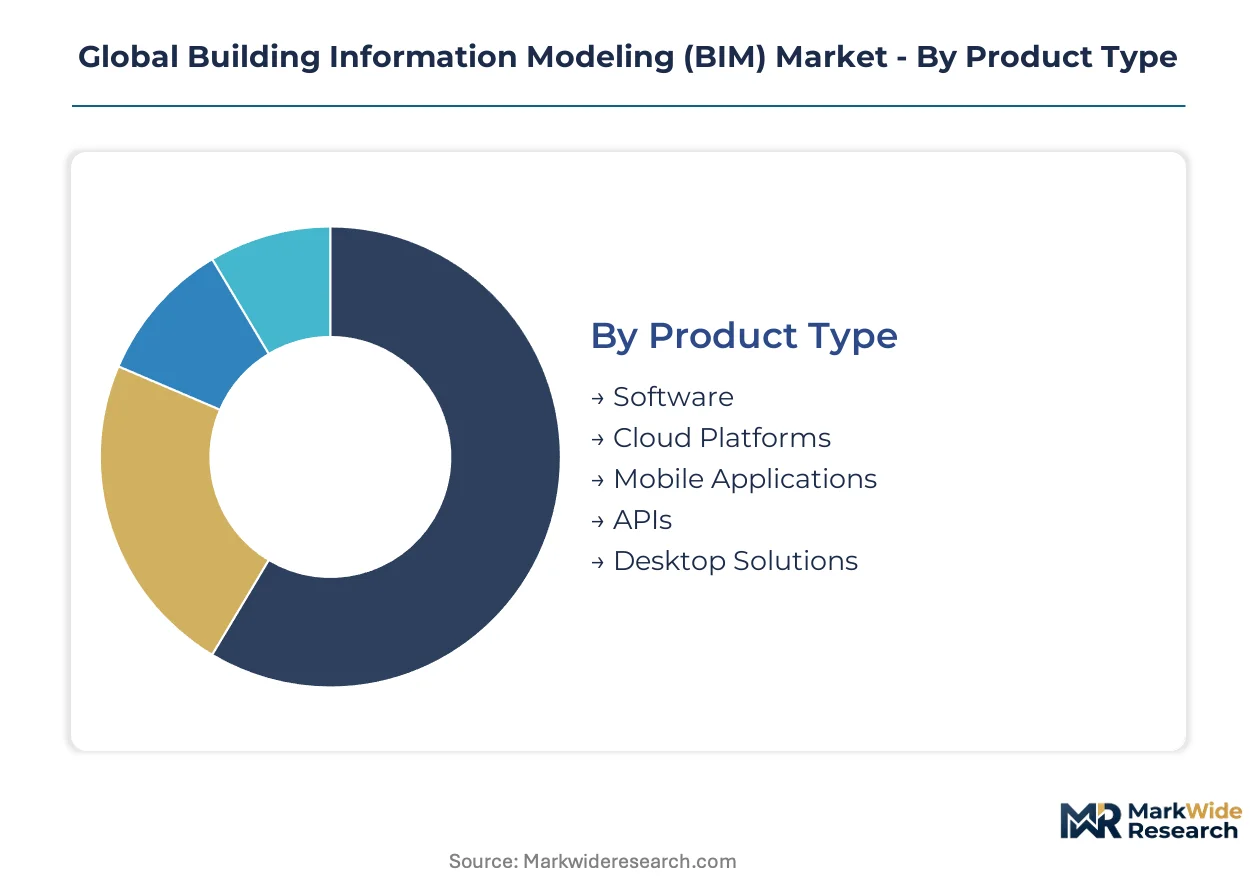
The Global Building Information Modeling (BIM) market differentiates across product types, deployment models, primary applications, and end-user profiles. Understanding these distinct segments provides stakeholders with clarity on where innovation and investment are concentrating within the evolving digital construction ecosystem. This segmentation highlights the diverse needs of various industry participants.
Product Type:
The product type segment faces significant substitution pressure as cloud-based platforms and APIs displace traditional desktop software solutions. This shift redefines how BIM tools are accessed and integrated across project workflows.
- Software:These encompass comprehensive desktop applications providing design, analysis, and documentation capabilities for architects and engineers. Demand for robust software remains strong for complex, large-scale projects requiring deep computational power and extensive customization.
- Cloud Platforms:These web-based, collaborative environments host BIM models and project data, enabling real-time access and multi-stakeholder coordination from any location. The increasing demand for flexible, scalable solutions drives adoption among distributed project teams.
- Mobile Applications:Provide on-site access to BIM data, enabling field teams to view models and manage tasks from portable devices.
- APIs:Allow custom integrations between BIM software and third-party tools, fostering an interconnected digital ecosystem.
- Desktop Solutions:Traditional, locally installed software packages offer specialized functionalities for specific design or analysis tasks.
Traditional software anchors the volume base while cloud platforms gain share at the steepest rate due to their collaborative advantages.
Deployment:
The deployment segment reflects varying levels of technological maturity and infrastructure investment across different organizations. Legacy systems co-exist with modern cloud-native approaches.
- SaaS:Software-as-a-Service models deliver BIM tools and data via the internet on a subscription basis, significantly reducing upfront costs and IT overhead for users. This model is preferred by smaller firms seeking agility and scalability without heavy infrastructure.
- Web-based:These solutions are accessed through standard web browsers, offering broad accessibility and facilitating collaboration among geographically dispersed project teams. Web-based platforms support a wide range of BIM functionalities.
- On-premise:These deployments involve installing BIM software on local servers, providing maximum data security control for large enterprises.
- Hybrid:Combines on-premise and cloud-based solutions, allowing local data control with cloud collaboration.
SaaS deployment models are expanding most quickly, driven by lower initial investment and enhanced accessibility for a broad user base.
Application:
The application segment is driven by the specific functional requirements of different project phases and stakeholder needs. Each application addresses distinct challenges within the asset lifecycle.
- Design Visualization:This involves creating realistic 3D renderings and interactive models to communicate design intent and facilitate stakeholder understanding. Architectural firms heavily utilize this for client presentations and design reviews, enhancing project buy-in.
- Project Management:These tools integrate scheduling, resource allocation, and progress tracking with BIM data, enabling efficient oversight and coordination of construction activities. Construction management companies depend on this for workflow optimization.
- Structural Analysis:Assesses structural integrity and performance of building components, ensuring compliance with engineering standards and safety regulations.
- Cost Estimation:Extracts quantities and specifications from BIM models to generate accurate cost projections, aiding in budgeting and financial planning.
- Facility Management:Uses BIM data for the operational phase, supporting maintenance, space planning, and asset tracking throughout an asset's lifecycle.
Design visualization provides foundational project understanding, while facility management applications are climbing the fastest in adoption for long-term asset value.
End User:
The end-user segment reflects the diverse professional groups leveraging BIM for their specific operational requirements and project contributions. Each group demands tailored functionalities.
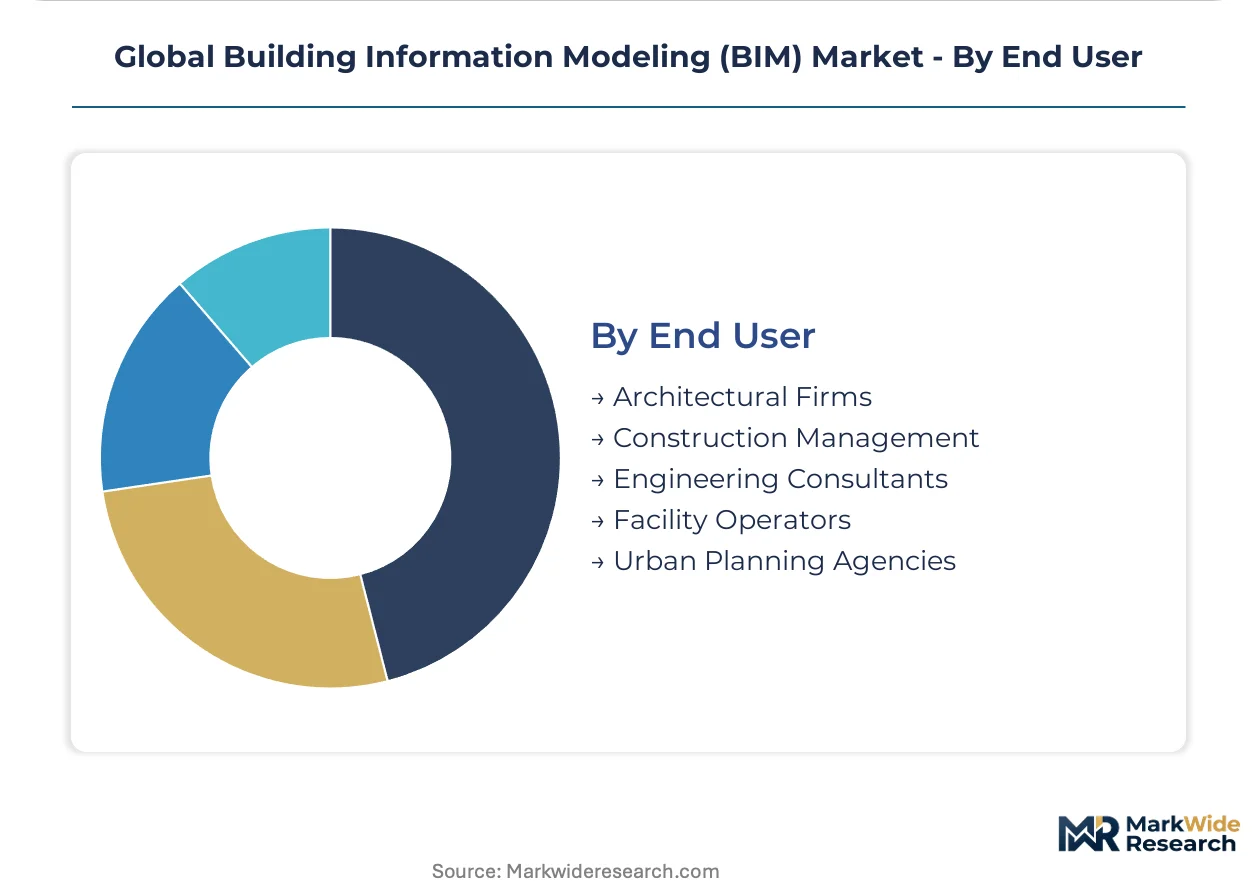
- Architectural Firms:These firms use BIM for comprehensive design, documentation, and visualization, integrating aesthetics with technical specifications. They drive requirements for advanced design visualization and collaborative tools for complex commercial projects.
- Construction Management:These companies utilize BIM for project planning, scheduling, clash detection, and site logistics, optimizing construction workflows and reducing rework. They rely on BIM for efficient project execution and cost control.
- Engineering Consultants:Specialists apply BIM for detailed structural, mechanical, electrical, and plumbing (MEP) design and analysis.
- Facility Operators:Entities use BIM models for asset management, maintenance scheduling, and operational efficiency.
- Urban Planning Agencies:Government bodies leverage BIM for large-scale infrastructure planning, city modeling, and regulatory review.
Architectural firms represent a foundational user base, while facility operators are demonstrating the steepest expansion trajectory for post-construction asset management.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Government mandates and the ISO 19650 standard are driving Building Information Modeling adoption across diverse geographies. These policy frameworks compel public and private sector entities to integrate digital workflows throughout project lifecycles. Demand is particularly strong in countries prioritizing infrastructure development and digital transformation initiatives for their construction sectors.
United Kingdom
Public infrastructure projects and complex commercial developments drive significant BIM demand. The UK's BIM Mandate requires Level 2 BIM for all centrally procured public projects. London's architectural, engineering, and construction (AEC) sector continues to adopt advanced BIM tools for efficient project delivery and asset management.
Singapore
Digital submission requirements and smart city initiatives accelerate BIM adoption in Singapore. The CORENET X platform standardizes digital submissions for regulatory approval, necessitating BIM use. Major developments like the expansion of Changi Airport integrate BIM for detailed planning and operational efficiency.
Germany
Sustainability regulations and the need for complex commercial building design fuel BIM integration in Germany. European directives, such as the Energy Performance of Buildings Directive (EPBD), encourage data-rich models for energy efficiency analysis. Berlin's burgeoning tech and construction sectors embrace BIM for innovative design and project coordination.
United States
Large-scale infrastructure upgrades and government procurement policies stimulate BIM demand across the United States. The US General Services Administration (GSA) mandates BIM for various federal projects. Major metropolitan areas like New York City leverage BIM for intricate urban development and facility management.
United Arab Emirates
Ambitious national development visions and rapid urbanization are compelling BIM adoption in the UAE. Government initiatives like Dubai's Smart City strategy promote digital construction technologies. Significant projects in Dubai and Abu Dhabi use BIM for design visualization, cost estimation, and project management.
Global Building Information Modeling (BIM) Market Key Industry Players
Listed leaders compete with private specialists across software development and platform integration within the BIM market. The competitive landscape exhibits a blend of established players offering comprehensive suites and agile firms providing niche, cloud-native solutions. Strategic archetypes include integrated platform providers, specialized analytical tool developers, and collaborative cloud environment hosts. Dominant competitive moves involve mergers and acquisitions for technology capabilities and strategic partnerships to expand ecosystem reach.
Integrated platform providers like Autodesk Inc. exemplify the market's shift towards comprehensive design and data management solutions. Trimble Inc. represents the focus on connecting office-to-field workflows through integrated hardware and software. Bentley Systems, a prominent player, anchors the segment specializing in large-scale infrastructure and industrial project solutions, offering specialized tools for civil engineering applications.
| Leading Market Players |
|---|
| Trimble Inc. |
| Procore Technologies |
| Autodesk Inc. |
| Hexagon AB |
| Schneider Electric |
| Nemetschek Group |
| Dassault Systèmes |
| Asite |
| Bentley Systems |
| Others |
Cost & Logistics Intelligence
Project-based licensing and subscription models lock in both software access and predictable revenue streams for BIM vendors. This structure influences long-term engagement with architectural firms and construction management companies.
Pricing Analysis
Functionality breadth creates the primary spread in BIM software pricing, differentiating comprehensive suites from specialized tools. Pricing models predominantly follow a subscription or SaaS-tiered structure, with some legacy project-based licenses still in use. Integration capabilities and cloud collaboration features drive significant price differentiation among offerings. Pricing pressure stems from the proliferation of agile, cloud-native solutions. Small and medium-sized enterprises (SMEs) exhibit the most price-sensitive buyer behavior, while large enterprises and government entities prioritize feature sets and vendor stability.
Supply Chain Analysis
Talent scarcity in software development underwrites the core supply chain vulnerability for BIM platforms. The supply chain for BIM software development concentrates heavily in established technology hubs across the United States, Europe, and India. Key dependencies include access to skilled software developers and robust cloud infrastructure services. Data security compliance across diverse regulatory environments represents a structural risk. Distribution primarily occurs through direct sales channels, value-added resellers, and rapidly expanding cloud marketplaces.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The BIM market presents a capability-scarcity narrative, particularly concerning the global shortage of skilled professionals proficient in advanced digital construction workflows.
For Market Incumbents: Consolidate comprehensive platform offerings through strategic acquisitions of niche cloud-native solutions. This defends against fragmentation from specialized tools and emerging entrants. Invest in advanced API integration capabilities to expand ecosystem reach and combat interoperability deficiencies. Prioritize R&D in AI-driven automation for design and clash detection to maintain a technological edge against disruptive startups.
For New Entrants and Emerging Players: Anchor in specific application white-spaces such as sustainability analysis or digital twin integration, where established players may have legacy system limitations. Target underpenetrated developing economies in Latin America and the Middle East, leveraging localized support. A go-to-market strategy focused on open-source integration and highly specialized SaaS offerings can attract early adopters and address specific project needs.
For Investors and Strategic Acquirers: Specialized SaaS providers offering high-value analytics or workflow automation represent attractive acquisition targets over the long term. The market's viability hinges on the continued digital transformation of the architecture, engineering, and construction (AEC) sector. The expansion of government mandates for BIM adoption across new geographies serves as a critical signal to watch for inflection in market growth and investment opportunities.
| Strategic Initiative | Industry Significance |
|---|---|
| Acquisition of Cloud-Native Platforms | Consolidates market share and integrates advanced collaborative technologies for incumbents. |
| Investment in AI-Driven Automation | Enhances design efficiency and reduces manual rework across complex projects. |
| Geographic Expansion into Developing Economies | Captures new demand in regions with emerging infrastructure development programs. |
| Development of Specialized Sustainability Tools | Addresses growing regulatory requirements for lifecycle carbon assessment and ESG reporting. |
| Strategic Partnerships for Digital Twin Integration | Extends BIM utility beyond construction into long-term asset management and operational efficiency. |
Research Approach
A spread of perspectives from architectural firm principals, construction project managers, government procurement officers, and software developers converged on the working assumptions. This approach combined primary interviews with extensive secondary validation. Secondary data sources included ISO standards documents, government tender databases, industry association reports, and academic journals. The methodology employed both bottom-up and top-down triangulation to ensure robust data integrity.
The forecast framework modeled segmentation dimensions including product type, deployment, application, end-user, and regional adoption maturity. Compound Annual Growth Rates (CAGRs) were derived through a rigorous analysis of historical data and projected market dynamics across the analysis window. Key industry-specific forecast inputs included global infrastructure spending forecasts and anticipated regulatory policy changes.
Underlying assumptions cover technology adoption rates and regulatory stability, with deviation risk concentrated in global economic slowdowns and skilled labor availability. Practitioners should keep alternative scenarios live as government mandates and technological advancements evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Automation Systems
Smart Window Film Market
Building Automation Systems
North America Building Automation System Market
Building Automation Systems
Integrated Building Management Systems Market
Building Automation Systems
LAMEA Building Automation System Market
Building Automation Systems
Automated Daylight Harvesting Systems Market
Building Automation Systems
Traction Elevator Market
Building Automation Systems
Global Solar Shading Systems Market
Building Automation Systems
China Revolving Doors Market
Building Automation Systems
Computer-Aided Facility Management (CAFM) Market
Building Automation Systems
Elevator Modernization Market
Building Automation Systems
Electrochromic Glass Market
Building Automation Systems
Residential Electric Underfloor Heating Market
Building Automation Systems
Global Enterprise Building Solutions Market
Building Automation Systems
Intelligent Building Automation Technologies Market
Building Automation Systems
Global Modularization Market
Building Automation Systems
Platform Screen Door System Market