
 Tunnel Automation Market | 2026-2036
Tunnel Automation Market Size, Share, and Industry Trends Forecast 2026-2036
Tunnel Automation Market Outlook
A capital-intensity divergence between large system integrators and component specialists is rotating competitive dynamics across the tunnel automation sector. Siemens AG leverages its integrated electrification portfolio to dominate turnkey tunnel management contracts across European rail corridors. Honeywell International Inc. sustains technology leadership in fire safety and environmental control subsystems for vehicular tunnels. SICK AG anchors its position through specialized sensor arrays that enable real-time particulate and traffic flow monitoring in underground environments.
Tunnel automation encompasses the integration of electromechanical, sensing, and software systems that monitor, control, and optimize infrastructure operations within enclosed subterranean passages, typically operating across temperature ranges from -20°C to +50°C with IP67-rated enclosures for moisture and dust resistance. The primary commercial purpose centers on ensuring occupant safety, minimizing energy consumption, and maintaining continuous traffic throughput in road, rail, and utility tunnels. Control systems command the largest installed base due to their centrality in coordinating ventilation, lighting, and emergency response protocols across extended tunnel networks. Sensor systems represent the fastest-expanding segment as operators deploy denser arrays for predictive maintenance and anomaly detection. Robotics remains nascent but concentrates margin pools in specialized inspection applications where human access carries prohibitive risk.
The European Union's F-Gas Regulation and Machinery Directive, alongside national frameworks from Germany's KBA and Switzerland's BAV, collectively mandate redundant safety architectures and emissions-compliant ventilation systems that elevate automation specification thresholds. Compliance with CE marking under the EU AI Act increasingly shapes software procurement decisions for traffic prediction and incident classification algorithms. Stakeholders must monitor evolving interoperability standards between legacy SCADA platforms and cloud-native analytics layers to preserve capital deployment flexibility.
Market Dynamics
European rail operators are accelerating replacement cycles for legacy SCADA architectures as the EU AI Act imposes algorithmic transparency mandates on predictive traffic management systems, forcing simultaneous hardware and software procurement decisions.
Growth Catalysts
- Alpine Tunnel Safety Mandates:Switzerland's BAV enforces redundant ventilation control architectures across the Gotthard and Lötschberg corridors, compelling operators to deploy integrated sensor networks.
- F-Gas Regulation Compliance:Germany's KBA requires lower-emission refrigerant systems in tunnel climate control, driving specification upgrades for variable-speed drive retrofits.
- Predictive Maintenance Algorithms:Machine learning models for anomaly detection in bearing and fan systems reduce unplanned downtime in Norway's subsea tunnel networks.
Market Restraints
- Copper and Rare Earth Volatility:Sensor array and motor winding costs fluctuate with concentrate supply from Chilean and Chinese smelters, compressing project margins for turnkey integrators.
- Legacy Protocol Lock-In:Proprietary fieldbus standards from 1990s installations resist interoperability with IP-native control layers, extending commissioning timelines.
- Subcontractor Concentration:Specialized tunnel boring machine automation expertise clusters in German and Swiss engineering firms, creating bottleneck risk for cross-border projects.
Strategic Opportunities
- Robotic Inspection Services:Unmanned ground vehicles for structural crack detection in high-radiation or oxygen-depleted tunnel segments command premium service contracts.
- Battery-Electric Ventilation:Integration of lithium-titanate storage with emergency smoke extraction systems addresses Austria's decarbonization targets for transport infrastructure.
- Cloud-Native SCADA:Containerized control software enables multi-site operators to centralize tunnel management across dispersed Alpine and Pyrenean corridors.
Industry Challenges
- Cyber-Physical Certification Timelines:CE marking under the EU AI Act for autonomous incident classification algorithms extends validation cycles by 12-18 months.
- Electromechanical Skill Scarcity:Technicians capable of servicing both pneumatic actuators and edge computing nodes are concentrated in aging workforces across Northern Italy and Southern Germany.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tunnel Automation Market |
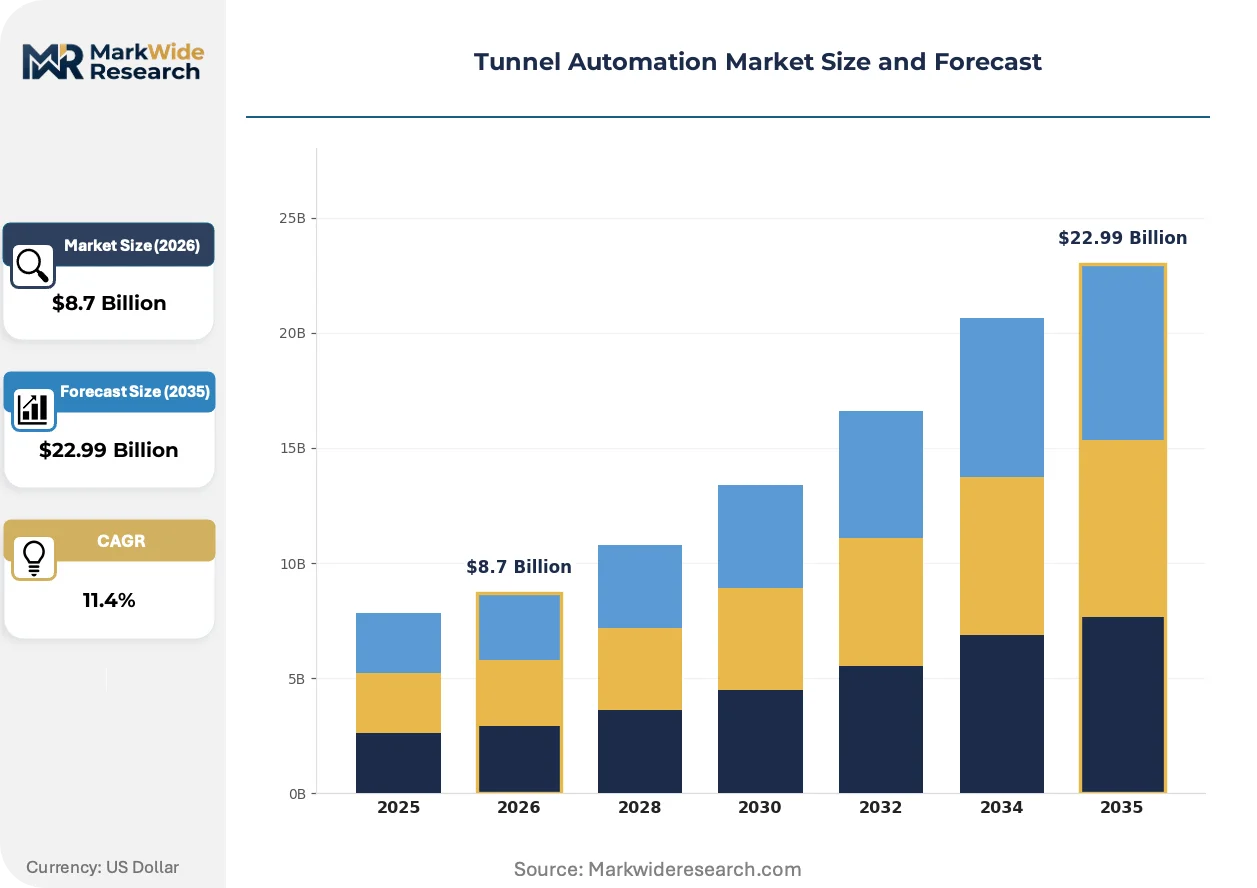
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Telematics, Sensor Systems, Robotics, Control Systems Application: Mining, Transportation, Waste Water Management, Construction End User: Government, Infrastructure Developers, Utility Companies, Mining Corporations Service Type: Consulting, Maintenance, Installation, Software Development |
| Companies Covered | SICK AG, Honeywell International Inc., Siemens AG, Indra Sistemas, Trane Technologies, Johnson Controls, Signify Holding BV, SICE, ABB Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tunnel Automation Market Strategic Shifts
Digital twin implementations are compressing commissioning schedules for complex ventilation networks, while edge computing architectures reduce latency for emergency response protocols in extended subterranean passages.
Silicon carbide power semiconductors are displacing insulated-gate bipolar transistors in variable frequency drives for tunnel ventilation fans. Austrian and Swiss operators deploying these modules report 15-20% energy recovery in regenerative braking applications for jet fan arrays. The technology is displacing conventional motor control cabinets in new-build Alpine corridor projects, reducing enclosure footprints by one-third.
The EU AI Act's risk classification framework for safety-critical infrastructure algorithms now mandates documented training data provenance and human oversight interfaces for automated traffic incident detection. Tunnel operators in Germany and France must retrofit existing video analytics pipelines or face operational license restrictions. Control system vendors are responding with modular software architectures that isolate AI inference engines from legacy PLC backplanes.
Swiss and Norwegian transport authorities now unbundle hardware procurement from decade-long maintenance contracts, forcing component suppliers to compete on lifecycle cost models rather than upfront capital expenditure. Specialist sensor manufacturers are capturing margin through performance-guaranteed service agreements covering calibration drift and firmware updates. This shift is most visible in the Gotthard Base Tunnel and Ryfast subsea corridor, where availability-based contracting now dominates tender specifications.
Tunnel Automation Market Segmentation
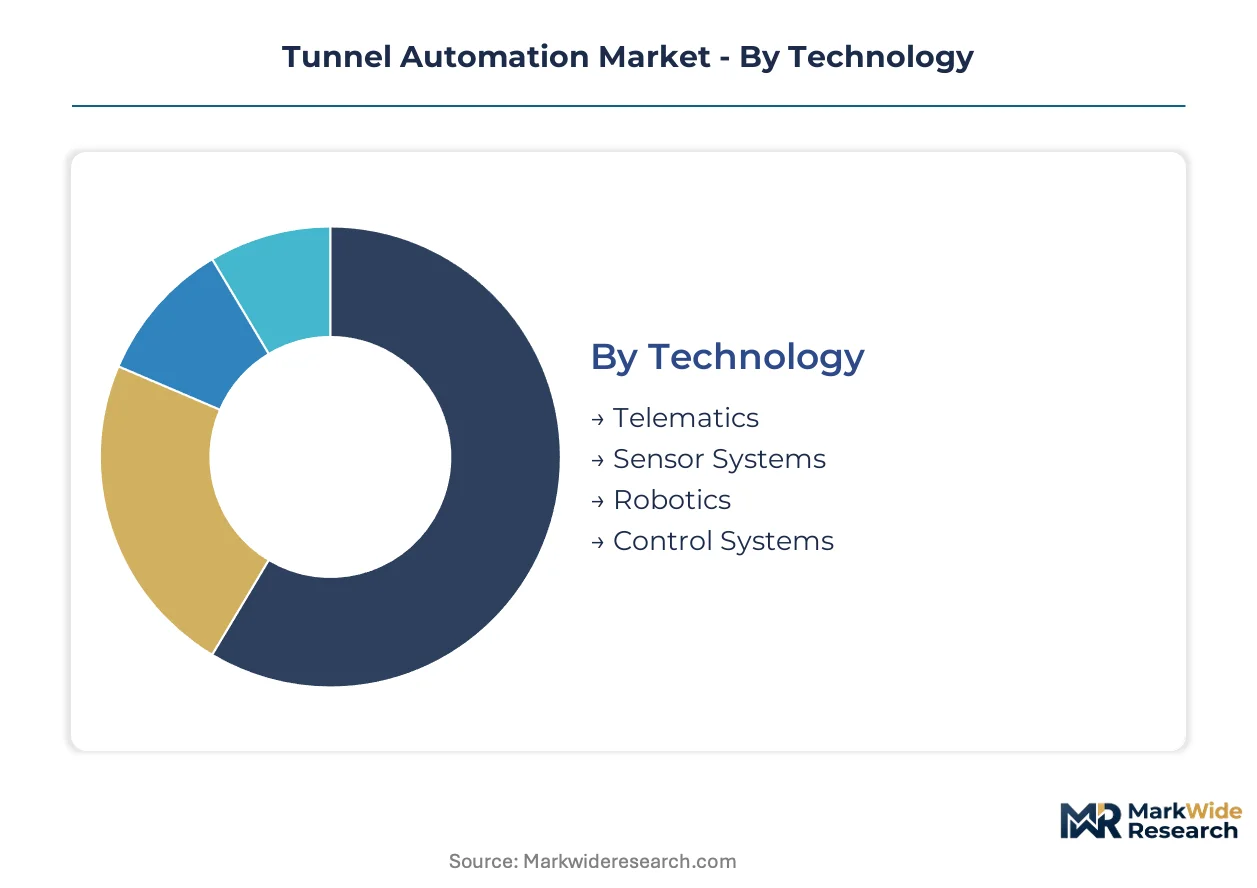
Tunnel automation procurement patterns diverge sharply across technology tiers and application contexts, with regulatory stringency in Alpine corridors and subsea networks dictating specification thresholds. Understanding these segment boundaries enables vendors to align R&D investment with enforcement-driven demand pockets.
Technology:
Germany's KBA and Switzerland's BAV impose distinct certification requirements that fragment specification standards across electromechanical, sensing, and algorithmic technology layers.
- Control Systems:Centralized PLCs and distributed SCADA architectures coordinate ventilation, lighting, and emergency protocols across extended tunnel networks. Operators in Switzerland's Gotthard Base Tunnel deploy redundant control architectures to satisfy BAV-mandated availability thresholds for smoke extraction sequences.
- Sensor Systems:Denser arrays of particulate, thermal, and traffic flow monitors enable predictive maintenance and anomaly detection in oxygen-depleted segments. Norwegian subsea tunnel operators drive densification of vibration and bearing-temperature sensors to reduce unplanned jet fan downtime in Ryfast and comparable corridors.
- Telematics:Vehicle-to-infrastructure communication modules relay position and speed data for automated incident response in vehicular tunnels.
- Robotics:Unmanned ground vehicles and aerial platforms execute structural inspection in high-radiation or confined segments where human access carries prohibitive safety risk.
Established volume favors Control Systems; emerging adoption favors Sensor Systems.
Application:
Capital deployment cycles and safety liability exposure create divergent margin profiles across underground infrastructure categories.
- Transportation:Road and rail tunnels command the largest installed automation base, with ventilation and fire suppression systems subject to continuous regulatory tightening. Swiss and Austrian Alpine corridor operators face the most stringent redundant-architecture mandates under national transport safety frameworks.
- Mining:Autonomous haulage and ventilation control in deep ore extraction operations. Australian and Canadian hard-rock mining jurisdictions drive specification of explosion-proof sensor housings and methane detection arrays.
- Construction:Temporary automation for tunnel boring machine guidance and segment placement during excavation phases.
- Waste Water Management:Level monitoring and pump control in combined sewer overflow tunnels and deep interceptor systems.
Transportation anchors current revenue concentration; mining applications are climbing the fastest as autonomous operations penetrate deeper extraction sites.
End User:
Procurement authority and lifecycle cost accountability shape vendor engagement models across public and private infrastructure ownership structures.
- Government:National transport ministries and regional authorities specify automation for strategic rail and road corridors. German federal infrastructure budgets prioritize F-Gas-compliant ventilation retrofits in existing Autobahn tunnels.
- Infrastructure Developers:Concession holders and public-private partnerships under long-term availability contracts. Swiss and Norwegian authorities now unbundle hardware procurement from decade-long maintenance agreements, forcing lifecycle cost competition.
- Utility Companies:Water and power transmission operators automating access tunnels and cable galleries.
- Mining Corporations:Integrated extraction companies deploying proprietary automation stacks for site-specific ore body conditions.
Government procurement dominates specification-setting; infrastructure developers are gaining share fastest through availability-based contracting models.
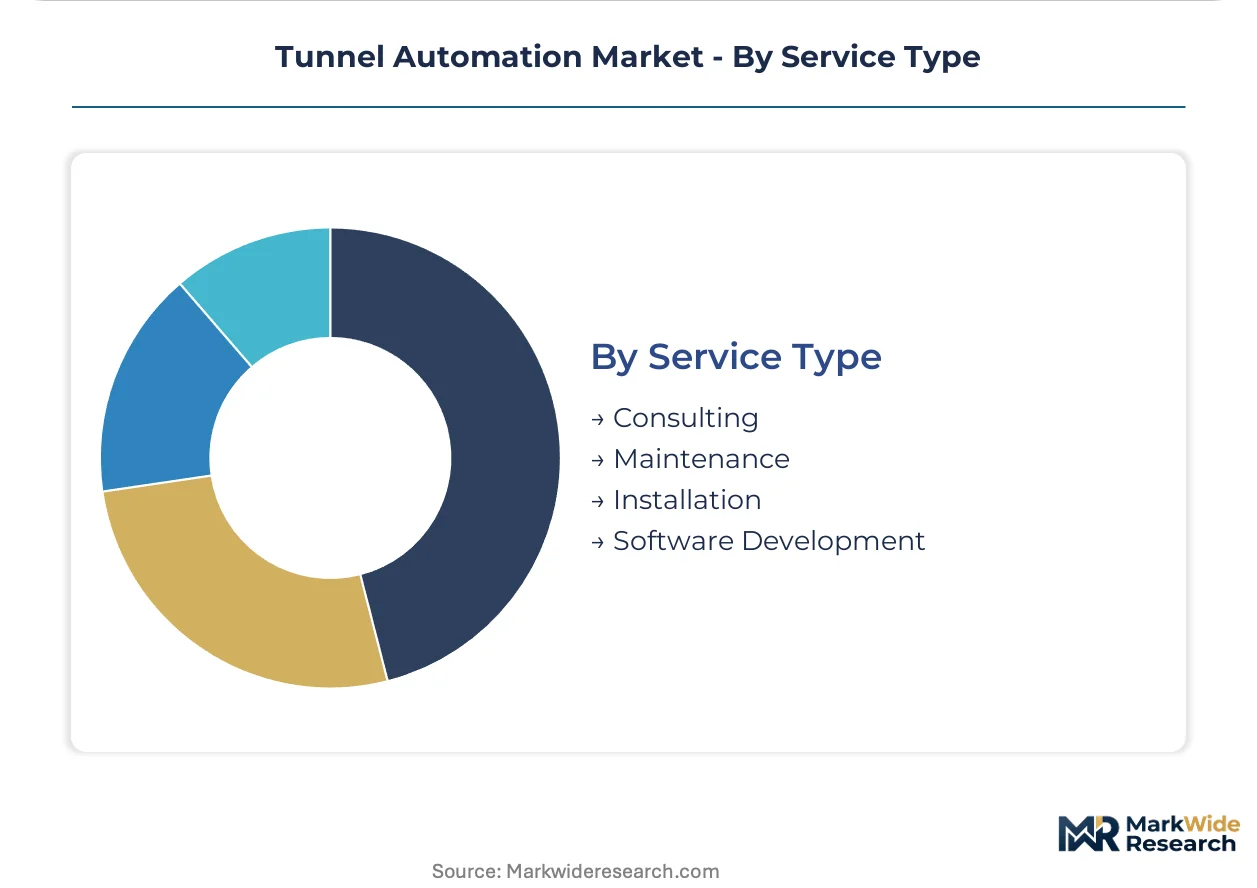
Service Type:
Revenue recognition timing and customer lock-in duration vary across the project lifecycle, with post-commissioning services capturing expanding margin pools.
- Installation:Turnkey electromechanical deployment and system integration for greenfield tunnels and brownfield retrofits. Alpine corridor projects in Switzerland and Austria concentrate demand for integrated ventilation and lighting control commissioning.
- Maintenance:Performance-guaranteed service agreements covering calibration drift, firmware updates, and predictive parts replacement. Specialist sensor manufacturers in the Gotthard Base Tunnel corridor capture margin through availability-based contracts.
- Consulting:Front-end engineering and regulatory compliance advisory for complex multi-system integrations.
- Software Development:Custom algorithm development for traffic prediction and incident classification under EU AI Act transparency mandates.
Installation commands upfront capital allocation; maintenance services represent the steepest expansion trajectory as operators shift to lifecycle contracting.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Germany and Switzerland exhibit low price elasticity due to stringent BAV and KBA mandates, while infrastructure developers in Norway and Austria negotiate harder on lifecycle costs under availability-based contracting models.
Germany
The KBA enforces F-Gas-compliant ventilation retrofits across Autobahn tunnel networks, compelling operators to specify variable-speed drive upgrades. Federal infrastructure budgets prioritize climate control modernization in legacy road corridors. Engineering clusters around Munich and Stuttgart concentrate turnkey integration expertise for multi-system automation deployments.
Switzerland
BAV-mandated redundant safety architectures drive specification of integrated sensor networks across the Gotthard and Lötschberg Alpine corridors. The authority unbundles hardware procurement from decade-long maintenance contracts, shifting vendor competition toward lifecycle cost models. Ticino and Valais cantons host specialized firms delivering availability-guaranteed service agreements for tunnel infrastructure.
Norway
Subsea tunnel operators in Ryfast and comparable corridors deploy densified vibration and bearing-temperature sensor arrays to minimize unplanned jet fan downtime. The Norwegian Public Roads Administration mandates predictive maintenance algorithms for critical ventilation assets. Bergen and Stavanger engineering consultancies specialize in anomaly detection systems for oxygen-depleted tunnel segments.
Austria
Decarbonization targets for transport infrastructure accelerate adoption of battery-electric ventilation systems with lithium-titanate storage integration. National tunnel safety frameworks require emissions-compliant emergency smoke extraction architectures. Tyrol and Salzburg corridor operators pilot regenerative braking applications for jet fan arrays in Alpine transit routes.
France
The EU AI Act's algorithmic transparency mandates force retrofit of existing video analytics pipelines for automated traffic incident detection. ANSM and CNIL guidance shapes procurement decisions for safety-critical infrastructure software. Lyon and Paris infrastructure authorities deploy modular control architectures that isolate AI inference engines from legacy PLC backplanes.
Tunnel Automation Market Competitive Environment
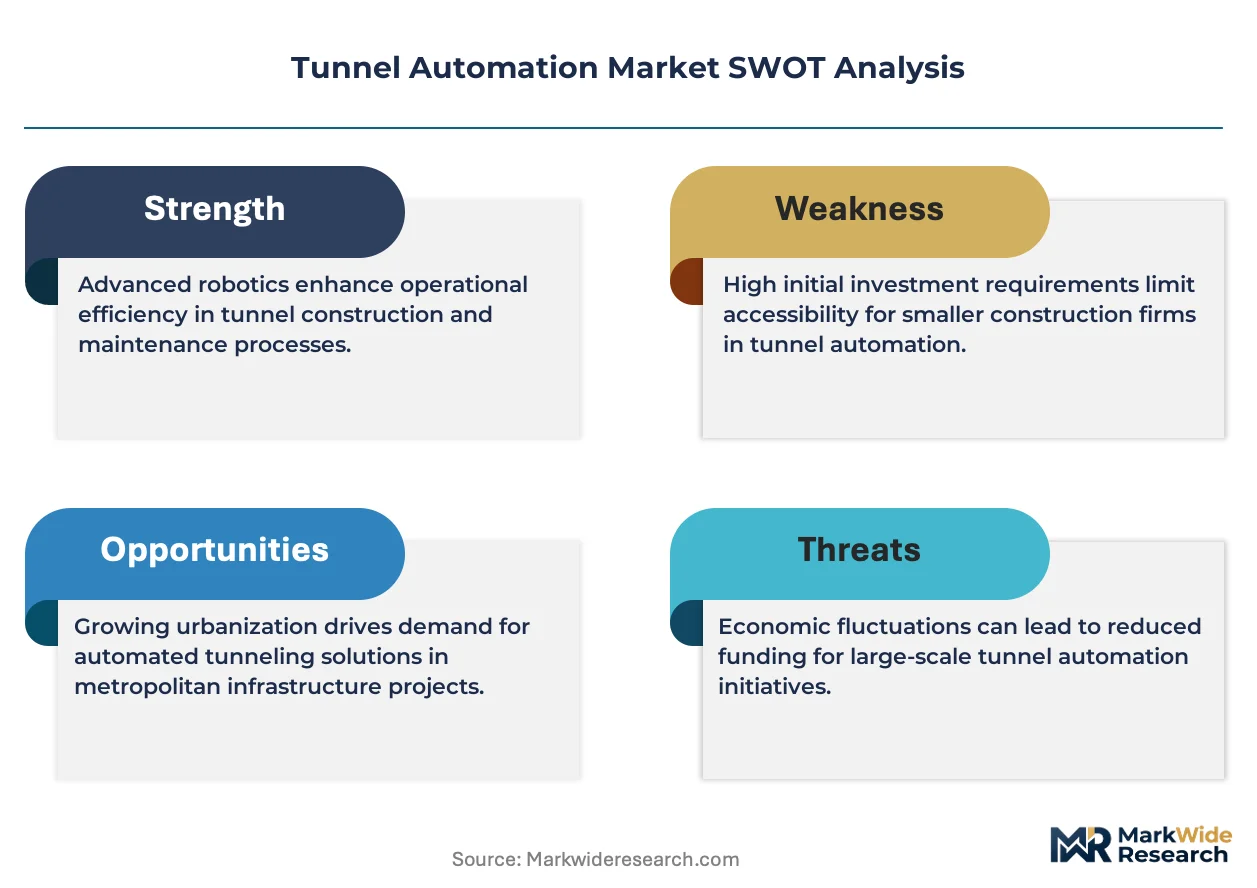
A small set of integrated leaders sits above a broader specialist tier, with capital-intensity divergence rotating competitive dynamics across contract types. Full-system integrators dominate turnkey tunnel management awards through bundled electrification and control portfolios. Component specialists capture margin pools in sensor arrays and predictive maintenance algorithms. Dominant competitive moves include strategic partnerships for cloud-native SCADA deployment and backward integration into silicon carbide power semiconductor sourcing.
Among German-based industrial conglomerates, Siemens AG exemplifies the integrated-leader archetype through its control and electrification portfolio breadth. Honeywell International Inc. and SICK AG occupy distinct specialist positions, with the former representing multi-industry automation incumbents and the latter anchoring the precision-sensor tier for environmental and traffic monitoring applications. These three entities collectively illustrate the market's vertical stratification between turnkey capability and component-level expertise.
| Leading Market Players |
|---|
| SICK AG |
| Honeywell International Inc. |
| Siemens AG |
| Indra Sistemas |
| Trane Technologies |
| Johnson Controls |
| Signify Holding BV |
| SICE |
| ABB Ltd |
| Others |
Value Chain & Pricing Dynamics
Ninety-to-120-day lead times for silicon carbide power modules and specialized tunnel-rated sensor housings concentrate procurement leverage among German and Swiss system integrators, compressing margin capture for component suppliers while elevating turnkey pricing power. This inventory intensity shapes how operators evaluate lifecycle contracts against upfront capital expenditure.
Pricing Analysis
After-sales service agreements covering predictive maintenance and firmware updates now drive lifetime value in tunnel automation procurement. Pricing stratifies across premium, standard, and economy tiers based on redundancy certification levels under BAV and KBA mandates and the scope of bundled availability guarantees. Cost compression in sensor arrays is intensifying because copper and rare earth concentrate volatility feeds through motor winding and particulate monitor production. Government transport ministries exhibit lowest price sensitivity due to regulatory compliance mandates, while infrastructure developers under availability-based contracts negotiate hardest on total cost of ownership.
Supply Chain Analysis
Inventory concentration for critical electromechanical components rests on German engineering clusters around Munich and Stuttgart, Swiss precision manufacturing in Ticino and Valais, and Chinese rare earth processing for sensor magnet assemblies. The supply chain draws from Chilean copper smelters, Chinese silicon carbide wafer foundries, and German variable-speed drive specialists. Single-source vulnerability in tunnel boring machine automation expertise creates bottleneck risk for cross-border Alpine corridor projects. Distribution runs through specialized systems integrators who bundle hardware procurement with decade-long maintenance contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Tunnel automation sits in early-cycle expansion as predictive maintenance algorithms penetrate subsea and Alpine networks previously served by reactive service models. Regulatory mandates for redundant safety architectures and F-Gas compliance accelerate replacement cycles beyond historical baselines.
For Market Incumbents: Compound technology leadership in integrated control architectures by deepening backward integration into silicon carbide power semiconductor sourcing and securing exclusive sensor calibration partnerships. Threats from cloud-native SCADA entrants and EU AI Act compliance costs demand defensive certification investments in algorithmic transparency documentation. Capacity addition in Norwegian and Austrian corridor markets anchors geographic lock-in against emerging specialist competitors. For New Entrants and Emerging Players: Predictive maintenance service gaps in legacy SCADA installations represent the most penetrable white-space target, particularly where human oversight interfaces for AI-driven incident classification remain undeveloped. Battery-electric ventilation retrofits in Austria's decarbonizing transport infrastructure offer second-entry traction. A go-to-market angle anchored in containerized software deployment bypasses hardware procurement bundling that favors established integrators. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with under-monetized tunnel automation divisions lacking lifecycle service infrastructure. Long-term viability hinges on positioning for availability-based contracting dominance as Swiss and Norwegian authorities unbundle hardware from maintenance procurement. The signal to watch is acceleration in robotic inspection service contract awards where premium margins concentrate.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Silicon Carbide Sourcing | Captive supply of power semiconductors secures margin recovery in regenerative braking applications for Alpine jet fan arrays. |
| Cloud-Native SCADA Platform Launch | Containerized control software enables multi-site operators to centralize tunnel management across dispersed corridors. |
| Robotic Inspection Service Expansion | Unmanned ground vehicles capture premium contracts in oxygen-depleted segments where human access carries prohibitive risk. |
| Battery-Electric Ventilation Partnership | Lithium-titanate storage integration addresses Austria's decarbonization targets for transport infrastructure emergency systems. |
| EU AI Act Compliance Certification | Documented training data provenance and human oversight interfaces satisfy algorithmic transparency mandates for incident detection. |
Study Parameters
Two parallel data streams informed the analysis: structured primary interviews with tunnel automation procurement directors, SCADA systems engineers, and BAV regulatory compliance officers across Germany, Switzerland, Norway, and Austria; and secondary validation through EU AI Act implementation guidance, KBA F-Gas retrofit specifications, BAV safety architecture mandates, and customs trade data for electromechanical component flows. Bottom-up segment sizing triangulated against top-down infrastructure budget allocations from national transport ministries.
Across the projection horizon, the analytical framework modeled technology segmentation by control system architecture, sensor density tiers, and algorithmic capability levels alongside application splits across transportation, mining, and utility tunnel contexts. CAGRs derived from replacement cycle acceleration under regulatory mandates and penetration curves for predictive maintenance adoption. Industry-specific inputs included BAV-mandated availability thresholds for smoke extraction sequences and KBA-driven variable-speed drive retrofit schedules.
Material uncertainties — copper and rare earth concentrate volatility, CE marking timeline extensions for autonomous algorithms, and subcontractor concentration in German-Swiss engineering clusters — sit outside the modeled envelope. Forecasts reflect assumptions about regulatory enforcement continuity and infrastructure budget prioritization. Revision becomes warranted when battery-electric ventilation adoption or cloud-native SCADA migration crosses acceleration thresholds in Alpine corridor tenders.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Automation Systems
Flushing Systems Market
Building Automation Systems
Dumbwaiter Lifts Market
Building Automation Systems
Residential Electric Underfloor Heating Market
Building Automation Systems
Underfloor Heating Actuator Market
Building Automation Systems
Building Information Management System Market
Building Automation Systems
Energy Efficient Elevators Market
Building Automation Systems
Europe Building Automation Systems Market
Building Automation Systems
Elevator Modernization Market
Building Automation Systems
Building Management System Market
Building Automation Systems
Europe Smart Windows Market
Building Automation Systems
Global Operating Equipment Room Market
Building Automation Systems
Smart Passenger Elevators Market
Building Automation Systems
Building Technologies Market
Building Automation Systems
Signage Market
Building Automation Systems
Electrochromic Glass Market
Building Automation Systems
Rotary Sprinkler System Market