
 Europe Building Automation Systems Market | 2026-2036
Europe Building Automation Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Building Automation Systems Market Foresight
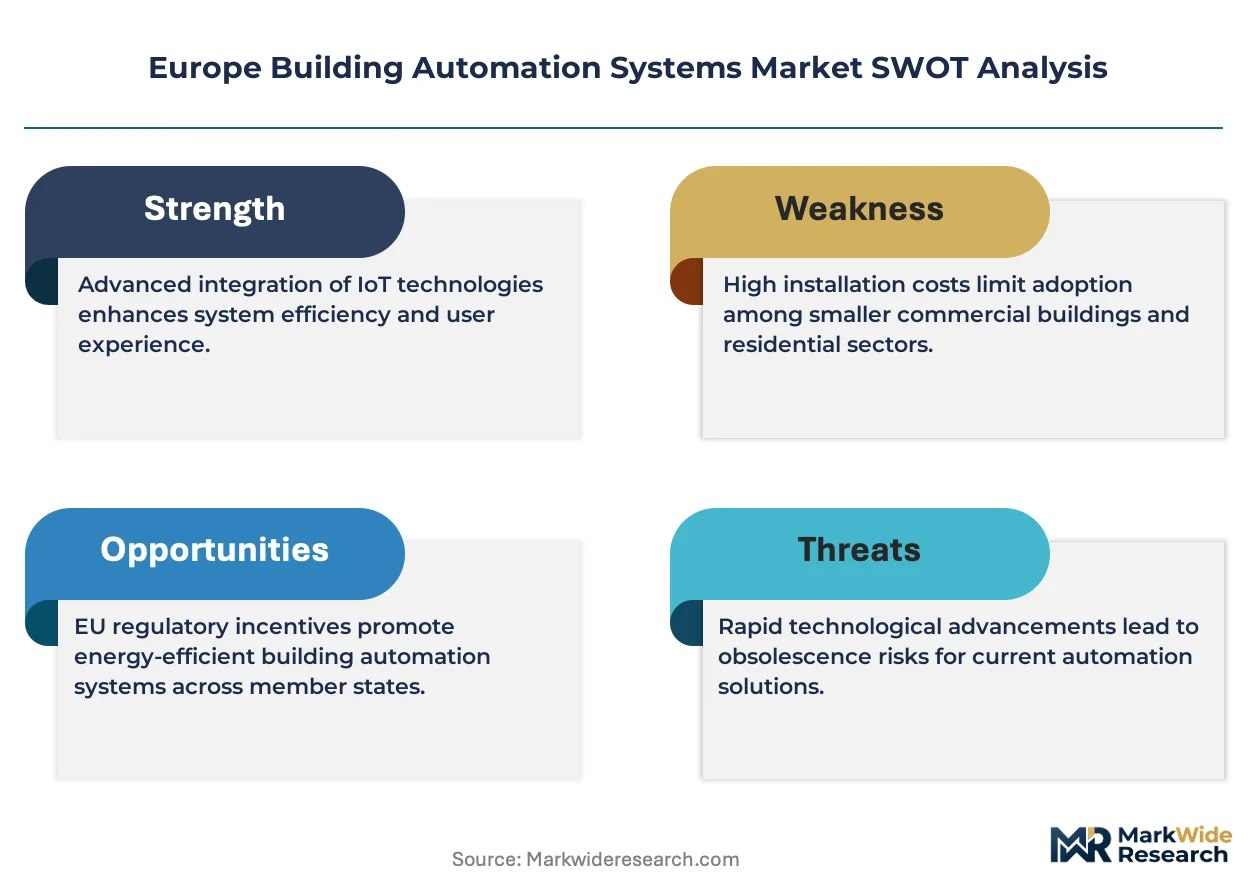
Project finance through energy performance contracting is tilting procurement power toward facility managers who lack upfront capital. Siemens AG leverages its hardware-software integration depth to dominate large commercial retrofit pipelines across German industrial zones. Schneider Electric SE anchors its position through EcoStruxure platform standardization, while Johnson Controls International plc specializes in OpenBlue digital twin deployments for healthcare and education campuses.
Building automation systems integrate sensors, controllers, and actuators to monitor and regulate mechanical, electrical, and plumbing infrastructure with response latencies below 100 milliseconds for critical HVAC loops. Their primary purpose is reducing operational energy expenditure while maintaining occupant comfort and safety compliance. HVAC Control commands the largest installed base across European commercial stock, though Energy Management captures expanding margin pools as utility tariffs fluctuate. Cloud-based Solutions within the Technology dimension are outpacing legacy centralized architectures in new specification cycles, particularly where remote portfolio management drives operational leverage for multi-site owners.
EU Green Deal carbon benchmarks and the F-Gas Regulation are tightening refrigerant and thermal efficiency standards, forcing controller upgrades across existing building stock. EMA energy efficiency directives and national transpositions in France, Italy, and Poland mandate sub-metering granularity that only modern automation architectures deliver. Stakeholders must weigh interoperability certification against vendor lock-in risk as open protocol adoption diverges across member state procurement codes.
Market Dynamics
EU Green Deal carbon benchmarks and the F-Gas Regulation are forcing controller upgrades across existing European commercial building stock, compressing technology refresh cycles from fifteen years to under eight in Nordic and German industrial corridors.
Growth Catalysts
- EMA Energy Efficiency Directives:National transpositions in France, Italy, and Poland mandate sub-metering granularity that only modern automation architectures deliver, compelling building owners toward comprehensive retrofits.
- Wireless IoT Sensor Networks:Municipal efficiency mandates in Nordic smart city corridors accelerate deployment of battery-powered environmental monitors that slash installation costs versus wired alternatives.
- Cloud-Based Energy Management:Multi-site commercial owners leverage remote portfolio management tools to centralize operational control across dispersed assets, reducing per-site engineering headcount requirements.
Market Restraints
- Semiconductor Supply Concentration:Controller manufacturers face extended lead times for specialized microcontrollers sourced from concentrated Asian foundry capacity, delaying project completions.
- Copper and Rare Earth Volatility:HVAC actuator and motor assemblies depend on copper windings and neodymium magnets whose price swings compress hardware margins unpredictably.
- Interoperability Certification Friction:Divergent open protocol adoption across German, French, and Dutch procurement codes forces vendors to maintain multiple certification tracks, elevating compliance overhead.
Strategic Opportunities
- Polish and Romanian Commercial Retrofits:These markets exhibit sub-thirty percent automation penetration in post-communist building stock, creating first-mover advantages for integrated platform vendors.
- Healthcare Digital Twin Convergence:OpenBlue-style deployments that merge building automation with clinical workflow optimization command premium pricing in hospital construction pipelines.
- Energy Performance Contracting:Project finance structures transfer upfront capital burden from facility managers to specialized ESCOs, expanding addressable customer base among capital-constrained municipalities.
Industry Challenges
- BACnet and KNX Integration Complexity:Legacy building management systems deployed in 1990s German industrial zones resist seamless protocol bridging, requiring costly gateway architectures and specialized commissioning engineers.
- Cybersecurity Certification Timelines:IEC 62443 compliance for cloud-connected controllers adds nine-to-fourteen month validation cycles that lag behind product development cadence.
- Cross-Border Technical Labor Mobility:Shortages of certified BMS programmers in Benelux markets force contractors to recruit from Eastern European training pipelines, inflating project wages.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Building Automation Systems Market |
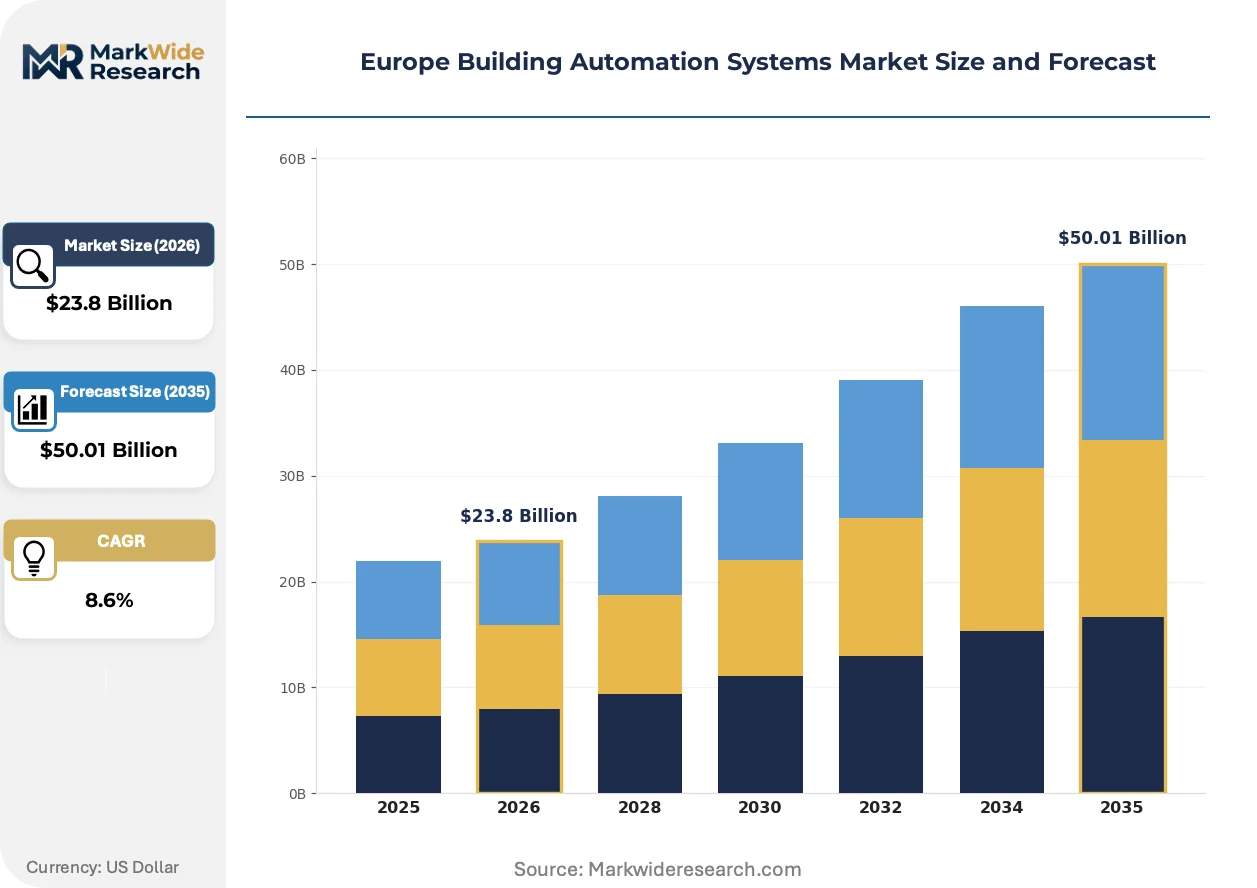
| Market Size in 2026 | $23.8 Billion |
| Market Size in 2035 | $50.01 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lighting Control, HVAC Control, Security Control, Energy Management Installation Type: New Installation, Retrofit Installation, Integrated Solutions, Expansion Projects End User: Commercial Buildings, Residential Buildings, Industrial Facilities, Government Infrastructure Technology: Internet of Things, Wireless Systems, Cloud-based Solutions, Centralized Control |
| Companies Covered | Siemens AG, Schneider Electric SE, Johnson Controls International plc, ABB Ltd, Honeywell International Inc., Robert Bosch GmbH, Kieback&Peter GmbH & Co. KG, Priva Holding BV, Trane Technologies plc, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Building Automation Systems Market Shifts & Advancements
Edge computing architectures and AI-driven predictive maintenance are compressing response latencies and shifting operational decision-making from centralized facilities teams to autonomous building systems.
Edge-native controllers with embedded machine learning inference engines are collapsing the distinction between sensing, control, and analytics layers that historically required separate hardware tiers. Healthcare and data center operators in the Netherlands and Ireland deploy these units to achieve sub-fifty-millisecond HVAC loop response without cloud dependency. The structural consequence is collapsing maintenance cost structures as predictive algorithms eliminate scheduled service intervals in favor of condition-based interventions.
The EU F-Gas Regulation mandates refrigerant phase-down schedules that force thermal system redesigns across European commercial stock. Equipment manufacturers must certify new low-global-warming-potential heat pumps and chillers that integrate with next-generation automation protocols. German industrial zones and French retail chains face the steepest compliance curves, accelerating specification of refrigerant-agnostic controller platforms.
Facility managers increasingly bundle automation procurement with long-term energy performance guarantees rather than capital purchase models. ESCOs and equipment-as-a-service providers displace traditional distributor channels in Nordic municipal and German healthcare verticals. This contractual pivot concentrates buying power among multi-site owners who demand standardized platforms across national portfolios, pressuring vendor pricing discipline.
Europe Building Automation Systems Market Segmentation
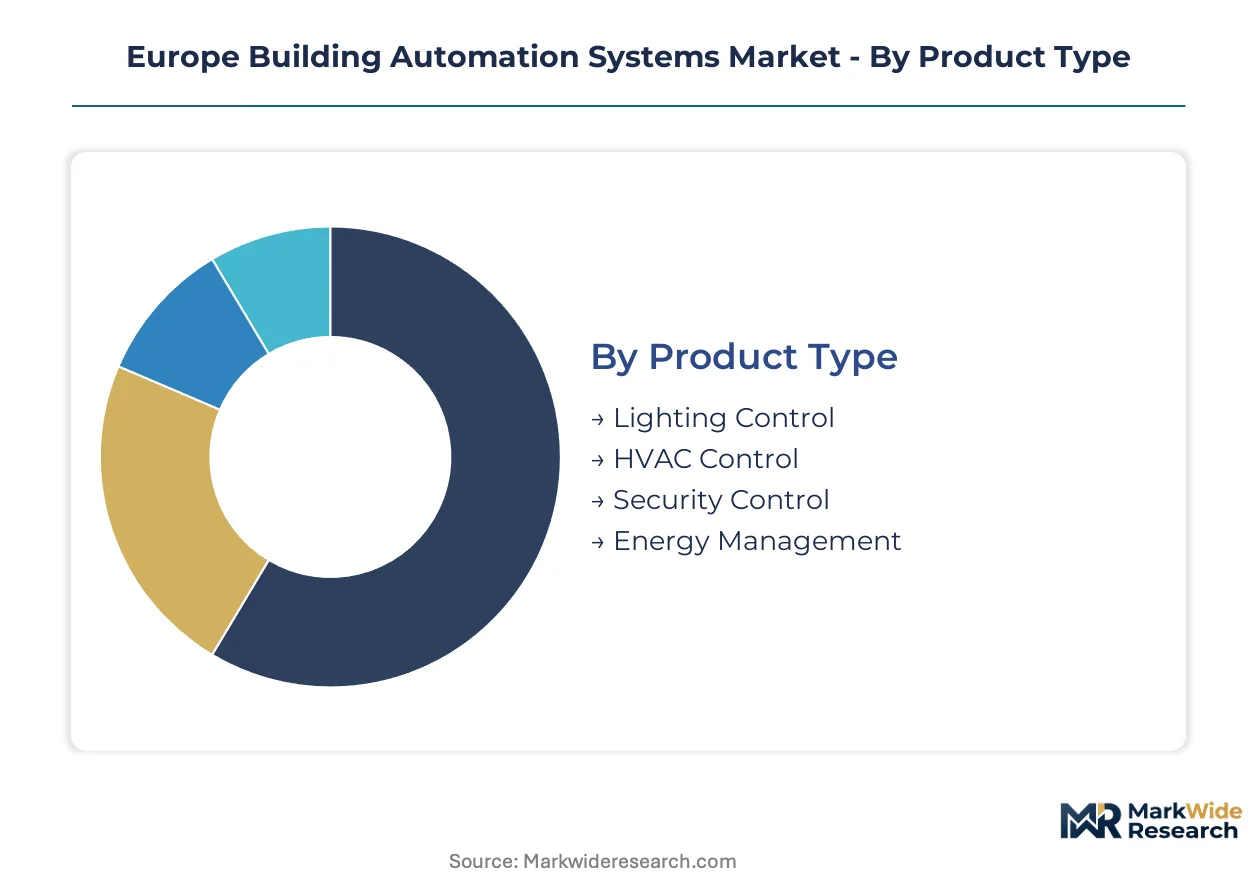
Building automation systems fragment across four structural dimensions that determine procurement workflows and technology specifications. Each category reflects distinct buyer priorities, from capital expenditure constraints in retrofit scenarios to cybersecurity requirements in cloud-connected deployments.
Product Type:
Mature control systems dominate installed base metrics while emerging platforms capture specification momentum in new construction pipelines.
- HVAC Control:Encompasses variable air volume controllers, chiller sequencing modules, and heat pump management units that regulate thermal loops with sub-100-millisecond response thresholds. German industrial zones and Dutch healthcare campuses drive replacement demand as F-Gas Regulation compliance forces refrigerant system overhauls requiring controller upgrades.
- Energy Management:Sub-metering dashboards and utility tariff optimization engines that aggregate consumption data across building systems. Nordic municipal portfolios and French retail chains concentrate procurement where EU Green Deal carbon benchmarking mandates granular visibility into scope 2 emissions.
- Lighting Control:Daylight harvesting sensors and circadian rhythm programming for commercial occupant wellness.
- Security Control:Integrated access and surveillance systems with building automation protocol bridging.
HVAC Control retains volume leadership; Energy Management holds the steepest expansion curve.
Installation Type:
Cost tier stratification separates capital-intensive new construction from operational-expenditure-driven retrofit models.
- Retrofit Installation:Wireless sensor overlays and controller gateway architectures that modernize legacy BACnet networks without structural demolition. Polish and Romanian commercial stock exhibits substantial penetration gaps, creating first-mover advantages for vendors offering protocol translation expertise.
- New Installation:Native IP-based control architectures specified during construction phase with embedded IoT connectivity. Netherlands data center corridors and Irish pharmaceutical manufacturing greenfield projects specify these systems for predictive maintenance integration from commissioning.
- Integrated Solutions:Single-contractor delivery combining mechanical, electrical, and digital infrastructure.
- Expansion Projects:Modular capacity additions to existing automation networks in growing commercial portfolios.
Retrofit Installation captures expanding margin pools; New Installation maintains premium pricing discipline.
End User:
Application intensity varies dramatically across customer types, with compliance burdens and operational complexity driving specification divergence.
- Commercial Buildings:Office towers, retail chains, and hospitality properties requiring tenant comfort optimization alongside energy cost containment. German logistics hubs and French supermarket networks deploy these systems where EMA energy efficiency directives mandate consumption transparency for properties exceeding threshold square footage.
- Industrial Facilities:Manufacturing plants and process environments with critical environmental control requirements. Benelux chemical processing and Italian automotive assembly lines specify hardened controllers for explosion-proof zones and washdown compliance.
- Government Infrastructure:Municipal buildings and public facilities subject to procurement code standardization.
- Residential Buildings:Multi-family housing with centralized plant automation and unit-level metering.
Commercial Buildings anchor revenue concentration; Industrial Facilities demonstrate the highest per-site technology spend.
Technology:
Supply concentration in semiconductor fabrication shapes availability timelines for advanced connectivity platforms.
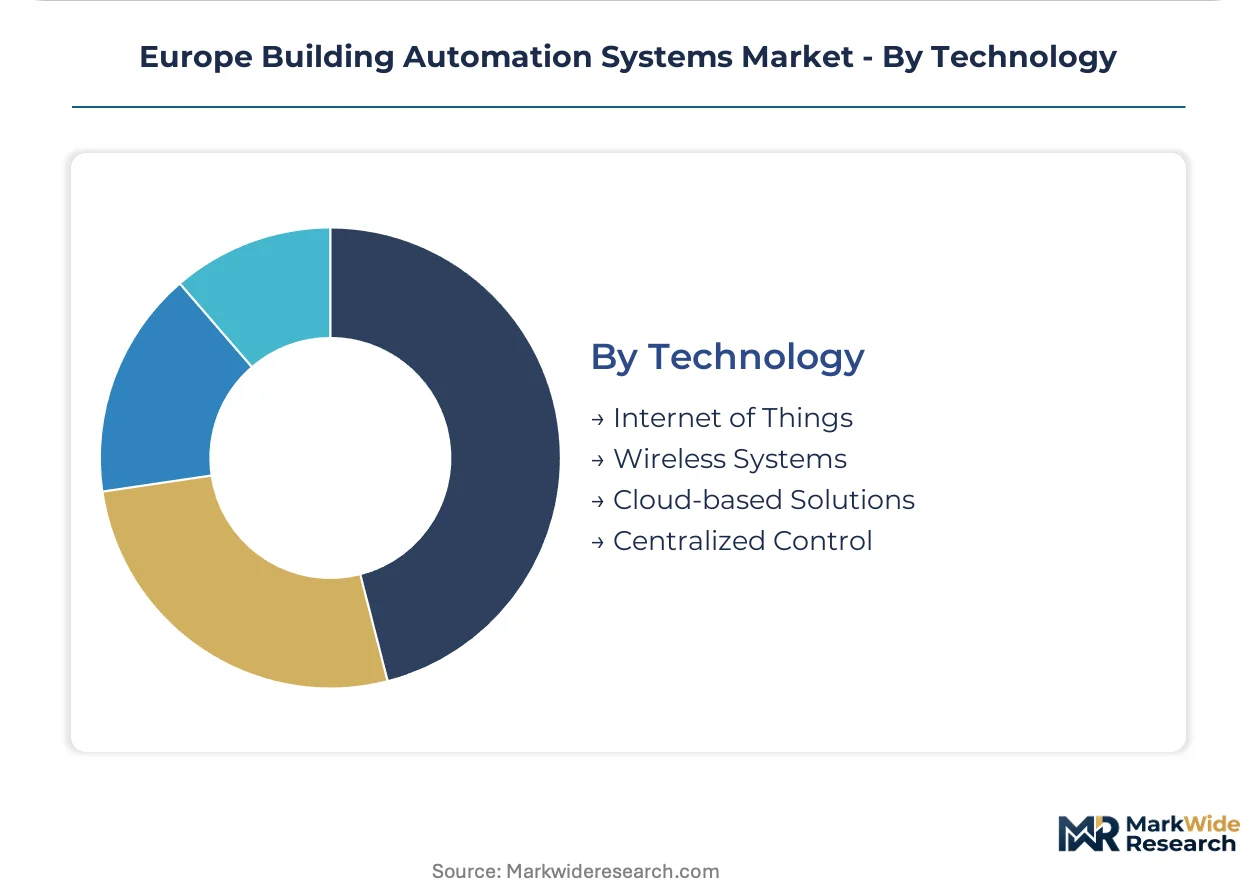
- Cloud-based Solutions:Browser-accessible energy dashboards and remote portfolio management platforms with API integration for third-party analytics. Nordic smart city corridors and German healthcare multi-site operators centralize operational control across dispersed assets, reducing per-location engineering headcount.
- Internet of Things:Battery-powered environmental sensors and edge-native controllers with embedded machine learning inference. Dutch hospital construction and Irish data center projects deploy these units for sub-fifty-millisecond HVAC loop response without cloud dependency.
- Wireless Systems:Mesh network protocols eliminating structured cabling in heritage building retrofits.
- Centralized Control:Legacy server-based architectures persisting in 1990s German industrial zone installations.
Cloud-based Solutions is gaining share fastest; Internet of Things climbs the fastest in new specification cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU Green Deal carbon benchmarks and national energy efficiency mandates are compressing technology refresh cycles across European commercial building stock, with retrofit intensity varying sharply by member state regulatory enforcement and existing automation penetration.
Germany
Industrial zone retrofits and F-Gas Regulation compliance are forcing controller upgrades across 1990s-era BACnet installations in the Ruhr and Bavarian manufacturing corridors. The national building energy ordinance mandates granular sub-metering for properties exceeding threshold consumption levels. Siemens AG anchors large commercial retrofit pipelines through hardware-software integration depth in Frankfurt-Rhine-Main logistics hubs.
France
EMA energy efficiency directive transpositions require consumption transparency for retail chains and supermarket networks exceeding square footage thresholds. ANSM and national regulators enforce refrigerant phase-down schedules that accelerate thermal system redesigns. Paris-Île-de-France office towers and Lyon-Auvergne-Rhône-Alpes healthcare campuses concentrate specification of refrigerant-agnostic controller platforms.
Netherlands
Data center construction in Amsterdam-Rotterdam corridors and hospital digital twin deployments drive demand for edge-native controllers with sub-fifty-millisecond HVAC response. Municipal efficiency mandates in Randstad smart city corridors accelerate wireless IoT sensor deployment. Cloud-based energy management platforms centralize operational control across dispersed multi-site healthcare and pharmaceutical manufacturing portfolios.
Poland
Post-communist commercial stock exhibits sub-thirty percent automation penetration, creating first-mover advantages for vendors offering protocol translation expertise. National transpositions of EMA directives mandate sub-metering granularity that legacy systems cannot deliver. Warsaw and Kraków municipal buildings concentrate energy performance contracting structures that transfer upfront capital burden to specialized ESCOs.
Nordic Region
Swedish and Danish municipal efficiency mandates accelerate battery-powered environmental sensor networks that slash installation costs versus wired alternatives. Norwegian and Finnish smart city corridors specify cloud-based portfolio management tools for multi-site owners. Stockholm, Copenhagen, and Oslo healthcare and education campuses deploy OpenBlue-style digital twin configurations that merge building automation with operational workflow optimization.
Europe Building Automation Systems Market Competitive Landscape
On the supply side, the industry is consolidating around integrated platform vendors capable of delivering hardware-software stacks across fragmented national procurement codes. Tiered competitive dynamics separate full-stack industrial conglomerates from specialized automation boutiques and regional system integrators. Dominant competitive moves include M&A activity targeting protocol translation capabilities and strategic partnerships with ESCOs to access capital-constrained municipal segments.
Within the full-stack tier, Siemens AG, Schneider Electric SE, and Johnson Controls International plc exemplify divergent strategic positioning. Siemens anchors large commercial retrofit pipelines through German industrial zone presence. Schneider occupies a position defined by EcoStruxure platform standardization across multi-site portfolios. Johnson Controls sits within the healthcare-education specialization vector through OpenBlue digital twin deployments. These three entities represent the competitive archetypes shaping procurement outcomes across EU member states.
| Leading Market Players |
|---|
| Siemens AG |
| Schneider Electric SE |
| Johnson Controls International plc |
| ABB Ltd |
| Honeywell International Inc. |
| Robert Bosch GmbH |
| Kieback&Peter GmbH & Co. KG |
| Priva Holding BV |
| Trane Technologies plc |
| Others |
Supply & Pricing Matrix
Semiconductor supply concentration in Asian foundry capacity determines both pricing tier spreads and supply chain shape across European building automation markets, compressing hardware margins while elongating lead times for controller manufacturers.
Pricing Analysis
Certification level creates the primary spread between IEC 62443-compliant cloud-connected controllers and uncertified legacy alternatives. Three-tier pricing structure across premium, standard, and economy levels reflects cybersecurity validation depth, volume scale, and after-sales service bundling. Pricing pressure stems from copper and rare earth volatility in HVAC actuator assemblies. Municipal ESCOs in Poland and Romania exhibit highest price sensitivity; Dutch data center operators demonstrate lowest sensitivity due to uptime-critical specifications.
Supply Chain Analysis
TSMC and Samsung Foundry hold concentrated capacity for specialized microcontrollers powering edge-native controllers. Manufacturing draws from Taiwan, South Korea, and Germany for silicon fabrication, PCB assembly, and final system integration respectively. Controller production rests on copper windings, neodymium magnets, and silicon carbide substrates. Single-source vulnerability in advanced node semiconductors threatens project completion timelines. Distribution runs through authorized system integrators and ESCO partnership channels rather than direct OEM sales.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU F-Gas Regulation refrigerant phase-down schedules constitute a technological-regulatory inflection that compresses technology refresh cycles and opens retrofit pipelines across European commercial building stock.
For Market Incumbents: Entrench protocol translation capabilities through targeted acquisitions of BACnet-KNX gateway specialists to defend against interoperability friction in German industrial zones. Expand captive semiconductor inventory positions to mitigate foundry lead time volatility threatening project completions.
For New Entrants and Emerging Players: Mid-market commercial buildings in Polish and Romanian post-communist stock represent the most penetrable entry point given sub-thirty percent automation penetration and ESCO-financed procurement models. Energy performance contracting structures offer a direct go-to-market angle bypassing capital-constrained facility manager budgets.
For Investors and Strategic Acquirers: EMA energy efficiency directive transpositions reshape the acquisition landscape by mandating sub-metering granularity that only modern architectures deliver. Five-to-ten year viability favors platform vendors with integrated hardware-software stacks over point-solution boutiques. Monitor Nordic municipal procurement standardization as an inflection indicator for portfolio-wide platform consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| Acquisition of Protocol Translation Specialist | Eliminates gateway complexity barriers in 1990s German BACnet installations. |
| ESCO Partnership Program | Unlocks capital-constrained municipal segments through performance contracting structures. |
| Edge-Native Controller Launch | Captures Dutch healthcare and Irish data center demand for sub-fifty-millisecond response. |
| IEC 62443 Certification Investment | Accelerates nine-to-fourteen month cybersecurity validation cycles for cloud-connected portfolios. |
| Polish-Romanian Distribution Expansion | Establishes first-mover positioning in sub-thirty percent penetration post-commercial stock. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with building automation system integrators, facility managers at multi-site commercial portfolios, and ESCO project developers; and secondary validation against EU regulatory filings, national energy agency consumption databases, and semiconductor trade flow records. Bottom-up and top-down triangulation cross-referenced controller shipment volumes with building stock retrofit penetration estimates.
Forecast inputs considered product type segmentation across HVAC control, energy management, lighting control, and security control; installation type splits between retrofit and new construction; and technology adoption curves for cloud-based versus edge-native architectures. CAGRs were derived from installed base replacement cycles, regulatory compliance deadlines, and utility tariff optimization payback periods. Modeled variables included F-Gas Regulation phase-down schedules and EMA directive transposition timelines.
Macroeconomic conditions sit as an overlay; deviation in construction investment cycles, utility tariff structures, or semiconductor foundry capacity allocation would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory enforcement consistency and technology refresh elasticity. Quarterly review of Nordic municipal procurement awards and German industrial zone retrofit permit filings is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Automation Systems
Building Information Management System Market
Building Automation Systems
Computer-Aided Facility Management (CAFM) Market
Building Automation Systems
Escalator Market
Building Automation Systems
Asia-Pacific Building Automation System Market
Building Automation Systems
Global Platform Screen Doors for Subway Lines Market
Building Automation Systems
Europe Smart Windows Market
Building Automation Systems
AEC Market
Building Automation Systems
Global Nordic Building Automation and Control Market
Building Automation Systems
Zero Energy Buildings Market
Building Automation Systems
Europe HVAC Controls Market
Building Automation Systems
Global Modularization Market
Building Automation Systems
LAMEA Building Automation System Market
Building Automation Systems
Platform Screen Door System Market
Building Automation Systems
Intelligent Building Automation Technologies Market
Building Automation Systems
Building Automation System Market
Building Automation Systems
Elevator Modernization Market