
 Building Technologies Market | 2026-2036
Building Technologies Market Size, Share, and Industry Trends Forecast 2026-2036
Building Technologies Market Insights
Modular system bundling is expanding buyer choice across the building technologies sector, enabling facility managers to mix HVAC, lighting, and security components from multiple suppliers rather than accepting rigid all-in-one packages. Honeywell International Inc. leverages its deep automation portfolio to anchor long-term service contracts in North American commercial real estate. Siemens AG competes through its building management software layer, while Schneider Electric SE differentiates via energy management integration that ties directly to utility tariff optimization.
Building technologies encompass electromechanical systems, control platforms, and software architectures that regulate indoor environmental quality, energy consumption, and operational security across built structures. These systems typically integrate sensors, actuators, and networked controllers to maintain temperature setpoints, illuminance levels, and access protocols within defined performance envelopes. HVAC Systems and Smart Building Technology represent the most capital-intensive segments, with the former carrying mature replacement cycles and the latter capturing expanding margin pools through software subscription models. Energy Management Systems within the technology dimension are attracting disproportionate R&D allocation as building owners face escalating carbon compliance obligations.
The EU Green Deal and F-Gas Regulation in Europe, alongside the EPA's phasedown rules in the United States, are reshaping refrigerant choices and thermal system specifications across new construction and retrofit activity. CE marking and MDR-equivalent conformity requirements for building safety components create non-tariff barriers that favor established suppliers with certified product lineups. Stakeholders must monitor how fragmented municipal energy codes converge or diverge, as this determines whether platform investments scale across jurisdictions or remain trapped in single-market deployments.
Market Dynamics
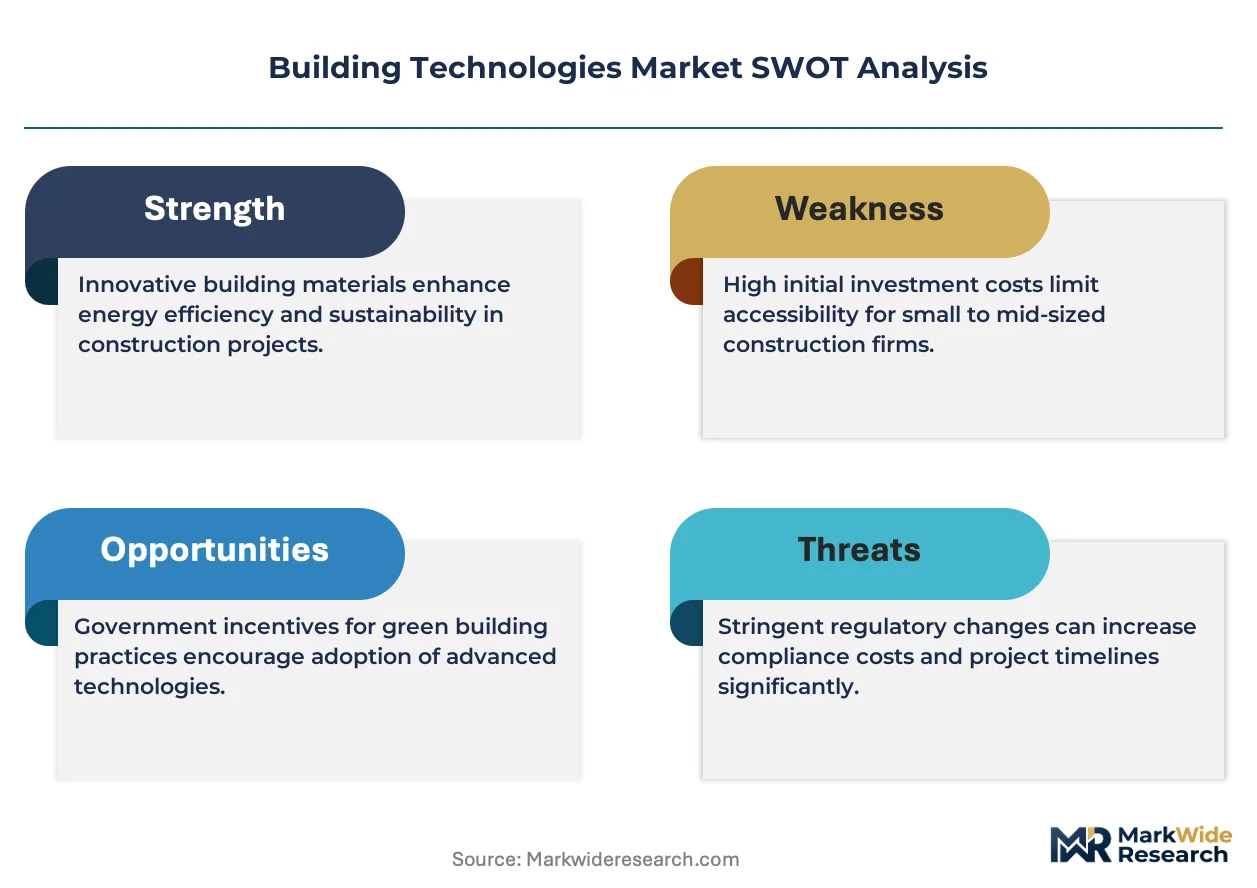
Retrofit mandates across the European Union are compressing replacement cycles for thermal systems and forcing building owners toward integrated automation platforms rather than point solutions. This regulatory pressure is restructuring supplier relationships and accelerating consolidation among controls specialists.
Growth Catalysts
- EU F-Gas Regulation:Phasedown schedules for hydrofluorocarbon refrigerants are compelling commercial facility managers to replace aging HVAC infrastructure with lower-GWP alternatives ahead of mechanical failure.
- Smart metering infrastructure:Utility-scale deployment of interval meters and time-of-use tariffs is creating immediate demand for building-level energy management systems that can automate load response.
- German municipal procurement:Public building renovation programs tied to federal climate targets are generating concentrated tender volume for integrated building automation across schools, hospitals, and administrative portfolios.
Market Restraints
- Semiconductor input volatility:Protracted lead times for industrial-grade sensors and microcontrollers are extending project timelines and inflating system costs for controls manufacturers.
- Installer capacity constraints:Certified building automation technicians remain concentrated in Northern European markets, creating execution bottlenecks for retrofit programs in Southern and Eastern Europe.
- Legacy protocol fragmentation:Persistent incompatibility between BACnet, Modbus, and proprietary vendor protocols forces costly middleware development and fragments platform ecosystems.
Strategic Opportunities
- Polish commercial real estate:Accelerating green building certification requirements and EU cohesion fund access are opening underserved demand for HVAC modernization in Warsaw and Kraków office markets.
- Grid-interactive thermal storage:Convergence of heat pump technology with phase-change materials is enabling new revenue streams from frequency regulation services and demand response aggregation.
- France's RE2020 building code:Stricter energy performance thresholds for new construction are mandating digital twin integration during design phase, expanding software subscription attach rates.
Industry Challenges
- Cybersecurity certification delays:IEC 62443 compliance timelines for building control networks are lagging behind insurer requirements, exposing asset owners to coverage gaps and liability uncertainty.
- Cross-trade coordination:Integration of mechanical, electrical, and digital systems demands project management capabilities that traditional HVAC contractors and IT integrators rarely possess in combined form.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Building Technologies Market |
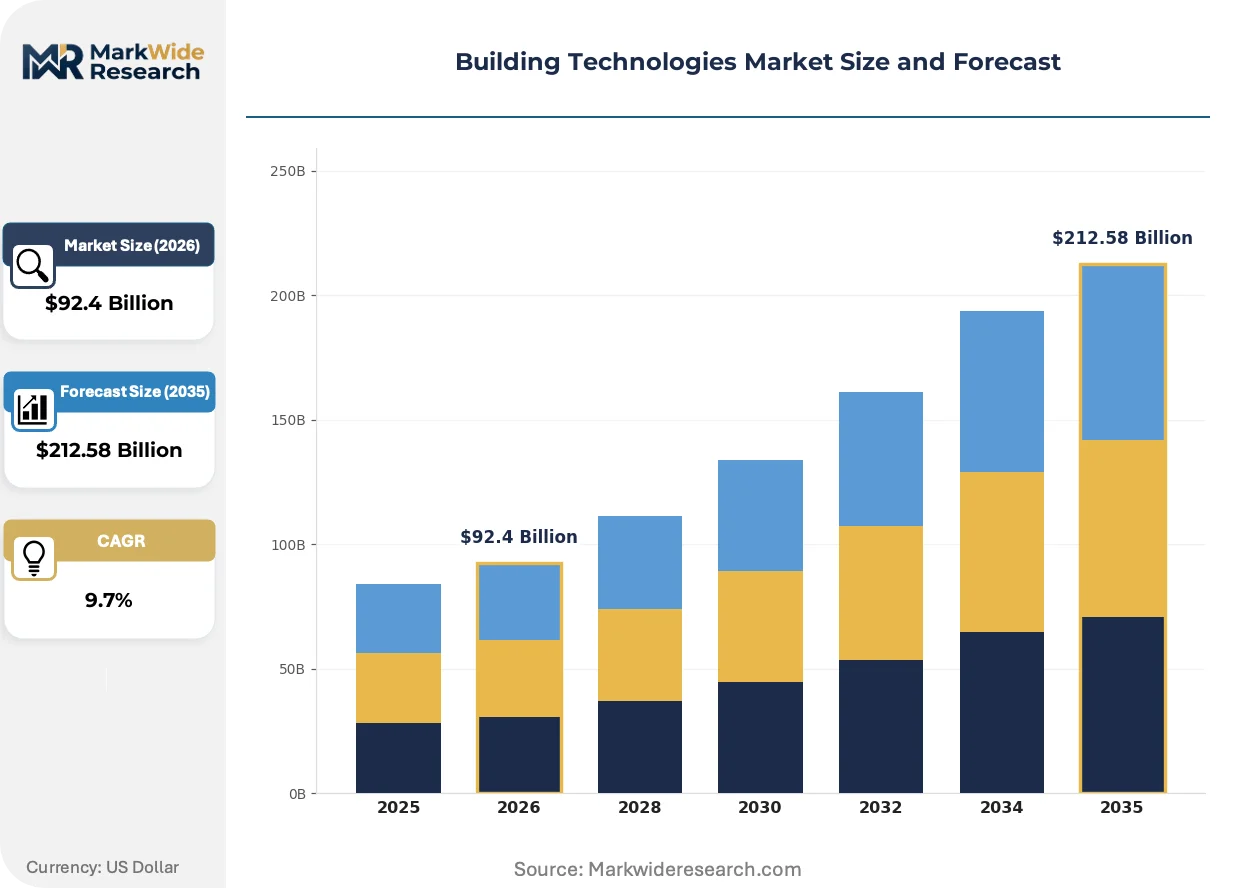
| Market Size in 2026 | $92.4 Billion |
| Market Size in 2035 | $212.58 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: HVAC Systems, Lighting Solutions, Security Systems, Smart Building Technology Application: Residential Buildings, Commercial Infrastructure, Industrial Facilities, Educational Establishments Technology: Energy Management Systems, Building Management Systems, IoT Integration, Automation Solutions End User: Contractors, Property Developers, Facility Managers, Government Agencies |
| Companies Covered | Honeywell International Inc., Schneider Electric SE, Siemens AG, Johnson Controls International plc, ABB Ltd., Carrier Global Corporation, Trane Technologies plc, Eaton Corporation, Rockwell Automation, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Building Technologies Market Trends and Innovations
Digital twin technology is migrating from design-phase visualization into operational optimization, compressing the feedback loop between building performance data and system configuration. This shift is redrawing competitive boundaries between hardware OEMs and software-native platforms.
Fault detection and diagnostics (FDD) software is automating anomaly identification in HVAC performance data streams, reducing technician dispatch frequency for commercial portfolios. Large facility management firms in the United States are deploying FDD across multi-site contracts to standardize maintenance protocols. The technology is automating work order generation and prioritization, displacing reactive service models with condition-based intervention schedules.
The EPA's phasedown rules under the American Innovation and Manufacturing Act are accelerating refrigerant transition timelines for commercial rooftop units and chillers. Equipment manufacturers must now certify new product lines for A2L mildly flammable alternatives ahead of previous market expectations. Cold storage and supermarket operators face compressed replacement windows as reclaimed R-404A supplies tighten and service costs escalate.
Subscription-based building performance contracts are displacing traditional equipment procurement with guaranteed energy savings arrangements. Institutional investors and REITs are favoring vendors that assume operational risk and compensate shortfalls through service credits. This model is most visible in German and Dutch commercial office markets where green lease clauses require documented carbon performance.
Building Technologies Market Segmentation
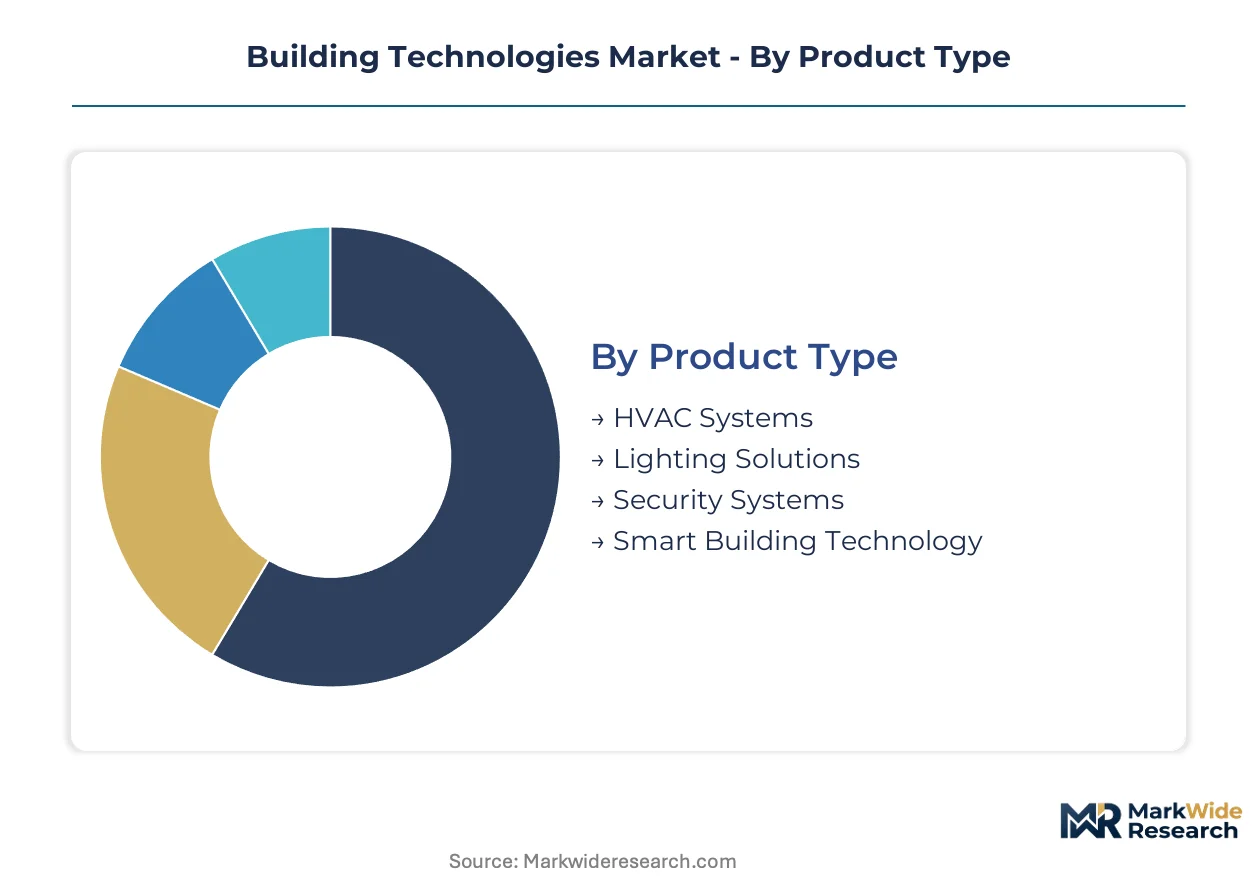
Building technologies span electromechanical hardware, control platforms, and software architectures with diverging margin profiles and replacement cycles. Segmentation reveals where capital concentrates versus where subscription revenue is displacing equipment sales.
Product Type:
Volume-weighted procurement favors established mechanical systems, while premium margins accrue to software-enabled platforms with recurring revenue models.
- HVAC Systems:Thermal regulation equipment including chillers, heat pumps, and air handling units specified by tonnage and efficiency ratings. German municipal retrofit programs and F-Gas Regulation compliance deadlines are compressing replacement timelines across commercial portfolios in Frankfurt, Munich, and Hamburg.
- Smart Building Technology:Integrated sensor networks, edge computing nodes, and cloud-based analytics platforms that optimize environmental controls through machine learning algorithms. Property developers in the Netherlands and Denmark are mandating digital twin integration during design phase, expanding software subscription attach rates.
- Lighting Solutions:LED fixtures with networked controls and daylight harvesting capabilities.
- Security Systems:Access control, video surveillance, and intrusion detection with building management system integration.
Mature deployment sits with HVAC Systems. Newer deployment is concentrated in Smart Building Technology.
Application:
End-use differentiation separates price-sensitive residential retrofits from performance-guaranteed commercial contracts with operational risk transfer.
- Commercial Infrastructure:Office towers, retail centers, and hospitality properties requiring 24/7 environmental control with SLA-backed uptime guarantees. Institutional investors and REITs in Germany and the Netherlands are favoring vendors that assume operational risk through guaranteed energy savings arrangements.
- Educational Establishments:Schools, universities, and research facilities with intermittent occupancy patterns and public procurement constraints. Federal climate targets in Germany are generating concentrated tender volume for integrated building automation across municipal school and hospital portfolios.
- Residential Buildings:Single-family and multi-family dwellings with fragmented owner decision-making.
- Industrial Facilities:Manufacturing plants and warehouses with process-critical environmental requirements.
Capital deployment concentrates in Commercial Infrastructure. Fastest expansion is occurring in Educational Establishments.
Technology:
Architecture layers separate commodity controls from platforms capturing margin through energy arbitrage and demand response aggregation.
- Energy Management Systems:Software platforms that monitor consumption patterns, automate load shifting, and optimize utility tariff exposure. Utility-scale deployment of interval meters and time-of-use tariffs in Italy and Spain is creating immediate demand for building-level systems that automate load response.
- IoT Integration:Sensor networks, edge gateways, and protocol translation layers enabling interoperability across vendor ecosystems. Persistent incompatibility between BACnet, Modbus, and proprietary vendor protocols forces costly middleware development that fragments platform ecosystems.
- Building Management Systems:Centralized control platforms for HVAC, lighting, and security coordination.
- Automation Solutions:Rule-based and AI-driven control logic for environmental setpoint optimization.
Established penetration characterizes Building Management Systems. Steepest expansion trajectory belongs to Energy Management Systems.
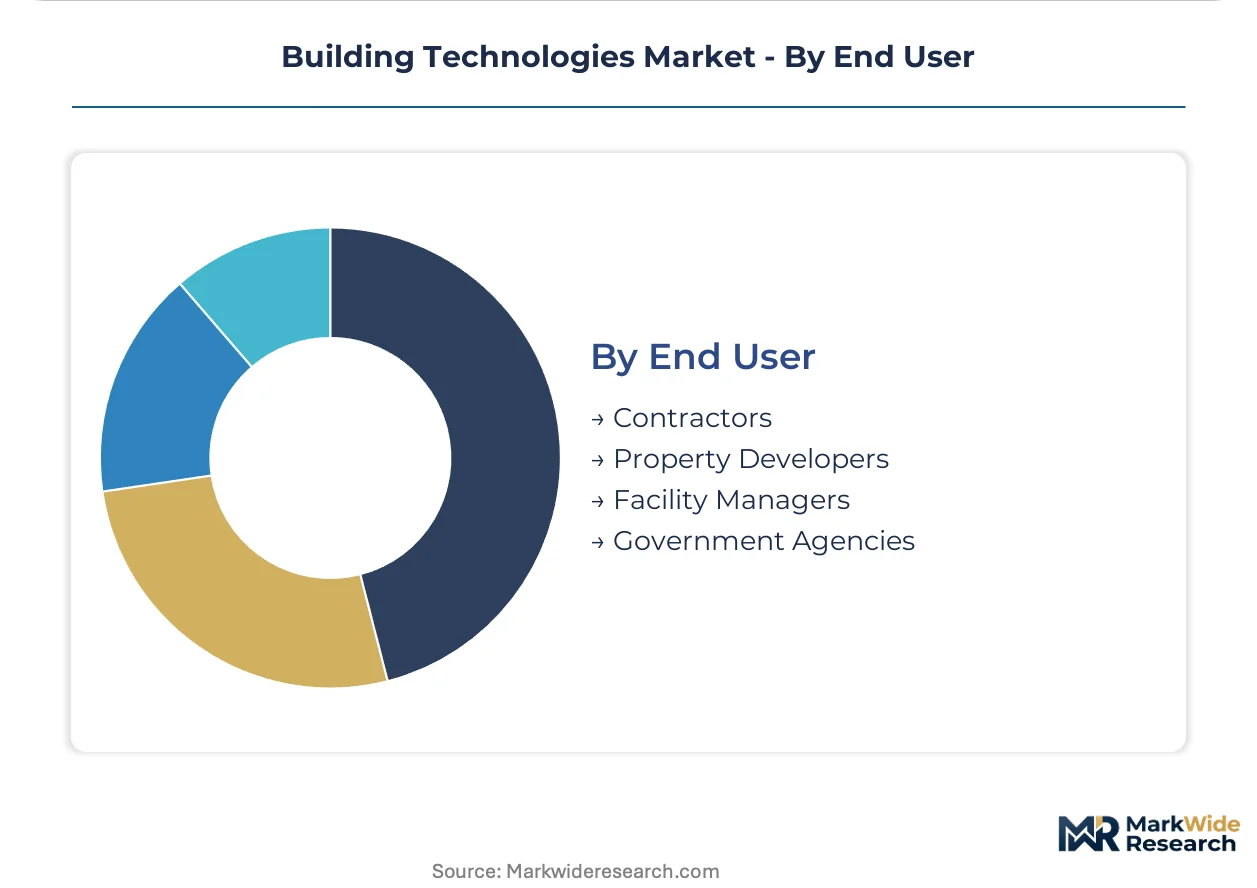
End User:
Procurement authority determines specification rigor and contract structure, from lowest-bid public tenders to performance-based private arrangements.
- Facility Managers:Professional operators of multi-site commercial portfolios with standardized maintenance protocols and FDD software deployment. Large facility management firms in the United States are deploying fault detection and diagnostics across multi-site contracts to standardize intervention schedules.
- Government Agencies:Public building owners bound by federal climate targets, green procurement rules, and documented carbon performance requirements. EU cohesion fund access and green building certification requirements are opening demand for HVAC modernization in Polish municipal portfolios.
- Contractors:Installation and integration specialists bidding on construction and retrofit projects.
- Property Developers:New construction sponsors specifying systems during design phase with lifecycle cost considerations.
Traditional purchasing authority rests with Contractors. Accelerating specification influence is shifting toward Facility Managers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany consumes the largest share of building automation systems in Europe, while the United States drives North American procurement through federal energy mandates. China and India are expanding domestic manufacturing capacity to serve accelerating retrofit demand across Asia-Pacific.
Germany
Federal climate targets and municipal procurement rules are compressing HVAC replacement cycles across public building portfolios. The F-Gas Regulation mandates hydrofluorocarbon phasedown schedules that force facility managers toward lower-GWP alternatives. Frankfurt, Munich, and Hamburg concentrate tender volume for integrated building automation in schools and hospitals.
United States
Commercial real estate investors and REITs are favoring vendors that assume operational risk through guaranteed energy savings arrangements. EPA phasedown rules under the American Innovation and Manufacturing Act are accelerating refrigerant transitions for rooftop units and chillers. Large facility management firms deploy fault detection and diagnostics across multi-site contracts to standardize maintenance protocols.
China
Dual carbon goals and building energy efficiency standards are mandating smart metering infrastructure and automated load response systems. The Ministry of Ecology and Environment enforces tightening emissions benchmarks for commercial construction. Yangtze River Delta cities including Shanghai and Hangzhou are piloting digital twin integration during design phase.
India
Green building certification requirements and smart city initiatives are opening demand for HVAC modernization across commercial office markets. The Bureau of Indian Standards certifies building safety components that create compliance barriers for uncertified suppliers. Maharashtra and Karnataka host concentrated deployment of energy management systems in Mumbai and Bangalore tech corridors.
Poland
EU cohesion fund access and accelerating green building certification requirements are driving procurement in Warsaw and Kraków office markets. CE marking requirements for building automation components favor established suppliers with certified product lineups. Municipal renovation programs are generating tender volume for integrated systems across public administrative portfolios.
Building Technologies Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across the building technologies sector. Tier-one suppliers anchor long-term service contracts through automation portfolios, while mid-tier controls specialists capture retrofit opportunities through software subscription models. Strategic consolidation and platform ecosystem expansion represent the dominant competitive moves as regulatory compliance costs rise.
Within the diversified industrial tier, Honeywell International Inc., Siemens AG, and Schneider Electric SE exemplify contrasting strategic positioning. The US-based conglomerate leverages deep automation expertise to anchor service contracts in commercial real estate. The German engineering group competes through building management software layers that integrate across mechanical systems. The French energy specialist differentiates via utility tariff optimization and energy management integration.
| Leading Market Players |
|---|
| Honeywell International Inc. |
| Schneider Electric SE |
| Siemens AG |
| Johnson Controls International plc |
| ABB Ltd. |
| Carrier Global Corporation |
| Trane Technologies plc |
| Eaton Corporation |
| Rockwell Automation, Inc. |
| Others |
Pricing and Supply Chain Analysis
F-Gas Regulation compliance deadlines across Germany, France, and the Netherlands are forcing facility managers toward lower-GWP refrigerant systems and integrated automation platforms, compelling suppliers to absorb certification costs and restructure component sourcing while passing selective premiums to buyers with carbon-mandated procurement requirements.
Pricing Analysis
Margin tightening in mid-tier HVAC equipment reflects semiconductor input volatility and extended lead times for industrial-grade sensors. Subscription-based building performance contracts are displacing transactional equipment sales, with pricing stratifying across premium certified systems, standard integrated platforms, and economy point solutions. Cost-down pressure on controls hardware accelerates because installer capacity constraints in Southern Europe limit execution scale. Government agencies with federal climate mandates show lowest price sensitivity; residential developers in fragmented markets exhibit highest.
Supply Chain Analysis
Industrial-grade microcontroller supply rests on Taiwanese and South Korean foundry capacity, with German and Chinese manufacturers dominating heat pump compressor production. Critical inputs span refrigerants, copper tubing, and edge computing nodes. Single-source vulnerability concentrates in advanced sensor modules for IoT integration. Distribution runs through certified building automation integrators with regional service territories, supplemented by direct OEM relationships for large commercial portfolios.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The building technologies sector is consolidating around platform ecosystems as EU regulatory compliance costs and cybersecurity certification requirements eliminate sub-scale controls specialists.
For Market Incumbents: Deploy software layer acquisitions to anchor long-term service contracts against pure-play FDD vendors. Integrate energy management capabilities with utility tariff optimization to defend margin pools in Dutch and German commercial real estate. Address cybersecurity certification delays through IEC 62443 pre-compliance investments before insurer mandates harden. For New Entrants and Emerging Players: The gap between premium digital twin-integrated systems and economy BACnet retrofit kits opens white-space in Polish municipal procurement and Indian smart city deployments. Target facility management firms with multi-site portfolios lacking standardized FDD deployment. Lead with grid-interactive thermal storage aggregation services to bypass incumbent hardware relationships. For Investors and Strategic Acquirers: The window for entry favors mid-tier controls specialists with certified product lineups and established CE marking pathways. Long-term viability centers on software attach rates and recurring revenue share within institutional investor portfolios. Watch German municipal tender volume as inflection indicator for EU retrofit program acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Consolidates HVAC, lighting, and security controls under unified software architecture for municipal portfolios. |
| Acquisition of Specialist Firm | Captures FDD software capabilities and technician networks to accelerate multi-site service contract penetration. |
| Geographic Expansion | Establishes certified installer capacity in Warsaw and Kraków to capture EU cohesion fund-driven retrofit demand. |
| Strategic Partnership | Links heat pump OEMs with phase-change material suppliers for frequency regulation revenue streams. |
| Green Certification Program | Aligns product portfolios with RE2020 digital twin mandates and green lease clause requirements in French new construction. |
Research Methodology
Multi-period observation of municipal tender volumes, refrigerant transition timelines, and smart meter deployment rates anchored the trend analysis, supplemented by interviews with facility management executives, building automation integrators, energy procurement officers, and controls engineering directors. Secondary validation drew from EU F-Gas Regulation filings, EPA AIM Act implementation documents, German federal climate target progress reports, and utility tariff structure disclosures. Bottom-up project pipeline assessment triangulated against top-down regulatory mandate scaling.
The input-output matrix linked technology adoption curves to capital expenditure flows across product type, application, and technology segmentation dimensions. CAGRs were derived from installed base turnover modeling and compliance-driven replacement cycle compression. Forecast inputs incorporated F-Gas phasedown schedules, RE2020 building code enforcement trajectories, and grid-interactive thermal storage pilot program expansion across the analysis window.
Inputs from regulatory filing databases and utility infrastructure disclosure reports were available through the study window; gaps in real-time installer capacity utilization data introduce uncertainty bands around Southern and Eastern European execution timelines. Forecasts reflect documented assumption sets regarding municipal procurement acceleration and semiconductor supply normalization. A small set of triggers—cybersecurity certification timeline shifts, refrigerant reclamation supply constraints, and municipal energy code convergence patterns—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Automation Systems
Building Analytics Market
Building Automation Systems
Residential Electric Underfloor Heating Market
Building Automation Systems
Building-To-Grid Technology Market
Building Automation Systems
Global Enterprise Building Solutions Market
Building Automation Systems
Building Information Management System Market
Building Automation Systems
Dumbwaiter Lifts Market
Building Automation Systems
Building Automation System Market
Building Automation Systems
Energy Efficient Elevators Market
Building Automation Systems
AEC Market
Building Automation Systems
Global Platform Screen Doors for Subway Lines Market
Building Automation Systems
Global HVAC Controls Market
Building Automation Systems
Automated Infrastructure Management (AIM) Solutions Market
Building Automation Systems
Global Modularization Market
Building Automation Systems
Escalator Market
Building Automation Systems
Tunnel Automation Market
Building Automation Systems
Elevator Modernization Market