
 Global Structural Health Monitoring Market | 2026-2036
Global Structural Health Monitoring Market Size, Share, and Industry Trends Forecast 2026-2036
Global Structural Health Monitoring Market Foresight
REACH compliance is recalibrating the cost-of-entry calculus for European suppliers of fiber optic and wireless sensing hardware. Geocomp Corporation leverages its geotechnical instrumentation heritage to anchor North American dam monitoring contracts. National Instruments Corporation sustains competitive positioning through modular data acquisition architectures that integrate with third-party sensor ecosystems. Campbell Scientific, Inc. specializes in ruggedized field communication equipment for remote infrastructure sites.
Structural health monitoring encompasses the continuous or periodic measurement of physical parameters—strain, vibration, displacement, acoustic emissions, and environmental loading—using embedded or surface-mounted sensor arrays to detect anomalies, predict degradation, and trigger maintenance interventions before catastrophic failure. Fiber optic sensors dominate high-precision applications due to electromagnetic immunity and distributed sensing capability, while wireless sensor networks are displacing cabled architectures in retrofit deployments where installation cost and accessibility constrain feasibility. Software platforms command expanding margin pools as infrastructure owners prioritize predictive analytics over raw data collection, and vibration monitoring leads technology adoption in wind turbine applications where blade and tower dynamics demand real-time assessment.
The EU Green Deal and F-Gas Regulation shape European demand by mandating lifecycle carbon accounting and restricting sensor cooling agents, while the US Federal Highway Administration pushes performance-based bridge management standards that reward predictive maintenance investments. ISO 18649 and IEC 61508 establish functional safety benchmarks for automated monitoring systems in transportation and energy infrastructure. Stakeholders must weigh proprietary platform lock-in against interoperability demands as public procurement specifications increasingly require open data formats and multi-vendor integration.
Market Dynamics
The transition from reactive maintenance to predictive intervention is compressing procurement cycles for integrated monitoring platforms as infrastructure owners seek unified dashboards over fragmented sensor networks.
Growth Catalysts
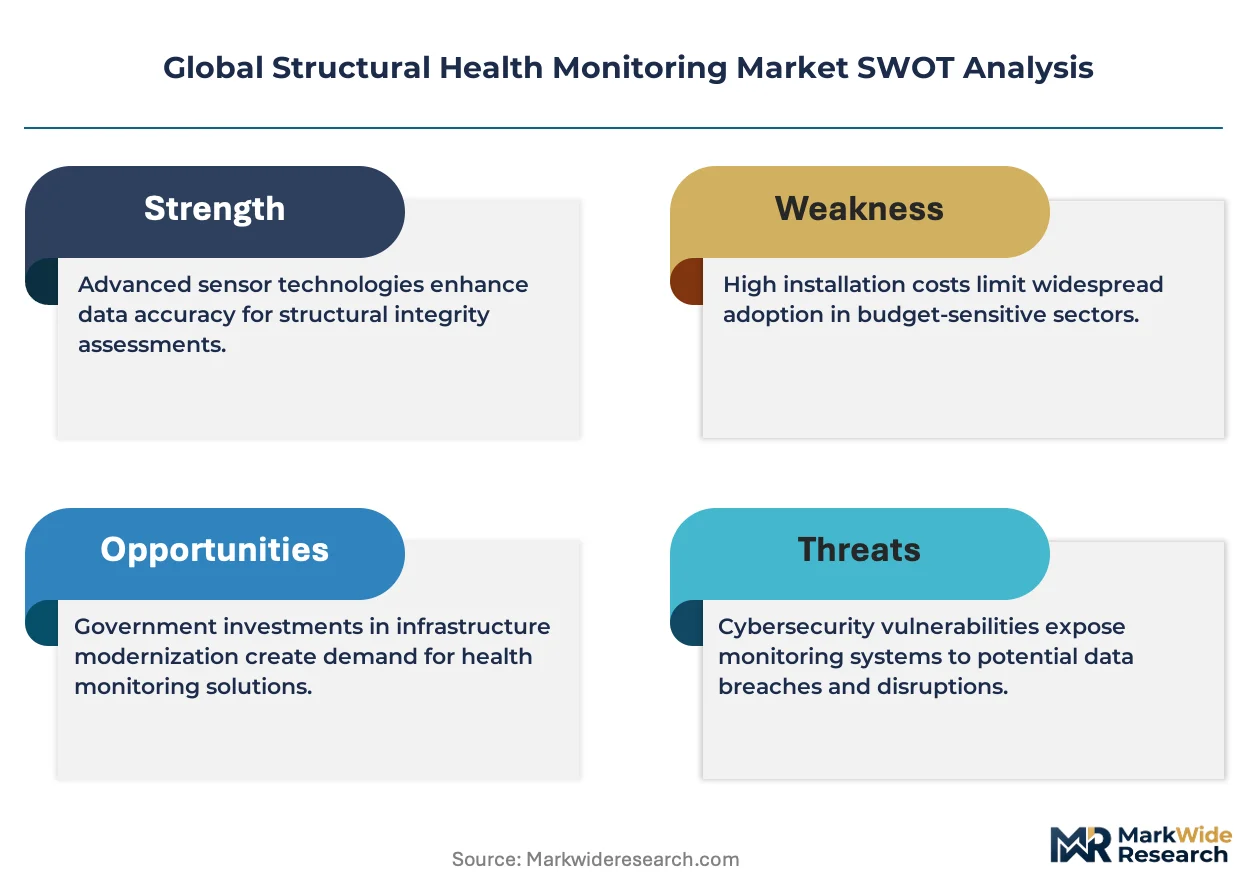
- EU Green Deal lifecycle mandates:Asset managers across Germany, France, and Italy now face binding carbon accountability requirements that necessitate continuous structural assessment to optimize maintenance timing and material efficiency.
- Fiber optic sensor maturation:Distributed acoustic sensing enables kilometer-scale coverage with single cable runs, slashing installation labor on bridge decks and tunnel linings where access windows are narrow.
- Wind turbine OEM specifications:Blade and tower monitoring clauses in supply contracts now require real-time vibration and strain telemetry as standard equipment, embedding SHM at manufacturing stage rather than retrofit.
Market Restraints
- Specialized installation labor scarcity:Qualified technicians for fiber optic splicing and sensor calibration command premium wages in Germany and Japan, inflating total deployment costs by 15-25% versus initial hardware quotes.
- Raw material concentration:Rare earth elements for piezoelectric sensors concentrate in Chinese processing facilities, exposing European and North American suppliers to export quota volatility and price spikes.
- REACH substance restrictions:ECHA classification of certain epoxy potting compounds as Substances of Very High Concern forces reformulation of ruggedized sensor housings, delaying product recertification by 12-18 months.
Strategic Opportunities
- India National Infrastructure Pipeline:$1.4 trillion committed to transport and energy assets through 2025 creates first-mover advantage for SHM vendors establishing local calibration and service capabilities.
- Digital twin convergence:Physics-based modeling fused with live sensor streams enables remaining-useful-life prediction for offshore wind foundations, opening premium service contracts with energy majors.
- US IIJA bridge formula funds:Performance-based maintenance clauses in federal highway grants reward states deploying continuous monitoring, creating procurement preference for predictive analytics platforms.
Industry Challenges
- Data science talent gaps:Civil engineering firms struggle to recruit machine learning engineers capable of training anomaly detection models on sparse failure datasets, forcing reliance on generic algorithms with elevated false-positive rates.
- Multi-vendor integration complexity:Legacy SCADA protocols in hydroelectric dams resist seamless incorporation of wireless sensor feeds, requiring costly protocol gateways and custom middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Structural Health Monitoring Market |
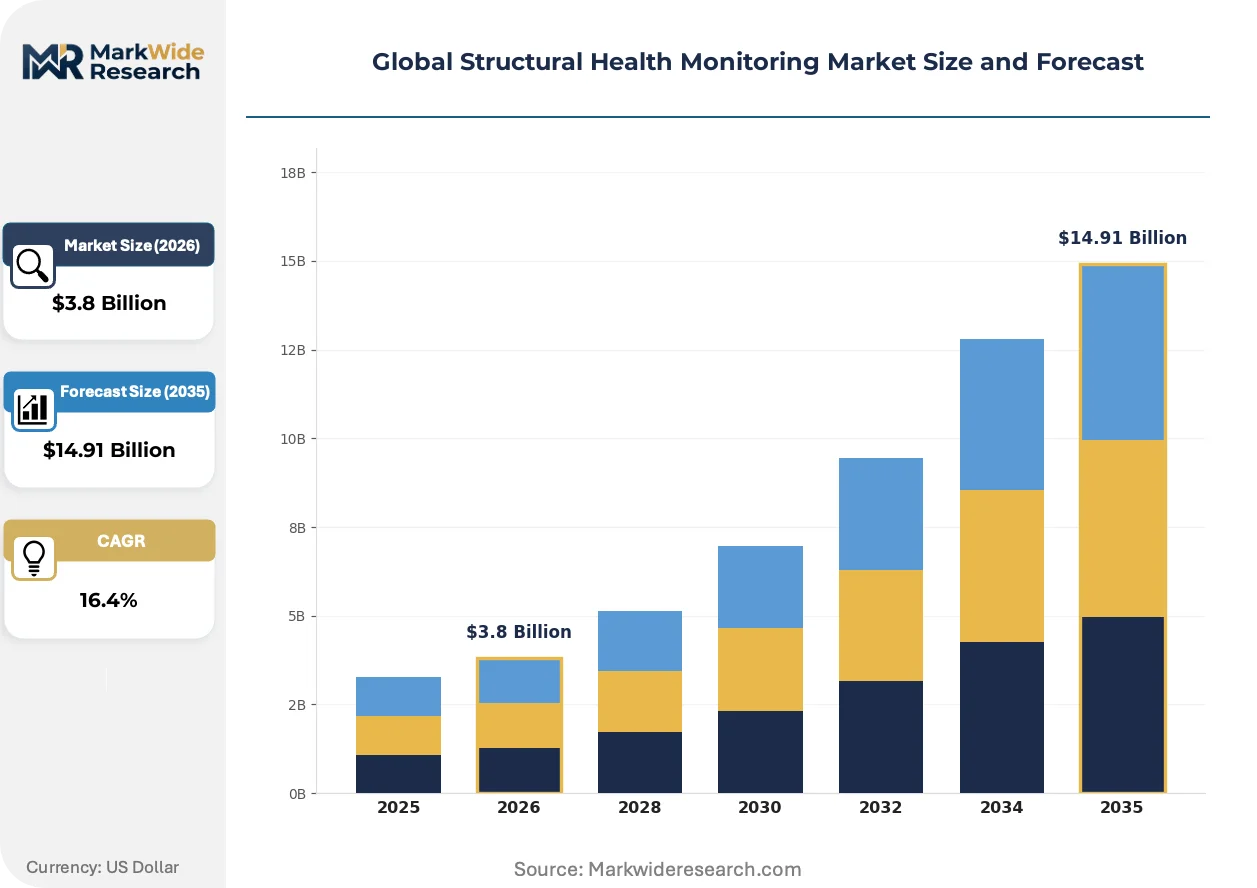
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $14.91 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sensors, Data Acquisition Systems, Communication Equipment, Software Platforms, Controllers Application: Bridges, Dams, Highways, Railway Infrastructure, Wind Turbines Technology: Wireless Sensor Networks, Fiber Optic Sensors, Ultrasonic Testing, Acoustic Emission, Vibration Monitoring End User: Infrastructure Owners, Construction Firms, Maintenance Contractors, Inspection Agencies |
| Companies Covered | Geocomp Corporation, Digitexx Data Systems, Inc., Acellant Technologies, Inc., National Instruments Corporation, Kinemetrics, Campbell Scientific, Inc., COWI A/S, Hottinger Brüel & Kjaer, Geokon, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Structural Health Monitoring Market Shifts & Advancements
Computational advances and regulatory stringency are converging to elevate software analytics above hardware commoditization, reshaping how infrastructure owners evaluate vendor proposals and structure long-term contracts.
Energy harvesting from ambient vibration is electrifying wireless sensor node deployment on bridge suspender cables and building façades. Kinetic-to-electrical transducers eliminate battery replacement cycles that previously drove 40% of lifecycle maintenance costs. German and Japanese operators are piloting self-powered mesh networks on heritage structures where cabling would compromise aesthetic or historical integrity, compressing payback periods for retrofit installations from seven years to under four.
EU F-Gas Regulation phase-down schedules are accelerating refrigerant-free cooling designs for data acquisition units in tropical climates. Equipment manufacturers face 2027 deadlines for eliminating hydrofluorocarbon-based thermal management, prompting adoption of thermoelectric and liquid cooling alternatives. Southeast Asian port authorities and Middle East airport operators—where ambient temperatures exceed 45°C—are specifying F-Gas-compliant hardware in new tenders, forcing incumbent suppliers to redesign product lines or cede these procurement cycles.
Performance-guaranteed service contracts are displacing capital expenditure purchases among municipal bridge authorities in France, the Netherlands, and California. Under these arrangements, vendors retain sensor ownership and charge per monitored asset per annum, aligning incentives on system uptime and prediction accuracy. The shift transfers obsolescence risk from public agencies to private operators, though it demands vendors maintain spare inventory and field service teams across dispersed geographic footprints.
Global Structural Health Monitoring Market Segmentation
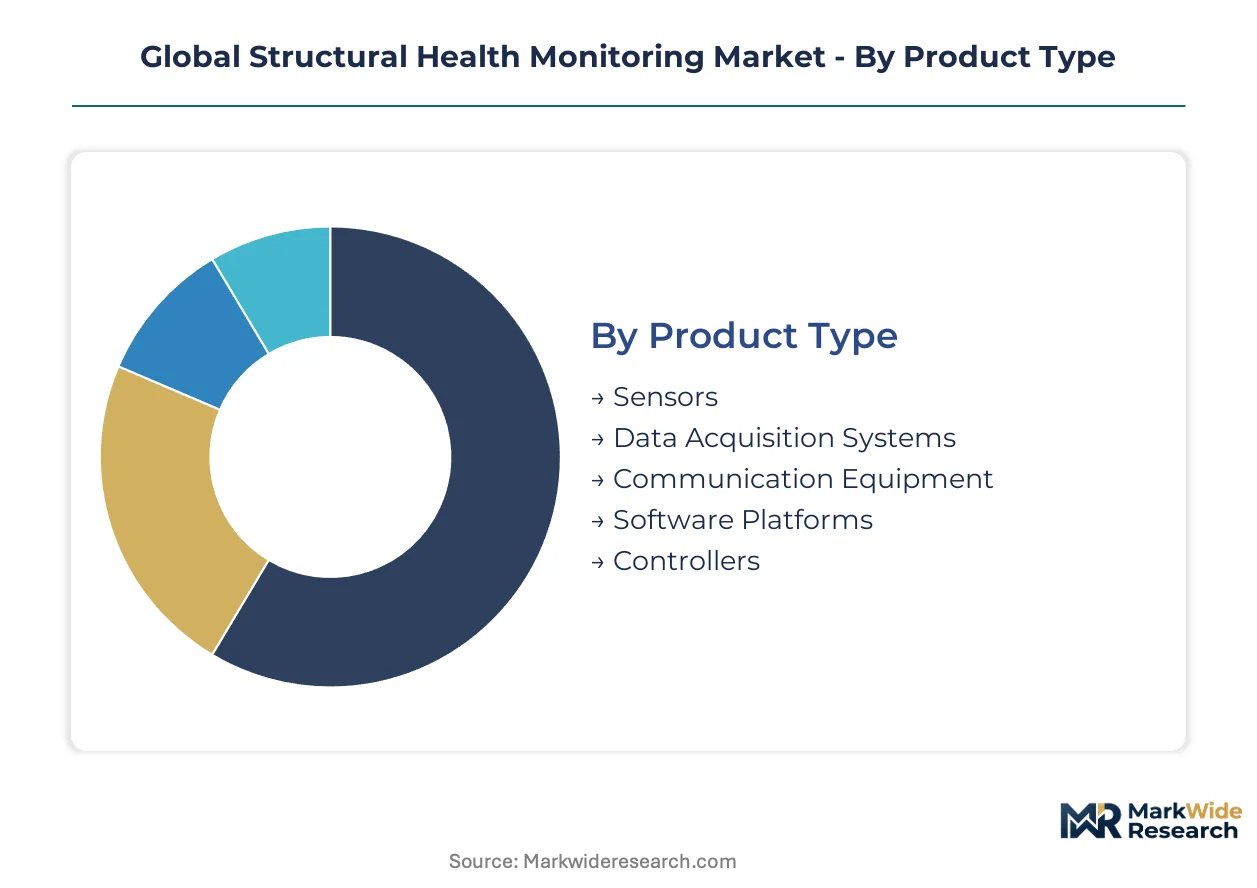
Structural health monitoring procurement diverges sharply across asset classes and operational models. Technology selection, integration complexity, and contracting structure all hinge on which segmentation axis dominates the buying decision.
Product Type:
Hardware specifications define interoperability thresholds and lifecycle cost profiles for infrastructure operators.
- Sensors:Strain gauges, accelerometers, and displacement transducers form the physical measurement layer. Fiber optic strain sensors command premium positioning on German autobahn bridges where electromagnetic immunity eliminates signal corruption from high-voltage traction systems. Piezoelectric variants dominate wind turbine blade monitoring where dynamic strain rates exceed optical response bandwidths.
- Data Acquisition Systems:Modular chassis with hot-swappable input cards aggregate multi-physics sensor streams. Campbell Scientific and National Instruments architectures prevail in North American dam safety networks where FERC guidelines mandate redundant signal conditioning paths.
- Communication Equipment:Ruggedized cellular and satellite modems bridge remote infrastructure to central analytics platforms. Mesh radio configurations are displacing cabled backhaul in Japanese railway tunnel retrofits where confined space prohibits conduit installation.
- Software Platforms:Cloud-native analytics suites with physics-informed machine learning engines command expanding margin pools. Predictive maintenance modules integrate with municipal asset management systems in the Netherlands and California.
- Controllers:Edge computing nodes execute threshold-based alerting without cloud latency. Programmable logic controllers anchor hydroelectric dam automation where IEC 61508 functional safety certification is mandatory.
Mature deployment sits with Sensors and Data Acquisition Systems. Newer deployment is concentrated in Software Platforms.
Application:
Asset-specific loading regimes and failure modes dictate sensor density, sampling frequency, and analytics sophistication.
- Bridges:Suspension cable monitoring with accelerometer arrays detects aerodynamic instability and corrosion-induced mass loss. Federal highway authorities in Germany, France, and Italy mandate continuous assessment on critical spans exceeding 500 meters.
- Wind Turbines:Blade pitch bearing vibration and tower base strain telemetry now ship as standard OEM equipment. Real-time structural assessment prevents catastrophic blade throw and foundation fatigue in North Sea offshore arrays.
- Dams:Seepage monitoring with piezometers and structural deformation tracking with inclinometers satisfy FERC and state-level safety mandates. Geotechnical instrumentation contracts concentrate in the western United States and Alpine Europe.
- Highways:Pavement strain and subgrade moisture sensors optimize maintenance timing on heavy freight corridors. Indian National Highway Authority specifications are embedding SHM in new concrete pavement designs.
- Railway Infrastructure:Track geometry and tunnel lining monitoring prevents service disruption on high-speed lines. Japanese and French operators deploy distributed acoustic sensing for landslide and intrusion detection.
Bridge monitoring represents the most established revenue base. Wind turbine applications are climbing the fastest as OEM specifications embed SHM at manufacturing stage.
Technology:
Measurement physics and network topology determine installation economics, maintenance burden, and data fidelity trade-offs.
- Fiber Optic Sensors:Distributed strain and temperature sensing along single cable runs eliminates discrete sensor wiring. Kilometer-scale coverage on German bridge decks and tunnel linings slashes installation labor where access windows are narrow.
- Wireless Sensor Networks:Self-organizing mesh topologies with energy harvesting eliminate battery replacement cycles. Kinetic-to-electrical transducers from ambient vibration compress payback periods on heritage structures where cabling compromises aesthetic integrity.
- Vibration Monitoring:Accelerometer-based modal analysis detects stiffness degradation and connection loosening. Wind turbine blade and tower dynamics assessment represents the dominant commercial application.
- Acoustic Emission:Passive listening for crack propagation signals in concrete and steel. Pressure vessel and storage tank inspection protocols in the United States and Japan specify periodic AE screening.
- Ultrasonic Testing:Active pulse-echo and through-transmission methods for thickness measurement and defect sizing. Weld inspection on bridge girders and offshore platforms remains the primary deployment context.
Fiber optic and wireless architectures are gaining share fastest as retrofit economics improve. Ultrasonic testing maintains steady demand in periodic inspection regimes rather than continuous monitoring.
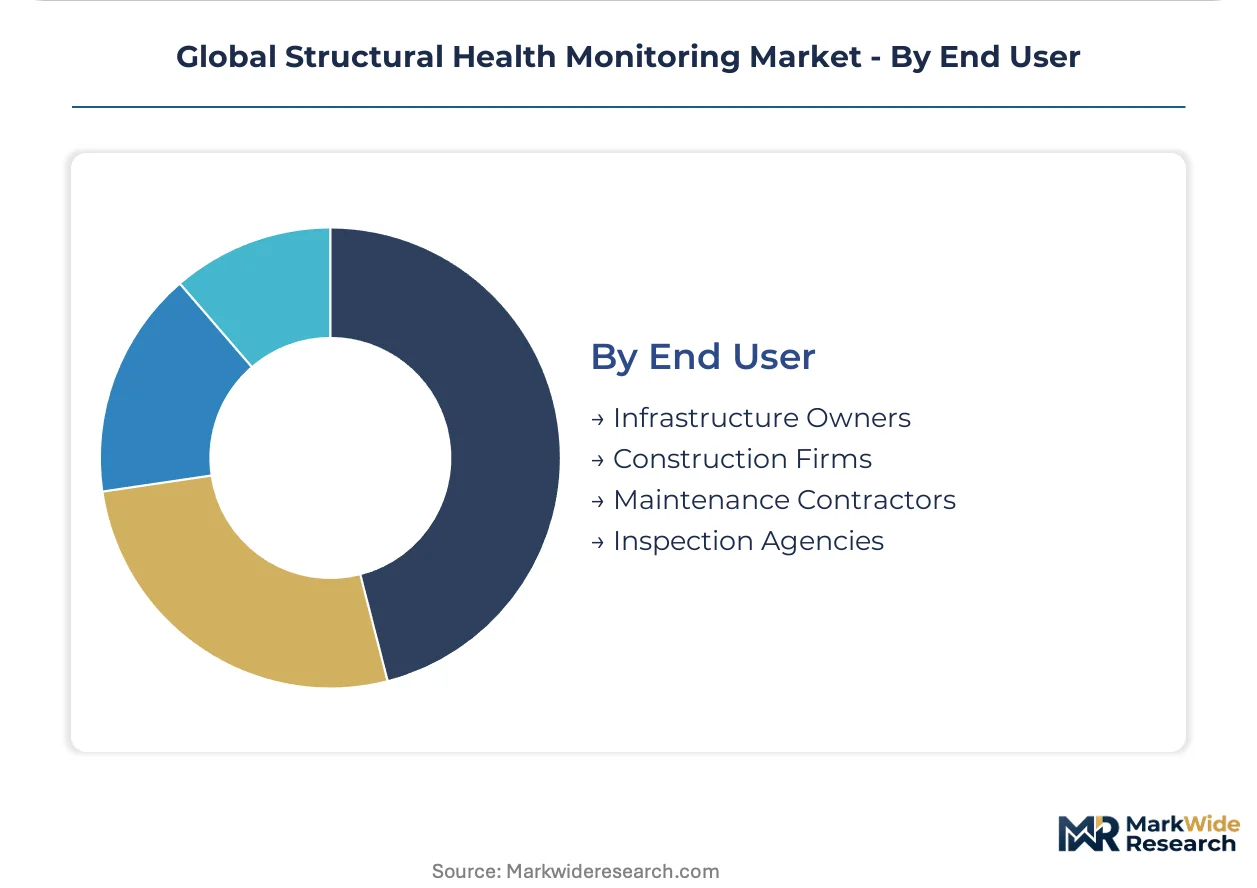
End User:
Procurement authority and technical capability determine platform complexity and contracting structure preferences.
- Infrastructure Owners:State highway agencies, port authorities, and utility operators with in-house engineering staff. French and Dutch bridge authorities are shifting to performance-guaranteed service contracts with annual per-asset fees.
- Construction Firms:EPC contractors embedding SHM as value-added differentiation on design-build contracts. Indian and Middle East megaproject tenders increasingly specify digital handover with integrated sensor networks.
- Maintenance Contractors:Specialized firms assuming operational responsibility under long-term service agreements. Equipment ownership transfers from public agencies to private operators, aligning uptime incentives.
- Inspection Agencies:Third-party certifiers integrating continuous monitoring data with periodic visual assessment. ISO 17020 accreditation requirements are expanding in European structural safety regulation.
Infrastructure Owners dominate current procurement volume. Maintenance Contractors represent the steepest expansion trajectory as performance-based contracting proliferates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German free-trade zones and Dutch port development districts concentrate European infrastructure sensor procurement, while Indian special economic zones accelerate manufacturing localization for dam and highway monitoring systems.
United States
Federal highway bridge formula funds and FERC dam safety mandates drive procurement volumes. The Infrastructure Investment and Jobs Act embeds performance-based maintenance clauses that reward continuous monitoring deployments. California and Texas transportation authorities lead sensor network expansion on critical spans exceeding 500 meters.
Germany
Federal autobahn authorities mandate real-time structural assessment on critical bridges, while EU Green Deal lifecycle accountability standards tighten procurement specifications. REACH compliance recalibrates cost structures for fiber optic sensor suppliers. Bavarian and North Rhine-Westphalian infrastructure clusters anchor continental deployment volumes for distributed acoustic sensing systems.
India
The National Infrastructure Pipeline commits substantial capital to transport and energy assets through 2025, creating demand for localized calibration capabilities. Central Electricity Authority guidelines and National Highway Authority specifications embed SHM in new concrete designs. Maharashtra and Gujarat industrial corridors concentrate first-mover vendor establishment for bridge and dam monitoring contracts.
Japan
High-speed railway operators deploy distributed acoustic sensing for landslide and intrusion detection along tunnel networks. METI industrial standards and heritage structure preservation rules constrain cabling aesthetics on historic bridges. Kansai and Kyushu railway maintenance depots pioneer self-powered mesh networks using kinetic energy harvesting from ambient vibration.
United Kingdom
Network Rail infrastructure modernization programs and Environment Agency reservoir safety directives sustain monitoring platform demand. ISO 17020 accreditation requirements expand for third-party structural safety certifiers. London and Southeast England municipal bridge authorities pilot performance-guaranteed service contracts with annual per-asset fee structures.
Global Structural Health Monitoring Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across the structural health monitoring value chain. The vendor base organizes into three tiers: integrated instrumentation conglomerates with geotechnical heritage, modular data acquisition specialists, and software-centric analytics platforms. Tier-one players leverage existing relationships with infrastructure authorities to bundle hardware and service contracts. Mid-tier specialists defend position through technology licensing partnerships and regional service density.
Within the geotechnical instrumentation tier, Geocomp Corporation and Geokon represent North American-focused archetypes with concentrated positioning in dam safety networks. Campbell Scientific, Inc. and National Instruments Corporation exemplify the modular hardware segment, with the former anchoring ruggedized field communication supply and the latter sustaining competitive positioning through chassis-based data acquisition architectures. COWI A/S occupies a distinct position among European engineering consultancies that integrate monitoring deployment with structural design services.
| Leading Market Players |
|---|
| Geocomp Corporation |
| Digitexx Data Systems, Inc. |
| Acellant Technologies, Inc. |
| National Instruments Corporation |
| Kinemetrics |
| Campbell Scientific, Inc. |
| COWI A/S |
| Hottinger Brüel & Kjaer |
| Geokon |
| Others |
Supply & Pricing Matrix
Rare earth oxide price indices for neodymium and dysprosium cascade through piezoelectric sensor manufacturing into three distinct procurement tiers for infrastructure operators. German autobahn authorities and Japanese railway operators absorb premium positioning for electromagnetic-immune fiber optic architectures, while Indian highway contractors face compressed margins on wireless retrofit deployments where spot-market sensor availability dictates project feasibility.
Pricing Analysis
Short lead-time premiums of 20-35% apply to fiber optic sensor arrays procured under emergency bridge safety mandates, while spot inventory discounts emerge for standard accelerometer SKUs held by North American distributors. Three-tier pricing structure separates F-Gas-compliant data acquisition units from legacy-cooled equivalents and economy-grade wireless nodes without edge computing capability. Cost compression in the economy tier intensifies because Chinese rare earth processing concentration exposes mid-tier suppliers to export quota volatility. Municipal bridge authorities in France and California exhibit highest price sensitivity, whereas offshore wind farm developers prioritize prediction accuracy over per-unit hardware costs.
Supply Chain Analysis
Direct-to-OEM channels handle wind turbine manufacturer demand for blade-embedded strain sensors, while systems integrators serve fragmented municipal infrastructure procurement. Manufacturing concentrates in Germany for precision fiber optic interrogators, China for piezoelectric wafer fabrication, and the United States for ruggedized field communication hardware. Rare earth element supply draws from Chinese separation facilities, Japanese magnet alloy processing, and Australian mining operations. Single-source vulnerability in Chinese rare earth oxide refining exposes European and North American sensor assemblers to quota-driven price spikes. Distribution runs through authorized regional service partners who maintain calibration laboratories and spare inventory pools.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The structural health monitoring sector sits at a technology-transition inflection where wireless sensor networks with energy harvesting displace cabled architectures in retrofit applications, compressing installation economics and reshaping vendor competitive moats.
For Market Incumbents: Acquire specialized machine learning engineering teams capable of training physics-informed anomaly detection models on sparse infrastructure failure datasets. Deepen backward integration into fiber optic cable manufacturing to secure electromagnetic-immune sensor supply against REACH-mandated epoxy reformulation delays. The threat of software-centric analytics platforms commoditizing hardware margins demands proprietary algorithm development as a defensive priority. For New Entrants and Emerging Players: Launch via performance-guaranteed service contracts targeting French and Dutch municipal bridge authorities transitioning from capital expenditure procurement. White-space opportunity concentrates in Indian National Infrastructure Pipeline projects requiring localized calibration capabilities, and in heritage structure monitoring where aesthetic constraints favor kinetic-harvesting wireless mesh networks. Partner with established geotechnical engineering consultancies to bypass incumbent relationships with infrastructure owners. For Investors and Strategic Acquirers: The window for entry favors software-centric analytics platforms with existing municipal asset management system integrations. Long-term viability hinges on recurring revenue streams from predictive maintenance subscriptions rather than transactional hardware sales. Target acquisition archetypes include cloud-native SHM analytics vendors with physics-informed machine learning engines and established channel partnerships with European engineering consultancies. Watch for inflection signals in F-Gas Regulation compliance deadlines accelerating refrigerant-free thermal management hardware procurement cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unified dashboards combining fiber optic, wireless, and vibration data streams satisfy EU Green Deal lifecycle accountability mandates. |
| Acquisition of Specialist Firm | Machine learning engineering boutiques with civil infrastructure domain expertise address talent scarcity in anomaly detection model development. |
| Geographic Expansion | Local calibration laboratories in Maharashtra and Gujarat industrial corridors capture Indian National Infrastructure Pipeline procurement preference. |
| Strategic Partnership | Alliances with wind turbine OEMs embed SHM specifications at manufacturing stage rather than retrofit installation. |
| Product Launch | Refrigerant-free data acquisition units meet EU F-Gas Regulation 2027 phase-down deadlines for tropical climate deployments. |
Research Methodology
Independent corroboration across infrastructure owner procurement directors, sensor hardware engineering leads, and predictive analytics software architects underwrites the qualitative findings in this analysis. Primary interviews with bridge maintenance superintendents at German autobahn authorities, dam safety officers at FERC-regulated utilities, and wind farm asset managers at North Sea offshore operators combined with secondary validation from EU Green Deal implementation reports, FHWA bridge formula fund disbursement records, and IEC 61508 certification databases. Bottom-up sensor deployment tallies triangulate against top-down infrastructure investment flow estimates.
Historical reference periods spanning pre-pandemic baseline, supply chain disruption interval, and post-stabilization recovery anchor the forecast window across the analysis window. Segmentation dimensions modeled include sensor technology type, asset class application, deployment architecture, and regional regulatory framework cluster. CAGRs derive from installed base expansion rates, replacement cycle compression, and predictive maintenance service contract penetration. Industry-specific forecast inputs incorporate EU F-Gas Regulation compliance deadlines, Indian National Highway Authority specification revisions, and wind turbine OEM embedded SHM clause adoption curves.
Export quota volatility in Chinese rare earth processing, REACH substance restriction recertification delays, and specialized installation labor scarcity are the dominant revision risks to deployment volume assumptions. Forecasts reflect base-case assumptions regarding infrastructure investment continuity and regulatory enforcement timelines. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Structural Engineering
Americas Structural Insulated Panel Market
Structural Engineering
Metal Structural Insulation Panels Market
Structural Engineering
Europe Bridge Bearings Market
Structural Engineering
Concrete Wind Tower Market
Structural Engineering
Offshore Structural Analysis Software Market
Structural Engineering
UK Facade Market
Structural Engineering
Steel Structure Anchor Bolt Market
Structural Engineering
FRP Bridge Market
Structural Engineering
Philippines Structural Insulated Panels Market
Structural Engineering
Europe Facade Market
Structural Engineering
Europe Structural Health Monitoring Market
Structural Engineering
Bridge Bearing Pad Market
Structural Engineering
Prestressed Concrete Market
Structural Engineering
Translucent Concrete Market
Structural Engineering
Cold-Formed Steel Market
Structural Engineering
North America Facade Market