
 Commercial Building Automation Systems Market | 2026-2036
Commercial Building Automation Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Commercial Building Automation Systems Market Analysis
Energy-as-a-service and performance contracting is rewriting capital deployment rules for building automation procurement, allowing facility operators to adopt advanced systems without upfront balance-sheet investment. Siemens AG leverages its digital infrastructure portfolio to anchor large-scale campus deployments across European metropolitan zones. Schneider Electric SE sustains competitive intensity through deep specialization in edge-computing energy management architectures. Johnson Controls International plc dominates North American service contracts by integrating hardware lifecycle management with predictive analytics capabilities.
Commercial building automation systems integrate sensor networks, programmable controllers, and centralized management platforms to regulate HVAC, lighting, security, and energy consumption across multi-tenant facilities, typically operating through BACnet or Modbus communication protocols with sub-second response thresholds. HVAC Control commands the largest installed base due to thermal regulation's direct impact on operating expenditure, while Energy Management captures accelerating interest as real-time carbon accounting becomes a procurement criterion for multinational tenants. Security Systems segments mature around video analytics and access credentialing, though margin pools shift toward cyber-physical integration as IT-OT convergence deepens.
EPA efficiency benchmarks and the EU Energy Performance of Buildings Directive tighten operational standards and compel retrofit investments across aging commercial stock. OSHA indoor air quality guidelines and Singapore's BCA Green Mark certification further shape product specifications and vendor qualification requirements. Stakeholders must weigh interoperability standards against proprietary ecosystem lock-in when specifying platforms intended for fifteen-to-twenty-year building lifecycles.
Market Dynamics
Energy-as-a-service financing models are collapsing traditional capital barriers for building automation adoption, enabling facility operators to deploy advanced systems through operational expenditure rather than upfront balance-sheet commitment.
Growth Catalysts
- EU Energy Performance of Buildings Directive:Mandatory efficiency retrofits across aging commercial stock in Germany, France, and Italy are accelerating controller and sensor replacement cycles.
- Healthcare facility construction:Hospital and clinic builds across the United States, Germany, and Japan are specifying integrated automation platforms for infection control and energy compliance.
- Edge-computing architectures:Real-time processing at the device level is reducing latency for HVAC and security subsystems below 100-millisecond thresholds.
Market Restraints
- Semiconductor supply concentration:Programmable logic controller production depends on concentrated Asian foundry capacity, creating 16-24 week lead time volatility.
- Cyber-physical integration costs:IT-OT convergence requires dedicated security infrastructure that adds 12-18% to total project deployment budgets.
- Legacy protocol fragmentation:BACnet, Modbus, and proprietary fieldbus coexistence forces expensive gateway hardware and integration labor.
Strategic Opportunities
- Singapore BCA Green Mark certification:Tiered sustainability ratings are creating premium automation specification tiers for new commercial developments.
- Predictive maintenance convergence:Machine learning integration with vibration and thermal sensors is opening service contract expansion in data center verticals.
- Direct digital control retrofits:Pneumatic-to-electronic HVAC upgrades in 1980s-era US office buildings represent underpenetrated white space.
Industry Challenges
- BAS-BMS integration complexity:Bridging standalone automation systems with enterprise building management platforms requires scarce systems integration specialists.
- OSHA indoor air quality compliance:Post-pandemic ventilation mandates are forcing rapid controller reprogramming without standardized verification protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Commercial Building Automation Systems Market |
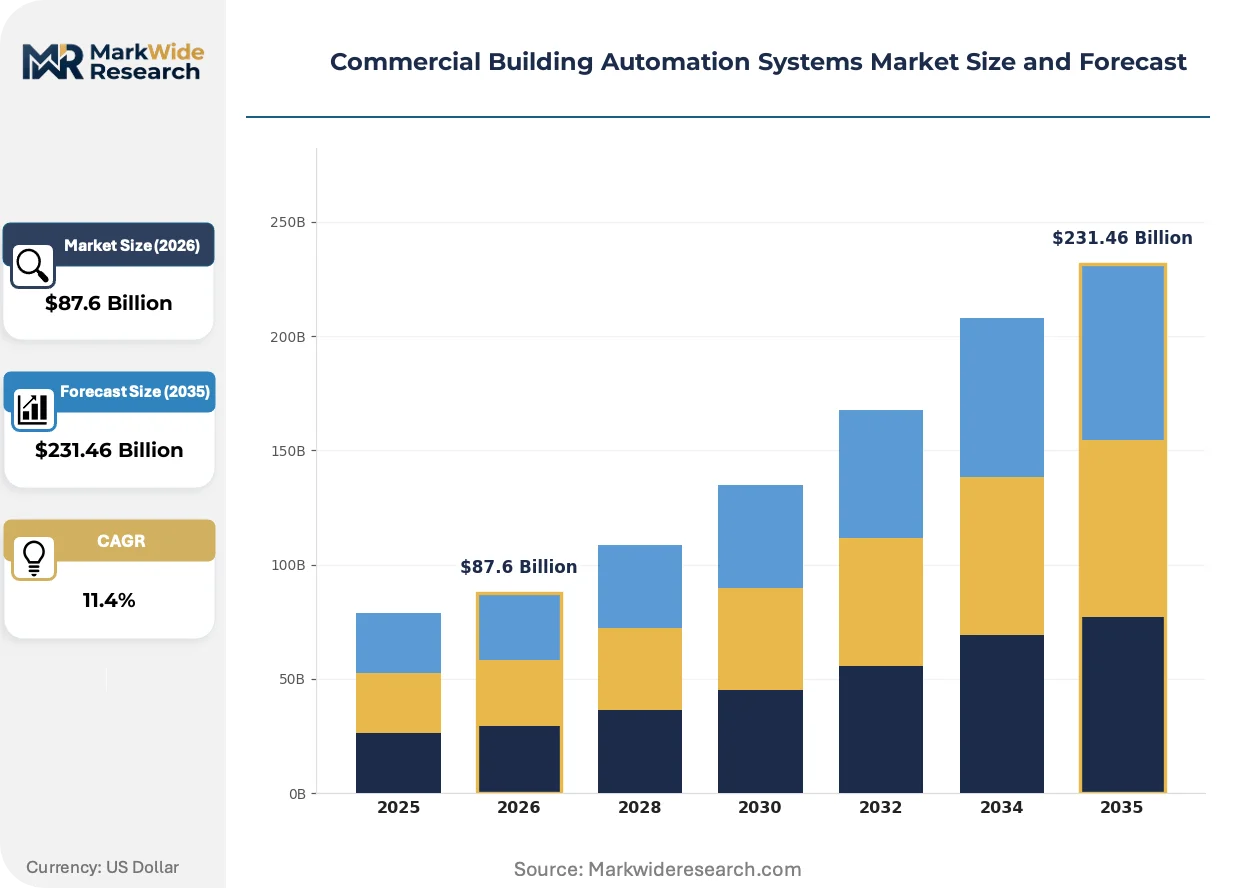
| Market Size in 2026 | $87.6 Billion |
| Market Size in 2035 | $231.46 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Lighting Control, HVAC Control, Security Systems, Energy Management Application: Office Buildings, Retail Spaces, Hotels, Industrial Facilities End User: Facility Managers, Building Owners, Contractors, System Integrators Service Type: Installation, Maintenance, Consulting, Training |
| Companies Covered | Siemens AG, Schneider Electric SE, Johnson Controls International plc, Honeywell International Inc., ABB Ltd., Carrier, Robert Bosch GmbH, Eaton Corporation, Trane Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Commercial Building Automation Systems Market Emerging Trajectories
Digital twin deployment is collapsing the boundary between design-phase simulation and operational optimization, enabling continuous calibration of building performance against modeled baselines.
Digital twin platforms ingest real-time sensor streams and weather data to simulate thermal and occupancy scenarios before physical adjustments. Large commercial developers in Singapore and the UAE are mandating twin integration for new Class A office specifications. This capability is collapsing the traditional separation between commissioning engineers and facilities management teams.
EPA efficiency benchmarks for commercial HVAC equipment are tightening minimum performance thresholds for new installations and major retrofits. Equipment manufacturers must certify seasonal energy efficiency ratios 15% above prior baselines to qualify for federal procurement preference. US federal building portfolios and state-level utility rebate programs are driving fastest compliance adoption.
Tenant procurement committees now require real-time carbon accounting dashboards as standard lease negotiation terms. Landlords in Australian and German metropolitan markets are unbundling automation service contracts from base rent to meet this specification. This behavioral shift is compressing traditional three-year capital planning cycles into annual technology refresh commitments.
Commercial Building Automation Systems Market Segmentation
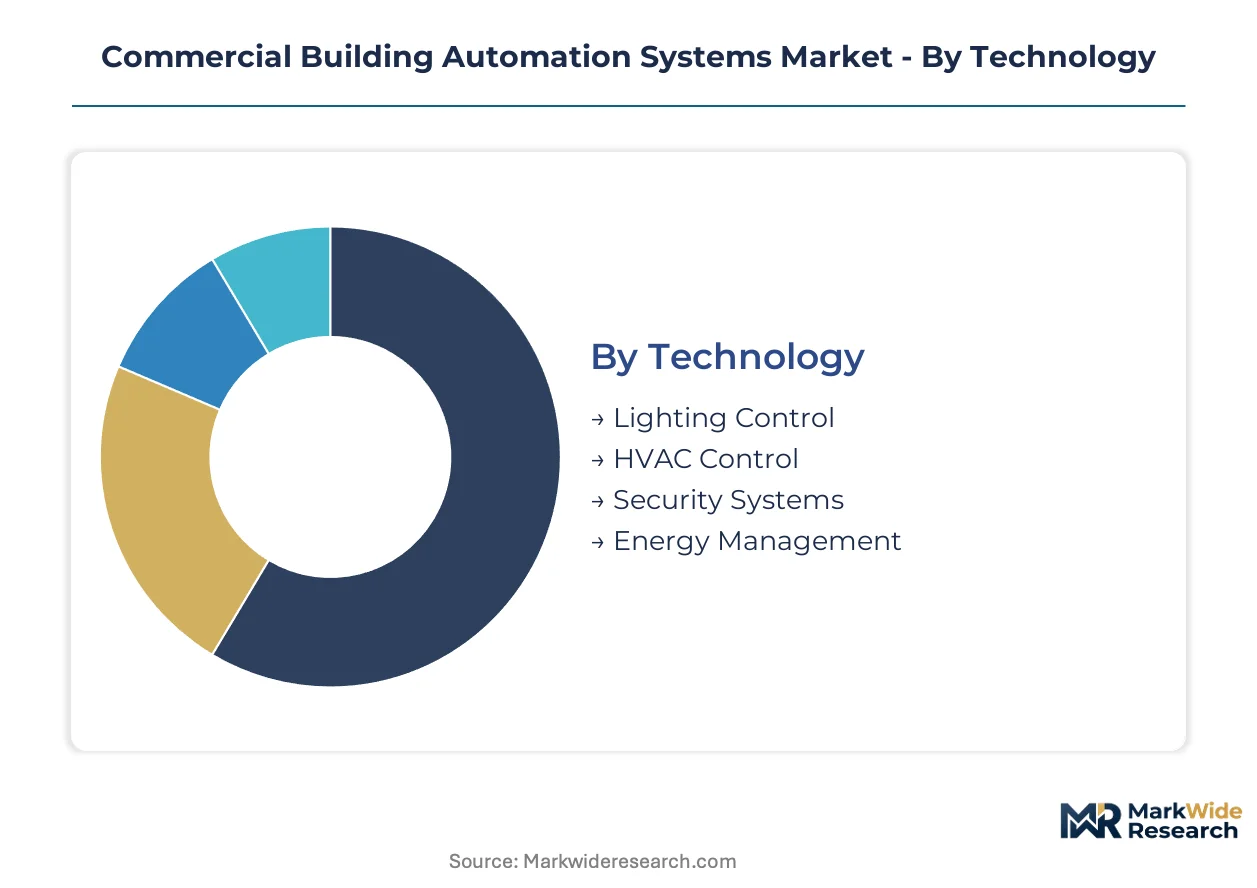
Segmentation in commercial building automation reveals divergent procurement cycles and margin structures across technology platforms and service delivery models. Understanding these dimensional splits enables vendors to align R&D roadmaps with replacement velocities and specification authority patterns.
Technology:
HVAC Control operates on the longest replacement cycles while Energy Management refreshes most rapidly as carbon accounting mandates tighten.
- HVAC Control:Programmable controllers, variable air volume boxes, and terminal unit interfaces regulate thermal zones through BACnet or Modbus protocols. Demand concentrates in German and Japanese healthcare construction where infection control specifications drive precision requirements. The segment commands the largest installed base due to thermal regulation's direct impact on operating expenditure.
- Energy Management:Edge-computing architectures process real-time consumption data at the device level for sub-100-millisecond carbon accounting responses. Singapore and Australian Class A office developers now mandate these platforms as standard lease negotiation terms. Tenant procurement committees require dashboard visibility into Scope 2 emissions.
- Lighting Control:Daylight harvesting systems and occupancy-based dimming reduce electrical loads through DALI or wireless mesh networks.
- Security Systems:Video analytics and access credentialing platforms mature around cyber-physical integration as IT-OT convergence deepens.
HVAC Control anchors the volume base while Energy Management gains share at the steepest rate.
Application:
Cost tier stratification separates premium-specification healthcare and hospitality deployments from standardized office retrofits.
- Office Buildings:Multi-tenant facilities require interoperable platforms spanning BACnet, Modbus, and proprietary fieldbus through expensive gateway hardware. US federal building portfolios and state-level utility rebate programs drive fastest compliance adoption for EPA efficiency benchmarks. The segment represents the most concentrated retrofit opportunity as 1980s-era pneumatic systems age out.
- Hotels:Guest room management systems integrate HVAC, lighting, and security through centralized property management platforms. UAE and Singapore developments specify tiered sustainability ratings that create premium automation specification tiers. Brand standards from major hospitality chains mandate consistent guest experience across properties.
- Retail Spaces:Open-plan configurations demand zonal control flexibility for changing merchandise layouts and seasonal occupancy patterns.
- Industrial Facilities:Process-critical environments require hardened controllers with extended temperature ranges and electromagnetic immunity certification.
Office Buildings dominate procurement volume while Hotels expand most quickly on new construction specifications.
End User:
Specification authority concentrates with facility managers on operational decisions and building owners on capital deployment.
- Facility Managers:Operational expenditure authority enables Energy-as-a-service financing adoption without upfront balance-sheet commitment. German and US healthcare facility operators prioritize infection control and energy compliance in procurement criteria. This stakeholder group drives predictive maintenance service contract expansion.
- Building Owners:Capital deployment decisions fifteen-to-twenty years ahead require weighing interoperability standards against proprietary ecosystem lock-in. Australian and German metropolitan landlords unbundle automation service contracts from base rent to meet tenant carbon accounting requirements. Asset holding periods determine technology refresh cycle compression.
- Contractors:Installation labor availability constrains project velocity in concentrated metropolitan construction markets.
- System Integrators:Scarce specialists bridge standalone automation systems with enterprise building management platforms for BAS-BMS integration.
Facility Managers anchor operational service revenue while Building Owners control the steepest capital deployment trajectory.
Service Type:
Margin pools shift from installation toward recurring maintenance as predictive analytics capabilities mature.
- Maintenance:Machine learning integration with vibration and thermal sensors opens service contract expansion in data center verticals. Johnson Controls International plc dominates North American contracts by integrating hardware lifecycle management with predictive capabilities. Recurring revenue streams stabilize vendor cash flows across economic cycles.
- Installation:Project-based delivery faces margin compression from semiconductor supply concentration creating 16-24 week lead time volatility. Cyber-physical integration costs add 12-18% to total deployment budgets through dedicated security infrastructure. Labor scarcity in systems integration specialists extends project timelines.
- Consulting:Digital twin deployment collapses boundaries between design-phase simulation and operational optimization for continuous calibration.
- Training:OSHA indoor air quality compliance mandates force rapid controller reprogramming without standardized verification protocols.
Installation anchors project-based revenue while Maintenance climbs the fastest on predictive service adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EU Energy Performance of Buildings Directive is accelerating automation retrofits across aging commercial stock, while healthcare construction and smart office developments concentrate procurement in specific metropolitan clusters worldwide.
United States
Hospital and clinic construction across Texas and California is specifying integrated automation platforms for infection control compliance. EPA efficiency benchmarks tighten minimum performance thresholds for new HVAC installations and major retrofits. Federal building portfolios in Washington DC and state-level utility rebate programs in New York drive fastest compliance adoption.
Germany
Mandatory efficiency retrofits under the EU Energy Performance of Buildings Directive accelerate controller and sensor replacement cycles in Frankfurt and Munich commercial districts. The F-Gas Regulation phases down hydrofluorocarbon refrigerants, forcing HVAC control system upgrades. Siemens AG leverages its digital infrastructure portfolio to anchor large-scale campus deployments across Berlin metropolitan zones.
Singapore
BCA Green Mark certification creates premium automation specification tiers for new Class A office developments in the Marina Bay district. Tiered sustainability ratings mandate edge-computing energy management architectures as standard lease terms. Digital twin deployment collapses boundaries between design-phase simulation and operational optimization for continuous calibration.
Japan
Healthcare facility construction in Tokyo and Osaka specifies integrated automation platforms for infection control and METI energy compliance. JIS standards shape product specifications for programmable controllers in commercial applications. Edge-computing architectures reduce latency for HVAC subsystems below 100-millisecond thresholds in data center verticals.
Australia
Tenant procurement committees in Sydney and Melbourne require real-time carbon accounting dashboards as standard lease negotiation terms. Landlords unbundle automation service contracts from base rent to meet multinational tenant specifications. This behavioral shift compresses traditional three-year capital planning cycles into annual technology refresh commitments.
Commercial Building Automation Systems Market Vendor Landscape
Channel-controlling players compete with product-specialist players across a consolidated vendor base anchored by diversified industrial conglomerates and pure-play automation specialists. Siemens AG, Schneider Electric SE, and Johnson Controls International plc occupy the top tier through integrated hardware-software-service portfolios. Mid-tier specialists compete on edge-computing energy management architectures and predictive maintenance capabilities. Dominant competitive moves include strategic partnerships for IT-OT convergence and portfolio diversification into energy-as-a-service financing models.
Within the diversified industrial tier, Siemens AG and Schneider Electric SE exemplify channel-controlling strategies through digital infrastructure and energy management specialization respectively. Johnson Controls International plc anchors the North American service contract segment by integrating hardware lifecycle management with predictive analytics capabilities. Honeywell International Inc. and ABB Ltd. occupy positions spanning building automation and broader industrial automation portfolios. Trane Technologies and Carrier represent HVAC-native players extending into full building automation integration. Robert Bosch GmbH and Eaton Corporation sit within the European and North American industrial conglomerate archetypes respectively.
| Leading Market Players |
|---|
| Siemens AG |
| Schneider Electric SE |
| Johnson Controls International plc |
| Honeywell International Inc. |
| ABB Ltd. |
| Carrier |
| Robert Bosch GmbH |
| Eaton Corporation |
| Trane Technologies |
| Others |
Supply Flow & Price Mechanics
Semiconductor foundry concentration in Taiwan and South Korea generates 16-24 week lead time volatility that compresses margins for programmable controller vendors while forcing buyers into premium tier commitments for supply security. This single-source dependency simultaneously widens pricing spreads between standard and expedited delivery tiers and reshapes inventory positioning across the value chain.
Pricing Analysis
Certification level creates the primary spread across the market, with BCA Green Mark and EU Energy Performance of Buildings Directive compliance tiers commanding 15-25% premiums over baseline BACnet installations. Project-based pricing dominates system deployments, though Energy-as-a-service financing is displacing upfront capital models in Australian and German office markets. Price differentiation rests on edge-computing architecture sophistication and predictive analytics bundling. Cost compression in standard HVAC retrofits is intensifying because of pneumatic-to-digital upgrade commoditization. Facility managers in US federal buildings exhibit highest price sensitivity, while Singapore Class A developers prioritize performance specifications over unit economics.
Supply Chain Analysis
Contract manufacturing for programmable logic controllers concentrates with Foxconn, Jabil, and Flex facilities across Shenzhen, Penang, and Guadalajara. Taiwan and South Korea anchor semiconductor wafer supply for sensor microcontrollers and communication modules. Raw material dependencies span copper for wiring harnesses, rare earth elements for actuator magnets, and epoxy resins for PCB encapsulation. Single-source vulnerability in advanced node foundry capacity creates procurement chokepoints for real-time processing chipsets. Distribution runs through authorized systems integrator channels in metropolitan construction clusters, with direct OEM relationships dominating large campus deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Interoperability protocol convergence is restructuring platform economics, as BACnet/Modbus gateway standardization collapses proprietary ecosystem premiums and enables modular procurement across fifteen-to-twenty-year building lifecycles.
For Market Incumbents: Pre-empt margin erosion in HVAC control hardware by accelerating vertical integration into edge-computing software stacks and predictive maintenance service contracts. Counter IT-OT convergence threats from cybersecurity specialists by embedding zero-trust architectures into controller firmware rather than bolt-on solutions. Certification investment in Singapore BCA Green Mark and EU Energy Performance of Buildings Directive tiers preserves specification authority in premium new construction verticals. For New Entrants and Emerging Players: Pursue direct digital control retrofits in 1980s-era US office buildings, where incumbent service relationships have atrophied and pneumatic system obsolescence creates urgent replacement demand. Target German healthcare facility construction, where infection control specifications favor specialized precision over established brand loyalty. A go-to-market angle through energy-as-a-service financing partnerships bypasses capital budget gatekeepers and accelerates pilot-to-scale velocity. For Investors and Strategic Acquirers: The EU Energy Performance of Buildings Directive reshapes the acquisition landscape by mandating efficiency retrofits that expand addressable market for automation controllers and sensors. Long-term viability centers on recurring maintenance revenue streams rather than installation project cyclicality. Acquisition target archetypes include edge-computing energy management specialists with machine learning integration capabilities and established service contracts in data center verticals. The signal to watch is tenant procurement committee carbon accounting mandates spreading from Australian and German metropolitan markets into US Class A office specifications.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Interoperability standardization collapses proprietary gateway costs and accelerates modular procurement across multi-tenant facilities. |
| Energy-as-a-Service Financing | Operational expenditure models unlock healthcare and government verticals with constrained capital budgets and compliance mandates. |
| Edge-Computing Architecture Deployment | Sub-100-millisecond processing enables real-time carbon accounting responses required by Singapore BCA Green Mark certification tiers. |
| Predictive Maintenance Service Expansion | Machine learning integration with thermal and vibration sensors stabilizes recurring revenue across HVAC replacement cycles. |
| Digital Twin Development | Continuous calibration against modeled baselines collapses commissioning-to-operations handoff delays in UAE and Singapore Class A developments. |
Methodological Framework
A spread of perspectives from facilities management executives, building automation systems integrators, healthcare procurement officers, commercial real estate developers, and energy service company contract managers converged on the working assumptions driving market sizing. Primary fieldwork combined structured interviews with secondary validation through EPA efficiency benchmark filings, EU Energy Performance of Buildings Directive regulatory databases, Singapore BCA Green Mark certification registries, and SEC 10-K disclosures from diversified industrial conglomerates. Bottom-up controller and sensor shipment analysis triangulated against top-down construction spending data across office, healthcare, and hospitality verticals.
Demand-supply balance modeling anchored the projection framework, with installation capacity constraints and semiconductor foundry lead times informing supply-side boundaries. Segmentation dimensions spanned technology platform, application vertical, end-user specification authority, and service delivery model, with regional regulatory cluster intensity as an additional cross-cutting variable. CAGRs derived from replacement cycle velocity analysis and new construction specification penetration curves, incorporating edge-computing adoption rates and energy-as-a-service financing penetration as industry-specific forecast inputs across the analysis window.
Macroeconomic conditions sit as an overlay; deviation in commercial construction lending rates, semiconductor capital expenditure cycles, or EU regulatory enforcement intensity would shift the trajectory. Forecasts reflect documented assumptions regarding BACnet/Modbus interoperability timelines and tenant carbon accounting mandate diffusion patterns. Quarterly review of healthcare construction permit issuance, foundry utilization rates, and BCA Green Mark certification volumes is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Automation Systems
Building-To-Grid Technology Market
Building Automation Systems
Energy Efficient Elevators Market
Building Automation Systems
Building Automation and Control System Market
Building Automation Systems
Underfloor Heating Actuator Market
Building Automation Systems
Vinyl Strip Door and Curtains Market
Building Automation Systems
Global Modularization Market
Building Automation Systems
Europe HVAC Controls Market
Building Automation Systems
Platform Lifts Market
Building Automation Systems
Electrochromic Glass Market
Building Automation Systems
Global HVAC Controls Market
Building Automation Systems
Automated Infrastructure Management (AIM) Solutions Market
Building Automation Systems
Escalator Market
Building Automation Systems
Rotary Sprinkler System Market
Building Automation Systems
Global Solar Shading Systems Market
Building Automation Systems
Building Management System Market
Building Automation Systems
Global Door Closers Market