
 China Revolving Doors Market | 2026-2036
China Revolving Doors Market Size, Share, and Industry Trends Forecast 2026-2036
China Revolving Doors Market Insights
The price-performance gap between premium automatic systems and basic manual units is hardening across procurement channels. Shanghai Yupeng Glass Products leverages its integrated glass fabrication capacity to control material costs for high-specification lobby installations. Shijiazhuang Depuer Automatic Door Control sustains competitive positioning through specialization in security-rated revolving configurations for government facilities. Nanjing Maosong Automatic Door anchors regional distribution networks across Jiangsu province, extending same-day technical service coverage to commercial developers.
A revolving door consists of a circular enclosure with multiple wings rotating around a central vertical axis, typically engineered with 2.1 to 3.6 meter diameter clear openings and brush-sealed perimeter gaps to minimize air infiltration. The assembly serves commercial buildings by reducing HVAC load through controlled airlock function while managing pedestrian throughput of 20 to 40 persons per minute. Automatic product types lead unit volume as building operators prioritize touchless entry protocols, while security configurations command the strongest margin pools due to certified blast-resistant and ballistic-rated engineering requirements. Aluminum material segments dominate fabrication tonnage for structural frames, though glass-intensive custom designs extract premium pricing from luxury hospitality and flagship retail applications.
China's national standards body administers GB 5237 for aluminum alloy building profiles and GB 15763 for safety glass in architectural applications, with provincial construction bureaus enforcing local energy codes that mandate thermal break performance in entrance assemblies. The national market regulator SAMR oversees product conformity assessment for automatic door safety systems, including emergency breakout and sensor reliability protocols. Stakeholders must monitor evolving municipal green building rating systems across Beijing, Shanghai, and Shenzhen, as these jurisdictions are tightening embodied carbon thresholds for facade and entrance subsystems ahead of national harmonization.
Market Dynamics
GB standards for building energy efficiency are tightening thermal performance requirements, forcing entrance system upgrades across commercial construction and retrofit programs in Tier-1 cities.
Growth Catalysts
- Dual carbon policy framework:China's national decarbonization targets mandate HVAC load reduction in commercial buildings, directly accelerating specification of airlock entrance systems in new construction.
- Facade modernization programs:Luxury hotel chains in Shanghai and Beijing are replacing legacy swing doors with revolving configurations as part of comprehensive lobby renovation cycles.
- Touchless entry protocols:Automatic product types are capturing expanded share as building operators prioritize sensor-activated systems for hygiene and throughput management.
Market Restraints
- Aluminum alloy price volatility:Structural frame fabrication depends on primary aluminum input costs, which fluctuate with energy pricing and smelter capacity constraints.
- Certified glass supply concentration:Safety-rated glass fabrication for blast-resistant configurations concentrates among limited domestic suppliers with SAMR conformity assessment.
- Manual unit substitution pressure:Basic manual revolving doors compete on first-cost for budget-constrained municipal and educational projects.
Strategic Opportunities
- Tier-2 Yangtze River Delta expansion:Emerging cities in Jiangsu and Zhejiang provinces show elevated commercial construction activity with underpenetrated automatic door specification.
- Security-rated engineering convergence:Integration of ballistic-rated glass with biometric access control opens government and embassy verticals.
- Municipal green building rating systems:Beijing and Shanghai are tightening embodied carbon thresholds for facade subsystems ahead of anticipated national harmonization.
Industry Challenges
- GB 15763 safety glass certification timelines:Compliance documentation for architectural applications creates extended approval cycles for custom lobby installations.
- Integration complexity with legacy HVAC:Retrofit projects require coordination with existing building management systems for pressure differential control.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Revolving Doors Market |
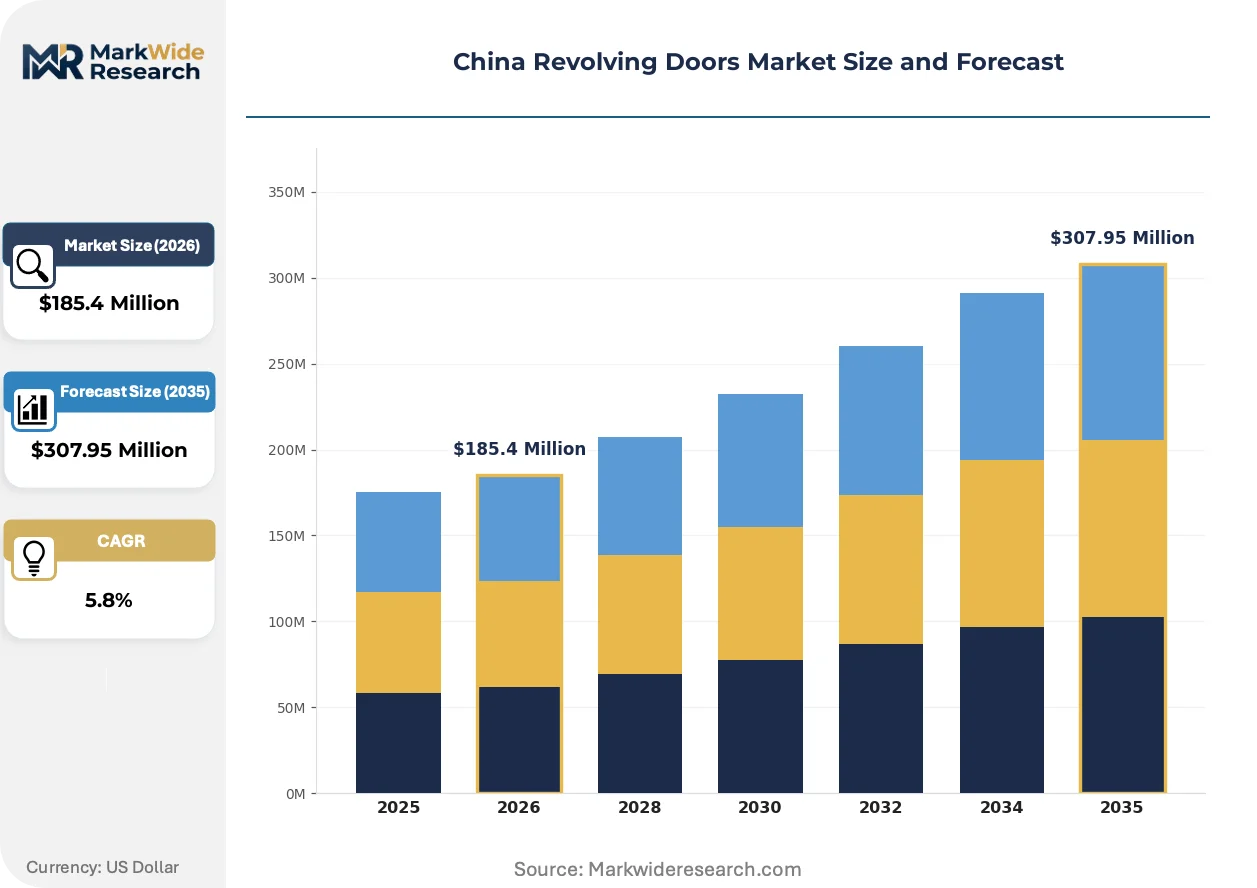
| Market Size in 2026 | $185.4 Million |
| Market Size in 2035 | $307.95 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual, Automatic, Security, Custom Material: Aluminum, Glass, Steel, Wood Application: Commercial Buildings, Airports, Malls, Hotels End User: Retailers, Corporations, Institutions, Government |
| Companies Covered | Shanghai Yupeng Glass Products Co., Ltd., Shijiazhuang Depuer Automatic Door Control Co., Ltd., Nanjing Maosong Automatic Door Co., Ltd., Beijing Hongtai Dingcheng Automatic Door Technology Co., Ltd., Hefei Tongsheng Doors and Windows Co., Ltd., Qingdao Kaibisheng Automatic Door Engineering Co., Ltd., Hualong Dingsheng Technology Co., Ltd., Zhuhai Jiaxin Building Materials Co., Ltd., ASSA ABLOY, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Revolving Doors Market Trends and Innovations
Brush-sealed perimeter gap engineering and sensor-activated drive systems are reshaping product architecture, while municipal energy codes accelerate specification of high-performance entrance assemblies.
Brush-sealed perimeter systems with thermally broken aluminum framing are electrifying the premium product tier. Luxury hospitality developers in Shanghai specify these configurations for flagship properties. The technology is compressing specification timelines as energy modeling software quantifies HVAC savings during design phases.
MEE enforcement of building energy efficiency codes is intensifying inspection protocols for thermal break performance in entrance assemblies. Provincial construction bureaus now require documented U-value calculations for permit approval. Commercial developers in Beijing are responding by pre-specifying certified systems to avoid construction delays.
Building operators are unbundling after-sales service contracts from initial equipment procurement. Facility management teams in Tier-1 cities now source technical service separately through regional distribution networks. This pattern is most visible in Jiangsu province, where same-day response coverage has become a competitive differentiator for commercial developers.
China Revolving Doors Market Segmentation
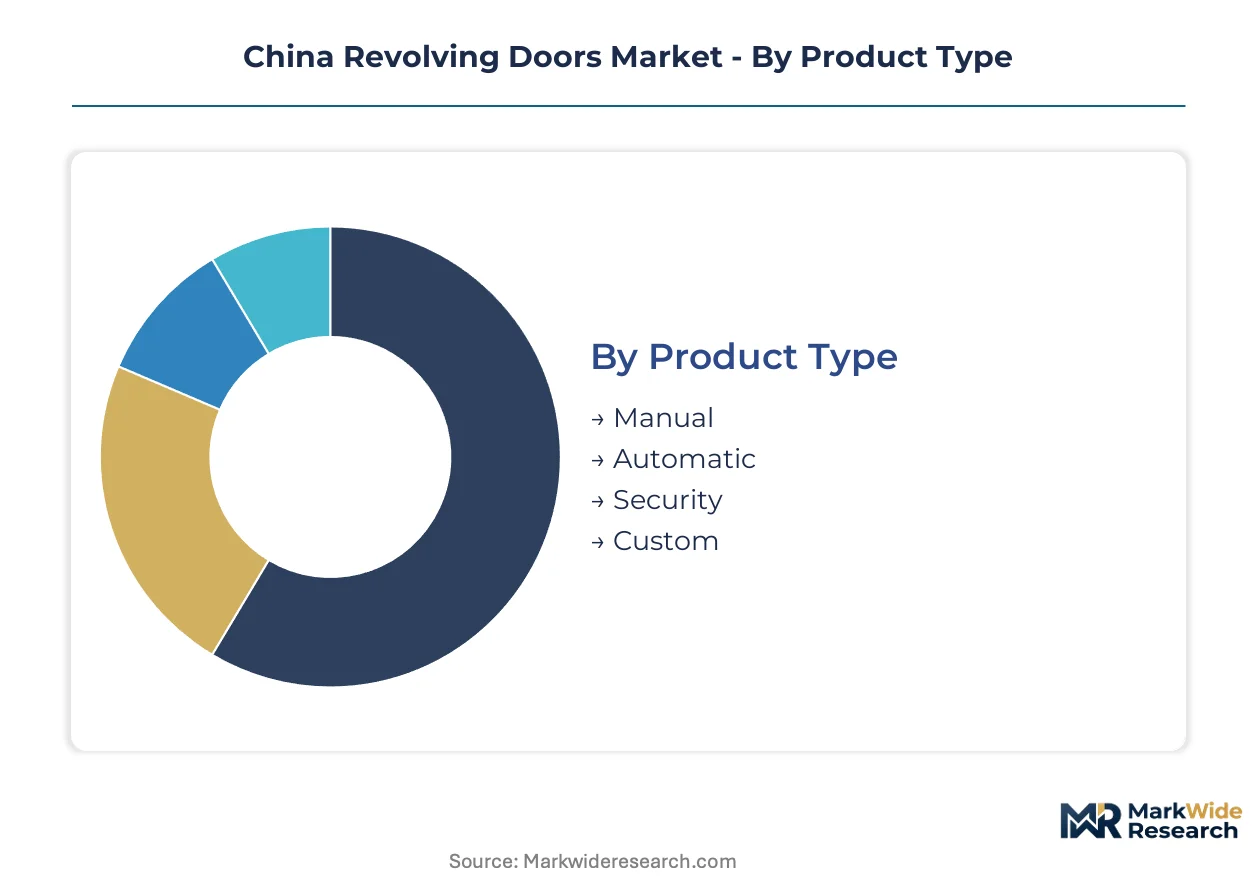
Segmentation in China's revolving door market reveals distinct procurement patterns across building types and security requirements. Facility managers prioritize thermal performance ratings and sensor integration capabilities when specifying entrance systems for new construction and lobby renovation cycles.
Product Type:
Upgrade cycles for entrance systems concentrate in Tier-1 cities where energy code enforcement has intensified inspection protocols for airlock performance.
- Manual:Basic hand-propelled configurations with minimal weathersealing serve budget-constrained municipal projects and educational facilities in inland provinces. Procurement concentrates through regional distributors serving Tier-3 construction markets where first-cost sensitivity dominates specification decisions.
- Automatic:Sensor-activated drive systems with brush-sealed perimeter gaps dominate new commercial construction in Shanghai and Beijing. Luxury hospitality developers specify these for flagship properties where touchless entry protocols and throughput management justify premium positioning.
- Security:Blast-resistant and ballistic-rated engineering for government facilities and embassy compounds.
- Custom:Bespoke glass-intensive designs for flagship retail and luxury brand flagship stores.
Automatic sits at the top of the volume ranking, with Security climbing the fastest.
Material:
Cost tier differentiation separates premium facade integrations from standard commercial installations across procurement channels.
- Aluminum:Thermally broken extrusions per GB 5237 dominate structural frame fabrication tonnage. Commercial developers in Beijing pre-specify certified systems to avoid construction delays from extended approval cycles.
- Glass:Safety-rated laminated configurations per GB 15763 command strongest margin pools in luxury hospitality applications. Limited domestic suppliers with SAMR conformity assessment create supply concentration for blast-resistant specifications.
- Steel:Reinforced framing for high-security government and institutional entrances.
- Wood:Premium veneer cladding for boutique hospitality and heritage building renovations.
Aluminum maintains the broadest application footprint, with Glass extracting the steepest price premiums.
Application:
Volume concentrates in commercial construction corridors where facade modernization programs are accelerating replacement cycles.
- Commercial Buildings:Office towers and mixed-use developments in Yangtze River Delta cities specify automatic systems for HVAC load reduction. MEE enforcement of building energy efficiency codes mandates documented U-value calculations for permit approval.
- Hotels:Luxury chains in Shanghai and Beijing replace legacy swing doors as part of comprehensive lobby renovation cycles. Brush-sealed perimeter systems compress specification timelines as energy modeling software quantifies operational savings.
- Airports:High-throughput terminals requiring sensor-activated systems for passenger flow management.
- Malls:Retail complexes prioritizing visibility and open sightlines through glass-intensive custom configurations.
Commercial Buildings anchor procurement volume, with Hotels gaining share fastest amid renovation spending.
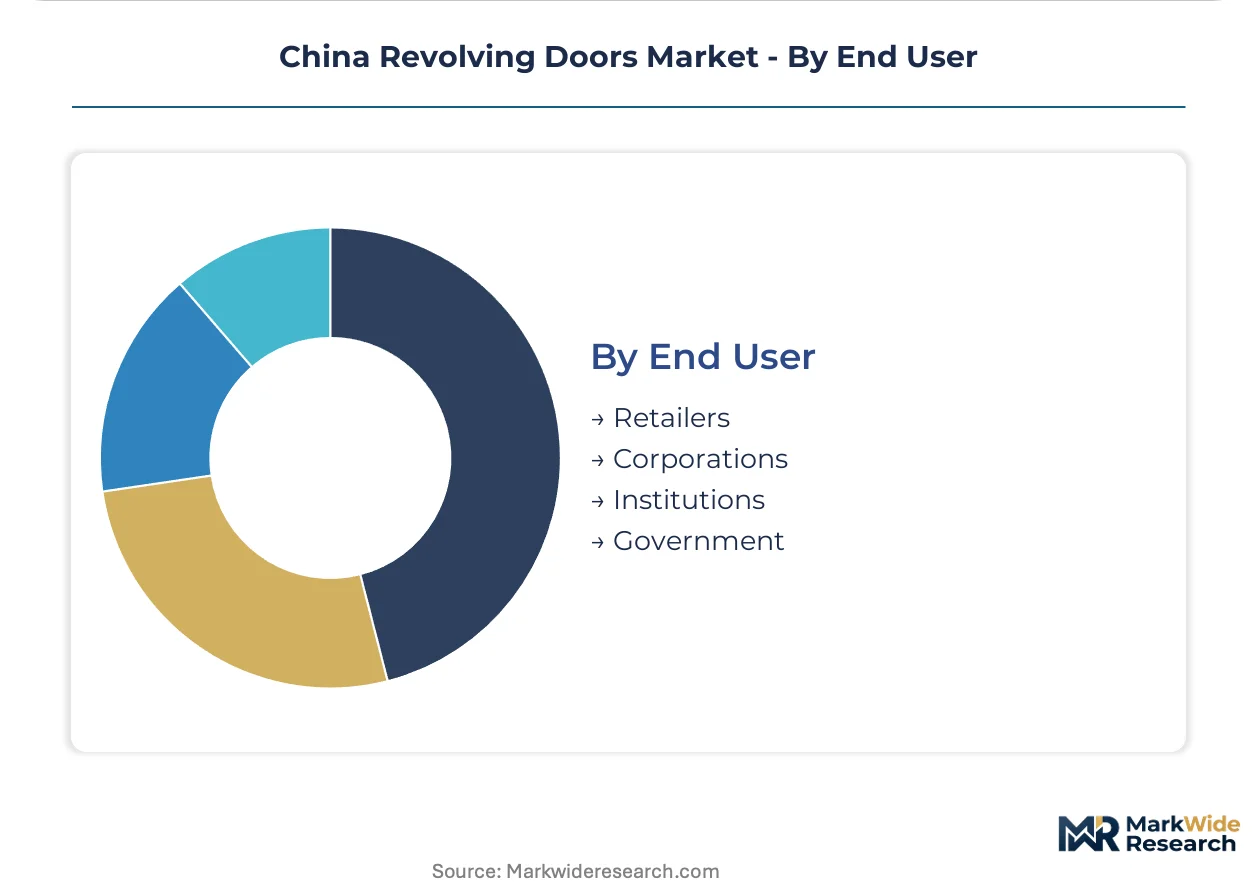
End User:
Customer type determines service contract structures and technical response requirements across regional distribution networks.
- Corporations:Facility management teams in Tier-1 cities unbundle after-sales service from initial equipment procurement. Same-day response coverage has become a competitive differentiator for commercial developers in Jiangsu province.
- Government:Security-rated specifications with certified blast-resistant engineering dominate embassy and administrative building procurement. SAMR conformity assessment creates extended approval timelines for custom installations.
- Retailers:Flagship store operators prioritizing brand visibility through bespoke glass-intensive entrance designs.
- Institutions:Universities and cultural facilities balancing budget constraints with durability requirements.
Corporations drive the largest contract values, with Government representing the most stringent certification pathway.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Skilled glazing technicians and aluminum fabrication specialists cluster along China's eastern seaboard, anchoring production capacity for high-performance entrance systems. Regional demand patterns track municipal energy code enforcement intensity and commercial construction permit volumes.
Beijing-Tianjin-Hebei
Administrative building modernization and embassy district security upgrades drive specification of blast-resistant configurations. MEE enforcement mandates documented U-value calculations for permit approval. Beijing developers pre-specify certified systems to avoid construction delays from extended GB 15763 safety glass certification timelines.
Yangtze River Delta
Shanghai luxury hospitality renovation cycles and Suzhou-Nantong commercial tower construction sustain automatic system procurement. Jiangsu provincial construction bureaus enforce thermal break performance requirements for entrance assemblies. Nanjing anchors regional distribution networks extending same-day technical service coverage across Jiangsu province.
Pearl River Delta
Shenzhen municipal green building rating systems tighten embodied carbon thresholds for facade subsystems ahead of national harmonization. Guangzhou mixed-use developments specify sensor-activated drive systems for HVAC load reduction. Dongguan fabrication clusters supply thermally broken aluminum extrusions per GB 5237 standards.
Sichuan-Chongqing
Chengdu commercial construction activity in emerging Tier-2 markets shows underpenetrated automatic door specification. Chongqing's western logistics hub status attracts regional distribution center investments. Local developers balance first-cost sensitivity with tightening provincial energy codes for entrance system upgrades.
China Revolving Doors Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across China's revolving door market structure. Integrated glass fabricators control material costs through captive supply chains, while specialized automatic door engineering firms compete on security-rated certification depth. The vendor base fragments across three strategic archetypes: integrated materials processors, security-specialized engineering houses, and regional service-anchored distributors. Dominant competitive moves include backward integration into aluminum extrusion and glass lamination, plus geographic expansion through provincial technical service networks.
Among Shanghai-based fabricators, Shanghai Yupeng Glass Products Co., Ltd. exemplifies the integrated materials processing archetype through its glass fabrication capacity. Shijiazhuang Depuer Automatic Door Control Co., Ltd. occupies a position within the security-specialized tier, while Nanjing Maosong Automatic Door Co., Ltd. represents the regional service-anchored model across Jiangsu province.
| Leading Market Players |
|---|
| Shanghai Yupeng Glass Products Co., Ltd. |
| Shijiazhuang Depuer Automatic Door Control Co., Ltd. |
| Nanjing Maosong Automatic Door Co., Ltd. |
| Beijing Hongtai Dingcheng Automatic Door Technology Co., Ltd. |
| Hefei Tongsheng Doors and Windows Co., Ltd. |
| Qingdao Kaibisheng Automatic Door Engineering Co., Ltd. |
| Hualong Dingsheng Technology Co., Ltd. |
| Zhuhai Jiaxin Building Materials Co., Ltd. |
| ASSA ABLOY |
| Others |
Pricing and Supply Chain Analysis
Backward integration into aluminum extrusion and glass lamination anchors supply positioning for leading fabricators while compressing cost structures for high-specification lobby installations. Shanghai Yupeng Glass Products leverages captive glass fabrication capacity to control material costs, while Dongguan-based extrusion clusters feed thermally broken frame production per GB 5237 standards. This integration choice directly shapes pricing power across procurement channels, as integrated producers defend margin structures against asset-light competitors dependent on spot-market aluminum and certified glass supply.
Pricing Analysis
The bundled-vs-unbundled service split is reshaping contract structures as facility management teams in Tier-1 cities separate after-sales technical service from initial equipment procurement. Three-tier pricing structure across premium automatic, standard manual, and economy security-rated configurations stratifies procurement decisions, with certification grade and after-sales response time driving price differentiation. Pricing pressure stems from aluminum alloy input cost volatility tied to smelter energy pricing, while municipal and educational buyers in inland provinces exhibit strongest first-cost sensitivity.
Supply Chain Analysis
Refurbishment flows for legacy entrance systems remain underdeveloped, though regional distributors in Jiangsu province are piloting component recovery programs for brush-sealed drive mechanisms. Primary supply concentrates in China, with secondary glass lamination capacity in South Korea and specialty sensor imports from Japan. Raw material dependencies rest on primary aluminum ingots, safety-rated laminated glass per GB 15763, and brush-seal polymer compounds. Single-source vulnerability characterizes SAMR-certified glass suppliers for blast-resistant configurations. Distribution runs through provincial technical service networks anchored in Nanjing and Shanghai.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
China's revolving door market functions as a regulatory compounder, with MEE enforcement of building energy efficiency codes and tightening GB standards for thermal break performance creating sustained specification pull across commercial construction and retrofit programs.
For Market Incumbents: Extend same-day technical service coverage into emerging Tier-2 Yangtze River Delta cities before regional distributors consolidate provincial networks. Deepen backward integration into thermally broken aluminum extrusion to offset primary aluminum price volatility threatening margin structures. Invest in GB 15763 safety glass certification depth to capture embassy and government verticals where SAMR conformity assessment creates extended approval barriers for competitors. For New Entrants and Emerging Players: Launch via unbundled after-sales service contracts targeting facility management teams in Jiangsu and Zhejiang provinces where incumbent coverage gaps persist. White-space concentrates in Chengdu and Chongqing commercial construction corridors with underpenetrated automatic door specification amid tightening provincial energy codes. Target security-rated engineering convergence by partnering with biometric access control specialists for government facility procurement. For Investors and Strategic Acquirers: Roll-up economics work for regional service-anchored distributors because fragmented technical coverage across China's provincial construction markets prevents national scale concentration. Long-term viability hinges on positioning ahead of municipal green building rating system harmonization. Acquisition targets should exhibit captive aluminum extrusion or glass lamination capacity. Monitor MEE inspection protocol intensity for thermal break performance as inflection indicator for specification acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Aluminum Extrusion | Captive supply of GB 5237-certified thermally broken frames insulates margin structures from smelter energy price spikes. |
| GB 15763 Safety Glass Certification Investment | SAMR conformity assessment depth opens blast-resistant government and embassy verticals with extended approval timelines. |
| Provincial Technical Service Network Expansion | Same-day response coverage in Jiangsu and Zhejiang secures unbundled after-sales contracts from facility management teams. |
| Biometric Access Control Partnership | Security-rated engineering convergence creates differentiated positioning for government facility procurement cycles. |
| Tier-2 Yangtze River Delta Market Entry | Emerging city commercial construction in Suzhou-Nantong corridor shows automatic system specification gaps versus Shanghai saturation. |
Research Methodology
Coverage spans Beijing-Tianjin-Hebei, Yangtze River Delta, Pearl River Delta, and Sichuan-Chongqing, with primary inputs from each construction bureau jurisdiction. The approach combines interviews with commercial developers, facility management directors, provincial construction bureau officials, and automatic door engineering specialists, validated against secondary sources including GB standards documentation, SAMR conformity assessment records, MEE energy code enforcement bulletins, and provincial permit approval databases. Bottom-up project pipeline analysis triangulates with top-down construction spending forecasts.
Rate-of-change decomposition separates volume growth from value mix shift across the projection horizon. The analytical framework models product type segmentation across manual, automatic, security, and custom configurations; material tier differentiation by aluminum, glass, steel, and wood; and application clustering across commercial buildings, hotels, airports, and malls. CAGRs derive from construction permit trajectory analysis and energy code compliance cost modeling. Industry-specific inputs include MEE inspection protocol intensity indices and GB 15763 certification timeline distributions.
Forecast precision tightens around the base case; tail outcomes carry wider variance under aluminum price volatility extremes or sudden GB standard revision cycles. Forecasts reflect documented assumptions regarding municipal green building rating system harmonization timing and Tier-2 city commercial construction permit trajectories. Practitioners should monitor MEE thermal break enforcement intensity and SAMR safety glass certification backlog durations for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Automation Systems
Intelligent Building Automation Technologies Market
Building Automation Systems
Europe Smart Windows Market
Building Automation Systems
Smart Window Film Market
Building Automation Systems
Asia-Pacific Building Automation System Market
Building Automation Systems
Building Management System Market
Building Automation Systems
Residential Electric Underfloor Heating Market
Building Automation Systems
Platform Screen Door System Market
Building Automation Systems
Elevator Modernization Market
Building Automation Systems
Smart Building Solutions Market
Building Automation Systems
Global HVAC Controls Market
Building Automation Systems
Global Enterprise Building Solutions Market
Building Automation Systems
Zero Energy Buildings Market
Building Automation Systems
Smart Garage Door Opener and Controller Market
Building Automation Systems
Computer-Aided Facility Management (CAFM) Market
Building Automation Systems
Flushing Systems Market
Building Automation Systems
United States Smart Windows Market