
 Elevator Modernization Market | 2026-2036
Elevator Modernization Market Size, Share, and Industry Trends Forecast 2026-2036
Elevator Modernization Market Intelligence
Aging certified elevator technician pools across Germany, Japan, and the United States is redrawing how service networks deploy upgrade crews. Otis Elevator Company leverages its apprenticeship pipelines in North America to sustain faster project turnaround times. KONE Corporation anchors its competitive stance through predictive maintenance platforms that reduce unplanned downtime for commercial clients. Schindler Group differentiates by controlling proprietary door system retrofit kits that integrate with legacy controller architectures.
Elevator modernization encompasses the partial or complete replacement of existing elevator components—controllers, drive motors, door operators, safety circuits, and landing systems—to extend equipment life, improve energy efficiency, and meet current safety codes. Modern traction upgrades typically replace DC gearless machines with permanent-magnet synchronous motors achieving efficiency ratings above ninety percent, while smart elevator retrofits add destination-dispatch algorithms and IoT sensor arrays to optimize passenger flow in high-rise commercial buildings. Control systems and door systems command the largest share of product-type revenue due to their shorter replacement cycles and direct impact on code compliance. Smart elevators represent the fastest-expanding technology segment as building operators seek connectivity platforms that interface with broader building-management systems.
The U.S. Department of Energy enforces minimum efficiency standards for new and modernized elevator installations, while the EU Green Deal and F-Gas Regulation restrict refrigerants and drive materials used in hydraulic system rebuilds. Japan's METI promotes elevator energy conservation through subsidy programs tied to permanent-magnet motor retrofits in commercial structures. Stakeholders must monitor how fragmented municipal adoption timelines for ASME A17.1 code updates across U.S. states reshape project backlogs and technician certification requirements.
Market Dynamics
The elevator modernization market is compressing around a single structural force: the collision between aging installed bases in commercial buildings and mandatory efficiency retrofits driven by the EU Green Deal and parallel U.S. Department of Energy standards. This pressure is forcing building operators to choose between full system replacement and phased component upgrades, redrawing supplier economics and technician deployment models.
Growth Catalysts
- EU F-Gas Regulation:Restrictions on hydraulic system refrigerants and drive materials are compelling commercial property owners in Germany and France to accelerate traction system conversions.
- Permanent-magnet synchronous motors:Efficiency ratings above ninety percent are displacing DC gearless machines in high-rise retrofits, cutting energy consumption for multi-tenant commercial properties.
- Japan METI subsidy programs:Direct financial incentives for commercial building energy conservation are accelerating motor retrofit adoption in Tokyo and Osaka metropolitan zones.
Market Restraints
- Copper and rare-earth magnet cost volatility:Permanent-magnet motor production faces input price swings that compress margins on fixed-price modernization contracts.
- Certified technician concentration in Germany and Japan:Aging apprenticeship pipelines in these markets are creating supply bottlenecks for complex control system installations.
- Fragmented ASME A17.1 adoption timelines:U.S. states are implementing code updates at uneven speeds, delaying project approvals and extending sales cycles.
Strategic Opportunities
- Destination-dispatch algorithm integration:Smart elevator retrofits that interface with building-management systems represent white space in mid-rise commercial properties.
- India's commercial building stock:Underpenetrated modernization demand in Mumbai and Bangalore is opening channels for predictive maintenance platform providers.
- IoT sensor array convergence with safety circuits:Combined hardware-software offerings are creating new revenue streams beyond traditional component replacement.
Industry Challenges
- Controller-to-legacy architecture integration:Retrofit kits must interface with proprietary door systems from multiple generations, requiring custom engineering for each installation.
- ASME A17.1 certification timelines:Technician recertification requirements vary across U.S. states, complicating crew deployment for national service networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Elevator Modernization Market |
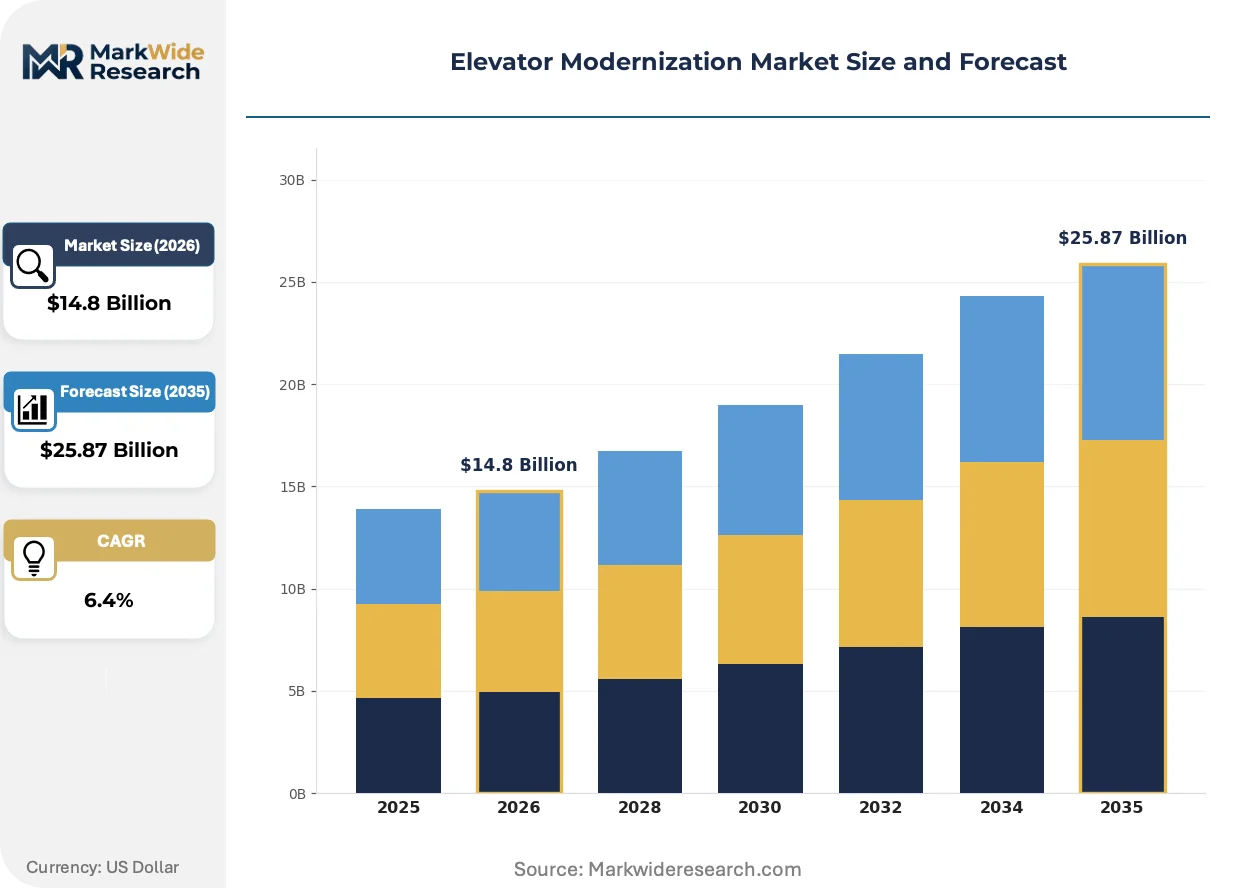
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $25.87 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Control Systems, Drive Systems, Door Systems, Safety Systems Technology: Hydraulic, Traction, Machine Room-Less, Smart Elevators Application: Commercial Buildings, Residential Buildings, Industrial Facilities, Healthcare Facilities Service Type: Replacement, Upgrade, Maintenance, Consulting |
| Companies Covered | Otis Elevator Company, KONE Corporation, Schindler Group, Thyssenkrupp AG, Mitsubishi Electric Corporation, Hitachi Ltd., Fujitec Co. Ltd., TK Elevator, Hyundai Elevator Co. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Elevator Modernization Market Strategic Shifts & Innovations
Modernization activity is pivoting from reactive component failure replacement toward preemptive efficiency-driven overhauls. This shift is compressing upgrade cycles and elevating the importance of connectivity platforms that extend equipment life while reducing operating costs.
Machine-room-less traction technology is bifurcating the modernization market between high-rise commercial buildings and mid-rise properties. Building operators in dense urban centers are adopting compact permanent-magnet gearless machines to reclaim leasable square footage. The technology is bifurcating supplier strategies, with some vendors specializing in space-constrained retrofits while others focus on heavy-duty freight and hospital elevator conversions.
The EU F-Gas Regulation is tightening material restrictions on hydraulic system rebuilds, forcing building owners to abandon refurbishment in favor of complete traction replacements. Industrial consequence includes accelerated obsolescence of legacy hydraulic infrastructure across multi-tenant commercial properties. Germany's federal building codes are responding fastest, with municipal inspectors rejecting permits for refrigerant-dependent rebuilds in Frankfurt and Munich commercial zones.
Service contract unbundling is fragmenting the traditional full-coverage model into component-specific agreements. Building operators in U.S. metropolitan markets are separating door operator maintenance from drive system coverage, enabling competitive bidding on individual subsystems. This pattern is most visible in Chicago and New York, where large commercial portfolios are driving standardization of modular service tiers.
Elevator Modernization Market Segmentation
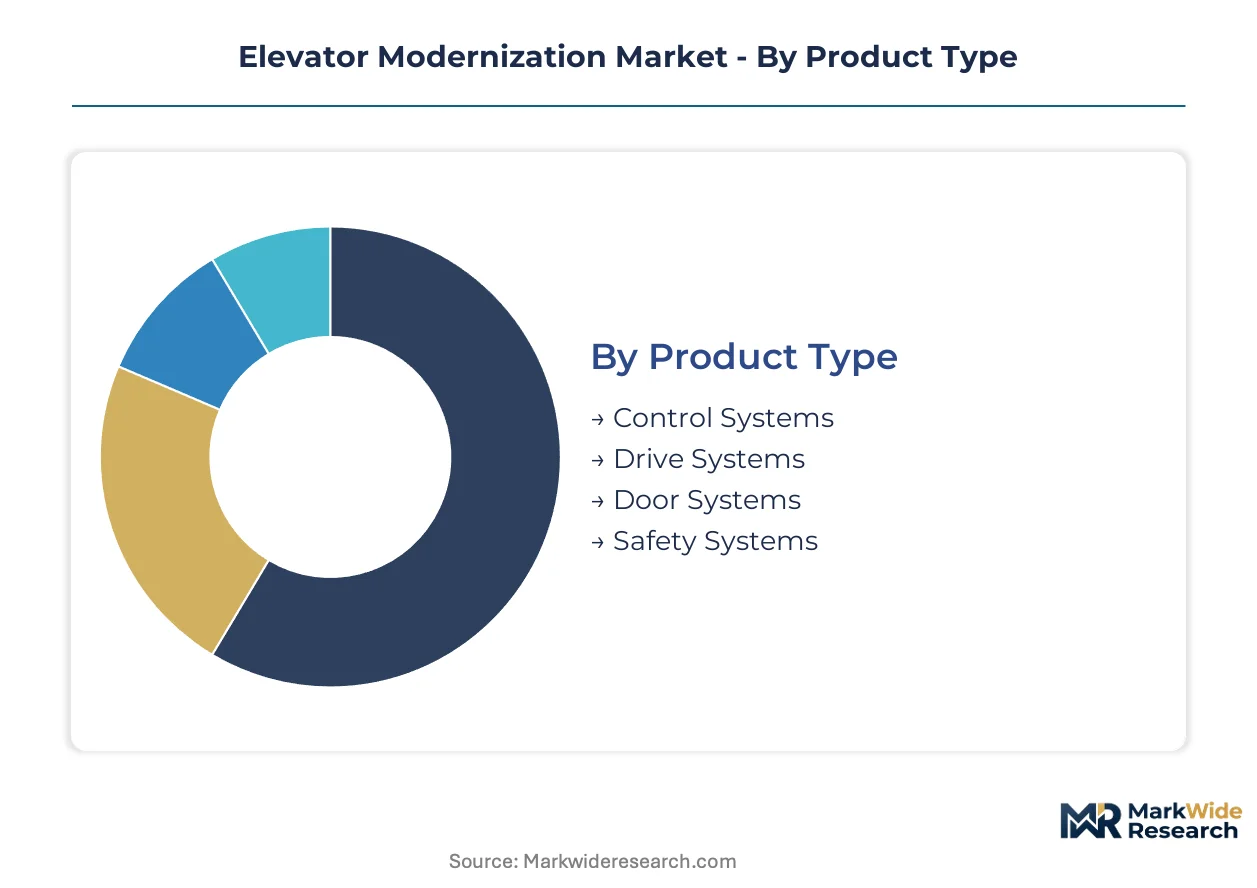
Elevator modernization suppliers capture margin through component specialization and technology tiering. Product type and technology segments command distinct pricing power based on replacement cycle urgency and regulatory compliance requirements.
Product Type:
Control systems and door systems concentrate margin pools through shorter replacement cycles and direct code compliance linkages.
- Control Systems:Microprocessor-based controllers replace relay-logic systems to meet current safety codes. Demand concentrates in Germany's commercial zones where F-Gas Regulation mandates traction conversions requiring controller reprogramming.
- Door Systems:Retrofit kits integrate landing door operators with legacy architectures to reduce entrapment incidents. Multi-tenant properties in Chicago and New York drive volume through unbundled service contracts separating door maintenance from drive coverage.
- Drive Systems:Permanent-magnet synchronous motors displace DC gearless machines in high-rise efficiency retrofits.
- Safety Systems:Brake monitors and overspeed governors address ASME A17.1 compliance gaps in aging installations.
The dominant share belongs to Control Systems, while Door Systems is closing the gap fastest through modular service tier adoption.
Technology:
Technology tiers separate refurbishment economics from full replacement premiums across building height categories.
- Smart Elevators:Destination-dispatch algorithms and IoT sensor arrays optimize passenger flow in high-rise commercial buildings. Tokyo and Osaka metropolitan zones accelerate adoption through METI subsidy programs tied to building energy conservation.
- Traction:Geared and gearless machine upgrades replace hydraulic systems under EU refrigerant restrictions. Frankfurt and Munich municipal inspectors reject permits for refrigerant-dependent rebuilds, forcing complete traction conversions.
- Machine Room-Less:Compact permanent-magnet gearless machines reclaim leasable square footage in space-constrained urban retrofits.
- Hydraulic:Cylinder and power unit rebuilds face accelerated obsolescence from F-Gas material restrictions.
Traction retains the largest installed base, though Smart Elevators expands most quickly through building-management system integration demand.
Application:
Building use type dictates upgrade urgency based on occupancy density and liability exposure.
- Commercial Buildings:Multi-tenant offices and retail centers prioritize efficiency retrofits to reduce operating costs. Germany's federal building codes impose the strictest traction conversion timelines in Frankfurt commercial zones.
- Healthcare Facilities:Hospital elevator reliability requirements drive preemptive control system overhauls to minimize patient transport delays.
- Residential Buildings:Condominium associations balance assessment costs against safety code update deadlines.
- Industrial Facilities:Freight elevators in manufacturing plants require heavy-duty drive system replacements.
Commercial Buildings anchor segment revenue, while Healthcare Facilities climbs fastest on reliability mandates.
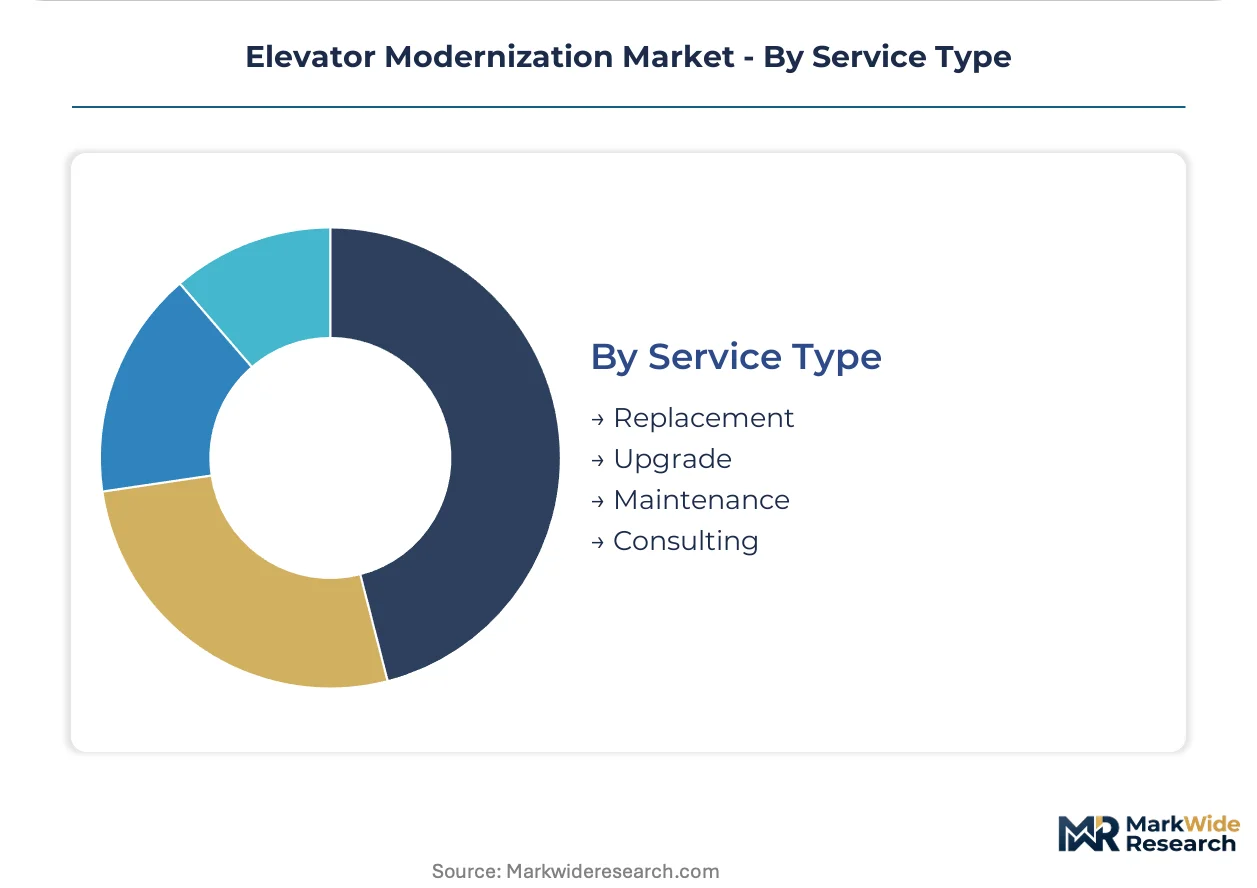
Service Type:
Service unbundling fragments traditional full-coverage contracts into component-specific revenue streams.
- Replacement:Full system overhauls address end-of-life equipment and regulatory non-compliance. EU F-Gas Regulation accelerates hydraulic-to-traction conversions in French commercial properties.
- Upgrade:Phased component modernization extends equipment life without full replacement.
- Maintenance:Predictive platforms reduce unplanned downtime through sensor-based monitoring.
- Consulting:Energy audits and code compliance assessments guide modernization prioritization.
Replacement commands the largest contract value, while Maintenance gains share fastest through platform subscription models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EU F-Gas Regulation anchors European demand dynamics, while Japan's METI subsidy programs and the U.S. Department of Energy standards shape parallel modernization waves across distinct regulatory environments.
Germany
Aging commercial building stock and municipal code enforcement accelerate traction system replacements. The F-Gas Regulation and federal building codes restrict hydraulic system rebuilds, forcing complete conversions. Frankfurt and Munich municipal inspectors reject refrigerant-dependent permits, concentrating project volume in these commercial zones.
United States
Multi-tenant commercial properties and unbundled service contracts drive component-level upgrades. The Department of Energy enforces minimum efficiency standards for modernized installations. Chicago and New York anchor demand through large commercial portfolios adopting modular service tiers.
Japan
Commercial building energy conservation targets and aging high-rise infrastructure propel permanent-magnet motor retrofits. METI subsidy programs tie financial incentives to efficiency improvements in commercial structures. Tokyo and Osaka metropolitan zones concentrate adoption through direct incentive alignment.
India
Underpenetrated modernization demand in commercial building stock creates expansion opportunities for predictive maintenance platforms. The Bureau of Indian Standards and state-level energy codes establish baseline compliance requirements. Mumbai and Bangalore emerge as primary clusters for service provider market entry.
France
Commercial property owners accelerate hydraulic-to-traction conversions under refrigerant material restrictions. The EU F-Gas Regulation and national implementation protocols compel full system replacements over refurbishment. Paris commercial districts concentrate permit activity as municipal enforcement tightens.
Elevator Modernization Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes, creating a tiered competitive structure where premium connectivity providers and volume-focused component suppliers occupy distinct economic positions. The market consolidates around full-service elevator OEMs with captive installed bases and independent modernization specialists targeting mid-rise commercial properties. Three archetypes dominate: integrated platform providers bundling hardware with predictive software, component specialists controlling proprietary retrofit architectures, and regional service contractors competing on technician deployment speed. M&A activity concentrates on predictive maintenance platform acquisitions, while vertical integration into door system manufacturing represents the second dominant competitive move.
Within the integrated platform tier, Otis Elevator Company, KONE Corporation, and Schindler Group exemplify archetypes competing through distinct capability emphases. Otis represents the apprenticeship pipeline model sustaining technician workforce scale. KONE occupies a position anchoring predictive maintenance platform deployment. Schindler exemplifies proprietary component control through specialized retrofit kit architectures. These three entities collectively illustrate how market positioning diverges across workforce development, software integration, and hardware specialization vectors without any single archetype commanding universal advantage.
| Leading Market Players |
|---|
| Otis Elevator Company |
| KONE Corporation |
| Schindler Group |
| Thyssenkrupp AG |
| Mitsubishi Electric Corporation |
| Hitachi Ltd. |
| Fujitec Co. Ltd. |
| TK Elevator |
| Hyundai Elevator Co. Ltd. |
| Others |
Cost & Logistics Intelligence
Permanent-magnet synchronous motor substitution for DC gearless machines is redrawing supply geography toward rare-earth processing clusters in China while compressing margins on fixed-price modernization contracts across European and North American markets. This input transition simultaneously elevates pricing volatility for motor-drive assemblies and forces building operators toward longer procurement cycles to hedge magnet cost exposure.
Pricing Analysis
German modernization projects command fifteen to twenty percent premiums over comparable French installations due to stricter F-Gas compliance engineering requirements and certified technician scarcity. Three-tier pricing structure across premium connectivity bundles, standard component replacements, and economy hydraulic refurbishments stratifies the market, with premium tiers capturing predictive maintenance subscriptions. Cost compression in the economy tier is intensifying because copper and rare-earth magnet price swings erode fixed-contract profitability. Mid-rise commercial property managers in Chicago and New York exhibit highest price sensitivity, while healthcare facilities in Tokyo accept premium positioning for reliability guarantees.
Supply Chain Analysis
Controller and drive motor inventories stretch to fourteen-week lead times when sourced from Chinese rare-earth processing centers, compressing project scheduling flexibility for North American service networks. Manufacturing concentrates in China for permanent-magnet motors, Germany for precision controllers, and Japan for safety circuit components. The supply chain draws from neodymium-iron-boron magnets, copper windings, and microprocessor chipsets. Single-source vulnerability in Chinese rare-earth refining creates exposure to export restriction shocks. Distribution runs through OEM captive service branches in Frankfurt and Tokyo, with independent contractors capturing mid-rise volume in Mumbai and Bangalore.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Elevator modernization is crossing into platform-economics territory where predictive maintenance data streams and building-management system interoperability determine supplier stickiness beyond hardware replacement cycles.
For Market Incumbents: Secure predictive maintenance platform dominance through backward integration into IoT sensor manufacturing, insulating against modular service unbundling by independent contractors. Deepen captive technician pipelines in Germany and Japan where aging apprenticeship pools threaten deployment capacity. Control proprietary door system architectures to lock out third-party retrofit kit competitors from legacy controller integrations. For New Entrants and Emerging Players: Lead with destination-dispatch algorithm specialization targeting mid-rise commercial properties in Mumbai and Bangalore where predictive maintenance penetration remains underdeveloped. India's Bureau of Indian Standards compliance pathway offers lower certification barriers than EU F-Gas or ASME A17.1 jurisdictions. Partner with regional facility management conglomerates to embed software subscriptions within bundled building operations contracts. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors predictive maintenance platform specialists with proven hospital and airport reference sites. Long-term viability hinges on recurring revenue attachment rates exceeding hardware replacement cyclicality. Monitor METI subsidy renewal trajectories and EU Green Deal enforcement intensity as demand inflection signals.| Strategic Initiative | Industry Significance |
|---|---|
| Predictive Maintenance Platform Acquisition | Captures recurring revenue streams from hospital and airport reliability contracts. |
| Permanent-Magnet Motor Manufacturing Scale-Up | Reduces rare-earth magnet cost exposure for German traction conversion projects. |
| Door System Retrofit Kit Patent Expansion | Blocks third-party competitors from legacy controller architectures in Chicago. |
| Technician Apprenticeship Pipeline Investment | Resolves certified crew bottlenecks constraining Tokyo metropolitan project throughput. |
| Building-Management System Integration Partnership | Positions smart elevator data streams within commercial property IoT ecosystems. |
Research Approach
Initial hypotheses were tested against primary input from elevator service operations directors, commercial property facility managers, certified technician union representatives, and municipal code enforcement officials, then refined through secondary validation. Primary fieldwork encompassed structured interviews across OEM service branches and independent modernization contractors. Secondary sources included ASME A17.1 code update filings, EU F-Gas Regulation implementation protocols, METI subsidy disbursement records, and Bureau of Indian Standards certification databases. Bottom-up project pipeline estimates were triangulated against top-down building stock age distributions.
Variance decomposition across the projection horizon isolates regulatory enforcement intensity, rare-earth magnet price trajectories, and technician workforce demographics as primary uncertainty sources. Segmentation modeling spans product type, technology tier, building application, and service contract structure. CAGRs were derived from installed base age profiles and replacement cycle compression rates. Forecast inputs incorporate F-Gas compliance deadline phasing and METI incentive program renewal assumptions.
The analysis sits within stated boundaries; outcomes outside sustained EU Green Deal enforcement or abrupt rare-earth export restrictions would require recalibration. Forecasts reflect documented assumptions regarding code adoption timelines and subsidy continuity. Copper price volatility and ASME A17.1 state-level fragmentation represent specific revision risks. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Automation Systems
Smart Garage Door Opener and Controller Market
Building Automation Systems
Building Analytics Market
Building Automation Systems
Smart Building Solutions Market
Building Automation Systems
Electrochromic Glass Market
Building Automation Systems
Global Platform Screen Doors for Subway Lines Market
Building Automation Systems
Smart Window Film Market
Building Automation Systems
Platform Lifts Market
Building Automation Systems
Global Enterprise Building Solutions Market
Building Automation Systems
Underfloor Heating Actuator Market
Building Automation Systems
Rotary Sprinkler System Market
Building Automation Systems
Europe Smart Windows Market
Building Automation Systems
Europe Building Automation Systems Market
Building Automation Systems
North America Building Automation System Market
Building Automation Systems
Dumbwaiter Lifts Market
Building Automation Systems
Smart Passenger Elevators Market
Building Automation Systems
Building Technologies Market