
 Platform Lifts Market | 2026-2036
Platform Lifts Market Size, Share, and Industry Trends Forecast 2026-2036
Platform Lifts Market Analytics
EN 81-41 certification is rotating the competitive landscape by filtering out suppliers lacking third-party validation for vertical platform lift safety systems. KONE leverages its pan-European service network to sustain recurring maintenance contracts alongside new equipment sales. Stannah specializes in compact residential inclined platform lifts that anchor its position in home accessibility retrofits. Otis competes through controls over high-rise commercial specification channels where dual-brand strategies with local installers extend geographic reach.
Platform lifts are electromechanical or hydraulic elevation systems designed to transport passengers or goods between levels at speeds typically below 0.15 m/s, incorporating interlocked gates, emergency lowering devices, and non-slip platform surfaces for safe vertical transit in low-rise buildings. Their primary purpose is to provide code-compliant accessibility in structures where full passenger elevators prove structurally or economically impractical. Vertical platform lifts occupy the largest installed base among product types due to straightforward retrofit compatibility with existing stairwells and doorways. Hydraulic technology leads in heavy-duty commercial and industrial applications where load capacity exceeds 400 kg, though electric drive systems are gaining specification share in residential settings where energy efficiency and reduced maintenance intervals matter more to facility managers and homeowners.
CE marking under the EU Machinery Directive, FDA facility accessibility guidelines for US healthcare construction, and BIS IS 14671 standards for Indian building accessibility collectively shape product design requirements, testing protocols, and market entry pathways across major demand centers. Japan's METI building barrier-free mandates and Australia's Disability Discrimination Act compliance deadlines are adding regulatory layers that favor permanent over portable installations in public infrastructure projects. Stakeholders must monitor how evolving national building codes reconcile with ISO 9386 platform lift standards to avoid specification conflicts during cross-border project bidding.
Market Dynamics
EN 81-41 certification timelines are compressing supplier qualification windows across Europe, forcing manufacturers to accelerate third-party validation or cede specification access to certified rivals.
Growth Catalysts
- Germany's public building mandates:Federal accessibility requirements for municipal structures are accelerating retrofit procurement cycles in aging infrastructure districts.
- EU Machinery Directive compliance:CE marking enforcement is standardizing safety protocols and expanding addressable market for validated platform lift systems.
- Electric drive technology:Energy-efficient motor systems are displacing hydraulic alternatives in residential specifications where maintenance intervals drive total cost decisions.
Market Restraints
- Steel and aluminum input volatility:Platform fabrication costs fluctuate with commodity pricing, compressing margin buffers for fixed-price contract bidders.
- Certification timeline friction:EN 81-41 third-party validation cycles extend 12-18 months, freezing new supplier market entry.
- Full passenger elevator substitution:New construction with adequate shaft space and budget flexibility bypasses platform lift specifications entirely.
Strategic Opportunities
- India's BIS IS 14671 adoption:National building accessibility standards are creating specification pathways for certified suppliers in commercial construction.
- Healthcare facility expansion:Patient mobility requirements in hospitals and long-term care centers are elevating platform lift priority in capital planning.
- IoT-enabled predictive maintenance:Sensor integration with remote diagnostics is opening recurring revenue streams beyond equipment sales.
Industry Challenges
- EN 81-41 technical documentation:Engineering teams face capacity constraints preparing safety system evidence packages for notified body review.
- Legacy building structural adaptation:Retrofit installations encounter load-bearing limitations and electrical supply inadequacies requiring costly site remediation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Platform Lifts Market |
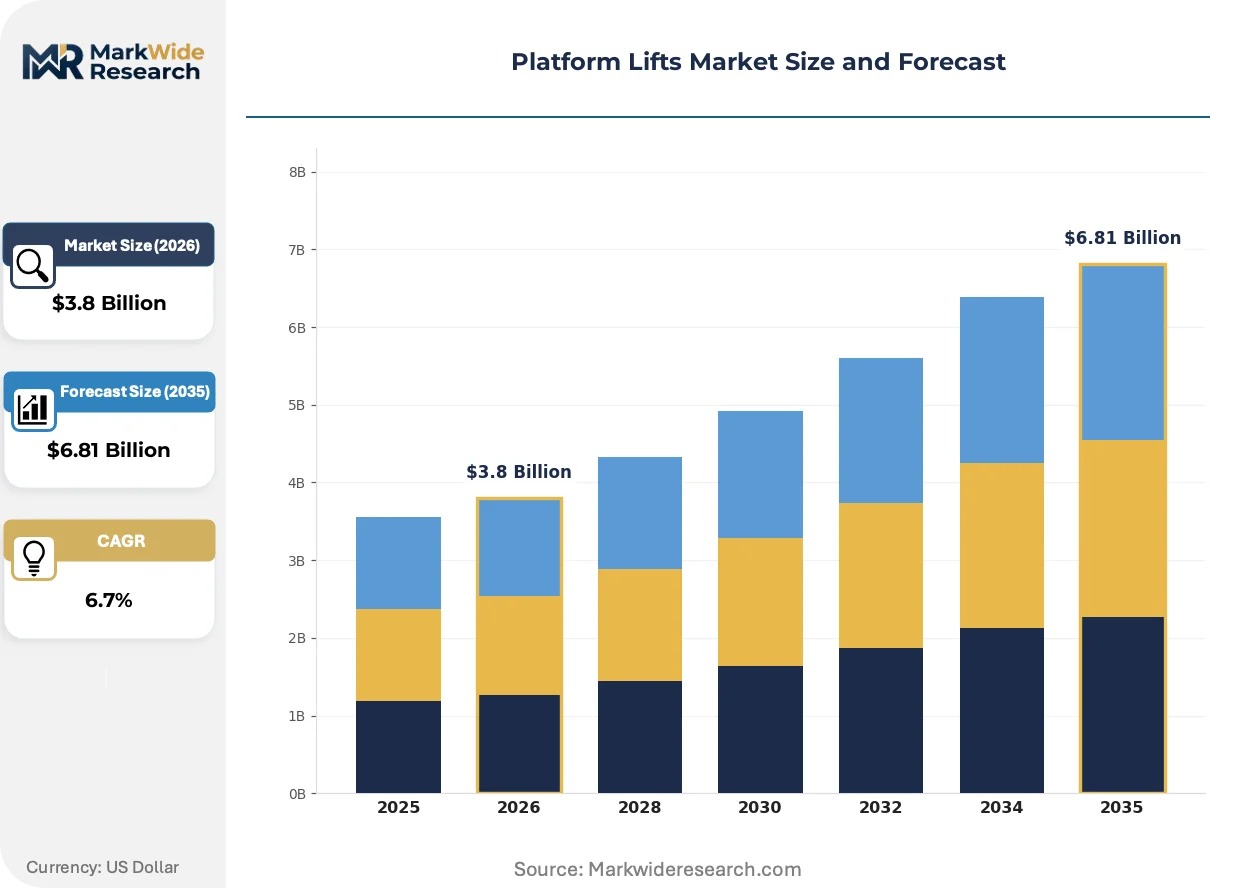
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
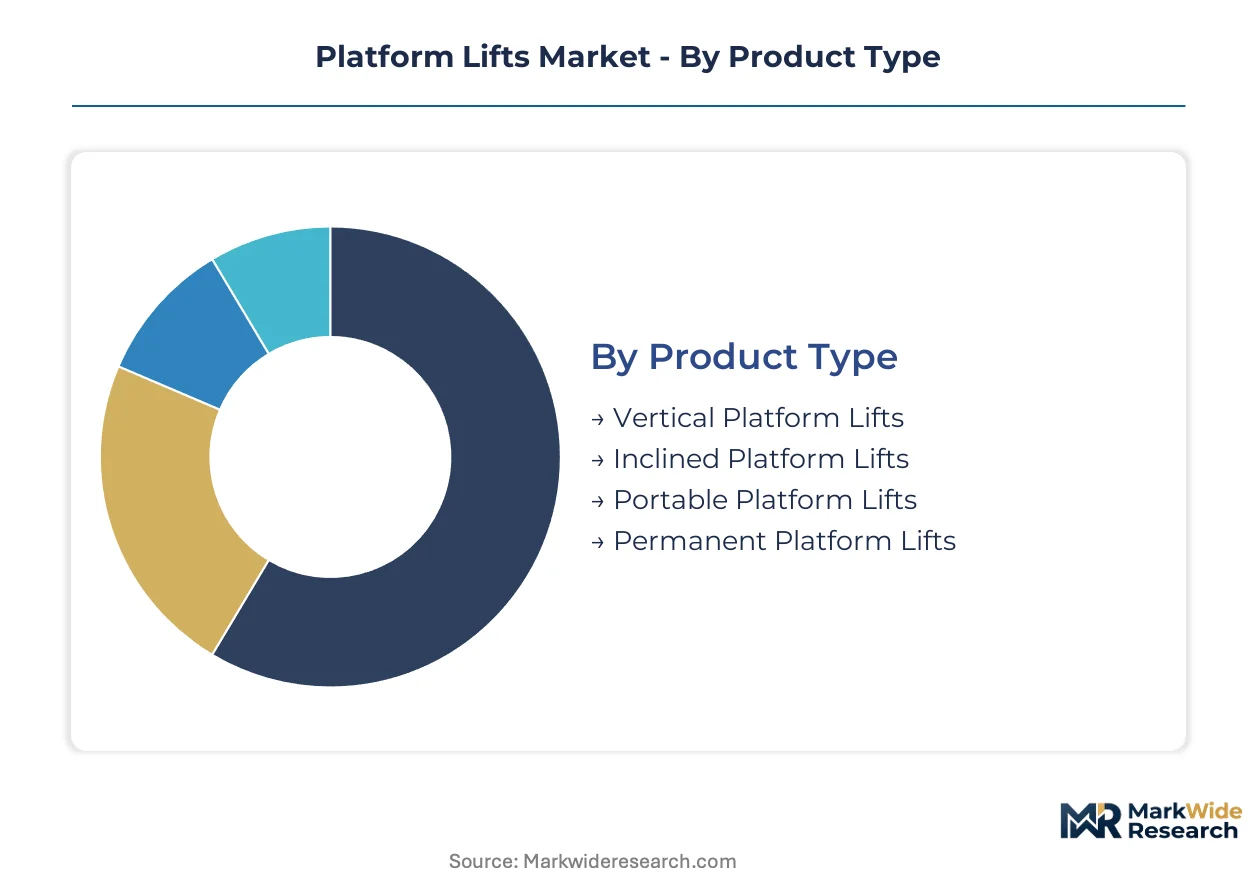
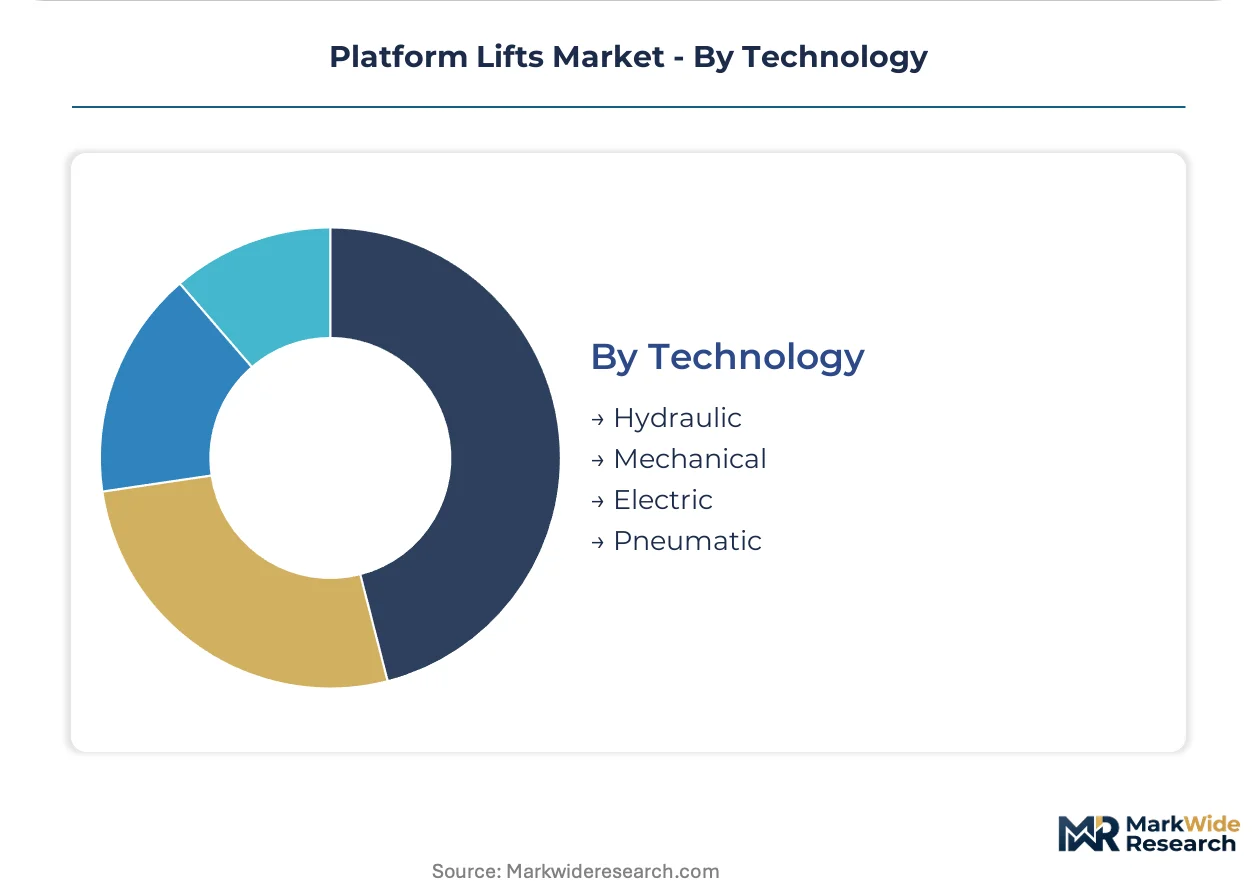
| Segmentation | Product Type: Vertical Platform Lifts, Inclined Platform Lifts, Portable Platform Lifts, Permanent Platform Lifts Application: Residential, Commercial, Public Buildings, Industrial Facilities End User: Homeowners, Facility Managers, Architects, Contractors Technology: Hydraulic, Mechanical, Electric, Pneumatic |
| Companies Covered | KONE, Savaria, Stannah, Thyssenkrupp, Aritco, Alimak, Schindler, Otis, Mitsubishi Electric, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Platform Lifts Market Evolving Landscape
Platform lift technology is fragmenting across performance tiers as end-use requirements diverge between heavy-duty commercial specifications and compact residential installations. Three developments are reshaping competitive positioning.
Electric drive systems is bifurcating the technology landscape between hydraulic heavy-duty platforms exceeding 400 kg capacity and energy-efficient residential alternatives. Facility managers in commercial and industrial settings prioritize load-bearing specifications, while homeowners and small residential developers specify electric units for reduced operational expenditure. This split is compressing mid-range product viability and forcing manufacturers to commit to distinct engineering roadmaps.
Japan's METI building barrier-free mandates are accelerating permanent installation specifications over portable alternatives in public infrastructure. The regulatory framework requires fixed accessibility solutions in new construction and major renovations, eliminating temporary lift options from compliant bids. Municipal project procurement in Tokyo, Osaka, and regional prefectures is rotating toward certified permanent systems with documented seismic resistance.
Specification decisions increasingly hinge on lifecycle service bundling rather than equipment-first procurement. Healthcare facility managers and commercial property operators are unbundling maintenance contracts from initial capital expenditure, selecting suppliers with demonstrated regional service technician density. Germany exhibits the most pronounced shift, where facility management contracts specify response time guarantees and spare parts availability as primary vendor selection criteria.
Platform Lifts Market Segmentation
Platform lift procurement decisions diverge sharply across end-use contexts, with specification criteria for healthcare retrofit projects bearing little resemblance to residential accessibility mandates. Understanding these segment boundaries clarifies where manufacturers must build distinct technical competencies versus where scale economies apply.
Product Type:
Permanent installations face the strongest substitution pressure from full passenger elevators in new construction with adequate shaft space, while portable systems compete against ramps and stairlifts in temporary accessibility scenarios.
- Vertical Platform Lifts:Enclosed or semi-enclosed cab systems moving vertically between levels at speeds below 0.15 m/s, typically accommodating wheelchairs and standing passengers. Demand concentrates in Germany's municipal building retrofits where aging infrastructure lacks elevator shafts and federal accessibility mandates drive compliance deadlines. CE marking under the EU Machinery Directive filters uncertified suppliers from specification pools.
- Inclined Platform Lifts:Folding platform mechanisms that travel along existing staircases on precision rail systems, requiring minimal structural modification. Residential applications in the United Kingdom and France anchor demand where homeowners seek cost-effective alternatives to vertical shaft construction. Compact footprint specifications favor electric drive systems with battery backup for power-independent operation.
- Portable Platform Lifts:Temporary elevation units deployed for event accessibility or short-term rehabilitation needs. Event venues and rental service providers in Japan specify METI-compliant units with documented seismic resistance for public infrastructure projects.
- Permanent Platform Lifts:Fixed installations integrated into building structure with interlocked gates and emergency lowering systems. Healthcare facility expansion in the United States drives FDA-guided accessibility specifications for patient mobility between clinical floors.
Vertical platform lifts anchor the volume base while inclined platform lifts gain share at the steepest rate in residential retrofit markets.
Application:
Cost tier stratification separates premium-specification healthcare installations from economy-focused residential retrofits, with commercial and industrial applications occupying the mid-range.
- Residential:Single-family homes, multi-unit dwellings, and assisted living facilities requiring compact footprint solutions. Electric drive systems displace hydraulic alternatives where energy efficiency and reduced maintenance intervals matter to homeowners. Stannah and similar specialists dominate compact inclined platform specifications.
- Commercial:Retail spaces, office buildings, and hospitality venues requiring code-compliant accessibility without full elevator infrastructure. Germany's public building mandates accelerate procurement cycles in municipal structures across aging infrastructure districts.
- Public Buildings:Government facilities, schools, libraries, and transportation hubs subject to strict accessibility enforcement. Japan's METI barrier-free mandates eliminate portable lift options from compliant bids in Tokyo and Osaka prefectures.
- Industrial Facilities:Manufacturing plants, warehouses, and distribution centers requiring heavy-duty load capacity exceeding 400 kg. Hydraulic technology retains specification dominance where durability under continuous operation outweighs energy efficiency considerations.
Commercial applications anchor the volume base while public buildings expand most quickly under regulatory mandate acceleration.
End User:
Customer type determines whether procurement emphasizes first-cost minimization or lifecycle service bundling, with facility managers and contractors occupying opposite ends of this spectrum.
- Homeowners:Individual purchasers prioritizing compact dimensions, aesthetic integration, and minimal structural disruption. Electric drive residential units with reduced maintenance intervals attract specification in Germany and France where operational expenditure awareness runs high.
- Facility Managers:Professional operators unbundling maintenance contracts from capital expenditure and specifying response time guarantees. Regional service technician density drives vendor selection in Germany's facility management contract market.
- Architects:Design-phase influencers embedding accessibility specifications into construction documents before contractor bidding. Early-stage involvement by KONE and Otis controls high-rise commercial specification channels.
- Contractors:Installation-phase decision-makers adapting specifications to field conditions and structural constraints. Legacy building retrofit projects encounter load-bearing limitations requiring costly site remediation.
Facility managers anchor the volume base while architects gain influence fastest as design-phase accessibility integration becomes standard practice.
Technology:
Supply concentration in hydraulic component manufacturing contrasts with fragmented electric drive motor sourcing, shaping margin structures and supplier negotiation leverage.
- Hydraulic:Fluid-power systems utilizing piston-cylinder arrangements for heavy-load vertical movement. Industrial and commercial specifications in India favor hydraulic technology where BIS IS 14671 compliance meets load capacity requirements.
- Mechanical:Screw-drive or rack-and-pinion systems offering precise positioning without hydraulic fluid maintenance. Niche applications in clean environments and food-processing facilities specify mechanical alternatives.
- Electric:AC or DC motor systems with energy-efficient operation and reduced maintenance intervals. Residential settings in Germany and Japan specify electric drives where total cost of ownership calculations favor operational expenditure reduction.
- Pneumatic:Air-pressure systems utilizing vacuum or positive pressure for cab elevation, rare in platform lift applications. Limited deployment in specialized explosion-risk environments where electrical spark hazards must be eliminated.
Hydraulic systems anchor the volume base while electric technology climbs the fastest in residential and light-commercial specifications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Facility managers and municipal procurement officers dominate platform lift purchasing decisions across concentrated demand pockets in Germany, Japan, and the United States, where aging infrastructure retrofits intersect with tightening accessibility mandates.
Germany
Federal accessibility requirements for municipal structures accelerate retrofit procurement cycles in aging infrastructure districts. EN 81-41 certification under the EU Machinery Directive filters uncertified suppliers from public sector specification pools. Procurement concentrates in North Rhine-Westphalia and Bavaria where municipal building renovation budgets prioritize permanent vertical platform installations.
Japan
METI building barrier-free mandates eliminate portable lift options from compliant bids in public infrastructure projects. The regulatory framework requires fixed accessibility solutions with documented seismic resistance in new construction and major renovations. Tokyo and Osaka prefectures rotate procurement toward certified permanent systems as municipal project specifications harden.
United States
FDA facility accessibility guidelines drive platform lift prioritization in hospital and long-term care capital planning. Healthcare construction standards embed patient mobility requirements between clinical floors into design-phase specifications. Demand clusters in Texas and Florida where healthcare facility expansion outpaces new elevator shaft construction.
India
BIS IS 14671 national building accessibility standards create specification pathways for certified suppliers in commercial construction. Bureau of Indian Standards compliance opens procurement channels previously blocked by inconsistent local code enforcement. Maharashtra and Karnataka lead adoption as commercial developers integrate accessibility specifications into premium office and retail projects.
United Kingdom
Residential retrofit demand anchors specification volume for compact inclined platform lifts in single-family homes and multi-unit dwellings. Homeowners prioritize cost-effective alternatives to vertical shaft construction in aging housing stock. Demand concentrates in Greater London and the Southeast where property values justify accessibility investments.
Platform Lifts Market Competitive Landscape
Player mix skews toward diversified industrial conglomerates with elevator divisions alongside specialized accessibility equipment manufacturers. The structure exhibits moderate consolidation at the top tier with fragmentation among regional service specialists. Two strategic archetypes dominate: pan-European service network operators bundling maintenance contracts with equipment sales, and compact residential specialists leveraging distribution through mobility dealers. Competitive moves center on geographic expansion through local installer partnerships and portfolio diversification into IoT-enabled predictive maintenance services.
Among diversified industrial conglomerates, KONE and Otis occupy positions as archetypal pan-European service network operators, while Stannah exemplifies the compact residential specialist model. KONE leverages its service infrastructure to sustain recurring maintenance relationships alongside new equipment specifications. Otis controls high-rise commercial specification channels through dual-brand strategies with local installers. Stannah anchors home accessibility retrofits through compact inclined platform lift specialization. These three represent distinct competitive vectors within a market where specification influence increasingly hinges on demonstrated regional technician density rather than equipment-first positioning.
| Leading Market Players |
|---|
| KONE |
| Savaria |
| Stannah |
| Thyssenkrupp |
| Aritco |
| Alimak |
| Schindler |
| Otis |
| Mitsubishi Electric |
| Others |
Value Network & Pricing Analysis
EN 81-41 certification timelines compress supplier qualification windows across Europe while simultaneously enabling price premiums for validated systems, creating a dual-gate mechanism that filters uncertified competitors from public sector procurement pools and stratifies pricing power between compliant and non-compliant manufacturers.
Pricing Analysis
Cost-plus contracts with steel and aluminum indexation dominate municipal procurement in Germany, where federal accessibility mandates drive specification volume. Price differentiation rests on certification grade and after-sales service bundling, with EN 81-41 validated systems commanding premiums over uncertified alternatives. Cost compression in mid-range hydraulic systems intensifies as electric drive alternatives gain residential share. Facility managers exhibit lowest price sensitivity due to lifecycle total cost of ownership calculations, while contractors face acute pressure on fixed-price retrofit bids.
Supply Chain Analysis
Specialized hydraulic component manufacturing concentrates in Germany, Italy, and China, creating sourcing dependencies for heavy-duty platform specifications. Steel fabrication, aluminum extrusion, and precision rail systems anchor raw material inputs. Single-source vulnerability in European hydraulic cylinder supply exposes manufacturers to extended lead times during demand surges. Distribution runs through authorized installer networks rather than direct OEM-to-end-user channels, with regional service technician density determining competitive access.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward facility managers and municipal procurement officers as specification influence consolidates among professional operators with lifecycle cost expertise, fragmenting price-taking behavior among smaller residential buyers.
For Market Incumbents: Secure EN 81-41 certification maintenance through accelerated third-party validation cycles to defend specification access against emerging entrants. Deepen backward integration into hydraulic component manufacturing to buffer margin pressure from steel and aluminum volatility. Channel control through exclusive installer partnerships in Germany and Japan represents the critical defensive lever against service-network competitors. For New Entrants and Emerging Players: Differentiate on IoT-enabled predictive maintenance capabilities to bypass incumbent service density advantages in healthcare and commercial segments. India's BIS IS 14671 adoption creates the most penetrable geography for certified suppliers lacking entrenched European networks. Direct engagement with architects during design-phase specification embedding offers the strongest go-to-market angle against specification-locked rivals. For Investors and Strategic Acquirers: EN 81-41 compliance deadlines reshaping the acquisition landscape toward certified manufacturers with established notified body relationships. Long-term viability centers on service contract recurring revenue rather than equipment sales cyclicality. Acquisition targets should demonstrate regional technician density in Germany or Japan. The signal to watch is municipal procurement contract unbundling trends separating maintenance from capital expenditure.| Strategic Initiative | Industry Significance |
|---|---|
| EN 81-41 Certification Acceleration | Third-party validation investment gates specification access in German municipal procurement pools. |
| IoT Predictive Maintenance Platform | Sensor integration opens recurring revenue streams beyond initial equipment sales to facility managers. |
| Electric Drive Technology Pivot | Energy-efficient motor systems displace hydraulic alternatives in residential German and Japanese specifications. |
| Authorized Installer Network Expansion | Regional technician density controls competitive positioning in lifecycle service bundling markets. |
| India BIS IS 14671 Compliance Pathway | Bureau of Indian Standards certification unlocks commercial construction procurement channels in Maharashtra and Karnataka. |
Research Methodology
Initial hypotheses were tested against primary input from facility managers, municipal procurement officers, elevator maintenance directors, and accessibility consultants and refined through secondary validation against EU Machinery Directive enforcement records, EN 81-41 certification databases, BIS IS 14671 adoption filings, and municipal building renovation budget disclosures. Bottom-up installation data triangulated against top-down construction spending analytics.
Variance decomposition across product type, application, technology, and regional regulatory framework dimensions structured the analytical framework throughout the projection horizon. CAGRs derived from segment-level growth rate reconciliation against macro construction indicators. Industry-specific forecast inputs incorporated healthcare facility capital planning cycles and METI barrier-free mandate implementation timelines.
Material uncertainties — commodity price volatility, certification timeline extensions, and substitution by full passenger elevators — sit outside the modeled envelope. Forecasts reflect assumptions about regulatory enforcement continuity and infrastructure retrofit funding stability. Practitioners should keep alternative scenarios live as EN 81-41 transition deadlines and BIS IS 14671 adoption rates evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Automation Systems
Global Building Information Modeling (BIM) Market
Building Automation Systems
Building Automation System Market
Building Automation Systems
Infrastructure Monitoring Market
Building Automation Systems
Global Enterprise Building Solutions Market
Building Automation Systems
Signage Market
Building Automation Systems
Smart Window Film Market
Building Automation Systems
Building-To-Grid Technology Market
Building Automation Systems
Traction Elevator Market
Building Automation Systems
Energy Efficient Elevators Market
Building Automation Systems
Residential Electric Underfloor Heating Market
Building Automation Systems
Europe Building Automation Systems Market
Building Automation Systems
Global Operating Equipment Room Market
Building Automation Systems
Electrochromic Glass Market
Building Automation Systems
Integrated Building Management Systems Market
Building Automation Systems
Global HVAC Controls Market
Building Automation Systems
Computer-Aided Facility Management (CAFM) Market