
 Germany Prefab Wood Buildings Market | 2026-2036
Germany Prefab Wood Buildings Market Size, Share, and Industry Trends Forecast 2026-2036
Germany Prefab Wood Buildings Market Foresight
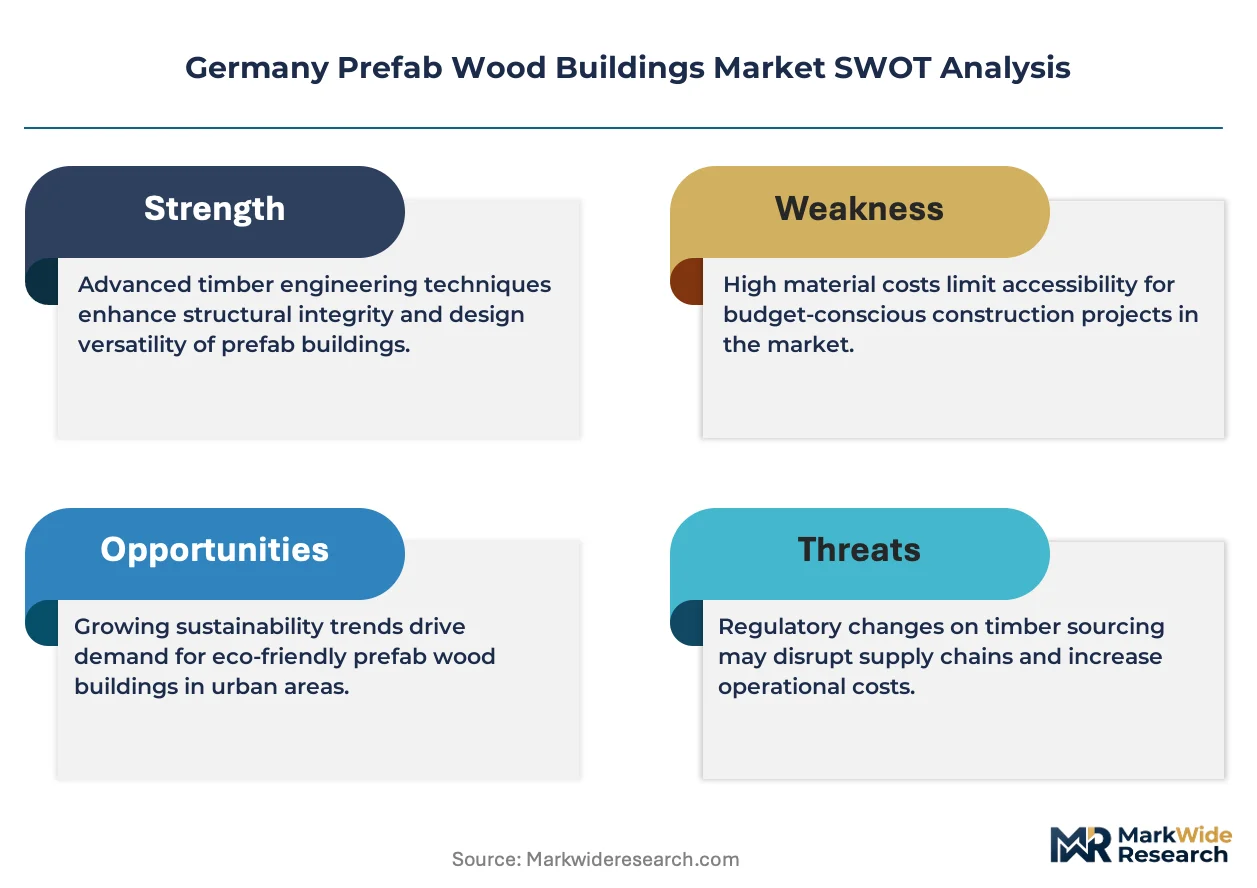
Passive House certification is redrawing competitive boundaries in the Germany prefab wood buildings sector. Baufritz leverages decades of integrated design-build expertise to sustain premium positioning among energy-conscious buyers. SchwörerHaus anchors its market presence through advanced timber engineering capabilities and factory-controlled precision. DFH Haus GmbH competes on modular system flexibility, enabling rapid project adaptation across varied municipal zoning requirements.
Germany prefab wood buildings are structural assemblies manufactured off-site using engineered wood products such as cross-laminated timber and glulam, with thermal performance parameters typically engineered to meet or exceed EnEV and GEG standards before site delivery. Panelized systems dominate current output volumes due to their transport efficiency and compatibility with existing crane logistics across dense German urban sites. Volumetric construction represents the fastest-growing technology segment, as whole-module completion reduces on-site labor hours and accelerates occupancy timelines for residential developers. Timber frame structures retain mature share in rural single-family applications, though margin pools increasingly shift toward hybrid techniques that combine solid wood panels with steel connectors for mid-rise multi-family units.
The German Building Energy Act (GEG) and DIN 68800 wood preservation standards collectively shape product specifications, thermal envelope requirements, and factory certification obligations for manufacturers serving the German market. KBA building code interpretations at the federal state level create additional compliance layers that regionally specialized producers must navigate. Stakeholders should monitor evolving GEG amendment cycles and municipal pre-approval pathways, as these regulatory instruments will determine which factory configurations achieve scalable market access without costly retrofit.
Market Dynamics
The German Building Energy Act (GEG) is compressing design timelines and forcing factory-level thermal envelope precision before modules reach Bavaria or Baden-Württemberg construction sites. This regulatory pressure is redistributing competitive advantage toward manufacturers with integrated design-build certification capabilities.
Growth Catalysts
- GEG thermal thresholds:The German Building Energy Act mandates stricter U-value requirements that factory-controlled timber envelopes satisfy more reliably than site-built alternatives. Residential developers in southern urban corridors face compliance deadlines that favor prefabricated solutions.
- Cross-laminated timber maturation:Engineered wood products now achieve structural spans and fire ratings previously requiring steel or concrete. Multi-family developers in Munich and Stuttgart are specifying CLT-core modules for mid-rise housing.
- Bavaria-Baden-Württemberg housing shortage:Municipal zoning in these states is accelerating approvals for modular residential projects. Factory completion reduces on-site labor hours where skilled construction workers are scarce.
Market Restraints
- Engineered wood input volatility:Spruce and beech lamella supply concentrates in Central European forestry operations. Price fluctuations in raw timber feed directly into panelized system manufacturing costs.
- KBA state-level code fragmentation:Germany's federal building code interpretations vary across Länder, forcing manufacturers to maintain multiple certification pathways. Factory configurations require costly adaptation for scalable market access.
- Concrete-steel substitution persistence:Traditional construction retains specification preference among risk-averse municipal housing associations. Timber's perceived fire and acoustic liabilities slow penetration in public-sector procurement.
Strategic Opportunities
- Volumetric construction in eastern Länder:Saxony and Brandenburg show underpenetrated prefab adoption despite comparable housing pressures. First-mover factory positioning could capture municipal pre-approval pathways before competitors consolidate.
- Hybrid timber-steel systems:Convergence of solid wood panels with steel connectors enables six-to-eight-story residential structures. This technical combination opens mid-rise segments previously inaccessible to pure timber solutions.
- GEG amendment cycles:Upcoming regulatory revisions will likely tighten envelope standards further. Manufacturers with DIN 68800 wood preservation certification and existing GEG compliance infrastructure can convert regulatory tailwind into margin expansion.
Industry Challenges
- Timber engineering talent scarcity:Factory-controlled precision manufacturing requires skilled technicians for CNC cutting and CLT lamination. Vocational pipelines in Baden-Württemberg and Bavaria are not replenishing these specialized roles at replacement rates.
- Passive House certification timelines:Third-party verification of thermal bridge-free design adds months to project schedules. Developers facing occupancy deadlines sometimes bypass premium certification despite market preference for the standard.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany Prefab Wood Buildings Market |
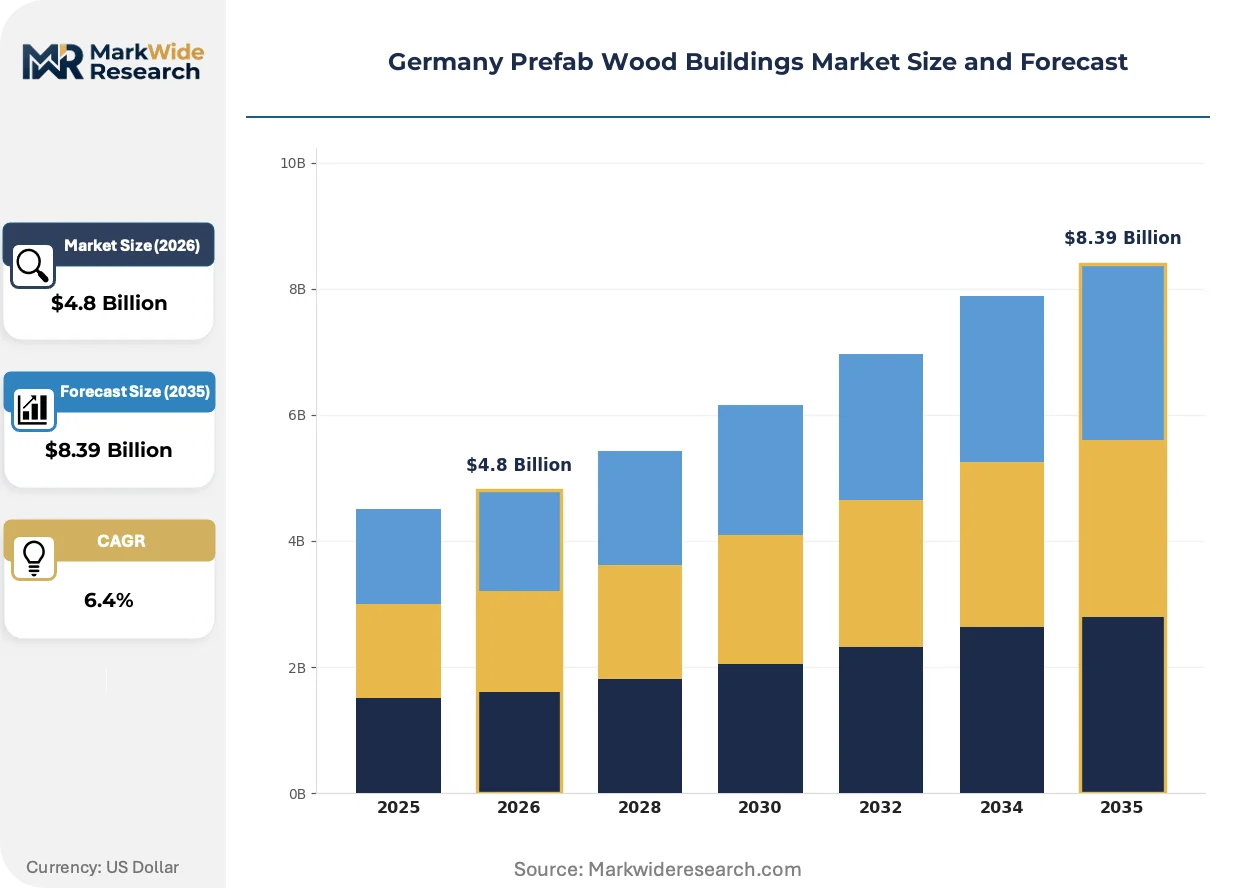
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.39 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Family Homes, Multi-Family Units, Commercial Structures, Modular Offices Construction Technology: Panelized Systems, Volumetric Construction, Hybrid Techniques, Timber Frame Structures Application Sector: Residential Development, Retail Establishments, Educational Facilities, Hospitality Venues End User: Property Developers, Real Estate Investors, Construction Firms, Architecture Studios |
| Companies Covered | W. u. J. Derix GmbH & Co., Kaufmann Bausysteme GmbH, DFH Haus GmbH, Bien-Zenker GmbH, Baufritz, ALHO Systembau, Blumer-Lehmann AG, Fertighaus Weiss GmbH, SchwörerHaus, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany Prefab Wood Buildings Market Shifts & Advancements
Digital fabrication workflows are compressing the gap between architectural design and factory floor execution. Timber modules now ship with embedded sensors and pre-installed MEP routing that site crews simply connect.
Volumetric whole-module completion is supplanting panelized assembly as the dominant delivery format for multi-family residential projects in Munich and Stuttgart. Developers facing compressed construction timelines are specifying factory-finished units with internal fit-out complete. This shift is compressing on-site labor requirements and accelerating occupancy certificates.
KBA interpretations of the German Building Energy Act are tightening thermal bridge assessment protocols for timber structures. Factory manufacturers must now document envelope continuity through infrared imaging before modules depart production facilities. Panelized system suppliers in Bavaria are investing in automated quality control stations to maintain certification velocity.
Direct contracting between housing associations and factory operators is fragmenting traditional general contractor intermediation. Municipal developers in Frankfurt and Hamburg are issuing design-build RFPs that specify performance outcomes rather than material inputs. This procurement evolution concentrates risk with manufacturers capable of warranting energy performance across multi-year horizons.
Germany Prefab Wood Buildings Market Segmentation
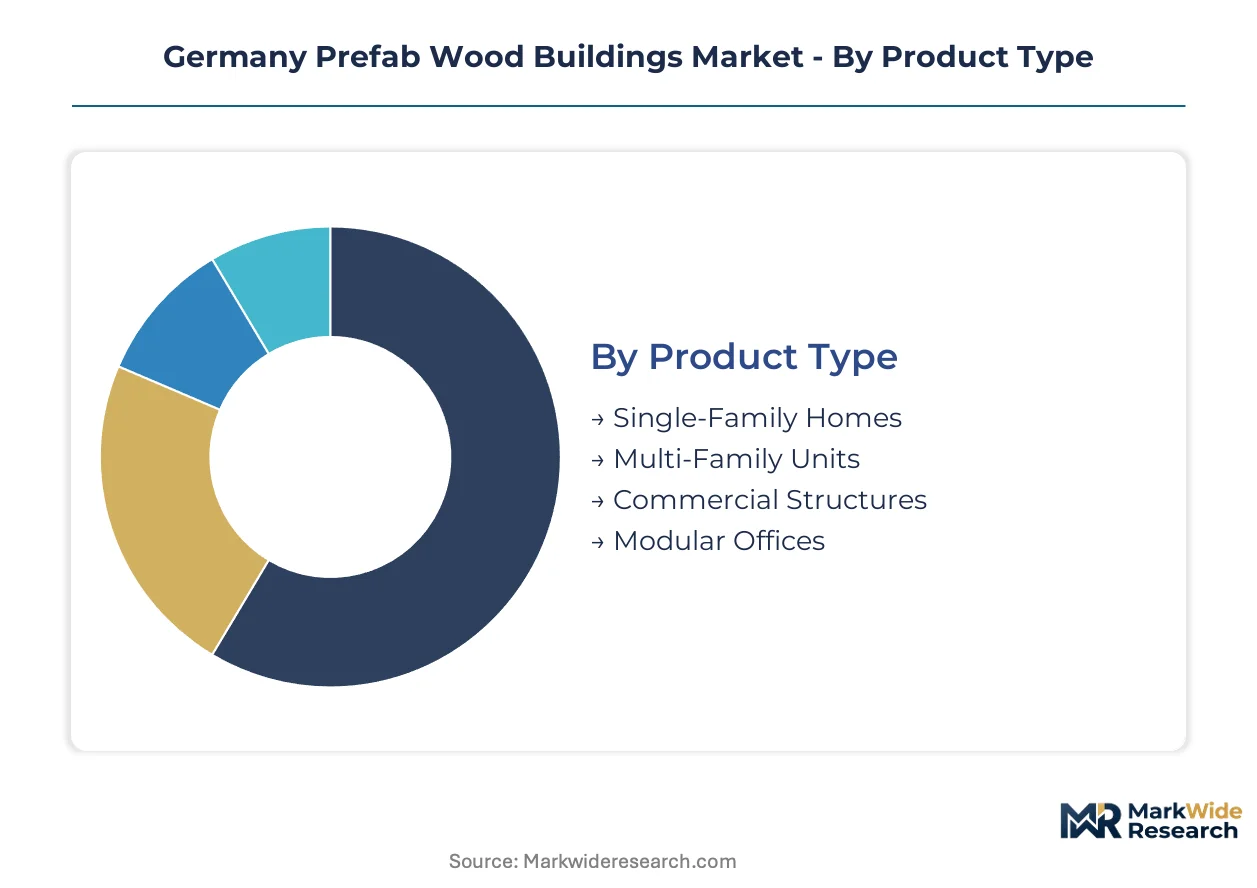
Segmentation reveals how German prefab wood buildings fragment across structural complexity, delivery methods, and buyer sophistication. Each dimension carries distinct margin profiles and regulatory exposure under the German Building Energy Act.
Product Type:
Domestic procurement concentrates in southern states, while export-oriented manufacturers in northern Germany target adjacent European markets with standardized modules.
- Single-Family Homes:Detached dwellings utilizing timber frame or panelized envelopes. Bavarian and Baden-Württemberg municipalities are fast-tracking approvals for these structures where housing shortages intersect with GEG compliance deadlines.
- Multi-Family Units:Mid-rise residential structures employing CLT cores and hybrid timber-steel connectors. Munich and Stuttgart developers specify these for five-to-eight-story projects where factory precision reduces thermal bridging risks.
- Commercial Structures:Retail and office shells manufactured off-site for rapid assembly.
- Modular Offices:Relocatable workspace units with integrated MEP systems.
Single-Family Homes commands the established base. The steepest expansion runs through Multi-Family Units.
Construction Technology:
Cost stratification separates premium volumetric solutions from economy panelized alternatives, with hybrid techniques occupying the mid-tier positioning.
- Panelized Systems:Wall and roof components prefabricated for crane-assisted assembly on-site. These systems dominate current output volumes due to transport efficiency across dense urban sites in Frankfurt and Hamburg.
- Volumetric Construction:Complete three-dimensional modules with internal fit-out finished at factory. Whole-module completion reduces on-site labor hours where skilled construction workers are scarce in Saxony and Brandenburg.
- Hybrid Techniques:Solid wood panels combined with steel connectors for enhanced structural spans.
- Timber Frame Structures:Traditional post-and-beam methods for rural single-family applications.
Panelized Systems commands the established base. The steepest expansion runs through Volumetric Construction.
Application Sector:
Volume concentration tilts toward residential, though non-residential segments offer superior margin pools for certified Passive House manufacturers.
- Residential Development:Housing projects across single and multi-family configurations. Municipal zoning in southern urban corridors accelerates approvals for modular residential projects facing occupancy timeline pressures.
- Retail Establishments:Commercial storefronts and shopping annexes.
- Educational Facilities:School buildings and university extensions.
- Hospitality Venues:Hotels and serviced accommodation modules.
Residential Development commands the established base. The steepest expansion runs through Educational Facilities.
End User:
Customer type determines procurement sophistication, with institutional investors demanding performance warranties that concentrate risk with integrated manufacturers.
- Property Developers:Residential and commercial project sponsors. These buyers in Munich and Stuttgart are issuing design-build RFPs that specify energy performance outcomes rather than material inputs.
- Real Estate Investors:Institutional capital deploying into yield-generating assets. Pension funds and REITs are contracting directly with factory operators to secure multi-year energy performance warranties.
- Construction Firms:General contractors and specialty trades.
- Architecture Studios:Design practices specifying prefabricated systems.
Property Developers commands the established base. The steepest expansion runs through Real Estate Investors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Residential developers and institutional investors concentrate procurement in southern German states where housing shortages intersect with stringent energy compliance deadlines. Municipal zoning accelerations in Bavaria and Baden-Württemberg are reshaping project pipelines toward factory-controlled timber solutions.
Bavaria
Munich's housing shortage drives municipal fast-tracking of volumetric residential projects. The German Building Energy Act mandates thermal envelope precision that factory completion satisfies more reliably than site-built alternatives. Industrial clusters around Augsburg and Nuremberg host panelized system manufacturers expanding capacity to serve southern urban corridors.
Baden-Württemberg
Stuttgart developers specify CLT-core modules for five-to-eight-story multi-family structures where hybrid timber-steel connectors enable mid-rise spans. KBA state-level building code interpretations require additional certification layers for cross-border project execution. Factory operators in the Stuttgart metropolitan area are investing in automated quality control stations to maintain Passive House certification velocity.
North Rhine-Westphalia
Cologne and Düsseldorf housing associations are issuing design-build RFPs specifying energy performance outcomes rather than material inputs. The state's industrial heritage provides skilled technician pipelines for CNC cutting and timber engineering operations. Panelized system suppliers near Dortmund leverage transport connectivity to serve dense Rhine-Ruhr urban sites.
Hesse
Frankfurt's financial sector capital is deploying into yield-generating prefab timber assets through direct factory contracting. Municipal pre-approval pathways for modular projects are consolidating risk with integrated manufacturers capable of warranting multi-year energy performance. Timber frame specialists in the Wiesbaden corridor retain mature share in suburban single-family applications.
Lower Saxony
Hanover and Brunswick municipalities show emerging demand for educational facility modules where rapid occupancy timelines align with factory-controlled delivery. DIN 68800 wood preservation standards shape factory certification obligations for manufacturers serving this northern market. Export-oriented producers near Bremen harbor target adjacent European markets with standardized volumetric units.
Germany Prefab Wood Buildings Market Competitive Landscape
Player mix skews toward integrated design-build specialists with decades of timber engineering heritage. The vendor base concentrates around factory-controlled precision manufacturers and modular system architects serving distinct municipal zoning requirements. Two strategic archetypes dominate: heritage-anchored family enterprises with Passive House certification depth, and engineering-driven fabricators with advanced CLT lamination capabilities. Competitive moves center on capacity expansion in eastern Länder and strategic partnerships with municipal housing associations for multi-year performance warranties.
Among heritage-anchored German fabricators, Baufritz and SchwörerHaus exemplify integrated design-build positioning where decades of timber engineering expertise sustains premium-tier access. DFH Haus GmbH occupies a position within the modular flexibility archetype, enabling rapid project adaptation across varied municipal zoning requirements. These three entities collectively represent the competitive spectrum from precision-manufactured timber envelopes to systematized volumetric completion.
| Leading Market Players |
|---|
| W. u. J. Derix GmbH & Co. |
| Kaufmann Bausysteme GmbH |
| DFH Haus GmbH |
| Bien-Zenker GmbH |
| Baufritz |
| ALHO Systembau |
| Blumer-Lehmann AG |
| Fertighaus Weiss GmbH |
| SchwörerHaus |
| Others |
Supply & Pricing Matrix
GEG thermal compliance certification gates both factory qualification and price stratification across the German prefab wood buildings sector. Manufacturers bearing DIN 68800 and Passive House credentials command premium positioning while uncertified competitors compete on transport-cost arbitrage alone.
Pricing Analysis
Cost-plus contracts with spruce lamella indexation dominate procurement between Bavarian developers and panelized system suppliers. Pricing stratifies across Passive House-certified, EnEV-compliant, and baseline thermal performance tiers, with certification grade and factory proximity to Munich-Stuttgart corridors driving differentiation. Cost compression in standard-tier panelized systems is intensifying because Czech and Polish cross-border suppliers are undercutting domestic transport premiums. Municipal housing associations exhibit highest price sensitivity, while institutional investors prioritize performance warranties over unit economics.
Supply Chain Analysis
Strategic stockpiling of CLT lamella prevails among Baden-Württemberg manufacturers confronting Central European spruce harvest volatility. Supply concentrates in Austrian, Czech, and southern German forestry operations, with engineered wood production drawing from beech and spruce feedstocks. Single-source vulnerability runs through glulam adhesive suppliers concentrated in German chemical clusters. Distribution runs through factory-direct contracting to municipal developers, bypassing traditional general contractor intermediation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Germany prefab wood buildings market constitutes a regulatory-entrenchment moat where GEG compliance infrastructure and KBA state-level certification pathways create switching costs that lock in incumbent positioning.
For Market Incumbents: Shield market share through captive supply of CLT lamella via backward integration into Bavarian forestry operations. Cement factory-level thermal envelope precision as non-replicable capability against emerging Polish and Czech panelized system entrants. Prioritize certification velocity investments to maintain Passive House pre-approval advantages as GEG amendment cycles tighten.
For New Entrants and Emerging Players: Differentiate on volumetric construction specialization targeting Saxony and Brandenburg municipal housing associations. Eastern Länder show underpenetrated prefab adoption despite comparable housing pressures. Pursue design-build RFP positioning that warranties energy performance outcomes rather than competing on material specifications.
For Investors and Strategic Acquirers: Carve-out targets emerge from family-owned timber engineering enterprises lacking succession liquidity in Baden-Württemberg industrial clusters. Long-term viability hinges on regulatory tailwind persistence through GEG enforcement tightening. Monitor KBA interpretation divergence across Länder as inflection indicator for factory configuration scalability.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Forestry | Captive spruce and beech lamella supply secures margin stability against Central European harvest volatility. |
| Passive House Certification Velocity Investment | Automated infrared quality control stations accelerate pre-approval timelines for Munich-Stuttgart developers. |
| Design-Build RFP Positioning | Direct municipal contracting fragments general contractor intermediation and concentrates multi-year warranty risk. |
| Volumetric Capacity Expansion in Eastern Länder | First-mover factory positioning captures Saxony and Brandenburg pre-approval pathways before competitor consolidation. |
| Hybrid Timber-Steel System Development | Steel connector integration opens six-to-eight-story multi-family segments previously inaccessible to pure timber solutions. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with factory operations directors, municipal housing association procurement leads, timber engineering specialists, and KBA building code administrators; and secondary validation through DIN standards documentation, GEG amendment drafts, federal state construction permit databases, and engineered wood product trade flow records. Bottom-up capacity assessments and top-down construction spend allocation were triangulated.
Across the projection horizon, the analytical framework modeled volume and value outputs through segmentation by construction technology, application sector, and end-user sophistication, with additional dimensioning by federal state regulatory cluster. CAGRs were derived from installer capacity buildout trajectories and municipal zoning acceleration timelines, incorporating CLT lamination throughput and crane logistics constraints as industry-specific forecast inputs.
Material uncertainties — GEG amendment stringency, spruce harvest volatility, and KBA interpretation divergence — sit outside the modeled envelope. Forecasts reflect assumptions on regulatory enforcement persistence and skilled technician pipeline replenishment. Revision becomes warranted when cross-border supplier penetration or concrete-steel substitution preference crosses thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Construction
Germany Prefabricated Buildings Market
Building Construction
Swiss Prefabricated Buildings Market
Building Construction
Europe 3D Printing Construction Market
Building Construction
Brazil Construction Market
Building Construction
Europe Prefabricated Buildings Market
Building Construction
Ireland Data Center Construction Market
Building Construction
Europe Prefab Wood Buildings Market
Building Construction
Early Production Facility Market
Building Construction
Japan Prefabricated Buildings Market
Building Construction
Africa Prefabricated Housing Market
Building Construction
Turkey Commercial Construction Market
Building Construction
Germany Commercial Construction Market
Building Construction
Scandinavia Construction Market
Building Construction
Italy Construction Market
Building Construction
Dominican Republic Construction Market
Building Construction
Construction Market