
 Building-To-Grid Technology Market | 2026-2036
Building-To-Grid Technology Market Size, Share, and Industry Trends Forecast 2026-2036
Building-To-Grid Technology Market Outlook
Germany's industrial corridor is reshaping Building-To-Grid Technology supply chains through aggressive factory investments in converter and inverter assembly. Schneider Electric leverages its European manufacturing footprint to dominate hardware integration for commercial deployments. Siemens sustains technology leadership in building management software that synchronizes HVAC loads with grid signals. ABB anchors its position through specialized medium-voltage connection equipment for large-scale industrial facilities.
Building-To-Grid Technology encompasses bidirectional power electronics, communication protocols, and control systems that enable structures to consume, store, and export electricity while responding to real-time grid conditions. These systems typically operate at 480V to 34.5kV interconnection points and rely on IEEE 2030.5 or IEC 61850 communication standards to coordinate with utility operators. Energy Storage Systems command the deepest margin pools as lithium-ion and emerging solid-state battery costs decline. Commercial Buildings represent the fastest-expanding end user category as corporate sustainability commitments harden into operational requirements. IoT Integration underpins nearly all scalable deployments through sensor networks that feed granular load data into cloud-based optimization engines.
The US Federal Energy Regulatory Commission and EPA shape demand through interconnection standards and building emissions benchmarks that effectively mandate grid-responsive capabilities. The EU F-Gas Regulation and EU Green Deal building renovation requirements are compressing deployment timelines across member states by penalizing static, non-interactive building energy profiles. Stakeholders must monitor how evolving cybersecurity mandates from ISO and national regulators alter certification burdens for connected building systems.
Market Dynamics
The US Inflation Reduction Act tax incentives are compressing deployment timelines for grid-interactive efficient buildings, forcing commercial portfolios to accelerate capital allocation toward bidirectional energy systems. This regulatory pull is concentrating vendor competition around hardware-software integration capabilities.
Growth Catalysts
- US IRA Tax Incentives:The Inflation Reduction Act's 48E and 179D provisions reduce payback periods for commercial building retrofits. Facility managers in Class A office towers are prioritizing grid-responsive HVAC and battery installations.
- German Building Codes:The country's Energieeinsparverordnung mandates grid-responsive capabilities in new construction above 500 square meters. District energy networks in the Ruhr industrial corridor require bidirectional interconnection standards.
- Lithium-Ion Cost Curves:Declining battery pack prices are unlocking economic viability for behind-the-meter storage paired with building load management. Industrial facilities with high peak demand charges are the primary adopters.
Market Restraints
- Converter Supply Concentration:Power electronics manufacturing clusters in Taiwan and South Korea create geographic vulnerability for inverter and bidirectional converter procurement. Lead times for medium-voltage equipment extend to 18 months.
- Cybersecurity Certification Burden:ISO/IEC 27001 and emerging NERC CIP requirements for connected building systems add 6-12 months to product launch timelines. Small vendors lack compliance resources.
- Legacy Building Stock:Pre-2000 commercial structures require electrical infrastructure upgrades before bidirectional interconnection. Retrofit costs often exceed 40% of total system investment.
Strategic Opportunities
- India Commercial Real Estate:The country's Smart Cities Mission and Green Building Council certification requirements are creating first-mover advantages for grid-interactive building technology. Mumbai and Bangalore office developments are piloting virtual power plant aggregation.
- AI-Driven Load Optimization:Machine learning algorithms forecasting 15-minute ahead building demand are converging with utility time-of-use signals. This pairing enables automated participation in wholesale electricity markets.
- EU F-Gas Regulation Phase-Down:The refrigerant transition is forcing HVAC replacement cycles that bundle grid-responsive controls. Building owners are capturing incremental value through demand response enrollment.
Industry Challenges
- Interconnection Queue Delays:Utility study timelines for behind-the-meter export capability stretch 12-24 months in congested distribution territories. Project developers face revenue recognition uncertainty.
- Protocol Fragmentation:IEEE 2030.5, IEC 61850, and proprietary utility APIs create integration complexity for multi-site building portfolios. Software vendors must maintain multiple certification tracks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Building-To-Grid Technology Market |
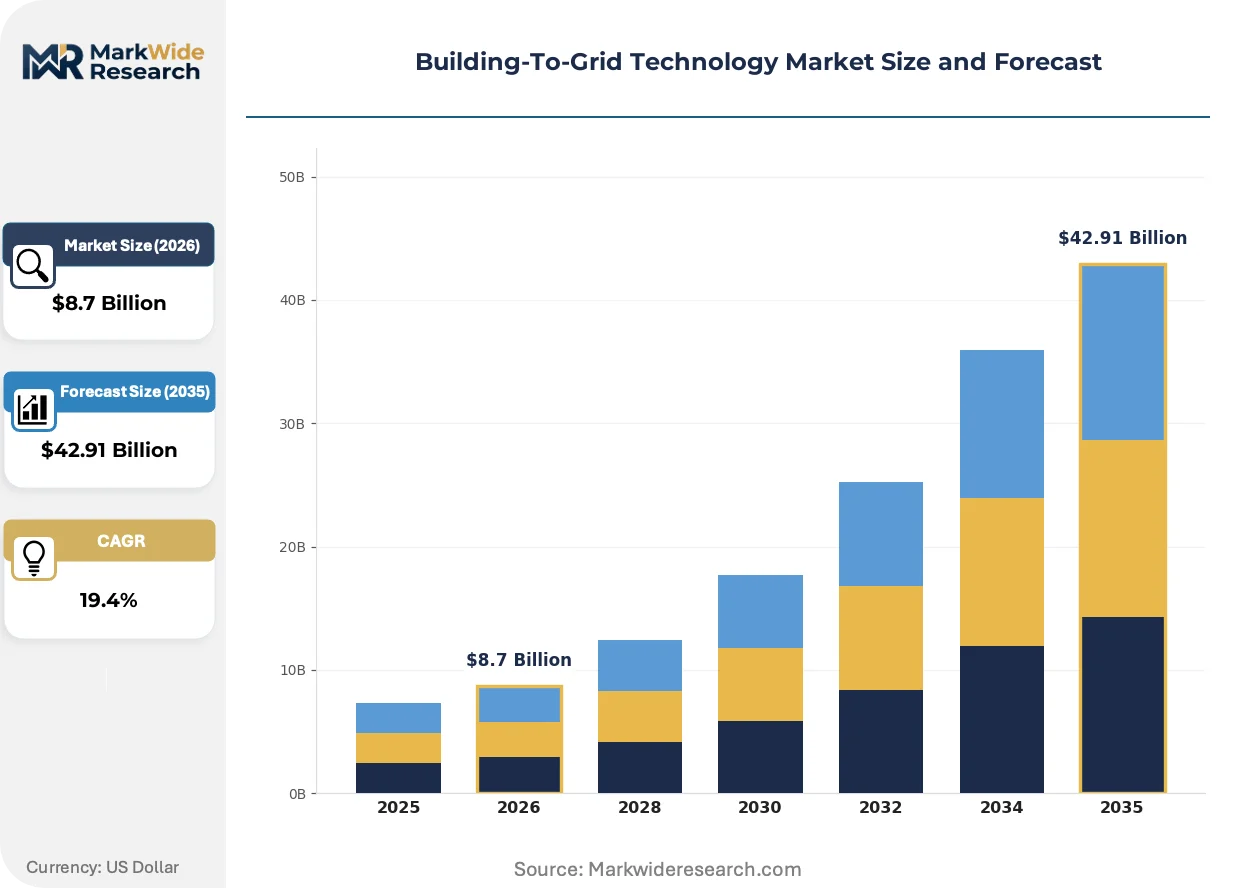
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $42.91 Billion |
| CAGR (2026 – 2036) | 19.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Energy Storage Systems, Smart Meters, Automation Controls, Demand Response Systems End User: Commercial Buildings, Residential Complexes, Industrial Facilities, Educational Institutions Technology: IoT Integration, Cloud Computing, Renewable Integration, Building Management Systems Application: Energy Management, Cost Reduction, Grid Stability, Renewable Energy Optimization |
| Companies Covered | Schneider Electric, General Electric, ABB, Honeywell, Siemens, Eaton, Rockwell Automation, Cisco Systems, Johnson Controls, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Building-To-Grid Technology Market Strategic Shifts
Digital twin architectures and edge computing are collapsing the latency between building sensor networks and grid operator signals. This infrastructure shift is enabling sub-second load modulation that was technically infeasible five years ago.
Silicon carbide power semiconductors are replacing silicon IGBTs in building-to-grid inverters. Data center operators in Northern Virginia and Frankfurt are specifying these units for their higher switching frequencies and reduced thermal losses. The technology is digitizing power conversion efficiency curves that previously required mechanical component substitution.
The EU F-Gas Regulation's refrigerant phase-down timeline is accelerating HVAC replacement cycles across member states. Building owners in Germany, France, and the Netherlands are bundling grid-responsive controls with equipment upgrades to capture demand response revenue streams. Commercial real estate investment trusts are reporting these retrofits as Scope 2 emissions reductions under CSRD disclosure requirements.
Energy-as-a-service contracting is displacing capital purchase models for building-to-grid systems. Third-party ownership structures transfer interconnection risk and performance guarantees to specialized developers. This arrangement dominates in California and Texas where wholesale market volatility creates arbitrage value for optimized battery dispatch.
Building-To-Grid Technology Market Segmentation
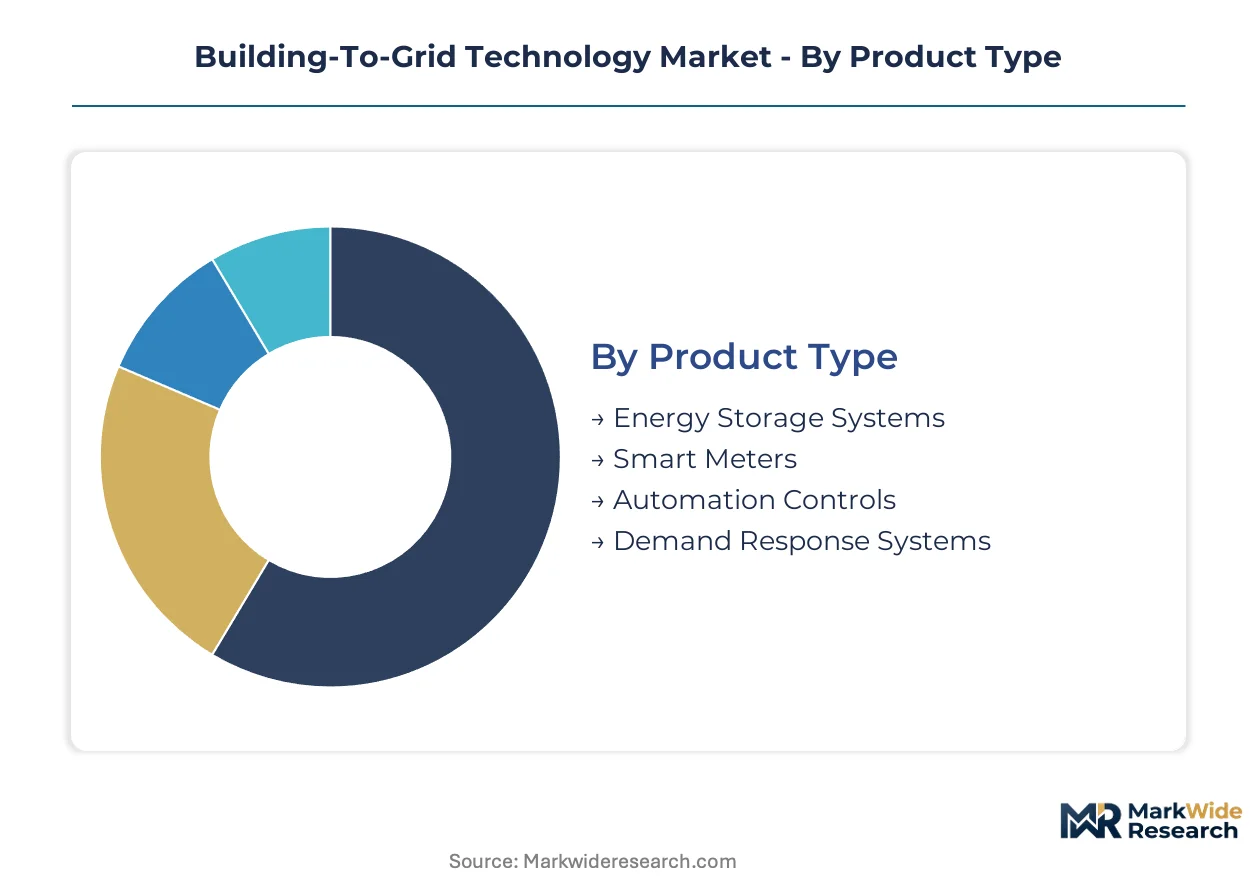
Segmentation in Building-To-Grid Technology reveals how hardware, software, and service layers combine differently across customer types. Each dimension—product, end user, technology, and application—carries distinct margin profiles and deployment complexity that shape vendor strategy.
Product Type:
Cost tier separates hardware-heavy segments from software-enabled systems, with capital intensity driving procurement patterns and ownership models.
- Energy Storage Systems:Lithium-ion battery packs paired with bidirectional inverters form the physical core of grid-interactive buildings. Industrial facilities in Germany's Ruhr corridor deploy these systems to capture peak shaving value and participate in frequency regulation markets.
- Smart Meters:Advanced metering infrastructure provides the data foundation for all downstream optimization. Commercial building portfolios across the US specify these units to satisfy FERC interconnection standards and enable real-time pricing exposure.
- Automation Controls:Programmable logic controllers and edge devices execute load modulation commands within sub-second windows.
- Demand Response Systems:Aggregation software enrolls distributed assets into utility-controlled dispatch programs.
Energy Storage Systems commands the established base. The steepest expansion runs through Demand Response Systems.
End User:
Customer type determines scale economics and regulatory exposure, with commercial portfolios offering the most attractive unit economics for technology deployment.
- Commercial Buildings:Class A office towers and retail portfolios aggregate sufficient load to justify dedicated grid interconnection infrastructure. US IRA tax incentives compress payback periods for these assets, accelerating capital commitment from real estate investment trusts.
- Industrial Facilities:Heavy manufacturing sites with high peak demand charges capture the strongest returns from behind-the-meter storage. German energy-intensive industries face binding grid-responsive mandates under Energieeinsparverordnung requirements.
- Residential Complexes:Multi-family developments pilot virtual power plant aggregation through shared inverter resources.
- Educational Institutions:University campuses leverage municipal bond financing for long-payback building retrofits.
Industrial Facilities anchor current deployment volumes. Commercial Buildings are gaining share fastest as sustainability commitments harden into operational requirements.
Technology:
Application maturity varies sharply, with IoT Integration now table stakes and Renewable Integration still climbing the adoption curve.
- IoT Integration:Sensor networks feeding cloud-based optimization engines underpin nearly all scalable deployments. These systems rely on IEEE 2030.5 or IEC 61850 protocols to coordinate with utility operators across voltage classes from 480V to 34.5kV.
- Building Management Systems:Software platforms synchronize HVAC, lighting, and storage assets against grid signals. Siemens sustains technology leadership in this layer for European commercial deployments.
- Cloud Computing:Centralized data processing enables portfolio-level optimization across geographically distributed assets.
- Renewable Integration:Co-optimization of solar PV, storage, and building loads maximizes self-consumption and export revenue.
IoT Integration commands the established base. Renewable Integration shows the steepest expansion trajectory as distributed generation costs decline.
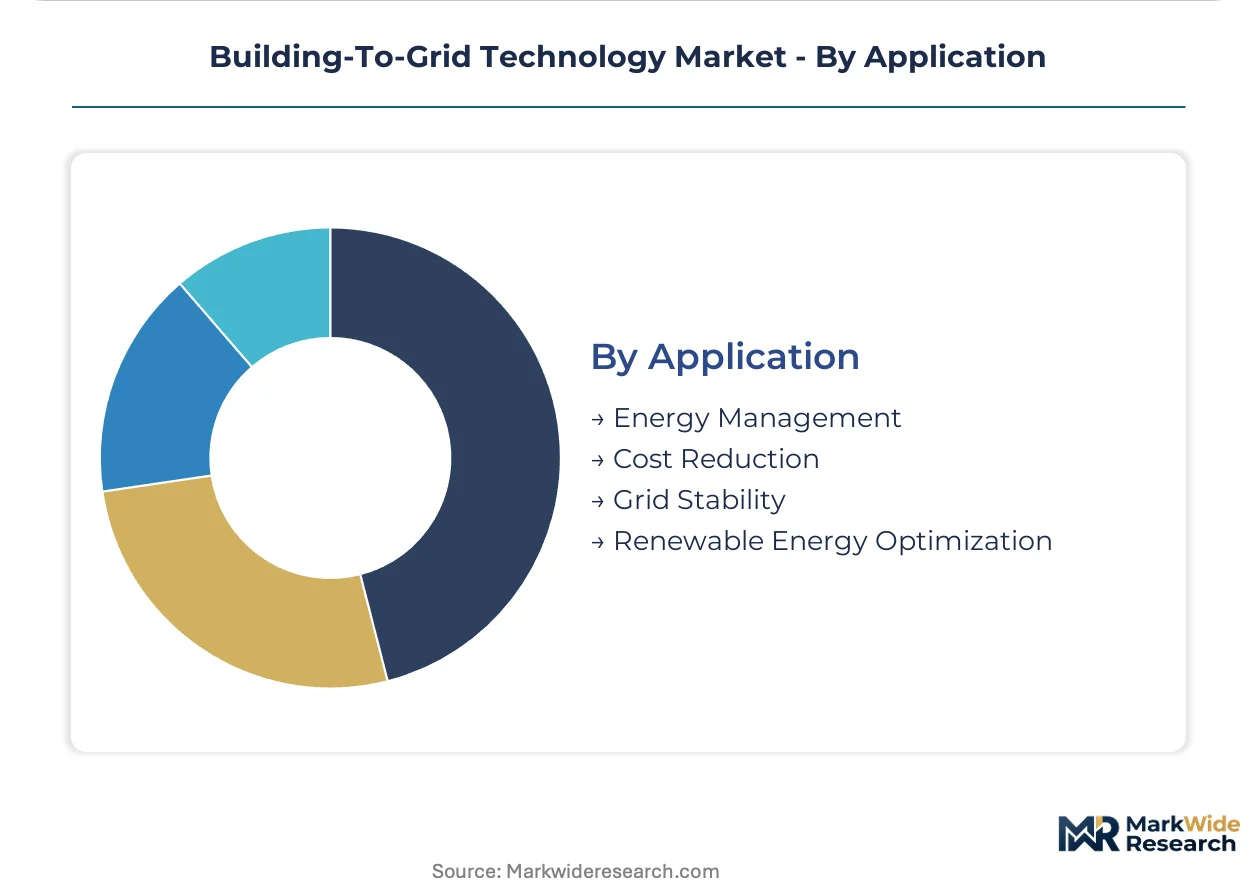
Application:
Volume concentration reflects regulatory pressure and economic returns, with grid services emerging as a revenue layer beyond simple cost reduction.
- Energy Management:Real-time load balancing against time-of-use rates delivers immediate utility bill savings. This application dominates in markets with volatile wholesale electricity pricing such as Texas and California.
- Grid Stability:Frequency regulation and voltage support services monetize building assets as grid infrastructure. German transmission system operators procure these services through standardized tender mechanisms.
- Cost Reduction:Peak demand charge avoidance and energy arbitrage stack multiple revenue streams.
- Renewable Energy Optimization:Self-consumption maximization and export timing improve project returns for on-site generation.
Energy Management commands the established base. Grid Stability exhibits the steepest expansion as ancillary service markets open to distributed resources.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's transmission grid interconnects with eleven neighboring countries, creating the densest cross-border electricity trading infrastructure in Europe and positioning the country as the operational hub for continental building-to-grid deployment.
United States
Class A office towers in Manhattan and Chicago are accelerating retrofits with bidirectional HVAC and battery systems. The Inflation Reduction Act's 48E and 179D provisions compress payback periods below five years for commercial portfolios. Northern Virginia data center clusters are specifying silicon carbide inverters for grid-responsive load management.
Germany
The Ruhr industrial corridor mandates grid-responsive capabilities under Energieeinsparverordnung for new construction above 500 square meters. District energy networks in Dortmund and Essen require standardized bidirectional interconnection protocols. Transmission system operators procure frequency regulation services through automated tender mechanisms that enroll building assets.
China
Dual carbon policy targets are driving grid-interactive requirements into commercial building codes in Shanghai and Shenzhen. The national energy administration mandates demand response enrollment for structures above 20,000 square meters in tier-one cities. Yangtze River Delta manufacturing zones are piloting virtual power plant aggregation for industrial facilities.
India
Mumbai and Bangalore office developments are testing building-to-grid integration under the Smart Cities Mission. The Bureau of Energy Efficiency mandates energy consumption benchmarks for commercial buildings that effectively require automated load response. Gujarat's industrial estates are deploying behind-the-meter storage paired with solar PV for peak shaving.
Japan
Tokyo's commercial districts face capacity constraints that prioritize buildings with verified grid-responsive capabilities in interconnection queues. METI's building energy efficiency standards require automated demand response for structures above 50,000 square meters. Osaka-Kobe industrial clusters are aggregating facility loads into wholesale electricity market participation.
Building-To-Grid Technology Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream in power electronics and connection hardware. The vendor base organizes into three layers: diversified electrical conglomerates with full-stack integration capabilities, automation specialists with building management software dominance, and pure-play hardware manufacturers concentrated in medium-voltage equipment. Competitive dynamics center on hardware-software bundling and energy-as-a-service contracting models that transfer interconnection risk to third-party owners.
Among diversified electrical conglomerates, Schneider Electric and ABB exemplify the integrated platform archetype, combining converter manufacturing with building management software stacks. Siemens occupies a position within the automation tier, anchoring technology leadership in control systems that synchronize HVAC loads with grid operator signals. These three companies represent the dominant competitive anchors across European and North American deployment corridors.
| Leading Market Players |
|---|
| Schneider Electric |
| General Electric |
| ABB |
| Honeywell |
| Siemens |
| Eaton |
| Rockwell Automation |
| Cisco Systems |
| Johnson Controls |
| Others |
Value Chain & Pricing Dynamics
Taiwanese and South Korean power electronics manufacturing clusters anchor converter procurement costs, concentrating margin capture with firms controlling silicon carbide wafer supply and medium-voltage assembly capacity. This upstream geography dictates where pricing power accumulates downstream.
Pricing Analysis
The US Inflation Reduction Act dictates the pricing tier structure across commercial building deployments. Three-tier pricing stratifies across premium silicon carbide inverters, standard silicon IGBT systems, and economy-grade bidirectional converters. Price differentiation centers on IEEE 2030.5 certification tier and after-sales service bundling. Cost compression in economy-grade hardware is intensifying because Chinese manufacturers are expanding 480V inverter capacity. Industrial facilities with high peak demand charges show the least price sensitivity, while small commercial retrofits exhibit the most.
Supply Chain Analysis
Silicon carbide wafers and lithium-ion battery cells feed the upstream feedstock dependencies for grid-interactive building systems. Manufacturing concentrates in China, South Korea, and Japan for battery packs, with Taiwan and Germany for power semiconductor fabrication. Single-source vulnerability runs through Taiwanese 12-inch silicon carbide substrate production. Distribution runs through EPC contractors and specialized energy-as-a-service developers who bundle hardware procurement with interconnection risk transfer.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbent building-to-grid technology vendors face substitution pressure from AI-native load optimization platforms that bypass traditional hardware-software bundles. Defense requires building structural moats before these platforms scale.
For Market Incumbents: Build certification moats around ISO/IEC 27001 and emerging NERC CIP cybersecurity standards to lock out undercapitalized entrants. Deepen backward integration into silicon carbide power module assembly to capture margin migrating from battery cells to inverters. The threat of AI-native virtual power plant operators unbundling hardware value demands preemptive software platform investments.
For New Entrants and Emerging Players: Build out white-space positions in India's Smart Cities Mission corridor, where grid-interactive mandates are new and incumbent relationships remain thin. Target Mumbai and Bangalore commercial developments with hardware-light, software-first virtual power plant aggregation models. A channel partnership with local EPC contractors bypasses direct interconnection queue navigation.
For Investors and Strategic Acquirers: Capital is best deployed toward mid-cap automation specialists with proven IEC 61850 protocol stacks and existing utility certification relationships. Long-term viability hinges on regulatory compliance capabilities rather than hardware cost curves alone. The signal to watch is FERC interconnection standard revisions that could disqualify non-compliant legacy systems.
| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Carbide Supply Agreement | Secures switching frequency advantages for data center operators in Northern Virginia. |
| Cybersecurity Certification Program | Locks out competitors lacking ISO/IEC 27001 resources for NERC CIP compliance. |
| Energy-as-a-Service Platform Launch | Transfers interconnection risk from building owners to specialized developers in Texas. |
| Backward Integration into Power Modules | Captures margin migrating from battery cells to inverter electronics assembly. |
| Utility API Integration Partnership | Resolves IEEE 2030.5 and IEC 61850 protocol fragmentation for multi-site portfolios. |
Study Parameters
A spread of perspectives from utility planning officers, commercial real estate portfolio managers, EPC contractors, and power electronics procurement leads converged on the working assumptions. Primary fieldwork combined with secondary validation from FERC filings, EIA project databases, IEA building energy reports, and EU Green Deal implementation tracking. Bottom-up project pipeline analysis triangulated against top-down regulatory mandate sizing.
Demand-supply balance modeling anchored volume projections across the analysis window. Segmentation dimensions included product type, end user category, technology layer, and application function. CAGRs derived from regulatory mandate acceleration curves and battery cost decline trajectories. Forecast inputs incorporated IRA tax incentive uptake rates and German Energieeinsparverordnung compliance deadlines.
Sensitivities concentrate around interconnection queue timeline revisions and silicon carbide substrate supply disruptions. Cross-checking against FERC Order 2023 implementation progress and transmission operator procurement data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Automation Systems
Smart Building Solutions Market
Building Automation Systems
Commercial Building Automation Systems Market
Building Automation Systems
Europe Building Automation Systems Market
Building Automation Systems
Global Solar Shading Systems Market
Building Automation Systems
Tunnel Automation Market
Building Automation Systems
Infrastructure Monitoring Market
Building Automation Systems
Global Platform Screen Doors for Subway Lines Market
Building Automation Systems
Traction Elevator Market
Building Automation Systems
Global HVAC Controls Market
Building Automation Systems
Smart Passenger Elevators Market
Building Automation Systems
US Commercial Building Automation Market
Building Automation Systems
Europe HVAC Controls Market
Building Automation Systems
Energy Efficient Elevators Market
Building Automation Systems
Zero Energy Buildings Market
Building Automation Systems
Integrated Building Management Systems Market
Building Automation Systems
Automated Infrastructure Management (AIM) Solutions Market