

Residential Electric Underfloor Heating Market Size, Share, and Industry Trends Forecast 2026-2036
Residential Electric Underfloor Heating Market Insights
Specialist heating contractor distribution is narrowing as manufacturers build direct specification relationships with property developers and large renovators. Danfoss leverages its European HVAC channel infrastructure to sustain specification pull across multiple EU member states. nVent Electric anchors North American project access through electrical contractor relationships and code-compliant cable systems. Warmup competes aggressively on digital thermostat integration, differentiating its offer through smart control compatibility rather than hardware alone.
Residential electric underfloor heating deploys resistive heating cables, polymer film elements, or woven mesh mats beneath finished floor surfaces, typically operating at 150-200 W/m² output to deliver radiant warmth at lower ambient air temperatures than conventional convection systems. Its primary purpose centers on energy-efficient zonal comfort, moisture control in wet rooms, and elimination of visible radiators to maximize usable floor area. Mat systems currently dominate new construction specifications for their thin profile and rapid installation, while smart controls represent the fastest-expanding technology segment as homeowners prioritize app-based scheduling and energy monitoring. Cable systems retain margin strength in custom renovation layouts where irregular room geometries demand field-configurable loops.
CE marking under the EU Construction Products Regulation governs mechanical and thermal performance claims for products sold across Europe, while the F-Gas Regulation indirectly channels demand toward electric alternatives by restricting fluorinated greenhouse gases in heat pump and hybrid systems. In the United States, the National Electrical Code (NEC) and UL certification shape product design and installer licensing requirements, filtering market access for non-compliant suppliers. Stakeholders must monitor how building decarbonization mandates in key states reshape the competitive balance between electric resistance and heat pump-based underfloor solutions.
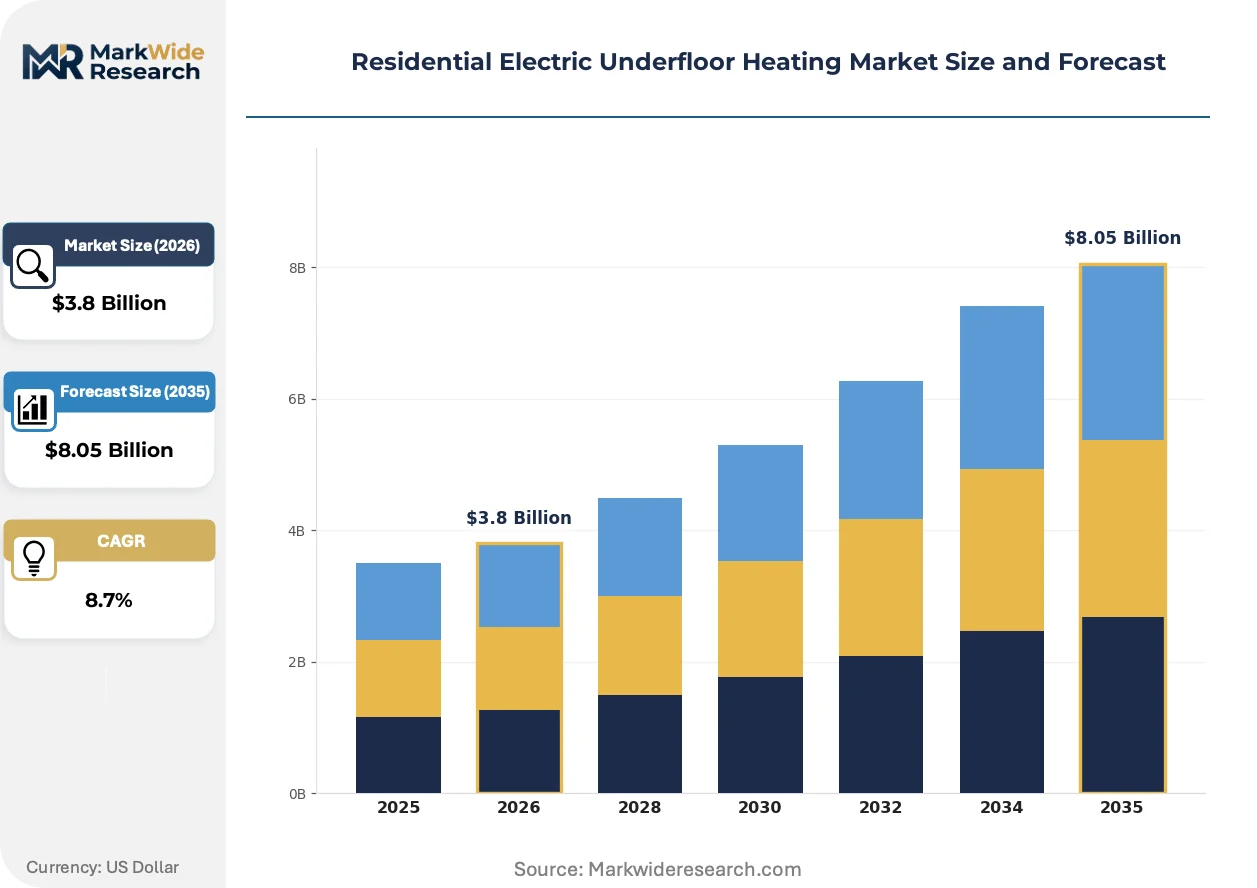
Market Dynamics
The EU F-Gas Regulation is compressing demand for fluorinated refrigerants in hybrid heat pumps, redirecting specification flows toward pure electric resistance systems in residential new-builds across Germany, France, and the Netherlands.
Growth Catalysts
- Building energy codes:Germany's EnEV and subsequent GEG standards mandate measurable thermal efficiency gains that electric underfloor systems deliver through zonal control and lower flow temperatures.
- CE marking harmonization:The EU Construction Products Regulation creates single-market access, reducing certification duplication costs for cable and mat manufacturers serving multiple member states.
- Renovation wave funding:Member state allocation of EU Green Deal subsidies toward residential retrofits accelerates replacement of aging gas boilers with electric alternatives in multi-unit housing.
Market Restraints
- Copper and polymer feedstock volatility:Resistive cable production depends on copper conductor pricing and fluoropolymer insulation materials subject to petrochemical supply swings.
- Contractor channel consolidation:Specialist heating installer networks in Northern Europe have narrowed to regional chains, concentrating specification influence among fewer intermediaries.
- Heat pump substitution:Air-source and ground-source heat pumps with integrated underfloor distribution threaten pure electric resistance systems in larger single-family applications.
Strategic Opportunities
- Smart thermostat convergence:Integration with home energy management systems and utility demand-response programs creates new recurring revenue streams beyond hardware sales.
- Wet room specification:Bathroom and kitchen renovations in aging European housing stock represent high-margin, low-competition entry points for mat-based systems.
- Electrical contractor bypass:Direct-to-developer specification relationships reduce margin erosion from traditional HVAC distribution layers in volume residential projects.
Industry Challenges
- Installer certification bottlenecks:NEC and local electrical code compliance in the United States requires licensed electrician involvement, constraining deployment velocity in renovation markets.
- Legacy control integration:Retrofit installations must interface with existing central heating infrastructure, complicating zone valve and pump coordination in mixed-system households.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Residential Electric Underfloor Heating Market Trends and Innovations
Digital control architectures are displacing electromechanical thermostats as the primary differentiation vector, with app-based scheduling and energy monitoring becoming baseline expectations rather than premium add-ons.
Self-regulating polymer composite heating elements are virtualizing the traditional fixed-output cable paradigm. These materials modulate heat output based on local temperature, reducing energy consumption in variable-load conditions. High-end residential developers in Scandinavia specify these systems for their adaptive response and reduced commissioning complexity. This technology is virtualizing the role of external sensors and complex control algorithms, compressing hardware requirements while improving thermal comfort consistency.
The EU F-Gas Regulation continues tightening permissible refrigerant volumes in heat pump systems, indirectly strengthening the competitive position of electric resistance alternatives. Equipment manufacturers face redesign costs to maintain heat pump efficiency under lower charge limits. The German and Dutch markets show the strongest pivot toward all-electric heating specifications as a compliance hedge against further refrigerant restrictions.
Homebuyers increasingly expect heating infrastructure to integrate with broader smart home ecosystems rather than operate as isolated subsystems. Property developers in urban UK and German markets now specify underfloor systems with open API architectures as standard, displacing proprietary control platforms. This pattern concentrates most visibly in new-build apartments where building management systems coordinate multiple residential units.
Residential Electric Underfloor Heating Market Segmentation
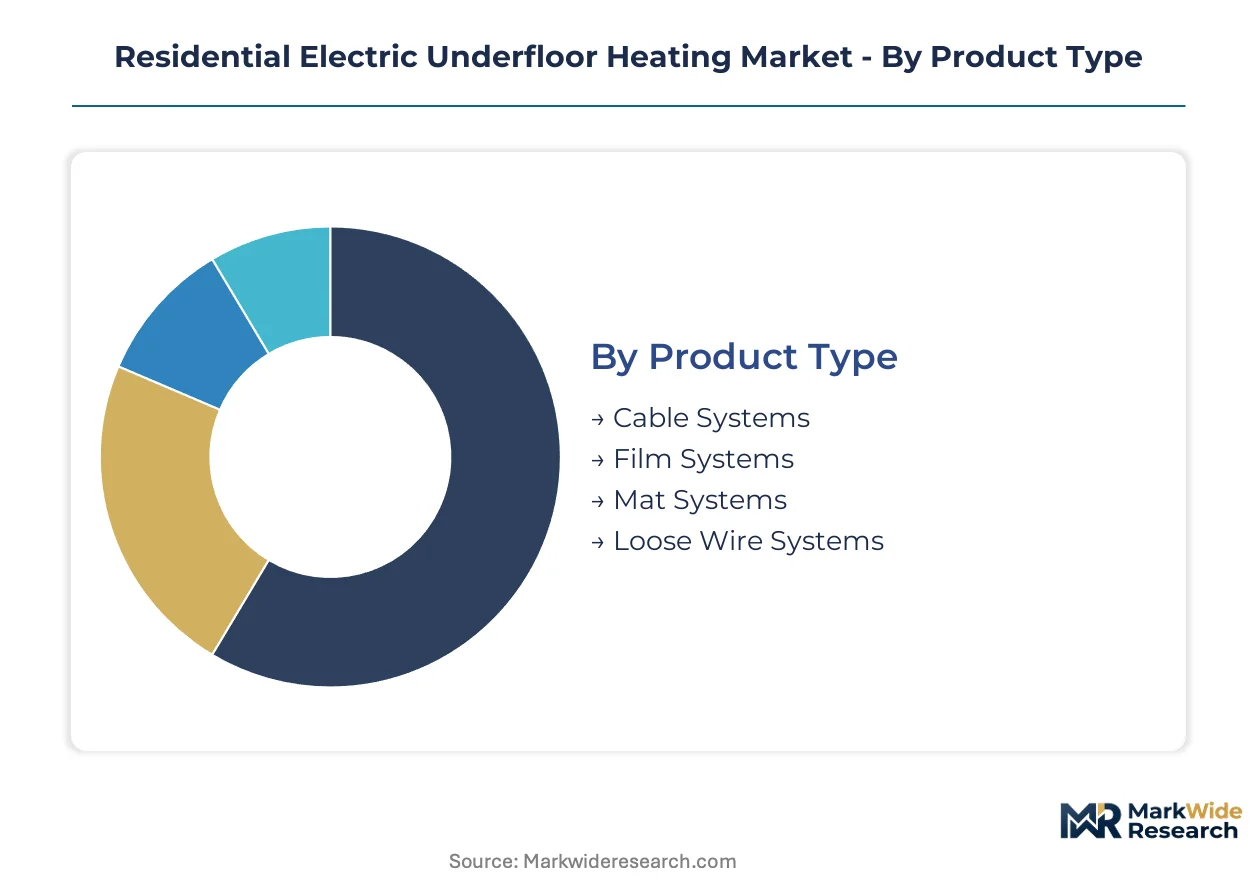
Product architecture, control sophistication, and specification channel each create distinct margin profiles and installation economics across the residential electric underfloor heating landscape. Understanding where volume concentrates versus where value accumulates shapes portfolio prioritization for manufacturers and distributors.
Product Type:
Maturity splits sharply between established cable formats and newer mat-based alternatives that have captured specification preference in volume construction.
- Cable Systems:Resistive heating cables with copper conductors and fluoropolymer insulation enable custom loop configurations for irregular room geometries. Demand concentrates in German and UK renovation markets where field flexibility outweighs installation speed. CE marking harmonization under the EU Construction Products Regulation has compressed certification costs for cable manufacturers serving multiple member states.
- Mat Systems:Pre-spaced cable arrays bonded to adhesive mesh backing deliver sub-4mm installed profiles ideal for new-build specifications. Property developers in the Netherlands and France specify these systems for rapid installation and reduced commissioning complexity in multi-unit residential projects.
- Film Systems:Polymer-based conductive films distribute heat across larger surface areas with minimal thermal mass. Scandinavian high-end residential developers specify these for adaptive response in variable-load conditions.
- Loose Wire Systems:Field-laid cable without mesh backing enables maximum layout flexibility for complex floor plans. Heating contractors in custom renovation markets prefer this format for its adaptability to existing subfloor conditions.
Mat systems handle the majority of throughput in new construction specifications; film systems are expanding most quickly in premium residential segments.
Technology:
Cost tier stratification runs from basic electromechanical controls through connected platforms that generate recurring service revenue.
- Smart Controls:WiFi-enabled thermostats with open API architectures integrate with home energy management systems and utility demand-response programs. German and UK property developers now specify these as standard in new-build apartments where building management systems coordinate multiple units.
- Wireless Thermostats:Battery-powered temperature sensors eliminate hardwired control infrastructure, reducing retrofit installation costs. Demand concentrates in French and Belgian renovation markets where minimizing wall disruption drives specification preference.
- Programmable Controllers:Time-based scheduling devices with 7-day programming capability deliver baseline zonal control without connectivity premiums. Budget-conscious homeowners in Poland and Czech Republic favor this tier for predictable operating costs.
- Wired Thermostats:Hardwired electromechanical or basic digital controls persist in utility-funded retrofit programs where minimizing upfront hardware cost outweighs functionality. Social housing providers in Germany deploy these in volume renovation contracts.
Smart controls command the highest margin tier; wireless thermostats are gaining share fastest in renovation applications.
Application:
Geography within residential units determines thermal load profiles, moisture exposure, and specification decision-makers.
- Bathroom:Wet-room installations demand IP-rated cable or mat systems with integrated moisture sensors and rapid thermal response for comfort and condensation control. German building energy codes mandate measurable efficiency gains that zonal bathroom heating delivers through lower flow temperatures.
- Kitchen:Cabinet-integrated heating beneath tiled or stone flooring eliminates cold spots without sacrificing wall space for radiators. UK renovation contractors specify mat systems here for thin profiles that preserve floor height transitions.
- Living Room:Large open-plan areas require higher wattage density and multi-zone control to address varying occupancy patterns. Dutch new-build specifications increasingly favor smart-controlled systems in these spaces.
- Basement:Below-grade installations prioritize moisture barrier integration and elevated thermal output to counter ground-coupled heat loss. Belgian and Luxembourg markets show concentrated demand for specialized basement-rated systems.
- Conservatory:High heat-loss envelopes with large glazing areas demand maximum output density and rapid response to solar gain variability. UK homeowners retrofit these spaces most frequently, driving replacement demand.
Bathroom applications generate the highest margin per square meter; living room specifications are climbing the fastest as open-plan design dominates new residential architecture.
End User:
Customer type determines procurement channel, price sensitivity, and technical support requirements.
- Property Developers:Volume residential constructors specify systems through direct manufacturer relationships, bypassing traditional HVAC distribution. German and French developers prioritize CE-marked mat systems with standardized control packages for multi-unit efficiency.
- Heating Contractors:Specialist installers retain influence in renovation markets where custom layouts and legacy system integration create specification complexity. Regional contractor chains in Northern Europe concentrate purchasing power.
- Renovators:Owner-managed residential retrofits prioritize rapid installation and smart control compatibility. UK and Netherlands markets show strongest direct-to-consumer purchasing through electrical retail channels.
- Homeowners:End consumers in new-build purchases typically accept developer-specified systems with limited customization. Post-occupancy upgrades concentrate on thermostat replacements rather than heating element modifications.
Property developers drive the majority of volume procurement; renovators are expanding fastest as EU Green Deal subsidies accelerate residential retrofit activity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EU F-Gas Regulation anchors European demand trajectories, redirecting specification flows toward electric resistance systems as member states tighten refrigerant restrictions in hybrid heat pumps. National building codes and renovation subsidy programs now determine installation velocity across key markets.
Germany
GEG standards mandate measurable thermal efficiency gains that zonal electric underfloor systems deliver through lower flow temperatures and precise room-by-room control. The Federal Office for Economic Affairs and Export Control channels BAFA subsidies toward residential retrofits, accelerating boiler-to-electric conversions in multi-unit housing. Berlin-Brandenburg and North Rhine-Westphalia concentrate specification activity where regional developer chains standardize mat-based systems in volume new-builds.
United Kingdom
Part L building regulations and Future Homes Standard timelines pressure developers toward all-electric heating in new residential construction ahead of gas grid phase-out dates. Ofgem-administered ECO4 retrofit funding supports electric heating upgrades in social housing stock. London and Southeast England drive premium specification rates where open-plan apartment designs prioritize invisible heating infrastructure.
France
RE2020 environmental regulations tighten carbon budgets for new residential construction, favoring electric distribution systems over fossil-fuel alternatives in building energy modeling. ANAH renovation grants accelerate electric heating adoption in aging urban housing stock. The Île-de-France region concentrates demand where Parisian developer specifications prioritize thin-profile mat systems for floor height constraints.
Netherlands
Natural gas extraction reductions in Groningen fields and national grid phase-out commitments accelerate all-electric heating transitions in both new and existing housing. Stimulation Scheme for Sustainable Energy Production and Climate Transition (SDE++) subsidies offset upfront installation costs for homeowners. Randstad urban corridors show fastest uptake where municipal building codes preempt national standards.
United States
State-level decarbonization mandates in California, New York, and Massachusetts reshape competitive balance between electric resistance and heat pump-based underfloor solutions. NEC Article 424 governing fixed electric space heating shapes product design and licensed electrician requirements, filtering market access. Pacific Northwest and Northeast Corridor markets lead specification rates where utility demand-response programs incentivize smart-controlled systems.
Residential Electric Underfloor Heating Market Competitive Landscape
Pan-European HVAC conglomerates and specialized heating technology firms split the market across distinct capability vectors. Consolidation pressure concentrates specification influence among manufacturers with direct developer relationships, compressing margins for distributor-dependent competitors. Three archetypes dominate: full-system integrators with control-to-cable portfolios, component specialists focused on heating elements alone, and building materials conglomerates leveraging construction channel access. Geographic expansion and smart control platform development represent the dominant competitive moves as hardware commoditization accelerates.
Within the full-system integrator tier, Danfoss and nVent Electric occupy positions anchored by continental infrastructure scale. Danfoss leverages its European HVAC channel presence across multiple EU member states, while nVent Electric anchors North American project access through electrical contractor relationships. Warmup exemplifies the control-differentiation archetype, competing through digital thermostat integration and smart home ecosystem compatibility rather than heating hardware alone.
| Leading Market Players |
|---|
| Danfoss |
| nVent Electric |
| Warmup |
| Schluter-Systems |
| Uponor |
| REHAU |
| Resideo Technologies |
| Robert Bosch |
| Honeywell International |
| Others |
Pricing and Supply Chain Analysis
Copper conductor volatility and fluoropolymer insulation cost swings determine both tiered pricing spreads and supply chain configuration across cable and mat production. These petrochemical-linked input risks compress margins for non-integrated manufacturers while rewarding those with captive compound supply or long-term polymer offtake agreements.
Pricing Analysis
Configured-to-order cable systems command substantial premiums over standard mat formats due to field-flexibility engineering and custom loop design labor. Pricing stratifies across premium, standard, and economy tiers driven by CE certification grade and smart control integration depth. Cost compression in economy-tier wired thermostats is intensifying because social housing procurement favors minimal hardware specifications. Property developers exhibit lowest price sensitivity given volume standardization, while direct-to-consumer renovators negotiate aggressively on installation bundles.
Supply Chain Analysis
Contract manufacturing for polymer film elements concentrates among specialized extrusion houses in Germany, Italy, and China with dedicated fluoropolymer compounding lines. Resistive cable production draws from copper smelters in Poland and Belgium plus fluoropolymer resin suppliers anchored in German chemical corridors. Single-source vulnerability around high-temperature insulation compounds creates exposure to REACH regulatory revisions on perfluorinated substances. Distribution runs through electrical wholesale networks in Northern Europe and direct specification channels with volume developers in the Netherlands and France.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scarcity of certified smart control firmware engineers constrains how quickly manufacturers can field app-integrated systems that meet utility demand-response protocols. This talent gap separates incumbents with captive development teams from component assemblers dependent on licensed platforms.
For Market Incumbents: Build switching-cost moats through embedded smart home API integrations that lock developers into recurring firmware update contracts. Deepen backward integration into polymer film extrusion to offset fluoropolymer price volatility and secure CE marking traceability. Prioritize direct specification relationships with Randstad and Berlin-Brandenburg developer chains before regional contractor consolidation accelerates.
For New Entrants and Emerging Players: Establish a beachhead in Belgian and Luxembourg basement-rated system segments where specialized moisture-barrier integration creates defensible expertise gaps. Target French ANAH-funded renovation workflows where wireless thermostat retrofit demand outpaces incumbent response capacity. Lead with electrical contractor certification support programs that accelerate NEC compliance velocity in Pacific Northwest markets.
For Investors and Strategic Acquirers: The market sits at a standardization phase that favors full-system integrators with control-to-cable portfolios over pure heating element manufacturers. Long-term viability hinges on recurring revenue from energy management software subscriptions rather than transactional hardware margins. Watch for German GEG amendment proposals as the signal indicating acceleration or deceleration of boiler-to-electric conversion subsidies.
| Strategic Initiative | Industry Significance |
|---|---|
| Smart Control Platform Development | Utility demand-response integration with Eversource and PG&E programs creates recurring revenue streams beyond hardware sales. |
| Polymer Film Extrusion Integration | In-house fluoropolymer compounding secures CE marking traceability and buffers against REACH regulatory revisions. |
| Direct Developer Specification Channel | Bypassing electrical wholesale layers captures margin in volume new-build contracts across German and Dutch markets. |
| Wet Room System Specialization | Bathroom and kitchen renovation concentration in UK and French urban housing stock delivers premium pricing with limited competition. |
| Installer Certification Program Expansion | NEC Article 424 compliance training accelerates deployment velocity in California and Massachusetts renovation markets. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with heating contractor network managers, property development procurement leads, electrical wholesale category buyers, and smart thermostat firmware engineers; plus secondary validation against EU Construction Products Regulation certification databases, BAFA subsidy disbursement records, NEC code revision dockets, and customs trade data for copper conductor and fluoropolymer imports. Bottom-up installation volume estimates triangulated against top-down building permit and renovation subsidy allocations across member states.
Forecast inputs incorporated product type segmentation by cable, mat, film, and loose wire formats; technology tiering across smart, wireless, programmable, and wired control architectures; application segmentation by bathroom, kitchen, living room, basement, and conservatory; and end-user channel splits between property developers, heating contractors, renovators, and homeowners. CAGRs were derived from regression analysis of historical installation rates against regulatory mandate timelines and subsidy program budgets. Industry-specific inputs included GEG standard compliance deadlines and F-Gas Regulation phase-down curves.
Sensitivities concentrate around copper price volatility, REACH amendments on fluorinated compounds, and German federal coalition shifts affecting BAFA funding continuity. Forecasts reflect documented assumptions on renovation subsidy persistence and building code enforcement intensity. Quarterly review of Groningen field extraction rates, copper LME forward curves, and utility demand-response program enrollment is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.