
 Electric Hoist Market | 2026-2036
Electric Hoist Market Size, Share, and Industry Trends Forecast 2026-2036
Electric Hoist Market Intelligence
The EU Green Deal is shifting procurement criteria for material handling equipment across European manufacturing and logistics sectors, favoring energy-efficient AC motor configurations and regenerative braking systems. Konecranes leverages its vertical integration into crane component manufacturing to control cost structures and delivery timelines. Columbus McKinnon anchors its competitive position through specialized alloy chain production and aftermarket service networks. KITO Corporation dominates compact electric chain hoist segments for Japanese automotive assembly applications.
An electric hoist is a motorized lifting device comprising a drum or lift-wheel, reduction gearbox, motor assembly, and brake system, designed to raise, lower, and suspend loads through wire rope or load chain engagement with rated capacities from fractional tons to several hundred tons. Wire rope hoists sustain the largest installed base in heavy manufacturing and shipyard applications due to superior lifting heights and durability under continuous duty cycles. Chain hoists compete aggressively in warehousing operations and equipment renting firms where portability, lower capital outlay, and reduced maintenance intervals offset capacity limitations. AC motor technology leads unit shipments across all application categories, though DC motor variants retain niche positions in explosive atmosphere environments and battery-powered mobile installations.
OSHA regulations govern workplace lifting equipment inspection intervals and operator certification requirements in the United States, while the EU Machinery Directive and CE marking framework mandate conformity assessment for hoist systems sold across member states. China's GB standards and SAMR enforcement protocols establish domestic safety factors and testing protocols that influence export-oriented manufacturer design decisions. Stakeholders must monitor evolving carbon border adjustment mechanisms and regional content requirements that threaten to fragment supplier qualification criteria across major demand centers.
Market Dynamics
Warehousing automation and e-commerce fulfillment center expansion are compressing replacement cycles for overhead material handling equipment, while OSHA duty-cycle tightening and EU carbon border mechanisms are reshaping supplier qualification criteria across procurement offices.
Growth Catalysts
- E-commerce Fulfillment Center Expansion:Third-party logistics operators in the United States are installing high-speed chain hoist systems to accelerate order picking throughput and vertical storage utilization.
- EU Green Deal Procurement Mandates:European manufacturing buyers now require regenerative braking and energy-efficient AC motor configurations in tender specifications for new crane installations.
- Port Modernization in China:Coastal industrial clusters are sustaining heavy procurement of wire rope hoist systems for container handling and shipyard maintenance operations.
Market Restraints
- Copper and Steel Input Volatility:Motor winding materials and alloy chain feedstock price swings compress margin stability for hoist manufacturers serving price-sensitive rental equipment markets.
- Supply Concentration in East Asian Component Manufacturing:Dependence on concentrated gearbox and brake assembly suppliers creates vulnerability to logistics disruption and extended lead times.
- Technical Limitation in Explosive Atmosphere Certification:DC motor variants required for hazardous zone installations carry higher capital costs and maintenance complexity than standard AC configurations.
Strategic Opportunities
- Underpenetrated Southeast Asian Manufacturing:Vietnam and Indonesia automotive assembly plants represent greenfield installation demand for compact electric chain hoist systems.
- Battery-Powered Mobile Installations:DC motor technology convergence with lithium-ion traction systems is enabling cordless overhead lifting in construction and maintenance applications.
- Aftermarket Service Network Expansion:Predictive maintenance contracts and remote monitoring subscriptions offer recurring revenue streams beyond initial equipment sales.
Industry Challenges
- Certified Technician Shortage:OSHA operator certification requirements and specialized brake system repair skills constrain service response capacity in North American markets.
- Legacy Crane Integration Complexity:Retrofitting modern variable-frequency drive controls onto existing runway systems demands custom engineering and extended commissioning timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electric Hoist Market |
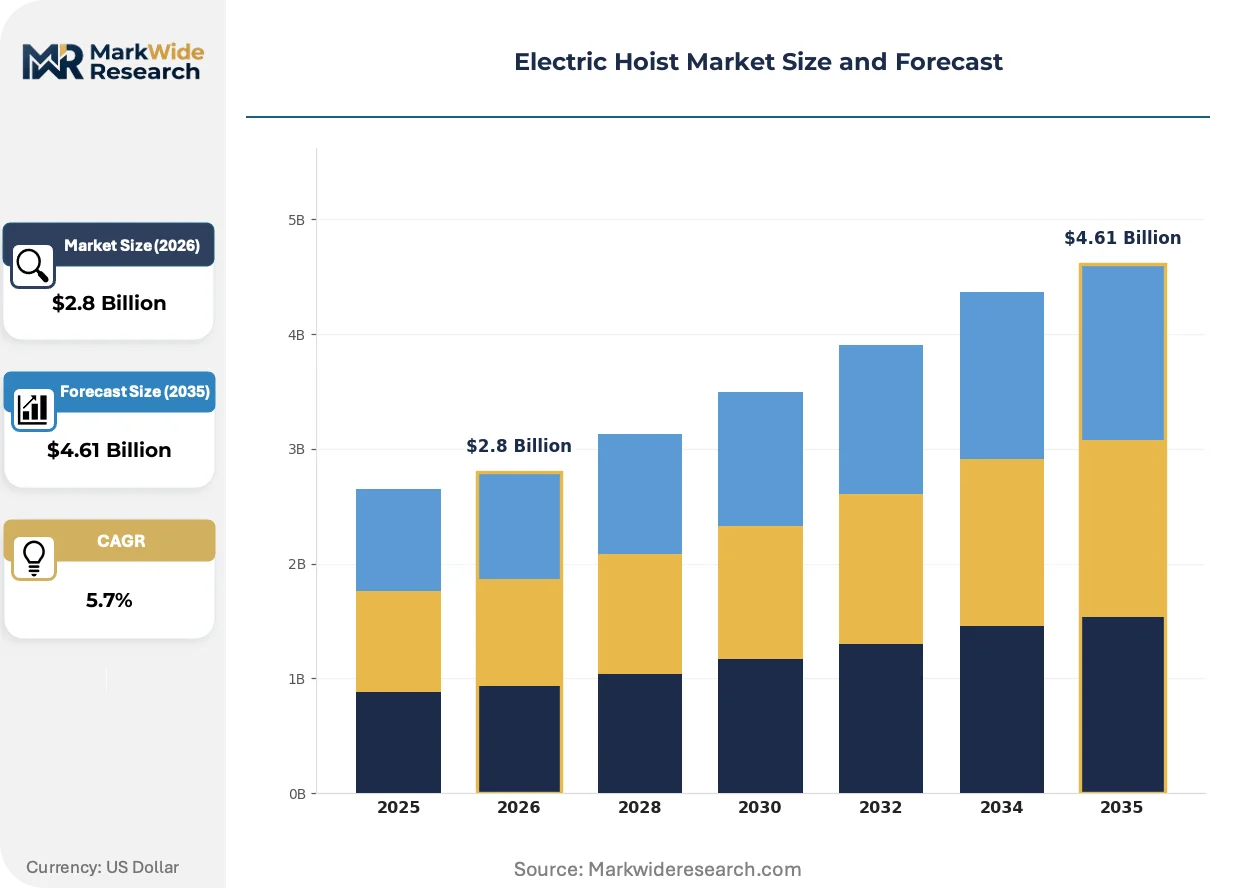
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.61 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wire Rope Hoist, Chain Hoist, Lever Hoist, Pneumatic Hoist, Hydraulic Hoist Technology: AC Motor, DC Motor, Pneumatic Drive, Hydraulic Drive, Magnetic Drive Application: Construction Sites, Warehousing Operations, Shipyards, Manufacturing Plants, Mining Facilities End User: Fabrication Shops, Logistics Providers, Assembly Lines, Equipment Renting Firms, Infrastructure Projects |
| Companies Covered | Konecranes, Street Crane Company, Columbus McKinnon, Hitachi, ABUS Crane Systems, KITO Corporation, Harrington Hoists, SWF Krantechnik, Demag Cranes and Components, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electric Hoist Market Strategic Shifts & Innovations
Variable-frequency drive technology and IoT-enabled condition monitoring are automating hoist operation and maintenance workflows, while regulatory carbon accounting and procurement centralization are rewriting vendor selection criteria.
Variable-frequency drive systems with regenerative braking are automating load positioning precision and energy recovery in high-duty-cycle manufacturing environments. Automotive assembly plants in Germany and Japan are adopting these configurations to meet EU Green Deal energy efficiency benchmarks and reduce per-unit power consumption. The technology is automating the displacement of traditional contactor-controlled motor starters in facilities seeking ISO 50001 energy management certification.
The EU Machinery Directive's 2023 update to conformity assessment protocols for safety-related control systems is extending third-party audit timelines for hoist manufacturers seeking CE marking. Industrial buyers in France and Italy are now requiring documented compliance with EN ISO 13849-1 safety integrity levels in purchase specifications. Wire rope hoist suppliers serving heavy manufacturing segments are responding by redesigning brake monitoring circuits and dual-channel encoder feedback architectures.
Centralized procurement through integrated facility management providers is consolidating supplier relationships and compressing vendor panels in multi-site logistics operations. Amazon and DHL fulfillment networks are unbundling equipment specification from installation service contracts, forcing hoist manufacturers to compete on component pricing while third-party integrators capture system integration margin. This pattern is most visible in the United States and Germany, where property management outsourcing has penetrated deepest among e-commerce infrastructure operators.
Electric Hoist Market Segmentation
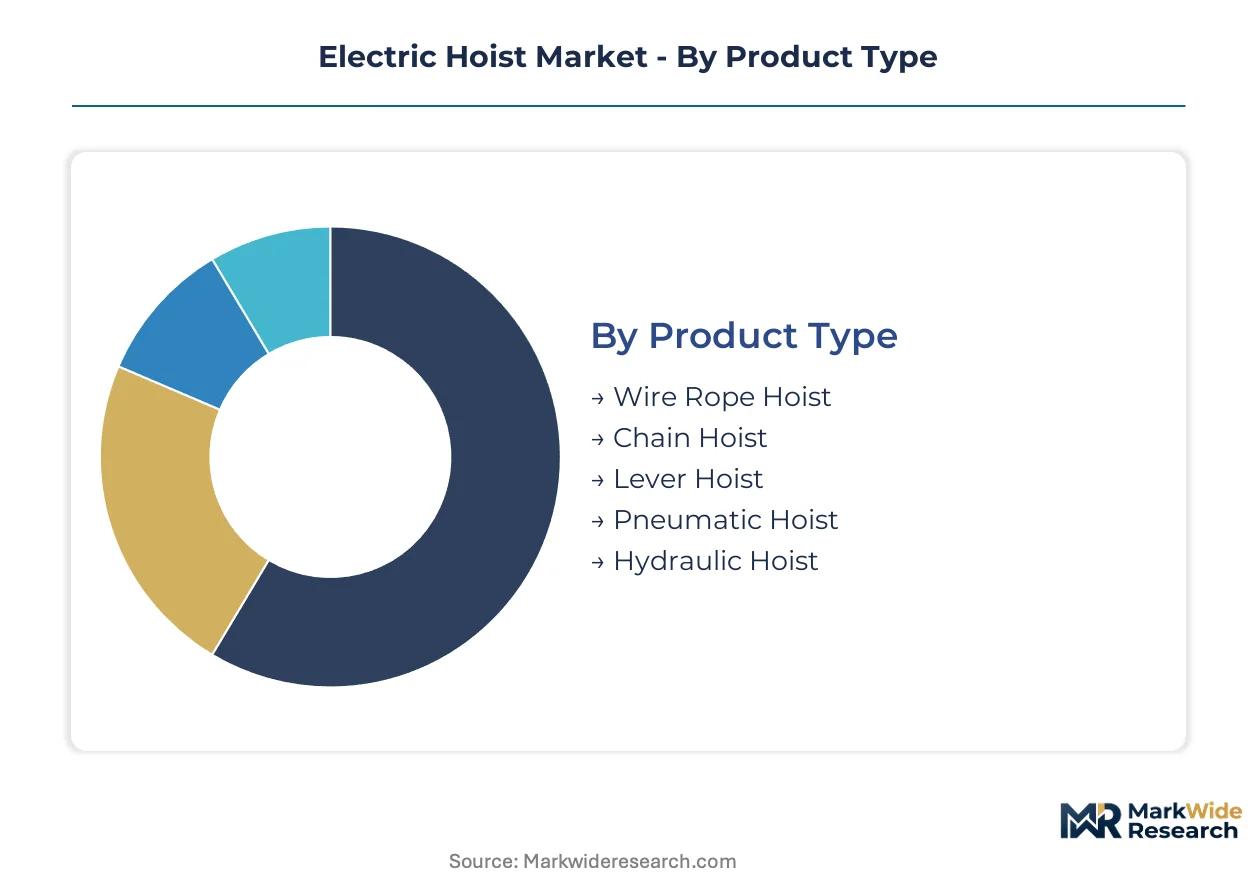
Electric hoist procurement patterns diverge sharply across technical specifications and duty-cycle requirements. Certification burdens vary by segment, with explosive atmosphere installations demanding DC motor variants and specialized third-party audits while standard AC configurations face lighter conformity obligations.
Product Type:
Wire rope hoists carry CE marking under the EU Machinery Directive's safety-related control system protocols, while chain hoists face streamlined conformity assessment in lower-capacity tiers. OSHA duty-cycle tightening affects wire rope systems most severely in continuous-use manufacturing environments.
- Wire Rope Hoist:These systems employ multi-strand steel cable wound around a motorized drum, achieving superior lifting heights and durability under continuous duty cycles. Shipyards in Germany and heavy manufacturing clusters in China sustain procurement for container handling and maintenance operations where height specifications exceed thirty meters.
- Chain Hoist:Compact units utilize hardened alloy load chains engaging with sprocket drives, offering portability and reduced capital outlay for intermittent lifting tasks. Third-party logistics operators across the United States install high-speed variants in e-commerce fulfillment centers to accelerate vertical storage utilization and order picking throughput.
- Lever Hoist:Manual-mechanical devices with ratchet and pawl mechanisms serve maintenance crews in remote construction sites lacking electrical infrastructure.
- Pneumatic Hoist:Compressed-air drive systems operate in explosive atmosphere environments where electrical spark risks are prohibitive.
- Hydraulic Hoist:Fluid-power configurations deliver extreme lifting capacities for mining facility maintenance and heavy infrastructure projects.
Wire rope hoists sit at the top of the volume ranking, with chain hoists climbing the fastest.
Technology:
Cost tiering separates premium regenerative braking AC systems from basic contactor-controlled configurations, with DC motor variants occupying a narrow premium niche for hazardous zone certifications.
- AC Motor:Three-phase induction motors with variable-frequency drive integration dominate unit shipments across standard industrial applications. Automotive assembly plants in Japan adopt regenerative braking configurations to meet ISO 50001 energy management certification and reduce per-unit power consumption.
- DC Motor:Brushed or brushless direct-current systems enable precise speed control and battery-powered mobility for construction site applications. These configurations carry higher capital costs and maintenance complexity due to explosive atmosphere certification requirements under ATEX directives.
- Pneumatic Drive:Compressed-air motor systems eliminate electrical ignition risks in chemical processing facilities and oil refining operations.
- Hydraulic Drive:Fluid-power motors deliver torque multiplication for extreme load conditions in mining and heavy infrastructure sectors.
- Magnetic Drive:Contactless torque transmission through magnetic coupling serves specialized cleanroom and corrosive environment applications.
AC motor configurations command the largest installed base, with DC motor technology expanding most quickly in cordless mobile installations.
Application:
Customer type clustering shows warehousing operators prioritizing speed and vertical density while shipyards demand corrosion resistance and extended lifting ranges.
- Construction Sites:Mobile and temporary lifting operations require portable chain hoists and battery-powered DC systems for steel erection and material positioning. Infrastructure stimulus programs in Vietnam and Indonesia drive greenfield procurement for high-rise commercial development.
- Warehousing Operations:High-throughput distribution centers specify rapid-cycle chain hoists with regenerative braking to maximize vertical storage cube utilization. Amazon and DHL fulfillment networks unbundle equipment specification from installation contracts, forcing manufacturers to compete on component pricing.
- Shipyards:Corrosive marine environments demand wire rope systems with galvanized or stainless steel configurations and sealed brake assemblies.
- Manufacturing Plants:Continuous-duty production lines specify heavy-capacity wire rope hoists with predictive maintenance integration.
- Mining Facilities:Explosive atmosphere certifications and extreme load ratings dominate procurement criteria for underground and surface extraction operations.
Warehousing applications lead current volume, with construction sites gaining share fastest on infrastructure investment cycles.
End User:
Margin structures vary by procurement sophistication, with integrated facility management providers extracting system integration value while equipment renting firms prioritize acquisition cost minimization.
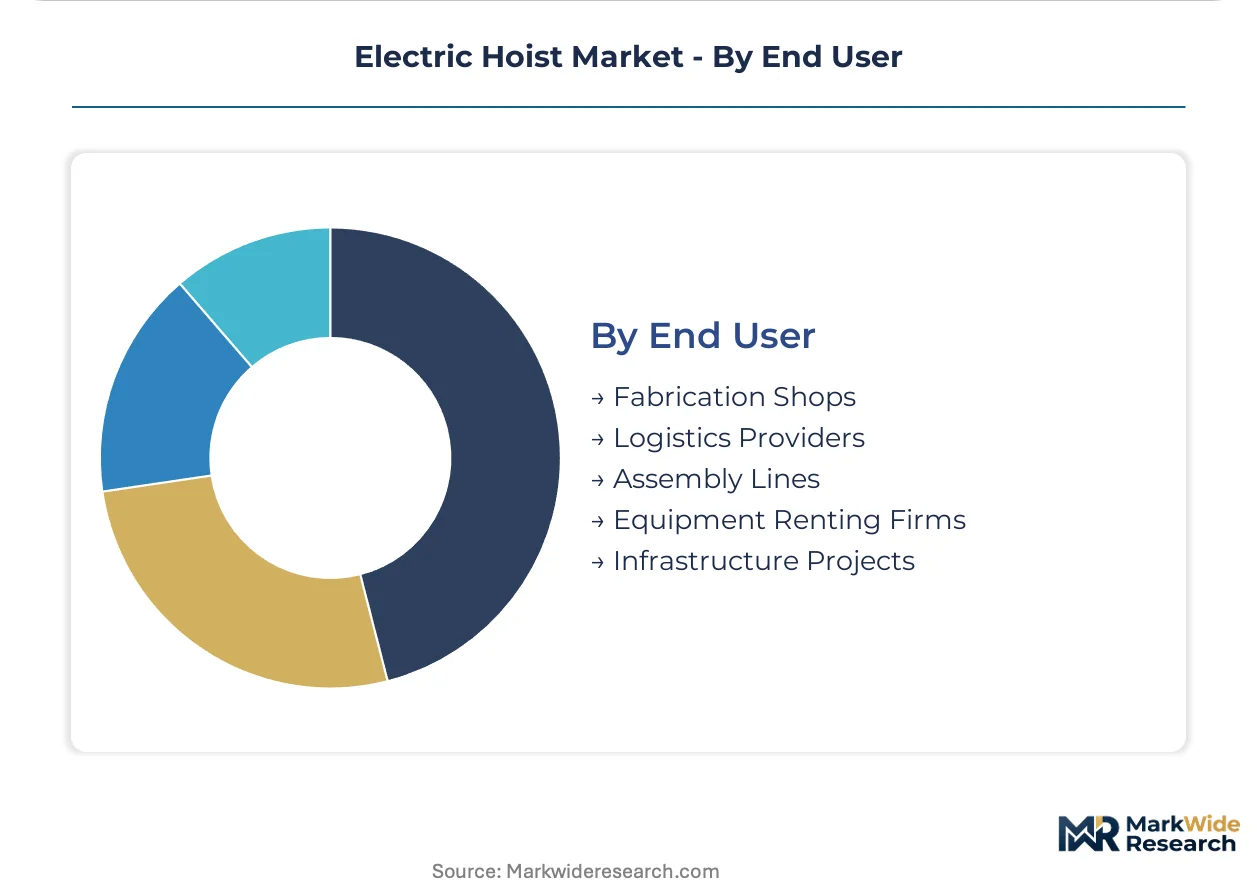
- Fabrication Shops:Small and mid-sized metalworking operations specify medium-capacity chain hoists for material handling and machine loading tasks.
- Logistics Providers:Third-party operators managing multi-site fulfillment networks centralize procurement through integrated facility management relationships.
- Assembly Lines:Automotive and electronics manufacturers specify precision-positioning hoists with variable-frequency drive control for component installation sequences.
- Equipment Renting Firms:Short-term rental markets prioritize low capital outlay and rapid deployment portability over extended duty-cycle specifications.
- Infrastructure Projects:Public works contractors deploy heavy-capacity wire rope and hydraulic systems for bridge construction and utility installation.
Logistics providers represent the largest addressable base, with equipment renting firms showing the steepest expansion trajectory on construction cycle volatility.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Electric hoist manufacturing originated in German engineering workshops and Japanese heavy industry complexes during the early twentieth century. These origins established technical standards that persist in current product architectures. Demand geography now follows industrial automation intensity and port modernization cycles across four major national markets.
United States
Third-party logistics operators are installing high-speed chain hoist systems to accelerate order picking throughput in e-commerce fulfillment centers. OSHA duty-cycle tightening for overhead material handling equipment is reshaping procurement specifications in manufacturing and warehousing sectors. Chicago and Detroit industrial corridors sustain heavy replacement demand for wire rope systems in automotive assembly applications.
Germany
Automotive assembly plants specify precision-positioning hoists with variable-frequency drive control for component installation sequences. The EU Machinery Directive's updated conformity assessment protocols extend third-party audit timelines for CE marking of safety-related control systems. Stuttgart and Munich manufacturing clusters are adopting regenerative braking configurations to meet EU Green Deal energy efficiency benchmarks.
China
Coastal industrial clusters are sustaining heavy procurement of wire rope hoist systems for container handling and shipyard maintenance operations. GB standards and SAMR enforcement protocols establish domestic safety factors that influence export-oriented manufacturer design decisions. Shanghai and Ningbo port modernization programs are driving continuous-duty specifications for heavy-capacity installations.
Japan
Automotive assembly applications dominate compact electric chain hoist procurement for precise component positioning workflows. METI industrial efficiency guidelines favor ISO 50001 energy management certification for manufacturing facilities. Toyota City and Nagoya industrial zones anchor demand for regenerative braking AC motor configurations in continuous production environments.
Electric Hoist Market Key Industry Players
Capital-heavy producers compete with asset-light designers across the electric hoist supply base, creating a tiered structure where integrated manufacturers control component costs while specialized assemblers compete on customization velocity. The vendor landscape concentrates around three strategic archetypes: vertically integrated crane system builders, alloy chain specialists with captive metallurgy capabilities, and compact hoist designers serving automotive precision applications. Dominant competitive moves include backward integration into motor and gearbox manufacturing and geographic expansion through aftermarket service network density.
Among European integrated system builders, Konecranes and ABUS Crane Systems occupy positions emphasizing upstream control over critical components. Columbus McKinnon anchors the alloy chain specialist tier with in-house production capabilities. KITO Corporation exemplifies the compact precision archetype for Japanese automotive assembly applications.
| Leading Market Players |
|---|
| Konecranes |
| Street Crane Company |
| Columbus McKinnon |
| Hitachi |
| ABUS Crane Systems |
| KITO Corporation |
| Harrington Hoists |
| SWF Krantechnik |
| Demag Cranes and Components |
| Others |
Cost & Logistics Intelligence
Backward integration into motor and gearbox manufacturing anchors pricing power for crane system builders while compressing margins for component-dependent assemblers. Konecranes and ABUS Crane Systems leverage captive production of critical drive assemblies to buffer against copper and steel volatility, whereas specialized hoist designers absorb alloy chain feedstock swings through premium positioning.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates regenerative braking AC systems from contactor-controlled configurations and DC motor variants. Certification grade under EU Machinery Directive safety integrity levels and ISO 50001 energy management status drive price differentiation. Cost compression in economy-tier chain hoists intensifies because equipment renting firms prioritize acquisition cost minimization over duty-cycle specifications. Third-party logistics operators demonstrate lowest price sensitivity due to centralized procurement through integrated facility management relationships.
Supply Chain Analysis
Skilled technician availability constraints in German engineering workshops and Japanese heavy industry complexes limit expansion velocity for precision assembly operations. Manufacturing concentrates in China, Germany, and Japan, with gearbox and brake assembly production drawing from concentrated East Asian supplier bases. Raw material dependencies center on copper motor windings, alloy steel chain feedstock, and rare-earth magnetic components. Single-source vulnerability in specialized encoder feedback architectures threatens lead time stability. Distribution runs through OEM direct sales for large crane installations and industrial distributors for replacement chain hoist units.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electric hoist procurement has shifted toward premium regenerative braking configurations as EU Green Deal mandates harden energy efficiency requirements, elevating late-cycle quality over volume capture.
For Market Incumbents: Acquire aftermarket service network density in North American logistics corridors to offset margin compression from centralized procurement unbundling. Defensive consolidation should prioritize certified technician training capacity, addressing OSHA operator certification bottlenecks that constrain service response. Threat substitution from battery-powered mobile DC systems demands R&D investment in lithium-ion traction integration. For New Entrants and Emerging Players: EU Machinery Directive updates to EN ISO 13849-1 safety integrity protocols open a window for specialized control system designers to capture retrofit demand from legacy crane operators. White-space targets include explosive atmosphere DC motor variants for chemical processing facilities and predictive maintenance subscription models for continuous-duty manufacturing. Vietnam and Indonesia automotive assembly plants represent the most penetrable geography for compact chain hoist greenfield installation. For Investors and Strategic Acquirers: Roll-up economics work for regional aftermarket service specialists because fragmented maintenance provider networks lack scale to meet predictive monitoring contract demands. Long-term viability favors platform consolidation around remote diagnostics capabilities and brake system repair certification. Watch for inflection in carbon border adjustment mechanism implementation timelines, which would accelerate procurement centralization and vendor panel compression.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Motor Manufacturing | Konecranes controls cost structures through captive gearbox production for crane system builds. |
| Regenerative Braking Configuration Rollout | Stuttgart automotive plants meet EU Green Deal benchmarks through ISO 50001-certified AC motor installations. |
| Predictive Maintenance Network Expansion | Aftermarket service contracts generate recurring revenue beyond initial equipment sales to logistics providers. |
| Explosive Atmosphere Certification Investment | DC motor variants capture chemical processing demand under ATEX directive compliance requirements. |
| Southeast Asian Distribution Partnership | Local assembly capability addresses Vietnam infrastructure stimulus program procurement timelines. |
Research Approach
Coverage spans United States, Germany, China, and Japan, with primary inputs from each manufacturing cluster. The research combines structured interviews with maintenance directors, plant engineers, OEM procurement teams, and aftermarket service heads with secondary validation through SEC filings, customs and trade data, OSHA enforcement records, and EU Machinery Directive conformity assessment databases. Bottom-up shipment analysis triangulates against top-down industrial automation expenditure tracking.
Rate-of-change decomposition separates volume drivers from value mix shifts across the projection horizon. The analytical framework models product type, motor technology, application environment, and end-user procurement sophistication dimensions. CAGRs derive from regression against industrial production indices, port throughput volumes, and e-commerce fulfillment center buildout rates. Industry-specific forecast inputs include OSHA duty-cycle compliance timelines and EU carbon border adjustment mechanism implementation signals.
Forecast precision tightens around the base case; tail outcomes carry wider variance under commodity price volatility and logistics disruption scenarios. Material deviation in copper and steel input trajectories, or acceleration in battery-powered mobile installation adoption, warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
Die Casting Market
Material Handling Equipment
Circular Stacker and Reclaimer Market
Material Handling Equipment
Crane Mats Market
Material Handling Equipment
Can Racks Market
Material Handling Equipment
Motorized Decoiler Machine Market
Material Handling Equipment
East Africa Elevator and Escalator Market
Material Handling Equipment
Automated Material Handling (AMH) Market
Material Handling Equipment
Loader Bucket Attachments Market
Material Handling Equipment
Clinching Machines Market
Material Handling Equipment
Electric Stacker Market
Material Handling Equipment
High-Pressure Die Casting Market
Material Handling Equipment
Global Large Conveyor Chain Market
Material Handling Equipment
India Automated Material Handling (AMH) Market
Material Handling Equipment
Selective Pallet Racking System Market
Material Handling Equipment
Pneumatic Equipment Market
Material Handling Equipment
Tube Rotator Market