
 Collapsible Gates Market | 2026-2036
Collapsible Gates Market Size, Share, and Industry Trends Forecast 2026-2036
Collapsible Gates Market Outlook
Chinese steel fabricators are pivoting toward automated welding lines for collapsible gate frames, tightening cost structures for export markets. Hörmann Group leverages its German engineering heritage to dominate premium automatic gate segments across European commercial installations. DormaKaba sustains channel control through integrated access-system bundling that pairs collapsible barriers with electronic entry platforms. Jiangsu Lida Group anchors volume production of manual folding gates for Asian residential contractors seeking standardized, quick-install solutions.
Collapsible gates are retractable barrier systems constructed from interlocking slats or mesh panels, typically spanning 2.5 to 6 meters in width, designed to secure openings while enabling compact storage when retracted. Steel and aluminum grades dominate material selection, with powder-coated finishes providing weather resistance for exterior commercial and industrial deployments. Automatic gates lead value generation due to motorization complexity and integration with building management systems, while manual gates occupy the highest unit volume through cost-sensitive residential channels. Folding gates represent the fastest-growing product configuration as architects specify space-efficient alternatives to swing or slide mechanisms in constrained urban footprints.
OSHA guidelines in the United States mandate load-rated barriers for industrial mezzanine and warehouse edge protection, directly specifying collapsible gate performance standards for fall-prevention compliance. The EU Construction Products Regulation requires CE marking on permanently installed security barriers, including fire-resistance testing for commercial building integration. India's BIS certification for steel fabricated products adds compliance layers for imported gate assemblies entering infrastructure projects. Stakeholders must monitor evolving smart building codes that increasingly mandate IoT connectivity for automated access points.
Market Dynamics
Commercial property managers are consolidating vendor relationships around integrated access-system providers, compressing the addressable market for standalone collapsible gate manufacturers and favoring bundling strategies that pair physical barriers with electronic entry management.
Growth Catalysts
- India's Smart Cities Mission:National infrastructure procurement is channeling investment toward Mumbai, Delhi, and Bangalore metropolitan clusters, concentrating demand for aluminum folding gates in humid climate zones.
- OSHA Fall-Protection Mandates:Load-rated barrier specifications for industrial mezzanine and warehouse edge protection are specifying collapsible gate performance standards across US commercial installations.
- Aluminum Corrosion Resistance:Material substitution toward powder-coated aluminum grades is extending product lifecycles in coastal and high-humidity environments, reducing replacement frequency for property managers.
Market Restraints
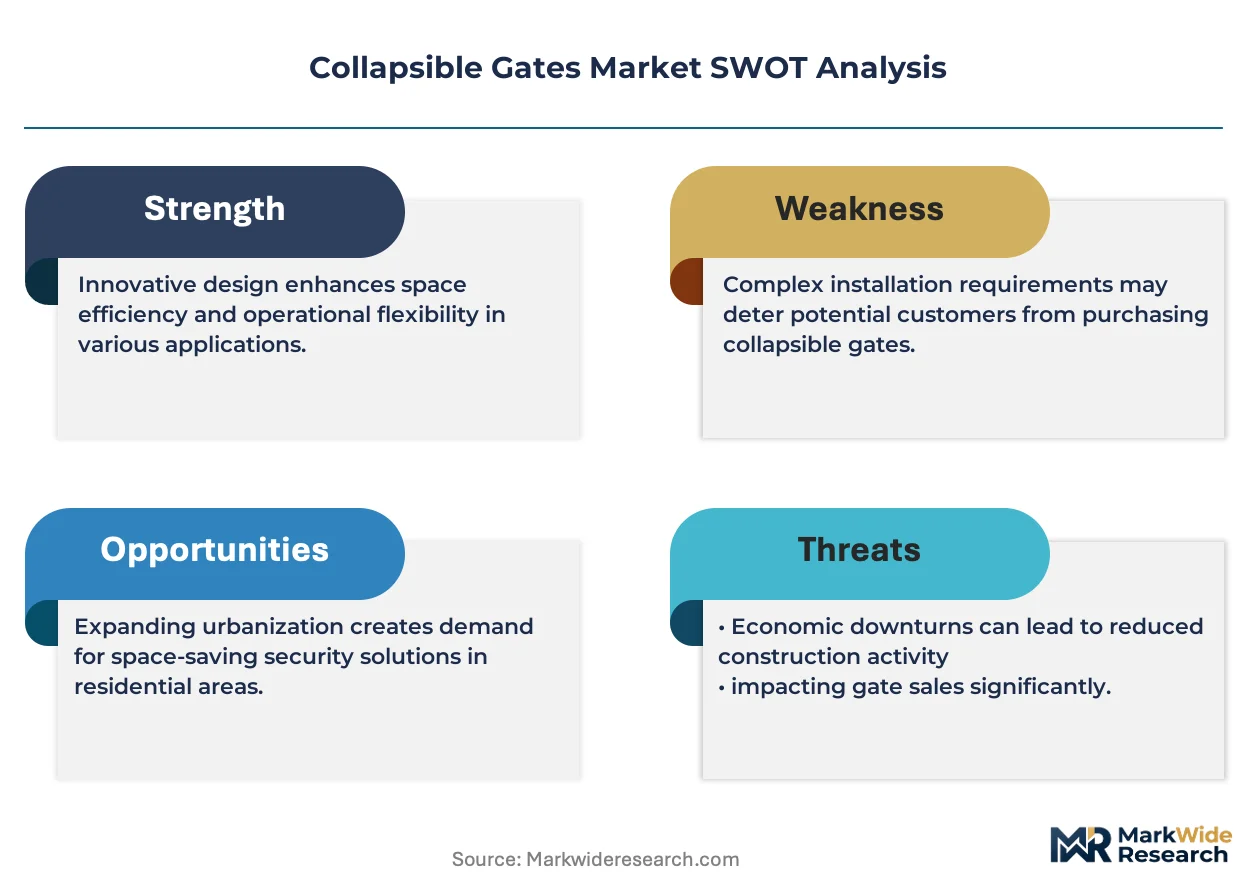
- Steel Input Volatility:Raw material cost swings for carbon steel grades are compressing margins for manual gate fabricators serving price-sensitive residential contractors.
- Chinese Supply Concentration:Automated welding line investments by East Asian fabricators are tightening export cost structures, limiting pricing power for regional competitors in Southeast Asian markets.
- CE Marking Friction:EU Construction Products Regulation fire-resistance testing requirements for permanently installed commercial barriers are extending certification timelines for non-European suppliers.
Strategic Opportunities
- IoT-Enabled Retrofit Demand:Smart building codes mandating connectivity for automated access points are creating upgrade pathways for legacy manual gate installations in US commercial portfolios.
- Integrated Access Bundling:Pairing collapsible barriers with electronic entry platforms is capturing higher-margin procurement from facility managers seeking single-vendor accountability.
- Urban Footprint Constraints:Architects specifying space-efficient alternatives to swing or slide mechanisms are accelerating specification of folding gate configurations in constrained European city centers.
Industry Challenges
- Certification Timeline Compression:BIS certification requirements for steel fabricated products are adding compliance layers for imported gate assemblies entering Indian infrastructure projects.
- Integration Complexity:Motorized gate deployment with building management systems demands specialized control-system expertise that mid-tier installers struggle to source.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Collapsible Gates Market |
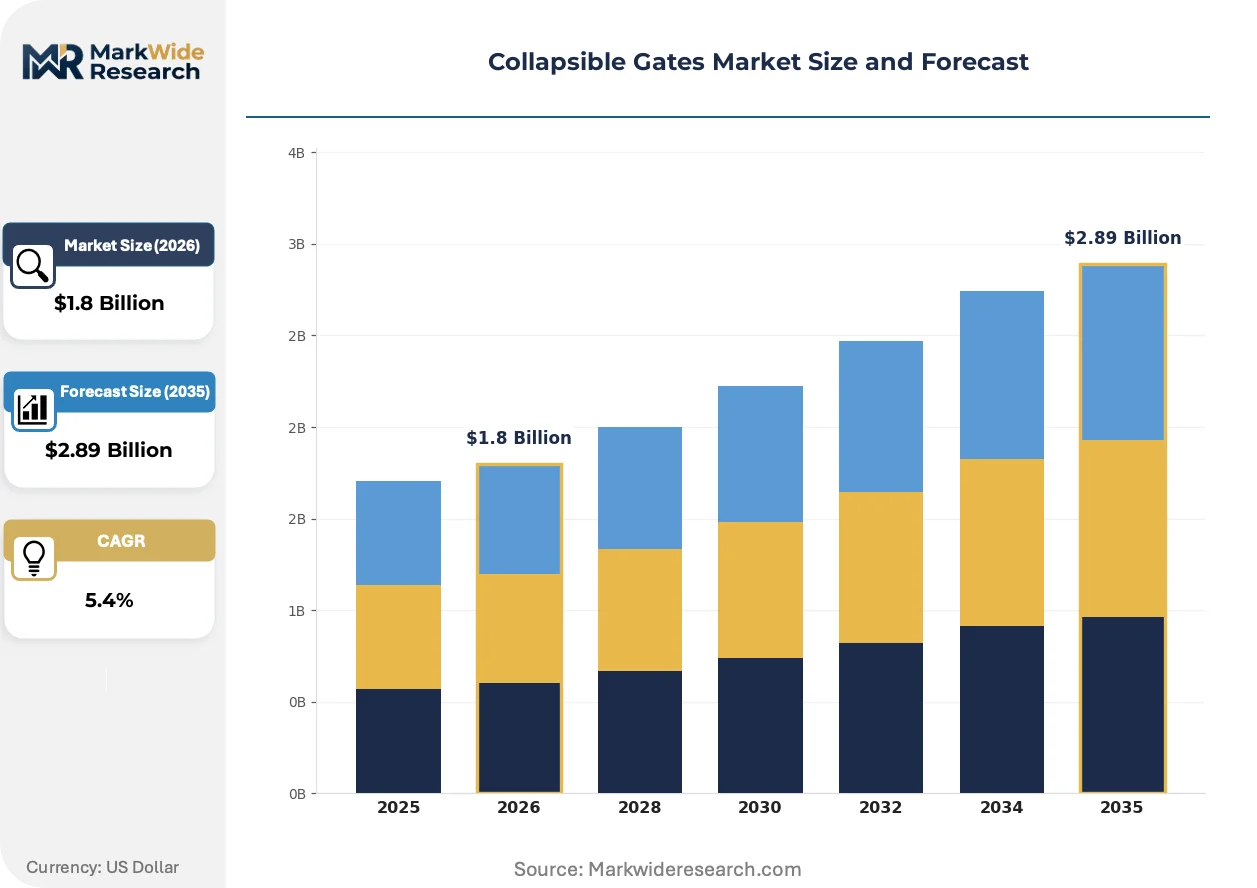
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.89 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual Gates, Automatic Gates, Remote-Controlled Gates, Folding Gates Material: Aluminum, Steel, Vinyl, Wood Application: Residential, Commercial, Industrial, Security Installation: Wall-Mounted, Free-Standing, Ground-Embedded, Portable |
| Companies Covered | The Chamberlain Group, DormaKaba, Hörmann Group, Banham Group, Bolton Gate, PHR Engineering, GateCraft, Jiangsu Lida Group, Porte-Rapid, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Collapsible Gates Market Strategic Shifts
Automation architecture is fragmenting into interoperable subsystems, allowing property owners to upgrade access control incrementally rather than replacing entire perimeter systems. This modularity is compressing replacement cycles and reshaping vendor competitive positioning.
Mesh-panel folding gate systems with standardized mounting interfaces are modularizing installation workflows for commercial retrofit projects. Facility managers in US retail complexes are adopting these configurations to minimize tenant disruption during access-point upgrades. The technology is modularizing what were previously custom-fabricated installations into repeatable, rapid-deployment solutions.
EU Construction Products Regulation fire-resistance testing protocols are mandating thermal-performance documentation for commercial building integration. Gate manufacturers serving European markets are reengineering slat geometries and hinge assemblies to achieve specified ratings. Automatic gate segments with integrated smoke-detection linkages are experiencing accelerated specification in German and French commercial developments.
Specification authority is migrating from general contractors to facilities-management departments with lifecycle-cost accountability. Direct vendor relationships are displacing traditional distributor channels for motorized gate procurement in US and UK commercial portfolios. This concentration is most visible in multi-site retail and logistics operators pursuing standardized perimeter security across distributed property networks.
Collapsible Gates Market Segmentation
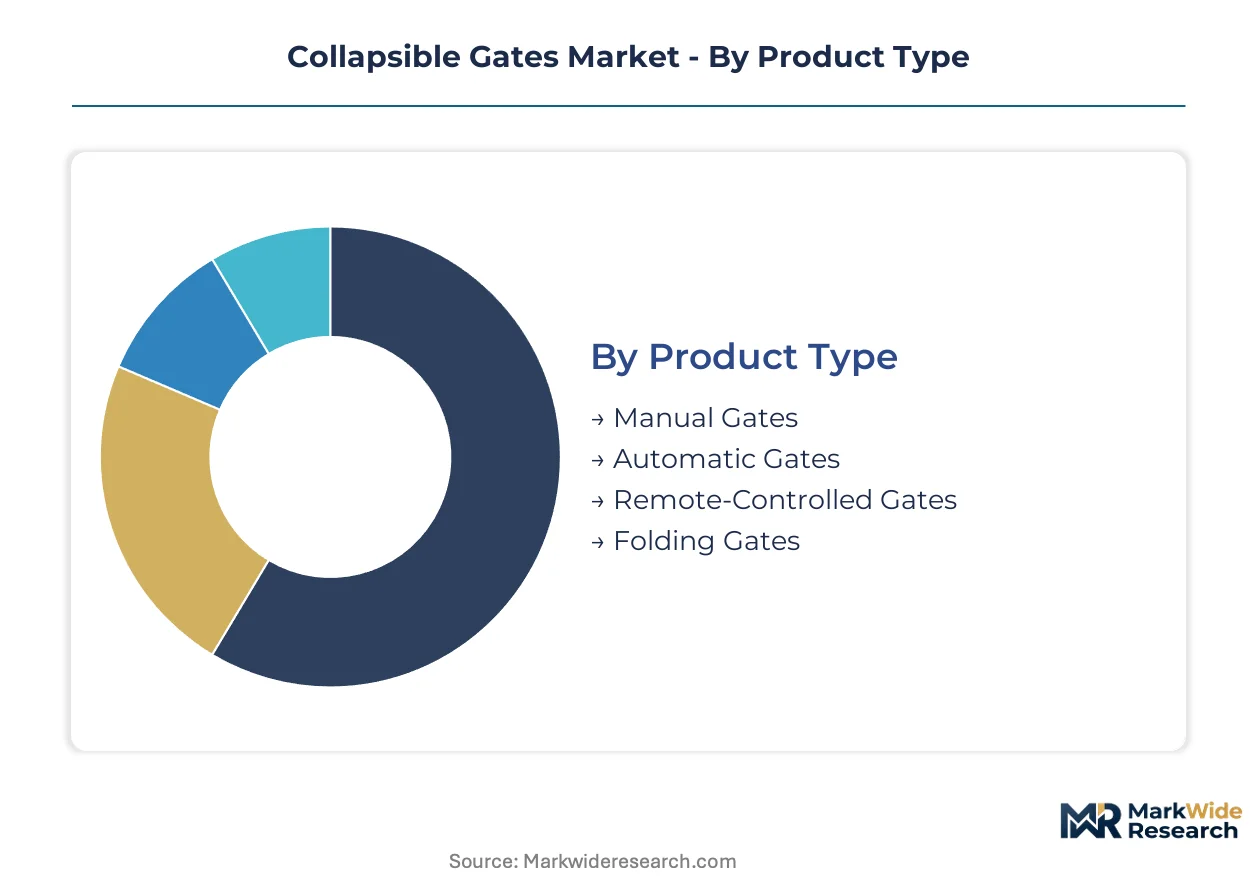
Segmentation in the collapsible gates market reveals how certification burdens, climate performance, and integration complexity stratify procurement decisions across property types. Product configuration and material selection determine compliance pathways, while installation method shapes labor economics and retrofit feasibility.
Product Type:
OSHA mandates load-rated performance for industrial automatic gates, while CE marking requirements under EU Construction Products Regulation apply to permanently installed motorized barriers. Manual gates face lighter documentation but must still meet regional structural safety codes.
- Automatic Gates:Motorized systems with integrated control electronics and building management system connectivity. Demand concentrates in US commercial logistics facilities where OSHA fall-protection compliance drives specification of load-rated barriers with documented performance testing.
- Folding Gates:Retractable interlocking slat systems enabling compact storage in constrained urban footprints. Architects in European city centers specify these configurations to maximize usable floor area in commercial retrofits where swing or slide mechanisms prove impractical.
- Manual Gates:Hand-operated barrier systems prioritizing cost minimization for residential and light commercial use. Indian residential contractors source standardized units from Jiangsu fabricators for rapid-install projects.
- Remote-Controlled Gates:Radio-frequency or infrared-actuated systems offering operator convenience without full building integration. Security-focused applications in Middle Eastern commercial complexes favor this mid-tier automation level.
Leading the category by volume: Manual Gates. Growing fastest: Folding Gates.
Material:
Material substitution patterns track corrosion exposure severity and lifecycle cost accountability, with coastal and humid climate zones driving specification shifts.
- Aluminum:Powder-coated grades deliver corrosion resistance in high-humidity environments without weight penalties. India's smart cities infrastructure procurement in Mumbai and Bangalore metropolitan clusters specifies aluminum folding gates for coastal and monsoon-exposed installations.
- Steel:Carbon and stainless grades provide structural capacity for load-rated industrial applications. US warehouse mezzanine edge protection under OSHA guidelines mandates steel construction with documented load testing.
- Vinyl:Polymer-composite barriers offering minimal maintenance for residential pool enclosures and light commercial privacy screening. Florida and Gulf Coast US residential markets specify vinyl for salt-air durability.
- Wood:Traditional material retained for aesthetic-sensitive historic district renovations and premium residential estate applications. European heritage building codes in German and French urban centers preserve wood specification for visual continuity.
Dominant by installed value: Steel. Expanding most quickly: Aluminum.
Application:
End-use segmentation maps directly to performance standards intensity and procurement authority concentration.
- Commercial:Retail complexes, office buildings, and hospitality properties requiring integrated access-system bundling. US multi-site retail operators consolidate vendor relationships around facility management departments with lifecycle-cost accountability.
- Industrial:Manufacturing facilities, warehouses, and logistics hubs with OSHA-mandated fall-protection and perimeter security requirements. Load-rated collapsible gates for mezzanine edges represent non-discretionary compliance spend.
- Residential:Single-family and multi-family dwellings prioritizing cost minimization and quick installation. Asian contractors source standardized manual folding gates for volume housing developments.
- Security:High-threat environments including data centers, government facilities, and critical infrastructure demanding enhanced penetration resistance. EU-specified fire-resistance testing applies to permanently installed security barriers in commercial building integration.
Highest revenue concentration: Commercial. Steepest expansion trajectory: Industrial.
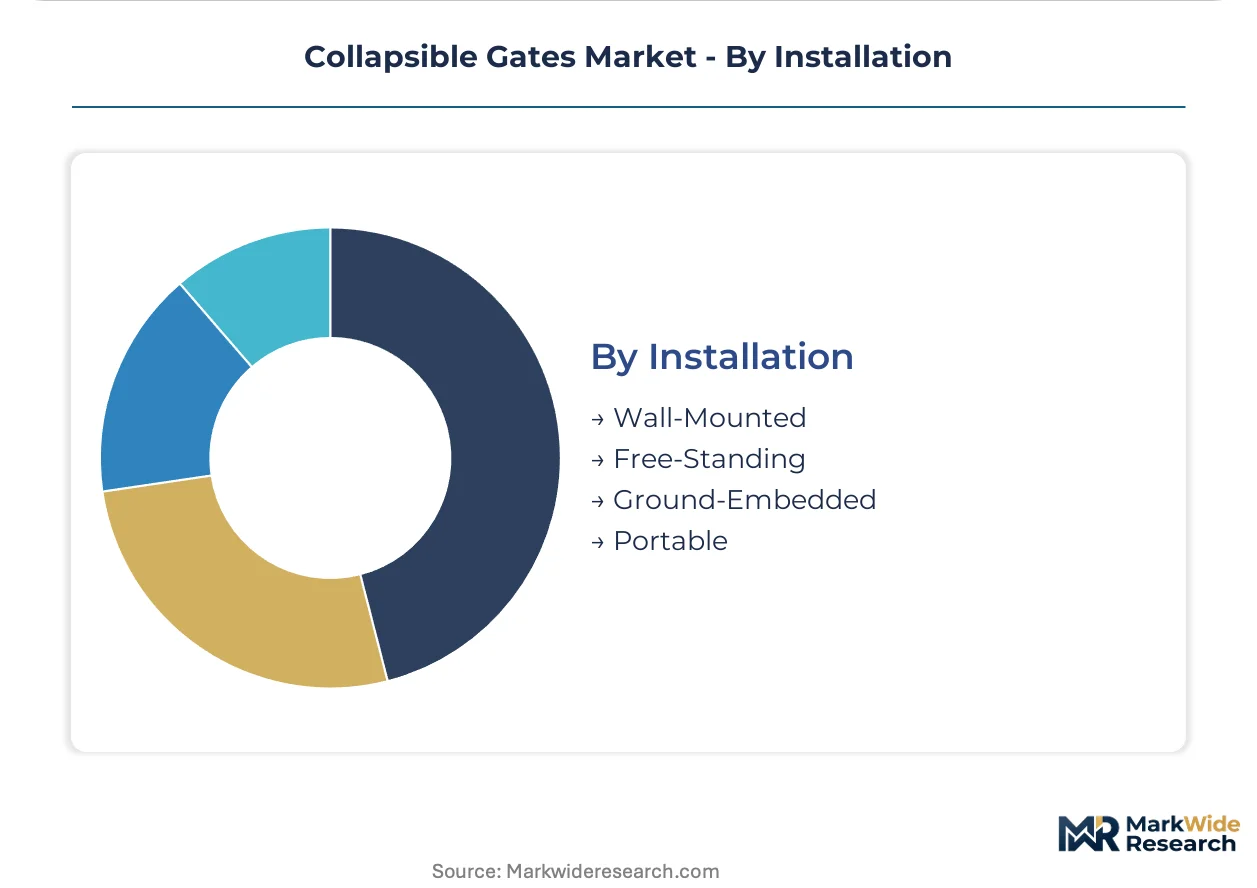
Installation:
Mounting configuration determines labor skill requirements, structural modification scope, and relocation flexibility.
- Wall-Mounted:Fixed attachment to structural elements providing maximum stability for high-frequency operation. German commercial installations specify wall-mounted automatic gates for building management system integration.
- Ground-Embedded:Foundation-anchored systems for heavy-duty industrial and security applications requiring vehicle impact resistance. US logistics hubs deploy ground-embedded steel gates for truck yard access control.
- Free-Standing:Self-supporting frames enabling rapid deployment without structural modification. UK retail retrofit projects favor free-standing folding gates to minimize tenant disruption.
- Portable:Modular units with standardized mounting interfaces for temporary event security and construction site perimeter control. French and German commercial developments specify portable mesh-panel systems for phased project delivery.
Standard specification: Wall-Mounted. Gaining share fastest: Portable.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Steel feedstock availability in Hebei Province anchors Chinese fabrication capacity for collapsible gate exports. Raw material proximity enables cost-competitive production of carbon-grade folding systems serving Asian residential contractors and Middle Eastern commercial developers.
United States
Warehouse logistics operators drive specification of load-rated automatic barriers for OSHA-compliant mezzanine edge protection. The Department of Labor mandates documented performance testing for industrial fall-prevention installations. Dallas-Fort Worth and Chicago metropolitan corridors concentrate procurement from multi-site retail and distribution networks standardizing perimeter security.
Germany
Commercial property developers prioritize CE-marked automatic gates with building management system integration. EU Construction Products Regulation fire-resistance testing protocols govern permanently installed security barriers. Frankfurt and Munich urban cores specify folding gate configurations to maximize usable floor area in constrained retrofit environments.
India
Smart Cities Mission infrastructure procurement channels aluminum folding gate demand toward corrosion-resistant coastal installations. BIS certification requirements for steel fabricated products add compliance layers for imported assemblies entering public projects. Mumbai, Delhi, and Bangalore metropolitan clusters concentrate procurement activity under national urban development programs.
China
Automated welding line investments by Hebei and Jiangsu fabricators tighten export cost structures for manual gate production. GB standards and MIIT industrial policy guide quality benchmarks for domestic and overseas shipments. Pearl River Delta manufacturing bases supply standardized quick-install units to Southeast Asian residential contractors.
United Arab Emirates
Commercial retail complex developers seek integrated access-system bundling for high-traffic hospitality and entertainment venues. MOHAP building safety regulations align with international fire-resistance standards for permanently installed barriers. Dubai and Abu Dhabi construction activity concentrates demand for premium automatic gate configurations in mixed-use developments.
Collapsible Gates Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue automation-adjacent spaces and IoT-enabled retrofit solutions. The vendor base stratifies across three functional tiers: premium engineering houses with German heritage, volume-oriented Asian fabricators, and regional installation specialists. Three archetypes dominate competitive positioning: integrated access-system bundlers, steel-grade standardization champions, and aluminum corrosion-resistance specialists. Dominant competitive moves include backward integration into automated welding capacity and strategic partnerships with building management system providers.
Within the premium-engineering archetype, Hörmann Group exemplifies German heritage positioning in automatic gate segments. DormaKaba occupies a position as an integrated access-system bundler pairing physical barriers with electronic entry platforms. Jiangsu Lida Group anchors the volume-production tier for Asian residential markets. These three entities represent distinct competitive vectors: heritage engineering, system integration, and scale manufacturing.
| Leading Market Players |
|---|
| The Chamberlain Group |
| DormaKaba |
| Hörmann Group |
| Banham Group |
| Bolton Gate |
| PHR Engineering |
| GateCraft |
| Jiangsu Lida Group |
| Porte-Rapid |
| Others |
Value Chain & Pricing Dynamics
Automated welding technicians in Hebei Province anchor fabrication cost structures, with labor-cost differentials between Chinese export hubs and European manufacturing centers driving 40-60 point spreads between economy and premium tier gate systems. This workforce concentration enables volume fabricators to undercut regional competitors while German engineering houses maintain pricing power through integrated service bundling.
Pricing Analysis
Warranty and preventive maintenance bundling separates premium automatic gate vendors from unbundled manual gate suppliers. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and motorization complexity, with CE-marked automatic systems commanding substantial premiums over BIS-compliant manual units. Price differentiation hinges on after-sales service depth, as facility managers prioritize single-vendor accountability for integrated access systems. Cost compression in economy-tier manual gates is intensifying because Hebei fabricators have automated frame welding, eroding margin buffers for regional competitors. Residential contractors in India exhibit highest price sensitivity, while US commercial logistics operators demonstrate lowest sensitivity due to OSHA compliance mandates.
Supply Chain Analysis
Container freight cost volatility from Shanghai to Hamburg and Jebel Ali has compressed margin structures for export-dependent fabricators, forcing inland logistics optimization. Supply concentrates in China, India, and Germany, with Hebei Province anchoring carbon steel folding gate production and Jiangsu feeding standardized manual units to Southeast Asian contractors. Raw material dependencies span hot-rolled steel coil from Baosteel, aluminum extrusion from Hindalco, and powder-coat resins from BASF supply chains. Single-source vulnerability concentrates in automated control system imports from Taiwanese electronics suppliers. Distribution runs through regional installation specialists who capture 25-35 point value-add for building management system integration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The collapsible gates sector is executing a technology-transition phase as IoT-enabled retrofit solutions displace legacy manual installations in commercial portfolios. Building management system connectivity requirements are accelerating replacement cycles and reshaping vendor competitive positioning.
For Market Incumbents: Acquire automated welding capacity in Hebei or Jiangsu to defend margin position against Chinese export cost compression. Secure BIS certification pathways for Indian infrastructure procurement before Smart Cities Mission tenders accelerate. Channel control through integrated access-system bundling offers defensive moats against standalone gate fabricators.
For New Entrants and Emerging Players: The mid-tier price-point gap between Hörmann-engineered premium systems and Jiangsu volume production creates entry space for aluminum corrosion-resistance specialists. Target portable mesh-panel configurations for UK and French retail retrofit projects where rapid deployment minimizes tenant disruption. Pursue direct facility management relationships displacing traditional distributor channels.
For Investors and Strategic Acquirers: Re-rating potential sits with integrated access-system bundlers given smart building code mandates for IoT connectivity across US commercial portfolios. Long-term viability favors vendors with captive control system expertise and backward integration into automated fabrication. Monitor OSHA enforcement intensity for industrial mezzanine fall-protection as inflection indicator for load-rated automatic gate demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Automated Welding | Hebei fabricators tighten cost structures for export markets, compressing regional competitor margins. |
| Building Management System Partnership | DormaKaba-style bundling captures higher-margin procurement from facility managers seeking single-vendor accountability. |
| BIS Certification Investment | Compliance layers for imported assemblies entering Indian Smart Cities infrastructure projects create competitive barriers. |
| IoT-Enabled Retrofit Platform Launch | Smart building codes mandating connectivity create upgrade pathways for legacy manual gate installations. |
| Aluminum Corrosion-Resistance Positioning | Powder-coated grades extend lifecycles in Mumbai and Bangalore coastal installations, reducing replacement frequency. |
Study Parameters
Multi-period observation of OSHA enforcement patterns, BIS certification timelines, and EU Construction Products Regulation fire-resistance testing protocols anchored the trend analysis, supplemented by interviews with facility management directors, commercial property developers, and regional installation contractors. Secondary validation drew from Department of Labor guidance documents, EU Official Journal regulatory filings, and Indian Ministry of Housing and Urban Affairs procurement disclosures. Bottom-up unit economics from fabricator cost structures and top-down infrastructure spend projections were triangulated to constrain forecast variance.
Segment-weighting across product type, material grade, application intensity, and installation method determined value allocation throughout the forecast period. CAGRs were derived from elasticity-adjusted demand curves incorporating climate exposure severity, regulatory compliance mandates, and urban footprint constraints. Industry-specific inputs included smart building code adoption rates and automated welding capacity expansion in Hebei Province.
Inputs from facility management procurement databases and infrastructure tender platforms were available through the study window; gaps in real-time steel coil pricing transparency introduce uncertainty bands around margin compression assumptions. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Automation Systems
Escalator Market
Building Automation Systems
Smart Building Solutions Market
Building Automation Systems
Elevator Modernization Market
Building Automation Systems
Building Analytics Market
Building Automation Systems
Residential Electric Underfloor Heating Market
Building Automation Systems
Platform Lifts Market
Building Automation Systems
Automated Daylight Harvesting Systems Market
Building Automation Systems
AEC Market
Building Automation Systems
Building Technologies Market
Building Automation Systems
Global Nordic Building Automation and Control Market
Building Automation Systems
Energy Efficient Elevators Market
Building Automation Systems
Signage Market
Building Automation Systems
Tunnel Automation Market
Building Automation Systems
Global Platform Screen Doors for Subway Lines Market
Building Automation Systems
Dumbwaiter Lifts Market
Building Automation Systems
Smart Passenger Elevators Market