
 Industrial Roller Chain Drives Market | 2026-2036
Industrial Roller Chain Drives Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial Roller Chain Drives Market Intelligence
The skilled labor gap for precision machining and heat treatment is collapsing the buffer between standard and premium product quality, creating an operational challenge. Tsubakimoto Chain Co. leverages extensive automation and in-house process control to maintain consistent output. Regal Rexnord Corporation competes on its global manufacturing footprint and broad distribution network to serve diverse end-user requirements. Meanwhile, Renold PLC differentiates through its focus on high-performance and custom-engineered solutions for demanding industrial environments.
An industrial roller chain drive is a method of mechanical power transmission composed of short cylindrical rollers linked together and driven by a toothed wheel, or sprocket. These drives, often made from carbon or alloy steel, are defined by specifications like chain pitch and roller diameter. Their primary purpose is to transfer torque and motion efficiently in applications ranging from conveyors to heavy machinery. Standard roller chains represent the largest segment by volume, while heavy-duty roller chains used in mining equipment and construction machinery command higher margins.
Regulatory frameworks ensure operational safety and product interoperability. Global standards like ISO 606 dictate chain dimensions and strength ratings, facilitating international trade and component replacement. In the United States, OSHA regulations mandate proper guarding for chain and sprocket drives to prevent worker injury. Similarly, the EU's Machinery Directive requires CE marking, confirming that equipment incorporating these drives meets high safety and health standards. The key decision for purchasers now hinges on evaluating total cost of ownership, balancing upfront investment against the long-term benefits of enhanced durability and reduced downtime.
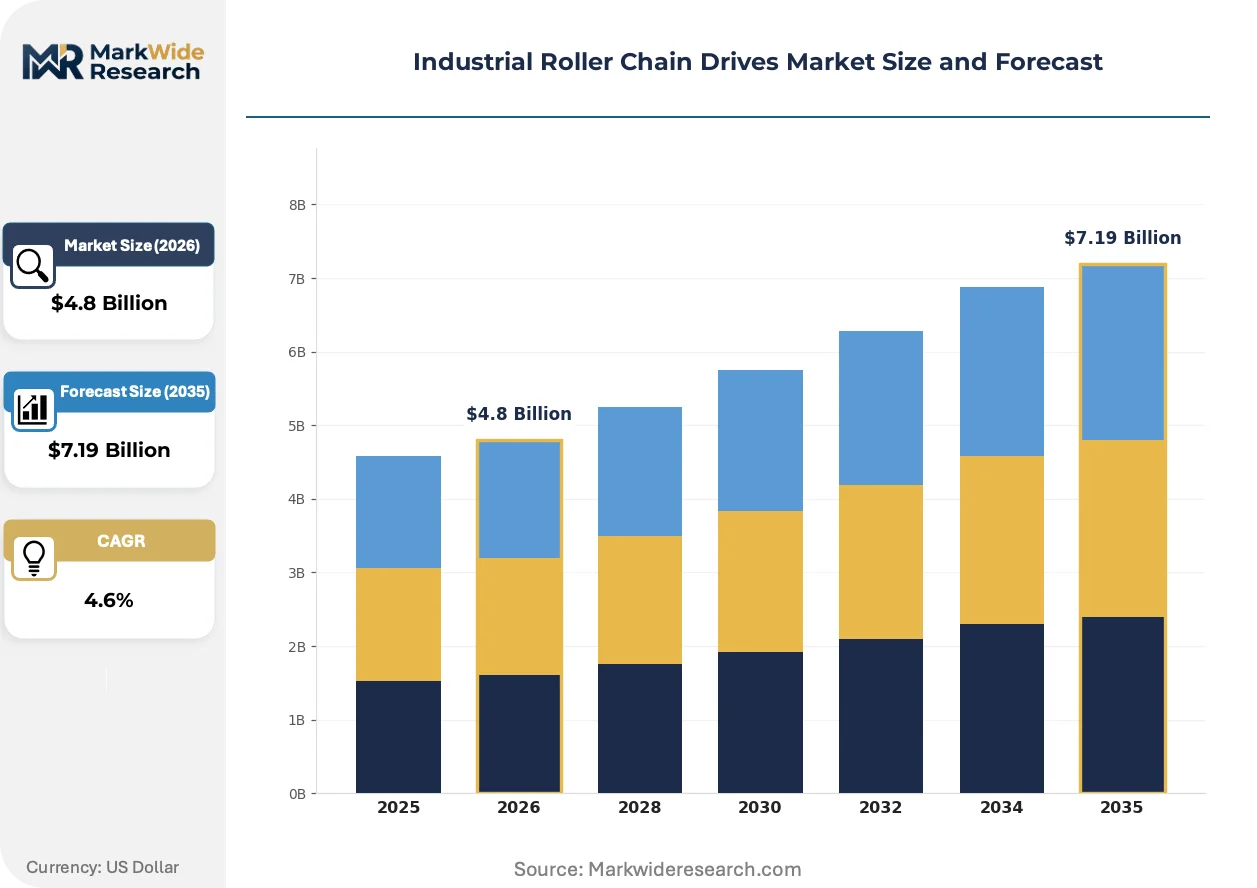
Market Dynamics
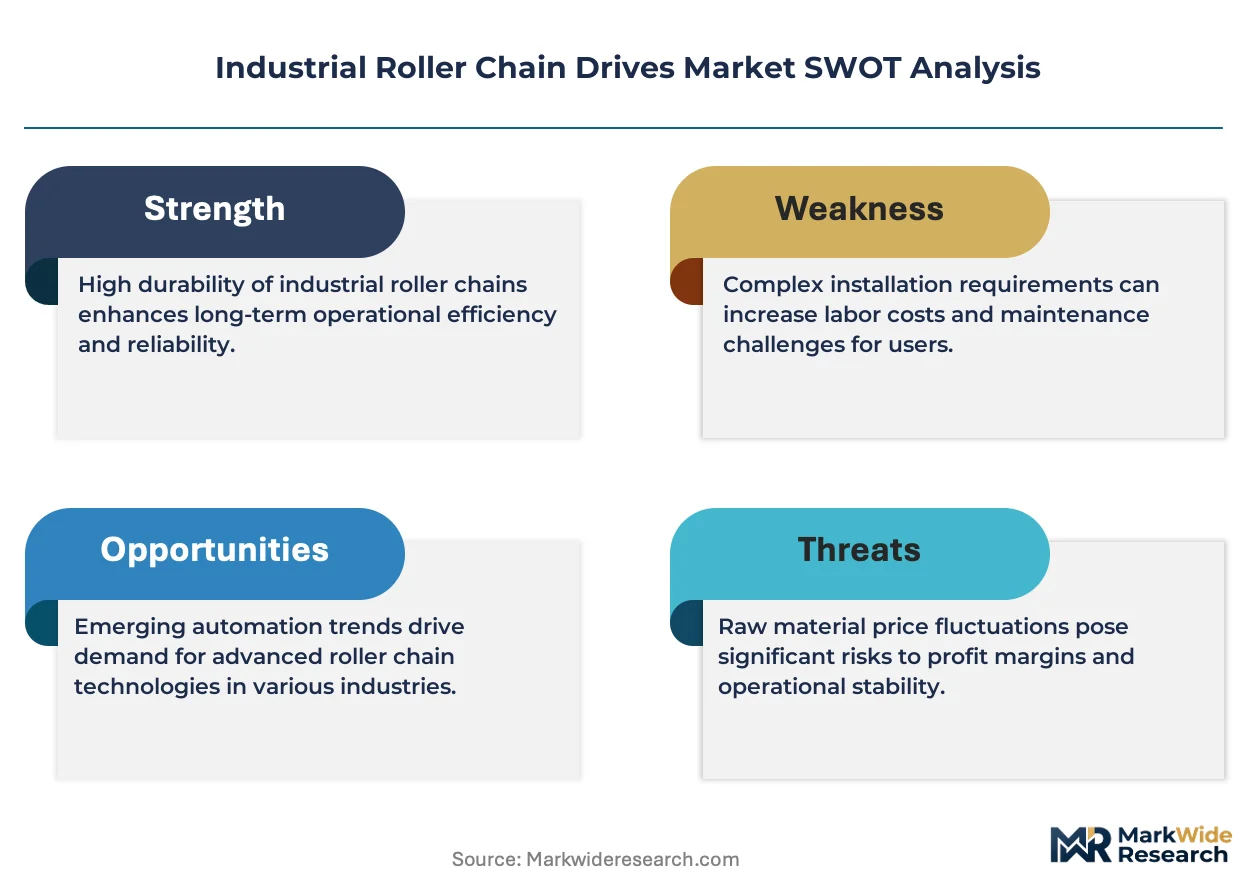
The fundamental market dynamic is the tension between global standardization, driven by ISO 606, and demand for custom-engineered chains for high-stress applications in automation and agricultural machinery.
Growth Catalysts
- Advanced Coatings:Specialized surface treatments enhance wear resistance and operational life, reducing long-term maintenance costs in food processing and manufacturing.
- Agricultural Mechanization:Government support for farm modernization in India and Brazil stimulates demand for durable chains in harvesting equipment.
- Global Standards:The ISO 606 framework ensures component interchangeability, simplifying supply chains for OEMs and facilitating international trade.
Market Restraints
- Input Cost Volatility:Price fluctuations for high-grade alloy steel directly impact manufacturing costs and create pricing instability for chain producers.
- Substitution Threat:High-torque synchronous belts gain share in applications where lower noise and lubrication-free operation are critical design factors.
- Technical Limitations:Operational noise and lubrication needs limit use in cleanroom environments like semiconductor manufacturing or specific food-grade processes.
Strategic Opportunities
- Warehouse Automation:Expanding e-commerce logistics centers creates demand for specialized chains within automated storage and retrieval systems (AS/RS).
- Predictive Maintenance:Integrating IoT sensors into chains enables real-time wear monitoring, creating new service-based revenue models for manufacturers.
- Infrastructure Development:Public works in Southeast Asia, including Vietnam, drive demand for heavy-duty chains in construction and material handling equipment.
Industry Challenges
- Skilled Labor Scarcity:A persistent shortage of technicians skilled in precision machining and advanced heat treatment processes constrains production capacity and impacts quality consistency.
- Regulatory Fragmentation:Manufacturers must navigate a complex web of regional safety standards, such as OSHA in the US and CE marking in the EU, increasing compliance costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial Roller Chain Drives Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.19 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Roller Chain, Heavy Duty Roller Chain, Leaf Chain, Silent Chain, Double Pitch Chain, Specialty Chain Technology: Heat Treatment, Case Hardening, Surface Coating, Alloy Steel, Stainless Steel Treatment, Lubrication Systems Application: Conveyors, Agricultural Machinery, Material Handling, Printing Presses, Packaging Equipment, Mining Equipment End User: Manufacturing Plants, Construction Firms, Mining Operators, Textile Producers, Food Processing Units, Automotive OEMs |
| Companies Covered | Tsubakimoto Chain Co., Regal Rexnord Corporation, Renold PLC, iwis SE & Co. KG, SKF Group, Timken Company, Diamond Chain Company, KettenWulf Betriebs GmbH, Peer Chain, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial Roller Chain Drives Market Strategic Shifts & Innovations
Technological advancements are pushing roller chain designs toward greater specialization. The market is shifting from a commodity focus to application-specific solutions that prioritize durability, efficiency, and integration with digital monitoring systems.
High-strength, lightweight alloy materials form the basis of next-generation roller chains. These advanced chains are seeing rapid adoption in robotics and automated guided vehicles (AGVs) where weight and inertia are critical performance factors. This evolution is miniaturizing power transmission systems, enabling more compact and energy-efficient machinery designs.
The EU's Machinery Directive mandates CE marking, requiring a thorough safety assessment for equipment with chain drives. This regulation forces manufacturers exporting to Europe to integrate safety features like enhanced guarding from the design stage. Heavy machinery and industrial automation segments are most affected, redesigning products for compliance.
A clear behavioral shift towards evaluating total cost of ownership (TCO) over initial purchase price is evident. This trend disrupts traditional distributor channels, favoring suppliers who offer lifecycle support and predictive maintenance services. This procurement model is most visible in capital-intensive sectors like mining and marine applications where downtime is extremely costly.
Industrial Roller Chain Drives Market Segmentation
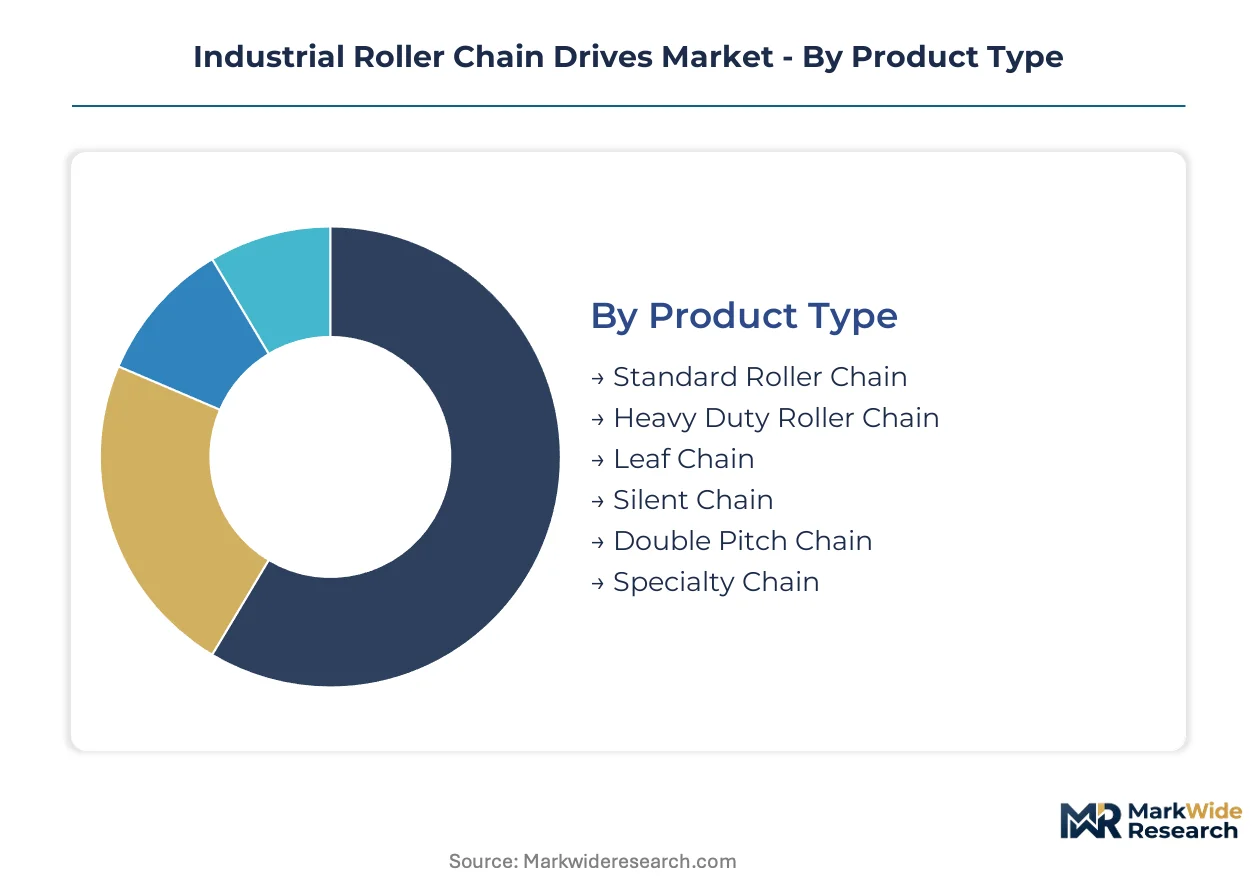
Understanding the varied requirements across industrial sectors is crucial for manufacturers in the roller chain drives market. This segmentation analysis provides a granular view of product types, enabling technologies, diverse applications, and distinct end-user categories. It highlights where specific innovation and demand drivers intersect within this mechanical power transmission landscape.
Product Type:
Margin pools within this product type category are heavily influenced by customization and performance demands.
- Standard Roller Chain:These chains adhere to global standards like ISO 606, offering broad compatibility and cost-effectiveness for general-purpose power transmission. Their widespread use makes them a volume leader.
- Heavy Duty Roller Chain:Engineered for extreme loads and harsh operating conditions, these chains are constructed from robust alloy steels with enhanced fatigue resistance. Demand concentrates in mining and construction machinery, where high torque transfer is critical.
- Leaf Chain:Composed of interleaved plates, leaf chains are designed for lifting and counterbalancing in forklifts and material handling equipment.
- Silent Chain:Featuring inverted teeth, silent chains provide smoother, quieter operation and higher speeds, favored in printing presses.
- Double Pitch Chain:With twice the pitch of standard chains, these suit longer center distances and slower speeds in conveyor systems.
- Specialty Chain:Custom-engineered for demanding industrial environments, these chains incorporate unique designs or materials for specific performance attributes like corrosion resistance. Demand is significant in food processing and advanced automation.
Standard Roller Chain holds significant installed capacity. Heavy Duty Roller Chain is rotating up the share rankings due to infrastructure development.
Technology:
Cost tiers define competitive positions across this technology segment, reflecting material science and advanced manufacturing processes.
- Heat Treatment:This process alters steel properties, enhancing hardness, strength, and wear resistance in roller chain components. It is fundamental for chain durability.
- Case Hardening:A specific heat treatment hardens the steel surface while maintaining a tough core, improving wear life. This technique is applied to critical wear surfaces.
- Surface Coating:Specialized surface treatments, such as nickel plating, enhance wear resistance and corrosion protection, extending operational life in corrosive environments. Demand is expanding in food processing and marine applications.
- Alloy Steel:The use of alloy steels provides superior strength-to-weight ratios and fatigue resistance for high-performance chains. These materials are critical for lightweight robotics and AGVs.
- Stainless Steel Treatment:Stainless steel chains offer inherent corrosion resistance, essential in applications requiring hygiene or chemical exposure.
- Lubrication Systems:Integrated or external lubrication systems ensure smooth operation, reduce friction, and extend service life. These systems are vital for heavy machinery.
Heat Treatment remains a foundational capability. Alloy Steel is witnessing expanded uptake in demanding industrial settings.
Application:
Demand for roller chain drives in different applications is shaped by operational intensity and regulatory compliance.
- Conveyors:Roller chains are widely used in conveyor systems for moving goods and materials, providing reliable power transmission. They are essential for logistics centers.
- Agricultural Machinery:Durable roller chains drive critical functions in tractors, harvesters, and other farm equipment, enduring harsh outdoor conditions and heavy loads. Government support for mechanization in India stimulates this segment.
- Material Handling:This includes forklifts, hoists, and AS/RS, where roller chains provide precise motion for warehouse automation.
- Printing Presses:Precision roller chains ensure synchronized movement of components in printing machinery, critical for high-quality output.
- Packaging Equipment:Chains facilitate precise indexing and movement of products through packaging lines, ensuring efficiency. This application demands reliability.
- Mining Equipment:Heavy-duty roller chains are indispensable in mining operations for excavators, crushers, and conveyors, designed to withstand abrasive conditions and extreme forces. These applications command higher margins.
Agricultural Machinery integration into new designs drives efficiency. Mining Equipment applications expand with infrastructure projects in Southeast Asia.
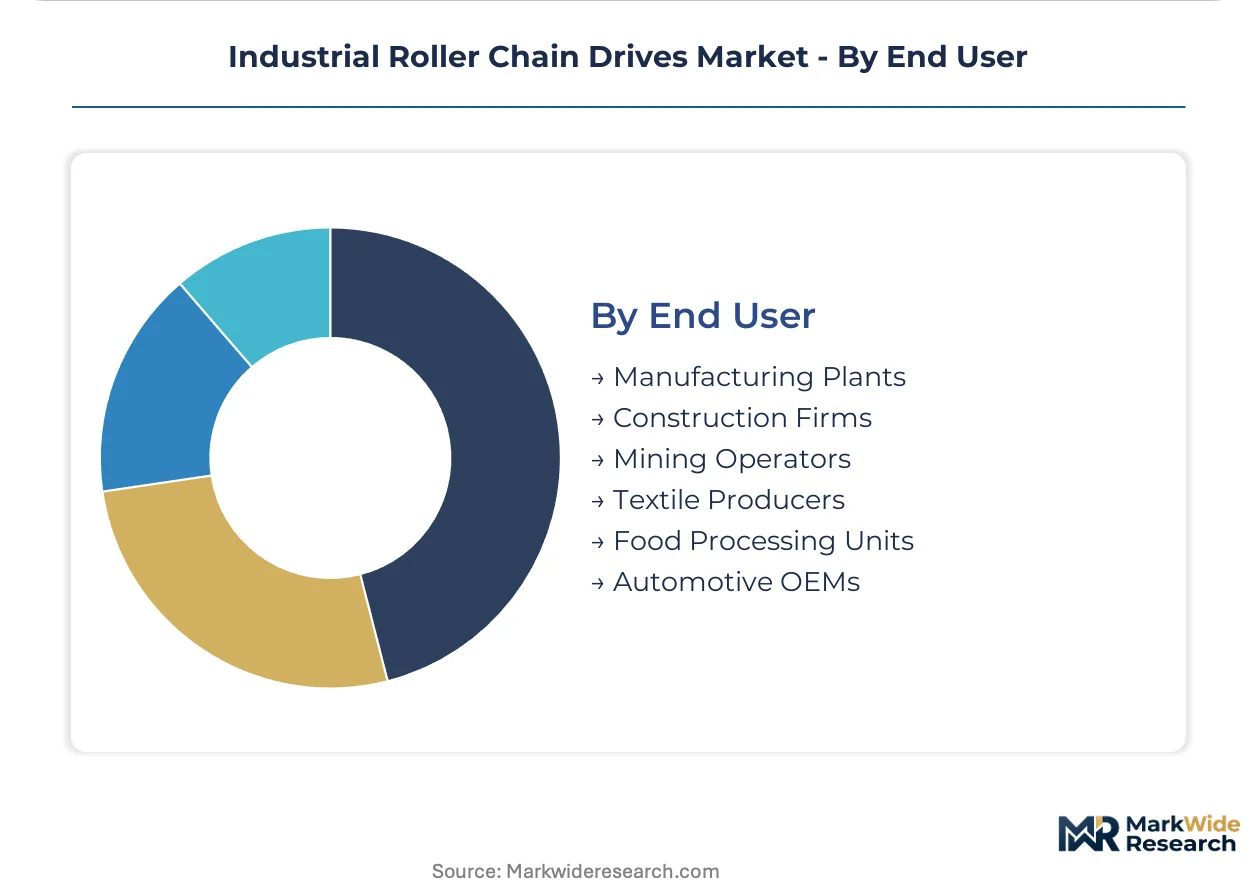
End User:
Customer type segmentation reveals distinct procurement patterns and performance requirements for roller chain drives.
- Manufacturing Plants:These facilities utilize roller chains for a wide array of machinery, including automation systems, assembly lines, and material handling equipment. Reliability and efficiency are paramount for continuous production.
- Construction Firms:Roller chains are integral to heavy construction machinery like excavators and cranes, operating in demanding outdoor environments. Durability against shock loads is a key purchasing factor.
- Mining Operators:This sector relies on robust, heavy-duty chains for power transmission in extraction and processing equipment. Total cost of ownership guides procurement.
- Textile Producers:Precision chains are used in looms and spinning machines, requiring smooth operation for consistent fabric quality.
- Food Processing Units:Chains in this segment often require corrosion-resistant materials like stainless steel and specialized coatings to meet hygiene standards. Regulatory compliance with food safety directives is critical.
- Automotive OEMs:Automotive manufacturers integrate roller chains into production machinery, including assembly lines and robotic systems. Precision and long service life are essential.
Manufacturing Plants procurement prioritizes operational uptime. Food Processing Units seek custom-engineered solutions for hygiene requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
OSHA regulations in the United States mandate proper guarding for chain and sprocket drives to prevent worker injury. This focus on safety influences product design and procurement decisions across North American industries. Demand for industrial roller chains remains strong in manufacturing and material handling applications.
United States
United States manufacturing plants demand reliable power transmission for assembly lines and material handling equipment. The country's regulatory environment emphasizes worker safety for industrial machinery. Automation clusters in the Midwest, like those around Chicago, increasingly integrate specialized chains into new robotic systems.
China
China's rapid industrial automation and extensive material handling equipment requirements drive substantial demand for roller chains. Adherence to GB standards ensures product quality and interoperability within its vast manufacturing sector. Manufacturing hubs in the Yangtze River Delta actively integrate advanced roller chain technologies into their production lines.
Germany
Germany's focus on high-precision engineering and automotive manufacturing creates sustained demand for specialized roller chains. The EU's Machinery Directive requires CE marking, influencing design for safety and performance in exported equipment. Industrial clusters in Baden-Württemberg lead in integrating advanced chain solutions for robotics and automated production.
India
India's government support for farm modernization significantly boosts demand for durable roller chains in agricultural machinery. Infrastructure development initiatives across the country also stimulate the heavy-duty chain segment. Manufacturing centers in Maharashtra increasingly produce components for both domestic agricultural and construction sectors.
Vietnam
Vietnam's robust infrastructure development projects and expanding manufacturing sector generate strong demand for heavy-duty and standard roller chains. Government policies aimed at attracting foreign direct investment fuel industrial growth and associated machinery needs. Industrial zones around Ho Chi Minh City actively adopt modern material handling and automation systems.
Industrial Roller Chain Drives Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier, defining the competitive landscape for industrial roller chain drives. The market exhibits a tiered structure, with global manufacturers offering comprehensive product portfolios. Several mid-sized companies focus on niche applications or specific regional markets. Strategic archetypes include scale producers, high-performance specialists, and regional solution providers. Portfolio diversification and geographic expansion are dominant competitive moves among key players.
On the premium-tier vector, Tsubakimoto Chain Co. represents a global leader, focusing on consistent output through extensive automation and in-house process control. Regal Rexnord Corporation, a United States-based entity, exemplifies players leveraging a broad global manufacturing footprint and distribution network to serve diverse end-user requirements across various sectors. Renold PLC, a European industrial chain manufacturer, occupies a position emphasizing high-performance and custom-engineered solutions tailored for demanding industrial environments. These companies collectively anchor the market's differentiation across scale, geographic reach, and product specialization, influencing competitive positioning.
| Leading Market Players |
|---|
| Tsubakimoto Chain Co. |
| Regal Rexnord Corporation |
| Renold PLC |
| iwis SE & Co. KG |
| SKF Group |
| Timken Company |
| Diamond Chain Company |
| KettenWulf Betriebs GmbH |
| Peer Chain |
| Others |
Cost & Logistics Intelligence
Three-month lead times for specialized roller chains, particularly those with advanced coatings, directly influence supply chain planning and pricing power for high-performance solutions. Global manufacturing hubs, especially in China, concentrate production capacity, impacting component availability and regional cost structures. This dynamic favors manufacturers with robust in-house process control and diversified production sites.
Pricing Analysis
Geographic price spreads for industrial roller chains reflect regional labor costs and regulatory compliance burdens, especially between Asian and European markets. The dominant pricing structure is contract-based long-term offtake for large industrial buyers, with tiered premium-mid-economy differentiation for general-purpose chains. Price differentiation stems from specialized surface coatings and adherence to global standards like ISO 606. Pricing pressure originates from volatility in high-grade alloy steel input costs. Construction firms are often the most price-sensitive buyers, while mining operators prioritize total cost of ownership over initial purchase price.
Supply Chain Analysis
Inventory turns for heavy-duty roller chains are closely tied to infrastructure project cycles in Southeast Asia, impacting regional stock levels. Geographic supply concentration for raw materials like high-grade alloy steel rests predominantly in China and Japan. The supply chain for industrial roller chains depends on specialized heat treatment facilities, often located near major manufacturing centers. A structural risk involves commodity price volatility for key input materials. Distribution runs through a network of global manufacturers and regional distributors, serving diverse end-user requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Industrial Roller Chain Drives market represents a significant service-attach opportunity, with predictive maintenance and IoT-enabled monitoring expanding faster than hardware sales. This shift allows manufacturers to capture recurring revenue streams beyond initial product sales.
For Market Incumbents: Secure long-term supply agreements for high-grade alloy steel to mitigate input cost volatility. Invest in advanced automation and in-house process control to counter the skilled labor gap in precision machining. This strategy will defend market share against emerging specialists offering high-performance alternatives, ensuring consistent output and product quality.
For New Entrants and Emerging Players: Lead with custom-engineered solutions for niche, high-stress applications in advanced automation and food processing units. Target the warehouse automation segment, particularly in rapidly expanding e-commerce logistics centers, which demand specialized chains for AS/RS. A focused go-to-market angle emphasizing corrosion resistance and integration with digital monitoring systems offers a clear path to market penetration.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across advanced manufacturing technologies, driven by automation and material science R&D. Long-term viability in this market hinges on companies capable of delivering high-performance, application-specific solutions that reduce total cost of ownership for end-users. Target acquisition archetypes include specialized manufacturers with strong intellectual property in advanced coatings or IoT integration capabilities. The signal to watch is the increasing adoption rate of real-time wear monitoring systems in heavy machinery.
| Strategic Initiative | Industry Significance |
|---|---|
| Develop IoT-integrated chain monitoring systems | Enables predictive maintenance, creating new service revenue models for manufacturers. |
| Invest in advanced surface coating technologies | Enhances chain durability and extends operational life in demanding industrial environments. |
| Expand manufacturing capacity in Southeast Asia | Captures demand from robust infrastructure development projects in emerging economies. |
| Form strategic partnerships with automation integrators | Facilitates the adoption of specialized chains in robotics and automated guided vehicles. |
| Strengthen in-house precision machining capabilities | Mitigates skilled labor scarcity and ensures consistent quality for high-performance products. |
Research Approach
Cross-validation between primary interviews with industry stakeholders and extensive secondary research anchors the qualitative findings and quantitative market projections. This study engaged plant engineers, procurement managers at manufacturing plants, R&D directors, and agricultural machinery OEMs to gather first-hand insights. Secondary sources included ISO 606 standards, OSHA regulations, EU Machinery Directive documents, and relevant industry association reports. Bottom-up and top-down triangulation ensured data integrity and consistency across various market segments.
Sensitivity analysis forms the basis of the analytical framework, evaluating market dynamics across the modeling period. The segmentation dimensions modeled include product type, technology, application, end-user, geographic region, and material composition. Compound annual growth rates were derived through a comprehensive analysis of historical data, current market trends, and projected demand drivers. Key industry-specific forecast inputs included global steel commodity prices and government spending on agricultural mechanization initiatives.
The analysis sits within stated boundaries; outcomes outside significant shifts in global trade policies or unforeseen technological disruptions would require recalibration. Forecasts reflect assumptions regarding economic stability and continued industrial mechanization. Input cost volatility for alloy steel and evolving regulatory frameworks present key risk factors. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Global Windshield Wiper Blades Market
Automotive Parts
Turkey Passenger Vehicles Lubricants Market
Automotive Parts
Automotive Parts Die Casting Market
Automotive Parts
Passenger Car Motor Oil Market
Automotive Parts
Mexico Automotive Air Filters Market
Automotive Parts
Automotive Steel Market
Automotive Parts
Auxiliary Oil Cooler Market
Automotive Parts
Asia-Pacific Electric Power Steering Market
Automotive Parts
India Electric Hydraulic Power Steering Market
Automotive Parts
Clutch Pedal Kit Market
Automotive Parts
Automotive Aluminum Parts High Pressure Die Casting (HPDC) Market
Automotive Parts
Lug Wrench Market
Automotive Parts
Brass Synchronizer Ring Market
Automotive Parts
Canada Automotive Parts Die Casting Market
Automotive Parts
Oil Catch Cans Market
Automotive Parts
North America Very Narrow Aisle Trucks (VNA Truck) Market