
 Global Windshield Wiper Blades Market | 2026-2036
Global Windshield Wiper Blades Market Size, Share, and Industry Trends Forecast 2026-2036
Global Windshield Wiper Blades Market Outlook
Supplier consolidation from single-source to multi-source procurement is shifting how Tier-1 automotive component vendors contract wiper blade manufacturing. Robert Bosch GmbH leverages integrated rubber compounding and metal stamping capabilities across its European plants. Valeo SA anchors its position through beam blade architecture patents and direct supply relationships with French and German OEMs. Federal-Mogul LLC competes in the aftermarket through private-label distribution networks spanning North American retail channels.
Windshield wiper blades are elastomeric wiping assemblies mounted to articulated or cantilever arms, engineered with natural rubber, silicone, or halogenated polymer edges to maintain optical clarity across curved glass surfaces at operational speeds exceeding 200 cycles per minute. Beam blade configurations, eliminating exposed metal frames through integrated spring-steel spines, now lead product type evolution due to aerodynamic stability and ice-shedding performance. Silicone material segments command margin premiums for hydrophobic coating transfer and ultraviolet degradation resistance, while conventional bracket-style blades retain volume dominance in emerging fleet replacement channels.
NHTSA Federal Motor Vehicle Safety Standard 104 governs wiping system field of view requirements across United States vehicle classifications, while ECE R48 and Japan's JIS D 5705 establish regional performance benchmarks for wipe pattern coverage and noise thresholds. China's GB 15085 standard, administered by MIIT, mandates salt spray and durability testing that shapes export qualification protocols for Asian manufacturing platforms. Stakeholders must monitor regulatory divergence between polymer content restrictions under REACH and emerging dual carbon goals in China that threaten to reshape material certification costs and supply base geography.
Market Dynamics
Beam blade architecture is displacing conventional bracket designs as OEMs prioritize aerodynamic stability and ice-shedding performance, while silicone rubber compounds rewrite material specifications across European and Asian supply bases.
Growth Catalysts
- ECE R48 wipe pattern mandates:European vehicle lighting regulations enforce stricter optical clarity standards, forcing fleet operators into shorter replacement cycles and premium blade adoption.
- Winter climate severity:Northern Japanese prefectures and the German Alpine corridor sustain demand for halogenated polymer edges rated below minus forty degrees Celsius.
- Silicone hydrophobic coating transfer:Advanced rubber chemistry enables water-repellent surface treatment deposition during wiping cycles, extending functional blade life.
Market Restraints
- Natural rubber price volatility:Thai and Indonesian latex supply disruptions transmit directly to compounder cost structures, compressing margin visibility for mid-tier manufacturers.
- REACH polymer content restrictions:European chemical registration requirements threaten halogenated compound formulations with phase-out timelines, forcing premature R&D redirection.
- Bracket blade residual dominance:Emerging fleet replacement channels in India and Brazil retain cost-optimized metal-frame designs, limiting beam blade volume penetration.
Strategic Opportunities
- China dual carbon goals:MIIT-administered GB 15085 revisions incorporate carbon intensity benchmarks, creating first-mover advantage for low-emission silicone production methods.
- Direct-to-fleet digital channels:North American commercial vehicle operators are consolidating procurement through integrated maintenance platforms, bypassing traditional retail distribution.
- UV degradation resistance:Saudi Arabian and Australian sun-belt markets remain underserved by standard natural rubber formulations, opening specialty product lines.
Industry Challenges
- Beam blade spring-steel spine fabrication:Precision metal forming capabilities concentrate in German and Japanese tool-and-die clusters, constraining geographic diversification.
- Multi-standard certification timelines:Simultaneous NHTSA FMVSS 104, ECE R48, and JIS D 5705 testing protocols extend product launch cycles by eight to fourteen months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Windshield Wiper Blades Market |
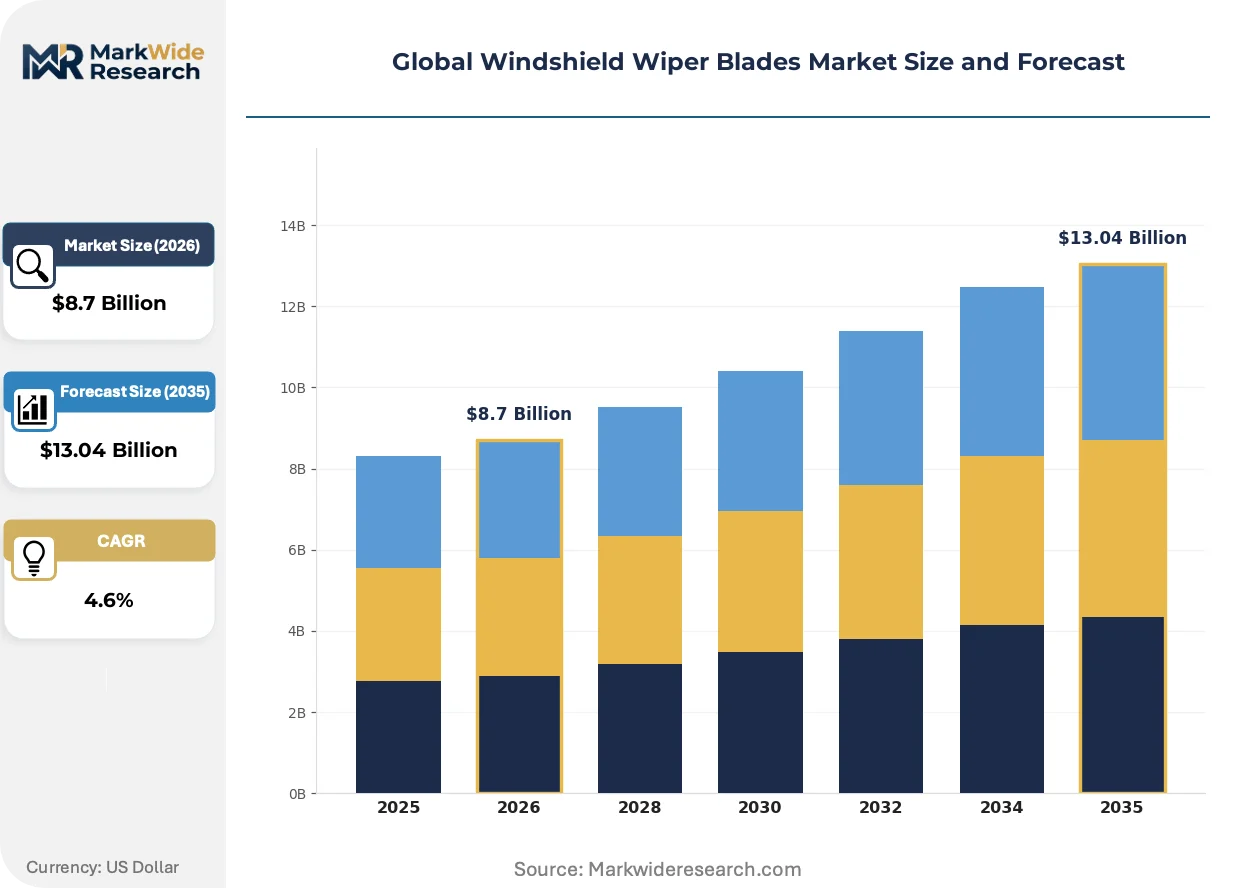
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.04 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Conventional Blades, Beam Blades, Hybrid Blades, Specialty Blades Vehicle Type: Passenger Cars, Trucks, SUVs, Commercial Vehicles Material: Rubber, Silicone, Metal, Polymer Distribution Channel: Online Retail, Auto Parts Stores, Dealerships, Supermarkets |
| Companies Covered | Trico Products Corporation, Federal-Mogul LLC, Robert Bosch GmbH, PIAA Corporation, Mitsuba Corporation, Valeo SA, HELLA GmbH & Co. KGaA, The Goodyear Tire & Rubber Company, Denso Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Windshield Wiper Blades Market Strategic Shifts
Material science breakthroughs and regulatory divergence are fragmenting competitive advantage sources, rewarding compounders who master multi-jurisdiction compliance while punishing single-standard specialists.
Silicone rubber formulation is converging with graphene additive integration to enhance thermal conductivity and ice-release properties. Japanese OEM specification teams are accelerating validation timelines for these hybrid compounds. The structural consequence is compressing development cycles for winter-rated blades while raising barriers for natural rubber-dependent competitors.
REACH polymer content restrictions are forcing halogenated compound phase-outs across European manufacturing platforms. Compounders face reformulation costs that disproportionately burden mid-volume producers serving aftermarket channels. German and French OEMs are responding by consolidating supplier qualifications around silicone-only portfolios.
Fleet maintenance platforms are consolidating procurement authority away from decentralized retail networks. North American commercial vehicle operators now specify blade performance metrics through integrated telematics rather than visual inspection. This behavior shift is most visible in long-haul trucking corridors linking Detroit to Dallas, where downtime cost calculations override unit price sensitivity.
Global Windshield Wiper Blades Market Segmentation
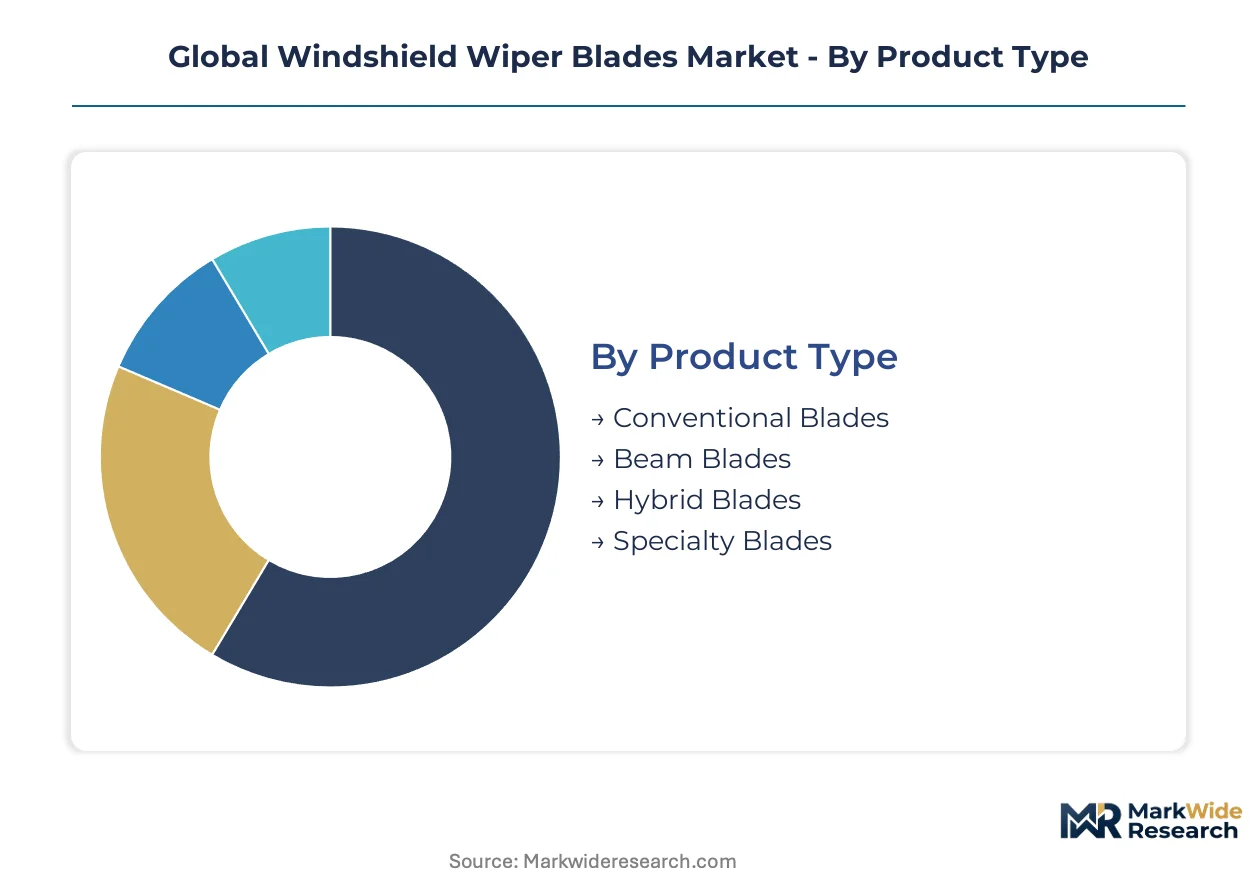
Product differentiation in wiper blade manufacturing tracks directly against vehicle specification tiers and climate exposure severity. Segmentation reveals where material science investments concentrate and which distribution channels capture replacement cycle economics.
Product Type:
Beam blade architecture eliminates exposed metal frames through integrated spring-steel spines, rewriting aerodynamic performance benchmarks across OEM specifications.
- Conventional Blades:Metal-frame bracket designs with articulated pressure points dominate emerging fleet replacement channels in India and Brazil where unit cost sensitivity overrides performance premiums. Volume concentration persists in commercial vehicle aftermarket networks.
- Beam Blades:Aerodynamic stability and ice-shedding performance have displaced conventional designs across German and Japanese OEM supply chains. Robert Bosch GmbH and Valeo SA anchor manufacturing around these specifications for European and Asian vehicle platforms.
- Hybrid Blades:Combines bracket durability with beam-style aerodynamics for mid-tier passenger vehicle segments.
- Specialty Blades:Configured for curved windshields and heavy-duty applications in mining and agricultural equipment.
Mature deployment sits with Conventional Blades. Newer deployment is concentrated in Beam Blades.
Vehicle Type:
Passenger vehicle replacement cycles drive aftermarket volume, while commercial specifications prioritize durability metrics over cost optimization.
- Passenger Cars:Beam blade adoption concentrates here as German and Japanese OEMs specify integrated spine designs for aerodynamic efficiency. ECE R48 wipe pattern mandates enforce shorter replacement cycles across European passenger fleets.
- SUVs:Larger curved glass surfaces demand specialized beam configurations with extended spine lengths. Northern Japanese prefectures sustain demand for halogenated polymer edges rated below minus forty degrees Celsius.
- Trucks:Heavy-duty bracket designs retain dominance where frame durability outweighs aerodynamic considerations.
- Commercial Vehicles:Fleet maintenance platforms in North American long-haul corridors now specify performance through telematics rather than visual inspection, favoring premium blade procurement.
Volume concentration remains with Passenger Cars. Specification intensity climbs fastest in Commercial Vehicles.
Material:
Silicone formulation advances are fragmenting competitive advantage around hydrophobic coating transfer and UV degradation resistance.
- Silicone:Hydrophobic coating deposition during wiping cycles extends functional blade life while commanding margin premiums. German and French OEMs are consolidating supplier qualifications around silicone-only portfolios under REACH polymer content pressures.
- Rubber:Natural rubber compounds face Thai and Indonesian latex supply disruptions that transmit directly to compounder cost structures. Saudi Arabian and Australian sun-belt markets remain underserved by standard formulations.
- Metal:Spring-steel spine fabrication for beam blades concentrates in German and Japanese tool-and-die clusters.
- Polymer:Halogenated compounds face phase-out timelines under REACH restrictions, forcing premature R&D redirection.
Cost-optimized deployment sits with Rubber. Premium specification deployment is concentrated in Silicone.
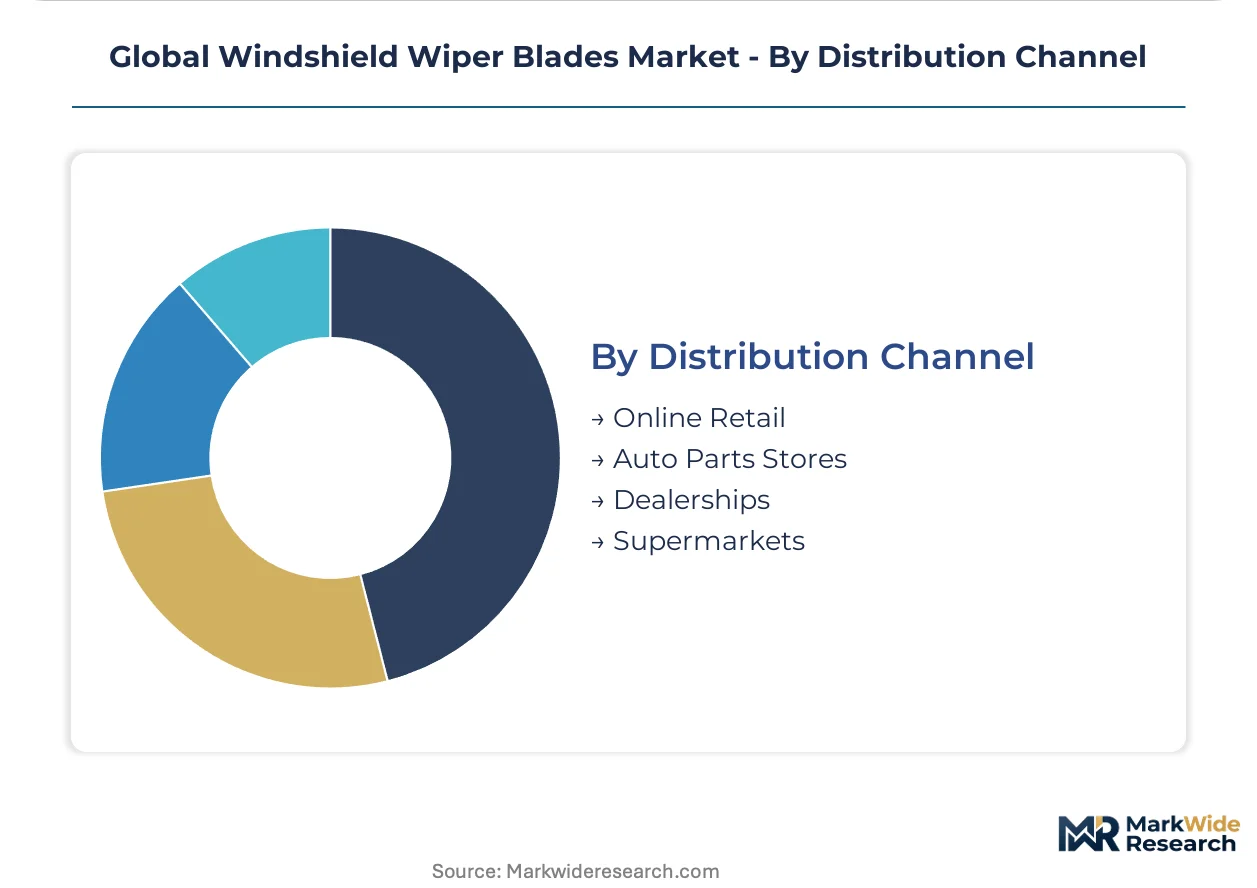
Distribution Channel:
Procurement authority is migrating from decentralized retail networks toward integrated fleet maintenance platforms with performance-based specifications.
- Auto Parts Stores:Private-label distribution networks span North American retail channels where Federal-Mogul LLC competes on volume scale. Bracket blade residual dominance in cost-optimized segments sustains this channel's relevance.
- Dealerships:OEM specification compliance and warranty integration anchor premium blade distribution. Direct supply relationships with French and German OEMs concentrate volume here.
- Online Retail:Digital channels bypass traditional distribution layers for price-transparent replacement purchases.
- Supermarkets:Emergency replacement demand and economy-tier products drive sporadic volume.
Traditional volume sits with Auto Parts Stores. Platform-integrated procurement is expanding fastest in Dealerships.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Thai and Indonesian latex plantations supply the natural rubber feedstock that underpins compounder operations across Asia-Pacific manufacturing platforms. German tool-and-die clusters fabricate precision spring-steel spines for beam blade architectures. Japanese OEM specification teams validate silicone-graphene hybrid compounds for winter-rated applications.
Germany
ECE R48 wipe pattern mandates enforce stricter optical clarity standards across passenger vehicle fleets. The KBA administers type-approval testing that shapes export qualification protocols for European OEM supply chains. Stuttgart and Wolfsburg anchor manufacturing concentration where Robert Bosch GmbH and Valeo SA operate integrated rubber compounding facilities.
Japan
Northern prefectures sustain demand for halogenated polymer edges rated below minus forty degrees Celsius. METI oversees JIS D 5705 performance benchmarks for wipe pattern coverage and noise thresholds. Nagoya and Tokyo-Yokohama clusters concentrate beam blade validation programs for domestic OEM specification teams.
United States
North American commercial vehicle operators consolidate procurement through integrated maintenance platforms linking Detroit to Dallas corridors. NHTSA Federal Motor Vehicle Safety Standard 104 governs wiping system field of view requirements across vehicle classifications. Michigan and Ohio retain metal-frame bracket production for cost-optimized aftermarket channels.
China
MIIT-administered GB 15085 revisions incorporate carbon intensity benchmarks for silicone production methods. Dual carbon goals reshape material certification costs and supply base geography across Yangtze River Delta manufacturing zones. Shanghai and Jiangsu province concentrate export-oriented blade assembly for Asian vehicle platforms.
Brazil
Emerging fleet replacement channels retain cost-optimized metal-frame designs for commercial vehicle aftermarket networks. ANVISA regulates polymer content for automotive components under Mercosur alignment pressures. São Paulo state anchors regional distribution hubs serving South American retail channels.
Global Windshield Wiper Blades Market Competitive Environment
Global majors compete with regional champions across material science and distribution reach, producing a tiered structure where integrated compounders face pressure from specialized metal-forming specialists. Three archetypes dominate: European integrated rubber-and-metal fabricators, Japanese precision-component specialists, and North American aftermarket distributors. Consolidation moves center on supplier qualification consolidation around silicone-only portfolios and direct-to-fleet digital channel bypass.
Among European integrated fabricators, Robert Bosch GmbH and Valeo SA occupy positions exemplifying the rubber-compounding-plus-metal-forming archetype. Federal-Mogul LLC represents the North American aftermarket distribution model. These three entities anchor competitive positioning across distinct value-chain segments without overlapping strategic emphasis.
| Leading Market Players |
|---|
| Trico Products Corporation |
| Federal-Mogul LLC |
| Robert Bosch GmbH |
| PIAA Corporation |
| Mitsuba Corporation |
| Valeo SA |
| HELLA GmbH & Co. KGaA |
| The Goodyear Tire & Rubber Company |
| Denso Corporation |
| Others |
Value Chain & Pricing Dynamics
Family-owned mid-cap compounders across Thailand and Indonesia anchor natural rubber supply, translating plantation ownership into feedstock cost discipline that shields them from spot-market volatility while constraining pricing flexibility for downstream metal-forming specialists in Germany and Japan.
Pricing Analysis
Warranty bundling separates OEM contract tiers from aftermarket unbundled transactions, with German and Japanese automakers specifying performance guarantees that absorb replacement cost risk. Three-tier pricing structure across premium silicone, standard natural rubber, and economy halogenated compounds tracks certification grade and volume scale. Pricing pressure stems from REACH polymer content restrictions forcing premature compound reformulation. Fleet operators in North American long-haul corridors exhibit lowest price sensitivity, while retail channels in Brazil and India retain acute cost optimization behavior.
Supply Chain Analysis
Dual-sourcing mandates from Robert Bosch GmbH and Valeo SA require Tier-2 compounders to maintain qualified backup facilities across multiple jurisdictions. Geographic supply concentration centers on Thailand and Indonesia for natural rubber latex, Germany and Japan for spring-steel spine fabrication, and China for carbon-intensive silicone processing. Raw material dependencies include Thai plantation latex, German tool-and-die capacity, and MIIT-certified carbon benchmarks. Single-source vulnerability concentrates in precision metal forming clusters. Distribution runs through integrated fleet maintenance platforms bypassing traditional retail layers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Spring-steel spine fabrication capacity constraints in German and Japanese tool-and-die clusters prop pricing power for integrated compounders, limiting volume expansion for natural rubber-dependent competitors.
For Market Incumbents: Anticipate REACH polymer content phase-outs by consolidating supplier qualifications around silicone-only portfolios before halogenated compound deadlines. Backward integration into Thai plantation networks secures feedstock cost visibility against latex supply disruptions. Channel control through direct-to-fleet digital platforms bypasses retail margin compression.
For New Entrants and Emerging Players: Launch via specialty UV-resistant product lines targeting Saudi Arabian and Australian sun-belt markets underserved by standard natural rubber formulations. White-space concentration sits with graphene-silicone hybrid compounds for winter-rated applications. Go-to-market leverage accelerates through Japanese OEM specification team relationships.
For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-volume compounders facing REACH reformulation cost burdens in France and Germany. Long-term viability hinges on carbon-intensity-compliant silicone production methods aligned with China dual carbon goals. Watch MIIT GB 15085 revision timelines as inflection signal for supply base geography reshaping.
| Strategic Initiative | Industry Significance |
|---|---|
| Silicone-Only Portfolio Consolidation | German and French OEMs are disqualifying halogenated compound suppliers under REACH pressure. |
| Thai Plantation Network Integration | Upstream latex sourcing insulates compounders from Indonesian supply disruption transmission. |
| Beam Blade Spring-Steel Capacity Expansion | Precision metal forming investments in Nagoya clusters relieve German tool-and-die bottlenecks. |
| Fleet Maintenance Platform Partnership | Telematics-integrated procurement in Detroit-Dallas corridors overrides unit price sensitivity. |
| Graphene-Silicone Hybrid Validation | Japanese OEM specification teams accelerate winter-rated compound development cycles. |
Study Parameters
Multi-period observation of replacement cycle frequency, OEM specification migration, and raw material cost transmission anchored the trend analysis, supplemented by interviews with Tier-1 supplier procurement officers, aftermarket distribution channel managers, rubber compounding technical directors, and fleet maintenance platform operators. Secondary validation drew from vehicle production databases, customs trade records for natural rubber and silicone feedstocks, NHTSA FMVSS 104 compliance filings, ECE R48 type-approval registries, and MIIT GB 15085 certification announcements. Bottom-up volume modeling triangulated against top-down OEM specification penetration estimates.
Segment-weighting across product architecture, material formulation, vehicle classification, and distribution channel governed value allocation throughout the projection horizon. Modeled dimensions included beam versus conventional versus hybrid blade configurations, silicone versus natural rubber versus halogenated polymer compounds, passenger car versus commercial vehicle replacement cycles, and OEM direct supply versus aftermarket retail versus fleet platform procurement. CAGRs derived from regression analysis of historical specification adoption curves and regulatory mandate implementation timelines. Industry-specific forecast inputs incorporated ECE R48 wipe pattern compliance deadlines and REACH polymer restriction phase-out schedules.
Natural rubber supply disruption, REACH reformulation cost acceleration, and MIIT carbon intensity benchmark revision are the dominant revision risks to volume and value projections. Deviation in Thai or Indonesian plantation output would shift compounder cost structures and pricing power distribution materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Automotive Rear Spoiler Market
Automotive Parts
Global Car Engine Oil Market
Automotive Parts
Europe Automotive Engine Oils Market
Automotive Parts
Automotive Parts Magnesium Die Casting Market
Automotive Parts
Automotive Adaptive Engine Mounts Market
Automotive Parts
Germany Passenger Vehicles Lubricants Market
Automotive Parts
Africa Automotive Engine Oils Market
Automotive Parts
North America Automotive Parts Magnesium Die Casting Market
Automotive Parts
Industrial V Belt Market
Automotive Parts
Automotive Trim Part Market
Automotive Parts
Australia Automotive Airfilters Market
Automotive Parts
Tappet Market
Automotive Parts
Mexico Automotive Parts Zinc Die Casting Market
Automotive Parts
Two-Wheeler Lubricants Market
Automotive Parts
Car Phone Holder Market
Automotive Parts
Norway Passenger Vehicles Lubricants Market