
 Brass Synchronizer Ring Market | 2026-2036
Brass Synchronizer Ring Market Size, Share, and Industry Trends Forecast 2026-2036
Brass Synchronizer Ring Market Insights
Capital-intensity divergence between integrated brass foundries and precision machining specialists is bifurcating competitive returns in this market. Diehl Metall leverages captive copper alloy smelting and hot-forging capacity to sustain margin control across European OEM supply chains. Schaeffler competes through automated synchronizer assembly integration, while Luzhou Changjiang anchors cost positioning via proximity to China's transmission manufacturing belt.
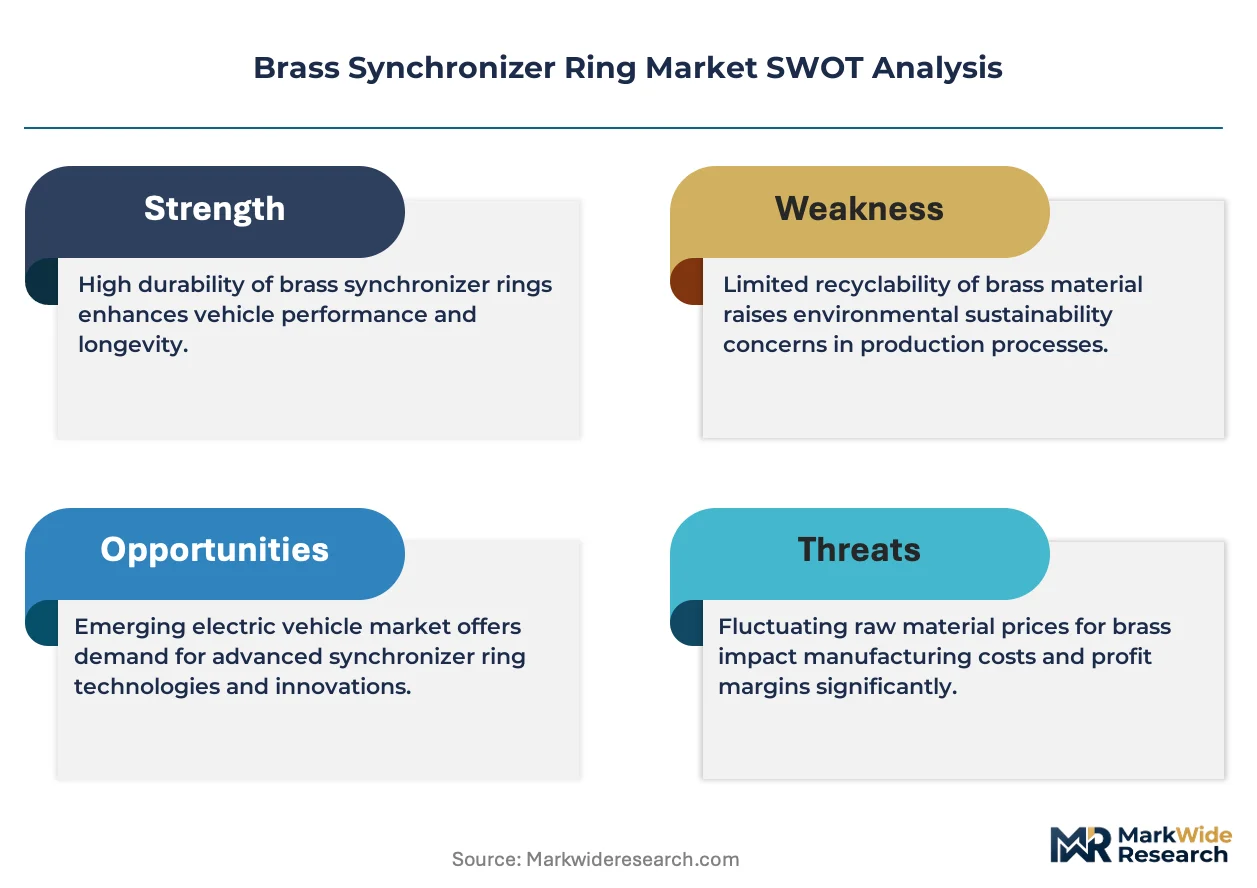
A brass synchronizer ring is a friction-wear component machined from copper-zinc alloys with tin or phosphorus additions, typically achieving 58-62 HRC surface hardness after heat treatment, and its primary function is to match rotational speeds between meshing gears during manual transmission shifts. Standard Synchronizer Rings occupy the mature volume base in passenger car applications where cost minimization dominates supplier selection, while High-Performance Rings capture expanding margin pools as OEMs specify tighter tolerances for synchronized dual-clutch manual architectures. Heavy-Duty Rings lead growth in agricultural and construction equipment segments where abrasive operating environments accelerate replacement cycles and command premium material grades.
The EPA regulates copper alloy machining effluents under Clean Water Act discharge limits, while REACH restricts lead content in brass alloys sold across European aftermarket channels, and India's BIS mandates material certification for automotive brass components under AIS standards. These frameworks elevate compliance costs for leaded brass producers while creating certification premiums for phosphor bronze and nickel silver alternatives. Stakeholders must monitor alloy substitution timelines and regional certification divergence to align capacity investments with shifting specification requirements.
Market Dynamics
Manual transmission architecture is bifurcating into torque-dense heavy-duty platforms and precision-synchronized light-duty systems, forcing brass alloy suppliers to dual-track material certification pathways across incompatible specification regimes.
Growth Catalysts
- Dual-clutch manual proliferation:Synchronized dual-clutch architectures in European passenger vehicles demand tighter-tolerance phosphor bronze rings, expanding addressable premium-grade volumes.
- India's PLI scheme for auto components:Domestic value-addition incentives are accelerating local forging capacity for heavy-duty rings serving commercial vehicle OEMs.
- Precision forging diffusion:Closed-die hot forging with real-time temperature control is reducing machining allowances and scrap rates in Sichuan manufacturing clusters.
Market Restraints
- Copper-zinc ingot volatility:Brass mills face margin compression when London Metal Exchange copper prices spike without corresponding ring price escalation clauses.
- REACH lead-content thresholds:ECHA restrictions on leaded brass alloys in European aftermarket channels force costly alloy reformulation or market exit.
- Single-source forging concentration:China's dominance in precision-forged ring supply creates geographic risk for tier-1 transmission assemblers seeking dual-source qualification.
Strategic Opportunities
- Brazilian heavy-duty OEM expansion:Agricultural and construction equipment manufacturers in São Paulo state are localizing transmission sourcing, opening import substitution windows for certified ring suppliers.
- Phosphor bronze substitution:Lead-free alloy penetration in EU aftermarket channels creates first-mover certification premiums for compliant producers.
- Direct-to-remanufacturer channels:Transmission rebuild specialists are bypassing traditional distribution tiers, enabling margin capture through certified aftermarket ring programs.
Industry Challenges
- Heat treatment precision staffing:Achieving 58-62 HRC surface hardness consistency requires scarce metallurgical technicians capable of salt-bath and induction process control.
- BIS-AIS certification timelines:India's automotive material standards impose multi-quarter approval cycles that delay market entry for new alloy formulations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Brass Synchronizer Ring Market |
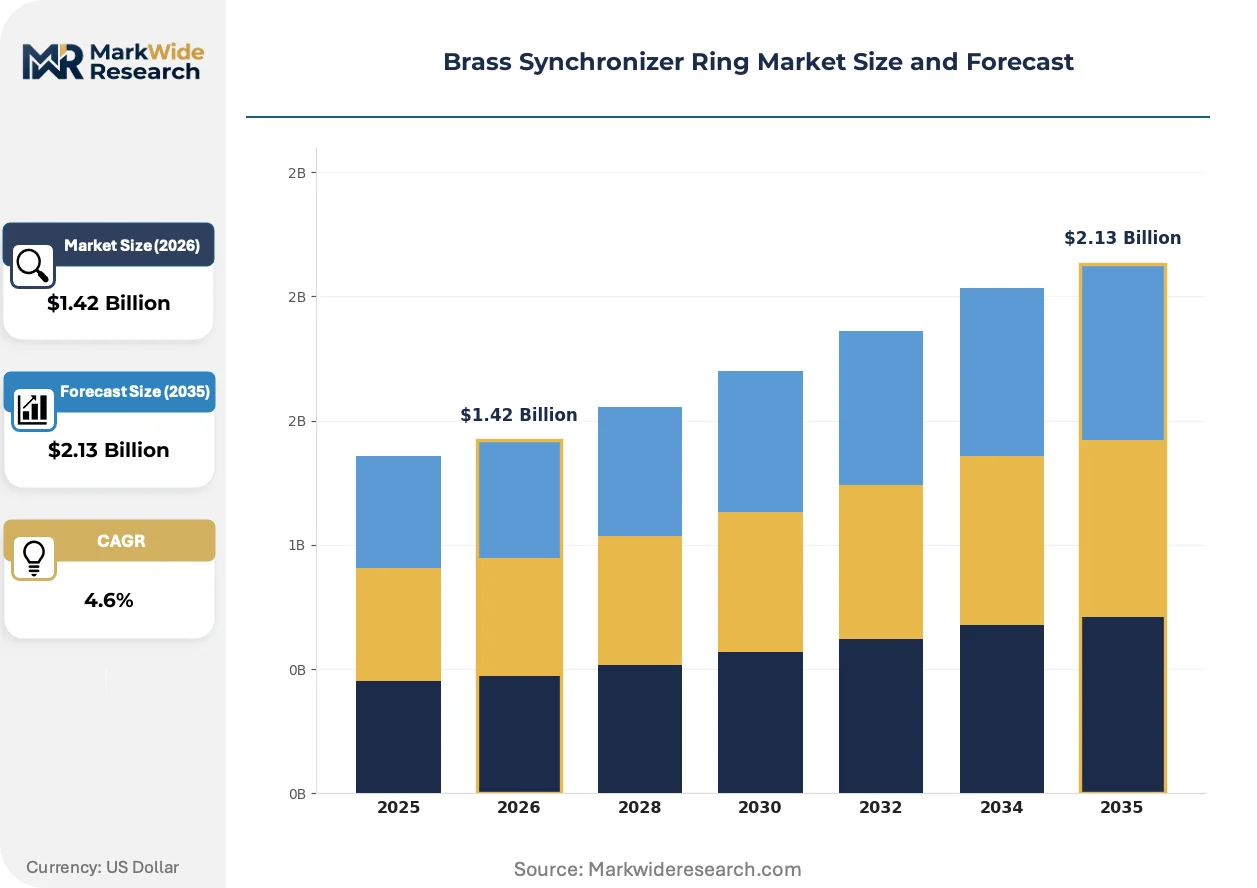
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.13 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Synchronizer Rings, High-Performance Rings, Heavy-Duty Rings, Custom-Fit Rings Material Grade: Standard Brass, Leaded Brass, Phosphor Bronze, Aluminum Bronze, Nickel Silver Application: Manual Transmissions, Agricultural Machinery, Construction Equipment, Commercial Vehicles, Marine Transmissions End User: OEMs, Aftermarket Suppliers, Transmission Repair Shops, Fleet Maintenance Providers |
| Companies Covered | Diehl Metall, SKF, Schaeffler, Euroricambi Group, Oerlikon, Luzhou Changjiang Machinery Co. Ltd, ETR Co. Ltd, JIUNMU Enterprise Co. Ltd, Yugal Precision, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Brass Synchronizer Ring Market Trends and Innovations
Material science advances and regulatory chemistry restrictions are converging to displace century-old leaded brass formulations while precision manufacturing techniques compress tolerance bands for next-generation transmission architectures.
Phosphor bronze alloys with tin content above five percent are replacing leaded brass in friction-wear applications requiring equivalent machinability without toxic metal content. European transmission OEMs have accelerated qualification timelines for these formulations since REACH amendments tightened aftermarket restrictions. The technology is miniaturizing allowable dimensional tolerances from fifty microns to twenty-five microns in synchronized dual-clutch hubs.
ECHA's REACH restrictions on lead content in brass alloys sold across European aftermarket channels have triggered wholesale material grade transitions. Producers face stranded inventory risk in leaded brass forging capacity while phosphor bronze alternatives command fifteen to twenty percent raw material premiums. Aftermarket distributors in Germany and France are prioritizing certified lead-free ring suppliers to preempt enforcement actions.
Remanufactured transmission specialists are consolidating procurement through direct mill relationships rather than traditional tiered distribution networks. Independent rebuilders in North America and Western Europe now specify certified ring batches with full metallurgical traceability, displacing anonymous bulk aftermarket supply. This pattern is most visible in California and Texas, where environmental liability concerns amplify documentation requirements for rebuilt commercial vehicle transmissions.
Brass Synchronizer Ring Market Segmentation
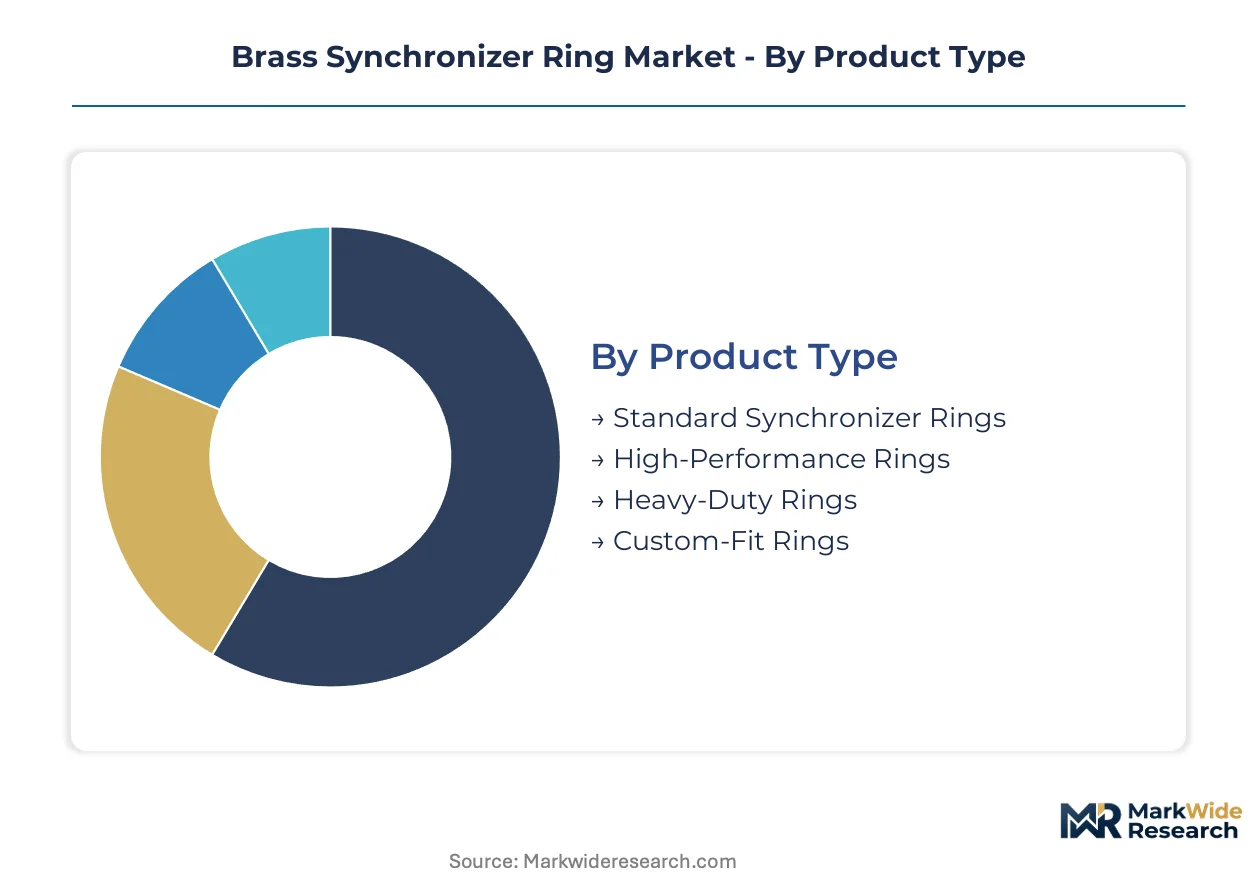
Brass synchronizer ring procurement patterns diverge sharply across product tiers, material grades, and end-use channels. Each segment carries distinct certification requirements, forging complexity, and geographic sourcing preferences that reshape supplier competitive dynamics.
Product Type:
Domestic production clusters in China and India supply Standard and Heavy-Duty variants for regional OEMs, while High-Performance and Custom-Fit rings flow through specialized export channels serving European and North American transmission assemblers.
- Standard Synchronizer Rings:These copper-zinc alloy rings with standard tin content achieve baseline friction coefficients for passenger car manual transmissions. Demand concentrates in India's Pune and Chennai manufacturing corridors where Maruti Suzuki and Tata Motors source cost-optimized rings under PLI scheme incentives. Price pressure from integrated foundries limits margin expansion for standalone machining specialists.
- High-Performance Rings:Precision-forged phosphor bronze formulations with sub-25 micron tolerances serve synchronized dual-clutch architectures. European OEMs in Germany and the Czech Republic specify these rings for performance passenger vehicles, driving qualification premiums for certified suppliers. REACH compliance mandates accelerate substitution away from legacy leaded brass in this tier.
- Heavy-Duty Rings:Thicker cross-section designs with nickel silver or aluminum bronze alloys withstand abrasive environments in commercial vehicle and off-highway applications. Brazilian OEMs in São Paulo state are expanding local forging partnerships to reduce import dependency for agricultural equipment transmissions.
- Custom-Fit Rings:Application-specific geometries for remanufactured transmissions and specialty marine gearboxes. North American rebuilders in Texas and California specify batch-traceable rings with full metallurgical documentation to satisfy environmental liability protocols.
Standard Synchronizer Rings hold the largest share; momentum sits with Heavy-Duty Rings as commercial vehicle OEMs in emerging markets localize sourcing.
Material Grade:
Cost tiers separate commodity brass mills from premium alloy specialists, with regulatory chemistry restrictions forcing wholesale grade transitions in European aftermarket channels.
- Standard Brass:Conventional copper-zinc alloys without specialized additives dominate volume production for economy passenger car segments. Indian BIS certification requirements under AIS standards constrain unqualified imports, protecting domestic Sichuan and Zhejiang suppliers.
- Leaded Brass:Legacy formulations with lead content above REACH thresholds face stranded inventory risk across EU distribution networks. Remaining demand concentrates in non-regulated export markets and specific industrial machinery exemptions.
- Phosphor Bronze:Tin-rich alloys above five percent content deliver equivalent machinability to leaded brass without toxic metal content. German and French aftermarket distributors prioritize certified phosphor bronze suppliers to preempt ECHA enforcement actions, creating fifteen to twenty percent raw material premiums.
- Aluminum Bronze:High-strength copper-aluminum alloys for extreme wear environments in mining and construction equipment transmissions. Australian mining equipment OEMs specify these grades for desert operating conditions.
- Nickel Silver:Copper-nickel-zinc formulations offering superior corrosion resistance for marine transmission applications. Japanese shipbuilders source nickel silver rings through specialized Osaka-based forging houses.
Phosphor Bronze is climbing the fastest as REACH amendments tighten; Standard Brass retains volume dominance in cost-sensitive emerging markets.
Application:
Customer type splits the market between high-volume OEM procurement with long-term contracts and fragmented aftermarket demand requiring flexible batch sizing.
- Manual Transmissions:Synchronized gearboxes in passenger cars and light commercial vehicles consume the majority of precision-forged ring output. European dual-clutch architectures demand tighter tolerances than legacy single-cone designs.
- Agricultural Machinery:Tractor and combine harvester transmissions operate in dust-laden environments requiring hardened surface treatments. Brazilian equipment manufacturers in Mato Grosso are expanding domestic ring forging capacity.
- Construction Equipment:Excavator and loader transmissions subject rings to shock loads and contamination. South Korean OEMs source heavy-duty aluminum bronze rings through certified suppliers in Busan.
- Commercial Vehicles:Heavy truck and bus transmissions prioritize durability over shift refinement. Indian commercial vehicle OEMs in Pithampur and Jamshedpur specify locally forged rings under domestic content requirements.
- Marine Transmissions:Saltwater corrosion resistance drives nickel silver specification. Italian yacht builders in Viareggio commission custom-fit rings with full material traceability.
Manual Transmissions anchor procurement volumes; Agricultural Machinery shows steepest expansion trajectory as Brazilian and Indian farm equipment production scales.
End User:
Supply chain configuration separates integrated transmission assemblers from fragmented service channels, with certification requirements varying dramatically across tiers.
- OEMs:Volume-contracted supply to transmission manufacturers and vehicle assemblers with multi-year qualification cycles. Schaeffler and Diehl Metall compete through automated assembly integration and captive alloy smelting respectively.
- Aftermarket Suppliers:Distributors serving independent repair networks with bulk inventory. German and French distributors face REACH compliance documentation burdens for leaded brass inventory.
- Transmission Repair Shops:Small-batch procurement with flexible specification tolerance. North American rebuilders in California require environmental liability documentation exceeding European standards.
- Fleet Maintenance Providers:Centralized procurement for commercial vehicle operators with predictive replacement scheduling. Brazilian sugarcane haulage fleets in São Paulo state negotiate direct mill relationships for heavy-duty ring supply.
OEMs command the largest procurement volumes; Fleet Maintenance Providers are gaining share fastest as predictive maintenance programs consolidate ring purchasing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across procurement geographies. Indian commercial vehicle OEMs prioritize cost-optimized standard rings under domestic content mandates, while European dual-clutch transmission assemblers absorb premium phosphor bronze pricing to satisfy REACH compliance. Brazilian agricultural equipment manufacturers occupy a middle tier, balancing durability requirements against import substitution economics.
China
Sichuan and Zhejiang manufacturing clusters supply precision-forged rings to domestic transmission OEMs and export aftermarket channels. MIIT industrial upgrading directives accelerate closed-die hot forging adoption with real-time temperature control systems. Luzhou Changjiang anchors cost positioning through proximity to the Yangtze River Delta transmission belt, serving both local OEMs and remanufacturer export demand.
Germany
Dual-clutch manual architectures from Stuttgart and Munich transmission plants specify sub-25 micron tolerance phosphor bronze rings. ECHA REACH restrictions on leaded brass alloys force wholesale material grade transitions across aftermarket distribution networks. Diehl Metall leverages captive copper alloy smelting in Stolberg to sustain margin control across European OEM supply chains.
India
Commercial vehicle OEMs in Pune and Chennai expand procurement of heavy-duty rings as manual transmission production shifts toward higher torque-density designs. BIS certification requirements under AIS standards constrain unqualified imports and protect domestic forging capacity. The PLI scheme for auto components accelerates local value-addition incentives for precision machining specialists in Tamil Nadu.
Brazil
Agricultural and construction equipment manufacturers in São Paulo state localize transmission sourcing to reduce import dependency for sugarcane haulage and mining applications. ANVISA environmental regulations align gradually with REACH chemistry restrictions, creating compliance preparation windows for lead-free alloy suppliers. Mato Grosso equipment OEMs expand domestic ring forging partnerships for tractor and combine harvester transmissions.
United States
Transmission rebuild specialists in Texas and California consolidate procurement through direct mill relationships, bypassing traditional distribution tiers. EPA Clean Water Act discharge limits regulate copper alloy machining effluents from brass foundries in the Midwest. Remanufactured transmission demand concentrates in Houston and Los Angeles, where environmental liability documentation requirements exceed European standards for commercial vehicle rebuilds.
Brass Synchronizer Ring Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes in this bifurcated market. Integrated brass foundries with captive copper alloy smelting sustain margin control through backward integration, while precision machining specialists compete on tolerance achievement and heat treatment consistency. Three archetypes dominate: European metallurgical conglomerates with captive smelting, Asian forging specialists with geographic proximity to transmission clusters, and diversified automotive suppliers with automated synchronizer assembly integration. Competitive moves center on alloy reformulation for REACH compliance and precision forging capacity expansion in Sichuan and São Paulo state.
Among European metallurgical conglomerates, Diehl Metall exemplifies the captive smelting archetype through its Stolberg copper alloy operations. Schaeffler represents the diversified automotive supplier model with automated transmission assembly integration. Luzhou Changjiang occupies the Asian forging specialist position, anchoring cost competitiveness through Sichuan basin manufacturing proximity. These three players illustrate the structural divergence between integrated metallurgy and precision machining business models.
| Leading Market Players |
|---|
| Diehl Metall |
| SKF |
| Schaeffler |
| Euroricambi Group |
| Oerlikon |
| Luzhou Changjiang Machinery Co. Ltd |
| ETR Co. Ltd |
| JIUNMU Enterprise Co. Ltd |
| Yugal Precision |
| Others |
Pricing and Supply Chain Analysis
India's BIS-AIS certification requirements for automotive brass components simultaneously gate supplier qualification and stratify price tiers, forcing unqualified imports into lower-margin aftermarket channels while certified domestic producers capture OEM premiums. This regulatory architecture concentrates pricing power among phosphor bronze specialists who have absorbed REACH compliance costs, leaving standard brass mills to compete on volume discounts in unregulated export markets.
Pricing Analysis
Aftermarket parts revenue, particularly certified ring batches for remanufactured transmissions, drives lifetime value capture for suppliers with metallurgical traceability capabilities. Three-tier pricing structure across phosphor bronze premium, standard brass mid-tier, and economy leaded brass legacy products separates REACH-compliant European channels from cost-sensitive Indian and Brazilian procurement. Cost compression in standard brass segments is intensifying because integrated foundries in Sichuan and Zhejiang exploit captive copper alloy smelting to undercut standalone machining specialists. Fleet maintenance providers in São Paulo state exhibit highest price sensitivity due to predictive replacement scheduling, while German dual-clutch OEMs absorb premium phosphor bronze pricing to satisfy ECHA enforcement timelines.
Supply Chain Analysis
China and India anchor precision-forged ring production, with Sichuan and Zhejiang manufacturing clusters feeding domestic transmission OEMs and export aftermarket channels. Raw material dependencies center on London Metal Exchange copper-zinc ingots, tin additives for phosphor bronze formulations, and nickel for corrosion-resistant marine grades. Single-source forging concentration in China's transmission manufacturing belt creates geographic vulnerability for tier-1 assemblers seeking dual-source qualification. Distribution runs through transmission rebuild specialists in Texas and California who consolidate procurement through direct mill relationships, bypassing traditional tiered distribution networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scarce metallurgical technicians capable of salt-bath and induction heat treatment process control constrain capacity expansion across all material grades, making technician training pipelines and automated temperature control systems critical competitive differentiators.
For Market Incumbents: Consolidate backward integration into captive copper alloy smelting to defend margin compression from London Metal Exchange price volatility, while accelerating phosphor bronze certification investments to preempt stranded leaded brass inventory across EU aftermarket channels. Diehl Metall's Stolberg operations exemplify this dual-track defense against both commodity cost spikes and REACH-driven material grade transitions. For New Entrants and Emerging Players: BIS-AIS fast-track certification for phosphor bronze formulations opens white-space penetration in India's commercial vehicle OEM supply chains, where PLI scheme incentives protect domestic value-addition. São Paulo state agricultural equipment manufacturers represent the most penetrable geography due to import substitution mandates and ANVISA regulatory alignment preparation windows. Direct-to-remanufacturer channel partnerships in California and Texas enable margin capture through certified batch-traceable ring programs. For Investors and Strategic Acquirers: REACH amendment enforcement reshapes the acquisition landscape toward phosphor bronze-capable forging assets with existing ECHA compliance documentation. Long-term viability across the analysis window favors integrated metallurgical conglomerates with captive alloy smelting over standalone machining specialists exposed to copper-zinc ingot volatility. The signal to watch is BIS-AIS certification timeline compression in Tamil Nadu, which would indicate regulatory inflection accelerating domestic Indian capacity consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Phosphor Bronze Alloy Qualification | ECHA REACH compliance secures European aftermarket channel access against leaded brass phase-out. |
| Closed-Die Hot Forging Expansion | Real-time temperature control systems in Sichuan clusters reduce machining allowances and scrap rates. |
| Direct Remanufacturer Channel Development | Texas and California rebuilders demand full metallurgical traceability exceeding traditional distribution tiers. |
| Captive Copper Alloy Smelting Integration | Stolberg and Yangtze River Delta smelting operations insulate margin control from LME price spikes. |
| Metallurgical Technician Training Pipeline | Salt-bath and induction process control expertise scarcity constrains 58-62 HRC hardness consistency achievement. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of customs trade data, SEC filings from listed automotive suppliers, MIIT industrial upgrading directives, and ECHA regulatory amendments. Interviews with transmission OEM procurement directors, brass foundry plant managers, aftermarket distributor category buyers, and metallurgical R&D specialists informed demand segmentation and pricing dynamics. Bottom-up volume estimates from Sichuan and Zhejiang production clusters triangulate against top-down OEM transmission assembly forecasts.
Segmentation dimensions modeled include product type tier, material grade chemistry, end-use application intensity, and geographic regulatory cluster across the projection horizon. CAGRs derive from production capacity expansion timelines, alloy substitution velocity under REACH enforcement, and commercial vehicle manual transmission platform longevity assumptions. Industry-specific forecast inputs incorporate BIS-AIS certification queue lengths and closed-die hot forging adoption rates in emerging manufacturing corridors.
Decision-makers should treat outputs as directional under sustained manual transmission production in commercial vehicles and gradual REACH compliance acceleration; material deviation in electric vehicle penetration or ECHA enforcement intensity would warrant model refresh. Recalibration cycles align with material shifts in copper-zinc ingot pricing volatility and phosphor bronze raw material premium stabilization.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Automotive Air Flow Meter Market
Automotive Parts
Europe Automotive Parts Die Casting Market
Automotive Parts
Europe Commercial Vehicles Lubricants Market
Automotive Parts
Nigeria Automotive Engine Oils Market
Automotive Parts
Automotive Brake by Wire Pedal Simulator Market
Automotive Parts
Automotive Oil and Air Filters Market
Automotive Parts
Germany Automotive Hydraulic Actuators Market
Automotive Parts
Global Very Narrow Aisle Trucks (VNA Truck) Market
Automotive Parts
Global EV Speed Reducer Market
Automotive Parts
Global Automotive Cup Holder Market
Automotive Parts
Automotive Electric Drive Axle Market
Automotive Parts
Automotive Tire Molds Market
Automotive Parts
Automatic Gearbox Valves Market
Automotive Parts
France Commercial Vehicles Lubricants Market
Automotive Parts
Automotive Parts Zinc Die Casting Market
Automotive Parts
Car Rack Market