
 Oil Catch Cans Market | 2026-2036
Oil Catch Cans Market Size, Share, and Industry Trends Forecast 2026-2036
Oil Catch Cans Market Analytics
Aluminum is recalibrating product economics across the oil catch cans category as manufacturers abandon heavier steel housings to reduce mass and improve thermal dissipation. Mishimoto leverages vertical integration from billet sourcing to anodized finishing, sustaining margin control across its performance cooling portfolio. Moroso Performance Products anchors its position through deep specialization in racing-derived crankcase management systems, while Radium Engineering differentiates via precision CNC machining and application-specific bracketry for forced-induction platforms.
Oil catch cans are closed-volume separators installed in positive crankcase ventilation circuits, typically fabricated from 6061-T6 aluminum with internal baffle stacks or mesh media designed to condense oil vapors before they re-enter intake tracts. The device protects intercoolers, valves, and combustion chambers from carbon deposit accumulation in turbocharged and high-compression engines. Aluminum product types command the dominant share of value owing to fabrication flexibility and aftermarket aesthetic preferences, while performance vehicles represent the fastest-expanding vehicle type segment as track-day participation and street-driven power builds proliferate. Composite variants occupy a nascent tier where weight-sensitive motorsport applications justify premium pricing over conventional metal constructions.
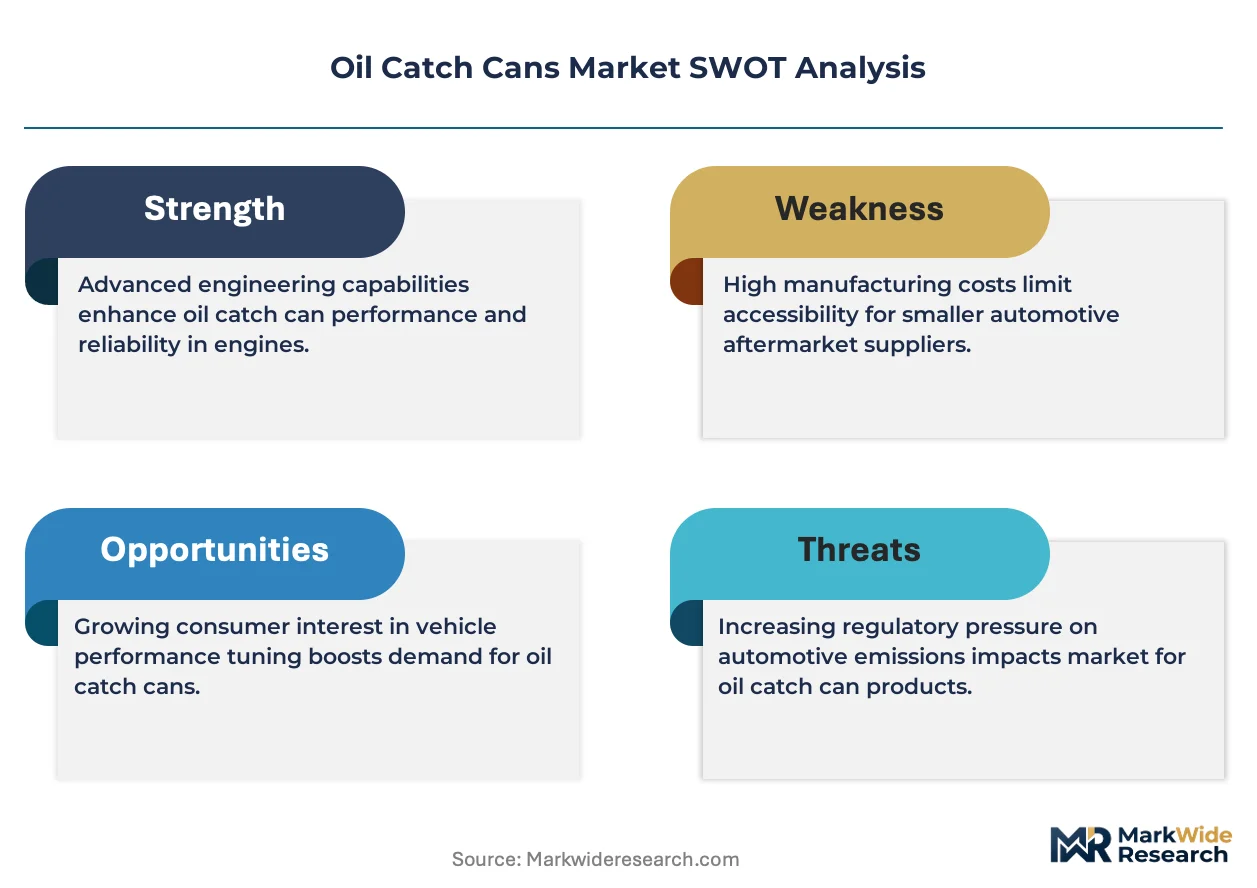
EPA tailpipe and evaporative emissions standards shape product legality for street-driven vehicles across the United States, while CARB executive orders determine market access for California-registered automobiles. SEMA works to preserve modification rights through federal regulatory engagement, directly influencing the addressable base for aftermarket catch can suppliers. Stakeholders must monitor state-level preemption battles and evolving EPA enforcement priorities to anticipate distribution restrictions and certification burdens that could reshape channel economics.
Market Dynamics
EPA crankcase ventilation enforcement and CARB certification mandates are compressing product development timelines while simultaneously expanding the addressable base for compliant aftermarket suppliers serving modified street vehicles.
Growth Catalysts
- Forced-Induction Proliferation:Turbocharger factory fitment rates on passenger vehicles are elevating baseline demand for crankcase vapor management hardware across OEM and aftermarket channels.
- EPA Emissions Enforcement:Heightened scrutiny of modified vehicle compliance is channeling enthusiast spending toward CARB-executive-order-certified catch can systems that preserve registration legality.
- Track-Day Participation:Amateur motorsport event volume is expanding the installed base of high-load engines requiring supplemental oil separation beyond factory PCV configurations.
Market Restraints
- Aluminum Price Volatility:6061-T6 billet and sheet input costs fluctuate with LME pricing, squeezing margin on anodized finished goods during commodity spikes.
- Regional Certification Fragmentation:CARB executive orders apply only to California-registered vehicles, forcing suppliers to maintain dual SKU streams for 50-state versus California-compliant distribution.
- Factory PCV System Improvement:OEM integrated oil separators on newer turbocharged engines reduce incremental aftermarket attachment rates for basic catch can configurations.
Strategic Opportunities
- Composite Material Adoption:Motorsport weight regulations are creating pull for carbon-fiber-reinforced polymer housings in professional racing categories willing to absorb premium pricing.
- Direct-to-Consumer Channel Expansion:E-commerce platforms are collapsing traditional wholesale markups, enabling specialized fabricators to capture full retail margin on application-specific bracketry.
- Emissions Testing Alignment:SEMA-backed federal legislative efforts to preserve modification rights could expand legal street use of closed-catch-can systems beyond current state-by-state patchwork.
Industry Challenges
- CNC Machining Talent Scarcity:Precision bracketry and custom bung fabrication require skilled machinists conversant with 5-axis programming for forced-induction plumbing integration.
- Certification Timeline Compression:CARB executive order pursuit demands extensive emissions testing documentation, stretching R&D resources for mid-tier suppliers lacking established regulatory affairs functions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Oil Catch Cans Market |
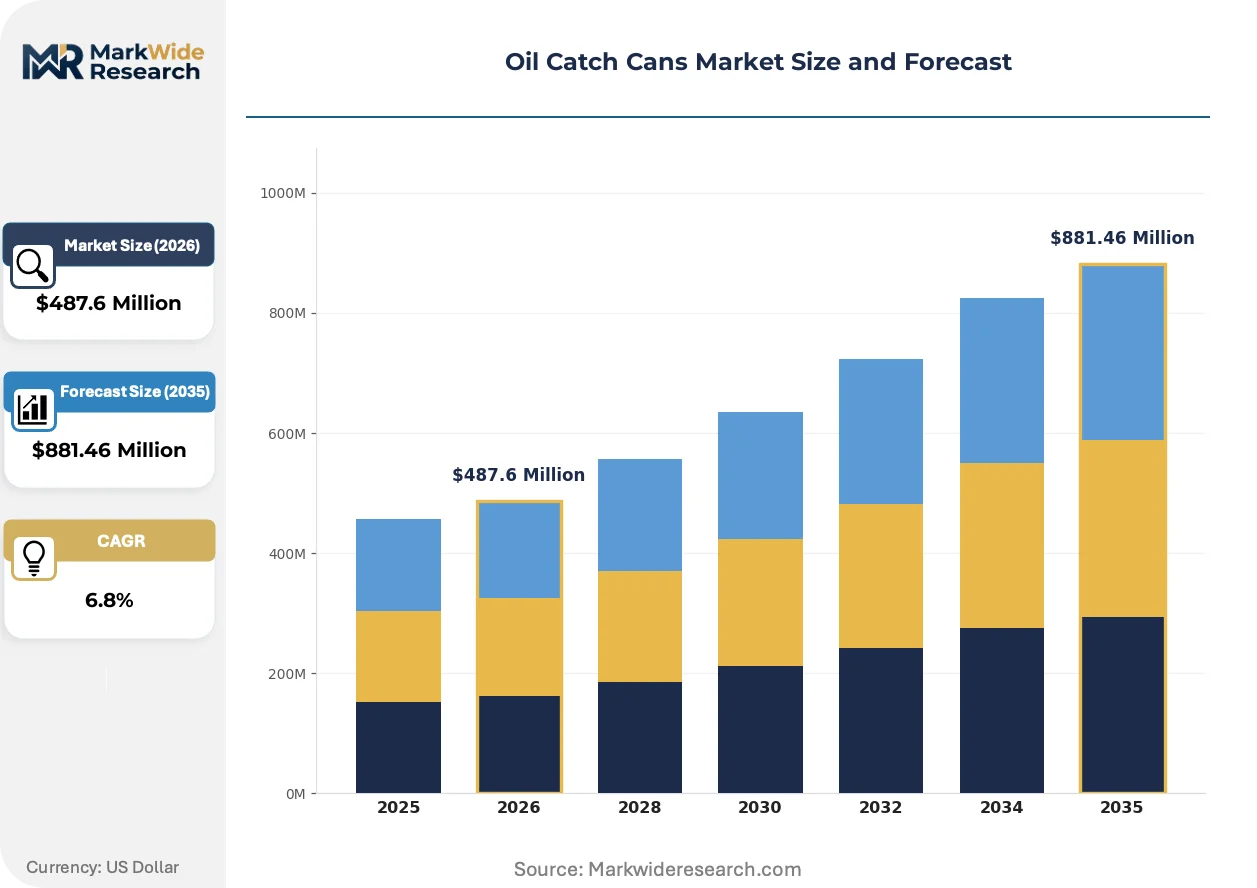
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $881.46 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Aluminum, Steel, Plastic, Composite Vehicle Type: Passenger Cars, Trucks, Motorcycles, Performance Vehicles Installation Type: Universal Fit, Custom Fit, Bolt-On, Integrated End User: DIY Enthusiasts, Automotive Professionals, Racing Teams, Workshops |
| Companies Covered | Mishimoto, Moroso Performance Products, Radium Engineering, Dorman Products, ECS Tuning, K&N Filters, Detroit Speed, GReddy, Cusco, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Oil Catch Cans Market Evolving Landscape
Product architecture is bifurcating between aesthetic-forward street configurations and function-optimized motorsport designs, with material selection and internal media geometry diverging accordingly.
Internal baffling automation is automating separation efficiency optimization across CNC-machined aluminum housings. Performance builders are specifying multi-chamber designs with integrated sight tubes at accelerating rates. This technology is automating the displacement of single-chamber catch cans in premium price tiers by delivering measurable flow restriction reduction and condensate retention improvement.
EPA tailpipe and evaporative emissions standards are tightening enforcement thresholds for modified vehicles nationwide. The regulatory consequence is elevating CARB certification from California niche to national distribution prerequisite for street-legal product lines. Domestic muscle car and sport compact modification communities are responding by consolidating purchase decisions around EO-numbered hardware despite 15-30% price premiums over uncertified alternatives.
Buyer research behavior has migrated almost entirely to video-centric platforms before purchase commitment. YouTube installation tutorials and dyno validation content are displacing traditional print media and forum recommendations as primary discovery channels. This shift concentrates influence among content creators with established forced-induction expertise, particularly within United States domestic and Japanese sport compact enthusiast segments.
Oil Catch Cans Market Segmentation
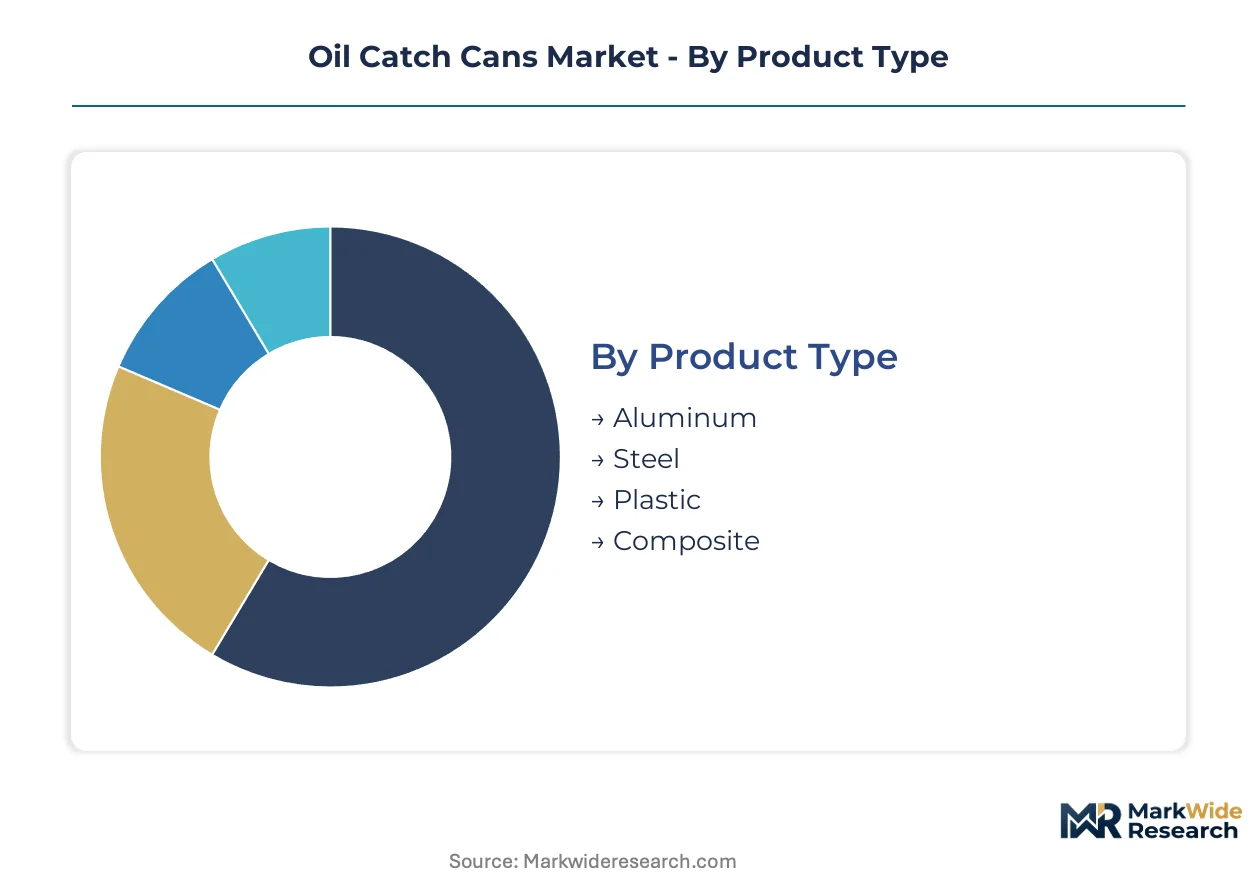
Segmentation in the oil catch cans market reveals how upgrade cycles differ across fabrication methods and vehicle applications. Replacement timing, performance requirements, and regulatory compliance create distinct demand profiles that suppliers must address through specialized product architectures.
Product Type:
Upgrade cycles vary by material durability and thermal management requirements, with enthusiasts replacing lower-grade housings as power levels escalate.
- Aluminum:Fabricated from 6061-T6 billet with anodized finishes, these housings deliver superior thermal dissipation and fabrication flexibility for custom baffle geometries. Demand concentrates among United States domestic muscle car builders seeking CARB-compliant street-legal configurations alongside aesthetic customization. The material's weldability supports integrated sight tubes and drain valves that simplify maintenance intervals.
- Steel:Heavier gauge constructions persist in budget-oriented universal-fit applications where cost sensitivity outweighs mass reduction priorities. Workshop installations in price-conscious segments favor these variants for fleet vehicles and daily-driver modifications where thermal performance is secondary to acquisition cost.
- Plastic:Injection-molded polymer housings serve entry-level universal-fit segments with molded-in baffle elements. DIY enthusiasts in sport compact communities select these for temporary installations before committing to premium metal upgrades.
- Composite:Carbon-fiber-reinforced polymer constructions target professional racing categories where FIA and sanctioning body weight regulations justify premium pricing. Motorsport fabricators in time-attack and endurance racing specify these for chassis-mounted installations.
Volume placements concentrate in Aluminum; the faster expansion belongs to Composite.
Vehicle Type:
Application requirements diverge sharply between daily-driven street vehicles and competition-purposed builds, driving differentiation in flow capacity and mounting hardware.
- Passenger Cars:Factory-turbocharged sedans and crossovers generate baseline demand for closed-catch-can systems that preserve warranty compliance. EPA enforcement priorities in the United States channel installations toward EO-certified configurations that avoid registration complications.
- Trucks:Heavy-duty diesel and gasoline pickups with elevated crankcase pressures from towing loads require high-volume separators with large-diameter inlet plumbing. Fleet operators and individual owners in Texas and the Southeast prioritize these for extended service intervals.
- Motorcycles:Compact packaging constraints necessitate miniature single-chamber designs with integrated mounting brackets. Track-day participants in amateur roadracing categories drive replacement cycles as engine modifications outpace factory PCV capacity.
- Performance Vehicles:Dedicated track cars and street-driven power builds demand multi-chamber designs with sight tubes and quick-drain provisions. Amateur motorsport event expansion across the United States accelerates attachment rates as builders seek carbon deposit mitigation beyond factory specifications.
Passenger Cars dominate current volume; Performance Vehicles are climbing the fastest as track-day participation proliferates.
Installation Type:
Distribution economics favor configurations that minimize labor content at the point of installation, with bolt-on and integrated designs capturing margin from professional channels.
- Universal Fit:Adjustable bracketry and flexible hose routing accommodate diverse engine bays without application-specific engineering. DIY enthusiasts favor these for initial experimentation before committing to permanent modifications.
- Custom Fit:Vehicle-specific bracketry and pre-cut hose lengths eliminate fabrication labor for professional installers. Automotive professionals in high-volume modification shops specify these to compress bay time and improve throughput.
- Bolt-On:Direct factory-mount replacement of PCV components using existing attachment points. United States sport compact communities prefer these for reversible installations that preserve resale value.
- Integrated:Welded or cast-in provisions that merge catch can function with adjacent cooling or breather hardware. Racing teams in professional categories specify these for weight reduction and packaging efficiency.
Custom Fit commands the highest channel margins; Bolt-On delivers the steepest volume trajectory through e-commerce direct-to-consumer expansion.
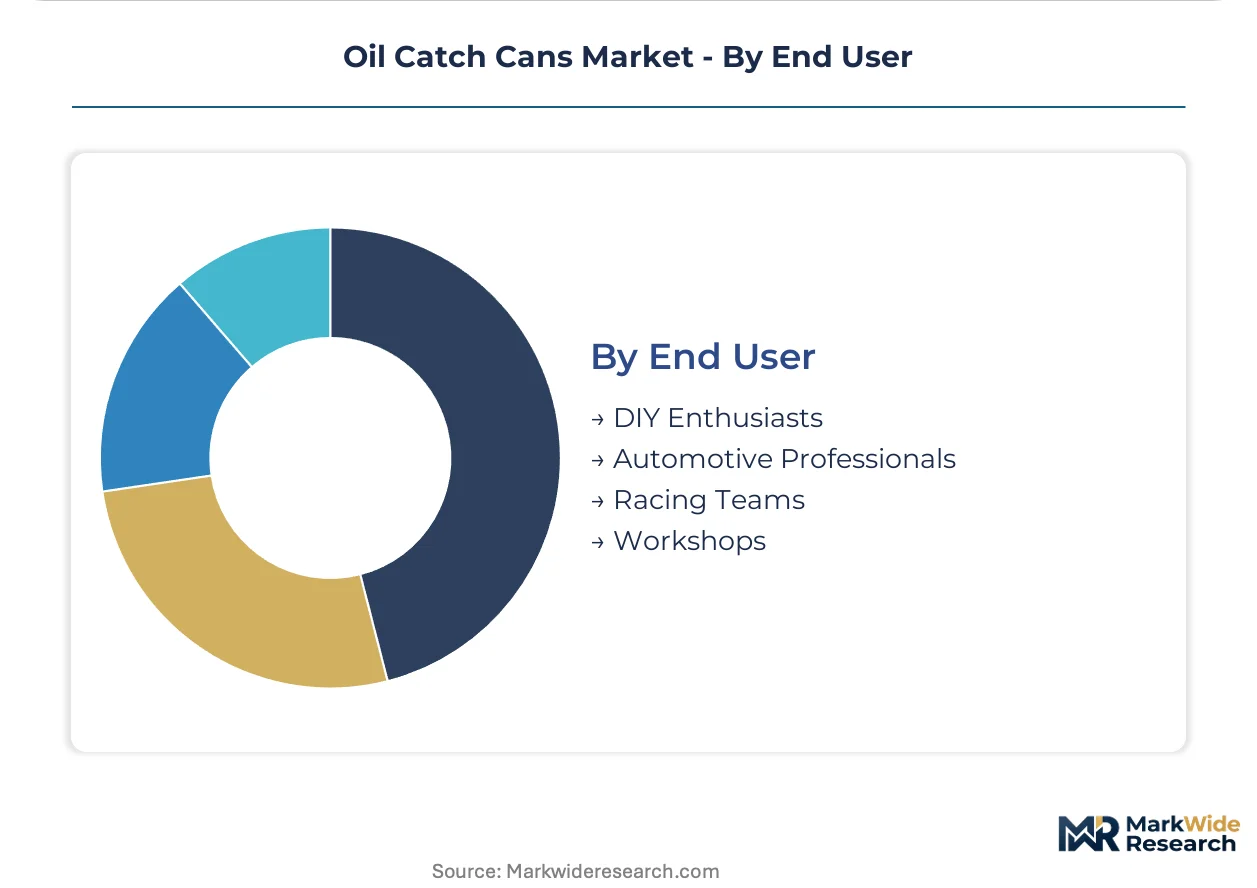
End User:
Procurement authority and technical sophistication create distinct buying behaviors that shape product positioning and support requirements.
- DIY Enthusiasts:Video-centric research behavior dominates purchase journeys, with YouTube installation tutorials serving as primary discovery channels. These buyers prioritize aesthetic finishes and social media visibility alongside functional performance.
- Automotive Professionals:High-volume installers demand consistent supply availability and streamlined warranty processing. Their procurement concentrates through distributor relationships with consolidated billing and technical support access.
- Racing Teams:Professional motorsport organizations specify custom-engineered solutions with engineering documentation for sanctioning body compliance. Their buying cycles align with chassis build schedules and season preparation timelines.
- Workshops:General repair facilities seeking incremental revenue streams from maintenance-additive sales. These users favor universal-fit inventory that addresses multiple vehicle platforms without SKU proliferation.
Automotive Professionals anchor current revenue; Racing Teams are gaining share fastest as professional motorsport participation expands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in the United States, where domestic muscle car and sport compact modification communities drive the majority of aftermarket catch can installations. EPA emissions enforcement and CARB certification requirements shape product legality across state lines. Secondary pockets emerge in Germany and Japan, where precision motorsport fabrication traditions support specialized supplier ecosystems.
United States
Domestic muscle car builders and sport compact enthusiasts generate the dominant share of aftermarket demand, with track-day participation expanding the installed base of high-load engines. EPA crankcase ventilation enforcement and CARB executive order requirements channel spending toward certified configurations that preserve registration legality. California and Texas anchor regional concentration, with Los Angeles and Dallas-Fort Worth metro areas hosting dense clusters of performance modification shops.
Germany
Precision motorsport fabricators and OEM-tier suppliers drive demand for CNC-machined aluminum housings with integrated sight tubes. REACH chemical regulations and TÜV certification standards govern aftermarket component legality for street-driven vehicles. Baden-Württemberg and Bavaria concentrate supplier activity, with Stuttgart and Munich anchoring engineering-intensive production of racing-derived crankcase management systems.
Japan
Time-attack and amateur roadracing communities sustain demand for compact multi-chamber designs suited to high-revving forced-induction platforms. METI industrial standards and JIS certification frameworks shape product specifications for domestic and export markets. Kansai and Chubu regions host specialized fabricators, with Osaka and Nagoya serving as hubs for precision machining of application-specific bracketry.
United Kingdom
Track-day participation and classic car restoration generate steady demand for closed-catch-can systems protecting vintage engine architectures. DVSA vehicle inspection standards and MOT compliance requirements influence product selection for road-legal modifications. Midlands and Southeast England concentrate distribution channels, with Birmingham and London anchoring specialist retailer networks serving enthusiast segments.
Australia
Recreational 4x4 and touring vehicle modifications drive demand for high-volume separators suited to elevated crankcase pressures from towing loads. Department of Infrastructure transport regulations and state-level vehicle modification codes govern aftermarket fitment legality. Victoria and New South Wales host the primary enthusiast clusters, with Melbourne and Sydney supporting specialized installation workshops.
Oil Catch Cans Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with premium-tier fabricators commanding margin through CARB certification and precision machining capabilities while volume-oriented suppliers compete on universal-fit accessibility. The vendor base organizes around three strategic archetypes: vertically integrated performance cooling specialists, racing-derived crankcase management purists, and precision CNC machining houses serving forced-induction platforms. Consolidation pressure operates selectively, with tier-one suppliers pursuing application-specific bracketry expansion and mid-tier players seeking emissions testing alignment to compress certification timelines.
Among branded performance specialists, Mishimoto, Moroso Performance Products, and Radium Engineering occupy archetype-defining positions. Mishimoto represents the vertically integrated cooling portfolio model, with backward integration from billet sourcing through anodized finishing sustaining margin control. Moroso Performance Products exemplifies racing-derived specialization in crankcase ventilation hardware. Radium Engineering anchors the precision CNC machining tier, with application-specific bracketry fabrication serving forced-induction platform requirements. These three entities collectively illustrate the competitive vectors shaping product architecture and channel economics.
| Leading Market Players |
|---|
| Mishimoto |
| Moroso Performance Products |
| Radium Engineering |
| Dorman Products |
| ECS Tuning |
| K&N Filters |
| Detroit Speed |
| GReddy |
| Cusco |
| Others |
Value Network & Pricing Analysis
Multi-chamber CNC-machined aluminum housings with integrated sight tubes are displacing single-chamber legacy designs across premium tiers, simultaneously elevating fabrication cost structures and concentrating supply among precision machining specialists with 5-axis programming capabilities. This technology transition tightens margin control for vertically integrated performance cooling specialists while compressing pricing power among universal-fit steel and plastic competitors.
Pricing Analysis
Volume placements cluster in economy-grade steel and injection-molded plastic universal-fit configurations, while margin capture concentrates in CARB-certified aluminum multi-chamber systems with anodized finishes and application-specific bracketry. Price differentiation rests on certification grade and thermal performance tier, with EO-numbered hardware commanding substantial premiums over uncertified alternatives. Cost compression in budget tiers is intensifying because OEM integrated oil separators reduce aftermarket attachment rates for basic configurations. DIY enthusiasts exhibit highest price sensitivity, while racing teams and professional motorsport organizations demonstrate lowest sensitivity given weight regulation compliance requirements.
Supply Chain Analysis
Freight cost escalation on 6061-T6 aluminum billet shipments from domestic mills to CNC machining centers in the United States is elevating landed input costs for anodized finished goods. Manufacturing concentrates in the United States, Germany, and Japan, with precision fabrication clusters anchored in Michigan, Baden-Württemberg, and Aichi prefecture. Raw material dependencies include 6061-T6 aluminum billet, anodizing chemicals, and carbon-fiber-reinforced polymer prepregs for motorsport variants. Single-source vulnerability around skilled 5-axis CNC machinists constrains capacity expansion. Distribution runs through performance automotive retailers, direct-to-consumer e-commerce platforms, and professional motorsport fabricators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Closed-volume crankcase separators with automated internal baffling represent a generational technology shift replacing legacy single-chamber passive designs, creating asymmetric opportunity for suppliers with precision machining and regulatory certification capabilities.
For Market Incumbents: To counter margin erosion from OEM integrated oil separator proliferation, deepen backward integration into billet sourcing and captive anodizing capacity while accelerating CARB executive order pursuit to compress certification timelines for street-legal product lines. Prioritize application-specific bracketry libraries for forced-induction platforms to defend channel positioning against universal-fit competitors. For New Entrants and Emerging Players: YouTube-native installation tutorial channels offer the most penetrable white-space route for building forced-induction expertise credibility before product launch. Target amateur motorsport participants in United States domestic muscle car and sport compact segments through dyno validation content partnerships. Pursue composite material motorsport variants for professional racing categories as the entry wedge. For Investors and Strategic Acquirers: Re-rating potential sits with precision CNC machining houses possessing established regulatory affairs functions given EPA enforcement escalation and CARB certification timeline compression. Long-term viability favors suppliers with demonstrated emissions testing documentation capabilities and application-specific bracketry IP. Watch SEMA-backed federal legislative efforts on modification rights preservation as the signal for addressable market expansion beyond current state-by-state patchwork.| Strategic Initiative | Industry Significance |
|---|---|
| CARB Executive Order Certification | EPA enforcement escalation makes EO-numbered hardware a national distribution prerequisite for street-legal lines. |
| 5-Axis CNC Machining Capacity Expansion | Precision bracketry fabrication for forced-induction platforms requires skilled programming talent that constrains supply. |
| Composite Material Motorsport Product Line | FIA weight regulations in professional racing categories justify premium pricing over conventional aluminum constructions. |
| Direct-to-Consumer E-Commerce Channel | YouTube-native discovery behavior collapses traditional wholesale markups for specialized fabricators. |
| Application-Specific Bracketry Library Buildout | Vehicle-specific mounting hardware eliminates fabrication labor for professional installers and compresses bay time. |
Research Methodology
Independent corroboration across primary interviews with performance cooling product managers, CNC machining operations leads, CARB certification consultants, and motorsport fabrication shop owners underwrites the qualitative findings. Secondary validation draws from EPA enforcement guidance documents, SEMA legislative tracking reports, and aluminum commodity pricing data from the London Metal Exchange. Bottom-up triangulation across end-user procurement patterns and top-down reconciliation against vehicle modification demographic trends anchor the analysis.
Comparable-period anchoring to historical aftermarket attachment rates for turbocharged vehicle populations establishes the forecast baseline across the projection horizon. The analytical framework models segmentation across material type, vehicle application, installation configuration, and end-user procurement authority. CAGRs derive from elasticity-adjusted demand curves incorporating forced-induction factory fitment trajectories and amateur motorsport event participation growth. Industry-specific inputs include CARB certification backlog estimates and 6061-T6 aluminum price volatility assumptions.
The model holds under sustained EPA crankcase ventilation enforcement and stable aluminum commodity pricing; deviation in federal preemption rulings or LME spike magnitude would shift trajectory. Forecasts reflect documented assumptions regarding modification rights legislative outcomes and OEM PCV system improvement rates. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Automotive Filter Paper Market
Automotive Parts
Automotive Carbon Canister Market
Automotive Parts
Global Automotive Differential System Market
Automotive Parts
Automotive Brake Shims Market
Automotive Parts
Automotive Grease Market
Automotive Parts
Automatic Gearbox Valves Market
Automotive Parts
Norway Passenger Vehicles Lubricants Market
Automotive Parts
France Automotive Parts Aluminium Die Casting Market
Automotive Parts
Racing Vehicles Market
Automotive Parts
Mexico Automotive Parts Die Casting Market
Automotive Parts
Malaysia Brake Pads Market
Automotive Parts
South Africa Commercial Vehicles Lubricants Market
Automotive Parts
Automotive Adaptive Engine Mounts Market
Automotive Parts
Garage Body Shop Equipment Market
Automotive Parts
Global Automotive Coolant Reservoir Tank Market
Automotive Parts
Automotive Paint Robots Market